
 Liquid Film Photoresist Market | 2026-2036
Liquid Film Photoresist Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Film Photoresist Market Insights
REACH compliance is expanding the cost-of-entry calculus for photoresist suppliers seeking European semiconductor markets. DuPont leverages its materials science heritage to sustain formulation leadership across advanced node applications. Fujifilm Electronic Materials anchors supply relationships with leading foundries through dedicated regional technical service centers. JSR Corporation competes on proprietary polymer architectures optimized for extreme ultraviolet sensitivity thresholds.
Liquid film photoresist denotes a photosensitive polymer solution coated as a uniform thin film onto substrates, typically ranging from hundreds of nanometers to several micrometers in thickness, which undergoes selective solubility changes upon exposure to patterned radiation for subsequent etching or deposition steps. Positive photoresist dominates volume consumption in leading-edge semiconductor manufacturing where exposed regions dissolve to create precise circuit patterns. Specialty photoresist differentiates margin pools as chipmakers pursue heterogeneous integration and three-dimensional stacking architectures requiring customized chemical formulations. Optical lithography remains the backbone technology for mainstream production, while electron beam lithography occupies niche applications in photomask fabrication and prototyping where pattern fidelity demands exceed conventional optical resolution limits.
The EPA regulates volatile organic compound emissions from photoresist coating operations in the United States, compelling solvent reformulation investments. ECHA oversees REACH registration requirements that govern chemical import and manufacturing across European semiconductor supply chains. Japan's METI coordinates domestic materials sovereignty programs that reinforce Shin-Etsu Chemical and Tokyo Ohka Kogyo positions in critical photoresist categories. Stakeholders must monitor how divergent regulatory timelines for per- and polyfluoroalkyl substance restrictions will reshape formulation roadmaps and supplier qualification protocols across major fabrication regions.
Market Dynamics
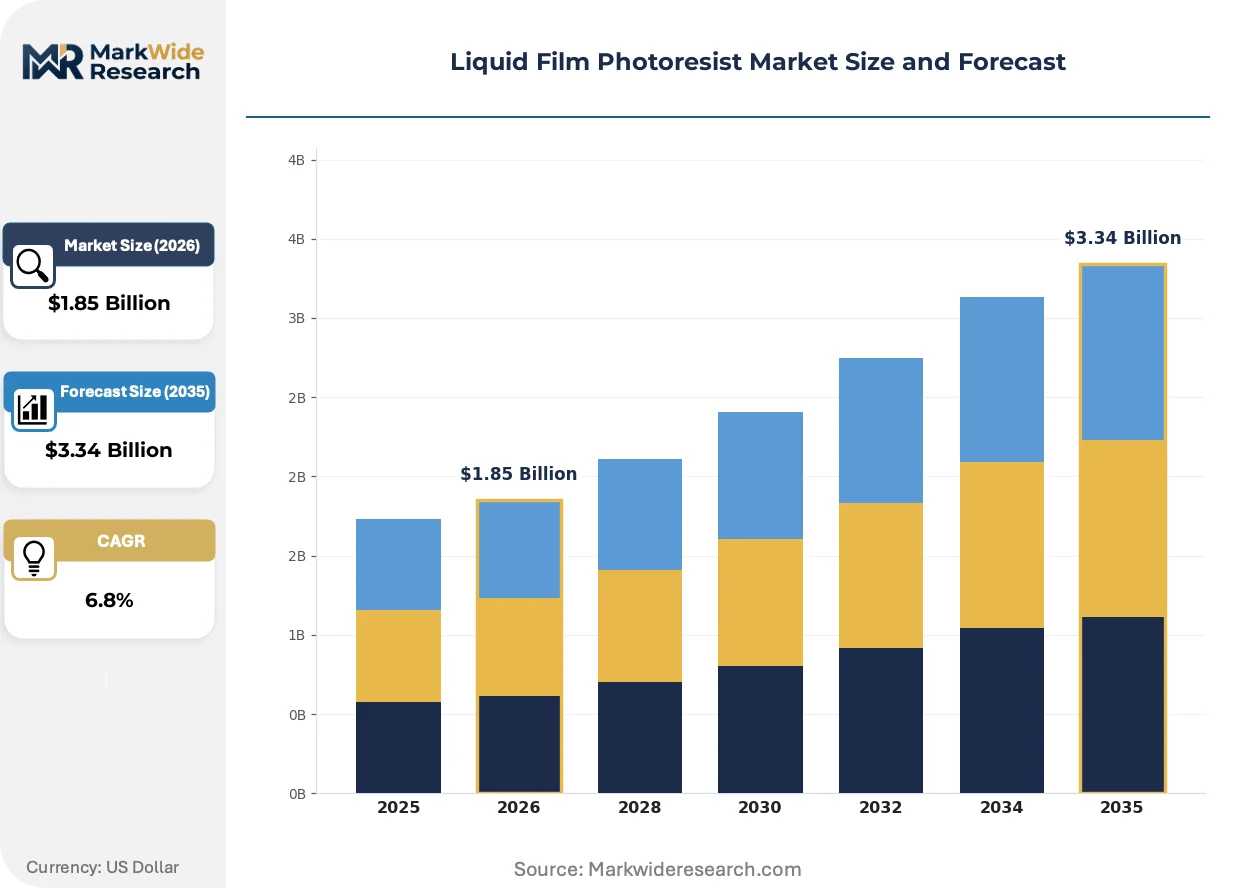
Advanced packaging architectures in semiconductor manufacturing are intensifying demand for high-resolution liquid film photoresist formulations, while subsidy frameworks like the EU Chips Act and East Asian equivalents are redistributing where capital equipment and materials procurement concentrates across fabrication corridors.
Growth Catalysts
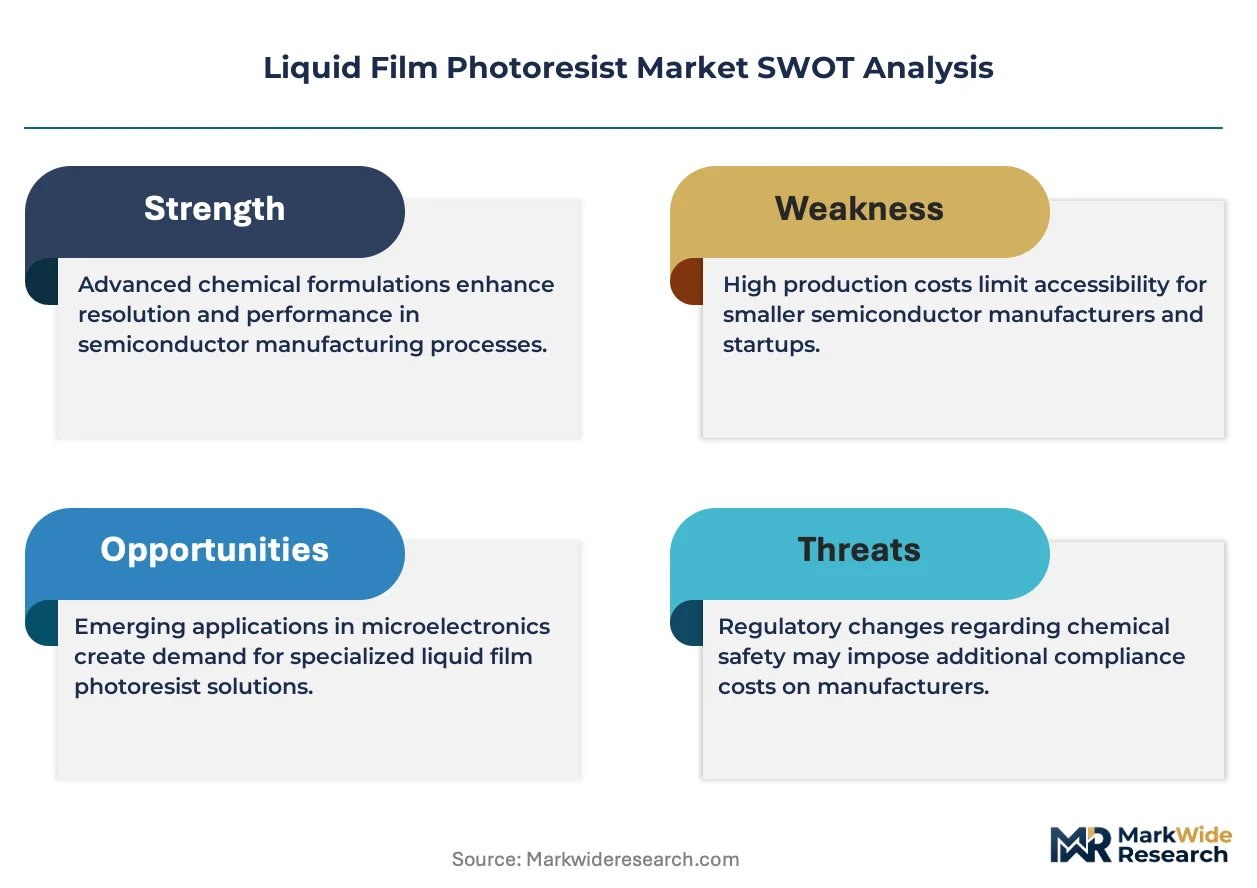
- EUV Lithography Penetration:Extreme ultraviolet sensitivity thresholds in leading-edge nodes are pulling demand for proprietary polymer architectures optimized at sub-7nm resolution.
- Subsidy Frameworks:The EU Chips Act and comparable East Asian incentive programs are channeling public capital into domestic photoresist supply chain localization.
- Heterogeneous Integration:Three-dimensional stacking architectures in high-performance computing are creating customized formulation requirements for interposer and through-silicon-via applications.
Market Restraints
- Feedstock Concentration:Specialty monomer and photoacid generator supply concentrates among Japanese chemical conglomerates, creating single-source vulnerability for non-Asian formulators.
- REACH Compliance Burden:ECHA registration requirements for novel chemical substances extend qualification timelines by 18-36 months for European market entry.
- Technical Resolution Ceiling:Optical lithography approaches fundamental physical limits at 3nm-equivalent half-pitch, constraining extendibility without wavelength reduction.
Strategic Opportunities
- Domestic Sovereignty Programs:Japan's METI-coordinated materials initiatives are opening procurement pathways for qualified local suppliers in critical photoresist categories.
- Photomask Fabrication Niche:Electron beam lithography applications in mask writing and prototyping represent underserved volume for high-viscosity, low-defect formulations.
- Packaging Redistribution:Taiwan's Hsinchu Science Park corridor is expanding capacity for fan-out wafer-level packaging, pulling demand for thick-film negative-tone resists.
Industry Challenges
- Formulation Chemistry Expertise Gap:The intersection of polymer science, photochemistry, and semiconductor process engineering requires talent pools concentrated in Osaka-Kobe and Boston-Waltham corridors.
- Fab Qualification Cycles:New photoresist formulations require 12-24 month integration validation at leading foundries before volume procurement authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Film Photoresist Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Photoresist, Negative Photoresist, Specialty Photoresist, Adhesion Promoters Application: Semiconductor Manufacturing, MEMS Fabrication, Microfabrication, PCB Production End User: Foundries, Integrated Device Manufacturers, Research Institutions, Electronic Component Manufacturers Technology: Optical Lithography, Electron Beam Lithography, X-ray Lithography, Nanoimprint Lithography |
| Companies Covered | DuPont, Fujifilm Electronic Materials, Tokyo Ohka Kogyo, JSR Corporation, Merck Group, Shin-Etsu Chemical, LG Chem, Sumitomo Chemical, Everlight Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Film Photoresist Market Trends and Innovations
Photoresist chemistry is undergoing forced evolution as patterning requirements tighten and environmental compliance tightens solvent formulations. Two parallel tracks dominate: molecular-scale precision in exposure response, and systemic reformulation to satisfy emission and substance restrictions.
Metal oxide resists are rewriting the resolution-performance tradeoff in extreme ultraviolet applications. These inorganic-organic hybrid formulations deliver superior etch resistance and reduced line-edge roughness compared to conventional chemically amplified resists. Leading foundries in Taiwan and South Korea are piloting metal oxide platforms at 3nm nodes. The technology is compressing the historical gap between laboratory resolution demonstrations and manufacturable process windows.
Per- and polyfluoroalkyl substance restrictions under REACH and emerging EPA frameworks are forcing solvent base transitions across formulation portfolios. Fluorinated surfactants historically critical for coating uniformity face phase-out timelines diverging between European and American regulatory calendars. Specialty photoresist suppliers serving automotive and industrial semiconductor segments are accelerating alkyl-substituted alternatives to maintain cross-regional product registration.
Direct procurement relationships between foundry chemical management teams and photoresist formulators are displacing traditional distributor intermediaries in leading-edge segments. TSMC and Samsung Foundry have established dedicated technical service center requirements that favor suppliers with localized application engineering presence. This pattern is most visible in Taiwan's Hsinchu-Taichung corridor where three of the five largest foundry chemical spenders operate captive qualification laboratories.
Liquid Film Photoresist Market Segmentation
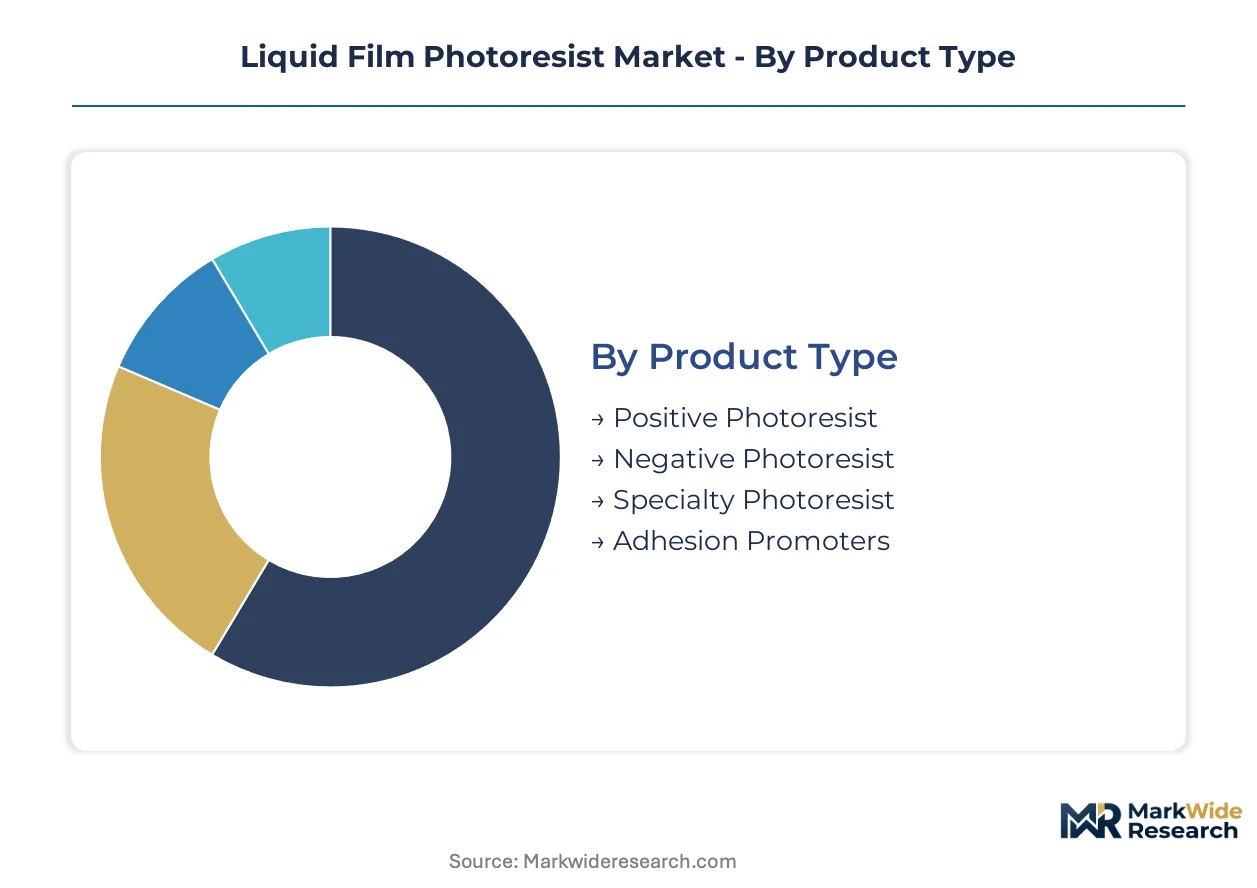
Liquid film photoresist segmentation reveals how formulation chemistry, patterning technology, and end-use requirements create distinct commercial battlegrounds. Each axis carries different margin profiles, qualification barriers, and supplier concentration dynamics that shape competitive positioning across the value chain.
Product Type:
Formulation chemistry determines resolution limits, process latitude, and environmental compliance burden across semiconductor and microfabrication applications.
- Positive Photoresist:Chemically amplified formulations dominate leading-edge semiconductor manufacturing where exposed regions dissolve in aqueous developer to create precise circuit patterns. Taiwan's Hsinchu Science Park corridor concentrates demand as foundries push toward sub-7nm resolution thresholds requiring proprietary polymer architectures.
- Specialty Photoresist:Customized formulations address heterogeneous integration and three-dimensional stacking architectures for high-performance computing interposers. These command premium pricing due to application-specific qualification requirements and limited qualified supplier pools.
- Negative Photoresist:Cross-linking chemistry suits thick-film applications in MEMS and advanced packaging where unexposed regions wash away.
- Adhesion Promoters:Surface preparation chemistries ensure coating uniformity on diverse substrate materials including copper, silicon, and glass.
Positive photoresist leads on scale; specialty photoresist leads on momentum.
Application:
End-use process requirements fragment demand across resolution, throughput, and substrate compatibility dimensions.
- Semiconductor Manufacturing:Leading-edge wafer fabrication drives the most demanding specifications for line-edge roughness, defect density, and critical dimension uniformity. The EU Chips Act subsidy frameworks are channeling capital toward domestic European fabrication capacity, reshaping procurement geography for qualified photoresist suppliers.
- MEMS Fabrication:Micro-electromechanical systems require thick-film resists capable of high aspect-ratio patterning for sensors and actuators. Automotive and consumer electronics demand is expanding foundry capacity for inertial measurement units and pressure sensors.
- Microfabrication:Research and prototyping applications span photonics, biomedical devices, and academic fabrication facilities with diverse specification requirements.
- PCB Production:Printed circuit board manufacturing consumes high-volume, cost-optimized formulations with relaxed resolution requirements compared to semiconductor grades.
Semiconductor manufacturing anchors volume procurement; MEMS fabrication is climbing the fastest.
End User:
Customer type determines technical service intensity, contract structure, and qualification timeline expectations.
- Foundries:Merchant wafer manufacturers in Taiwan and South Korea operate the most demanding supplier qualification protocols, requiring 12-24 month integration validation before volume authorization. Direct procurement relationships are displacing distributor intermediaries as TSMC and Samsung Foundry establish captive chemical management teams.
- Integrated Device Manufacturers:Captive fabrication facilities at IDMs maintain diversified supplier portfolios to mitigate single-source risk in critical photoresist categories.
- Research Institutions:Academic and government laboratories pilot emerging lithography technologies before commercial scale-up.
- Electronic Component Manufacturers:Passive component and packaging specialists consume standardized formulations with shorter qualification cycles.
Foundries command supplier attention through volume concentration; IDMs retain negotiating leverage through dual-sourcing requirements.
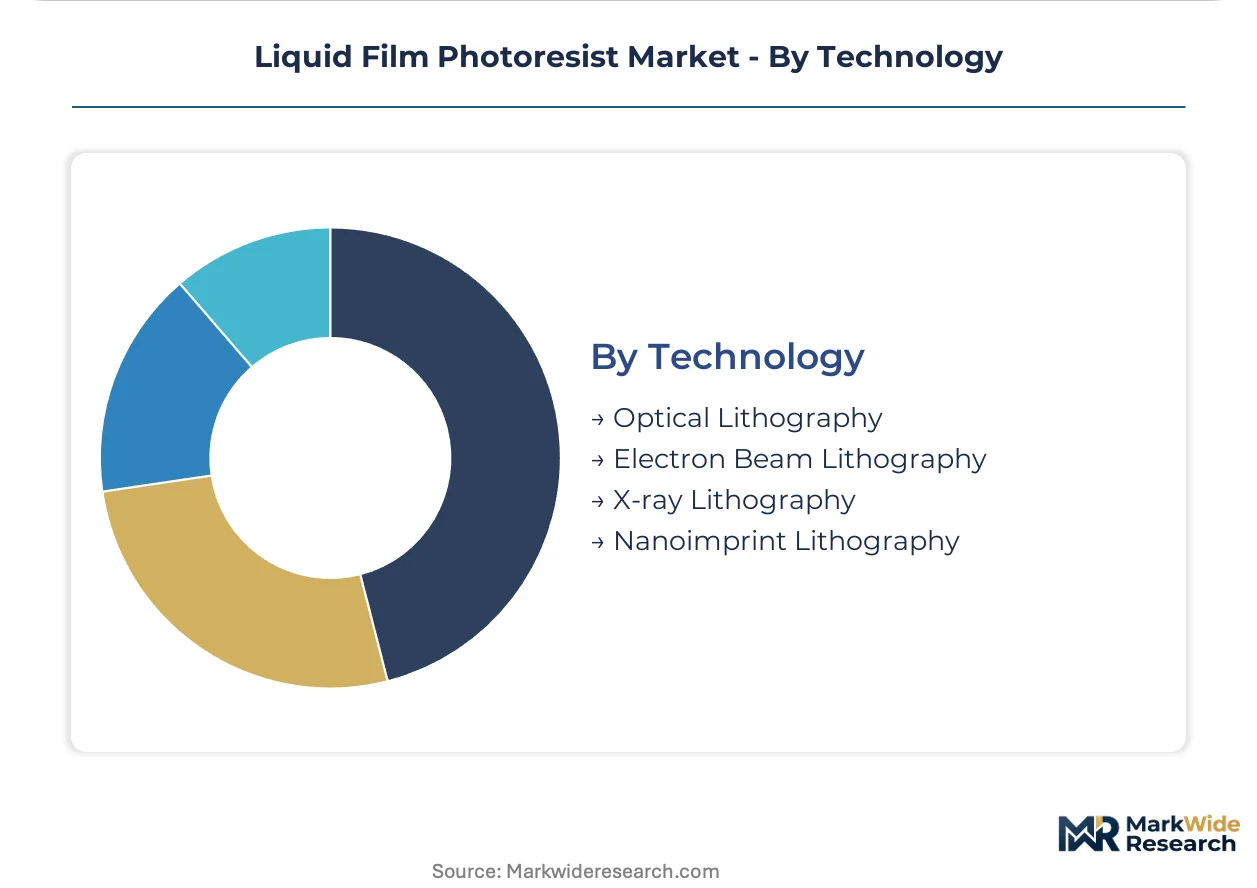
Technology:
Patterning modality dictates resist sensitivity, contrast requirements, and equipment compatibility constraints.
- Optical Lithography:Deep ultraviolet and immersion systems remain the backbone of mainstream semiconductor production. Resolution extension through multiple patterning techniques sustains demand for high-contrast, low-defect formulations at mature nodes.
- Electron Beam Lithography:Maskless direct-write systems serve photomask fabrication and prototyping applications where pattern fidelity demands exceed optical resolution limits. High-viscosity, low-defect formulations represent underserved volume for qualified suppliers.
- X-ray Lithography:Synchrotron-based systems occupy niche applications in specialized MEMS and packaging research.
- Nanoimprint Lithography:Mechanical pattern transfer offers cost advantages for high-volume optical and storage applications with less demanding overlay requirements.
Optical lithography sustains installed base dominance; electron beam lithography offers the steepest expansion trajectory in mask writing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer scientists and photochemists concentrate in the Osaka-Kobe and Boston-Waltham corridors, anchoring formulation expertise that suppliers leverage for foundry qualification cycles. Talent density in these clusters accelerates integration validation timelines.
United States
EPA regulations on volatile organic compound emissions from coating operations compel solvent reformulation investments across domestic fabrication facilities. The Boston-Waltham corridor hosts concentrated application engineering teams serving leading-edge foundry customers. Research institutions in this cluster pilot metal oxide resist platforms before commercial scale-up.
Germany
ECHA oversight of REACH registration requirements extends qualification timelines for novel chemical substances entering European semiconductor supply chains. The EU Chips Act channels public capital toward domestic fabrication capacity expansion in Saxony and Bavaria. Dresden's Silicon Saxony cluster attracts photoresist suppliers establishing localized technical service presence.
Japan
METI coordinates materials sovereignty programs reinforcing domestic positions in critical photoresist feedstock categories. Specialty monomer and photoacid generator supply concentrates among Osaka-Kobe chemical conglomerates. Tokyo Ohka Kogyo and JSR Corporation anchor formulation expertise in this corridor.
South Korea
Samsung Foundry and SK Hynix operate captive qualification laboratories with dedicated technical service center requirements for suppliers. Domestic suppliers leverage proximity to reduce 12-24 month integration validation cycles. The Yongin-Giheung corridor concentrates demand for sub-7nm resolution formulations.
Taiwan
TSMC's direct procurement relationships displace distributor intermediaries in leading-edge segments. The Hsinchu Science Park corridor concentrates three of the five largest foundry chemical spenders with captive qualification laboratories. Fan-out wafer-level packaging expansion pulls demand for thick-film negative-tone resists.
Liquid Film Photoresist Market Competitive Landscape
The competitive structure tilts toward integrated materials conglomerates with captive polymer architecture capabilities. Japanese and American chemical groups dominate proprietary formulation portfolios. Three archetypes define positioning: diversified materials conglomerates with semiconductor chemicals divisions, specialized electronic materials pure-plays, and regional chemical groups leveraging domestic foundry relationships. Competitive moves concentrate on strategic partnerships for EUV platform qualification and geographic expansion through technical service center establishment.
Among diversified materials conglomerates, DuPont and Fujifilm Electronic Materials exemplify archetypes anchored by broad materials science heritage. JSR Corporation occupies a position representing specialized electronic materials expertise with concentrated photochemistry capabilities. These three entities sit within the premium-tier supplier pool where foundry qualification protocols create 12-24 month barriers to volume procurement authorization.
| Leading Market Players |
|---|
| DuPont |
| Fujifilm Electronic Materials |
| Tokyo Ohka Kogyo |
| JSR Corporation |
| Merck Group |
| Shin-Etsu Chemical |
| LG Chem |
| Sumitomo Chemical |
| Everlight Chemical |
| Others |
Pricing and Supply Chain Analysis
Foundry chemical management teams at TSMC and Samsung Foundry anchor procurement concentration, locking in contract-based long-term offtake structures that bundle technical service with volume commitments. This buyer archetype's dual-sourcing mandates create pricing stratification across premium qualified formulations and standard-tier alternatives.
Pricing Analysis
Service bundling separates pure material supply from integrated qualification support, with foundry-direct contracts commanding premium positioning over distributor-mediated transactions. Price differentiation hinges on EUV platform certification status and localized application engineering presence. Cost compression in standard-grade optical lithography resists is intensifying because Chinese suppliers are expanding 193nm immersion-compatible portfolios. MEMS fabricators and PCB producers exhibit highest price sensitivity; leading-edge foundries prioritize performance consistency over unit economics.
Supply Chain Analysis
Polymer synthesis expertise concentrates in Japan's Osaka-Kobe corridor and the Boston-Waltham cluster, constraining workforce mobility for new capacity buildouts. Specialty monomer and photoacid generator supply draws from Japanese chemical conglomerates, while formulated photoresist production rests on Taiwan and South Korean foundry proximity. Single-source vulnerability in EUV-grade polymer architectures represents the dominant structural risk. Distribution runs through direct technical service centers for leading-edge segments and regional chemical distributors for mature-node applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with heterogeneous integration and 3D stacking architectures pulling specification thresholds upward across interposer and through-silicon-via applications.
For Market Incumbents: Acquire captive photoacid generator synthesis capabilities to secure feedstock autonomy against Japanese supply concentration. Lock in multi-year technical service center commitments with Hsinchu and Yongin-Giheung corridor foundries before emerging Korean suppliers complete METI-backed qualification cycles. Metal oxide resist platform patents represent the critical defensive asset to consolidate. For New Entrants and Emerging Players: Electron beam lithography mask-writing specialists present the most penetrable buyer archetype, as incumbent suppliers underinvest in high-viscosity, low-defect formulation portfolios. Photomask fabrication houses in Germany's Silicon Saxony cluster and Japan's Tsukuba corridor operate shorter qualification protocols than wafer foundries. Lead with rapid-turn prototyping services to establish technical credibility before scaling to volume semiconductor accounts. For Investors and Strategic Acquirers: Semiconductor materials conglomerates are the most active acquirer in this space, seeking polymer architecture capabilities to complement existing electronic chemicals portfolios. Target formulation pure-plays with qualified positions in EUV or metal oxide platforms. Watch for METI subsidy disbursement acceleration as the inflection signal for Japanese domestic supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoacid Generators | Shin-Etsu Chemical and JSR Corporation are securing monomer supply autonomy against feedstock bottlenecks. |
| EUV Platform Qualification Partnership | Direct collaboration with ASML exposure tool roadmaps accelerates formulation validation at TSMC and Samsung Foundry. |
| Technical Service Center Expansion | Localized application engineering in Hsinchu-Taichung corridor satisfies captive laboratory requirements for foundry direct procurement. |
| Metal Oxide Resist Portfolio Development | Inorganic-organic hybrid platforms address 3nm node line-edge roughness specifications for leading-edge logic production. |
| REACH-Compliant Solvent Reformulation | Fluorinated surfactant substitutions maintain European market registration ahead of per- and polyfluoroalkyl substance restrictions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with photoresist formulators, foundry chemical management teams, semiconductor equipment engineers, and polymer synthesis specialists with secondary validation through SEC 10-K filings, customs and trade data, and SEMI materials market reports. Bottom-up formulation volume estimates and top-down wafer fabrication capacity models were triangulated against foundry capex disclosures.
Historical reference periods anchored the projection horizon to demonstrated qualification cycle timelines and subsidy framework disbursement patterns. Segmentation modeling spanned formulation chemistry type, patterning technology modality, end-use process requirement, and regional fabrication cluster. CAGRs were derived from installed base equipment forecasts and node migration assumptions. EUV penetration curves and heterogeneous integration adoption rates served as key demand-side inputs.
Underlying measurement precision varies by segment; leading-edge semiconductor manufacturing carries tighter precision than MEMS and PCB applications due to disclosed foundry chemical spend data. Forecasts reflect assumptions on subsidy program continuity, regulatory phase-out timelines, and lithography technology transition speeds. Practitioners should monitor EUV platform qualification announcements, METI materials sovereignty disbursement schedules, and per- and polyfluoroalkyl substance restriction calendars for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Silicon Carbide Ceramics Market
Semiconductor Material
Global Magnesium Oxide Nanopowder Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Compound Semiconductor Materials Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market