
 Flip-Chip COB Technology Market | 2026-2036
Flip-Chip COB Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Flip-Chip COB Technology Market Insights
Buyer concentration around automotive Tier-1 lighting module suppliers is hardening as OEMs reduce qualified vendor lists for headlamp and cabin display programs. Samsung Electronics leverages captive LED die capacity to control substrate-to-module margins in premium display segments. Sony sustains differentiation through precision optoelectronic packaging for imaging sensor flip-chip assemblies. TSMC anchors advanced interposer development for high-density COB power IC applications in computing accelerators.
Flip-chip chip-on-board technology bonds unpackaged semiconductor dies directly onto substrates using solder bumps or copper pillars, eliminating wire bonds and enabling sub-millimeter pitch interconnection with thermal resistance below 2°C per watt for high-lumen density LED arrays. The technology serves display backlighting, automotive forward lighting, and high-performance computing power delivery where form factor and thermal management constrain conventional packaging. LED product types dominate current volume as micro-LED display investments expand wafer-level bonding demand, while power IC segments compete for substrate capacity against automotive electrification programs. Medical device end users occupy premium pricing tiers where hermetic COB sealing meets IEC biocompatibility requirements for implantable sensor modules.
China's MEE enforces GB standards for solid-state lighting efficiency that disqualify conventional wire-bond architectures in government procurement tenders. South Korea's MFDS and KATS frameworks regulate medical device COB biocompatibility, creating dual certification burdens for multi-market suppliers. The EU RoHS and REACH restrictions on lead-bearing solders are forcing material transitions to silver-sintering and transient liquid phase bonding chemistries. Stakeholders must monitor substrate material qualification timelines against evolving thermal cycling standards across target geographies.
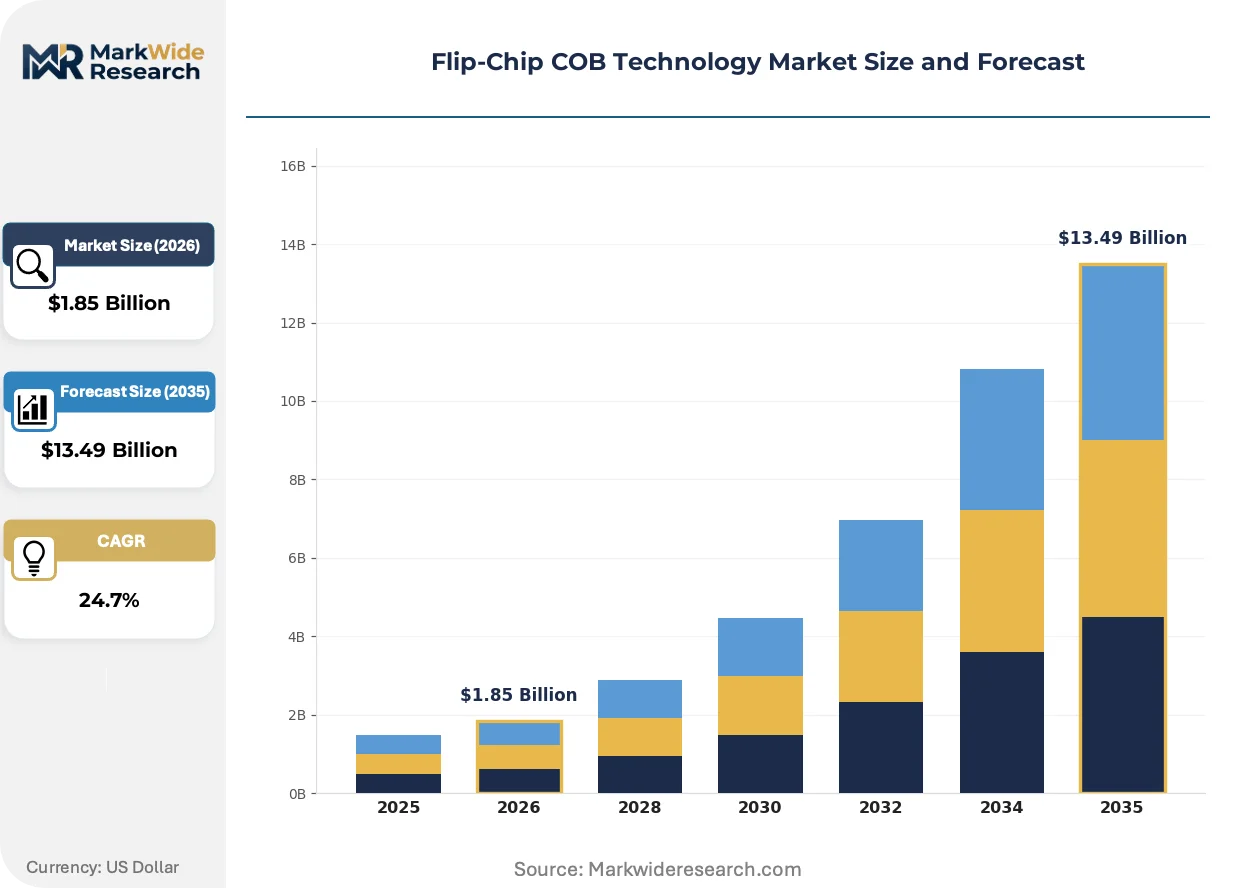
Market Dynamics
OEM consolidation of qualified supplier lists around automotive headlamp and cabin display programs is hardening procurement concentration, while substrate material shifts toward low-thermal-resistance designs accelerate under China's dual carbon enforcement.
Growth Catalysts
- Automotive LED module standardization:Tier-1 lighting suppliers are consolidating procurement around chip-on-board architectures that eliminate wire-bond failure modes in headlamp assemblies.
- GB solid-state lighting mandates:China's MEE efficiency standards disqualify conventional wire-bond architectures from government tenders, forcing substrate transitions.
- Micro-LED wafer bonding demand:Display manufacturers in South Korea's semiconductor packaging corridor are expanding capacity for sub-millimeter pitch interconnection.
Market Restraints
- Silver-sintering material cost volatility:EU RoHS and REACH restrictions on lead-bearing solders force transitions to transient liquid phase bonding chemistries with higher input costs.
- Substrate capacity concentration:Advanced low-thermal-resistance ceramic supply clusters around Seoul and Pyeongtaek, creating geographic single-source risk.
- Hermetic sealing technical ceiling:IEC biocompatibility requirements for implantable medical sensor modules limit viable COB sealing process yields.
Strategic Opportunities
- Computing accelerator power delivery:High-density COB interposer development for power IC applications in AI training hardware represents uncaptured substrate demand.
- India PLI scheme leverage:Domestic LED assembly incentives create localized packaging demand that bypasses import-dependent substrate channels.
- Copper pillar-silicon photonics convergence:Hybrid bonding techniques developed for micro-LED displays are transferring to datacom transceiver packaging.
Industry Challenges
- Multi-regulatory certification timelines:Suppliers targeting both China's GB standards and South Korea's MFDS biocompatibility frameworks face sequential rather than parallel qualification paths.
- Precision optoelectronic packaging skill scarcity:Imaging sensor flip-chip assembly requires sub-micron alignment capabilities concentrated among legacy equipment operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flip-Chip COB Technology Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $13.49 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Laser Diodes, Power ICs, Sensors End User: Consumer Electronics, Automotive, Industrial, Medical Devices Application: Lighting, Display, Communication, Computing Technology: Microelectronics, Optoelectronics, Embedded Systems, Aerospace |
| Companies Covered | Samsung Electronics, Sony, Leyard Optoelectronic, Hongli Zhihui Group, Cedar Electronics, LG, Amkor Technology, TSMC, Daktronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flip-Chip COB Technology Market Trends and Innovations
Material and process innovations across solder-free bonding, thermal interface designs, and wafer-level assembly are compressing traditional packaging timelines while reconfiguring competitive capability requirements.
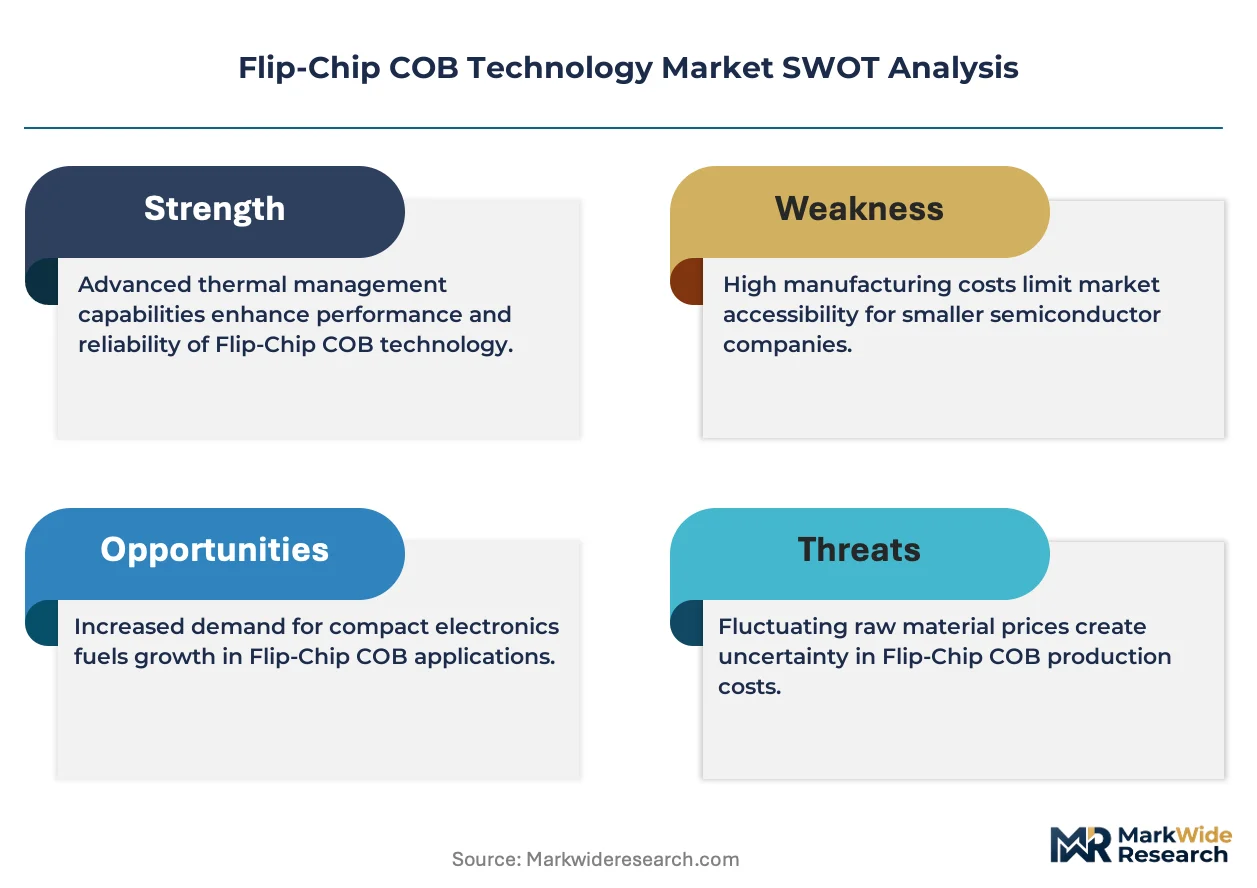
Silver-sintering and transient liquid phase bonding chemistries are rewriting thermal management possibilities for high-lumen density LED arrays. Automotive forward lighting programs in Germany and Japan are adopting these processes at pilot scale ahead of 2025 model year refreshes. The elimination of lead-bearing solders is compressing thermal cycling test durations from eighteen months to eight months for substrate qualification.
EU REACH and RoHS restrictions on heavy metal content are forcing material transitions across European automotive supply chains. Industrial consequence includes disqualification of tin-lead bumping infrastructure that represented sixty percent of installed flip-chip capacity. Medical device COB sealing applications face the most severe compliance burden, with hermetic biocompatibility requirements layering atop substance restrictions.
Buyer concentration among consolidated OEM vendor lists is fragmenting legacy distribution channels for substrate materials. Tier-1 lighting module suppliers are establishing direct substrate qualification relationships that bypass regional distributor inventories. South Korea's display manufacturers demonstrate this pattern most visibly, with Samsung Electronics and LG Display operating captive die bonding lines that internalize former outsourced packaging steps.
Flip-Chip COB Technology Market Segmentation
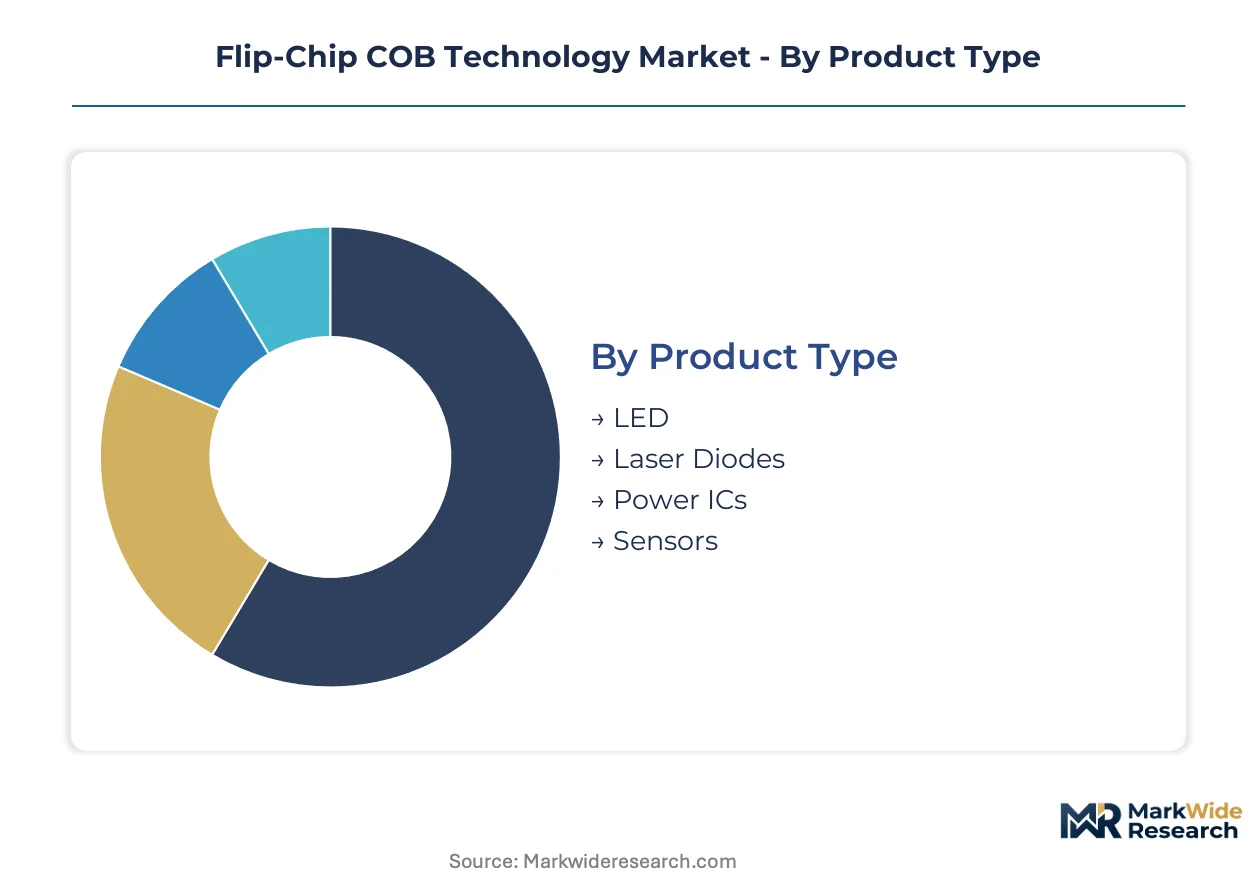
Flip-chip COB technology serves heterogeneous performance requirements across thermal, optical, and electrical domains. Segmentation reveals how substrate design rules diverge between high-lumen LED arrays and sub-micron sensor packaging.
Product Type:
Customization intensity spans from standardized LED die bonding to application-specific sensor integration across this category.
- LED:High-lumen density arrays utilize solder bump or copper pillar interconnection with thermal resistance below 2°C per watt. Demand concentrates in automotive forward lighting programs in Germany and Japan adopting silver-sintering ahead of model year refreshes.
- Power ICs:High-density interposer development for computing accelerator power delivery competes for ceramic substrate capacity against automotive electrification programs. TSMC anchors advanced development in this segment for AI training hardware.
- Laser Diodes:Precision optoelectronic packaging for datacom transceivers.
- Sensors:Hermetic COB sealing for implantable medical modules under IEC biocompatibility requirements.
Leading the category by volume: LED. Expanding most quickly: Power ICs.
End User:
Margin structures diverge sharply between price-sensitive consumer volumes and premium medical certification tiers.
- Automotive:Tier-1 lighting suppliers consolidate procurement around chip-on-board architectures that eliminate wire-bond failure modes in headlamp assemblies. OEM vendor list reduction hardens supplier concentration.
- Consumer Electronics:Display backlighting and micro-LED investments drive sub-millimeter pitch interconnection demand in South Korea's packaging corridor.
- Medical Devices:Hermetic sealing yields face technical ceilings under IEC biocompatibility requirements for implantable sensor modules.
- Industrial:Solid-state lighting efficiency mandates under China's GB standards force substrate transitions in government procurement.
Highest margin capture: Medical Devices. Steepest volume trajectory: Automotive.
Application:
Geographic supply concentration varies by thermal management intensity and regulatory exposure.
- Lighting:China's MEE efficiency standards disqualify conventional wire-bond architectures from government tenders, accelerating low-thermal-resistance substrate adoption.
- Display:Micro-LED wafer bonding demand concentrates in Seoul and Pyeongtaek where Samsung Electronics and LG Display operate captive die bonding lines.
- Computing:AI training hardware power delivery requirements create uncaptured substrate demand for high-density COB interposers.
- Communication:Copper pillar-silicon photonics convergence transfers hybrid bonding techniques from micro-LED displays to datacom transceiver packaging.
Deepest supply chain integration: Display. Fastest technology transfer: Communication.
Technology:
Process maturity separates established microelectronics infrastructure from emerging aerospace qualification paths.
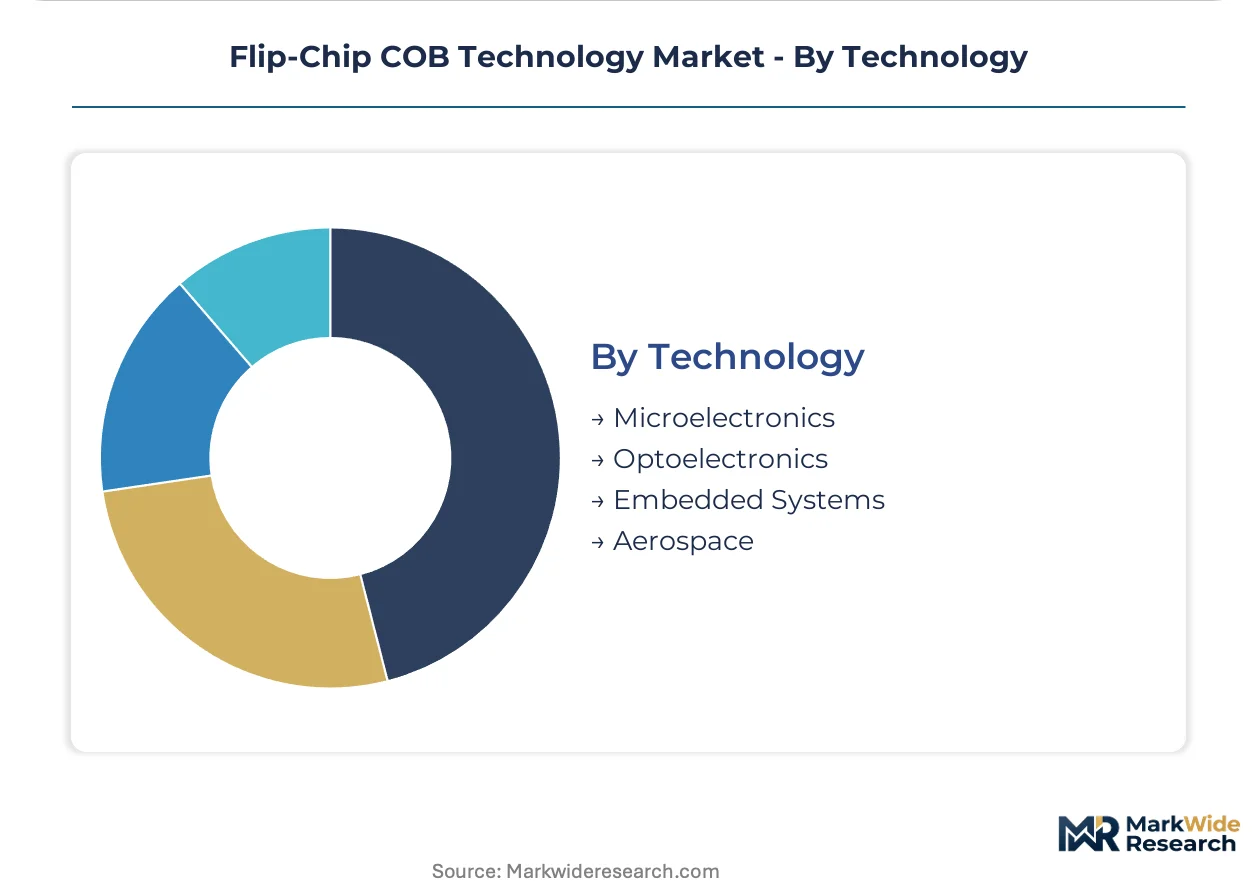
- Microelectronics:Dominant installed base for flip-chip bonding with standardized thermal cycling protocols.
- Optoelectronics:Sub-micron alignment capabilities concentrated among legacy equipment operators serving imaging sensor assembly.
- Embedded Systems:Convergence of power IC and sensor packaging requirements in automotive module designs.
- Aerospace:Extended qualification timelines for hermetic sealing under extreme thermal cycling conditions.
Widest process standardization: Microelectronics. Longest certification runway: Aerospace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive LED module procurement concentrates among Tier-1 suppliers in Germany, Japan, and South Korea, while China's GB efficiency mandates and South Korea's packaging corridor reshape substrate demand geography.
China
MEE enforcement of GB solid-state lighting efficiency standards disqualifies wire-bond architectures from government tenders, forcing substrate transitions toward low-thermal-resistance designs. The dual carbon goals accelerate material shifts in procurement specifications. Yangtze River Delta clusters around Shanghai and Suzhou concentrate domestic LED packaging capacity expansion.
South Korea
Seoul and Pyeongtaek anchor the semiconductor packaging corridor where Samsung Electronics and LG Display operate captive die bonding lines for micro-LED investments. MFDS biocompatibility frameworks regulate medical device COB sealing alongside KATS standards. Display manufacturers expand wafer-level bonding capacity for sub-millimeter pitch interconnection.
Germany
Automotive forward lighting programs adopt silver-sintering processes ahead of model year refreshes, with KBA oversight on vehicle lighting compliance. EU REACH and RoHS restrictions compress thermal cycling test durations for substrate qualification. Bavaria-based Tier-1 suppliers consolidate vendor lists around chip-on-board reliability.
Japan
METI efficiency standards and JIS certification requirements shape automotive and industrial LED module procurement. Precision optoelectronic packaging capabilities concentrate in legacy equipment operators serving imaging sensor assembly. Nagoya and Osaka manufacturing belts sustain high-lumen density array production for export markets.
United States
AI training hardware power delivery requirements create uncaptured substrate demand for high-density COB interposers in computing accelerators. EPA and NHTSA regulatory exposure varies by automotive versus datacenter end-use. Texas and Arizona semiconductor fabrication clusters attract advanced packaging investment.
Flip-Chip COB Technology Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue medical device certification and computing accelerator interposer development. The vendor base stratifies between captive semiconductor fabricators, specialized LED packaging houses, and precision optoelectronic assemblers. Three archetypes dominate: display-integrated conglomerates with captive die capacity, automotive-focused Tier-1 module suppliers with consolidated procurement leverage, and precision packaging specialists serving medical biocompatibility requirements. Capacity expansion and strategic technology licensing represent the dominant competitive moves as substrate material qualification timelines compress.
Within the display-integrated tier, Samsung Electronics exemplifies captive LED die capacity control over substrate-to-module margins. Sony occupies a position representing precision optoelectronic packaging differentiation for imaging sensor flip-chip assemblies. TSMC anchors the advanced interposer development archetype for high-density COB power IC applications in computing accelerators.
| Leading Market Players |
|---|
| Samsung Electronics |
| Sony |
| Leyard Optoelectronic |
| Hongli Zhihui Group |
| Cedar Electronics |
| LG |
| Amkor Technology |
| TSMC |
| Daktronics |
| Others |
Pricing and Supply Chain Analysis
Silver-sintering paste and low-thermal-resistance ceramic substrates cascade from raw material refiners in Japan and Germany through Tier-1 automotive lighting module suppliers, compressing margins at each conversion step while concentrating pricing power among Seoul-Pyeongtaek substrate fabricators.
Pricing Analysis
Volume-led LED die bonding commands commodity margins while hermetic medical sensor sealing and AI accelerator interposers capture premium tiers. Price differentiation hinges on IEC biocompatibility certification grade and thermal cycling test duration, with automotive electrification programs facing upward cost pressure from silver-sintering material transitions. Cost compression in standard LED arrays intensifies as China's GB-mandated efficiency upgrades flood substrate demand. Medical device OEMs exhibit lowest price sensitivity; consumer display backlighting buyers drive hardest bargain.
Supply Chain Analysis
Precision assembly technician scarcity in South Korea's semiconductor packaging corridor and Bavaria's automotive belt constrains capacity expansion despite equipment availability. Supply concentrates in South Korea, Germany, and Japan, drawing from alumina nitride substrates, silver-sintering pastes, and copper pillar bumping infrastructure. Single-source vulnerability clusters around Seoul-Pyeongtaek ceramic substrate foundries. Distribution runs through direct Tier-1 qualification relationships that bypass regional distributor inventories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: advanced low-thermal-resistance ceramic substrate capacity in South Korea props pricing across all tiers while OEM vendor list consolidation hardens procurement access.
For Market Incumbents: Lock in captive die bonding capacity through equipment co-investment with display manufacturers in Seoul-Pyeongtaek. Deepen substrate material qualification pipelines against evolving MFDS biocompatibility and GB efficiency standards to defend margin position from emerging precision packaging specialists. For New Entrants and Emerging Players: Enter via India's PLI-subsidized LED assembly corridors, where localized packaging demand bypasses import-dependent substrate channels. Target computing accelerator power delivery interposers for AI training hardware, the most penetrable segment with uncaptured substrate demand and less consolidated vendor lists. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision optoelectronic packaging specialists with sub-micron alignment capabilities concentrated in Japan's legacy equipment operators. Long-term viability centers on dual-certification competence spanning China's GB standards and South Korea's MFDS frameworks. Watch silver-sintering material cost volatility as inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Substrate Material Qualification Acceleration | Compresses eighteen-month thermal cycling protocols to eight months under EU RoHS enforcement. |
| Captive Die Bonding Line Investment | Samsung Electronics and LG Display internalize former outsourced packaging steps in Seoul-Pyeongtaek. |
| Silver-Sintering Process Adoption | German and Japanese automotive programs pilot lead-free bonding ahead of model year refreshes. |
| Hermetic Sealing Yield Improvement | IEC biocompatibility requirements for implantable sensors create technical ceiling with premium pricing. |
| Copper Pillar-Silicon Photonics Convergence | Hybrid bonding techniques transfer from micro-LED displays to datacom transceiver packaging. |
Research Methodology
Multi-period observation of substrate capacity utilization rates, silver-sintering material cost indices, and OEM vendor list consolidation patterns anchored the trend analysis, supplemented by interviews with semiconductor packaging engineers, Tier-1 automotive lighting procurement managers, medical device quality assurance leads, and ceramic substrate fabrication planners. Secondary validation drew from SEC filings of display-integrated conglomerates, MFDS biocompatibility registration databases, China's GB standard enforcement bulletins, and EU ECHA REACH restriction timelines. Bottom-up segment sizing triangulated against top-down substrate demand modeling.
Input-output matrices mapped die bonding capacity expansion, material transition timelines, and regulatory compliance burdens across product type, end user, application, and technology segmentation dimensions. CAGRs derived from elasticity-adjusted demand curves incorporating automotive electrification program ramps and micro-LED wafer bonding investment cycles. Forecast inputs included silver-sintering paste price trajectories and thermal cycling test duration compression rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU RoHS enforcement acceleration or MFDS biocompatibility standard revisions. Material deviation in substrate capacity expansion schedules or silver supply chain disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
3D Semiconductor Packaging Market
Semiconductor Packaging
Through-Silicon via (TSV) IC Packaging Market
Semiconductor Packaging
Quad-Flat-No-Lead Packaging (QFN) Market
Semiconductor Packaging
ESD Stackable Boxes Market
Semiconductor Packaging
System in Package (Sip) Technology Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Global Semiconductor Equipment Packaging and Test Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
Asia-Pacific Quad-Flat-No-Lead Packaging Market
Semiconductor Packaging
IC Packaging and Testing Market
Semiconductor Packaging
System in Package (SIP) Die Market
Semiconductor Packaging
3D TSV Packages Market
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
Wafer Level Packaging (WPL) Market