
 Glass Substrate in Semiconductor Market | 2026-2036
Glass Substrate in Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Substrate in Semiconductor Market Foresight
South Korea is tilting the competitive map through Pyeongtaek and Yongin capacity expansions targeting glass-core substrate production. Samsung Electro-Mechanics leverages its captive display glass heritage to anchor advanced packaging roadmaps. Corning Incorporated sustains R&D intensity in fused silica formulations for extreme ultraviolet lithography compatibility. Absolics differentiates through laser-drilled via architectures purpose-built for chiplet integration.
Glass substrate in semiconductor refers to engineered glass panels serving as interposer or carrier substrates, typically manufactured via precision grinding, chemical strengthening, and through-glass via drilling to achieve sub-10 micrometer flatness and thermal expansion coefficients matching silicon. Its primary purpose is enabling higher interconnect density and thermal stability than organic alternatives in advanced packaging architectures. Aluminosilicate glass dominates current volume owing to its ion-exchange strengthenability and established supply chains from display industry crossover. Fused silica commands premium positioning where near-zero thermal expansion protects overlay accuracy during photolithography steps. Specialty glass variants, including boron-doped formulations, occupy nascent but expanding roles in microelectromechanical systems hermetic sealing.
Japan's METI and South Korea's Ministry of Trade, Industry and Energy each administer semiconductor material subsidies that directly influence glass substrate qualification timelines and foundry adoption thresholds. The EPA and OSHA in the United States impose particulate and chemical handling standards that shape cleanroom manufacturing economics and facility location decisions. Stakeholders must monitor which regulatory fast-track programs in Seoul, Tokyo, and Washington actually translate to volume purchase commitments rather than pilot-line announcements.
Market Dynamics
Advanced packaging roadmaps at Samsung and Intel are compressing qualification cycles for glass-core substrates, forcing suppliers to synchronize R&D timelines with foundry tape-out schedules rather than traditional material development cadences.
Growth Catalysts
- High-performance computing packaging:AI accelerator chiplet architectures demand glass interposers for thermal and electrical performance beyond organic substrate limits.
- South Korea's Pyeongtaek cluster expansion:Concentrated pilot-line investments by memory manufacturers create demand density that justifies dedicated glass substrate capacity.
- METI semiconductor revitalization policies:Japan's material subsidies accelerate domestic qualification programs for EUV-compatible fused silica formulations.
Market Restraints
- Aluminosilicate supply concentration:Display glass crossover dependence limits pricing leverage and creates single-source vulnerability for ion-exchange strengthenable substrates.
- Fused silica technical limitations:Near-zero thermal expansion properties require specialized handling protocols that constrain throughput in standard semiconductor fabrication facilities.
- OSHA particulate standards:US cleanroom manufacturing economics face cost escalation from chemical handling compliance requirements during precision grinding operations.
Strategic Opportunities
- Microelectromechanical systems hermetic sealing:Boron-doped glass variants address unmet packaging needs in automotive sensor and medical device applications.
- Intel Ohio fab investments:Domestic US substrate qualification programs create first-mover advantage for suppliers establishing regional technical service presence.
- Through-glass via lithography convergence:Laser drilling and photolithography process integration enables sub-10 micrometer feature resolution for next-generation chiplet density.
Industry Challenges
- Photolithography overlay accuracy certification:Thermal expansion coefficient matching validation extends qualification timelines beyond traditional organic substrate adoption curves.
- Chemical strengthening process integration:Ion-exchange equipment capex requirements strain mid-tier substrate manufacturers attempting glass-core entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Substrate in Semiconductor Market |
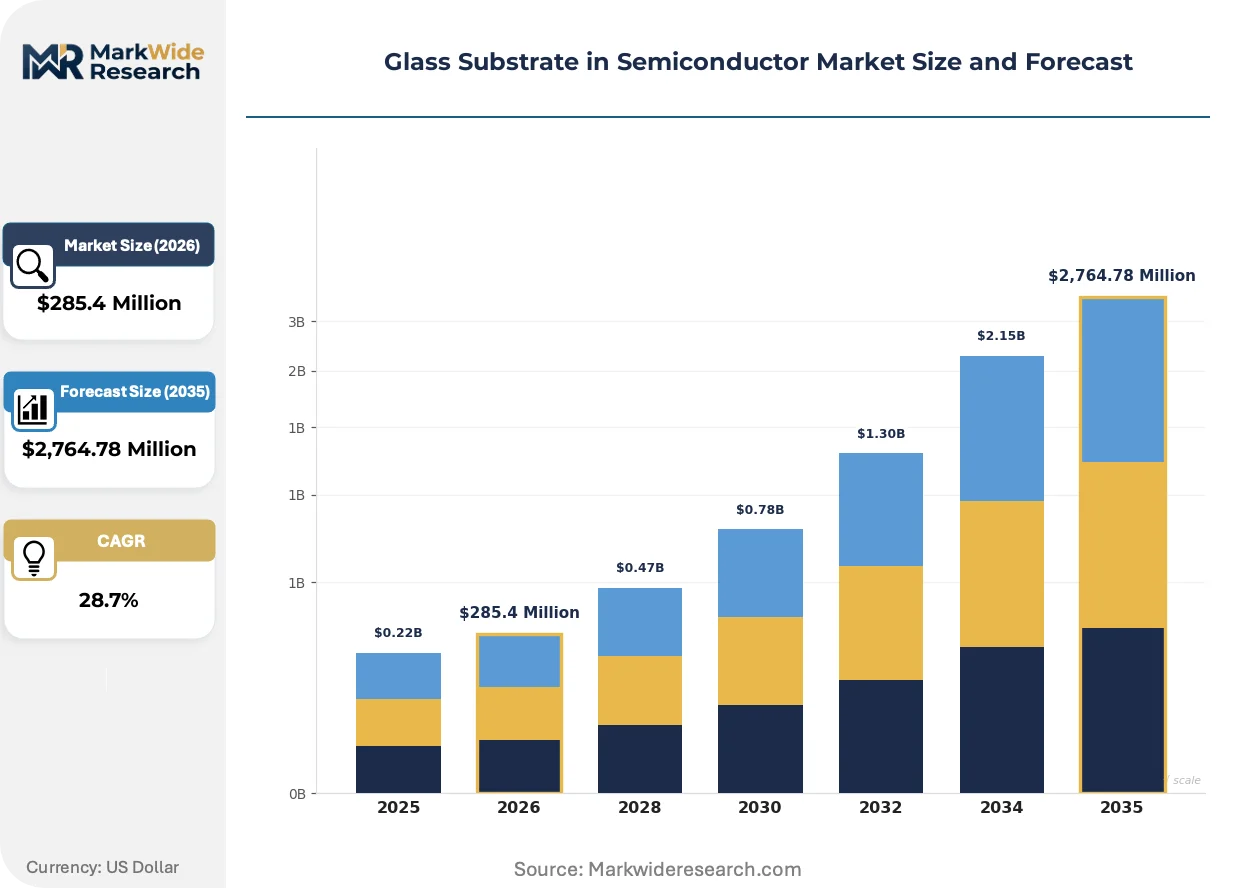
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $2,764.78 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminosilicate Glass, Borosilicate Glass, Soda-lime Glass, Fused Silica, Specialty Glass Technology: Thin Film Transistor, Photolithography, Chemical Vapor Deposition, Atomic Layer Deposition, Etching Application: Display Panels, Microelectromechanical Systems, Integrated Circuits, Sensors, Logic Devices End User: Foundries, Chip Designers, Assembly & Packaging Units, Test Laboratories, Semiconductor Fabricators |
| Companies Covered | Nippon Electric Glass, LG Innotek, Corning Incorporated, Intel Corporation, Absolics, AGC Inc., Samsung Electro-Mechanics, Applied Materials, SCHOTT AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Substrate in Semiconductor Market Shifts & Advancements
Glass substrate manufacturing is pivoting from display-industry process inheritance toward semiconductor-specific precision requirements, with equipment vendors and materials scientists co-developing next-generation formulations.
Laser-drilled through-glass via architectures are rendering obsolete mechanical drilling methods for high-density interconnect applications. Advanced packaging foundries in South Korea's Yongin corridor have adopted femtosecond laser systems for sub-50 micrometer via formation. This transition is rendering obsolete capital equipment investments in mechanical drill platforms across substrate fabrication facilities.
Japan's METI administers subsidy programs that tie glass substrate qualification timelines to domestic foundry adoption thresholds. Equipment purchase incentives require suppliers to co-locate technical service capabilities within Japanese semiconductor clusters. Memory manufacturers in the Pyeongtaek region are accelerating parallel qualification programs to maintain supply chain optionality.
Consolidated procurement contracts now dominate substrate sourcing for high-volume packaging operations. Memory and logic foundries are displacing fragmented supplier relationships with multi-year volume commitments tied to roadmap alignment. South Korea's Ministry of Trade, Industry and Energy fast-track programs are reinforcing this concentration through purchase commitment verification requirements.
Glass Substrate in Semiconductor Market Segmentation
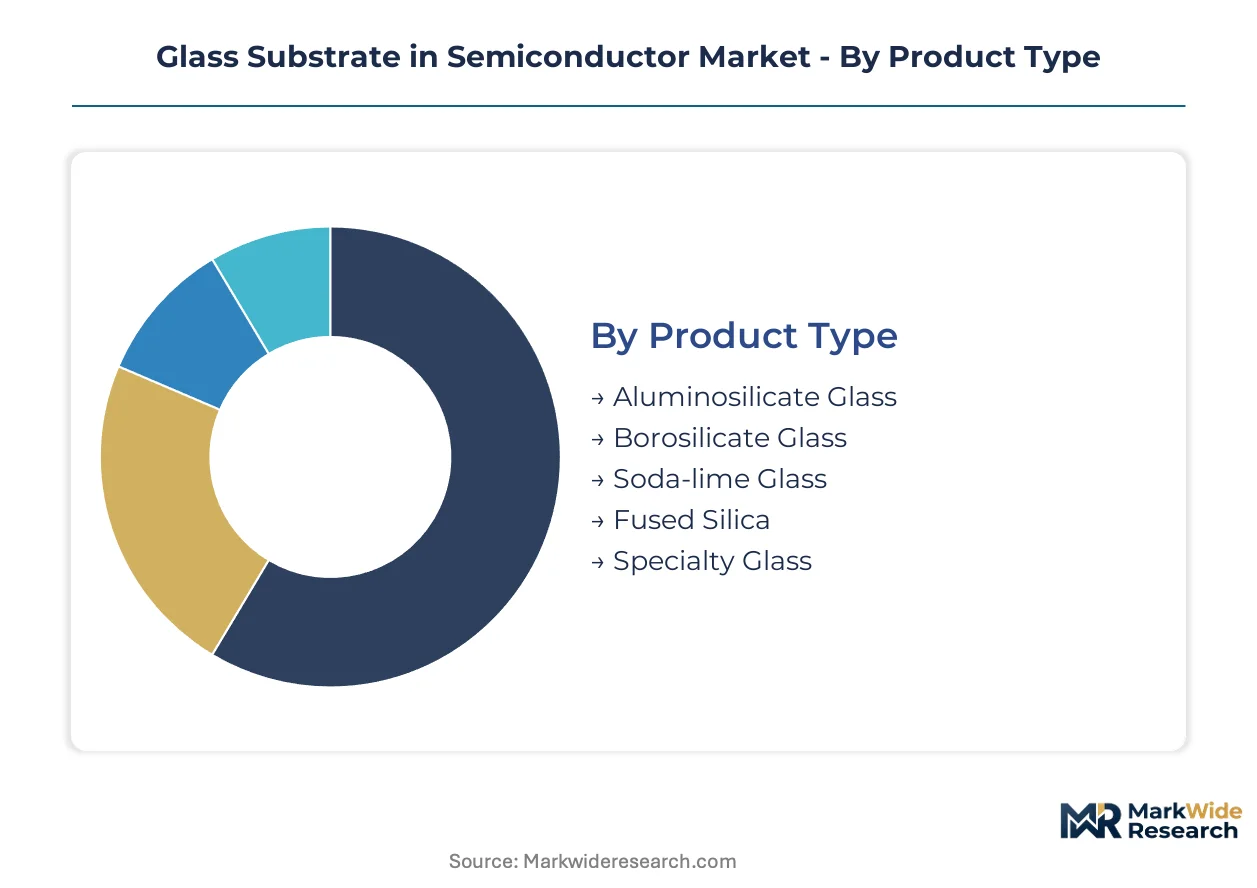
Glass substrate segmentation reveals how material composition, fabrication technology, and downstream application each impose distinct performance thresholds. Suppliers must align formulation expertise with specific foundry qualification requirements rather than pursuing universal platform strategies.
Product Type:
Cost tier determines qualification accessibility, with ion-exchange strengthenability and thermal expansion properties separating premium formulations from commodity crossover materials.
- Aluminosilicate Glass:Ion-exchange chemistry enables surface compression layers that withstand thermal cycling in advanced packaging. Samsung Electro-Mechanics and Corning dominate qualification programs for this formulation in South Korea's Pyeongtaek cluster, where memory manufacturers demand proven supply chains over experimental alternatives.
- Fused Silica:Near-zero thermal expansion coefficient protects photolithography overlay accuracy during EUV exposure sequences. METI subsidy programs in Japan accelerate domestic qualification for this premium tier, though specialized handling protocols constrain throughput in standard fabrication facilities.
- Borosilicate Glass:Thermal shock resistance suits hermetic sealing applications without requiring ion-exchange equipment investment.
- Soda-lime Glass:Display industry crossover volumes support cost-sensitive prototyping and non-hermetic carrier applications.
- Specialty Glass:Boron-doped and rare-earth formulations address emerging MEMS and sensor packaging requirements.
Aluminosilicate commands the established base. The steepest expansion runs through fused silica as EUV lithography penetration accelerates.
Technology:
Application maturity separates production-proven deposition methods from emerging patterning approaches still seeking foundry integration.
- Photolithography:Stepper and scanner compatibility demands sub-10 micrometer flatness specifications that glass substrates achieve through precision grinding and chemical strengthening. Intel's Ohio fab investments include dedicated qualification tracks for photolithography-compatible glass interposers.
- Etching:Wet and dry etch process integration enables through-glass via formation with sidewall roughness control critical for high-density interconnect scaling. Yongin corridor foundries have adopted plasma etch platforms specifically for glass-core substrate patterning.
- Thin Film Transistor:Backplane fabrication heritage from display manufacturing transfers directly to active interposer applications.
- Chemical Vapor Deposition:Dielectric layer uniformity supports multi-layer redistribution structures.
- Atomic Layer Deposition:Angstrom-level thickness control enables barrier coatings for hermetic packaging.
Photolithography retains the production volume leadership. Etching is climbing the fastest as via density requirements intensify.
Application:
Volume concentration varies sharply between established display markets and emerging semiconductor packaging segments.
- Integrated Circuits:Chiplet architectures in AI accelerators drive glass interposer adoption where organic substrate thermal and electrical limits constrain performance. SK Hynix pilot lines in South Korea validate glass-core substrates for high-bandwidth memory stacking.
- Logic Devices:Advanced packaging roadmaps at Intel and Samsung compress qualification cycles, forcing material suppliers to synchronize development with foundry tape-out schedules rather than traditional material cadences.
- Display Panels:OLED and microLED backplanes sustain volume demand for established glass substrate specifications.
- Microelectromechanical Systems:Hermetic sealing requirements favor boron-doped glass variants in automotive sensor applications.
- Sensors:Miniaturization trends push toward thinner glass substrates with through-glass via integration.
Display panels anchor current shipment volumes. Integrated circuits are gaining share fastest as advanced packaging penetration accelerates.
End User:
Procurement sophistication separates captive substrate operations from merchant market relationships.
- Foundries:Multi-year volume commitments now dominate sourcing for high-volume packaging operations, displacing fragmented supplier relationships. South Korea's Ministry of Trade, Industry and Energy fast-track programs reinforce this concentration through purchase commitment verification requirements.
- Assembly & Packaging Units:OSAT qualification timelines determine substrate adoption thresholds, with technical service proximity influencing supplier selection more than price differentiation.
- Semiconductor Fabricators:IDM substrate strategies vary between captive production and strategic outsourcing.
- Chip Designers:Fabless architects specify interposer requirements without direct substrate procurement responsibility.
- Test Laboratories:Reliability validation services create secondary demand for standardized substrate samples.
Foundries dominate procurement authority. Assembly and packaging units are expanding their sourcing influence fastest as OSAT consolidation proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass substrate supply chains concentrate in three East Asian manufacturing corridors where display-industry heritage and semiconductor packaging roadmaps intersect. South Korea's Pyeongtaek cluster and Japan's Nagoya-Osaka axis anchor current capacity, while the United States builds domestic alternatives through Ohio and Arizona fab investments.
South Korea
Memory manufacturers in Yongin and Pyeongtaek drive pilot-line expansion for glass-core substrates targeting high-bandwidth memory stacking. The Ministry of Trade, Industry and Energy fast-track programs require verified purchase commitments before subsidy disbursement. Samsung Electro-Mechanics leverages captive display glass expertise to anchor advanced packaging supply chains in the Seoul Capital Area.
Japan
Domestic foundries and materials suppliers coordinate fused silica qualification for EUV lithography compatibility. METI semiconductor revitalization policies tie equipment purchase incentives to technical service co-location requirements. Nagoya and Osaka host concentrated substrate R&D facilities serving domestic logic and memory fabricators.
United States
Intel's Ohio fab investments create first-mover opportunities for substrate suppliers establishing regional technical presence. EPA particulate standards and OSHA chemical handling requirements shape cleanroom manufacturing economics. The Phoenix-Tucson corridor in Arizona attracts packaging-focused substrate qualification programs.
Taiwan
OSAT consolidation drives consolidated procurement contracts for glass interposer volumes. The Hsinchu Science Park anchors advanced packaging R&D coordination between foundries and substrate specialists. Domestic regulators emphasize supply chain security reviews for critical materials.
Germany
Automotive sensor packaging creates niche demand for hermetic sealing glass variants. ECHA REACH compliance requirements influence formulation chemistry decisions for European market access. Dresden and Bavaria host MEMS packaging clusters exploring boron-doped glass applications.
Glass Substrate in Semiconductor Market Competitive Landscape
Display-industry incumbents and semiconductor-focused entrants split the market along heritage and specialization lines. Samsung Electro-Mechanics and Corning leverage captive glass manufacturing scale against Absolics and pure-play substrate specialists. Three archetypes dominate: diversified materials conglomerates with display crossover capabilities, captive semiconductor supplier divisions, and venture-backed specialists in laser-drilled via architectures. Competitive dynamics center on foundry qualification timeline acceleration and regional technical service proximity rather than price-based rivalry.
Within the diversified materials tier, Corning Incorporated and AGC Inc. represent display-industry heritage applied to semiconductor packaging requirements. Samsung Electro-Mechanics exemplifies captive supplier strategy leveraging internal demand from memory and logic roadmaps. Absolics occupies the specialist position with purpose-built architectures for chiplet integration. SCHOTT AG and Nippon Electric Glass sit within European and Japanese materials traditions respectively. LG Innotek bridges display and semiconductor applications through Korean industrial group coordination.
| Leading Market Players |
|---|
| Nippon Electric Glass |
| LG Innotek |
| Corning Incorporated |
| Intel Corporation |
| Absolics |
| AGC Inc. |
| Samsung Electro-Mechanics |
| Applied Materials |
| SCHOTT AG |
| Others |
Supply & Pricing Matrix
Japanese fused silica concentration anchors premium substrate pricing, with METI subsidy thresholds determining which suppliers capture margin pools in EUV-compatible formulations. Aluminosilicate crossover from display glass feeds mid-tier pricing, while Korean memory foundry procurement contracts compress spot-market leverage for non-qualified entrants.
Pricing Analysis
METI equipment purchase incentives dictate the pricing tier structure across Japanese domestic qualification tracks. Three-tier pricing structure across premium, standard, and economy levels separates EUV-grade fused silica from ion-exchange aluminosilicate and commodity soda-lime carrier substrates. Cost compression in standard-tier aluminosilicate is intensifying because Samsung Electro-Mechanics and Corning anchor volume contracts in Pyeongtaek. Memory manufacturers exhibit highest price sensitivity due to consolidated procurement mandates, while logic foundries prioritize photolithography overlay certification over unit cost.
Supply Chain Analysis
Export controls on extreme ultraviolet lithography equipment limit fused silica substrate flows to Chinese foundries, reshaping regional allocation patterns. Manufacturing concentrates in Japan, South Korea, and the United States, with Nagoya-Osaka and Yongin-Pyeongtaek corridors feeding memory and logic packaging lines. Raw material supply draws from high-purity quartz deposits, ion-exchange salt chemistry, and precision grinding consumables. Single-source vulnerability runs through aluminosilicate ion-exchange equipment vendors. Distribution runs through foundry-direct technical service relationships rather than merchant distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass substrate demand fragments across chiplet architectures, EUV lithography roadmaps, and MEMS hermetic sealing applications, creating specialist niches beyond display-industry scale economics.
For Market Incumbents: Entrench through captive ion-exchange equipment capacity in Seoul Capital Area corridors and fused silica technical service co-location within Japanese semiconductor clusters. Defend against Absolics laser-drilled via specialists by accelerating through-glass via lithography convergence roadmaps with Intel and Samsung foundry partners. For New Entrants and Emerging Players: Pursue boron-doped specialty glass variants for automotive sensor hermetic sealing in German MEMS packaging clusters, where ECHA REACH compliance creates formulation barriers for Asian incumbents. Target Ohio technical service presence alongside Intel substrate qualification programs as the most penetrable geographic entry point. For Investors and Strategic Acquirers: Capital is best deployed toward laser-drilled via architecture specialists with foundry qualification timelines already initiated, rather than greenfield ion-exchange capacity plays. Long-term viability hinges on EUV lithography penetration rates in logic foundries. Watch for METI subsidy disbursement verification thresholds as the inflection signal for Japanese domestic supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Through-Glass Via Lithography Convergence | Femtosecond laser integration with photolithography enables sub-10 micrometer feature resolution for chiplet density scaling. |
| Ion-Exchange Equipment Capacity Expansion | Chemical strengthening process integration requires dedicated capex that strains mid-tier manufacturers attempting glass-core entry. |
| EUV-Compatible Fused Silica Qualification | METI subsidy programs accelerate domestic Japanese programs for near-zero thermal expansion formulations protecting overlay accuracy. |
| Regional Technical Service Co-Location | Equipment purchase incentives in Japan and purchase commitment verification in Korea require supplier proximity to foundry clusters. |
| Boron-Doped Specialty Glass Development | Hermetic sealing applications in automotive sensors and medical devices address unmet packaging needs beyond mainstream interposers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade data, foundry capex disclosures, and METI subsidy program documentation. Interviews with advanced packaging engineers, substrate procurement leads at memory manufacturers, ion-exchange equipment vendors, and EUV lithography specialists inform qualification timeline assumptions. Bottom-up substrate volume estimates triangulate against top-down foundry packaging capacity projections.
Forecast inputs include material composition segmentation, fabrication technology adoption curves, and downstream application penetration rates across the analysis window. Modeled dimensions span glass type, patterning technology, end-use device category, and procurement authority archetype. CAGRs derive from foundry roadmap synchronization requirements and subsidy disbursement pacing rather than historical organic substrate adoption curves. EUV lithography penetration and chiplet architecture deployment serve as primary demand-side inputs.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or memory pricing recoveries would shift the trajectory. Forecasts reflect documented assumptions regarding foundry qualification thresholds and regulatory fast-track program efficacy. Material shifts in export control regimes or ion-exchange equipment vendor consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Polysilicon for Solar Semiconductor Market
Semiconductor Material
Global Electronic Materials Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
PP Capacitor Films Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
Yttrium Oxide Market
Semiconductor Material
Tellurium Market
Semiconductor Material
Global Silicon Carbide (SIC) Market
Semiconductor Material
Global Strontium Market