
 Europe Touch Screen Controllers Market | 2026-2036
Europe Touch Screen Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Touch Screen Controllers Market Foresight
Buyer concentration in European automotive OEMs is decoupling from traditional consumer electronics volumes as fleet electrification reorders procurement priorities. STMicroelectronics leverages its Grenoble R&D footprint to sustain capacitive controller leadership for haptic dashboards. NXP Semiconductors anchors high-reliability automotive supply through its Eindhoven design center. Texas Instruments Incorporated competes across industrial automation with extended-temperature product lines.
Europe touch screen controllers are mixed-signal integrated circuits that translate capacitive or resistive panel disturbances into digital coordinates, typically operating at supply voltages between 1.8V and 3.3V with sampling rates exceeding 100Hz for gesture responsiveness. These devices serve as the primary human-machine interface in applications ranging from medical imaging consoles to production line terminals. Capacitive controllers dominate value capture owing to their prevalence in premium automotive and medical displays, while resistive architectures retain share in industrial settings where gloved operation and electromagnetic immunity outweigh multi-touch sophistication. Gesture recognition technology is gaining structural importance as automakers integrate air-touch and proximity sensing into cabin control concepts.
REACH and the EU Green Deal restrict hazardous substances in controller substrates and mandate supply chain disclosure for conflict minerals, elevating compliance costs for non-European suppliers. CE marking under the Radio Equipment Directive governs electromagnetic compatibility for wireless-enabled touch modules entering the European Economic Area. ECHA substance evaluations are accelerating substitution timelines for legacy flame retardants in flexible printed circuit assemblies. Stakeholders must monitor evolving CSRD reporting obligations that will extend material provenance requirements deep into semiconductor packaging tiers.
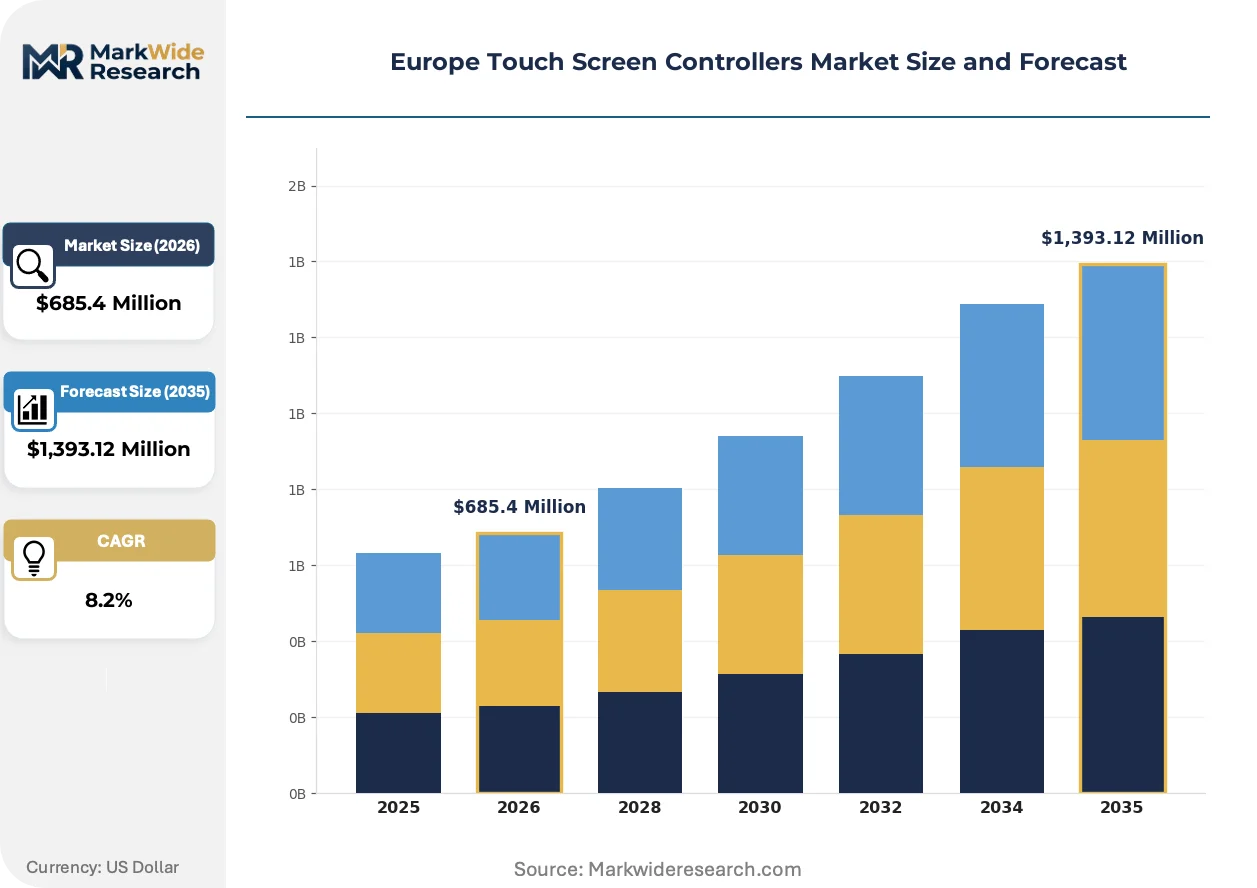
Market Dynamics
Fleet electrification across Germany, France, and Italy is reordering automotive procurement priorities, decoupling touch controller demand from traditional consumer electronics volumes as OEMs prioritize haptic-enabled cabin interfaces.
Growth Catalysts
- EU Green Deal material mandates:Halogen-free substrate requirements under REACH compliance are accelerating supplier qualification programs for sustainable controller packaging.
- Capacitive multi-touch migration:Premium automotive clusters in Stuttgart and Ingolstadt are displacing resistive panels with gesture-capable interfaces for infotainment control.
- Medical imaging console refresh:Diagnostic equipment manufacturers in Switzerland and the Netherlands are retrofitting legacy interfaces with projected-capacitive controllers for sterile-field operation.
Market Restraints
- Indium tin oxide supply concentration:Transparent conductor sourcing from East Asian refiners exposes European controller fabricators to price volatility and export restriction risk.
- REACH substance evaluation timelines:ECHA's accelerated flame retardant substitution protocols are compressing redesign cycles for flexible printed circuit assemblies.
- Resistive technology lock-in:Industrial automation buyers in heavy manufacturing retain legacy four-wire architectures where electromagnetic immunity outweighs multi-touch functionality.
Strategic Opportunities
- Poland and Czechia manufacturing expansion:Automotive electronics corridors east of Germany offer untapped controller assembly capacity with EU structural fund access.
- Air-touch proximity sensing:Cabin hygiene concerns are driving German OEM interest in non-contact gesture stacks combining infrared and capacitive sensing.
- CSRD supply chain disclosure:Extended material provenance requirements will favor European packaging houses with established conflict mineral traceability systems.
Industry Challenges
- Mixed-signal design talent scarcity:Analog-digital integration expertise for high-sampling-rate controllers concentrates in Grenoble and Eindhoven, constraining expansion timelines.
- CE marking synchronization:Radio Equipment Directive electromagnetic compatibility testing for wireless-enabled touch modules creates certification bottlenecks for multi-protocol devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Touch Screen Controllers Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Resistive, Infrared, Optical End User: Consumer Electronics, Automotive, Healthcare, Industrial Automation Technology: Multi-Touch, Single-Touch, Gesture Recognition, Voice Control Size: Small, Medium, Large, Custom |
| Companies Covered | Texas Instruments Incorporated, STMicroelectronics, NXP Semiconductors, Integrated Device Technology, Microchip Technology Incorporated, Renesas Electronics Corporation, Analog Devices, Synaptics Incorporated, Samsung Electronics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Touch Screen Controllers Market Shifts & Advancements
Distributed sensing architectures and regulatory material mandates are restructuring how touch controllers are designed, sourced, and integrated across European automotive and industrial value chains.
Haptic feedback integration is decentralizing the traditional separation between display and input subsystems. Piezoelectric actuator controllers now embed directly beneath capacitive sensing layers, eliminating discrete vibration motor modules. German luxury OEMs are qualifying these consolidated stacks for center-console deployment, compressing supplier tier structures from three layers to two.
REACH substance restrictions are forcing reformulation of flexible printed circuit dielectrics and solder mask materials. ECHA evaluations of legacy brominated flame retardants are accelerating substitution timelines, with medical device manufacturers in Switzerland facing the most compressed compliance windows due to parallel MDR recertification requirements.
Automotive buyers are consolidating touch controller procurement under long-term framework agreements tied to platform lifecycle commitments. Tier-1 suppliers in Munich and Stuttgart are displacing spot purchasing with captive sourcing arrangements, transferring inventory risk to semiconductor packaging houses. This concentration is most visible in electric vehicle programs where infotainment cluster designs remain fixed across model generations.
Europe Touch Screen Controllers Market Segmentation
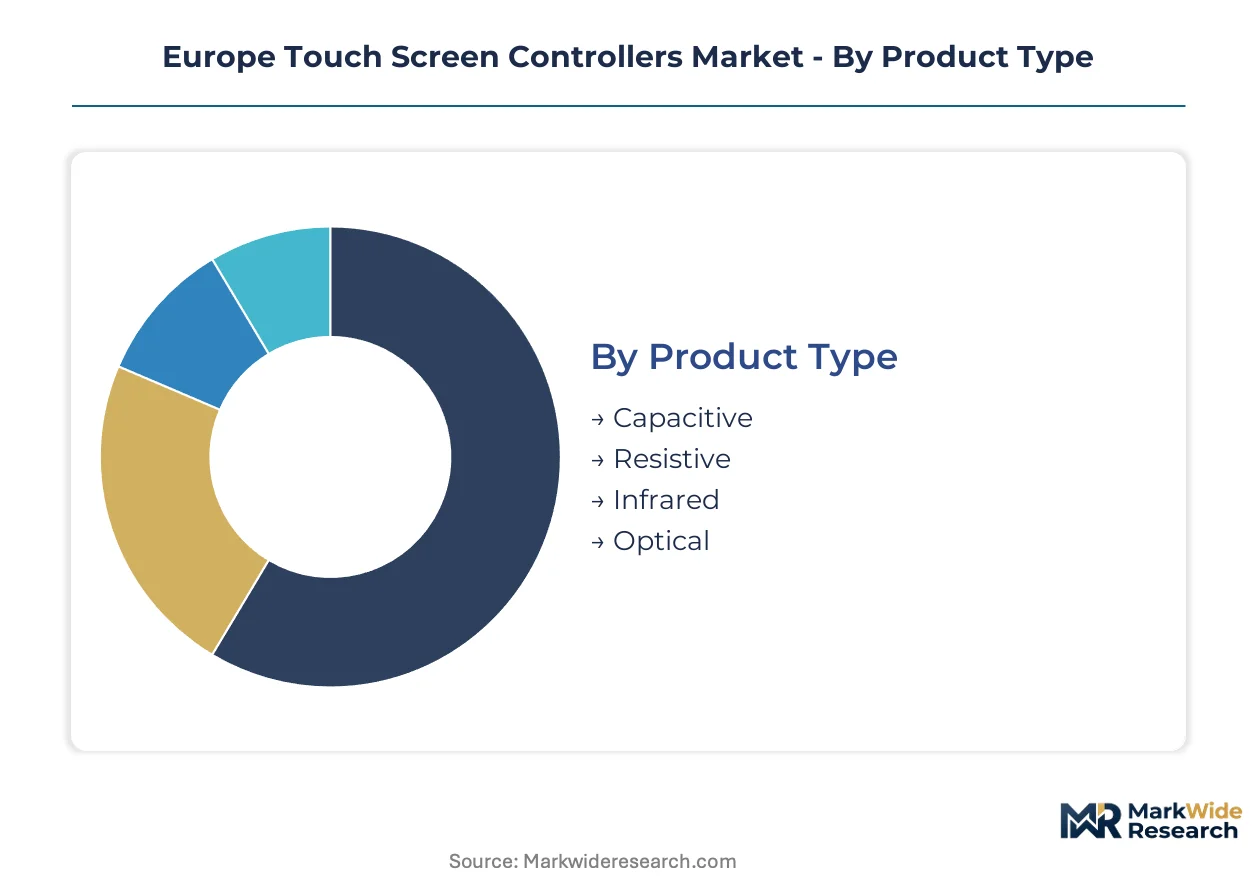
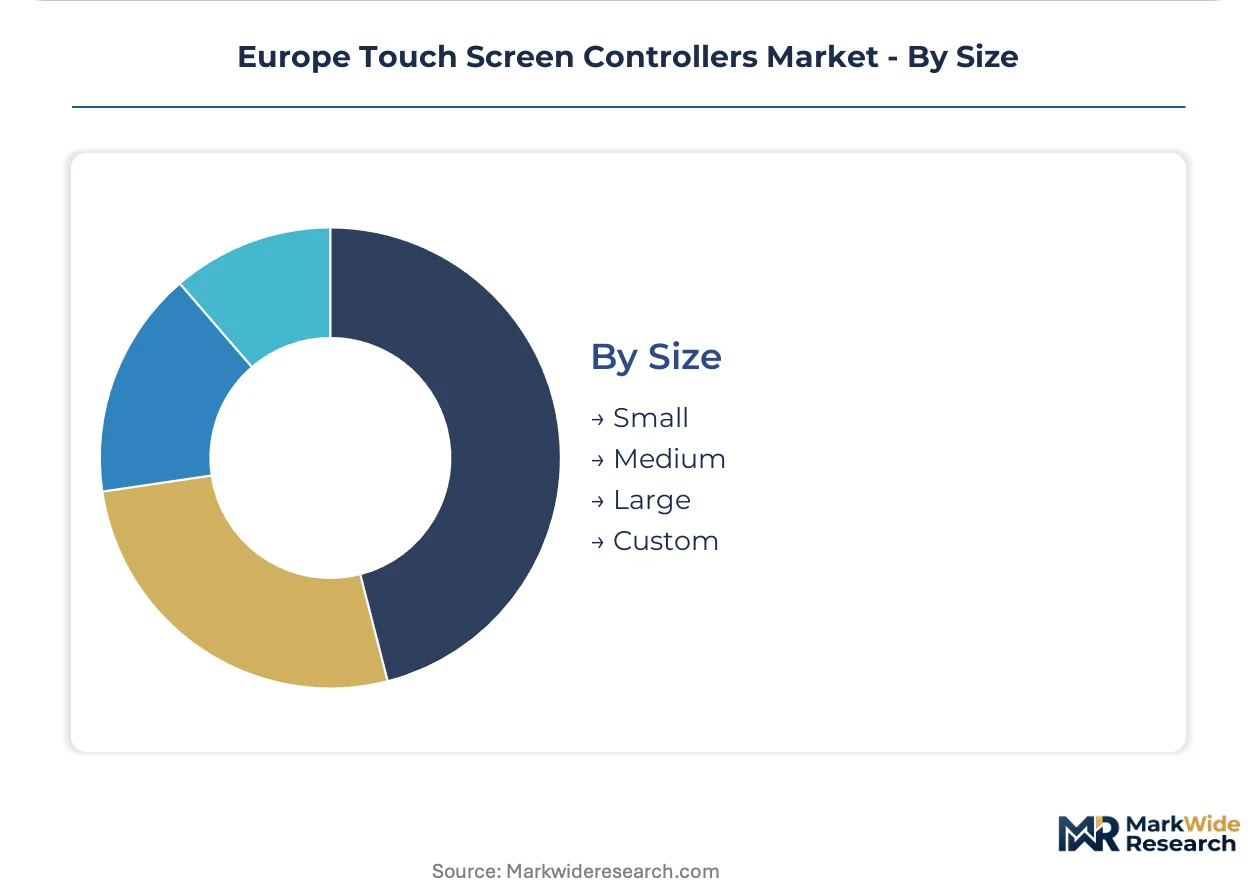
Touch controller segmentation in Europe reflects divergent technical requirements across automotive electrification, medical sterilization protocols, and industrial electromagnetic immunity standards. Procurement patterns increasingly favor application-specific qualification over generic multi-purpose controllers.
Product Type:
Controller architectures differentiate by sensing physics and electrode configuration, with capacitive designs commanding premium positioning in gesture-intensive applications.
- Capacitive:Projected-capacitive controllers detect finger position through mutual-capacitance or self-capacitance arrays etched on indium tin oxide layers. Stuttgart and Ingolstadt automotive clusters specify these for haptic-enabled infotainment clusters in electric vehicle platforms.
- Resistive:Four-wire and five-wire membrane stacks measure voltage division across conductive layers when pressure deforms a flexible top sheet. Heavy manufacturing facilities in Germany's Ruhr region specify resistive controllers for gloved operation near welding equipment.
- Infrared:LED-phototransistor arrays detect beam interruption without surface contact. Cleanroom equipment manufacturers in Switzerland deploy these for sterile-field medical imaging consoles.
- Optical:Camera-based or vision-processing controllers interpret surface interaction through image recognition. Kiosk integrators in France specify optical controllers for vandal-resistant public access terminals.
Mature deployment sits with resistive controllers in legacy industrial settings. Newer deployment is concentrated in capacitive controllers for automotive cabin electrification.
End User:
Demand concentration tracks capital expenditure cycles and regulatory recertification timelines across European manufacturing corridors.
- Consumer Electronics:Smartphone and tablet OEMs in the Netherlands specify ultra-low-power controllers with sub-millisecond wake latency for always-on displays.
- Automotive:Tier-1 suppliers along Munich-Stuttgart-Ingolstadt corridors procure automotive-qualified controllers with AEC-Q100 Grade 2 temperature ratings and functional safety documentation for ISO 26262 compliance.
- Healthcare:Diagnostic imaging OEMs in Switzerland and the Netherlands integrate projected-capacitive controllers with antimicrobial surface treatments for sterile-field operation.
- Industrial Automation:Production line integrators specify extended-temperature controllers with reinforced electromagnetic immunity for programmable logic interface panels.
Procurement volume concentrates in automotive end users. Fastest qualification timelines sit with healthcare manufacturers facing parallel MDR and REACH substance deadlines.
Technology:
Interface sophistication tiers separate commodity single-point detection from premium gesture and proximity stacks.
- Multi-Touch:Controllers resolving simultaneous contact points through mutual-capacitance matrix scanning. German luxury OEMs specify ten-point tracking for center-console pinch-to-zoom navigation.
- Single-Touch:Basic coordinate reporting from single contact detection. Industrial panel vendors in Italy retain single-touch architectures for cost-sensitive human-machine interface retrofits.
- Gesture Recognition:Proximity and air-touch detection combining capacitive sensing with infrared time-of-flight. Cabin hygiene concerns are accelerating German OEM interest in non-contact stack qualification.
- Voice Control:Audio front-end integration with touch controllers for multimodal input fusion. Infotainment system architects in France specify these for hands-free operation compliance with distracted-driving regulations.
Volume manufacturing runs through single-touch controllers. Gesture recognition is climbing the fastest as automakers integrate air-touch into next-generation cabin concepts.
Size:
Panel dimensions dictate controller channel count, scan frequency requirements, and substrate routing complexity.
- Small:Controllers for panels under five inches diagonal, typical in wearable devices and handheld instrumentation. Swiss medical device manufacturers specify small-form-factor controllers for portable diagnostic equipment.
- Medium:Five-to-fifteen inch panels dominating automotive center stacks and industrial terminals. Czechia-based EMS providers assemble medium-format controllers for German automotive Tier-1s.
- Large:Controllers exceeding fifteen inches for interactive whiteboards and digital signage. French railway operators specify large-format controllers for passenger information kiosks in SNCF stations.
- Custom:Non-rectangular or irregular aspect ratio panels requiring firmware-customized scan matrices. Specialty vehicle manufacturers in Italy commission custom controllers for curved dashboard integration.
Standardized production concentrates in medium sizes. Custom formats are expanding most quickly as automotive interior designers abandon rectangular display conventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electrification programs across Germany, France, and Italy are concentrating controller procurement within established manufacturing corridors. Tier-1 suppliers in Munich, Stuttgart, and Ingolstadt dominate volume allocation for haptic-enabled cabin interfaces.
Germany
Electric vehicle platform launches at BMW Group and Mercedes-Benz Group are driving capacitive controller demand for center-stack infotainment clusters. REACH compliance deadlines under ECHA substance evaluations are accelerating halogen-free substrate qualification timelines for Stuttgart-based packaging houses. The Munich-Stuttgart-Ingolstadt automotive electronics corridor hosts the continent's densest concentration of touch controller design and assembly operations.
France
Renault Group and Stellantis are expanding projected-capacitive deployments across BEV and PHEV lineups for gesture-capable human-machine interfaces. CE marking requirements under the Radio Equipment Directive govern electromagnetic compatibility certification for wireless-enabled touch modules entering the French market. Auvergne-Rhône-Alpes hosts specialized EMS providers serving Lyon-based automotive Tier-1s with medium-format controller assembly.
Italy
Ferrari and Lamborghini are commissioning custom-form-factor controllers for curved dashboard integration in next-generation supercar platforms. EU Green Deal material traceability mandates are pushing Modena-area specialty vehicle manufacturers toward conflict-mineral-disclosure supply chains. Emilia-Romagna's precision manufacturing cluster supports low-volume, high-complexity controller customization for premium automotive applications.
Switzerland
Diagnostic imaging OEMs in Basel and Zurich are retrofitting legacy interfaces with projected-capacitive controllers for sterile-field operation in surgical suites. Parallel MDR recertification and REACH substance deadlines are compressing qualification timelines for medical device controller suppliers. Swissmedic oversight of antimicrobial surface treatments adds regulatory layering to healthcare controller specifications.
Netherlands
Philips HealthSuite and ASML are driving demand for ultra-low-power controllers with sub-millisecond wake latency in portable diagnostic and lithography equipment. CSRD reporting obligations will extend material provenance requirements into semiconductor packaging tiers serving Eindhoven-based technology groups. The Brainport Eindhoven ecosystem anchors mixed-signal design expertise for high-sampling-rate medical and industrial controllers.
Europe Touch Screen Controllers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized automotive qualification and medical sterilization protocols. The vendor base stratifies across three layers: integrated semiconductor conglomerates with captive controller divisions, fabless mixed-signal specialists, and automotive-qualified packaging houses. Two dominant competitive moves are reshaping positioning: long-term framework agreements tying controller supply to electric vehicle platform lifecycles, and backward integration into indium tin oxide touch sensor fabrication.
Within the integrated semiconductor tier, STMicroelectronics, NXP Semiconductors, and Texas Instruments Incorporated exemplify divergent geographic anchoring strategies. STMicroelectronics leverages its Grenoble R&D footprint to sustain capacitive controller leadership for haptic dashboard applications. NXP Semiconductors anchors high-reliability automotive supply through its Eindhoven design center and AEC-Q100 qualification infrastructure. Texas Instruments Incorporated competes across industrial automation with extended-temperature product lines, representing the diversified conglomerate archetype that spans multiple end-use verticals without vertical specialization.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| STMicroelectronics |
| NXP Semiconductors |
| Integrated Device Technology |
| Microchip Technology Incorporated |
| Renesas Electronics Corporation |
| Analog Devices |
| Synaptics Incorporated |
| Samsung Electronics |
| Others |
Supply & Pricing Matrix
AEC-Q100 Grade 2 certification bifurcation separates automotive-qualified controllers from industrial commodity units, with this divergence manifesting in both margin structures and supply chain configurations. Premium automotive Tier-1 procurement in Stuttgart and Ingolstadt commands captive sourcing arrangements with packaging houses, while industrial buyers in Germany's Ruhr region transact through spot markets with Czechia-based EMS providers.
Pricing Analysis
Volume manufacturing concentrates in single-touch resistive controllers for cost-sensitive industrial retrofits, while margin capture sits with multi-touch capacitive stacks for electric vehicle infotainment clusters. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with automotive OEM framework agreements compressing supplier margins through inventory risk transfer. Pricing pressure stems from indium tin oxide supply concentration among East Asian refiners, exposing European fabricators to commodity volatility. Healthcare manufacturers in Switzerland exhibit lowest price sensitivity due to parallel MDR and REACH compliance deadlines, while Italian industrial panel vendors retain highest sensitivity for four-wire resistive retrofits.
Supply Chain Analysis
Freight cost escalation from East Asian indium tin oxide refiners through Rotterdam port corridors elevates landed costs for transparent conductor substrates. Controller assembly concentrates in Germany, Czechia, and Poland, with Grenoble and Eindhoven anchoring mixed-signal design expertise. Raw material dependencies center on indium tin oxide layers, halogen-free flexible printed circuit substrates, and piezoelectric actuator materials. Single-source vulnerability in East Asian transparent conductor sourcing creates structural exposure to export restriction risk. Distribution runs through automotive Tier-1 suppliers in Munich-Stuttgart-Ingolstadt corridors for premium segments, and through industrial distributors for legacy resistive applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over indium tin oxide touch sensor fabrication determines margin sustainability. Players are pursuing captive supply arrangements to secure substrate qualification timelines under REACH substance mandates.
For Market Incumbents: Deploy long-term framework agreements tying controller supply to electric vehicle platform lifecycles, compressing supplier tiers from three layers to two for Stuttgart-based packaging houses. Consolidate procurement relationships with Munich automotive OEMs to defend against emerging fabless specialists qualifying through Czechia EMS expansion. Prioritize halogen-free substrate R&D investment ahead of ECHA flame retardant substitution deadlines. For New Entrants and Emerging Players: Digital-channel qualification platforms offer direct access to healthcare OEMs in Switzerland facing compressed MDR recertification windows. Poland and Czechia automotive electronics corridors present the most penetrable geography with EU structural fund access and established EMS infrastructure. Target sterile-field medical imaging console retrofits with projected-capacitive controllers featuring antimicrobial surface treatments, bypassing incumbent automotive qualification barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated semiconductor conglomerates seeking automotive qualification infrastructure. Long-term viability favors packaging houses with established conflict mineral traceability systems ahead of CSRD supply chain disclosure expansion. Watch ECHA substance evaluation acceleration as the inflection signal for halogen-free substrate formulation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indium Tin Oxide Fabrication | Captive transparent conductor supply insulates margin from East Asian export volatility. |
| Halogen-Free Substrate Qualification | REACH compliance ahead of ECHA deadlines secures automotive Tier-1 procurement continuity. |
| Poland and Czechia EMS Expansion | EU structural fund access reduces assembly cost for medium-format automotive controllers. |
| Air-Touch Proximity Sensing Development | Non-contact gesture stacks address German OEM cabin hygiene requirements. |
| Conflict Mineral Traceability System Implementation | CSRD-ready provenance documentation attracts healthcare OEM procurement in Switzerland. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across automotive Tier-1 procurement managers, EMS operations directors, semiconductor packaging engineers, and healthcare device regulatory affairs leads. ECHA substance evaluation databases, CE marking certification registries, and EU customs import records provided supply-side validation. Bottom-up controller shipment analysis triangulated against top-down automotive electronics expenditure estimates from national statistical offices.
Segment-level granularity modeled product type across capacitive, resistive, infrared, and optical architectures; end user across automotive, healthcare, industrial automation, and consumer electronics; technology across multi-touch, single-touch, gesture recognition, and voice control; and size across small, medium, large, and custom formats. CAGRs derived from regression analysis of historical procurement patterns against electric vehicle platform launch schedules and MDR recertification timelines. Indium tin oxide price indices and REACH compliance cost curves informed cost-structure projections across the analysis window.
The model holds under stable EU Green Deal implementation timelines and ECHA substance evaluation schedules; deviation in East Asian export restriction severity or accelerated flame retardant substitution protocols would shift capacity expansion trajectories. Stakeholders should weight assumptions against their own operating context and qualification pipeline visibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Leadframes Market
Semiconductor Devices
T-Con Board Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
Gan-On-Silicon Market
Semiconductor Devices
MBE Components Market
Semiconductor Devices
Middle East and Africa Silicon Carbide Wafers Market
Semiconductor Devices
Europe Semiconductor Device Market
Semiconductor Devices
Middle East and Africa Ultra-Low-Power Microcontroller Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
FPGA Market
Semiconductor Devices
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Analog and Mixed Signal Device Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market