
 Glass Wafer Market | 2026-2036
Glass Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Wafer Market Analysis
East Asian capacity expansion is fragmenting competitive dynamics across the glass wafer supply base. Corning Incorporated leverages its fused silica heritage to anchor high-end optical and semiconductor substrate demand. SCHOTT AG sustains European process leadership through specialized borosilicate formulations for MEMS and sensor packaging. Shin-Etsu Chemical Co., Ltd. dominates silicon-to-glass hybrid wafer development, extending its materials science platform into advanced packaging substrates.
A glass wafer is a precision-manufactured, ultra-flat substrate composed of fused silica, borosilicate, or aluminosilicate glass, typically produced through float, fusion draw, or re-melt processes to achieve thickness tolerances below 50 micrometers and surface roughness under 1 nanometer RMS. These specifications enable its primary function as a carrier, interposer, or permanent substrate in semiconductor packaging, MEMS fabrication, CMOS image sensors, and microfluidic devices. Semiconductor wafers lead value generation due to their critical role in fan-out panel-level packaging and 3D integration schemes. Optical glass wafers represent the fastest-growing technology segment as augmented reality waveguides and LiDAR receiver arrays multiply die-level optical requirements. Display glass retains scale maturity in OLED encapsulation and micro-LED transfer applications, though margin pools have compressed amid panel maker consolidation.
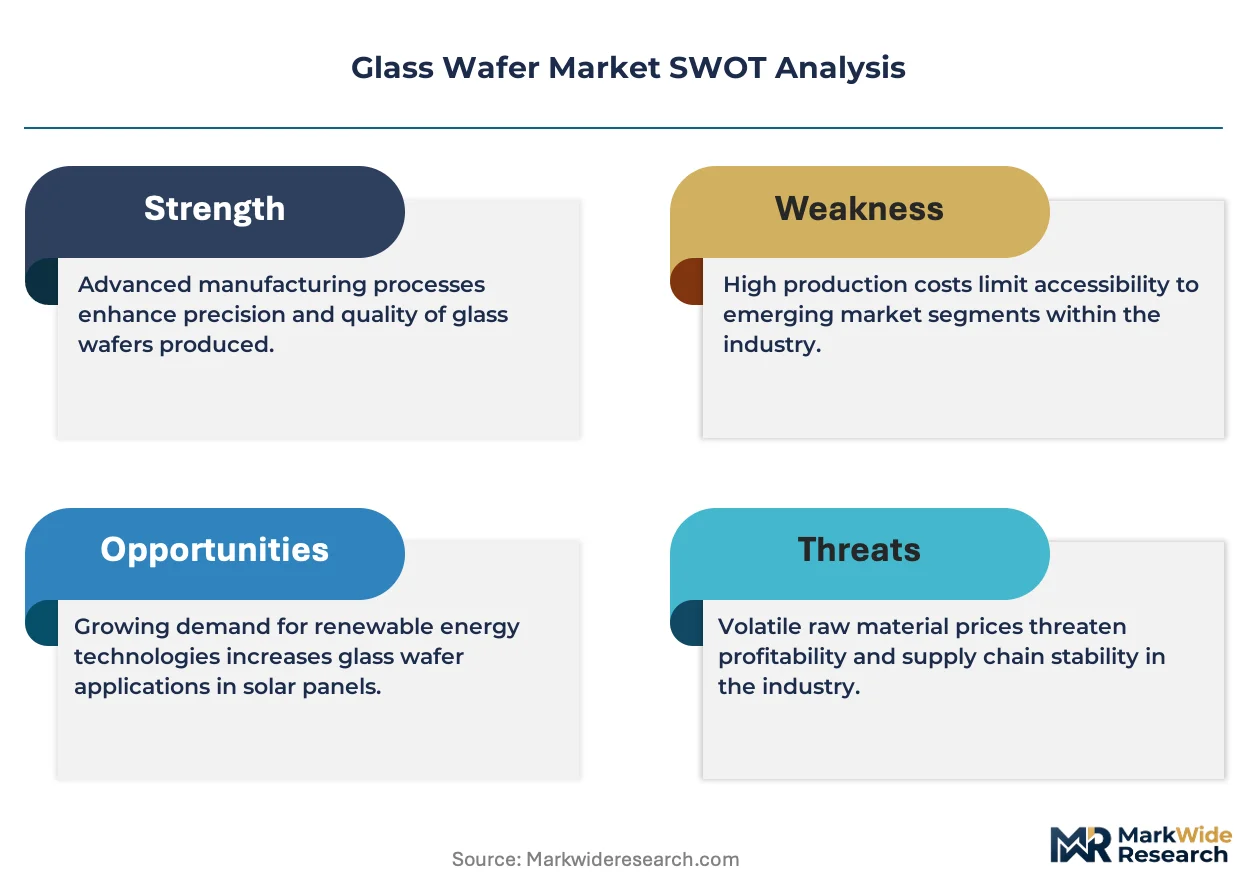
Japan's METI enforces JIS standards for electronic-grade glass substrates, while the EU REACH framework restricts heavy metal content in optical coatings exported to European telecom and automotive buyers. China's SAMR and GB standards mandate traceability certificates for glass wafers entering domestic semiconductor fabs, reshaping supplier qualification timelines. FDA oversight of diagnostic MEMS devices in the United States further tightens biocompatibility and particulate specifications for microfluidic glass substrates. Stakeholders must monitor divergence between East Asian purity protocols and European chemical registration requirements when siting qualification laboratories and regional distribution hubs.
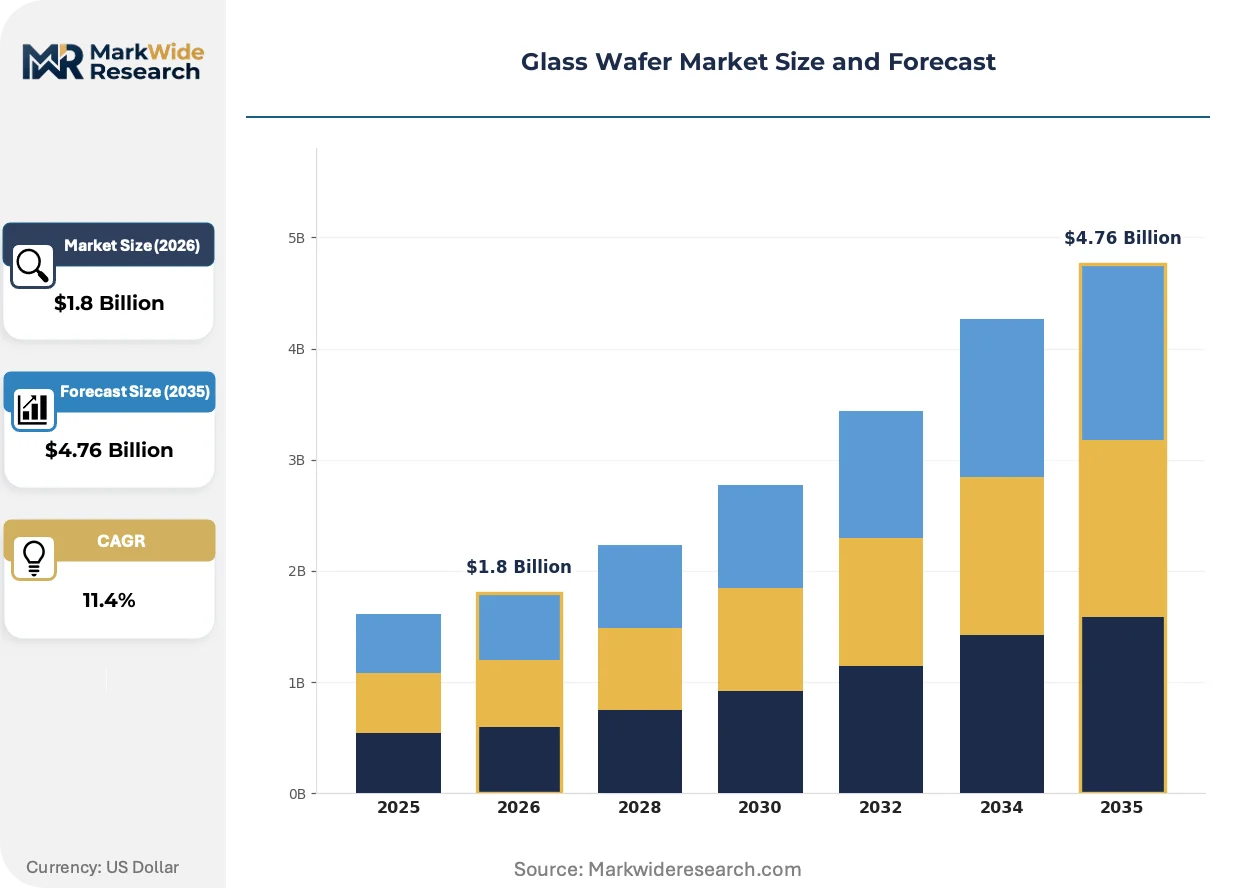
Market Dynamics
Fan-out panel-level packaging is compressing substrate qualification timelines across semiconductor fabs, forcing glass wafer suppliers to synchronize thickness tolerance roadmaps with advanced packaging equipment cycles. This packaging migration is redrawing competitive boundaries between fused silica specialists and borosilicate formulators.
Growth Catalysts
- Fan-out wafer-level packaging expansion:Semiconductor fabs in Japan and South Korea are scaling panel-level formats that demand glass carriers with sub-50-micrometer thickness stability. This process shift anchors procurement volumes for precision substrate suppliers.
- China's GB standards tightening:SAMR-mandated traceability certificates for electronic-grade glass are accelerating qualification of domestic suppliers. Foreign manufacturers must establish in-country testing laboratories to maintain fab access.
- LiDAR receiver array proliferation:Automotive Tier-1 suppliers are specifying optical-grade borosilicate wafers for frequency-doubling crystals. This specification is multiplying die-level optical substrate demand beyond traditional telecom applications.
Market Restraints
- High-purity silica feedstock concentration:Ultra-low-iron sand deposits suitable for semiconductor-grade fused silica concentrate in specific coastal mining jurisdictions. This geographic lock constrains capacity expansion for premium substrate tiers.
- EU REACH coating restrictions:Heavy metal content limits on optical thin-film coatings are disqualifying legacy electroplating suppliers from European telecom and automotive qualification pools. Reformulation cycles extend certification timelines by 18-24 months.
- Temporary bonding adhesive substitution:Laser debonding systems are displacing thermal-release tapes in fan-out packaging flows. This equipment shift threatens glass carrier reuse rates and associated consumables revenue.
Strategic Opportunities
- Micro-LED transfer substrate white space:Display equipment makers in Taiwan and South Korea are piloting glass interposers for chiplet mass transfer. This application opens volume contracts outside traditional semiconductor packaging.
- India's semiconductor PLI scheme:Central government production-linked incentives for domestic fab construction are attracting substrate suppliers to establish Bengaluru and Ahmedabad qualification centers. Early entrants capture design-in relationships with emerging foundries.
- Augmented reality waveguide convergence:Nanoimprint lithography and atomic layer deposition are combining to pattern glass wafers for AR optics. This process integration enables single-supplier solutions for optical engine manufacturers.
Industry Challenges
- Atomic-scale surface metrology talent scarcity:White-light interferometry and atomic force microscopy expertise concentrates in Japanese and German equipment ecosystems. Substrate manufacturers struggle to staff qualification laboratories in lower-cost manufacturing zones.
- Multi-standard certification fragmentation:Divergent purity protocols between China's GB standards, Japan's JIS specifications, and FDA biocompatibility requirements for diagnostic MEMS force redundant testing. This duplication extends time-to-revenue for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Wafer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semiconductor Wafers, Display Glass, Optical Glass, Micro-electronic Wafers Technology: Thin-Film Deposition, Etching, Dicing, Polishing End User: Consumer Electronics, Telecom, Automotive, Aerospace Packaging Type: Tray Packaging, Vacuum Packaging, Custom Packaging, Standard Packaging |
| Companies Covered | Hoya Corporation, Shin-Etsu Chemical Co., Ltd., Corning Incorporated, Plan Optik AG, Ohara Corporation, SCHOTT AG, Nippon Electric Glass Co., Ltd., SUMITA Optical Glass, AGC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Wafer Market Emerging Trajectories
Packaging format migration and regulatory divergence are compressing technology refresh cycles across the glass wafer value chain. Suppliers must now synchronize material roadmaps with both equipment maker cycles and multi-jurisdictional compliance timelines.
Fused silica carrier technology is migrating from temporary bonding applications toward permanent interposer substrates in 3D integration schemes. Memory and logic stack designers at leading foundries are specifying silica for through-glass via reliability. This substrate permanence is compressing the addressable market for reusable carrier formats while expanding value-per-wafer metrics.
Japan's METI is enforcing updated JIS standards for electronic-grade glass substrates that mandate particulate contamination thresholds below prior industry norms. Substrate suppliers must retrofit cleanroom classifications and particle monitoring protocols to maintain fab qualification. Korean memory manufacturers are accelerating domestic supplier certification to hedge against import compliance friction.
Buyers are consolidating procurement authority at the packaging house level rather than dispersing decisions across device design teams. This concentration is compressing supplier negotiation cycles and favoring substrate vendors with integrated metrology and logistics capabilities. The shift is most visible in Taiwan's OSAT ecosystem, where turnkey substrate-plus-inspection contracts are displacing component-level purchasing.
Glass Wafer Market Segmentation
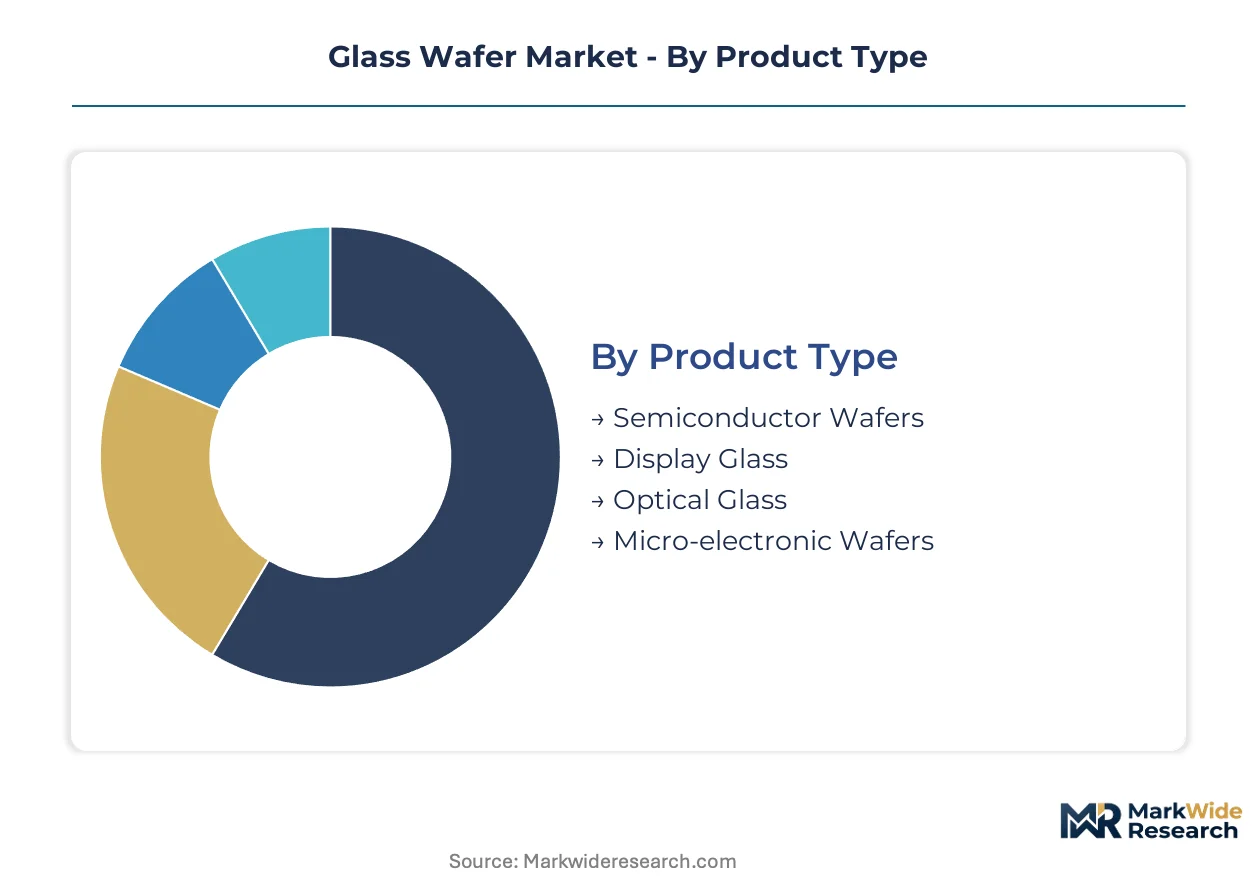
Glass wafer procurement patterns diverge sharply across application tiers, with semiconductor packaging demanding sub-50-micrometer thickness stability while optical segments prioritize surface roughness below 1 nanometer RMS. Understanding these specification clusters enables suppliers to align process roadmaps with distinct equipment cycles and qualification timelines.
Product Type:
Semiconductor wafers turn inventory fastest through fan-out packaging line cycles, while optical glass moves slowest due to extended AR waveguide qualification protocols. Display glass occupies the middle tier with seasonal panel maker procurement patterns.
- Semiconductor Wafers:Fused silica and borosilicate substrates engineered for through-glass via reliability in 3D integration schemes. Procurement concentrates at Japan and South Korea foundries scaling panel-level packaging formats, driven by temporary bonding carrier demand and permanent interposer migration.
- Optical Glass:Ultra-low-iron formulations achieving sub-nanometer surface roughness for LiDAR receiver arrays and AR waveguides. Taiwanese optical engine manufacturers and German automotive Tier-1 suppliers dominate qualification activity, constrained by EU REACH coating restrictions on heavy metal thin-films.
- Display Glass:OLED encapsulation and micro-LED transfer substrates requiring thermal stability during chiplet mass transfer. Korean panel makers anchor volume procurement amid margin compression from manufacturer consolidation.
- Micro-electronic Wafers:MEMS and sensor packaging substrates leveraging SCHOTT's borosilicate heritage for biocompatibility compliance. FDA diagnostic device oversight tightens particulate specifications for microfluidic applications in US healthcare markets.
Semiconductor wafers dominate installed base. Optical glass is where expansion concentrates.
Technology:
Process selection maps directly to specification tier, with thin-film deposition commanding premium pricing for optical coatings while polishing scales through automation in display applications.
- Thin-Film Deposition:Atomic layer deposition and nanoimprint lithography patterning glass for AR waveguides and frequency-doubling crystals. Japanese equipment ecosystems anchor process expertise, with qualification timelines extending 18-24 months under EU REACH reformulation cycles.
- Polishing:Chemo-mechanical planarization achieving sub-nanometer RMS surface finish for CMOS image sensors and optical interposers. Korean memory manufacturers accelerate domestic supplier certification to hedge against import compliance friction.
- Etching:Plasma and wet chemical processes creating through-glass vias for 3D integration schemes. China's SAMR traceability mandates reshape supplier qualification timelines for etchant chemistry documentation.
- Dicing:Laser and mechanical singulation for die-level substrate formatting. Taiwan OSATs consolidate procurement authority at packaging house level, compressing negotiation cycles for dicing service contracts.
Polishing captures the highest volume throughput. Thin-film deposition is climbing the fastest as AR and LiDAR specifications multiply.
End User:
Automotive qualification cycles run longest due to safety-critical reliability testing, while consumer electronics turns fastest through seasonal smartphone release schedules.
- Consumer Electronics:CMOS image sensor substrates and fingerprint module packaging for smartphone OEMs. Japanese fab equipment cycles synchronize with Apple and Samsung annual release calendars, compressing substrate delivery windows.
- Automotive:LiDAR receiver arrays and HUD waveguides requiring AEC-Q100 thermal cycling compliance. German KBA and US NHTSA safety standards extend qualification timelines beyond consumer electronics norms.
- Telecom:Optical transceiver substrates and fiber alignment structures for 5G infrastructure. European REACH restrictions on coating heavy metals disqualify legacy suppliers from telecom qualification pools.
- Aerospace:Radiation-hardened optical components and satellite sensor substrates. US FAA and EASA certification requirements for space-grade materials limit qualified supplier bases.
Consumer electronics dominates installed base. Automotive is gaining share fastest as ADAS penetration deepens.
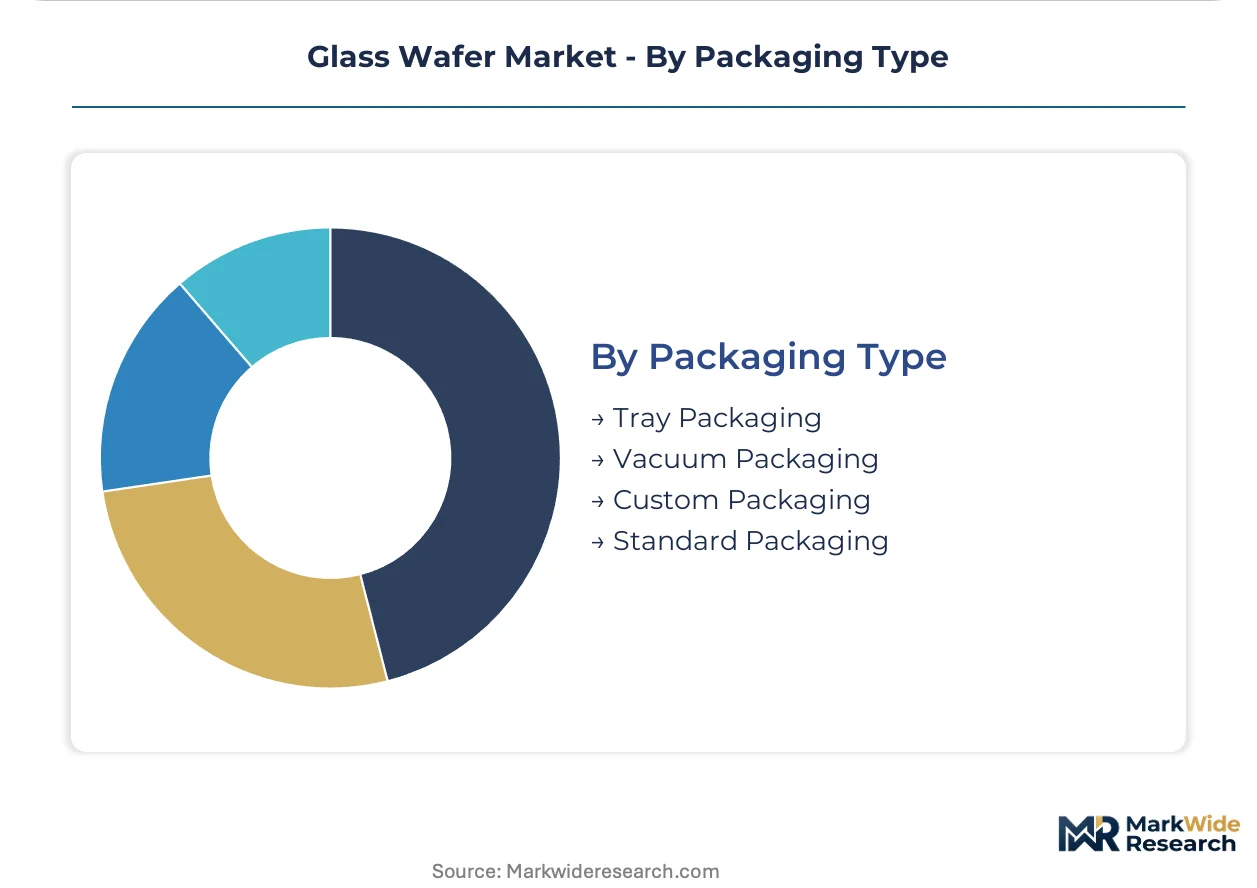
Packaging Type:
Protection requirements scale with substrate value, with vacuum packaging for optical grades carrying 3-4x cost premium over standard tray formats for display glass.
- Vacuum Packaging:Hermetic sealing for optical and semiconductor wafers requiring particulate isolation below Class 100 cleanroom equivalence. Japanese METI JIS standards mandate upgraded packaging protocols for electronic-grade substrates.
- Tray Packaging:Standardized handling for display glass and micro-electronic wafers in high-volume manufacturing. Korean panel makers drive standardization to reduce logistics fragmentation.
- Custom Packaging:Application-specific designs for fragile AR waveguides and large-format panel-level carriers. Taiwan OSATs specify turnkey substrate-plus-inspection contracts displacing component-level purchasing.
- Standard Packaging:Generic protection for non-critical MEMS and sensor substrates. India's semiconductor PLI scheme attracts suppliers to establish Bengaluru qualification centers with standard packaging capabilities.
Tray packaging dominates installed base. Vacuum packaging is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's JIS standards for electronic-grade glass substrates anchor procurement protocols across East Asian semiconductor clusters. The report traces how regulatory divergence between Japan, China, South Korea, and the United States compresses supplier qualification timelines.
Japan
Memory manufacturers in Yokkaichi and Hiroshima specify fused silica carriers for panel-level packaging formats. METI enforces particulate contamination thresholds below prior industry norms through updated JIS standards. Nagoya equipment ecosystems concentrate atomic-scale surface metrology expertise that substrate suppliers struggle to replicate elsewhere.
China
Domestic foundries in Shanghai and Beijing accelerate glass carrier procurement for fan-out wafer-level packaging expansion. SAMR and GB standards mandate traceability certificates for electronic-grade glass entering semiconductor fabs. Suzhou and Hefei manufacturing clusters attract foreign suppliers establishing in-country testing laboratories to maintain fab access.
South Korea
Memory stack designers at Pyeongtaek and Giheung foundries specify silica for through-glass via reliability in 3D integration schemes. Domestic supplier certification accelerates to hedge against import compliance friction from divergent purity protocols. Suwon OSATs consolidate procurement authority, compressing negotiation cycles for substrate-plus-inspection contracts.
United States
Diagnostic MEMS device manufacturers in Boston and San Jose face FDA oversight tightening biocompatibility and particulate specifications for microfluidic glass substrates. FAA certification requirements for space-grade materials limit qualified supplier bases for radiation-hardened optical components. Phoenix and Austin semiconductor equipment makers synchronize thickness tolerance roadmaps with advanced packaging cycles.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich specify optical-grade borosilicate wafers for LiDAR receiver arrays requiring AEC-Q100 thermal cycling compliance. KBA safety standards extend qualification timelines beyond consumer electronics norms. Dresden and Frankfurt qualification centers anchor European process leadership for specialized borosilicate formulations.
Glass Wafer Market Vendor Landscape
Capability concentration sits with fused silica specialists; scale advantage sits with diversified materials platforms. The market structures around three tiers: heritage optical glass fabricators, silicon-to-glass hybrid developers, and display glass diversifiers. Strategic moves center on backward integration into high-purity silica feedstock and geographic expansion into India and Southeast Asia to capture emerging fab construction.
Among heritage optical specialists, Corning Incorporated and SCHOTT AG exemplify the premium-tier archetype through decades of process refinement in fused silica and borosilicate formulations. Shin-Etsu Chemical Co., Ltd. occupies a bridging position, extending silicon materials science into glass substrate development. These three anchors represent distinct capability vectors: optical heritage, semiconductor materials integration, and hybrid wafer innovation.
| Leading Market Players |
|---|
| Hoya Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| Corning Incorporated |
| Plan Optik AG |
| Ohara Corporation |
| SCHOTT AG |
| Nippon Electric Glass Co., Ltd. |
| SUMITA Optical Glass |
| AGC Inc. |
| Others |
Supply Flow & Price Mechanics
Yokkaichi and Hiroshima manufacturing clusters anchor premium fused silica substrate pricing through METI-enforced JIS certification tiers. This geographic concentration of memory foundry demand compresses negotiation leverage for unqualified suppliers while rewarding domestic incumbents with pricing power tied to particulate contamination thresholds.
Pricing Analysis
Japanese and Korean fab procurement creates a 40-60% price spread between JIS-certified premium grades and standard borosilicate tiers. Three-tier pricing structure across premium, standard, and economy levels segments by particulate grade and through-glass via reliability certification. Cost compression in display glass intensifies as Korean panel makers consolidate procurement authority and squeeze margin pools. OSATs in Taiwan exhibit highest price sensitivity due to turnkey substrate-plus-inspection contract consolidation, while AR optical engine manufacturers absorb premiums for sub-nanometer surface roughness specifications.
Supply Chain Analysis
SEMI members and specialized glass formulators in Japan, Germany, and South Korea hold contract-manufacturing capacity for semiconductor-grade substrates. High-purity silica feedstock draws from coastal mining jurisdictions in the United States and Australia, while borosilicate formulations rest on European process heritage. Single-source vulnerability concentrates in atomic-scale surface metrology equipment anchored in Nagoya and Dresden equipment ecosystems. Distribution runs through packaging house consolidation in Taiwan and direct fab relationships in East Asian manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fan-out panel-level packaging migration represents an early-cycle expansion story, with panel format adoption creating substrate demand multiples beyond traditional wafer-level volumes.
For Market Incumbents: Entrench JIS certification leadership through cleanroom retrofit investments that lock in Yokkaichi and Pyeongtaek foundry relationships. Backward integration into high-purity silica feedstock hedges against coastal mining jurisdiction concentration risk. Counter laser debonding substitution threats by developing permanent interposer substrate roadmaps that capture value-per-wafer expansion in 3D integration schemes. For New Entrants and Emerging Players: Pursue micro-LED transfer substrate qualification with Taiwan and South Korea display equipment makers piloting chiplet mass transfer applications. India's semiconductor PLI scheme offers the most penetrable geography for establishing Bengaluru qualification centers ahead of domestic fab construction. Lead with standard packaging capabilities and SAMR traceability documentation to accelerate design-in relationships with emerging foundries. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified materials conglomerates with undermonetized glass substrate divisions lacking semiconductor fab certification. Long-term viability hinges on capturing panel-level packaging format transitions and AR waveguide convergence over the next decade. Watch for acceleration in domestic supplier certification by Korean memory manufacturers as an inflection signal for import substitution pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Silica | Captive feedstock supply hedges against coastal mining jurisdiction concentration and METI purity mandates. |
| JIS Certification Laboratory Expansion | In-country testing capabilities satisfy SAMR traceability requirements and compress qualification timelines for Shanghai foundries. |
| Permanent Interposer Substrate Development | Migrates fused silica carriers from temporary bonding to 3D integration schemes, expanding value-per-wafer metrics. |
| AR Waveguide Process Integration | Combines nanoimprint lithography and atomic layer deposition to capture single-supplier contracts with optical engine manufacturers. |
| India PLI Scheme Qualification Center | Early Bengaluru presence captures design-in relationships with emerging foundries under central government production-linked incentives. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including packaging house procurement directors at Taiwan OSATs, substrate R&D leads at Japanese fused silica formulators, and metrology equipment specialists in Nagoya and Dresden ecosystems. Secondary validation drew from SAMR traceability filings, METI JIS standard updates, SEC 10-K disclosures by heritage optical glass fabricators, and customs data on high-purity silica import flows. Bottom-up volume builds across fan-out packaging line cycles triangulated against top-down market sizing through equipment maker shipment disclosures.
Calibration against historical substrate procurement patterns at Yokkaichi memory foundries and Pyeongtaek logic fabs anchored volume assumptions across the projection horizon. Segmentation modeling spanned product type, technology process, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of equipment cycle synchronization and packaging format migration timelines, with specific inputs from LiDAR receiver array proliferation rates and AR waveguide pilot production schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic suppliers or accelerated laser debonding adoption would shift outcomes beyond modeled ranges. Quarterly review of JIS certification retrofit announcements, SAMR traceability mandate enforcement intensity, and panel-level packaging equipment order flows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Hafnium Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
Silicon Dioxide Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Quartz Market
Semiconductor Material
Indium Market
Semiconductor Material
Yttrium Market
Semiconductor Material
Gallium Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Asia Pacific Graphene Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
Global Silicon Carbide (SIC) Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Semiconductor Glass Market