
 Global Silicone Market | 2026-2036
Global Silicone Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silicone Market Outlook
A capital-intensity divergence between integrated monomer producers and formulation specialists is redrawing competitive boundaries in silicone manufacturing. Dow Inc. leverages captive silicon metal and chlorosilane capacity to sustain margin control across the elastomer value chain. Wacker Chemie AG anchors its position through Munich-based R&D centers that specialize in high-purity silicone fluids for semiconductor fabrication. Shin-Etsu Chemical Co., Ltd. dominates upstream methyl chloride and fumed silica production, extending cost advantages into Asian electronics supply chains.
Silicone denotes a synthetic polymer family built on alternating silicon-oxygen backbones with organic side groups, typically produced via Rochow direct process or hydrolysis of dimethyldichlorosilane into polydimethylsiloxane fluids with viscosities spanning 0.65 to 1,000,000 centistokes. These materials deliver thermal stability from minus 60 to 250 degrees Celsius, electrical insulation, and biocompatibility for applications spanning medical implants to aerospace gaskets. Silicone elastomers occupy the largest value pool due to entrenched demand in automotive sealing and construction glazing, while silicone fluids capture premium margins in electronics cooling and personal care formulations. Healthcare applications represent the fastest-growing demand segment as regulatory clearance timelines shorten for implantable device grades.
The EPA oversees volatile organic compound limits in silicone sealant formulations across the United States, while REACH and the EU F-Gas Regulation constrain fluorinated silicone precursor availability in Europe. China's MEE enforces wastewater discharge standards at chlorosilane production hubs, raising compliance costs for regional converters. Stakeholders must monitor divergence between EU Green Deal material restrictions and United States IRA-linked domestic content incentives as they recalibrate regional supply footprints and certification investments.
Market Dynamics
Automotive electrification programs in Germany, Japan, and the United States are compressing silicone qualification timelines for thermal interface materials and battery encapsulation systems, forcing suppliers to synchronize R&D cycles with OEM platform launches rather than traditional specification-led adoption.
Growth Catalysts
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases are redirecting demand toward silicone-based alternatives in refrigeration and HVAC sealant applications across European industrial markets.
- Semiconductor fabrication expansion:Advanced lithography and wafer processing in Taiwan, South Korea, and the United States is pulling high-purity silicone fluids for photoresist coating and chemical mechanical planarization.
- Photovoltaic installation surge:China's eastern manufacturing corridor is consuming specialized silicone sealants for frame bonding and junction box potting in utility-scale solar deployment.
Market Restraints
- Silicon metal supply concentration:Over two-thirds of metallurgical-grade silicon originates from Chinese smelters concentrated in Yunnan and Xinjiang provinces, exposing downstream converters to energy-curtailment risks and export policy volatility.
- REACH SVHC candidate expansion:The European Chemicals Agency's growing list of substances of very high concern is extending compliance timelines and reformulation costs for medical-grade and food-contact silicone portfolios.
- Fluorosilicone precursor scarcity:Limited global capacity for trifluoropropylmethyldichlorosilane monomer is constraining specialty elastomer output for aerospace fuel-seal applications.
Strategic Opportunities
- India's electronics manufacturing incentive schemes:Production-linked incentives for semiconductor assembly and mobile device manufacturing are creating localized demand for thermal management silicones previously imported from East Asian suppliers.
- Bioresorbable silicone development:Convergence of silicone chemistry with controlled-degradation polymer science is opening implantable device applications where permanent foreign-body response limits traditional elastomer use.
- Direct-to-device-maker distribution:Bypassing traditional chemical distributor networks to supply formulated silicone systems directly to automotive tier-1 sealant applicators is compressing margin leakage and accelerating technical service response.
Industry Challenges
- Chlorosilane process engineering expertise:The cohort of engineers capable of designing and troubleshooting direct-process reactor operations is aging, with limited university pipeline replenishment in Western Europe and North America.
- Medical-grade certification timelines:FDA master file establishment and ISO 10993 biocompatibility testing for new implantable silicone grades extends 18-36 months, misaligning with compressed product development cycles in cardiovascular and neuromodulation devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silicone Market |
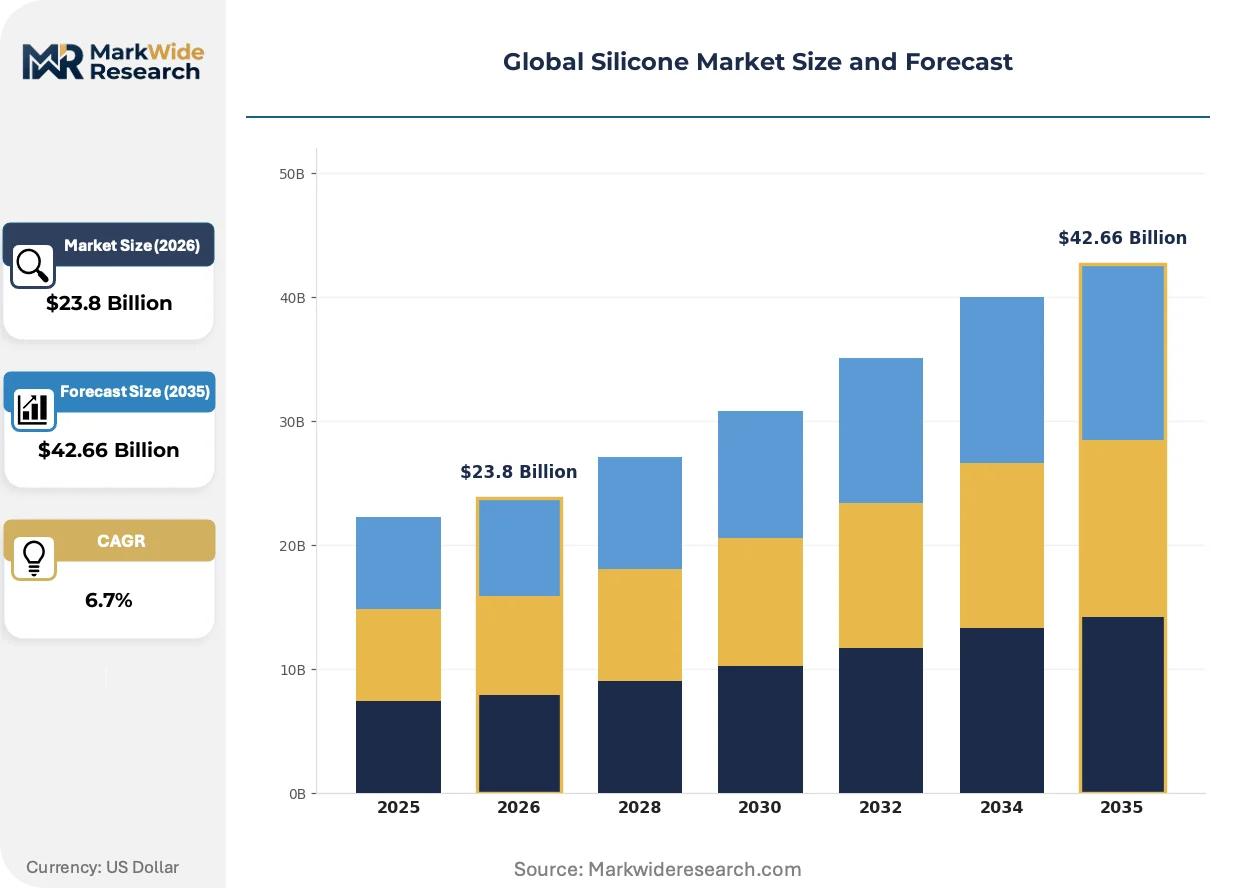
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $42.66 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Elastomers, Silicone Fluids, Silicone Resins, Silicone Gels Application: Construction, Automotive, Electronics, Healthcare Form: Liquid, Solid, Gel, Paste End User: Aerospace, Consumer Goods, Industrial, Personal Care |
| Companies Covered | Dow Inc., Evonik Industries AG, Wacker Chemie AG, Specialty Silicone Products, Inc., KCC Corporation, Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials, Gelest Inc., Elkem ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silicone Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are jointly redirecting silicone formulation priorities, with performance specifications now co-designed alongside compliance roadmaps rather than treated as sequential gates.
Liquid silicone rubber injection molding with in-mold curing is supplanting conventional high-consistency rubber compression molding in automotive connector sealing. Tier-1 suppliers in Germany and Japan are adopting this transition to achieve flash-free geometries and cycle-time reductions. The shift is compressing tolerance bands for medical-device seals and enabling miniaturized electronics encapsulation previously unachievable with legacy processing.
REACH authorization requirements for octamethylcyclotetrasiloxane (D4) and related cyclosiloxanes are forcing reformulation of personal-care silicone fluids across European cosmetic and skincare markets. Manufacturers are accelerating substitution with low-cyclic-content linear polydimethylsiloxanes or alternative emollient chemistries. The regulatory pressure is most acute in France and Germany, where national cosmetic ingredient registries pre-empt EU-wide restrictions.
Consolidated procurement of silicone formulations by automotive platform engineering teams is displacing decentralized purchasing by individual component suppliers. Volkswagen, Toyota, and Ford are centralizing material specifications to reduce qualification redundancy and secure volume commitments. This concentration is most visible in battery pack assembly operations, where thermal interface material selection now occurs at the platform-architecture level rather than the module-supplier level.
Global Silicone Market Segmentation
Silicone product specifications diverge sharply across end-use contexts, with automotive electrification and semiconductor fabrication pulling distinct purity grades and viscosity profiles. Formulation complexity and certification requirements fragment procurement patterns, forcing suppliers to align production assets with specific demand corridors rather than generic commodity positioning.
Product Type:
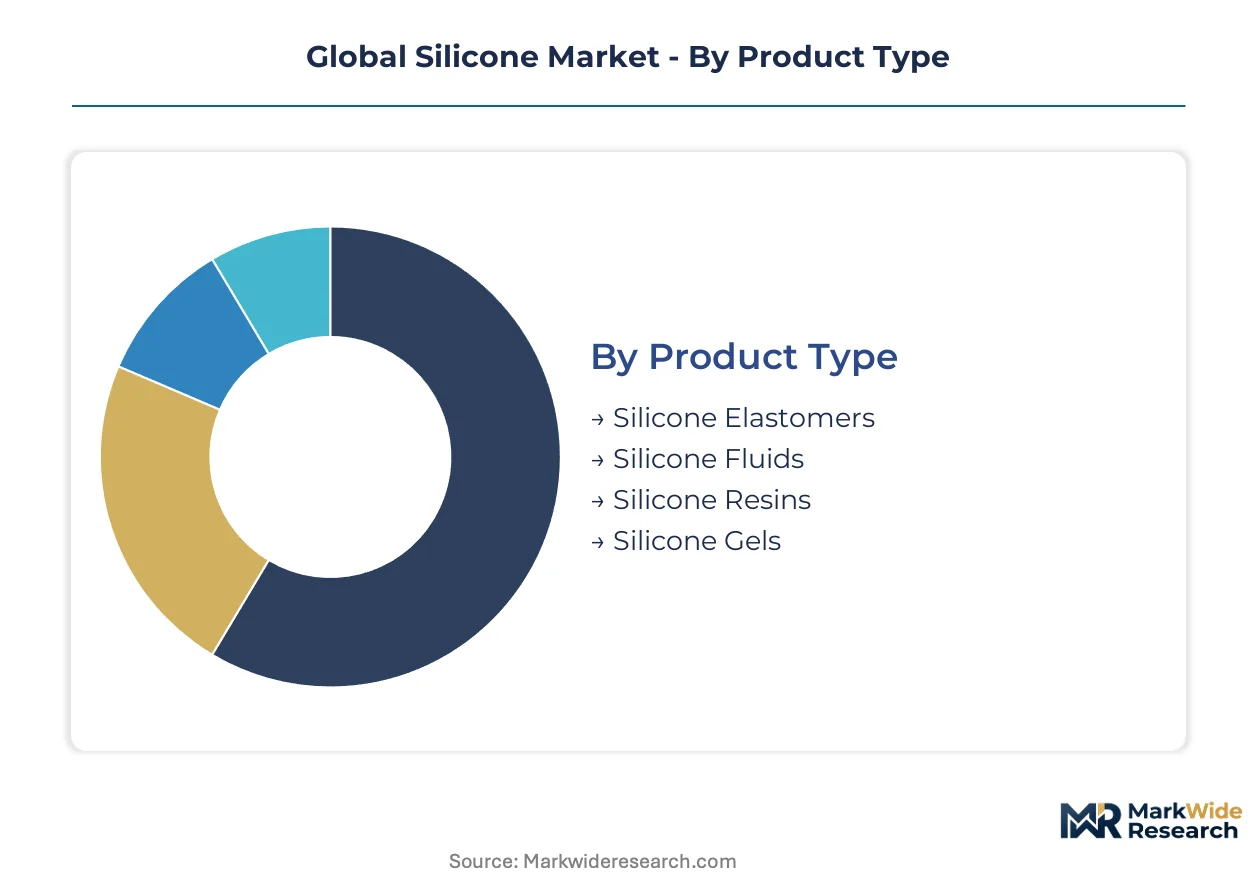
Domestic consumption patterns concentrate silicone elastomers and fluids in integrated manufacturing clusters across Germany, Japan, and the United States, while silicone resins and gels flow disproportionately into export-oriented electronics and medical device supply chains.
- Silicone Elastomers:Cross-linked polydimethylsiloxane networks with Shore A hardness ranging 10-80 deliver compression set resistance and thermal stability for automotive sealing and construction glazing. Demand concentrates in Germany's automotive tier-1 supplier corridor, where Volkswagen and BMW platform specifications dictate high-consistency rubber grades for battery pack gaskets.
- Silicone Fluids:Linear polydimethylsiloxanes spanning 0.65 to 1,000,000 centistokes serve thermal management and personal care applications, with high-purity semiconductor grades commanding premium positioning. Taiwan and South Korea fabrication facilities pull ultra-low-metal-content fluids for chemical mechanical planarization, tightening supply availability for industrial grades.
- Silicone Resins:Three-dimensional siloxane networks with methyl or phenyl substitution provide weatherability coatings for architectural cladding and electrical insulation.
- Silicone Gels:Soft, unfilled elastomeric materials with controlled penetration values encapsulate sensitive electronics and medical implants requiring stress relief.
Silicone elastomers hold the largest share; momentum sits with silicone fluids.
Application:
Cost tier stratification separates specification-heavy automotive and healthcare applications from volume-driven construction and electronics segments, with certification burden and technical service intensity determining margin architecture.
- Construction:Structural glazing sealants and weatherproofing membranes consume high-modulus elastomers formulated for 50-year durability in facades and infrastructure. Demand clusters in China's eastern manufacturing corridor, where integrated silicone monomer-to-sealant complexes serve domestic photovoltaic installation surges.
- Automotive:Thermal interface materials, battery encapsulation systems, and connector seals require flame-retardant grades meeting OEM platform specifications. Germany's electrification programs compress qualification timelines, forcing suppliers to synchronize R&D cycles with Volkswagen and BMW launch schedules.
- Electronics:Potting compounds and conformal coatings protect circuit assemblies from moisture and thermal cycling.
- Healthcare:Implantable device grades demand ISO 10993 biocompatibility and FDA master file clearance for cardiovascular and neuromodulation applications.
Construction captures the greatest volume throughput; healthcare climbs the fastest.
Form:
Volume concentration favors liquid formulations in automated dispensing environments, while solid and gel forms retain position in legacy compression molding and specialized encapsulation contexts.
- Liquid:Low-viscosity pumpable systems enable precision dispensing in automotive battery assembly and electronics potting operations.
- Solid:High-consistency rubber compounds require mill mixing and compression molding, constraining throughput in medical device seal production.
- Gel:Soft, self-leveling materials conform to complex geometries in implantable electronics and optical fiber protection.
- Paste:Thixotropic formulations maintain position on vertical surfaces in construction joint sealing and aerospace gap-filling.
Liquid forms dominate throughput; gel formulations gain share fastest.
End User:
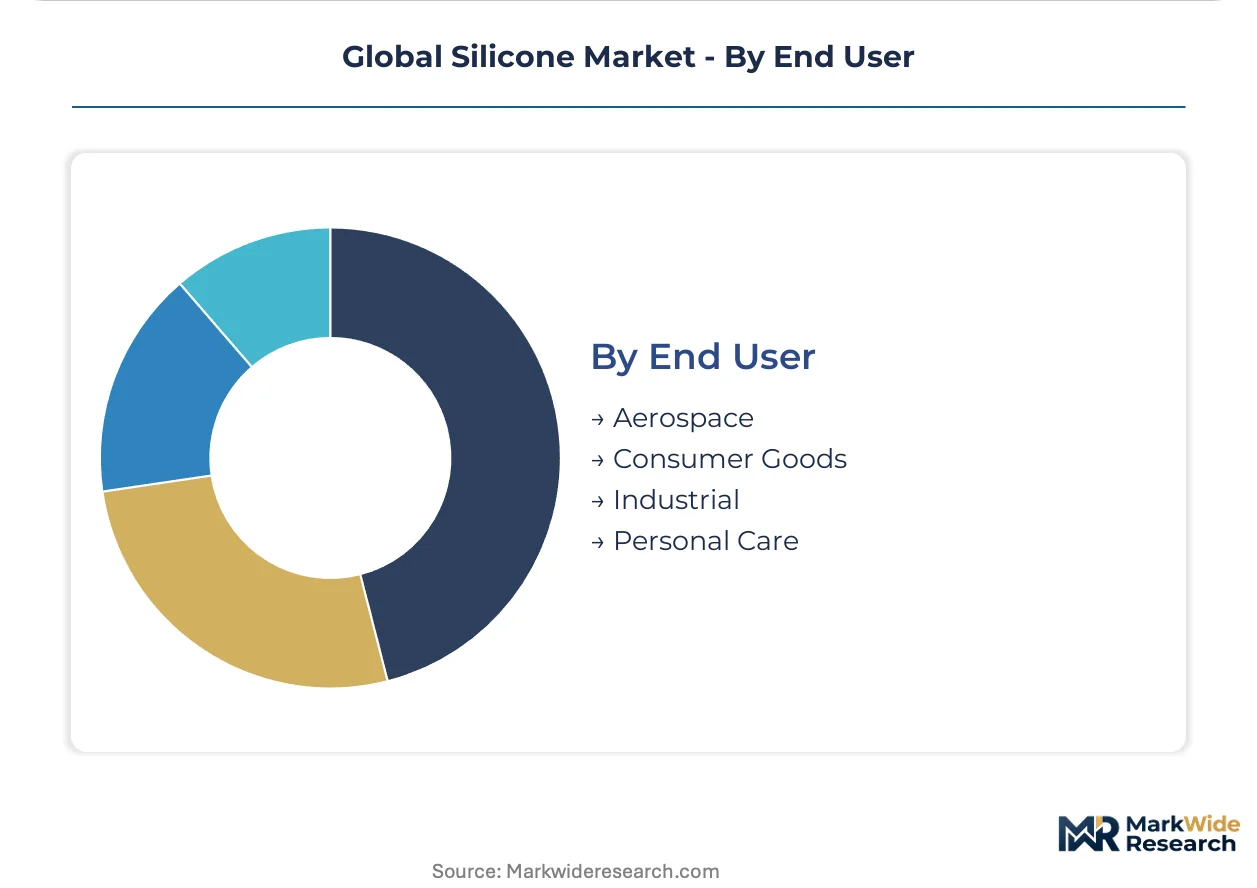
Customer type fragmentation separates aerospace and industrial procurement—driven by specification longevity and qualification inertia—from fast-cycle consumer goods and personal care segments responsive to formulation fashion and regulatory substitution pressures.
- Aerospace:Fuel-resistant fluorosilicone elastomers and high-temperature sealants must meet FAA certification and OEM durability specifications. Limited global capacity for trifluoropropylmethyldichlorosilane monomer constrains specialty output for Boeing and Airbus fuel-seal programs.
- Consumer Goods:Kitchenware, bakeware, and infant care products demand food-contact compliant formulations meeting FDA and EU migration limits. REACH SVHC expansion and state-level disclosure requirements in California and Washington extend reformulation cycles.
- Industrial:Mold-making, antifoam, and release agent applications consume commodity-grade fluids and emulsions in process manufacturing.
- Personal Care:Volatile silicone fluids and emollients face cyclosiloxane restrictions under REACH D4/D5/D6 regulations, forcing substitution with low-cyclic-content linear polydimethylsiloxanes in French and German cosmetic markets.
Industrial end users absorb the greatest volume; personal care shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Construction buyers in China negotiate aggressively on commodity sealants. Automotive OEMs in Germany and Japan absorb premium pricing for battery-grade thermal materials. Healthcare procurement in the United States shows inelastic demand for implantable device certifications.
United States
Semiconductor fabrication expansion in Arizona and Texas pulls ultra-high-purity silicone fluids for chemical mechanical planarization. The EPA enforces volatile organic compound limits in construction sealant formulations. Integrated silicone monomer-to-elastomer complexes in the Gulf Coast corridor serve domestic automotive electrification programs.
Germany
Volkswagen and BMW platform specifications compress qualification timelines for battery pack gasket grades. The EU F-Gas Regulation redirects demand toward silicone-based refrigeration sealants. Automotive tier-1 suppliers cluster in Bavaria and Baden-Württemberg, synchronizing R&D cycles with OEM launch schedules.
China
Photovoltaic installation surges consume specialized frame-bonding and junction-box potting sealants. The MEE enforces wastewater discharge standards at chlorosilane production hubs in Yunnan and Xinjiang. Eastern manufacturing corridor complexes integrate monomer production through finished elastomers for domestic electronics markets.
Japan
Advanced lithography operations in Kyushu and Chubu pull high-purity silicone fluids for photoresist coating. METI industrial policy supports domestic semiconductor material supply chain security. Shin-Etsu Chemical anchors upstream methyl chloride and fumed silica production in the Kanto region.
South Korea
Memory and foundry fabrication in Gyeonggi Province consumes premium thermal management materials. The MFDS regulates medical-grade silicone implant certifications. Seoul Capital Area electronics assemblers concentrate procurement of potting compounds for circuit protection.
Global Silicone Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier. Captive silicon metal and chlorosilane capacity separates upstream-integrated players from formulation-dependent competitors. Three archetypes dominate: diversified chemical conglomerates with backward integration, regional specialists with process expertise, and technology licensors with patent estates. Capacity expansion and direct-to-device-maker distribution represent the dominant competitive moves.
Within the integrated chemical conglomerate tier, Dow Inc. and Wacker Chemie AG exemplify upstream-anchored positioning through captive raw material access. Shin-Etsu Chemical Co., Ltd. occupies a distinct position bridging methyl chloride production with Asian electronics supply chain proximity. These three represent the structural division between resource-controlled and technology-specialized competitive vectors.
| Leading Market Players |
|---|
| Dow Inc. |
| Evonik Industries AG |
| Wacker Chemie AG |
| Specialty Silicone Products, Inc. |
| KCC Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive Performance Materials |
| Gelest Inc. |
| Elkem ASA |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between chlorosilane producers and automotive OEMs lock in supply access and price visibility across volatile silicon metal markets, compressing margin exposure for integrated manufacturers while exposing formulation specialists to spot-market volatility in Yunnan and Xinjiang smelter output.
Pricing Analysis
After-sales service contracts for thermal interface material reapplication and battery encapsulation system maintenance drive lifetime value capture in automotive electrification programs. Three-tier pricing structure across medical-grade, industrial-grade, and commodity-grade silicone fluids separates ISO 10993-certified implantable formulations from construction sealants. Pricing pressure stems from REACH cyclosiloxane restrictions forcing personal-care reformulation costs onto European converters. Construction buyers in China's eastern corridor exhibit highest price sensitivity; healthcare procurement in the United States shows lowest elasticity due to FDA master file switching costs.
Supply Chain Analysis
Strait of Malacca transit vulnerability exposes silicone fluid shipments from Singapore blending hubs to Southeast Asian fabrication centers. Metallurgical-grade silicon concentrates in Chinese smelters across Yunnan and Xinjiang provinces; high-purity chlorosilane production clusters in Germany's Bavarian chemical corridor and Japan's Kanto region. Methyl chloride and fumed silica dependencies tether downstream elastomer output to Shin-Etsu's upstream position. Single-source vulnerability for trifluoropropylmethyldichlorosilane monomer constrains aerospace fluorosilicone supply. Distribution runs through authorized chemical distributor networks serving automotive tier-1 sealant applicators and direct-to-device-maker channels for semiconductor fabrication customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive platform consolidation and semiconductor supply chain regionalization fragment procurement authority, creating specialist niches for formulation developers capable of synchronizing R&D cycles with compressed OEM qualification timelines.
For Market Incumbents: Secure captive silicon metal supply through backward integration into Yunnan or Xinjiang smelter partnerships, insulating margin control from energy-curtailment risks. Anchor certification investments in FDA master file pre-submission pathways for implantable device grades, defending against bioresorbable silicone entrants. Prioritize direct-to-device-maker distribution bypasses to compress margin leakage in automotive thermal interface material supply.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks offer compressed timelines for cardiovascular and neuromodulation silicone grades, opening white-space entry against entrenched implantable suppliers. Target India's production-linked incentive corridors for semiconductor assembly and mobile device manufacturing, where localized thermal management silicone demand outpaces domestic supply. Pursue technical service partnerships with automotive tier-1 sealant applicators as the primary go-to-market angle.
For Investors and Strategic Acquirers: Regional formulation specialists with captive chlorosilane tolling agreements and automotive platform approval footprints represent priority acquisition targets in fragmented European and North American markets. Long-term viability hinges on regulatory chemistry adaptation capacity across REACH SVHC expansion and EPA volatile organic compound limits. Watch for EU Green Deal material restriction divergence from United States IRA-linked domestic content incentives as the inflection signal requiring supply footprint recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Metal | Captive Yunnan smelter access insulates Dow and Wacker from export policy volatility and energy curtailment. |
| Medical-Grade Certification Fast-Track | FDA breakthrough device designation compresses 18-36 month ISO 10993 timelines for neuromodulation entrants. |
| Direct-to-Device-Maker Distribution | Bypassing chemical distributors accelerates technical service response for Volkswagen and BMW battery programs. |
| Regional Manufacturing Footprint Expansion | India PLI-linked capacity captures semiconductor assembly demand previously served by East Asian suppliers. |
| Green Manufacturing Transition | MEE wastewater compliance investments at chlorosilane hubs defend market access in China's eastern corridor. |
Study Parameters
Initial hypotheses were tested against primary input from silicone plant managers, automotive tier-1 procurement leads, semiconductor fabrication material directors, and medical device regulatory affairs specialists, then refined through secondary validation against SEC 10-K filings, Cefic chemical industry reports, customs and trade data, and FDA master file databases. Bottom-up segmentation modeling triangulated with top-down macroeconomic drivers across product type, application, form, and end-user dimensions.
Variance decomposition across silicon metal price volatility, REACH compliance cost trajectories, and automotive platform launch timing uncertainty shaped analytical framework construction over the projection horizon. Segmentation dimensions modeled include grade tier purity specifications, end-use industry certification requirements, regional production hub concentration, and form factor automation compatibility. CAGRs derived from elasticity-adjusted demand curves incorporating photovoltaic installation surges, semiconductor fabrication expansion, and electrification program acceleration.
Decision-makers should treat outputs as directional under base assumptions of sustained automotive electrification investment and stable silicon metal supply from Chinese smelters; material deviation through export restriction or energy curtailment would warrant model refresh. Practitioners should keep alternative scenarios live as EU Green Deal material restrictions and United States IRA domestic content incentives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Europe Semiconductor Materials Market
Semiconductor Material
Metallurgical Grade Silicon Market
Semiconductor Material
Global Electronic Materials Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Yttrium Oxide Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
Synthetic Single Crystal Diamond Market