
 Titanium Diboride Market | 2026-2036
Titanium Diboride Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Diboride Market Intelligence
Increased production capacity in China is reshaping the competitive positioning for titanium diboride suppliers. H.C. Starck focuses on high-purity powder grades for specialized electronics and aerospace applications. Kennametal leverages its expertise in hard materials to offer integrated cutting tool solutions. Meanwhile, PENSC operates with significant manufacturing scale, influencing pricing in standard-grade material segments.
Titanium diboride (TiB2) is an extremely hard ceramic with high thermal conductivity, produced via methods like hot pressing. Its primary industrial purpose is serving applications that require extreme hardness and stability, such as in aluminum smelting. Demand for cutting tools and wear-resistant parts constitutes a mature, high-volume application segment. In terms of product form, powder remains the foundational input, while higher-margin opportunities exist in finished composite and ceramic block components.
The market is influenced by workplace safety and material handling regulations, such as those from the US Occupational Safety and Health Administration (OSHA). In Europe, material registration under REACH and substance classification impact market access for producers. In China, compliance with GB standards for industrial materials is mandatory for market entry. Navigating these varied material qualification and certification pathways is a key strategic consideration for suppliers.
Market Dynamics
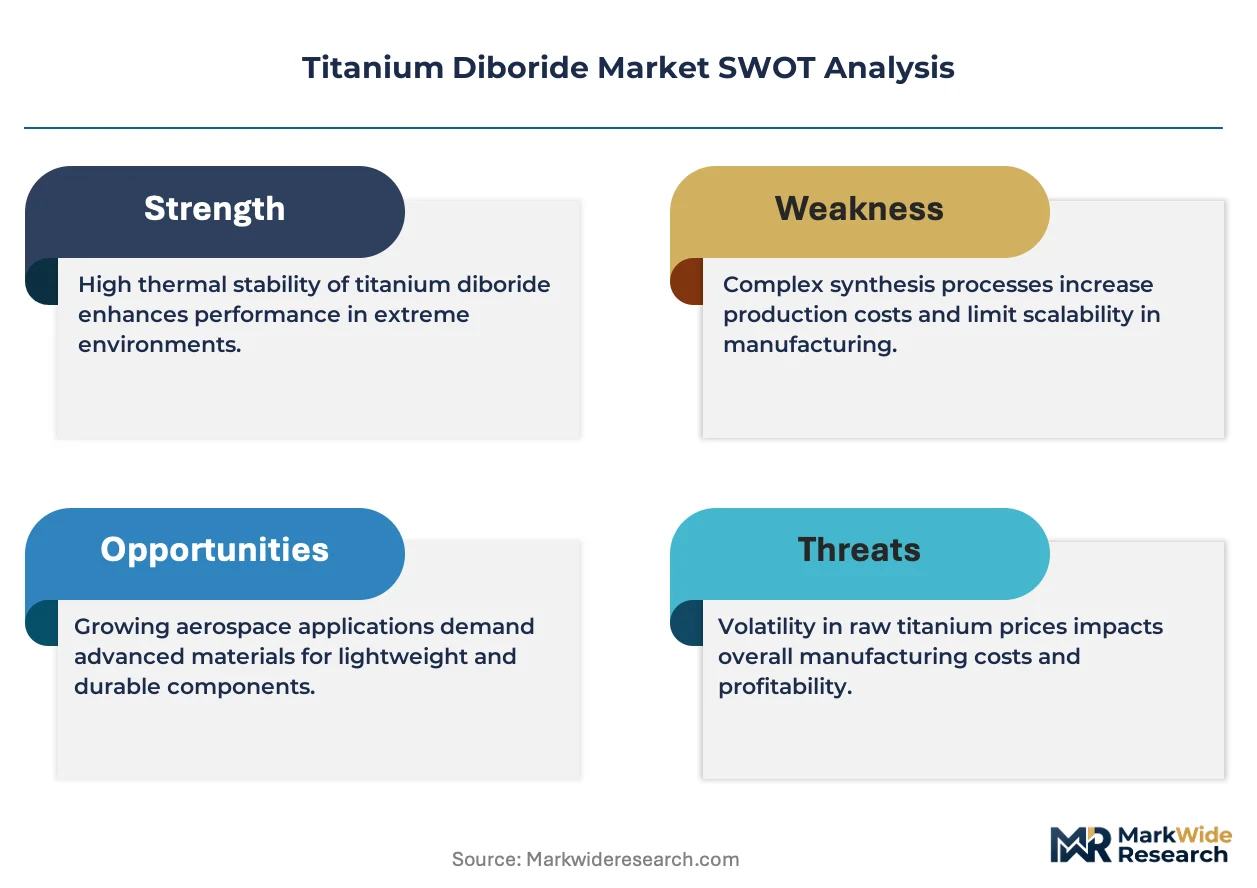
The central dynamic shaping the titanium diboride market is the tension between commoditization and specialization. Large-scale Chinese production of standard-grade material creates significant price pressure, while demand from high-value aerospace and electronics sectors requires specialized, high-purity grades with rigorous quality assurance.
Growth Catalysts
- Aerospace Modernization:Demand for lightweight, high-temperature resistant components in next-generation commercial and military aircraft engines and structures stimulates consumption of TiB2-based composites and coatings.
- Advanced Synthesis Methods:The refinement of Self-Propagating High-Temperature Synthesis (SHS) enables more energy-efficient and scalable production, improving the cost-competitiveness of TiB2 against other hard materials.
- National Industrial Policies:China's strategic focus on advanced materials, particularly for its defense and high-tech manufacturing sectors, underpins substantial and concentrated domestic demand for titanium diboride.
Market Restraints
- High Energy Consumption:Traditional production methods like hot pressing are extremely energy-intensive, making manufacturing costs highly sensitive to electricity price volatility and impacting producer margins.
- Material Brittleness:Despite its extreme hardness, the inherent brittleness of monolithic TiB2 ceramic can limit its use in applications subjected to high impact or tensile stress, creating design constraints.
- Substitution from Carbides:In the high-volume cutting tool market, established materials like tungsten carbide and silicon carbide offer a different balance of properties and often a lower cost, presenting a persistent substitution threat.
Strategic Opportunities
- Advanced Ceramic Armor:The material's hardness and relatively low density create opportunities in next-generation lightweight armor systems for personnel and vehicles, an area with evolving performance requirements.
- Metal Matrix Composites:Integrating TiB2 particles into aluminum or titanium alloys to create advanced metal matrix composites (MMCs) opens applications in high-performance automotive and industrial components.
- Indian Industrial Growth:India's expanding manufacturing and defense sectors, supported by initiatives like 'Make in India', represent an underpenetrated market for wear-resistant components and advanced ceramics.
Industry Challenges
- Fragmented Regulatory Compliance:Suppliers face complexity and cost in navigating disparate material safety and import regulations, including REACH in Europe, OSHA standards in the US, and GB standards in China.
- High Capital Investment:Establishing or expanding production capacity requires significant capital expenditure for specialized high-temperature furnaces and controlled atmosphere processing equipment, creating a high barrier to entry.
- Specialized Talent Scarcity:A limited pool of materials scientists and process engineers with expertise in high-temperature synthesis and ceramic processing can constrain research and development and operational scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Diboride Market |
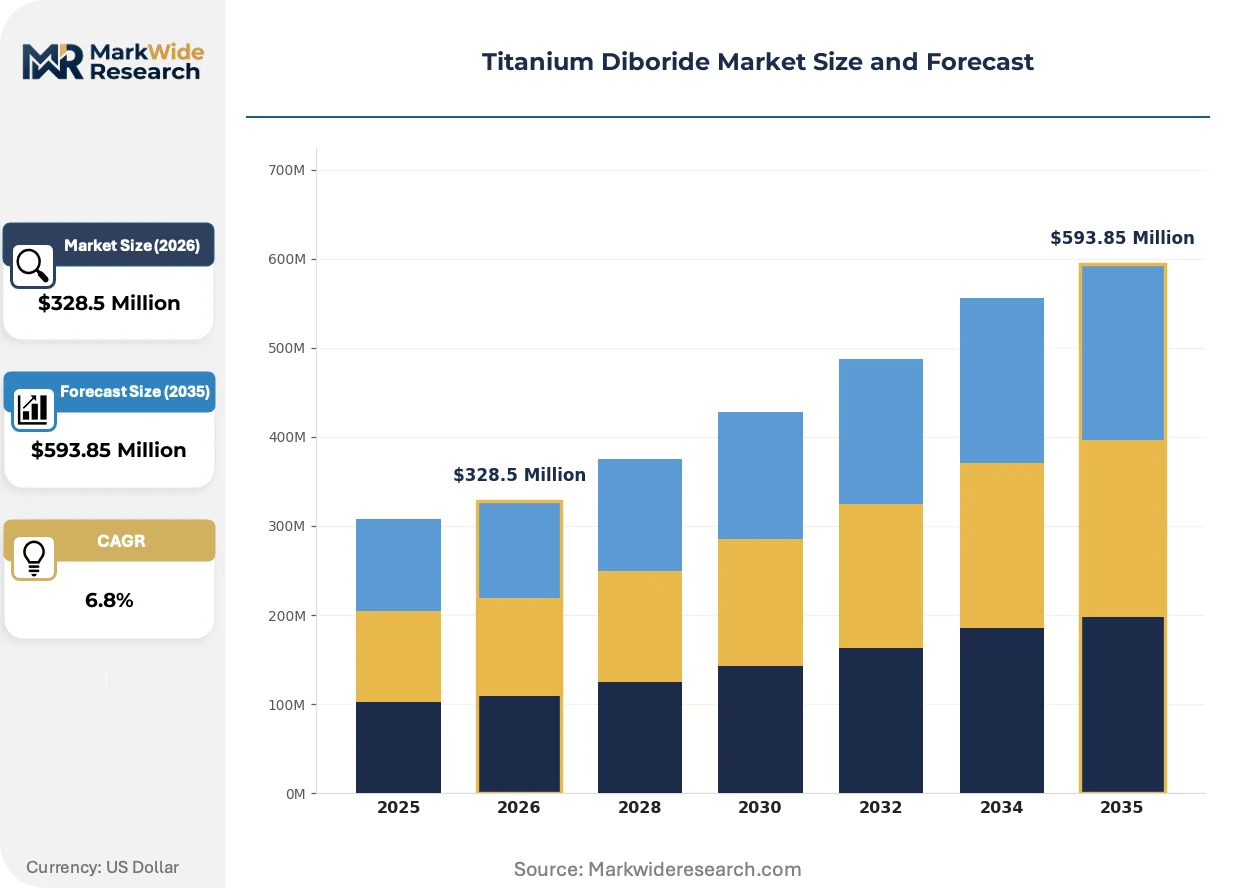
| Market Size in 2026 | $328.5 Million |
| Market Size in 2035 | $593.85 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Coating, Composite, Ceramic Blocks Application: Aerospace Components, Cutting Tools, Armor Systems, Electronics, Wear-Resistant Parts End User Industry: Defense Manufacturers, Electronics Producers, Metalworking Plants, Chemical Processing Units Manufacturing Type: Sintered, Hot Pressed, Self-Propagating High-Temperature Synthesis, Chemical Vapor Deposition |
| Companies Covered | PENSC, Orient Special Ceramics, H.C.Starck, Kennametal, Japan New Metals, Momentive, Dandong Rijin, Treibacher, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Diboride Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward process efficiency and material qualification. Innovations in synthesis are making titanium diboride more economically viable for a broader set of applications, while increasingly stringent end-user requirements drive a focus on purity and consistency.
Self-Propagating High-Temperature Synthesis (SHS) offers a rapid, exothermic reaction pathway to produce TiB2 powder. Producers of standard-grade materials are adopting this method to reduce energy consumption and production cycle times compared to conventional furnace-based processes. This technology is collapsing the cost structure that historically separated TiB2 from other industrial hard materials.
Europe's REACH regulation mandates detailed chemical safety assessments and registration for substances manufactured or imported into the territory. This directive imposes significant compliance overhead on TiB2 powder producers, requiring extensive material characterization and documentation. Non-EU suppliers find this a substantial barrier, often forcing them to partner with larger European distributors to gain market access.
A notable shift in purchasing behavior is the move toward performance-specified procurement in advanced sectors. Buyers in the defense and semiconductor industries are increasingly defining requirements based on final component performance rather than raw powder specifications alone. This trend is most visible in North American and European supply chains, favoring suppliers who can provide integrated solutions and certified material traceability.
Titanium Diboride Market Segmentation
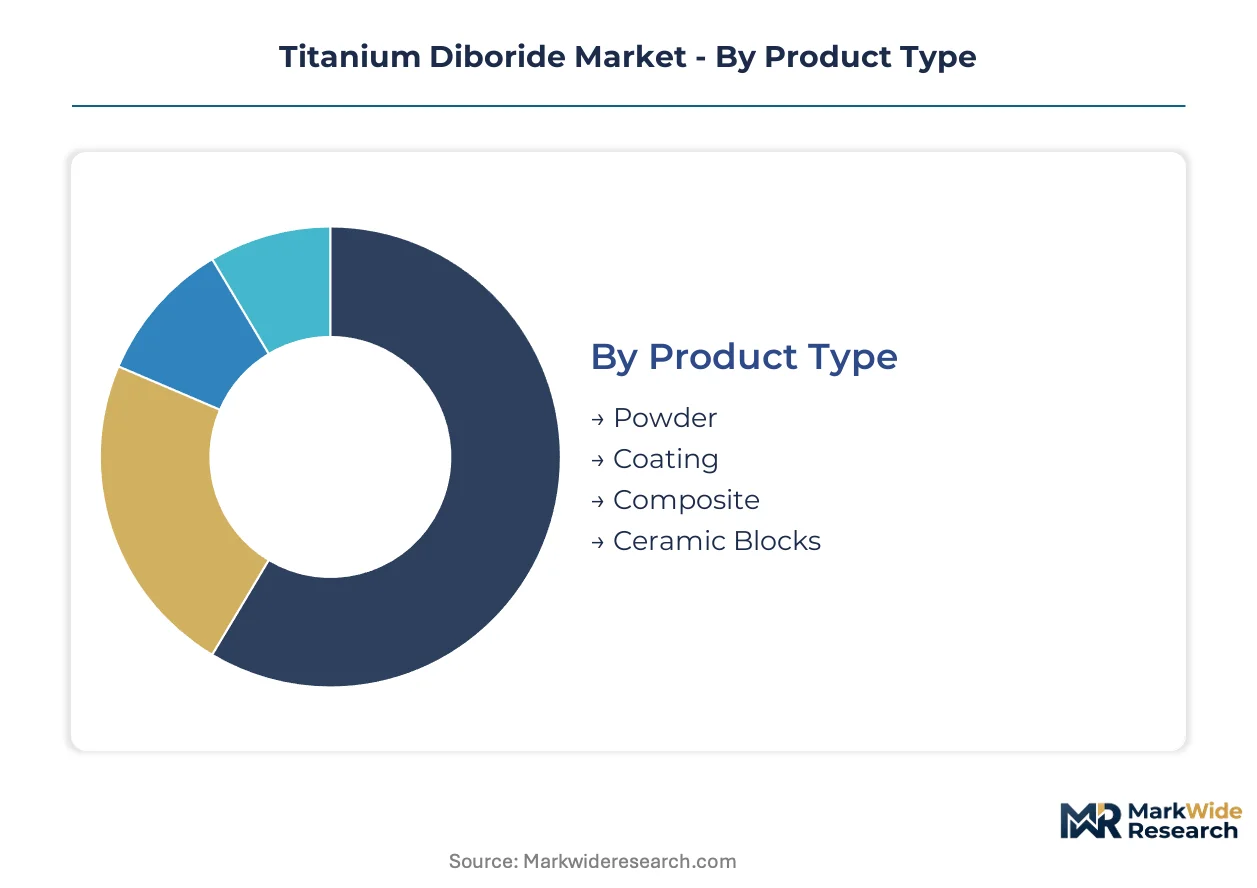
Understanding the titanium diboride market through segmentation reveals distinct value propositions and competitive dynamics across product forms, applications, end-user industries, and manufacturing processes. This granular view allows stakeholders to identify specific growth pockets and assess the varying levels of technological maturity influencing demand and supply.
Product Type:
The production cycle time for titanium diboride varies significantly by product type, with powder forms having the shortest turnaround for bulk production and complex ceramic blocks requiring longer, more intricate manufacturing sequences.
- Powder:Titanium diboride powder is the foundational input, characterized by particle size, purity, and morphology for downstream processing. Demand concentrates in China's advanced materials sector, driven by its role in producing cost-effective standard-grade materials.
- Composite:Titanium diboride composites integrate TiB2 particles into a matrix, often metal or ceramic, enhancing properties like wear resistance and strength. Demand for these materials is accelerating in the European aerospace industry for lightweight structural components.
- Coating:Titanium diboride coatings provide extreme hardness and wear resistance, primarily applied through physical vapor deposition onto cutting tools.
- Ceramic Blocks:Monolithic titanium diboride ceramic blocks offer superior hardness for demanding applications like armor and high-temperature furnace components.
Powder dominates the installed base of titanium diboride production. Composite is where expansion concentrates, driven by performance requirements.
Application:
The cost-effectiveness of titanium diboride varies considerably across its diverse applications, with high-volume, cost-sensitive uses like cutting tools contrasting with premium, performance-driven aerospace requirements.
- Aerospace Components:Titanium diboride is utilized in aerospace for high-temperature resistant parts, such as engine components and thermal protection systems, due to its high melting point and hardness. Demand is strong in the US defense sector, supporting the development of next-generation aircraft.
- Cutting Tools:TiB2 enhances the hardness and wear resistance of cutting tool inserts, improving their lifespan and performance in machining operations. This application sees consistent demand from German metalworking industries, focused on precision and durability.
- Armor Systems:Titanium diboride offers excellent ballistic performance for lightweight armor systems in military vehicles and personnel protection equipment.
- Electronics:In electronics, TiB2 serves as a sputtering target for thin-film applications and as a component in high-performance semiconductor devices.
- Wear-Resistant Parts:This segment includes industrial components requiring extreme durability against abrasion and erosion, such as nozzles and impellers.
Cutting tools represent the highest volume application for titanium diboride. Aerospace components command the highest average value per unit due to stringent performance specifications.
End User Industry:
The maturity of titanium diboride adoption varies across end-user industries, with established use in metalworking contrasting with emerging applications in advanced defense and electronics sectors.
- Defense Manufacturers:Defense manufacturers integrate titanium diboride into armor plating, missile components, and specialized protective gear for its hardness and lightweight properties. Demand is robust from the Indian defense sector, aligning with national self-reliance initiatives.
- Electronics Producers:Electronics producers use TiB2 for its high electrical conductivity and thermal stability in sputtering targets, resistors, and advanced semiconductor packaging. South Korean electronics giants drive significant demand for high-purity material.
- Metalworking Plants:Metalworking plants utilize TiB2-enhanced cutting tools and wear parts to improve efficiency and longevity in various machining and forming processes.
- Chemical Processing Units:Chemical processing units employ titanium diboride components in harsh environments where resistance to corrosion and erosion is critical.
Supply concentration for titanium diboride is currently highest for metalworking plants. Defense manufacturers are increasingly seeking diversified supply chains for strategic resilience.
Manufacturing Type:
The supply concentration for titanium diboride production methods is shifting, with traditional hot pressing facing competition from more scalable and energy-efficient synthesis techniques.
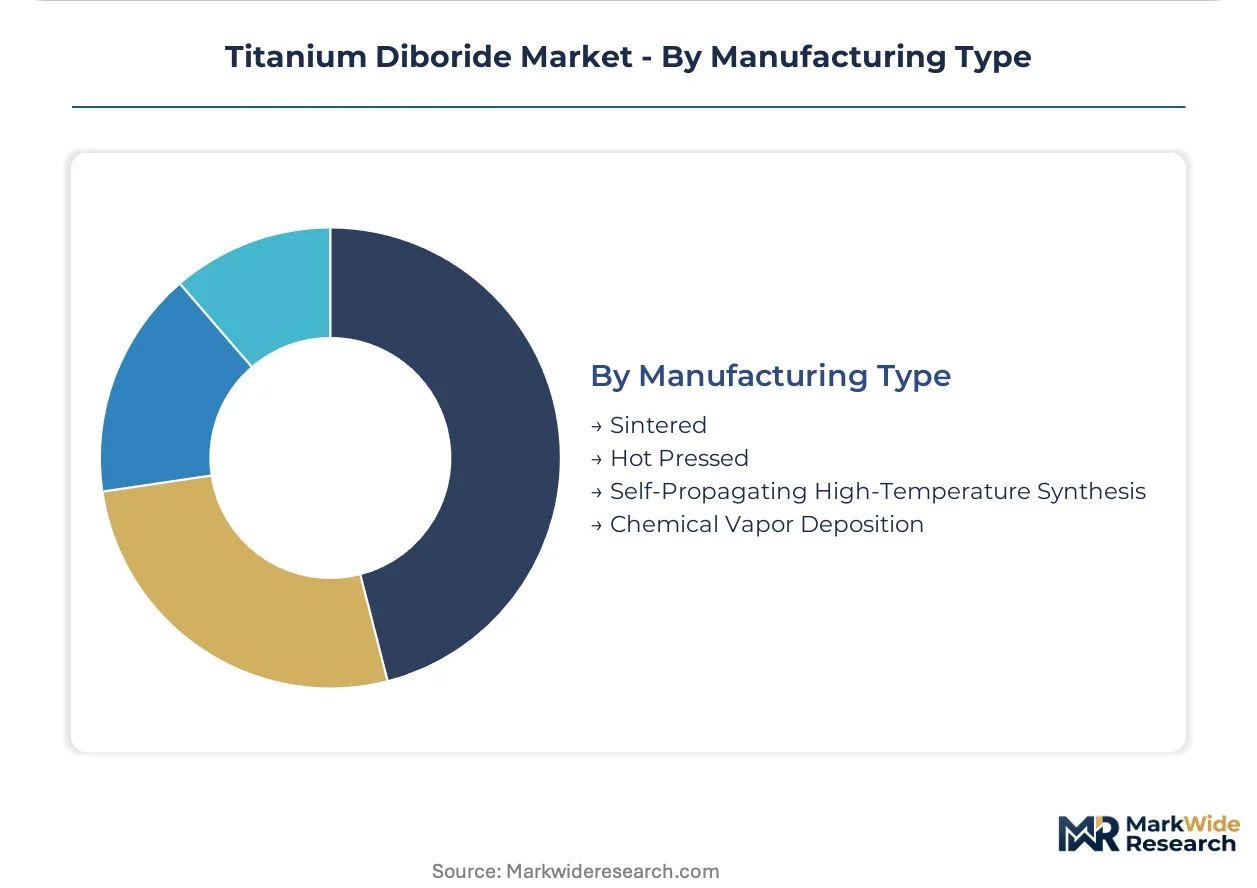
- Self-Propagating High-Temperature Synthesis:SHS is an energy-efficient method producing TiB2 powder through a rapid, exothermic reaction, reducing processing time and energy costs. This method is gaining traction among Chinese producers aiming for higher volume and cost-effectiveness.
- Hot Pressed:Hot pressing involves simultaneously applying heat and pressure to TiB2 powder, yielding dense, near-net-shape ceramic components with superior mechanical properties. European specialized manufacturers often employ this for high-performance aerospace parts.
- Sintered:Sintering involves compacting TiB2 powder and heating it below its melting point to form a solid mass, often used for simpler shapes.
- Chemical Vapor Deposition:CVD produces high-purity TiB2 coatings and films by reacting gaseous precursors on a heated substrate, ideal for thin-film applications.
Self-Propagating High-Temperature Synthesis shows the steepest expansion trajectory in new capacity. Hot Pressed technology maintains its premium position for high-density, complex geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The titanium diboride market exhibits a notable concentration of supply-side activity. China's significant production capacity influences global pricing dynamics for standard-grade materials. This regional focus impacts competitive strategies and material availability across diverse end-use sectors.
China
China's strategic focus on advanced materials and defense manufacturing drives substantial domestic demand. Compliance with GB standards for industrial materials is mandatory for market entry and local supply. High-volume production in regions like the Yangtze River Delta continues to influence global material availability and cost structures.
United States
The United States defense sector strongly demands titanium diboride for next-generation aircraft and armor systems. Workplace safety and material handling regulations from OSHA impact domestic production and import processes. Aerospace manufacturing hubs, such as those near Wichita, Kansas, prioritize high-purity material for critical applications.
Germany
German metalworking industries consistently require titanium diboride for precision cutting tools, emphasizing durability and performance. Europe's REACH regulation mandates detailed chemical safety assessments for imported substances, affecting market access for producers. Stuttgart's robust automotive and precision engineering cluster drives innovation in wear-resistant applications.
India
India's expanding manufacturing and defense sectors represent a significant, underpenetrated market for wear-resistant components. National initiatives like 'Make in India' support domestic production and procurement of advanced ceramics. Bangalore's growing defense and aerospace R&D ecosystem stimulates local demand for specialized materials.
South Korea
Electronics producers in South Korea drive demand for high-purity titanium diboride in sputtering targets and semiconductor devices. Stringent quality standards and advanced material qualification pathways shape procurement practices within the industry. Gyeonggi Province, a major electronics manufacturing hub, focuses on consistent material performance for advanced applications.
Titanium Diboride Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the titanium diboride market. The competitive landscape is tiered, with large-scale producers of standard-grade material coexisting with specialized suppliers of high-purity powders. Strategic archetypes include high-volume commodity suppliers, advanced material innovators, and integrated solution providers. Capacity expansion in China and strategic partnerships for specialized applications are dominant competitive moves.
Specialized material suppliers, such as Germany-based H.C. Starck, focus on high-purity powder grades tailored for demanding electronics and aerospace applications requiring rigorous quality assurance. Meanwhile, Kennametal, a US-based hard materials expert, leverages its extensive expertise to offer integrated cutting tool solutions that enhance performance and longevity across various industrial processes. PENSC, operating with significant manufacturing scale, represents a key player influencing pricing in standard-grade material segments, particularly through its substantial production capacity originating from China and its focus on cost-effective supply.
| Leading Market Players |
|---|
| PENSC |
| Orient Special Ceramics |
| H.C.Starck |
| Kennametal |
| Japan New Metals |
| Momentive |
| Dandong Rijin |
| Treibacher |
| 3M |
| Others |
Cost & Logistics Intelligence
China's significant overcapacity in standard-grade titanium diboride production drives aggressive pricing strategies among suppliers, impacting global market stability and competitive dynamics.
Pricing Analysis
Europe's REACH regulation dictates the pricing tier structure for titanium diboride, emphasizing certification and purity levels. Per-unit transactional pricing dominates, with significant differentiation based on material purity and geographic delivery costs. Price softness stems from high-volume Chinese output. Metalworking plants exhibit high price sensitivity, while aerospace component manufacturers prioritize performance over cost.
Supply Chain Analysis
Large-scale Chinese producers like PENSC and Orient Special Ceramics hold substantial manufacturing capacity for standard-grade titanium diboride. Geographic supply concentration exists in China, with specialized production in Germany and Japan. Production relies on boron carbide and titanium sponge as key raw materials. Regulatory restrictions, such as varied GB standards, present a structural risk. Distribution runs through a mix of direct sales to large industrial users and specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The titanium diboride market experiences a buyer-power shift, driven by the increasing consolidation of defense manufacturers seeking integrated material solutions.
For Market Incumbents: Pre-empt further commoditization by investing in advanced SHS production lines in non-Chinese geographies, mitigating the threat of supply chain disruptions. Deepen vertical integration into composite and coating formulation, leveraging specialized expertise to counter substitution from carbides. Focus R&D on high-purity grades for electronics, securing premium margins against emerging cost pressures.
For New Entrants and Emerging Players: India's expanding defense and manufacturing sectors represent a significant underpenetrated market for titanium diboride. Target wear-resistant parts and advanced ceramic armor applications, leveraging local partnerships for market entry. A go-to-market angle involves offering performance-specified materials with certified traceability, appealing to strategic procurement needs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting in an upward direction across advanced ceramic block manufacturing, signaling long-term value creation. Focus on acquiring specialized producers of high-purity powders or composite formulators with proprietary SHS technology. The signal to watch is the adoption rate of TiB2 in next-generation aerospace engine components.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in SHS | Increases cost-efficiency for high-volume standard-grade material production. |
| Advanced Composite Development | Expands applications in high-performance aerospace and automotive sectors. |
| Certification Pathway Investment | Ensures market access and compliance with stringent European REACH regulations. |
| Strategic Regional Partnerships | Facilitates entry into underpenetrated markets like India's defense sector. |
| High-Purity Powder R&D | Addresses demand for specialized electronics and semiconductor applications. |
Research Approach
Desk research of academic journals, patent databases, and industry association reports preceded structured interviews with materials scientists, procurement managers, and defense sector engineers. This approach combined primary insights with secondary validation from customs data and company filings. Bottom-up aggregation of regional demand and top-down market sizing provided comprehensive triangulation.
Assumptions regarding raw material availability and geopolitical stability were held fixed across the analysis window, while technological advancements in synthesis methods were varied. The analytical framework modeled segmentation by product type, application, end-user industry, and manufacturing process. Compound annual growth rates were derived from historical trends and projected adoption rates of advanced ceramics. Industry-specific inputs included aerospace R&D spending and defense procurement budgets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by high-volume Chinese producers or specialized European innovators would shift outcomes. Forecasts reflect assumptions concerning regulatory stability and energy price trends. Quarterly review of SHS capacity additions and aerospace material qualification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Tellurium Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Silicon Carbide Ceramics Market
Semiconductor Material
Global Electronic Materials Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Europium Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Organic Silicon Coating Market