
 Silicon Germanium Material Market | 2026-2036
Silicon Germanium Material Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Germanium Material Market Analytics
Aftermarket service revenue for SiGe device characterization and reliability testing is fragmenting across foundries and IDMs. GLOBALFOUNDRIES leverages its specialty process portfolio to sustain captive testing operations. IQE PLC anchors merchant epitaxial wafer supply for RF applications. Tower Semiconductor Ltd competes through geographic diversification of its SiGe BiCMOS capacity.
Silicon germanium material denotes semiconductor alloys with germanium mole fractions typically ranging from 20% to 35%, engineered through epitaxial growth on silicon substrates to achieve tunable bandgap properties for high-frequency operation. These alloys serve primarily as the active layer in heterojunction bipolar transistors and photodetectors where silicon alone cannot deliver sufficient carrier mobility. The wafer segment dominates commercial value, with epitaxial layer supply capturing the densest margin pool due to exacting thickness uniformity specifications. RF Devices application demand outpaces photovoltaics, reflecting 5G base station and radar module buildouts. Powder and alloy categories occupy narrower industrial niches in infrared optics and specialized electronics packaging.
The EPA governs hazardous substance reporting for germanium compounds under TSCA, while REACH mandates full supply chain disclosure of SiGe precursor chemicals in Europe. FCC equipment authorization rules for millimeter-wave devices indirectly shape SiGe performance benchmarks for domestic manufacturers. Stakeholders must monitor evolving export control classifications for compound semiconductor substrates and assess dual-source strategies for epitaxial growth equipment before capacity commitments solidify.
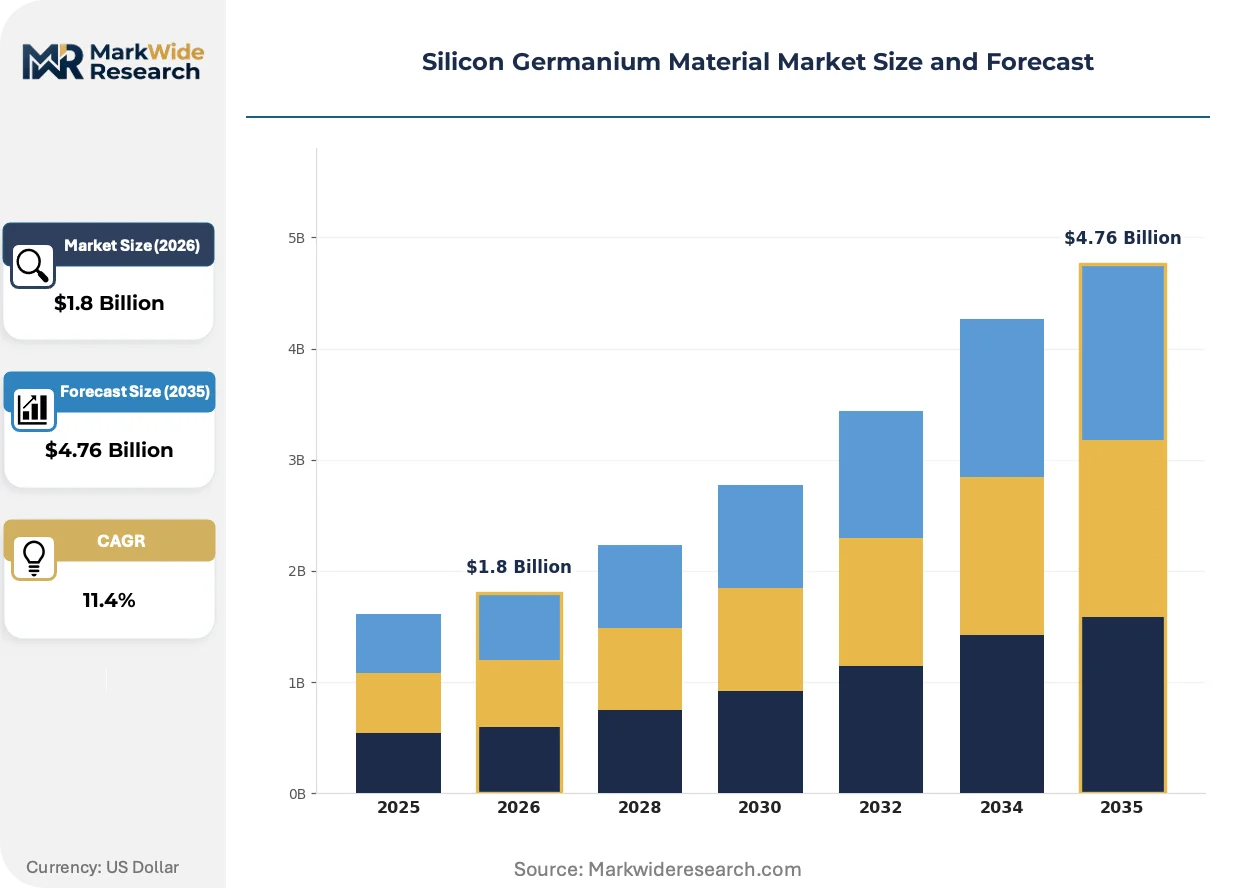
Market Dynamics
Telecommunications infrastructure deployment is concentrating SiGe demand around RF front-end modules for 5G base stations and automotive radar, tightening specifications for epitaxial wafer thickness uniformity while REACH compliance mandates full supply chain disclosure of precursor chemicals across European manufacturing clusters.
Growth Catalysts
- Millimeter-wave spectrum allocation:FCC equipment authorization rules for 60 GHz and above are accelerating SiGe BiCMOS adoption in domestic radar and communication modules.
- REACH disclosure mandates:Full supply chain traceability requirements for SiGe precursor chemicals are standardizing material sourcing protocols across European epitaxial wafer production.
- RF front-end module buildouts:5G base station deployment in Germany, Japan, and South Korea is pulling demand for heterojunction bipolar transistors with germanium mole fractions above 25%.
Market Restraints
- Germanium feedstock volatility:Concentrated mining operations in China and Russia expose epitaxial wafer manufacturers to input cost swings and export licensing delays.
- Substrate diameter limitations:Silicon germanium epitaxy remains constrained to 200mm wafers, capping economies of scale against silicon CMOS migration to 300mm.
- Gallium nitride substitution:GaN-on-SiC power amplifiers are capturing frequency bands above 6 GHz where SiGe efficiency degrades.
Strategic Opportunities
- Photonic integration convergence:SiGe photodetectors paired with silicon photonics waveguides are opening datacom transceiver applications beyond traditional RF.
- India PLI scheme alignment:Domestic semiconductor manufacturing incentives are attracting epitaxial equipment investment for RF device captive supply.
- Automotive radar tiering:Premium L3+ autonomy systems are specifying SiGe-based 77 GHz modules, creating specification tiers distinct from economy radar.
Industry Challenges
- Epitaxial growth technician scarcity:Molecular beam epitaxy and chemical vapor deposition specialists command premium wages, constraining capacity expansion timelines.
- Dual-source equipment qualification:Foundries must validate second-source epitaxial reactors before capacity commitments, extending time-to-market for new SiGe nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Germanium Material Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wafer, Powder, Alloy, Substrate End Use Industry: Aerospace, Telecommunications, Consumer Electronics, Automotive Application: RF Devices, Infrared Sensors, Photovoltaics, Laser Diodes Form: Thin Film, Bulk, Epitaxial Layer, Composite |
| Companies Covered | GLOBALFOUNDRIES, NXP Semiconductors NV, Hitachi Ltd., Tower Semiconductor Ltd, IHP Microelectronics GmbH, Infineon Technologies, IQE PLC, MACOM, STMicroelectronics N.V, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Germanium Material Market Evolving Landscape
Process architecture evolution and regulatory disclosure mandates are compressing development cycles while procurement patterns shift toward captive epitaxial capacity. Three developments are restructuring competitive positioning across the value chain.
Strained silicon germanium channel engineering is rendering obsolete conventional silicon CMOS for millimeter-wave transceiver applications. RF module suppliers in South Korea and Japan are adopting SiGe BiCMOS for 28 GHz and 39 GHz 5G bands. This migration is compressing foundry process development timelines and concentrating volume with specialty analog-capable facilities.
REACH Article 33 disclosure obligations for substances of very high concern are mandating granular material flow documentation from germanium tetrachloride suppliers through finished device manufacturers. European epitaxial wafer producers are deploying blockchain-anchored certificates of analysis to satisfy downstream audit requirements. German and French RF component houses are prioritizing suppliers with pre-validated disclosure systems, reshaping procurement qualification criteria.
Aftermarket characterization services are fragmenting across foundry captive labs and independent test houses. IDMs are unbundling reliability testing from wafer supply contracts, creating discrete revenue pools for burn-in and RF parameter verification. This disintermediation is most visible in North American defense and aerospace supply chains, where security-cleared independent labs are capturing classified device qualification work previously retained in-house.
Silicon Germanium Material Market Segmentation
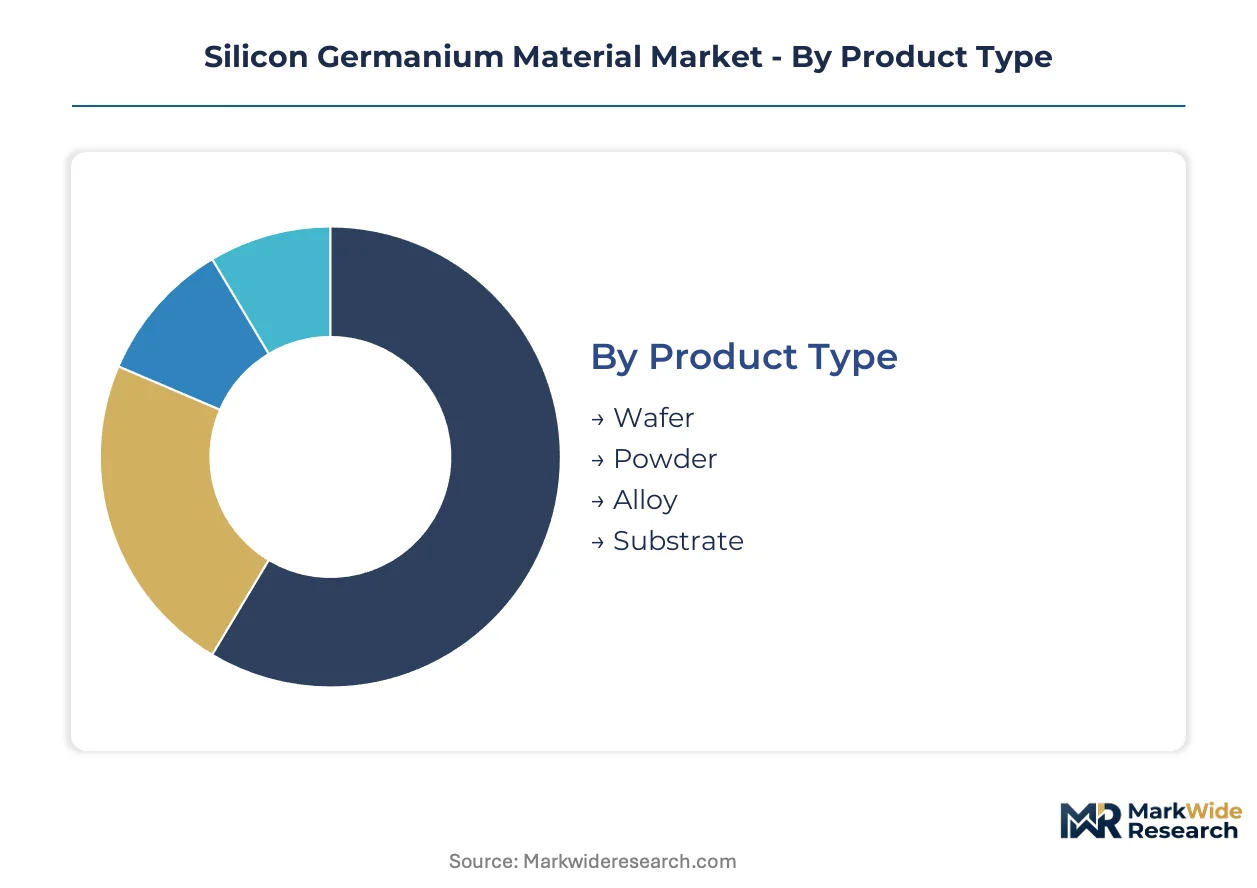
Silicon germanium material markets fragment across four distinct classification schemes, each revealing different competitive dynamics. Product type segmentation exposes margin concentration in epitaxial wafer supply. End-use and application splits illuminate where RF device demand is pulling capacity investments versus where photonics applications are emerging.
Product Type:
Technical specifications vary dramatically across the use-case spectrum, from atomic-level thickness control in epitaxial structures to bulk material for packaging substrates.
- Wafer:Epitaxial wafers with germanium mole fractions of 20-35% command the densest margin pool due to thickness uniformity specifications below 2% variation. Demand concentrates in Germany's IHP Microelectronics cluster, where 5G base station RF front-end modules are tightening specifications for heterojunction bipolar transistor substrates.
- Alloy:Silicon germanium alloys serve as active layers in photodetectors where tunable bandgap properties enable high-frequency operation beyond pure silicon capabilities. Japan's automotive radar suppliers are specifying alloys with germanium content above 25% for 77 GHz modules in premium L3+ autonomy systems.
- Powder:Germanium-silicon powder occupies narrow infrared optics niches, with Chinese and Russian mining operations supplying feedstock for specialized electronics packaging applications.
- Substrate:Bare silicon substrates for SiGe epitaxy remain constrained to 200mm diameter, capping economies of scale against silicon CMOS migration to 300mm.
The dominant share belongs to Wafer, while Alloy is closing the gap fastest.
End Use Industry:
Customer procurement patterns split between defense-aerospace qualification requirements and high-volume automotive tiering.
- Telecommunications:5G infrastructure deployment in South Korea and Japan is pulling demand for RF front-end modules with germanium mole fractions optimized for millimeter-wave bands. FCC equipment authorization rules for 60 GHz and above are accelerating domestic SiGe BiCMOS adoption.
- Automotive:Radar module buildouts are creating specification tiers distinct from economy radar, with premium systems specifying SiGe-based 77 GHz modules for L3+ autonomy.
- Aerospace:North American defense supply chains require security-cleared independent labs for classified device qualification, fragmenting aftermarket testing revenue.
- Consumer Electronics:Millimeter-wave transceiver applications for WiGig and short-range radar are compressing foundry process development timelines.
Telecommunications holds the largest revenue position, with Automotive expanding most quickly through radar tiering.
Application:
Performance requirements diverge between high-frequency RF operation and photonic integration convergence.
- RF Devices:Heterojunction bipolar transistors for 5G base stations and automotive radar dominate commercial volume, with South Korean and Japanese module suppliers adopting SiGe BiCMOS for 28 GHz and 39 GHz bands.
- Photovoltaics:Concentrated solar cell applications represent a mature niche with limited growth trajectory.
- Infrared Sensors:Thermal imaging systems utilize SiGe absorption characteristics in defense and industrial monitoring segments.
- Laser Diodes:Emerging datacom transceiver applications pair SiGe photodetectors with silicon photonics waveguides beyond traditional RF.
RF Devices captures the dominant application share, while Laser Diodes is gaining share fastest through photonic integration.
Form:
Manufacturing complexity and capital intensity separate thin-film epitaxy from bulk material processing.
- Epitaxial Layer:Molecular beam epitaxy and chemical vapor deposition processes require scarce technician expertise, constraining capacity expansion timelines for RF device manufacturers.
- Thin Film:Strained channel engineering is rendering conventional silicon CMOS obsolete for millimeter-wave applications.
- Bulk:Traditional ingot-based material serves legacy packaging and substrate applications with lower technical barriers.
- Composite:Hybrid structures combining SiGe with other semiconductor materials occupy emerging photonics integration niches.
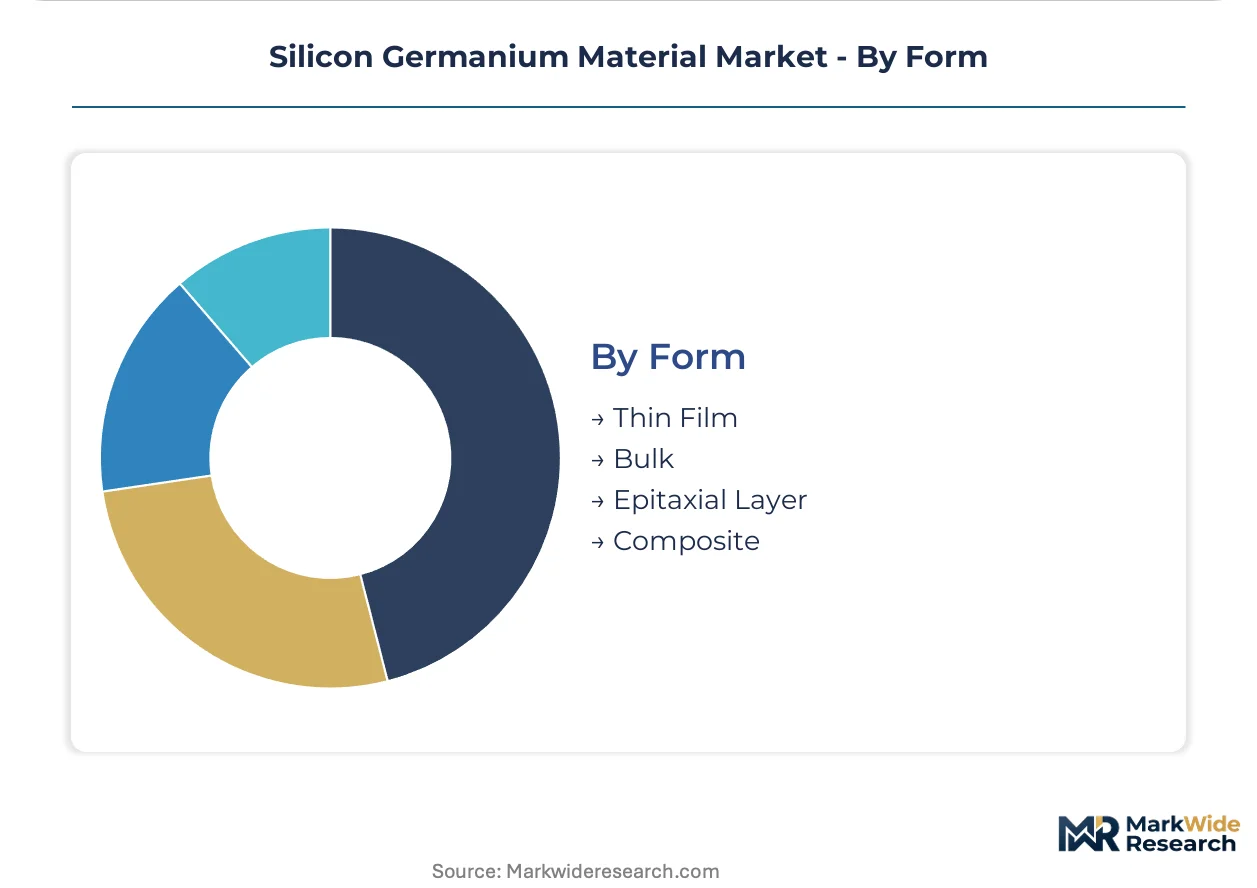
Epitaxial Layer maintains the leading form factor position, with Thin Film climbing the fastest through strained channel adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Epitaxial wafer production concentrates in Germany, South Korea, Japan, and the United States, with each geography anchoring distinct supply chain segments from heterojunction bipolar transistor substrates to RF module assembly.
Germany
REACH Article 33 disclosure obligations mandate granular material flow documentation for SiGe precursor chemicals. The IHP Microelectronics cluster in Frankfurt (Oder) anchors heterojunction bipolar transistor substrate production for 5G base station modules. Infineon Technologies anchors epitaxial wafer capacity serving automotive radar specifications.
South Korea
RF module suppliers adopt SiGe BiCMOS for 28 GHz and 39 GHz 5G bands, compressing foundry process development timelines. The country's national telecommunications regulator shapes millimeter-wave equipment authorization standards. Seoul Capital Area fabrication facilities concentrate strained silicon germanium channel engineering for transceiver applications.
Japan
METI industrial policy directs domestic semiconductor manufacturing incentives toward RF device captive supply. Automotive radar suppliers specify alloys with germanium content above 25% for 77 GHz modules in premium L3+ autonomy systems. Nagoya industrial corridor houses specialized epitaxial growth equipment serving defense-aerospace qualification requirements.
United States
FCC equipment authorization rules for 60 GHz and above accelerate domestic SiGe BiCMOS adoption in radar and communication modules. EPA hazardous substance reporting governs germanium compound handling under TSCA. Greater Boston security-cleared independent labs capture classified device qualification work previously retained in-house.
China
MIIT standards development influences millimeter-wave device performance benchmarks for domestic manufacturers. Concentrated mining operations in Chinese and Russian territories expose epitaxial wafer manufacturers to input cost swings and export licensing delays. Yangtze River Delta fabrication clusters strain against 200mm substrate diameter limitations capping economies of scale.
Silicon Germanium Material Market Competitive Landscape
Integrated device manufacturers and merchant foundries split the market between captive epitaxial capacity and specialty process outsourcing. The structure tiers across three strategic archetypes: full-flow IDMs controlling substrate through module assembly, specialty foundries monetizing analog-capable process nodes, and merchant epitaxial suppliers selling thickness-uniformity-critical wafers. Dominant competitive moves include backward integration into precursor chemical sourcing and geographic diversification of BiCMOS capacity to hedge against export control volatility.
Among IDM-architype anchors, GLOBALFOUNDRIES exemplifies specialty process portfolio leverage, while Infineon Technologies occupies a position within European automotive-qualified supply chains. Tower Semiconductor Ltd represents geographic diversification strategy execution across multiple fabrication jurisdictions.
| Leading Market Players |
|---|
| GLOBALFOUNDRIES |
| NXP Semiconductors NV |
| Hitachi Ltd. |
| Tower Semiconductor Ltd |
| IHP Microelectronics GmbH |
| Infineon Technologies |
| IQE PLC |
| MACOM |
| STMicroelectronics N.V |
| Others |
Value Network & Pricing Analysis
Undercapacity in European epitaxial wafer production is driving aggressive supplier qualification timelines and pricing premiums for thickness-uniformity-critical substrates, while German foundries leverage REACH disclosure mandates to justify long-term contract premiums against spot-market volatility.
Pricing Analysis
Aftermarket service revenue for device characterization and reliability testing now drives lifetime value capture across the value chain. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling intensity. Cost compression in standard-tier epitaxial wafers is intensifying because 200mm substrate constraints limit economies of scale. Automotive radar module suppliers exhibit lowest price sensitivity due to L3+ autonomy qualification requirements, while consumer electronics WiGig transceiver manufacturers face acute margin pressure.
Supply Chain Analysis
GLOBALFOUNDRIES, Tower Semiconductor Ltd, and IHP Microelectronics hold the dominant foundry capacity for SiGe BiCMOS processing. Supply concentrates in Germany, South Korea, and Japan, with raw material sourcing drawing from Chinese and Russian germanium mining operations. Single-source vulnerability in molecular beam epitaxy equipment creates qualification bottlenecks for capacity expansion. Distribution runs through captive foundry networks for IDMs and merchant wafer supply for fabless RF module designers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across aftermarket testing services and epitaxial equipment supply creates entry niches for specialists, as 5G base station deployment pulls demand heterogeneity across millimeter-wave frequency bands.
For Market Incumbents: Harden supply chain resilience through backward integration into precursor chemical sourcing and dual-source qualification for epitaxial growth equipment before capacity commitments solidify. Infineon Technologies anchors European automotive-qualified supply chains against GaN-on-SiC substitution threats above 6 GHz. Captive testing operations at GLOBALFOUNDRIES defend margin pools against independent lab disintermediation in North American defense supply chains. For New Entrants and Emerging Players: India's PLI scheme-aligned domestic semiconductor manufacturing incentives represent the most penetrable entry point for RF device captive supply buildout. Photonic integration convergence in datacom transceiver applications opens white-space beyond traditional RF dominance. A go-to-market angle pairing SiGe photodetectors with silicon photonics waveguides bypasses entrenched heterojunction bipolar transistor competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across epitaxial layer processing due to molecular beam epitaxy technician scarcity and equipment lead time extension. Long-term viability favors merchant epitaxial suppliers with pre-validated REACH disclosure systems serving European RF component houses. Watch blockchain-anchored certificate of analysis adoption rates as an inflection indicator for procurement qualification priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemical Sourcing | REACH Article 33 disclosure mandates in Germany reward suppliers with granular material flow documentation. |
| Dual-Source Epitaxial Equipment Qualification | Tower Semiconductor Ltd's geographic diversification strategy hedges against export control volatility across jurisdictions. |
| Photonic Integration Convergence | SiGe photodetectors paired with silicon photonics waveguides open datacom transceiver applications beyond traditional RF. |
| Blockchain-Anchored Certificate of Analysis Deployment | European epitaxial wafer producers satisfy downstream audit requirements from German and French RF component houses. |
| Security-Cleared Independent Lab Capability Buildout | Greater Boston labs capture classified device qualification work previously retained in-house by North American defense supply chains. |
Research Methodology
A spread of perspectives from epitaxial growth technicians, RF module procurement leads, foundry process engineers, and REACH compliance officers converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from SEC filings of specialty semiconductor foundries, ECHA substance registration databases, FCC equipment authorization records, and customs trade data for germanium compounds. Bottom-up wafer shipment tallies and top-down RF device production estimates were triangulated to anchor volume assumptions.
Demand-supply-balance modeling across the projection horizon segmented by product type, end-use industry, application, and form factor. Modeled dimensions included germanium mole fraction tiers, substrate diameter constraints, and regional regulatory cluster effects. CAGRs were derived from segment-level growth rate convergence analysis. Forecast inputs incorporated millimeter-wave spectrum allocation timelines and automotive radar tiering specifications for L3+ autonomy systems.
Practitioners should monitor germanium feedstock export licensing delays, GaN-on-SiC power amplifier substitution rates above 6 GHz, and epitaxial growth technician wage inflation for early signals of forecast revision. Assumptions reflect disclosed regulatory frameworks and announced capacity commitments. Quarterly review of REACH disclosure system adoption rates and equipment qualification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
Tungsten Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
Gallium Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Transparent Conductive Films Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Electroceramics Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Encapsulant Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
India Liquid Silicon Rubber Market