
 Asia-Pacific Silicone Market | 2026-2036
Asia-Pacific Silicone Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Silicone Market Outlook
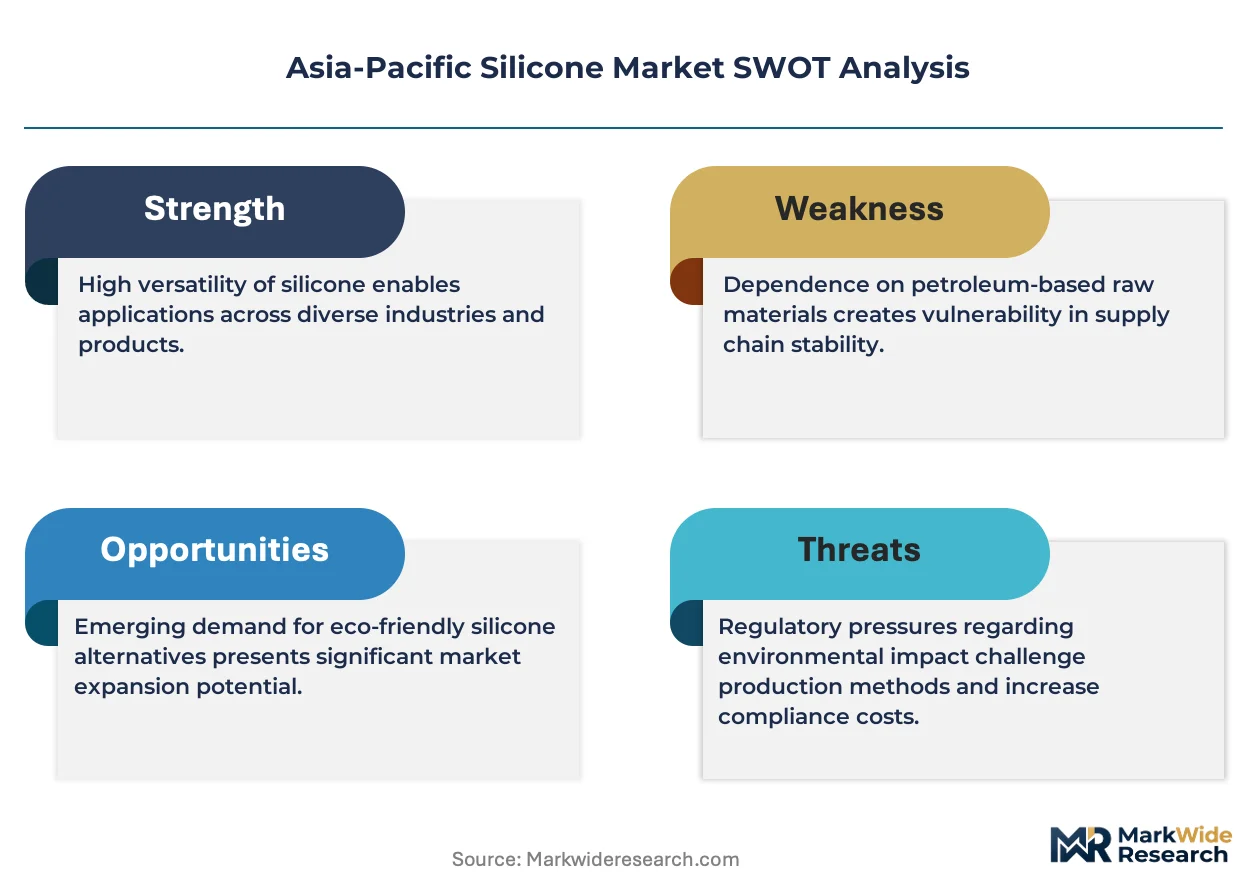
Software-defined formulation services is decoupling silicone procurement from traditional bulk chemical purchasing across the Asia-Pacific region. Shin-Etsu Chemical leverages captive siloxane production to sustain margin control across Japan and China. Wacker Chemie AG anchors its regional position through specialized medical-grade silicone capacity in South Korea. Dow Inc. competes on automotive thermal interface materials, differentiating through direct OEM qualification programs.
Asia-Pacific silicone comprises synthetic polymers built on alternating silicon-oxygen backbones with organic side groups, typically produced via hydrolysis of chlorosilanes followed by polymerization into elastomers, fluids, or resins. These materials provide thermal stability from minus sixty to over two hundred degrees Celsius, electrical insulation, and biocompatibility for industrial sealing, electronic encapsulation, and implantable medical devices. Silicone rubber leads product type revenue due to its dominance in automotive gasketing and healthcare tubing, while silicone oil captures faster growth from transformer fluid and personal care formulation demand. The electronics application segment concentrates margin pools in high-purity semiconductor-grade materials, whereas construction applications remain volume-heavy with thinner pricing.
China's MEE enforces emissions controls on siloxane production facilities, pushing manufacturers toward closed-loop D4/D5 recovery systems. Japan's METI implements chemical substance reporting under its industrial safety framework, filtering market access for non-compliant imports. India's BIS certification requirements for construction sealants create additional compliance layers for regional suppliers. Stakeholders must monitor how China's dual carbon goals reshape energy-intensive silicone monomer production economics and whether India's PLI scheme for electronics manufacturing redirects specialty silicone demand toward domestic formulation.
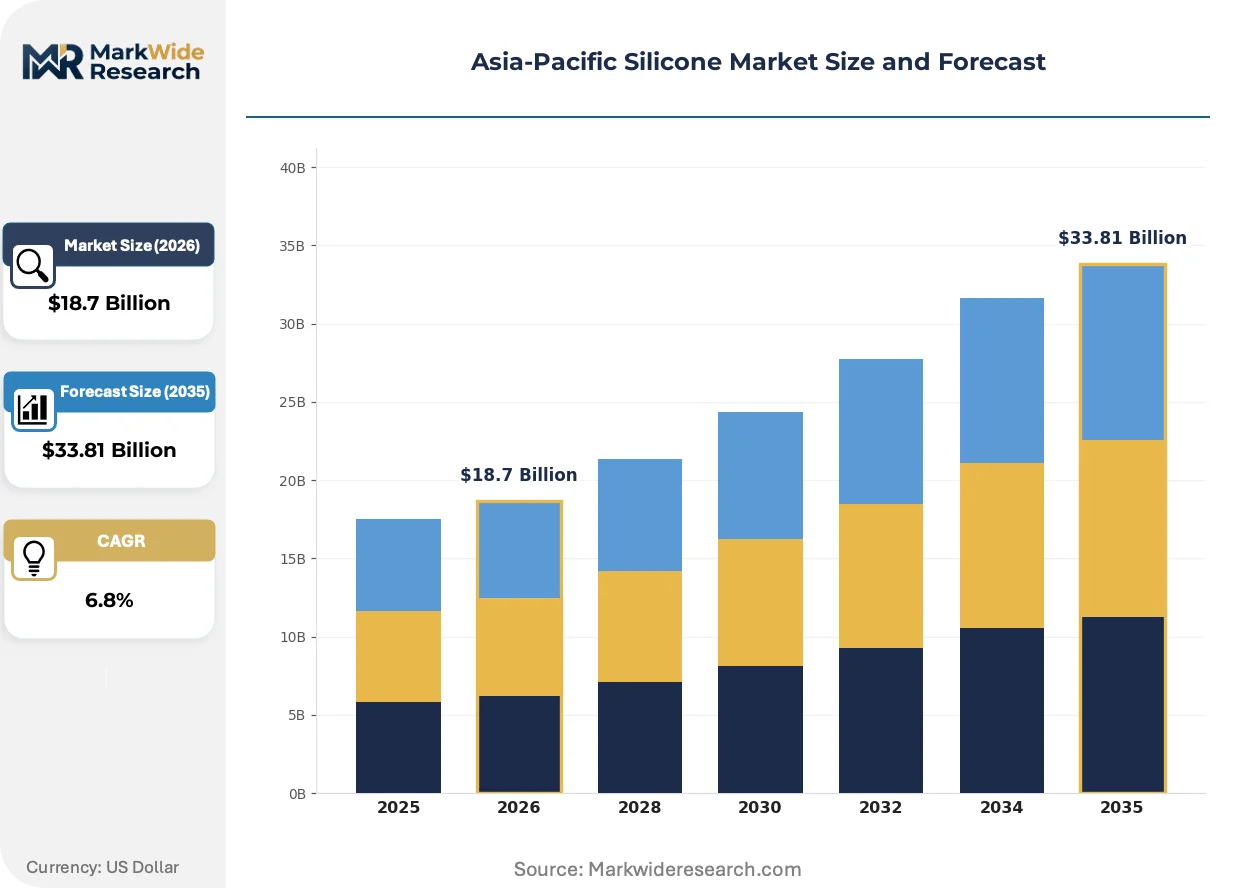
Market Dynamics
China's dual carbon goals are compressing siloxane production economics across the Asia-Pacific silicone market, forcing manufacturers toward closed-loop D4/D5 recovery systems and captive energy supply arrangements.
Growth Catalysts
- Electric vehicle battery thermal management:Automakers across China, Japan, and South Korea are specifying high-purity silicone thermal interface materials for lithium-ion pack cooling, creating specification lock-in with qualified suppliers.
- Japan's METI energy-efficiency mandates:Tightening material specifications for industrial equipment are filtering non-compliant imports and accelerating domestic formulation upgrades.
- Semiconductor-grade purity requirements:Advanced packaging processes in Taiwan and South Korea are demanding ultra-low volatile content silicones, concentrating margin pools with qualified producers.
Market Restraints
- Siloxane feedstock concentration:China's Yangtze River Delta manufacturing corridor controls critical D4/D5 monomer supply, exposing downstream formulators to geographic supply risk.
- MEE emissions compliance costs:China's Ministry of Ecology and Environment enforcement on siloxane facilities is elevating capital requirements for closed-loop recovery infrastructure.
- Fluoropolymer substitution in high-heat automotive:Perfluoroelastomers are displacing silicone in certain turbocharger sealing applications above 250°C.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor and mobile device assembly are redirecting specialty silicone demand toward domestic formulation capacity.
- Medical-grade silicone localization:Underpenetrated implantable device manufacturing in Southeast Asia offers white space for biocompatibility-certified production.
- Software-defined formulation services:Digital specification platforms are decoupling procurement from bulk chemical purchasing, enabling margin capture through technical service bundling.
Industry Challenges
- Semiconductor-grade contamination control:Achieving sub-ppm metallic impurity levels in high-purity silicones requires specialized cleanroom infrastructure and analytical capability that remains scarce regionally.
- Cross-border GB standard harmonization:China's evolving industrial chemical safety standards create compliance timeline uncertainty for multi-country suppliers serving the region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Silicone Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Rubber, Silicone Oil, Silicone Resin, Silicone Sealants Application: Automotive, Construction, Electronics, Medical End User: Manufacturers, Contractors, Hospitals, Consumers Delivery Mode: Bulk, Pails, Drums, Totes |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Elkem ASA, KCC Corporation, DIC Corporation, Wacker Chemie AG, Dow Inc., Mitsubishi Chemical Holdings Corporation, Momentive Performance Materials Inc., Wynca Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Silicone Market Strategic Shifts
Formulation digitization and thermal management material upgrades are restructuring how silicone value is captured across Asia-Pacific industrial supply chains.
Thermally conductive silicone gap fillers with boron nitride loading are electrifying electric vehicle battery pack assembly. Automotive OEMs in China and South Korea are specifying these materials for cell-to-cell thermal runaway protection. This chemistry is compressing traditional thermal pad attachment processes into integrated dispensing operations.
China's GB standards for industrial chemical safety are tightening material traceability requirements. Facilities must now document siloxane chain length distribution and residual chlorosilane content through batch records. High-purity electronics-grade silicones face the steepest compliance burden, with formulators investing in dedicated analytical laboratories.
Specification-driven buying patterns are consolidating procurement around qualified material libraries. Tier-1 automotive and electronics manufacturers in Japan and South Korea are reducing approved supplier lists from dozens to single-digit panels. This concentration is most visible in semiconductor encapsulation grades, where device makers now require direct formulation partnership rather than distributor intermediation.
Asia-Pacific Silicone Market Segmentation
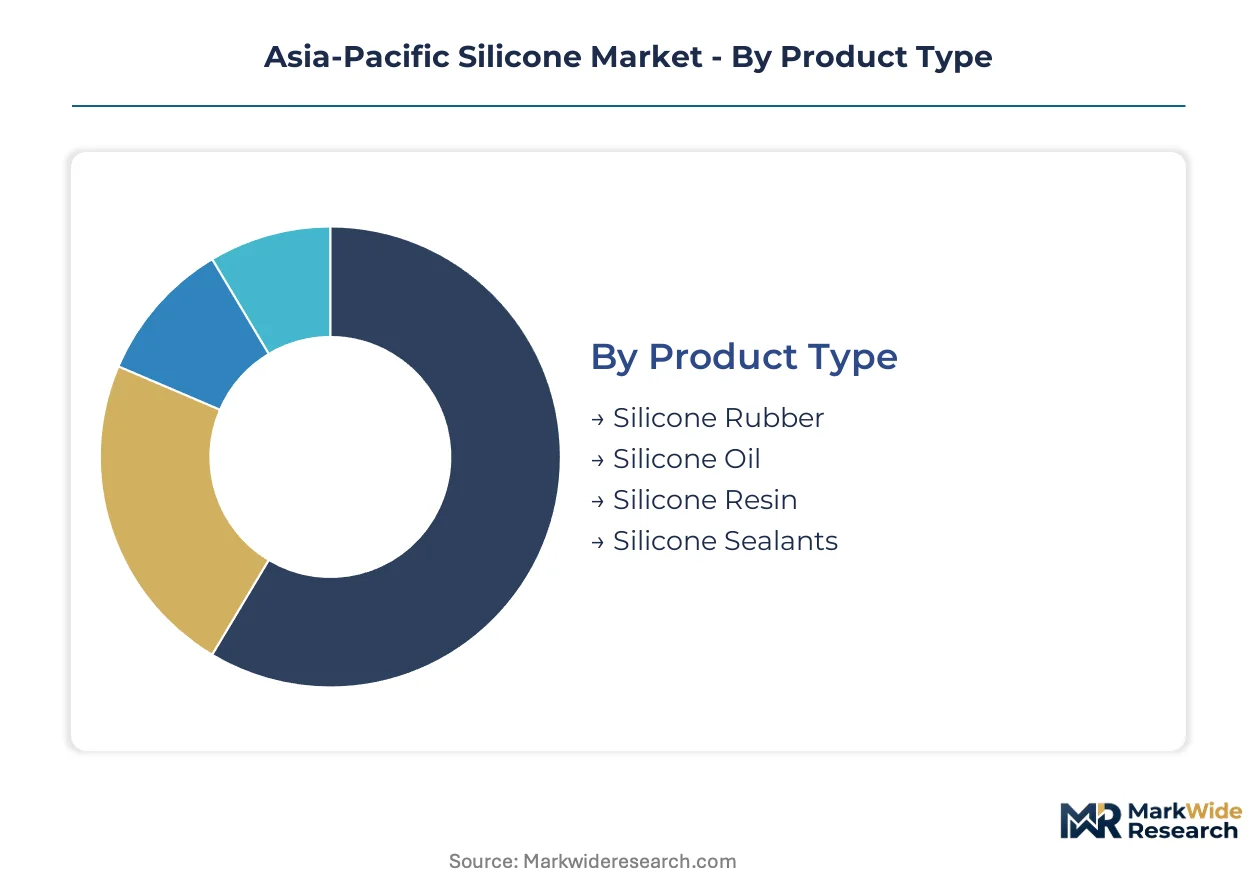
Silicone value capture across Asia-Pacific diverges sharply by molecular architecture and formulation complexity. Product type determines margin structure, while application specificity governs qualification barriers and customer switching costs.
Product Type:
Thermal stability specifications and polymerization chemistry separate commodity from specialty grades across regional supply chains.
- Silicone Rubber:Cross-linked elastomer formulations dominate automotive gasketing and healthcare tubing through vulcanization of high-consistency rubber or liquid silicone rubber. China's Yangtze River Delta automotive cluster consumes volume for EV battery sealing, while Japan's medical device manufacturers specify platinum-cured grades for implantable applications.
- Silicone Oil:Linear polydimethylsiloxane fluids serve transformer dielectric cooling and personal care formulation bases. South Korea's semiconductor fabs demand ultra-low volatile content grades for wafer processing, with viscosity grades from 0.65 to 1,000,000 centistokes tailoring performance to thermal management or lubrication functions.
- Silicone Resin:Three-dimensional branched polymers provide high-temperature coatings and electrical insulation.
- Silicone Sealants:One-part moisture-cure or two-part addition-cure systems serve construction glazing and industrial bonding.
Silicone rubber leads on scale; silicone oil leads on momentum.
Application:
End-use performance requirements stratify procurement behavior from specification-driven to price-sensitive.
- Electronics:Semiconductor encapsulation and thermal interface materials demand sub-ppm metallic impurity control. Taiwan's advanced packaging foundries and South Korea's memory chip manufacturers lock in qualified suppliers through direct formulation partnerships rather than distributor channels.
- Automotive:EV battery thermal management systems specify boron nitride-loaded gap fillers for cell-to-cell runaway protection. Chinese OEMs integrate dispensing operations into pack assembly lines, compressing traditional thermal pad attachment processes.
- Construction:Curtain wall glazing and infrastructure sealing drive volume through India's urban infrastructure buildout and Southeast Asian commercial development.
- Medical:Implantable device tubing and wound care adhesives require biocompatibility certification under varying national frameworks.
Electronics commands premium positioning; automotive is climbing the fastest.
End User:
Procurement sophistication separates direct material specification from intermediary-purchased formulations.
- Manufacturers:Tier-1 automotive and electronics OEMs maintain approved supplier lists of single-digit breadth, requiring direct technical partnership and batch-level traceability documentation under China's GB standards.
- Contractors:Construction applicators purchase through distributor networks with price sensitivity dominating except for high-visibility architectural projects.
- Hospitals:Healthcare procurement departments source medical-grade silicones through group purchasing organizations with regulatory compliance as primary filter.
- Consumers:Personal care and household product formulations reach end users through brand owner retail channels.
Manufacturers concentrate margin capture; contractors represent volume throughput.
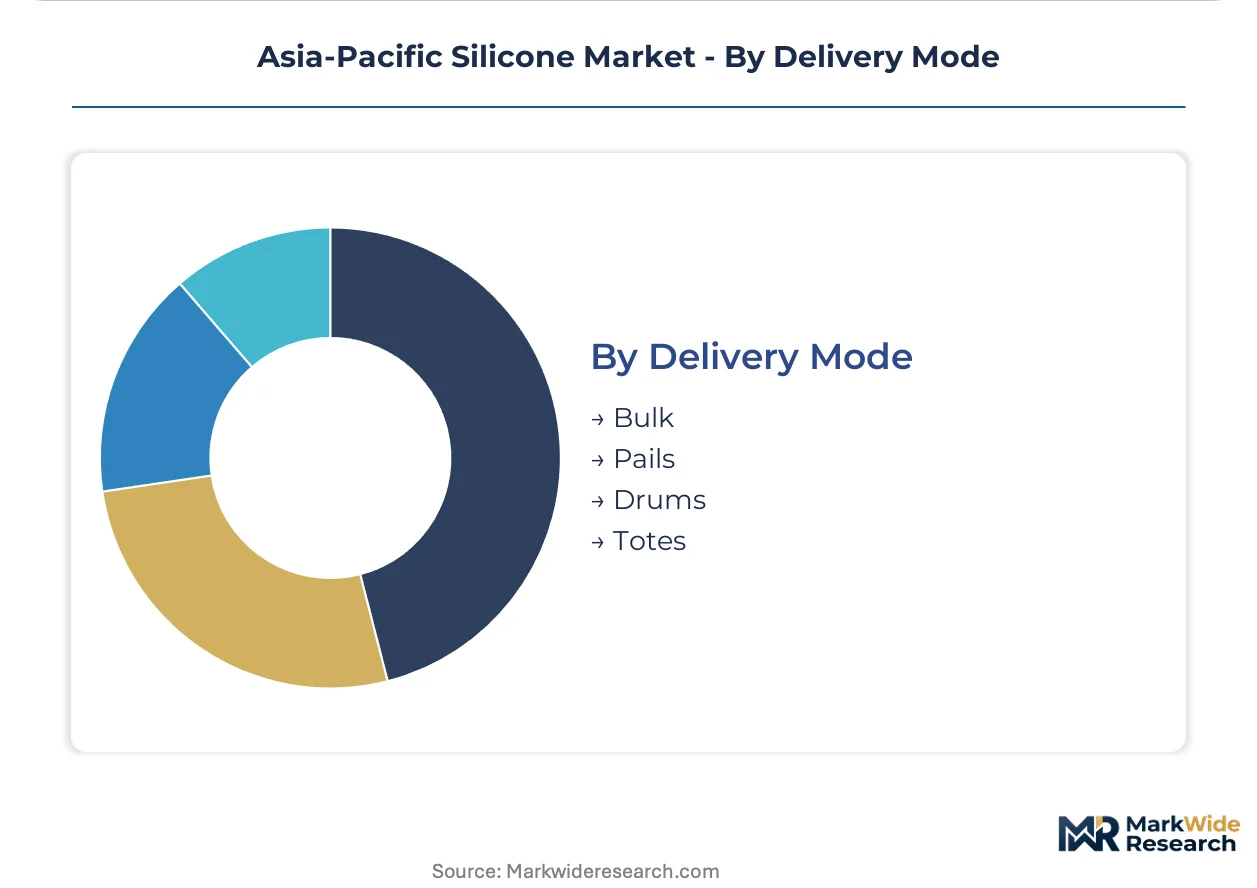
Delivery Mode:
Packaging configuration aligns with customer scale and handling infrastructure across the region's manufacturing geography.
- Bulk:Tanker truck or railcar delivery serves high-volume automotive and electronics manufacturers with dedicated storage and metering systems.
- Pails:Five-gallon containers suit mid-scale formulators and specialty compounders requiring frequent material rotation.
- Drums:Fifty-five gallon steel containers balance logistics efficiency with material protection for regional distributors serving fragmented construction markets.
- Totes:Intermediate bulk containers enable just-in-time delivery to manufacturers without fixed tankage infrastructure.
Bulk delivery anchors industrial supply; totes are gaining share fastest among scaling mid-tier processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands siloxane production scale while Japan concentrates specialty formulation expertise. South Korea anchors semiconductor-grade demand. India's industrialization trajectory and Southeast Asia's manufacturing expansion reshape regional supply chain geometry.
China
Electric vehicle battery manufacturing and construction sealants absorb volume from Yangtze River Delta chemical clusters. MEE emissions enforcement on siloxane facilities pushes producers toward closed-loop D4/D5 recovery systems and captive renewable energy supply. Zhejiang and Jiangsu provinces concentrate domestic formulation capacity serving automotive OEMs.
Japan
Medical device tubing and advanced automotive gasketing sustain premium-grade silicone consumption. METI chemical substance reporting requirements filter import access and accelerate domestic formulation upgrades. Osaka and Nagoya industrial corridors host platinum-cured silicone rubber production for implantable applications.
South Korea
Semiconductor encapsulation and thermal interface materials drive ultra-low volatile content specifications. Memory chip manufacturers and advanced packaging foundries lock suppliers through direct technical partnerships. Seoul metropolitan area and Gyeonggi Province concentrate electronics-grade silicone demand.
India
Urban infrastructure buildout and electronics manufacturing incentives expand construction sealant and specialty silicone consumption. BIS certification requirements for construction applications create compliance layering for regional suppliers. Maharashtra and Gujarat industrial corridors attract formulation investments under PLI scheme coverage.
Thailand
Automotive component manufacturing and medical device assembly sustain mid-tier silicone rubber demand. Japanese and Korean OEM supplier networks localize procurement for regional vehicle production. Eastern Economic Corridor manufacturing zones concentrate foreign direct investment in silicone processing.
Asia-Pacific Silicone Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise commanding premium positioning in medical and electronics grades while commodity elastomers consolidate around scale players. The vendor base organizes into three strategic archetypes: integrated siloxane-to-formulation operators, regional compounders serving automotive tier networks, and application-specific specialists qualifying through OEM direct partnerships. M&A activity concentrates on medical-grade certification assets and Southeast Asian distribution infrastructure. Capacity expansion focuses on high-purity electronics grades and thermally conductive EV battery materials.
Among Japan-based chemical conglomerates, Shin-Etsu Chemical Co., Ltd. exemplifies captive siloxane integration sustaining margin control across formulation tiers. German specialty chemical operators including Wacker Chemie AG occupy positions anchored in medical-grade certification and semiconductor purity standards. Dow Inc. represents North American multinational participation competing through automotive thermal interface material qualification programs and direct OEM technical partnerships.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Elkem ASA |
| KCC Corporation |
| DIC Corporation |
| Wacker Chemie AG |
| Dow Inc. |
| Mitsubishi Chemical Holdings Corporation |
| Momentive Performance Materials Inc. |
| Wynca Group |
| Others |
Value Chain & Pricing Dynamics
Captive siloxane integration across China's Yangtze River Delta anchors both supply security and pricing power for regional silicone formulators. Shin-Etsu Chemical's backward control over D4/D5 monomer production insulates margin structures from feedstock volatility while METI-compliant Japanese producers command specification premiums.
Pricing Analysis
Capacity additions in Zhejiang and Jiangsu provinces are reshaping price floors for standard-grade silicone rubber. Three-tier pricing structure across semiconductor-grade, automotive-certified, and construction-standard levels reflects purity certification and batch traceability investments. Cost compression in construction sealants intensifies as domestic Chinese producers expand high-volume output. Contractors represent the most price-sensitive buyer segment, while semiconductor foundries accept substantial premiums for sub-ppm metallic impurity control.
Supply Chain Analysis
Dual-sourcing mandates from Tier-1 automotive OEMs in Japan and South Korea require qualified suppliers in both China and Southeast Asia. Geographic supply concentration centers on China, Japan, and South Korea for siloxane monomers and specialty formulations. Raw material dependencies rest on methyl chloride, silicon metal, and platinum catalysts. Single-source vulnerability persists for high-purity electronics grades where Taiwan and South Korean foundries lock in direct partnerships. Distribution runs through qualified material libraries with approved supplier lists narrowing to single-digit panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific silicone has entered a late-cycle quality phase where specification lock-in with EV battery and semiconductor manufacturers commands durable margin premiums. The demand shift toward ultra-low volatile content grades for advanced packaging processes justifies premium positioning over volume competition.
For Market Incumbents: Deploy direct OEM qualification programs to secure thermal interface material specification lock-in with Chinese and South Korean battery manufacturers. Fluoropolymer substitution above 250°C threatens turbocharger sealing applications, necessitating R&D investment in phenyl-modified silicone alternatives. Channel control through dedicated analytical laboratories supports GB standard compliance documentation. For New Entrants and Emerging Players: Tier-2 automotive suppliers in Thailand's Eastern Economic Corridor offer accessible entry points for mid-grade silicone rubber qualification. Medical device assembly in Southeast Asia remains underpenetrated for biocompatibility-certified production. A formulation partnership model with Japanese trading houses provides regulatory navigation and customer access without greenfield certification investment. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders serving automotive tier networks because specification-driven buying patterns consolidate procurement around qualified material libraries. The five-to-ten year viability thesis rests on EV thermal management material demand trajectories. Acquisition targets should demonstrate direct OEM technical partnerships rather than distributor-dependent revenue. The signal to watch is BIS certification timeline acceleration under India's PLI scheme coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomers | Captive D4/D5 supply insulates margin control against MEE emissions compliance cost pass-through. |
| Medical-Grade Certification Investment | Biocompatibility certification under Japan's PMDA framework unlocks implantable device tubing premiums. |
| Direct OEM Technical Partnership | Semiconductor foundries in Taiwan now require formulation partnership bypassing distributor intermediation. |
| Closed-Loop D4/D5 Recovery Systems | MEE enforcement on siloxane facilities elevates capital requirements filtering non-compliant producers. |
| Software-Defined Formulation Services | Digital specification platforms enable margin capture through technical service bundling beyond commodity sales. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down siloxane production tracking forms the analytical core of this study. Primary interviews with silicone plant managers, automotive Tier 1 procurement leads, semiconductor fab materials engineers, and medical device regulatory affairs directors combined with secondary validation from customs trade data, GB standard documentation, METI chemical substance filings, and SEC 10-K disclosures from listed chemical conglomerates. Triangulation across these sources ensures demand estimates align with verified supply-side capacity.
Historical trendline analysis of silicone rubber, oil, and resin consumption patterns across automotive, electronics, construction, and medical applications established baseline growth trajectories. The projection framework models grade tier, end-use industry, packaging format, and regional production hub segmentation throughout the forecast period. CAGRs derive from elasticity-adjusted demand curves incorporating EV battery thermal management content per vehicle and semiconductor advanced packaging silicon intensity metrics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to China's dual carbon policy enforcement stringency and India's PLI scheme electronics manufacturing uptake. Deviation in MEE emissions compliance timeline or GB standard harmonization pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Electronic Ceramics Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Europe Semiconductor Materials Market
Semiconductor Material
Solar Silicon Ingots Market
Semiconductor Material
Compound Semiconductor Materials Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Semiconductor Materials Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Semiconductor Silicon Material Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
Synthetic Sapphire Market