
 Monocrystalline Silicone Market | 2026-2036
Monocrystalline Silicone Market Size, Share, and Industry Trends Forecast 2026-2036
Monocrystalline Silicone Market Analytics
ISO 9001 certification for semiconductor material suppliers is collapsing the vendor landscape as tier-one foundries disqualify uncertified ingot sources. LONGi Green Energy Technology leverages polysilicon-to-module vertical integration to dominate solar-grade supply. Shin-Etsu Chemical sustains its position through unmatched R&D intensity in 300mm wafer engineering. SUMCO Corporation anchors the memory chip segment with captive supply agreements binding Korean and Japanese fabs.
Monocrystalline silicone consists of a single-crystal silicon structure grown via the Czochralski or float-zone process, achieving defect densities below one per square centimeter and resistivity controlled to within 0.001 ohm-cm for semiconductor applications. Its primary purpose is to serve as the substrate material for photovoltaic cells and integrated circuits where electron mobility and thermal stability determine device performance. The wafer segment leads value capture as 300mm diameter substrates command premium pricing in advanced logic foundries, while the photovoltaics application category extends volume dominance through utility-scale deployment in Asia-Pacific markets. The electronics application segment concentrates margin pools where purity grades exceed eleven nines for power semiconductor devices.
The EPA enforces perfluorinated compound emission limits at US polysilicon purification plants, while REACH restricts hazardous dopant usage in European wafer fabrication, and China's MEE implements carbon intensity benchmarks for metallurgical-grade silicon converters. These frameworks collectively raise capital requirements for new entrants and redirect investment toward closed-loop recycling systems. Stakeholders must monitor divergence between solar-grade and semiconductor-grade purity standards as end-use specifications harden.
Market Dynamics
Semiconductor-grade purity requirements are hardening faster than solar-grade specifications, bifurcating capital allocation and technical roadmaps across the value chain. Foundry migration to 3nm nodes demands defect densities below 0.1 per square centimeter, forcing ingot producers to choose between diverging certification paths.
Growth Catalysts
- Advanced Node Migration:Logic foundries in Taiwan and South Korea now require 300mm wafers with eleven-nines purity for gate-all-around transistor architectures. This specification tier commands 40-60% price premiums over preceding nodes.
- EU Green Deal Carbon Border Adjustments:European solar module imports face embodied carbon audits starting 2026, favoring polysilicon produced via hydropower-powered reduction. Norwegian and French ingot sources gain procurement preference.
- China's Dual Carbon Mandates:Provincial governments in Xinjiang and Inner Mongolia now tie metallurgical-grade silicon converter permits to renewable energy quotas. This policy compresses high-carbon capacity while concentrating compliant supply.
Market Restraints
- Polysilicon Feedstock Volatility:Metallurgical-grade silicon metal prices swing with Chinese smelter curtailments during power rationing seasons. Wafer producers lack pass-through mechanisms for these input spikes.
- Equipment Lead Time Concentration:Czochralski crystal pullers from German and Japanese suppliers carry 18-24 month delivery backlogs. New entrants cannot secure capacity without incumbent relationships.
- Fluorinated Gas Substitution Limits:REACH restrictions on sulfur hexafluoride etchants lack technically viable alternatives for certain wafer cleaning steps. Process engineers face compliance-performance trade-offs.
Strategic Opportunities
- India's PLI Scheme for Solar Manufacturing:Production-linked incentives cover integrated polysilicon-to-module investments with 50% capital expenditure support. Domestic wafering capacity remains underdeveloped relative to cell and module assembly.
- Silicon Carbide Hybrid Substrates:Heterogeneous integration of monocrystalline silicon with SiC layers enables power semiconductor performance without full SiC wafer costs. Electric vehicle traction inverters represent the anchor application.
- Closed-Loop Dopant Recovery:Ion implantation waste streams contain recoverable boron and phosphorus at concentrations viable for re-purification. EPA emission limits on phosphorus trichloride create economic incentive for circular systems.
Industry Challenges
- Crystal Growth Technician Scarcity:Czochralski process optimization requires 10-15 year apprenticeship curves. Foundry expansion plans outpace vocational pipeline output in Taiwan, Japan, and Germany.
- ISO 9001 Certification Timelines:Semiconductor material qualification cycles span 18-36 months from ingot sample to approved vendor status. Solar-grade producers attempting upstream migration face cash flow gaps during transition.
- Legacy Furnace Retrofit Complexity:Existing 200mm crystal pullers cannot economically convert to 300mm diameter production. Asset stranding risk concentrates among second-tier Japanese and European equipment owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monocrystalline Silicone Market |
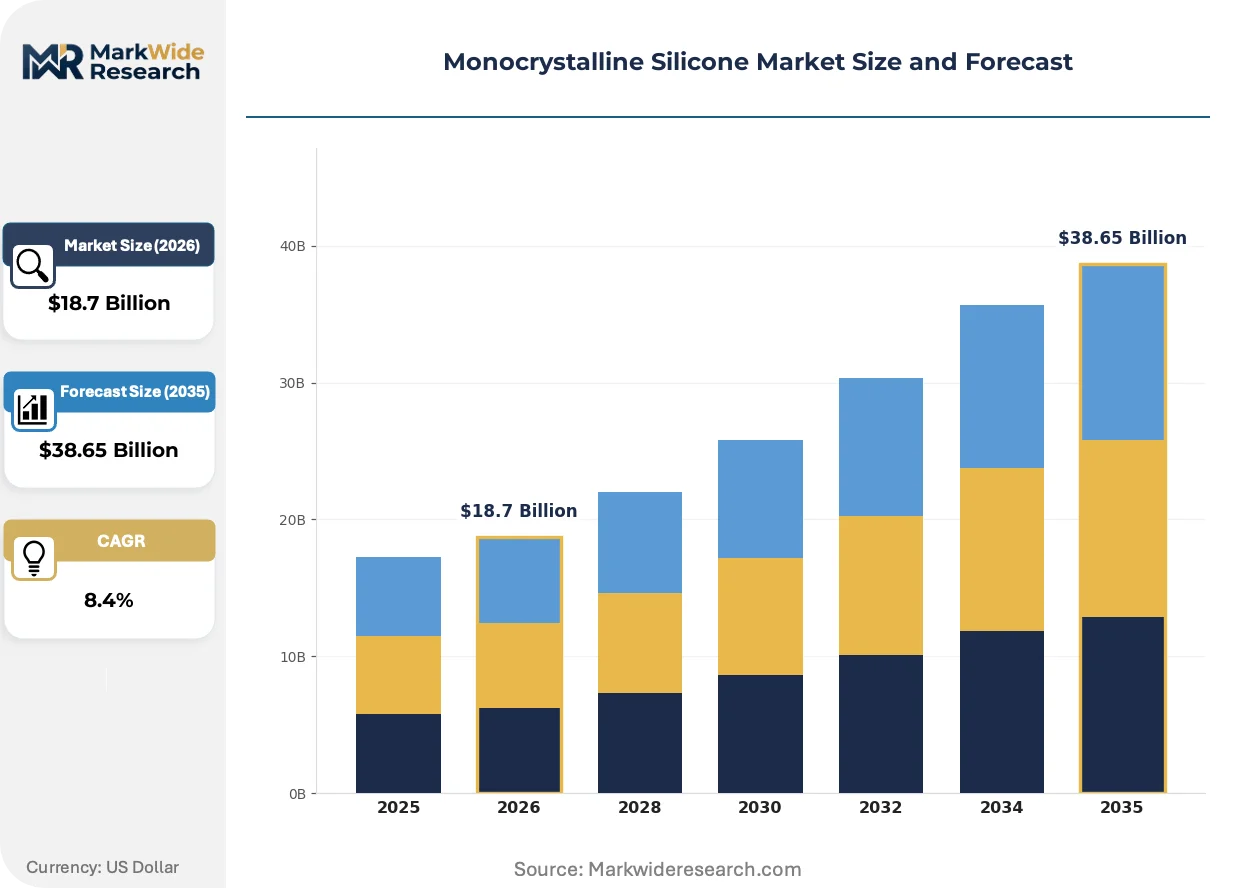
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Cells, Wafers, Ingots, Modules End User: Residential, Commercial, Industrial, Utilities Application: Photovoltaics, Electronics, Automotive, Aerospace Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | LONGi Green Energy Technology, SUMCO Corporation, Shin-Etsu Chemical, Siltronic, GlobalWafers, Comtec Solar, MCL Electronic Materials, GRINM Semiconductor Materials, Pure Wafer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monocrystalline Silicone Market Evolving Landscape
Continuous crystal growth methods are displacing batch Czochralski processing, promising 30-40% throughput gains but requiring fundamental reactor redesign. This transition coincides with magnetic field-assisted doping control and AI-driven defect prediction entering commercial deployment.
Magnetic Czochralski (MCZ) technology applies superconducting magnets to molten silicon during crystal pulling, suppressing thermal convection and oxygen incorporation. Memory chip fabricators in South Korea now specify MCZ wafers for DRAM cell capacitors where oxygen precipitate control determines yield. The technology is fragmenting supplier tiers as only Shin-Etsu and SUMCO maintain qualified MCZ capacity at scale.
China's MEE implements carbon intensity benchmarks for metallurgical-grade silicon converters starting 2025, with provincial variation in enforcement stringency. Xinjiang smelters face 20% reduction targets versus 2020 baselines, accelerating furnace electrification and hydropower sourcing. European wafer producers now audit Chinese polysilicon suppliers for MEE compliance documentation to satisfy downstream CSRD disclosure requirements.
Long-term supply agreements are displacing spot procurement for semiconductor-grade ingots as foundries lock in 300mm capacity through 2030. Korean memory chip makers bind Japanese wafer suppliers to five-year take-or-pay contracts with price reopeners tied to polysilicon indices. This concentration is most visible in HBM3 and advanced DRAM supply chains where any disruption halts billion-dollar fab output.
Monocrystalline Silicone Market Segmentation
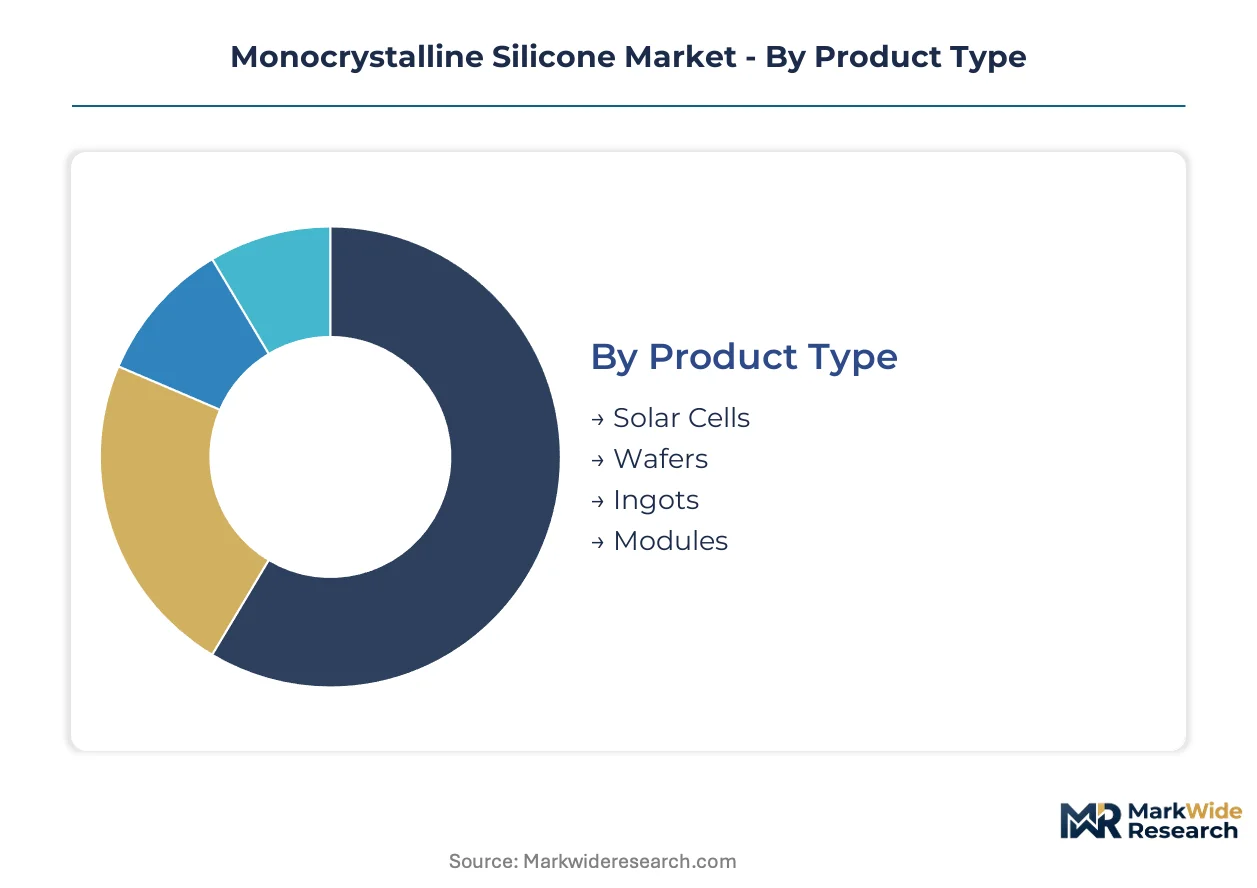
Segmentation in monocrystalline silicone reveals divergent purity standards and capital intensity across end-use categories. Semiconductor-grade specifications command premium positioning while solar-grade volumes anchor capacity utilization.
Product Type:
Domestic production concentrates on solar cells and modules for local installation markets, whereas wafers and ingots flow disproportionately toward export-led semiconductor supply chains in East Asia.
- Wafers:300mm diameter substrates achieve eleven-nines purity through magnetic Czochralski processing. Foundries in Taiwan and South Korea specify these for 3nm gate-all-around architectures where defect densities below 0.1 per square centimeter determine yield.
- Solar Cells:Photovoltaic substrates prioritize cost-efficient crystal growth over extreme purity, with utility-scale deployment in Asia-Pacific driving volume procurement. China's dual carbon mandates accelerate domestic cell manufacturing capacity.
- Ingots:Cylindrical silicon crystals grown via float-zone or Czochralski methods serve as feedstock for subsequent wafering operations.
- Modules:Encapsulated cell assemblies integrate glass, encapsulant, and framing for field installation.
Wafers hold the largest share; momentum sits with solar cells.
End User:
Cost tiers separate residential rooftop systems from utility-scale procurement, with industrial captive generation occupying a mid-tier pricing band.
- Utilities:Centralized solar farms in India and the United States procure monocrystalline modules at gigawatt scale, leveraging production-linked incentives and investment tax credits to compress levelized cost of electricity.
- Industrial:Manufacturing facilities deploy rooftop and ground-mounted systems to offset carbon disclosure obligations under CSRD and similar frameworks.
- Commercial:Office buildings and retail properties install smaller-scale arrays for operational expenditure reduction.
- Residential:Distributed generation systems serve single-family homes with net metering arrangements.
Utilities command dominant procurement volumes; industrial adoption is climbing fastest.
Application:
Volume concentrates in photovoltaics while margin pools concentrate in electronics where purity certifications create supplier stickiness.
- Photovoltaics:Utility-scale and distributed solar generation consumes monocrystalline silicon at terawatt-scale annual deployment, with hydropower-powered polysilicon gaining preference under EU carbon border adjustments.
- Electronics:Integrated circuit substrates require ISO 9001-certified supply chains with qualification cycles spanning 18-36 months, binding foundries to qualified Japanese and Korean wafer vendors.
- Automotive:Electric vehicle inverters and onboard charging systems specify power semiconductor-grade material.
- Aerospace:Satellite and high-reliability electronics demand radiation-hardened silicon with specialized doping profiles.
Photovoltaics anchors volume demand; electronics captures premium expansion.
Distribution Channel:
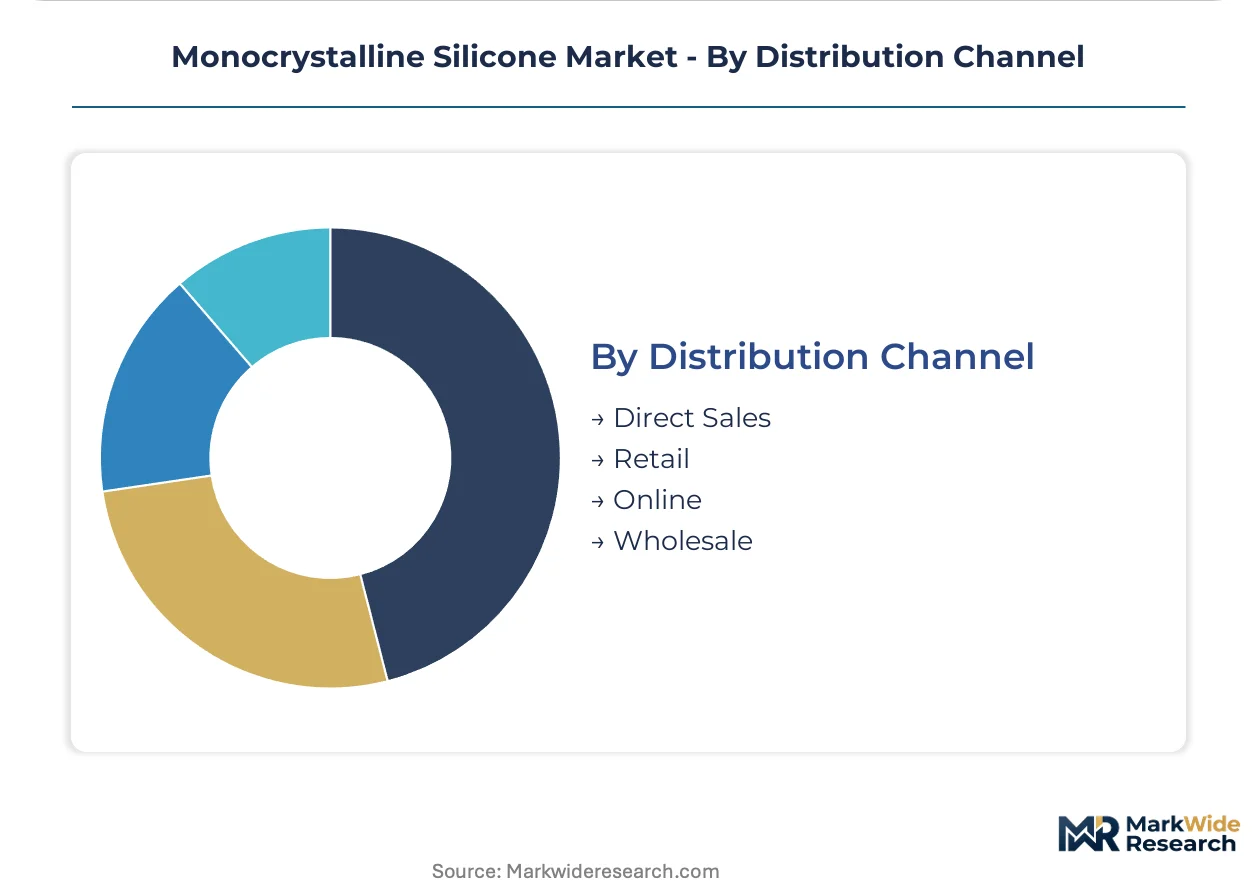
Supply concentration favors direct sales for semiconductor-grade material while solar-grade products flow through wholesale and retail intermediaries.
- Direct Sales:Foundries and solar developers negotiate long-term supply agreements with ingot and wafer producers, locking in capacity through 2030 with price reopeners tied to polysilicon indices.
- Wholesale:Module assemblers and EPC contractors source cells and encapsulation materials through distributor networks.
- Retail:Residential installers procure modules and balance-of-system components through local supply houses.
- Online:Emerging procurement channel for standardized solar components in distributed generation markets.
Direct sales dominates semiconductor supply; wholesale channels serve solar volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon mandates and India's PLI scheme for solar manufacturing are redirecting capital toward integrated polysilicon-to-module investments. Taiwan and South Korea foundries lock in 300mm wafer supply through long-term agreements. European carbon border adjustments favor hydropower-powered polysilicon from Nordic sources.
China
Xinjiang and Inner Mongolia smelters face 20% carbon intensity reduction targets under MEE benchmarks starting 2025, accelerating furnace electrification. Provincial governments now tie metallurgical-grade silicon converter permits to renewable energy quotas. The Yangtze River Delta concentrates solar cell manufacturing where LONGi Green Energy Technology operates integrated polysilicon-to-module facilities.
Taiwan
TSMC and UMC foundries demand 300mm wafers with eleven-nines purity for 3nm gate-all-around transistor production. The island's EPA enforces perfluorinated compound emission limits at wafer fabrication facilities. Hsinchu Science Park anchors captive wafer supply serving leading memory and logic chip fabricators with ISO 9001-certified material.
South Korea
Samsung and SK Hynix bind Japanese wafer suppliers to five-year take-or-pay contracts with price reopeners tied to polysilicon indices. MFDS regulates hazardous dopant usage in semiconductor manufacturing processes. The Seoul Capital Area concentrates DRAM and HBM3 production where magnetic Czochralski wafer specifications determine yield.
United States
The Inflation Reduction Act's domestic content bonuses incentivize polysilicon purification investments for solar supply chains. EPA enforces perfluorinated compound emission limits at US polysilicon plants. The Pacific Northwest attracts hydropower-dependent metallurgical-grade silicon converters seeking compliance with EU Green Deal carbon border adjustments.
Germany
REACH restrictions on sulfur hexafluoride etchants create compliance-performance trade-offs for wafer cleaning operations. The country's central bank monitors capital flows into semiconductor material investments under CSRD disclosure frameworks. Saxony's Silicon Saxony cluster hosts Siltronic operations serving European automotive power semiconductor demand.
Monocrystalline Silicone Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with public companies dominating semiconductor-grade supply and private entities capturing solar-grade volume. The vendor base stratifies into three tiers: integrated polysilicon-to-module operators, pure-play wafer manufacturers, and captive foundry suppliers. Strategic moves center on backward integration into polysilicon purification and capacity expansion for 300mm diameter substrates.
Within the integrated operator archetype, LONGi Green Energy Technology exemplifies vertical control from metallurgical-grade silicon through module assembly. Among pure-play wafer specialists, SUMCO Corporation and Shin-Etsu Chemical occupy positions defined by magnetic Czochralski qualification and long-term foundry agreements. These three entities anchor the competitive structure, representing divergent paths: solar volume scale versus semiconductor purity premiums versus captive memory chip supply.
| Leading Market Players |
|---|
| LONGi Green Energy Technology |
| SUMCO Corporation |
| Shin-Etsu Chemical |
| Siltronic |
| GlobalWafers |
| Comtec Solar |
| MCL Electronic Materials |
| GRINM Semiconductor Materials |
| Pure Wafer |
| Others |
Value Network & Pricing Analysis
Eighteen-to-twenty-four-month lead times for Czochralski crystal pullers from German and Japanese suppliers concentrate procurement power among established foundry relationships, compressing pricing leverage for solar-grade producers attempting upstream migration while amplifying premiums for qualified semiconductor-grade supply.
Pricing Analysis
Certification level creates the primary spread between solar-grade and semiconductor-grade material, with ISO 9001 qualification cycles spanning eighteen-to-thirty-six months and commanding forty-to-sixty percent price premiums at the wafer level. Three-tier pricing structure across premium, standard, and economy levels separates eleven-nines purity foundry supply from solar cell feedstock and metallurgical-grade silicon metal. Cost compression in solar-grade tiers is intensifying because polysilicon feedstock volatility lacks pass-through mechanisms, while memory chip fabricators show least price sensitivity due to yield-critical specifications.
Supply Chain Analysis
Inventory buffers for Czochralski equipment and polysilicon feedstock draw from concentrated geographic pools, with China, Taiwan, and South Korea anchoring wafer and ingot production. Raw material dependencies rest on metallurgical-grade silicon metal from Xinjiang and Inner Mongolia smelters, high-purity quartz crucibles, and specialized dopant gases. Single-source vulnerability concentrates in magnetic Czochralski puller supply from German and Japanese OEMs. Distribution runs through direct long-term offtake agreements for semiconductor-grade material and wholesale channels for solar module components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry migration to three-nanometer nodes and gate-all-around architectures is accelerating penetration of ultra-high-purity substrates, positioning monocrystalline silicone as an early-cycle expansion story with durable tailwinds from advanced semiconductor manufacturing.
For Market Incumbents: Compound certification advantages by extending ISO 9001 qualification timelines into captive supply agreements that bind Korean and Japanese memory fabricators through multi-year take-or-pay structures. Expand magnetic Czochralski capacity in Taiwan and South Korea before equipment lead times widen further, defending against emerging Chinese wafer specialists with state-backed polysilicon integration. For New Entrants and Emerging Players: Closed-loop dopant recovery services represent an under-served layer where EPA emission limits on phosphorus trichloride create immediate compliance demand without requiring full ingot qualification. Target India's production-linked incentive scheme for integrated polysilicon-to-module investments, where domestic wafering capacity lags cell and module assembly. Lead with hydropower-powered polysilicon sourcing to satisfy EU Green Deal carbon border adjustment documentation requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with under-monetized semiconductor material divisions possessing dormant Czochralski capacity. Five-to-ten-year viability hinges on qualification momentum rather than scale alone. Monitor divergence between solar-grade and semiconductor-grade purity standards as the inflection signal for margin pool migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Purification | Captures margin pool migration as EU carbon audits favor hydropower-powered reduction. |
| Magnetic Czochralski Capacity Expansion | Secures DRAM yield premiums as Samsung and SK Hynix specify oxygen-controlled wafers. |
| Long-term Supply Agreement Restructuring | Locks in foundry capacity through price reopeners tied to polysilicon indices. |
| Closed-loop Dopant Recovery System Deployment | Converts EPA phosphorus trichloride limits into circular revenue streams. |
| India PLI Scheme Manufacturing Localization | Captures fifty percent capital expenditure support for integrated polysilicon-to-module investments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across crystal growth technicians, foundry procurement managers, polysilicon plant engineers, and solar module EPC contractors. Secondary validation drew from SEC filings of listed wafer manufacturers, China's MEE carbon intensity benchmark disclosures, EU REACH restriction updates, and customs trade data for metallurgical-grade silicon flows. Bottom-up capacity modeling and top-down demand segmentation were triangulated to reconcile equipment lead time constraints with foundry expansion announcements.
Across the analysis window, forecasts incorporate product type segmentation by wafer diameter and purity grade, end-user segmentation by utility and industrial procurement scale, and application segmentation by photovoltaics versus electronics demand. CAGRs were derived from installed base growth in advanced node foundries and utility-scale solar deployment trajectories. Key inputs include polysilicon price index movements, Czochralski equipment delivery schedules, and regional renewable energy quota enforcement intensity.
Underlying assumptions cover continued foundry migration to three-nanometer production, sustained EU carbon border adjustment implementation, and stable enforcement of China's dual carbon mandates, with deviation risk concentrated in polysilicon feedstock volatility and magnetic Czochralski equipment availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Asia-Pacific Transparent Conductive Films Market
Semiconductor Material
Yttrium Market
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Semiconductor Silicon Wafer Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Europium Market
Semiconductor Material
Silicon Hydride Market
Semiconductor Material
Europe Silicon Carbide Market
Semiconductor Material
Glass Wafer Market