
 Japan Digital Signal Processor Market | 2026-2036
Japan Digital Signal Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Digital Signal Processor Market Insights
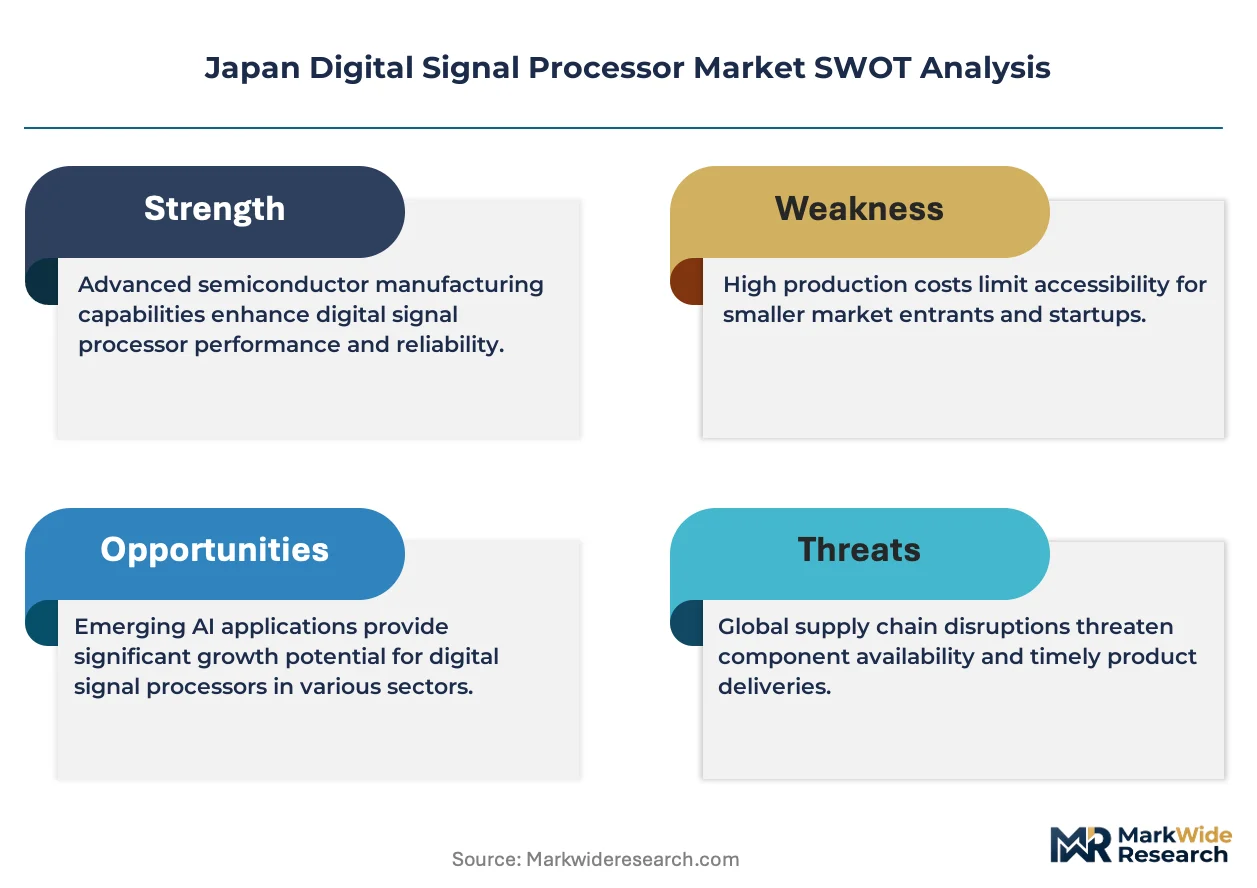
METI's semiconductor supply chain reinforcement policy is consolidating the cost-of-entry calculus for foreign DSP vendors seeking Japanese market access. Texas Instruments leverages its broad analog portfolio to sustain design-win momentum across industrial automation controllers. Renesas Electronics anchors domestic supply security through in-house fabrication partnerships and automotive-grade certification depth. Infineon Technologies competes on silicon-carbide integration, positioning its DSP cores adjacent to power management in electric vehicle inverters.
A digital signal processor is a specialized microprocessor architecture optimized for high-speed mathematical operations on digitized analog signals, typically executing multiply-accumulate instructions within single clock cycles at clock speeds ranging from hundreds of megahertz to several gigahertz. Its primary commercial purpose centers on real-time transformation, filtering, and compression of sensor, audio, video, and communication waveforms across embedded systems. Audio processors command the largest revenue share within product type segmentation, reflecting sustained investment from consumer electronics OEMs in voice-interface devices and professional sound equipment. Automotive end-user demand for video processors is expanding fastest, driven by surround-view camera fusion and driver-monitoring systems requiring sub-10-millisecond latency. Software-defined DSP technology captures emerging margin pools as manufacturers migrate algorithm flexibility from fixed hardware to updatable firmware layers.
PMDA medical device software guidelines and JIS standards for electromagnetic compatibility jointly shape DSP validation requirements, extending certification timelines for suppliers targeting diagnostic imaging and patient-monitoring equipment. METI's data-free flow with trust framework and national cybersecurity standards for critical infrastructure further constrain architecture choices, particularly in telecommunications and industrial control applications. Stakeholders must monitor how Japan's export control alignment with multilateral chip restrictions redraws competitive boundaries for high-performance DSPs used in advanced sensing and communication systems.
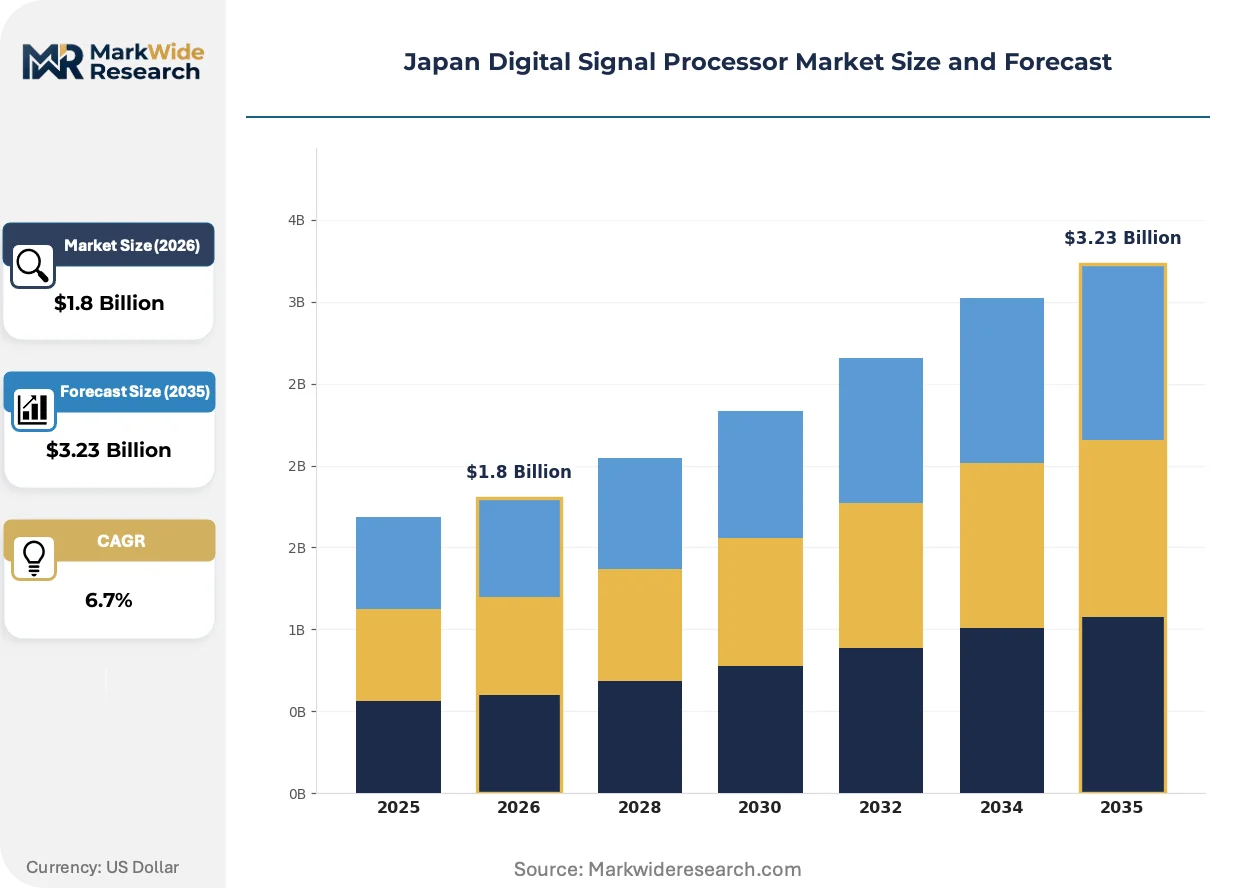
Market Dynamics
METI's semiconductor supply chain reinforcement policy is consolidating the cost-of-entry calculus for foreign DSP vendors seeking Japanese market access. Tier-1 automotive suppliers are accelerating procurement timelines as ADAS integration mandates tighten across vehicle platforms.
Growth Catalysts
- Automotive ADAS integration:Tier-1 suppliers are accelerating DSP procurement to meet surround-view camera fusion and driver-monitoring latency requirements below ten milliseconds.
- METI's semiconductor resilience roadmap:Domestic foundry capacity redirection toward edge-AI chip fabrication is creating captive supply security for automotive and industrial DSP demand.
- Kansai corridor concentration:Osaka and Kyoto electronics manufacturing clusters are generating localized procurement pull for voice-interface and professional audio processing applications.
Market Restraints
- Domestic foundry capacity constraints:Edge-AI fabrication prioritization is crowding out mature-node DSP production, extending lead times for industrial-grade components.
- PMDA-JIS dual certification burden:Medical device software guidelines and electromagnetic compatibility standards jointly extend validation timelines for diagnostic imaging DSP suppliers.
- Silicon-carbide integration complexity:Power management convergence with DSP cores in electric vehicle inverters is raising design-in technical barriers for non-integrated vendors.
Strategic Opportunities
- Software-defined DSP migration:Algorithm flexibility migration from fixed hardware to updatable firmware layers is capturing emerging margin pools in consumer electronics.
- Telecommunications cybersecurity standards:METI's national cybersecurity framework for critical infrastructure is creating certified-supplier preference windows for domestic DSP architects.
- Hokkaido-Tokyo corridor expansion:Underpenetrated northern manufacturing zones present whitespace for industrial automation controller DSP deployment.
Industry Challenges
- Automotive-grade certification depth:Extended AEC-Q100 validation cycles and functional safety documentation requirements are compressing design-win windows.
- Legacy industrial controller integration:Firmware updatability requirements are clashing with fixed-function DSP architectures in brownfield manufacturing environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Digital Signal Processor Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Audio Processors, Video Processors, Image Processors, High-Performance DSPs End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Technology: Analog DSP, Digital DSP, Hybrid DSP, Software-Defined DSP Application: Speech Recognition, Noise Cancellation, Video Encoding, Medical Imaging |
| Companies Covered | Texas Instruments Inc., Analog Devices Inc., Renesas Electronics Corp., Infineon Technologies AG, NXP Semiconductors NV, Intel Corporation, Toshiba Electronic Devices & Storage Corporation, ROHM Semiconductor, Mitsubishi Electric Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Digital Signal Processor Market Trends and Innovations
Algorithm execution flexibility is migrating from silicon-fixed architectures toward reprogrammable firmware layers. This shift is compressing hardware refresh cycles while expanding aftermarket service revenue pools across automotive and consumer electronics segments.
Software-defined DSP architectures are overtaking fixed-function silicon in automotive surround-view systems. Tier-1 suppliers are adopting firmware-updatable cores to accommodate evolving camera fusion algorithms without hardware redesign. This capability is compressing platform development timelines from thirty-six to eighteen months while locking in longer supplier relationships.
METI's data-free flow with trust framework is mandating localized data processing for telecommunications infrastructure DSPs. Equipment vendors are redesigning baseband processors to satisfy residency requirements without performance degradation. Industrial control and smart city applications are absorbing the highest compliance costs as they retrofit edge-processing capabilities.
Buyer concentration among consolidated automotive OEMs is compressing component negotiation cycles. Tier-1 suppliers are consolidating DSP vendor panels from six to three approved sources per platform. Procurement teams in the Kansai corridor are demanding firmware update guarantees extending ten years post-production.
Japan Digital Signal Processor Market Segmentation
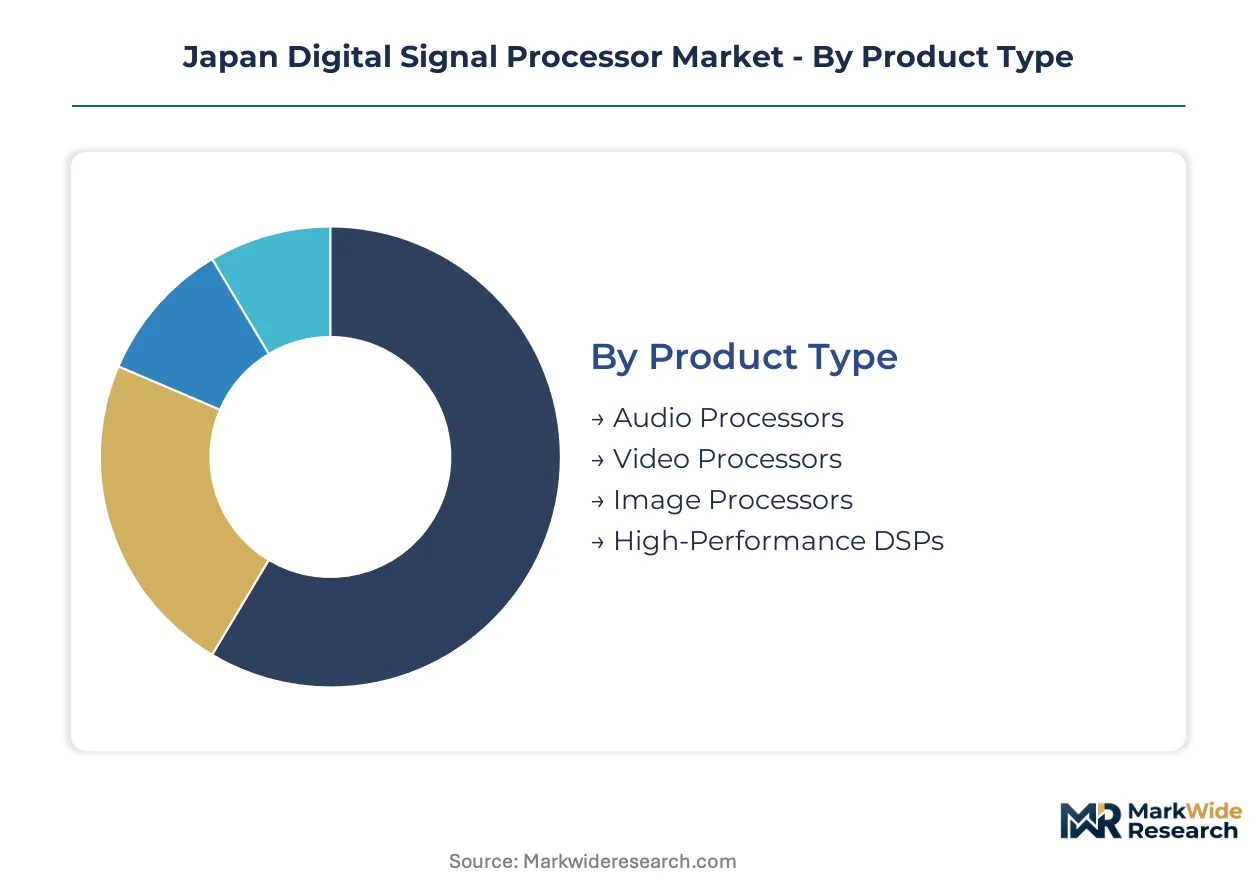
Segmentation in Japan's DSP market reveals how technical specifications intersect with regulatory mandates and supply chain geography. Product architecture choices determine certification pathways under METI and PMDA frameworks, while end-use concentration in the Kansai corridor shapes procurement patterns.
Product Type:
Architectural specialization determines clock-speed requirements, power budgets, and integration complexity across Japanese manufacturing clusters.
- Audio Processors:These cores execute real-time filtering and compression algorithms on voice waveforms at clock speeds from hundreds of megahertz to several gigahertz. Osaka and Kyoto consumer electronics OEMs are driving procurement for voice-interface devices and professional sound equipment, with METI's data-free flow framework mandating localized processing capabilities.
- Video Processors:Specialized architectures handle surround-view camera fusion and driver-monitoring systems with sub-ten-millisecond latency requirements. Tier-1 automotive suppliers in the Kansai corridor are accelerating procurement to meet tightening ADAS integration mandates across vehicle platforms.
- Image Processors:Optimized for pixel-parallel operations in diagnostic imaging and industrial inspection systems.
- High-Performance DSPs:Multi-core architectures targeting baseband processing and advanced sensing applications with stringent thermal envelopes.
Audio processors lead on scale; video processors lead on momentum.
End User:
Customer concentration patterns reflect Japan's industrial geography and regulatory segmentation.
- Automotive:Tier-1 suppliers are consolidating vendor panels from six to three approved sources per platform, demanding ten-year firmware update guarantees. AEC-Q100 validation cycles and functional safety documentation requirements are compressing design-win windows for DSP architects targeting this segment.
- Consumer Electronics:Voice-interface device OEMs in Osaka and Kyoto sustain investment in audio processing solutions, with software-defined migration capturing emerging margin pools through updatable firmware layers.
- Telecommunications:Equipment vendors redesign baseband processors to satisfy METI's data residency requirements without performance degradation.
- Industrial Equipment:Brownfield manufacturing environments present firmware updatability challenges against fixed-function DSP architectures.
Automotive commands procurement concentration; consumer electronics offers margin expansion through software-defined transition.
Technology:
Implementation approach determines flexibility, power efficiency, and supply chain positioning against foundry capacity constraints.
- Software-Defined DSP:Algorithm execution migrates from silicon-fixed architectures toward reprogrammable firmware layers, compressing hardware refresh cycles while expanding aftermarket service revenue. Tier-1 automotive suppliers adopt these cores to accommodate evolving camera fusion algorithms without hardware redesign.
- Digital DSP:Fixed-logic implementations dominate high-volume consumer applications where unit economics prioritize die area over flexibility.
- Analog DSP:Continuous-time processing architectures serve specialized sensor interface requirements in industrial control systems.
- Hybrid DSP:Mixed-signal integration combines analog front-end conditioning with digital back-end processing for medical imaging equipment.
Digital DSP retains volume leadership; software-defined DSP climbs the fastest on algorithm flexibility demand.
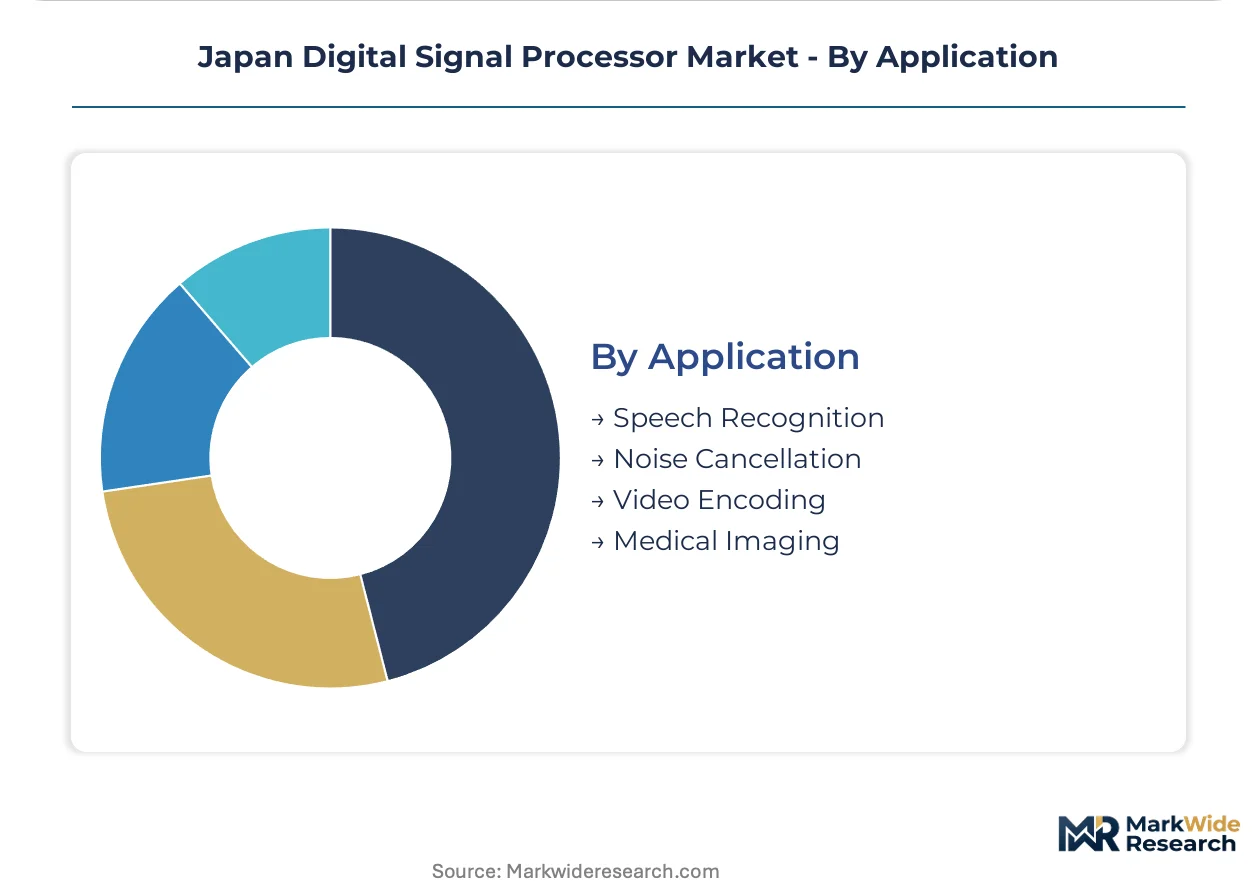
Application:
Functional use case determines latency thresholds, certification requirements, and integration complexity with adjacent system components.
- Video Encoding:Compression algorithms for automotive surround-view systems and telecommunications infrastructure require real-time throughput with minimal frame buffering. METI's cybersecurity standards for critical infrastructure constrain architecture choices in this application.
- Medical Imaging:Diagnostic equipment and patient-monitoring systems face PMDA software guidelines and JIS electromagnetic compatibility standards that jointly extend validation timelines.
- Speech Recognition:Natural language processing endpoints in consumer electronics demand low-power inference at the edge.
- Noise Cancellation:Active acoustic suppression in professional audio and automotive cabin systems requires adaptive filter convergence within strict millisecond boundaries.
Video encoding leads on technical complexity; medical imaging faces the steepest regulatory barrier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's electronics industry crystallized around Tokyo and Osaka in the post-war decades, establishing semiconductor fabrication clusters that persist today. DSP demand concentrates where automotive Tier-1 suppliers and consumer electronics OEMs maintain headquarters and manufacturing operations.
Kanto/Tokyo
Automotive R&D centers and telecommunications equipment vendors drive DSP procurement for ADAS validation and baseband processing. METI's cybersecurity framework for critical infrastructure mandates localized data residency in telecommunications applications. Yokohama and surrounding prefectures host concentrated design houses serving Tier-1 automotive suppliers with sub-ten-millisecond latency requirements.
Kansai/Osaka-Kyoto
Voice-interface device OEMs and professional audio manufacturers sustain demand for audio processing solutions with real-time filtering capabilities. METI's data-free flow with trust framework requires edge-processing capabilities in consumer electronics. Osaka and Kyoto electronics manufacturing clusters generate localized procurement pull for software-defined DSP migration.
Chubu/Nagoya
Toyota and supplier ecosystem concentration accelerates automotive-grade DSP procurement for surround-view camera fusion systems. AEC-Q100 validation cycles and functional safety documentation requirements compress design-win windows. Nagoya's industrial corridor anchors procurement for electric vehicle inverter integration with silicon-carbide power management.
Kyushu
Industrial automation controller manufacturers seek DSP cores for brownfield manufacturing environment retrofits. JIS electromagnetic compatibility standards shape validation requirements for equipment targeting domestic and export markets. Fukuoka and Kitakyushu host emerging electronics assembly operations seeking firmware-updatable architectures.
Hokkaido
Underpenetrated northern manufacturing zones present whitespace for industrial automation DSP deployment. METI's semiconductor resilience roadmap redirects foundry capacity toward edge-AI fabrication, creating supply security gaps for mature-node industrial components. Sapporo and Tomakomai electronics assembly operations remain dependent on Kansai and Kanto supply corridors.
Japan Digital Signal Processor Market Competitive Landscape
The competitive structure tilts toward diversified semiconductor conglomerates with captive fabrication partnerships. Three to four approved vendor panels per automotive platform concentrate procurement leverage among consolidated Tier-1 suppliers. Strategic archetypes include: broad analog-digital portfolio holders, automotive-grade certification specialists, and power management integration leaders. Dominant competitive moves center on silicon-carbide convergence in electric vehicle inverters and firmware update guarantee extensions reaching ten years post-production.
Among United States-based diversified suppliers, Texas Instruments Inc. and Analog Devices Inc. occupy positions reflecting broad analog portfolio depth. Renesas Electronics Corp. exemplifies the domestic automotive-grade certification archetype through in-house fabrication partnerships. Infineon Technologies AG represents power management integration specialists competing on silicon-carbide adjacency. NXP Semiconductors NV sits within the automotive platform consolidation tier, while Intel Corporation anchors high-performance multi-core architectures for advanced sensing applications.
| Leading Market Players |
|---|
| Texas Instruments Inc. |
| Analog Devices Inc. |
| Renesas Electronics Corp. |
| Infineon Technologies AG |
| NXP Semiconductors NV |
| Intel Corporation |
| Toshiba Electronic Devices & Storage Corporation |
| ROHM Semiconductor |
| Mitsubishi Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
Tier-1 automotive supplier consolidation from six to three approved DSP sources per platform has compressed negotiation leverage toward contract-based long-term offtake agreements with ten-year firmware update guarantees. METI's domestic foundry capacity redirection toward edge-AI fabrication has tightened mature-node DSP availability, amplifying pricing power for automotive-grade certified vendors.
Pricing Analysis
Three-tier pricing structure across automotive-grade certified, industrial-standard, and economy consumer tiers dominates procurement frameworks. Price differentiation hinges on AEC-Q100 validation depth and firmware updatability guarantees extending post-production. Cost compression in industrial-grade tiers is intensifying because domestic foundry crowding extends lead times for mature-node production. Consumer electronics OEMs in Osaka and Kyoto exhibit highest price sensitivity, while automotive Tier-1 suppliers absorb premium tiers for functional safety documentation.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced-node wafer fabrication serving high-performance DSP architectures. Raw material dependencies include silicon wafers, photoresist chemicals, and rare-earth elements for magnetic components in automotive power integration. Tariff exposure on semiconductor manufacturing equipment imports from the United States threatens capacity expansion timelines. Distribution runs through authorized distributors serving Kansai and Kanto manufacturing corridors with direct allocation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined DSP migration is expanding service revenue pools as algorithm flexibility shifts from silicon-fixed to firmware-updatable architectures, compressing hardware refresh cycles while extending supplier relationships through aftermarket guarantees.
For Market Incumbents: Anchor design-win momentum through captive in-house fabrication partnerships that secure automotive-grade certification depth against foundry capacity constraints. Deepen backward integration into silicon-carbide power management adjacencies for electric vehicle inverter platforms. Extend firmware update guarantee structures to fifteen-year horizons to match Tier-1 supplier panel consolidation timelines. For New Entrants and Emerging Players: The price-point gap between premium automotive-certified DSPs and economy consumer-tier alternatives presents whitespace for mid-tier industrial automation controllers. Target Hokkaido's underpenetrated northern manufacturing zones with firmware-updatable architectures designed for brownfield retrofit compatibility. Pursue METI cybersecurity framework pre-certification to unlock telecommunications infrastructure preference windows. For Investors and Strategic Acquirers: Domestic automotive semiconductor conglomerates are the most active acquirer in this space, seeking software-defined DSP capabilities to complement power management portfolios. Long-term viability centers on algorithm flexibility IP rather than fixed-function silicon assets across the next decade. Watch for METI export control alignment shifts with multilateral chip restrictions as the critical inflection signal for high-performance DSP competitive boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbide Power Integration | Infineon Technologies leverages SiC adjacency to capture electric vehicle inverter DSP sockets in Nagoya's industrial corridor. |
| Software-Defined Firmware Migration | Tier-1 suppliers compress platform development timelines from thirty-six to eighteen months through updatable algorithm cores. |
| Domestic Foundry Partnership Expansion | Renesas Electronics anchors supply security through METI-aligned captive capacity for automotive-grade certification depth. |
| Cybersecurity Framework Pre-Certification | Equipment vendors redesign baseband processors to satisfy METI data residency mandates without performance degradation. |
| Ten-Year Firmware Guarantee Extension | Procurement teams in the Kansai corridor demand extended post-production support as vendor panel consolidation tightens. |
Research Methodology
Bottom-up automotive and consumer electronics end-use modeling reconciled against top-down semiconductor supply-side tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, foundry operations managers, and telecommunications equipment vendors were validated against secondary sources including METI semiconductor policy filings, PMDA medical device software guidelines, JIS electromagnetic compatibility standards, and customs trade data for DSP component flows.
Historical trendline analysis across product type, end user, technology, and application dimensions established baseline growth patterns over the projection horizon. Segmentation modeling incorporated automotive content per vehicle, consumer electronics voice-interface device shipments, and telecommunications infrastructure deployment cycles. CAGRs were derived from regression analysis against foundry capacity allocation shifts and ADAS integration mandate timelines.
Caveats apply where METI export control alignment with multilateral chip restrictions, domestic foundry capacity reallocation priorities, or automotive OEM platform consolidation decisions could materially shift the outlook. Forecasts reflect documented assumptions about edge-AI fabrication crowding effects and Tier-1 supplier vendor panel reduction trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Wifi Chip Market
Communication Chips & Hardware
Global Navigation Satellite System Chip Market
Communication Chips & Hardware
Chip Antenna Market
Communication Chips & Hardware
Bluetooth Low Energy Market
Communication Chips & Hardware
Ethernet Phys Market
Communication Chips & Hardware
Communication Standard Logic IC Market
Communication Chips & Hardware
Bluetooth Low Energy (BLE) Module Market
Communication Chips & Hardware
System Basis Chip Market
Communication Chips & Hardware
Wi-Fi Semiconductor Chipset Market
Communication Chips & Hardware
Smart TV Chip Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
Wi-Fi Adapter Card Market
Communication Chips & Hardware
Jobsite Radios Market
Communication Chips & Hardware
Power Line Communication System-On-Chip Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Optical Communications Market