
 Transparent Conductive Films Market | 2026-2036
Transparent Conductive Films Market Size, Share, and Industry Trends Forecast 2026-2036
Transparent Conductive Films Market Intelligence
China's significant investment in domestic silver nanowire production capacity is rewriting the material sourcing landscape for display manufacturers. Nitto Denko Corporation leverages its expertise in polymer chemistry to develop high-performance films for complex device architectures. Teijin Limited specializes in advanced materials, including conductive polymers for flexible electronics, while Canatu Oy differentiates with its carbon nanobud-based films for automotive and consumer touch sensor applications.
Transparent conductive films are thin layers of optically clear and electrically conductive material. Performance is defined by a balance between low sheet resistance, measured in ohms per square, and high optical transmittance, typically above 90%. These films serve as essential electrodes in devices like touchscreens and solar cells. While Indium Tin Oxide (ITO) sputtering remains the dominant product type, silver nanowires represent the fastest-growing segment for flexible displays and smart windows.
Material selection is influenced by regulations such as the EU's RoHS directive, which restricts hazardous substances in electronics, and EPA rules in the United States governing chemical production. Compliance with national standards, like China's GB standards for electronic components, is also critical for market access. The strategic choice between materials like ITO and silver nanowires will increasingly depend on balancing performance requirements with supply chain security for critical raw materials.
Market Dynamics
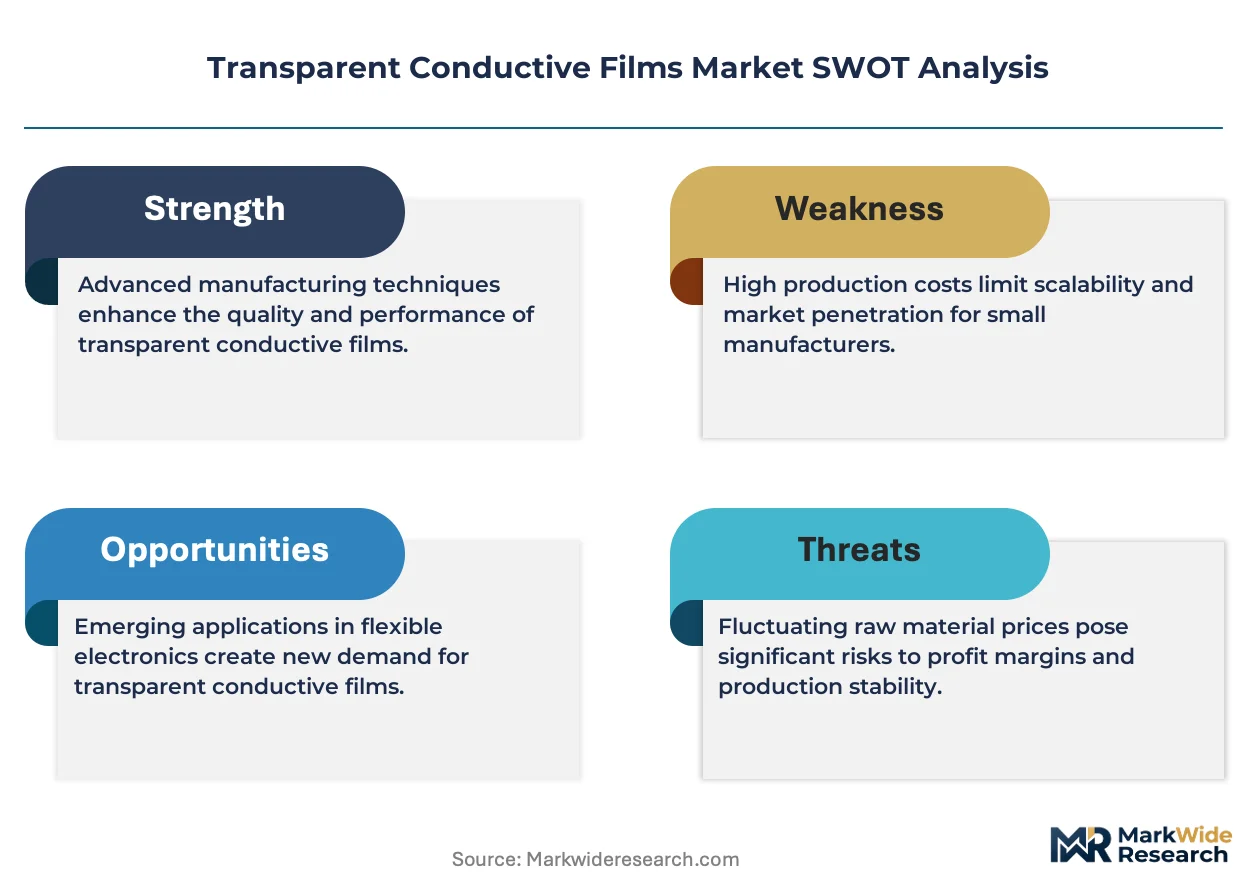
The market's central dynamic involves the strategic trade-off between the established performance of Indium Tin Oxide and its associated raw material supply risks. This tension accelerates the evaluation of alternative materials like silver nanowires for next-generation flexible devices.
Growth Catalysts
- Flexible Electronics:Foldable smartphones and OLED displays demand films that bend without cracking, a key limitation of traditional ITO.
- Roll-to-Roll Processing:This method enables high-volume, cost-effective production of silver nanowire films, improving their competitiveness versus sputtering.
- Demand Concentration:A dense ecosystem of display makers in South Korea, Taiwan, and China provides a large, focused customer base.
Market Restraints
- Indium Supply Risk:Dependence on rare, geographically concentrated indium creates price volatility and supply vulnerability for dominant ITO film producers.
- Performance Trade-offs:Achieving high transparency and low sheet resistance simultaneously remains a core technical challenge, especially for emerging non-ITO materials.
- Material Substitution:The development of alternatives like carbon nanotubes and graphene poses a persistent displacement threat to established film technologies.
Strategic Opportunities
- Automotive Integration:Integrating large touch displays into vehicle cockpits opens a new market for durable, formable films beyond consumer electronics.
- Smart Windows:Energy efficiency mandates for buildings, like those in the EU Green Deal, create a market for TCFs in electronically switchable glass.
- Biomedical Sensors:Use in transparent biosensors for medical diagnostics presents a high-value opportunity for specialized, biocompatible conductive films.
Industry Challenges
- Regulatory Compliance:Navigating disparate regulations like the EU's RoHS directive and China's GB standards adds complexity and cost for global suppliers.
- Capital Expenditure:The high cost of vacuum sputtering equipment for ITO and precision coating lines for alternatives creates significant barriers to entry.
- Intellectual Property:A crowded IP landscape for novel materials like carbon nanobuds can lead to licensing disputes and slow commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transparent Conductive Films Market |
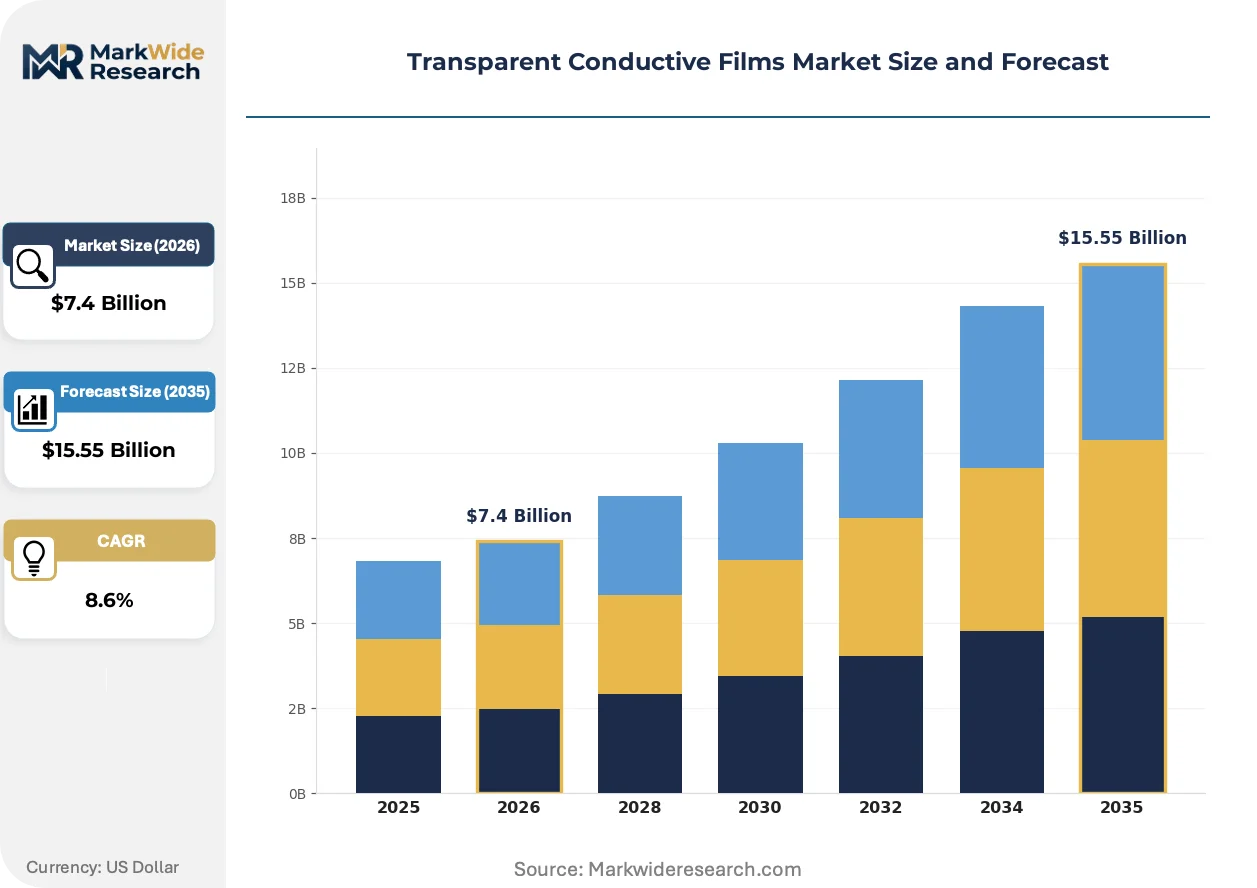
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indium Tin Oxide, Aluminum-Doped Zinc Oxide, Silver Nanowires, Graphene, Conductive Polymers Application: Touchscreens, OLED Displays, Solar Cells, Smart Windows, Electronic Paper Manufacturing Technology: Sputtering, Chemical Vapor Deposition, Spray Coating, Electroplating, Roll-to-Roll Processing End User Industry: Consumer Electronics, Renewable Energy, Aerospace, Defense, Architectural Glazing |
| Companies Covered | 3M Company, OFILM Group Co., Ltd., Nitto Denko Corporation, Canatu Oy, Toyobo Co., Ltd., Teijin Limited, AGC Inc., Cambrios Technologies Corporation, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transparent Conductive Films Market Strategic Shifts & Innovations
Material selection is moving beyond the dominance of a single solution. Application-specific requirements for flexibility, conductivity, and transparency are fostering a diverse ecosystem of material choices, from established oxides to emerging nanomaterials, fundamentally changing sourcing strategies.
Hybrid films combine different conductive materials, such as metal mesh with conductive polymers, to optimize performance characteristics for specific uses. Large-format interactive displays and automotive touchscreens are driving adoption of these composite structures. This development is hybridizing the material selection process, shifting it from a single-choice paradigm to a customized, multi-material approach.
The EU's RoHS directive, restricting hazardous substances, influences material choices in electronics. This regulation pressures manufacturers to find alternatives to indium-based films or document robust recycling and supply chain management for compliance. Electronics producers targeting the European market are most affected, accelerating R&D into silver nanowires and conductive polymers.
Design priorities for consumer electronics are shifting towards flexible, foldable, and non-rectangular display formats. This trend directly challenges the dominance of rigid, brittle ITO films, creating an opening for alternatives like silver nanowires and carbon nanobuds. The shift is most visible in the premium smartphone and wearable device segments, particularly from manufacturers in South Korea.
Transparent Conductive Films Market Segmentation
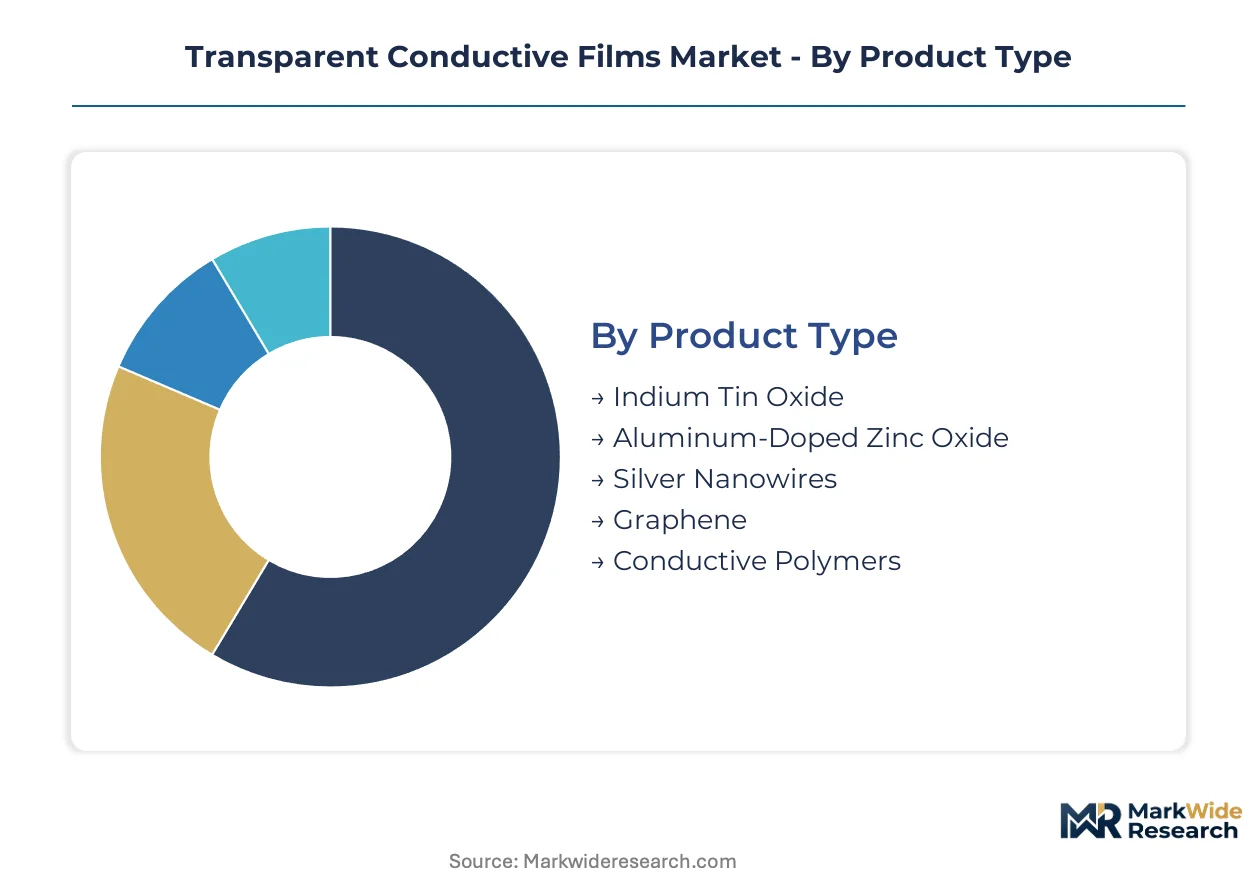
This market analysis dissects the Transparent Conductive Films market into distinct categories, revealing the nuanced interplay of material science, application demands, and production methodologies. Understanding these segments is critical for identifying specific growth vectors and assessing competitive landscapes. Each segment reflects unique performance requirements and market dynamics.
Product Type:
The product type segmentation highlights the maturity spectrum of conductive film materials, from established oxides to rapidly emerging nanomaterials.
- Indium Tin Oxide:This transparent ceramic oxide, often sputtered, balances high optical transparency with electrical conductivity. Demand concentrates in established touchscreen and display manufacturing centers, driven by its proven performance in rigid device architectures.
- Silver Nanowires:These films contain networks of metallic silver nanowires in a polymer matrix, offering flexibility and high conductivity for bendable displays. Demand accelerates in China for flexible OLEDs and foldable smartphones, where mechanical properties are critical.
- Aluminum-Doped Zinc Oxide:A cost-effective, environmentally benign alternative to ITO, frequently used in solar cells and select display applications.
- Graphene:This single-atom-thick carbon material provides exceptional electrical and thermal conductivity for flexible and transparent electronics.
- Conductive Polymers:Organic materials like PEDOT:PSS offer flexibility and printability for wearable sensors and flexible displays.
Indium Tin Oxide retains volume leadership; Silver Nanowires hold the steepest expansion curve.
Application:
The segmentation by application illustrates the diverse functional requirements that transparent conductive films must meet across various end-use devices.
- Touchscreens:These applications require films providing precise touch response and durability, serving as primary interfaces in smartphones and automotive systems. Demand is global, driven by pervasive integration of interactive displays across consumer devices.
- OLED Displays:Transparent conductive films act as electrodes in organic light-emitting diode displays, enabling flexible, high-contrast visuals in premium devices. South Korean and Chinese display manufacturers drive demand for ultra-thin, bendable form factors.
- Solar Cells:TCFs serve as front electrodes in photovoltaic devices, balancing light transmission with efficient charge collection.
- Smart Windows:These films enable electronically switchable glass for building energy efficiency, controlling light and heat transmission.
- Electronic Paper:Used in e-readers and digital signage, these applications require TCFs for low-power, reflective displays.
Touchscreens continue to absorb significant film volumes, while OLED Displays are expanding most quickly.
Manufacturing Technology:
This category reveals how different manufacturing technologies influence production scale and supply chain concentration for transparent conductive films.
- Sputtering:A vacuum deposition method, sputtering ejects material onto a substrate, primarily for Indium Tin Oxide films due to its precision. Production concentrates in specialized facilities in Japan and South Korea, supporting high-performance display manufacturing.
- Roll-to-Roll Processing:This high-throughput method continuously coats flexible substrates, enabling cost-effective, large-volume production of silver nanowire and conductive polymer films. Adoption increases in China and Taiwan for flexible electronics and smart windows.
- Chemical Vapor Deposition:Gaseous precursors react on a substrate surface to form a solid film, used for thin-film solar cells and some oxide materials.
- Spray Coating:A versatile, scalable method for depositing conductive inks or nanoparticle suspensions, useful for large-area or complex geometries.
- Electroplating:An electrochemical process depositing a thin metal layer onto a conductive substrate, offering precise thickness control for film types.
Sputtering maintains its stronghold for established materials, while Roll-to-Roll Processing is gaining share fastest for flexible film alternatives.
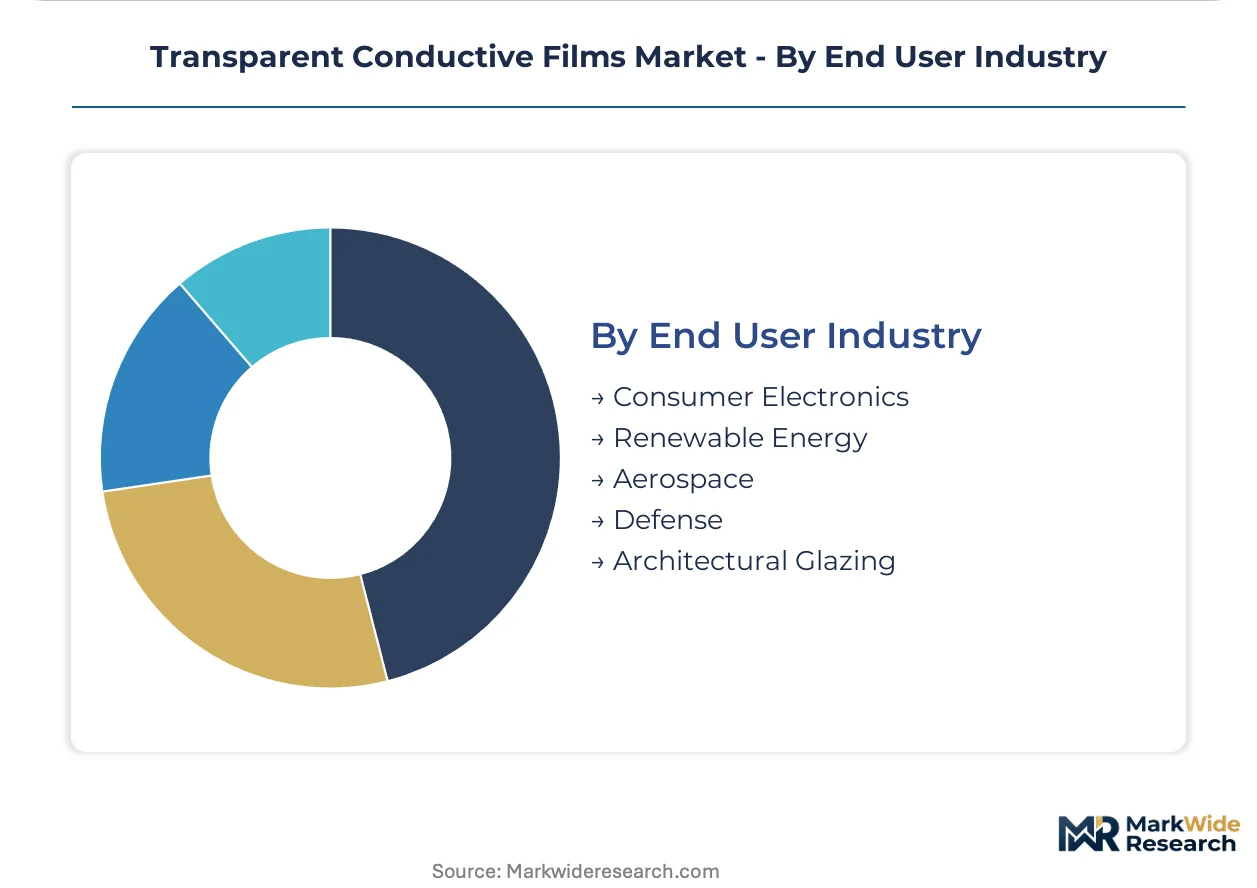
End User Industry:
The segmentation by end user industry delineates the diverse customer types driving demand for transparent conductive films, each with distinct performance and regulatory requirements.
- Consumer Electronics:This sector is the largest end-user, integrating TCFs into smartphones, tablets, and wearables for touch interfaces. Demand is global, with major manufacturing operations in China, South Korea, and Vietnam driving material procurement.
- Renewable Energy:Transparent conductive films are integral to solar cells and energy harvesting, requiring high efficiency and long-term stability outdoors. Sector growth in Germany and the United States is spurred by government incentives and environmental mandates.
- Aerospace:TCFs are used in aircraft displays, de-icing systems, and sensors, demanding high reliability under extreme conditions.
- Defense:Applications include ruggedized displays, night vision, and specialized sensors for military equipment, prioritizing durability and stealth.
- Architectural Glazing:This segment uses TCFs in smart windows for buildings, offering energy management and privacy features in commercial and residential constructions.
Consumer Electronics remains the dominant volume driver, with Renewable Energy showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global fiber optic network underpins the rapid data exchange necessary for distributed electronics manufacturing, enabling specialized production hubs to serve diverse transparent conductive film applications. This infrastructure facilitates supply chain fluidity for critical materials like indium and silver nanowires. Regional demand dynamics are closely tied to the presence of major display manufacturers and evolving regulatory landscapes.
China
China's extensive high-speed rail network supports the efficient distribution of electronic components, including transparent conductive films, to various manufacturing hubs. The country's demand for flexible OLEDs and foldable smartphones drives significant domestic silver nanowire production. Compliance with China's GB standards for electronic components is essential for market access. The Yangtze River Delta region, encompassing cities like Shanghai, anchors a large display manufacturing ecosystem.
South Korea
South Korea's advanced port infrastructure facilitates the import of raw materials and export of high-value electronic components, including transparent conductive films. Demand concentrates in premium smartphone displays and advanced flexible electronics. The MFDS (Korean Ministry of Food and Drug Safety) influences material choices for specialized biomedical sensor applications. Gyeonggi Province, within the Seoul metropolitan area, hosts major display manufacturers.
Japan
Japan's robust electricity grid ensures stable power supply for energy-intensive processes like sputtering, crucial for high-performance ITO film production. The country exhibits strong demand for specialized automotive displays and continued R&D in new materials. Manufacturers adhere to stringent JIS standards for electronic components and materials. The Kansai region, including Osaka and Kyoto, is a hub for precision manufacturing and material science research.
Germany
Germany's highly integrated logistics network supports the just-in-time delivery of components for its automotive and industrial sectors. Transparent conductive films are increasingly integrated into large automotive touch displays and smart windows. The EU Green Deal mandates for energy-efficient buildings influence material selection for architectural glazing. Bavaria, with cities like Munich and Stuttgart, drives innovation in automotive electronics and advanced materials.
United States
The United States' vast interstate highway system enables efficient transport of materials and finished goods across diverse manufacturing and R&D centers. Demand stems from biomedical sensors, renewable energy applications like solar cells, and aerospace displays. EPA rules governing chemical production influence material sourcing and manufacturing processes. Silicon Valley in California remains a key center for R&D in flexible electronics and advanced materials.
Transparent Conductive Films Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the transparent conductive films market. This market exhibits a tiered structure, with established material suppliers coexisting with innovative nanomaterial developers. Archetypes include large chemical conglomerates, specialized film manufacturers, and emerging technology startups. Capacity expansion and strategic partnerships are dominant competitive moves for market participants.
Specialists in advanced material science, Nitto Denko Corporation and Teijin Limited, represent established players leveraging polymer chemistry and conductive polymers respectively. Canatu Oy, a Finnish company, exemplifies an innovator focused on carbon nanobud-based films for specialized applications. These companies anchor different segments of the value chain, from high-volume film production to niche high-performance solutions.
| Leading Market Players |
|---|
| 3M Company |
| OFILM Group Co., Ltd. |
| Nitto Denko Corporation |
| Canatu Oy |
| Toyobo Co., Ltd. |
| Teijin Limited |
| AGC Inc. |
| Cambrios Technologies Corporation |
| TDK Corporation |
| Others |
Cost & Logistics Intelligence
Underutilized ITO sputtering capacity in Japan and South Korea drives aggressive pricing strategies from established film producers. This capacity overhang influences material selection decisions for display manufacturers and automotive integrators.
Pricing Analysis
A multi-tier pricing structure governs transparent conductive films, separating premium flexible OLED applications from standard touchscreen needs. Price differentiation stems from film performance specifications, volume scale commitments, and customization for specific device architectures. Pricing pressure stems from the rapid commoditization of standard ITO films and the increasing competitiveness of silver nanowire alternatives. Consumer electronics manufacturers purchasing high volumes exhibit the highest price sensitivity, while specialized biomedical sensor applications prioritize performance over cost.
Supply Chain Analysis
Specialized film manufacturers in Japan and South Korea hold significant capacity for ITO film production, while China and Taiwan lead in silver nanowire manufacturing. The supply chain draws heavily from critical raw materials like indium for ITO and silver for nanowires, alongside specialized polymer substrates. Indium supply vulnerability, concentrated in a few geographic regions, poses a persistent structural risk. Distribution runs through direct sales channels, connecting film producers directly with major display manufacturers and electronics integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transparent conductive films market presents a defensive moat, largely due to high capital expenditure requirements for specialized manufacturing equipment like sputtering lines. This cost barrier creates significant switching costs for established display manufacturers.
For Market Incumbents:Pre-empt market share erosion from emerging nanomaterial alternatives by diversifying product portfolios into hybrid films and advanced conductive polymers. Secure long-term supply contracts for critical raw materials like indium to mitigate supply risks and price volatility. Invest in roll-to-roll processing capabilities to compete with lower-cost silver nanowire producers, addressing the threat of material substitution. Strengthen intellectual property portfolios around novel film architectures to maintain a competitive edge.
For New Entrants and Emerging Players:Build out specialized manufacturing for carbon nanobud or graphene films, targeting niche high-performance applications in automotive integration and biomedical sensors. The smart windows segment presents a highly penetrable application, driven by energy efficiency mandates like the EU Green Deal. Focus on developing biocompatible and durable solutions for medical diagnostics, leveraging a performance-over-cost go-to-market angle. Form strategic partnerships with specialized device integrators for faster market entry.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized film manufacturers providing custom solutions for high-value applications like aerospace displays. The long-term viability favors firms with diversified material portfolios and robust intellectual property in next-generation conductive materials. Target acquisition candidates include mid-sized innovators specializing in carbon-based films or advanced conductive polymers. The shift in capital expenditure from sputtering to roll-to-roll processing serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Silver Nanowires | Addresses demand from flexible OLED manufacturers in China and South Korea. |
| R&D in Hybrid Film Technologies | Optimizes performance for large-format interactive displays and automotive touchscreens. |
| Strategic Partnership with Display OEMs | Secures long-term supply agreements for next-generation flexible devices. |
| Investment in Roll-to-Roll Processing | Enables cost-effective, high-volume production of flexible films. |
| Compliance with EU RoHS Directive | Ensures market access for electronics producers targeting the European market. |
Research Approach
The analysis maps transparent conductive film sub-sectors, including ITO, silver nanowires, and graphene, each validated through primary interviews with R&D directors and procurement leads at display manufacturers. Secondary validation draws from SEC 10-K filings, customs data, and technical journals. This approach combines bottom-up market sizing with top-down validation, incorporating insights from material scientists and automotive integrators.
The forecast framework assumes stable geopolitical conditions and consistent technological advancements across the analysis window, while varying raw material prices and regulatory impacts. Segmentation dimensions modeled include product type, application, manufacturing technology, and end-user industry, alongside regional demand patterns. Compound annual growth rates were derived from historical data trends and projected adoption rates for flexible electronics. Forecast inputs include display panel production volumes and electric vehicle integration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new nanomaterial developers or major display manufacturers would shift outcomes. Rapid shifts in raw material availability or unexpected regulatory changes, like new RoHS restrictions, pose significant risk factors. Quarterly review of display technology roadmaps and material innovation pipelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Ultra High Purity Silicon Carbide Market
Semiconductor Material
North America Silicone Market
Semiconductor Material
Europe Semiconductor Materials Market
Semiconductor Material
Germanium Market
Semiconductor Material
PP Capacitor Films Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Global Strontium Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Semiconductor Silicon Wafer Market