
 Global Automotive Semiconductor Market | 2026-2036
Global Automotive Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Semiconductor Market Intelligence
Automotive Safety Integrity Level D certification is rotating the market towards higher-value, fault-tolerant microcontrollers and sensors. This move benefits specialized suppliers capable of meeting stringent functional safety requirements. Infineon Technologies AG leverages its deep expertise in power semiconductors for electric vehicle powertrains and industrial applications. NXP Semiconductors N.V. competes on its broad portfolio of secure connectivity and processing solutions, while Texas Instruments Inc. sustains a strong position in analog ICs.
Automotive semiconductors are integrated circuits and discrete components specifically engineered for in-vehicle electronic systems, qualified for harsh temperature and vibration profiles. These devices, fabricated on process nodes ranging from mature 90nm to advanced 7nm technologies, control and process data for critical functions. Microcontrollers remain a foundational product segment by volume. Power semiconductors, especially silicon carbide devices for electric vehicles, and sensors for Advanced Driver Assistance Systems represent the key areas of value growth.
Functional safety standards, primarily ISO 26262, dictate the design, validation, and production processes for all safety-critical electronic systems. Concurrently, mandates from the US NHTSA on autonomous vehicle testing, Europe's upcoming CSRD reporting on supply chain ethics, and China's GB standards for connectivity impose specific performance and compliance requirements. Automakers and Tier-1 suppliers must therefore decide between traditional sourcing or direct design partnerships with foundries and fabless designers.
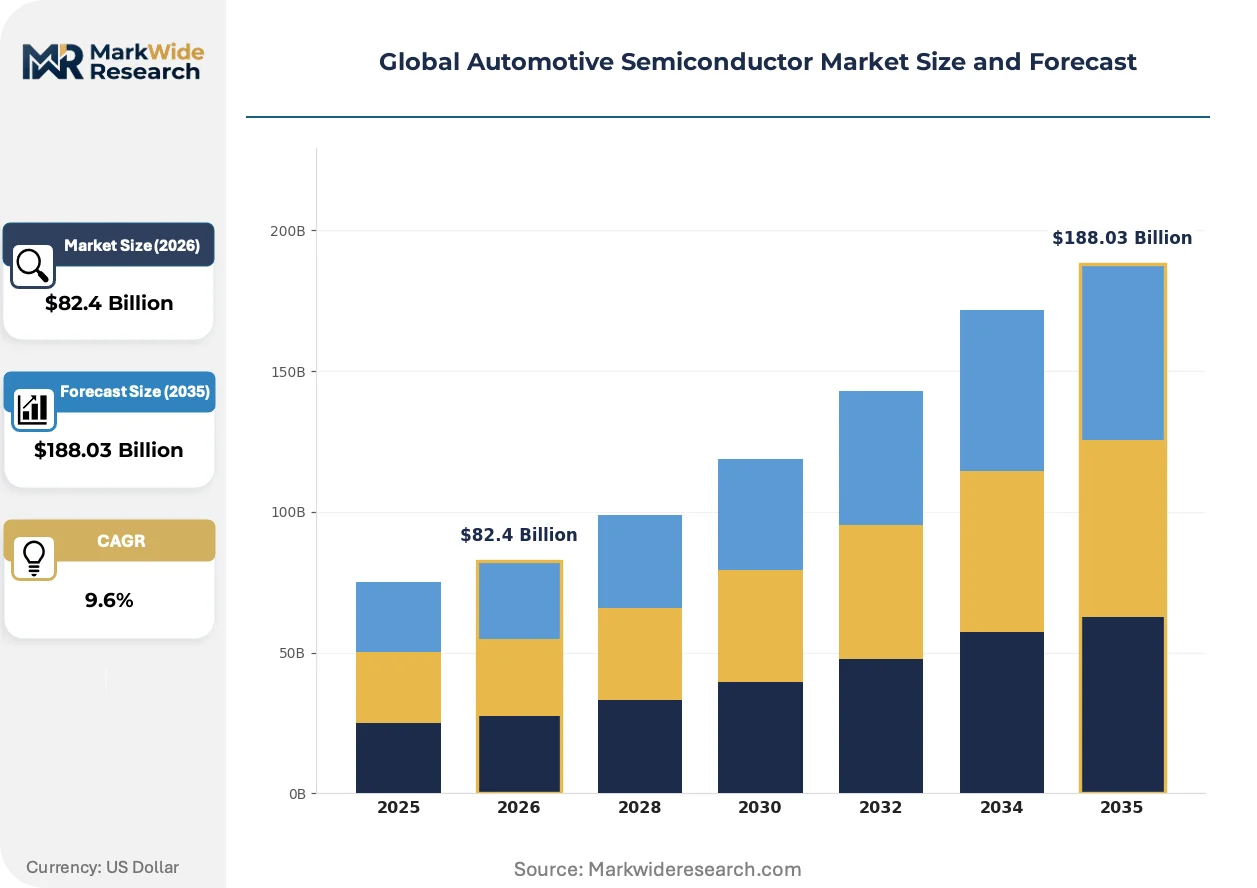
Market Dynamics
The architectural transformation of vehicles toward electrification and autonomy is the market's central structural force. This creates bifurcated demand for high-voltage power semiconductors and sophisticated compute for ADAS, pulling the market in two distinct value directions.
Growth Catalysts
- Regulatory Mandates:Europe’s General Safety Regulation is making ADAS features standard, increasing the required number of sensors and microcontrollers per vehicle.
- Wide-Bandgap Materials:Adoption of silicon carbide in EV inverters improves powertrain efficiency, a critical differentiator for automakers in Germany and China competing on battery range.
- EV Production Volume:Government incentives in China create a massive, concentrated end-market for power management ICs and battery management systems.
Market Restraints
- High Fabrication Costs:Manufacturing advanced logic nodes and silicon carbide substrates requires immense capital expenditure, limiting the supplier base and creating bottlenecks.
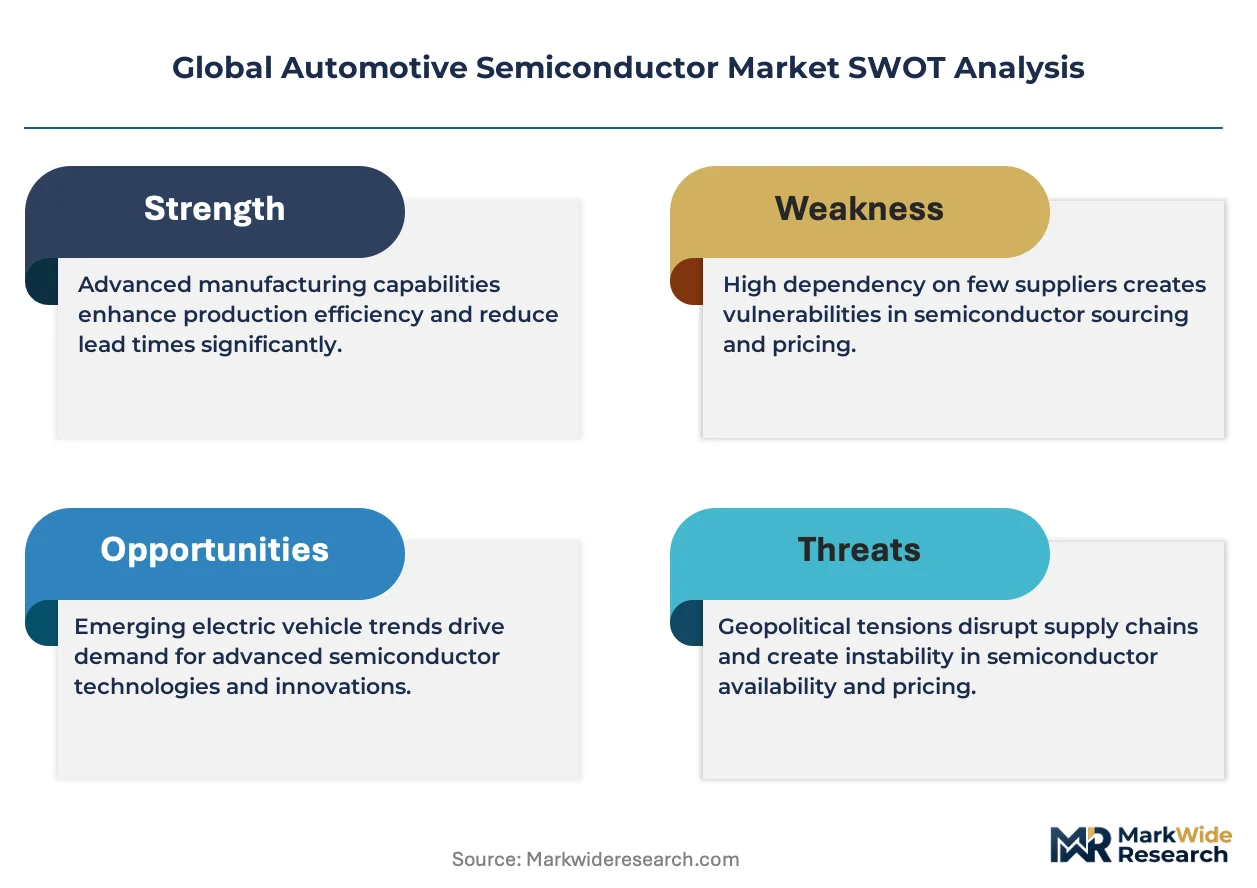
- Foundry Concentration:The geographic concentration of advanced foundries in Taiwan introduces significant geopolitical and supply chain continuity risks for the automotive industry.
- Thermal Management Complexity:High compute density in centralized controllers creates significant heat dissipation challenges, requiring more complex and costly thermal solutions.
Strategic Opportunities
- In-Cabin Sensing Systems:Driver and occupant monitoring applications, driven by safety regulations, create a new market for dedicated image sensors and microcontrollers.
- Onshoring Incentives:The US CHIPS Act and European Chips Act provide subsidies for building new semiconductor fabs, de-risking domestic capacity expansion.
- V2X Connectivity Modules:The convergence of 5G and V2X communication opens a market for secure connectivity modules that enable cooperative autonomous driving.
Industry Challenges
- Functional Safety Talent:A scarcity of engineers with expertise in ISO 26262 compliance and mixed-signal IC design for safety-critical systems constrains product development timelines.
- Automotive Qualification Timelines:The lengthy and rigorous AEC-Q100 qualification process for automotive-grade components slows the deployment of new semiconductor technologies into production vehicles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Semiconductor Market |
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $188.03 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Power Semiconductors, Sensors, Analog ICs, Memory Chips, Logic ICs Technology: Advanced Driver Assistance Systems, Powertrain Control, Body Electronics, Infotainment, Communication Modules, Safety Systems Application: Electric Vehicles, Hybrid Vehicles, Internal Combustion Engines, Autonomous Vehicles, Connected Cars, Commercial Vehicles End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Assemblers, Electronics Suppliers, Retrofitters |
| Companies Covered | STMicroelectronics N.V., NVIDIA, Infineon Technologies AG, TSMC, Qualcomm, Renesas Electronics Corporation, Texas Instruments Inc., Wolfspeed, NXP Semiconductors N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Semiconductor Market Strategic Shifts & Innovations
The automotive semiconductor market is defined by a fundamental vehicle architecture shift from distributed electronic control units to centralized domain and zonal controllers. This consolidation drives demand for higher-performance processing, networking, and power management integrated circuits.
Wide-bandgap materials like Silicon Carbide (SiC) provide superior thermal conductivity and higher efficiency for electric vehicle powertrain components. Leading automakers are integrating SiC into inverters and on-board chargers to improve overall system performance. This advanced material is supplanting traditional silicon IGBTs in high-voltage systems, enabling longer vehicle range and faster charging capabilities.
Europe's Corporate Sustainability Reporting Directive (CSRD) imposes strict reporting requirements on supply chain due diligence, including raw material sourcing and labor practices. The mandate compels semiconductor firms and their automotive customers to establish verifiable traceability for minerals used in chip manufacturing. This particularly impacts suppliers of discrete components and analog ICs, who must audit complex, multi-tiered global supply networks.
Select automakers are bypassing traditional Tier-1 supply models to engage in direct chip design and procurement relationships. This disintermediates the supply chain, allowing OEMs to co-develop custom silicon with fabless designers and foundries for optimized performance. This direct-sourcing model is most visible within North American EV startups and German luxury car manufacturers aiming for software-defined vehicle architectures.
Global Automotive Semiconductor Market Segmentation
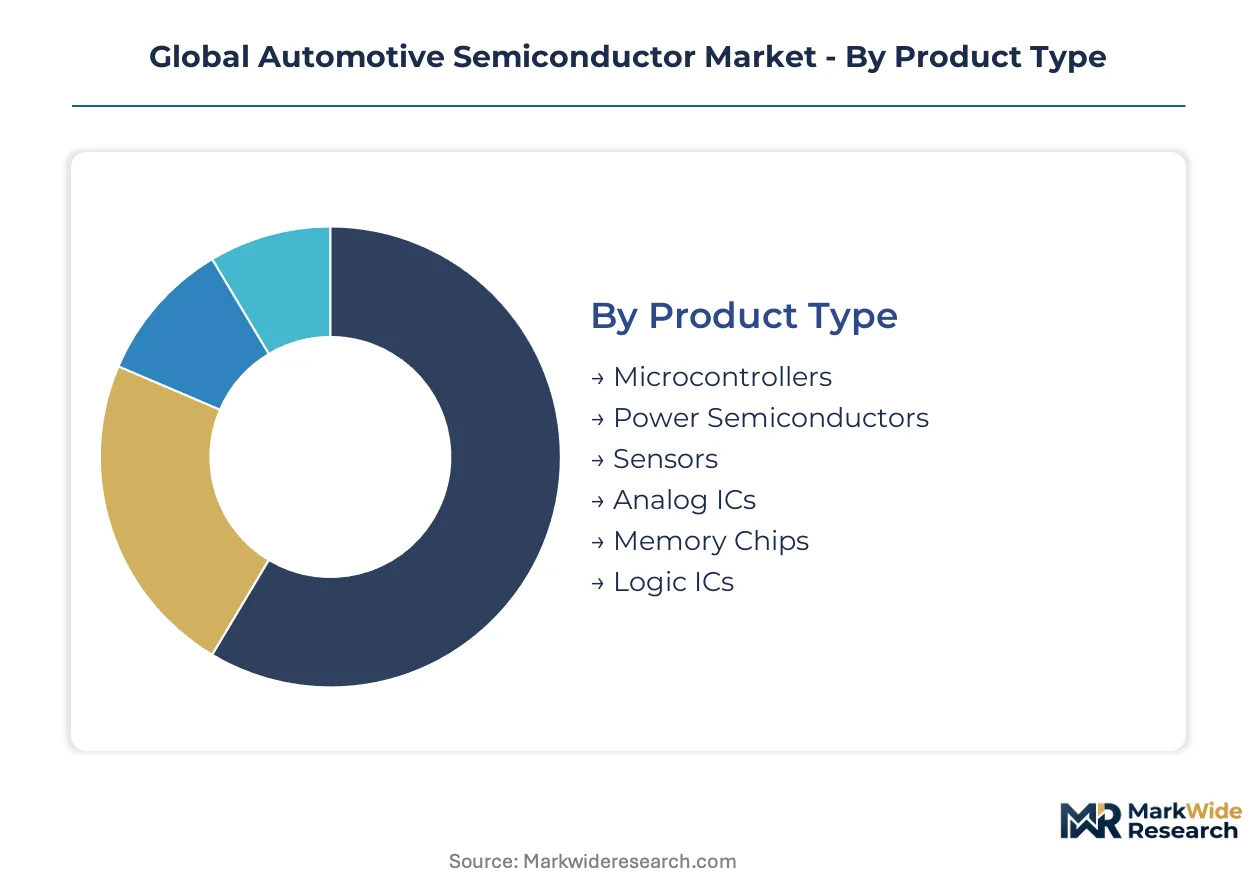
Understanding the segmentation of the global automotive semiconductor market is crucial for identifying key growth vectors and strategic investment areas. The diverse functional requirements and evolving vehicle architectures necessitate a granular view of product types, technologies, applications, and end-users.
Product Type:
The functional safety requirements, particularly from ISO 26262, significantly differentiate product types within the automotive semiconductor market.
- Microcontrollers:Foundational products control diverse vehicle functions, often operating on mature process nodes. Europe's General Safety Regulation mandates for ADAS features significantly increase demand for these embedded processors.
- Power Semiconductors:Manage high-voltage systems in electric vehicles, frequently employing wide-bandgap materials like SiC. China's massive EV production volume drives concentrated demand for these critical components.
- Sensors:Detect physical parameters for ADAS and in-cabin monitoring, enabling features like automatic emergency braking.
- Analog ICs:Process real-world signals for power management and interface functions, crucial for robust system operation.
- Memory Chips:Store firmware, maps, and vehicle data, with increasing capacity needs for advanced infotainment systems.
- Logic ICs:Perform complex computations for central processing units and graphics processing units, supporting high-performance applications.
Microcontrollers handle the majority of throughput; Power Semiconductors are the fastest mover on share.
Technology:
Technology segmentation reflects the distinct functional domains within modern vehicles, each demanding specialized semiconductor solutions.
- Advanced Driver Assistance Systems:Integrate radar, camera, and lidar sensors with high-performance processors for adaptive cruise control and lane keeping. Regulatory mandates in Europe drive demand for these integrated systems.
- Powertrain Control:Manages engine, transmission, and electric motor operations, with increasing complexity due to electrification. Demand for SiC-based solutions is high in Germany for EV inverter efficiency.
- Body Electronics:Controls comfort and convenience features such as power windows and lighting, often relying on mature microcontroller technologies.
- Infotainment:Provides navigation, media, and connectivity features, requiring powerful processors and secure communication modules.
- Communication Modules:Facilitate vehicle-to-everything (V2X) and in-vehicle networking, supporting advanced connectivity and autonomous driving.
- Safety Systems:Beyond ADAS, these include passive safety components like airbag deployment units, crucial for occupant protection.
Advanced Driver Assistance Systems and Powertrain Control represent the highest value contribution within this segment.
Application:
Segmentation by application highlights the varying stages of technological maturity and future growth trajectories across vehicle types.
- Electric Vehicles:Require high-voltage power semiconductors, battery management systems, and advanced motor control units for efficiency and range. Government incentives in China significantly boost this application.
- Autonomous Vehicles:Demand extremely high-performance compute platforms, specialized sensors, and redundant safety systems for self-driving capabilities. US NHTSA mandates influence testing and development for this segment.
- Hybrid Vehicles:Combine internal combustion engines with electric powertrains, requiring a mix of traditional and electric vehicle semiconductor components.
- Internal Combustion Engines:Utilize semiconductors for engine control, emissions management, and traditional vehicle functions.
- Connected Cars:Integrate communication modules and secure gateways for V2X capabilities and over-the-air updates.
- Commercial Vehicles:Incorporate robust semiconductors for fleet management, telematics, and specialized safety systems.
Demand is rapidly shifting towards Electric Vehicles and Autonomous Vehicles, displacing traditional internal combustion engine applications.
End User:
End-user segmentation reveals the complex procurement and integration strategies within the automotive value chain.
- OEMs:Directly integrate semiconductors into vehicle designs, increasingly engaging in direct design partnerships with foundries and fabless designers. German luxury car manufacturers exemplify this trend.
- Tier-1 Suppliers:Act as intermediaries, developing modules and sub-systems for OEMs, requiring strong relationships with semiconductor manufacturers. Established automotive manufacturing hubs like Japan rely heavily on these suppliers.
- Aftermarket Suppliers:Provide replacement parts and upgrade components, typically using standardized semiconductors for various vehicle models.
- Vehicle Assemblers:Focus on the final integration of components and systems, ensuring overall vehicle functionality.
- Electronics Suppliers:Specialize in providing electronic control units and modules, often working closely with Tier-1s and OEMs.
- Retrofitters:Install aftermarket systems like ADAS upgrades or infotainment units into existing vehicles.
OEMs increasingly influence semiconductor design and procurement, while Tier-1 Suppliers remain critical for system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive semiconductor market exhibits a complex interplay of import and export dynamics, driven by localized manufacturing hubs and specialized component production. Demand often concentrates where vehicle assembly and Tier-1 ecosystems are robust. This regional specialization influences supply chain resilience and technological adoption.
Germany
Demand for high-value power semiconductors is strong, driven by domestic luxury automakers and their electrification strategies. The KBA (Kraftfahrt-Bundesamt) mandates rigorous safety standards for vehicle components. Bavaria and Baden-Württemberg host significant automotive OEM and Tier-1 supplier clusters, focusing on advanced ADAS and EV powertrain development.
China
Government incentives create a massive end-market for power management ICs and battery management systems in electric vehicles. GB standards for connectivity and autonomous driving impose specific performance requirements on semiconductors. The Yangtze River Delta region is a major hub for EV production and semiconductor integration, attracting both domestic and international investment.
Japan
Established automotive manufacturing hubs rely heavily on Tier-1 suppliers for semiconductor integration into vehicle systems. JIS standards guide component quality and reliability for the domestic automotive industry. The Kanto region, particularly around Tokyo, supports a dense network of automotive electronics R&D and manufacturing facilities.
United States
Autonomous vehicle testing mandates from the NHTSA drive demand for high-performance compute platforms and specialized sensors. The US CHIPS Act provides subsidies for building new semiconductor fabs, de-risking domestic capacity expansion. Silicon Valley and Michigan's automotive corridor foster innovation in software-defined vehicles and advanced semiconductor design.
South Korea
Rapid electrification of domestic vehicle fleets creates demand for advanced power semiconductors and battery management solutions. The country's national automotive safety regulations align with global standards, influencing component design. Gyeonggi Province hosts major automotive and electronics manufacturers, driving innovation in in-vehicle infotainment and connectivity.
Global Automotive Semiconductor Market Key Industry Players
Listed leaders compete with private specialists across the automotive semiconductor value chain. The market structure exhibits a tiered consolidation, with a few integrated device manufacturers alongside numerous fabless designers and specialized foundries. Strategic archetypes include broad-portfolio suppliers, power semiconductor experts, and advanced logic specialists. Dominant competitive moves involve strategic partnerships for co-development and capacity expansion to meet demand surges.
Among the established semiconductor manufacturers, Infineon Technologies AG exemplifies a power semiconductor specialist, leveraging deep expertise in electric vehicle powertrains and industrial applications. NXP Semiconductors N.V. occupies a position as a broad-portfolio supplier, offering secure connectivity and processing solutions for diverse automotive applications, from infotainment to ADAS. Renesas Electronics Corporation represents another key player, providing microcontrollers and system-on-chip solutions crucial for various vehicle control systems. These firms anchor the market's technological evolution, supply chain resilience, and functional safety compliance.
| Leading Market Players |
|---|
| STMicroelectronics N.V. |
| NVIDIA |
| Infineon Technologies AG |
| TSMC |
| Qualcomm |
| Renesas Electronics Corporation |
| Texas Instruments Inc. |
| Wolfspeed |
| NXP Semiconductors N.V. |
| Others |
Cost & Logistics Intelligence
Wide-bandgap material substitution, particularly silicon carbide for traditional silicon, simultaneously reshapes the automotive semiconductor supply chain towards specialized foundries and introduces new pricing economics based on efficiency gains.
Pricing Analysis
Industrial OEM buyers anchor long-term contract-based pricing for automotive semiconductors, prioritizing supply stability over short-term cost fluctuations. Price differentiation stems from functional safety certification levels, such as ISO 26262 ASIL-D, and the degree of custom intellectual property integration. Pricing pressure stems from the high capital expenditure required for advanced logic nodes and silicon carbide substrates, which limits the supplier base. Tier-1 suppliers exhibit the most price sensitivity, balancing cost with OEM specifications, while luxury German automakers are least sensitive for performance-critical components.
Supply Chain Analysis
Taiwan and South Korea anchor advanced wafer fabrication, supplying critical logic ICs and memory chips for automotive applications. The supply chain draws from silicon ingots, rare earth elements for magnetics, and specialized silicon carbide substrates. Geopolitical tensions and the geographic concentration of advanced foundries in Taiwan introduce significant single-source vulnerability. Distribution runs through a complex network of direct sales to large OEMs and indirect channels via Tier-1 suppliers who integrate components into modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The architectural transformation of vehicles toward electrification and autonomy marks a high-growth disruption, fundamentally altering semiconductor demand.
For Market Incumbents: Shield core microcontroller and analog IC market share by investing heavily in functional safety talent and accelerating AEC-Q100 qualification for new products. Leverage deep customer relationships with established Tier-1 suppliers to co-develop next-generation platforms, addressing the threat from direct OEM sourcing. Expand capacity in power semiconductors, particularly for silicon carbide devices, to meet growing EV production volumes, utilizing subsidies from acts like the US CHIPS Act.
For New Entrants and Emerging Players: Specialized software and integration services for complex ADAS architectures represent an under-served gap in the market. Target the rapidly expanding in-cabin sensing segment, focusing on image sensors and microcontrollers for driver monitoring systems. A go-to-market angle should emphasize agility and deep expertise in specific functional safety domains, partnering with North American EV startups seeking custom silicon solutions.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with established fabless designers and specialized foundries with strong intellectual property in wide-bandgap materials or secure connectivity. The long-term viability favors firms with proven ISO 26262 compliance and a clear roadmap for 7nm and below process nodes. A key signal to watch is the increasing number of direct design partnerships between automakers and semiconductor firms, indicating market validation for specialized capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Accelerate Silicon Carbide Capacity | Ensures supply for high-demand EV inverters, enhancing powertrain efficiency for automakers. |
| Invest in Functional Safety Expertise | Meets stringent ISO 26262 requirements, critical for high-value ADAS and autonomous systems. |
| Form Direct OEM Design Partnerships | Allows co-development of custom silicon, optimizing performance for software-defined vehicle architectures. |
| Develop Advanced In-Cabin Sensing Solutions | Captures emerging market for driver and occupant monitoring, driven by safety regulations. |
| Expand Secure V2X Connectivity Modules | Enables cooperative autonomous driving and enhances vehicle-to-infrastructure communication capabilities. |
Research Approach
Operator-level perspectives from Tier-1 procurement leads, OEM platform engineers, and fabless design executives anchored the qualitative base for this analysis. This primary research was rigorously combined with secondary validation from vehicle production databases, regulatory filings from the US NHTSA and Europe's KBA, and reports from industry associations. The approach utilized both bottom-up market sizing and top-down revenue validation.
Sensitivity analysis framed the analytical framework across the projection horizon, modeling segmentation by product type, technology, application, end-user, and regional production clusters. Compound annual growth rates were derived through a multi-variable regression model, incorporating historical market trends and projected technological shifts. Key forecast inputs included global EV production targets and the phased implementation of ADAS feature mandates in Europe.
Underlying assumptions cover stable macroeconomic conditions and consistent regulatory enforcement, with deviation risk concentrated in geopolitical instability impacting supply chains. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Global Computer Microchip Market
Semiconductors
China Semiconductor Market
Semiconductors
Digital Semiconductors Market
Semiconductors
Indium Phosphide Compound Semiconductor Market
Semiconductors
Analog Semiconductor Market
Semiconductors
India Semiconductor Market
Semiconductors
Semiconductor Bonding Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
Asia Pacific Flash Memory Market
Semiconductors
Semiconductor Target Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Logic Semiconductor Market
Semiconductors
Chiplets Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Global FD-SOI Wafers Market
Semiconductors
Discrete Semiconductor Market