
 India Liquid Silicon Rubber Market | 2026-2036
India Liquid Silicon Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
India Liquid Silicon Rubber Market Foresight
Market Dynamics
The India liquid silicone rubber market is expanding along a widening gap between medical-grade formulations and general-purpose commodity grades. Shin-Etsu Chemical India Private Limited leverages its parent company's polymer synthesis expertise to dominate high-purity segments. Dow Corning India Private Limited anchors its position through backward integration into siloxane feedstock production. Wacker Chemicals India Private Limited differentiates via localized compounding facilities serving automotive OEMs in Chennai and Pune.
Product Landscape
Liquid silicone rubber denotes a two-part platinum-cured elastomer system with viscosity typically below 500,000 mPa·s, enabling injection molding of complex geometries with Shore A hardness ranging from 3 to 80. Addition cure systems lead volume consumption due to their absence of byproduct volatiles, making them indispensable for medical device molding and electronics encapsulation where outgassing tolerance approaches zero. The medical devices end-use industry captures the deepest margin pools, driven by catheter component and respiratory mask demand, while automotive sealant applications sustain the broadest volume base across Tier-1 suppliers.
Regulatory Environment
BIS standards govern silicone rubber imports and domestic production quality benchmarks, while CDSCO regulates medical-grade formulations through device master file requirements that constrain unapproved suppliers. The PLI scheme for specialty chemicals channels capital toward domestic silicone intermediate capacity, reducing import dependence on Chinese dimethylcyclosiloxane feedstock. Stakeholders must monitor BIS notification timelines and CDSCO biocompatibility testing protocol updates to preempt compliance-driven supply disruptions.
Market Dynamics
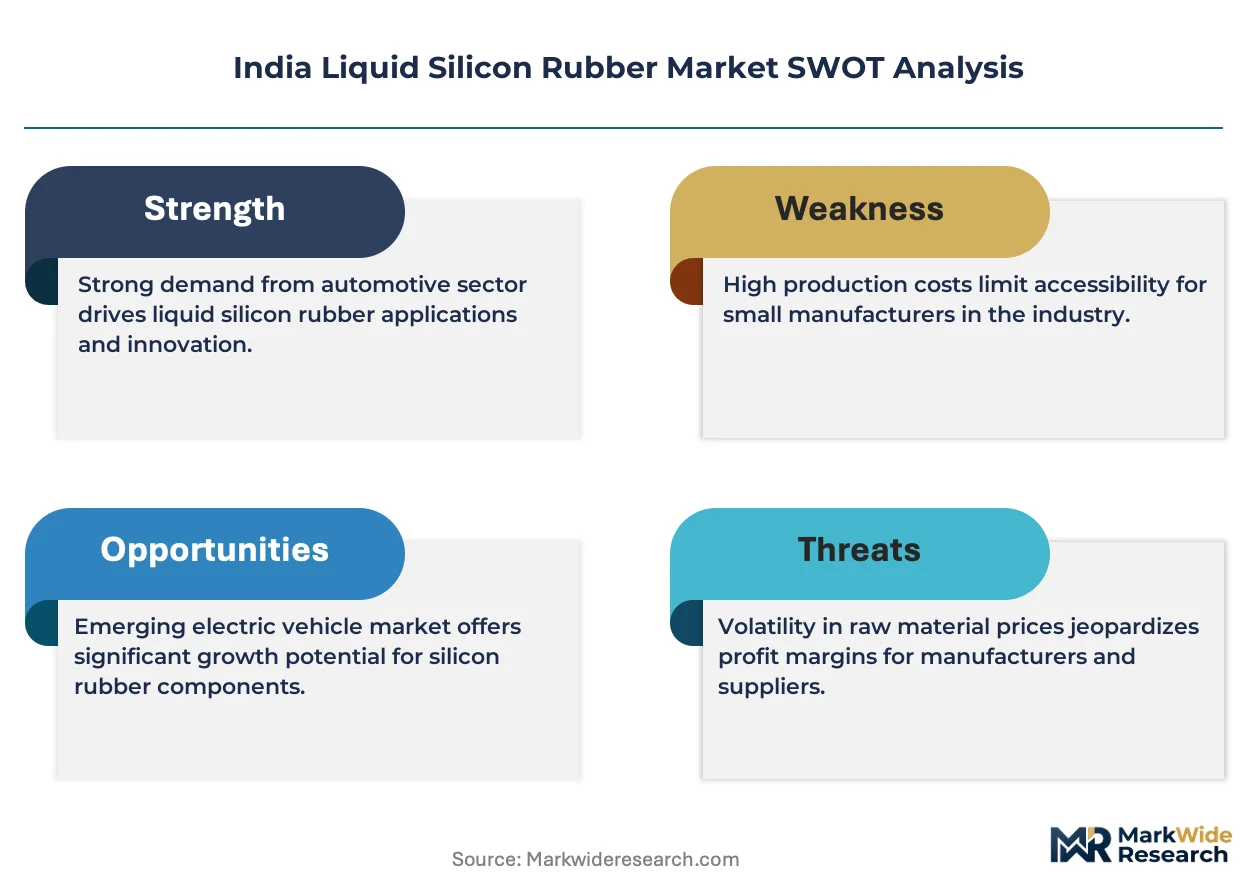
PLI scheme disbursements for specialty chemicals are concentrating domestic silicone intermediate capacity in Gujarat and Maharashtra, compressing import dependence on Chinese dimethylcyclosiloxane while medical device OEMs in Pune escalate implant-grade formulation requirements.
Growth Catalysts
- BIS Certification Mandates:Compulsory quality benchmarks for silicone rubber imports are forcing domestic compounding investments, expanding localized formulation capabilities across Maharashtra and Tamil Nadu industrial corridors.
- Medical Device OEM Procurement:Catheter component and respiratory mask manufacturers are scaling platinum-cured LSR volumes, driving demand for high-purity grades with zero outgassing tolerance.
- Automotive Cluster Concentration:Pune and Chennai OEM ecosystems are absorbing broad-base sealant volumes, anchoring general-purpose grade consumption across Tier-1 supplier networks.
Market Restraints
- Feedstock Import Concentration:Dimethylcyclosiloxane supply remains concentrated in Chinese upstream capacity, exposing formulators to freight volatility and currency fluctuation risks.
- CDSCO Master File Friction:Medical-grade silicone device approvals require biocompatibility testing protocols that extend qualification timelines for unapproved domestic suppliers.
- Fluorosilicone Substitution:Aggressive fuel-system applications in automotive are migrating toward fluorosilicone alternatives with superior hydrocarbon resistance, constraining standard LSR addressable market.
Strategic Opportunities
- Karnataka Electronics Corridor:Bengaluru's semiconductor packaging and sensor encapsulation demand remains underpenetrated by localized LSR compounders, creating white space for medical-grade crossovers.
- PLI Capital Channeling:The specialty chemicals production-linked incentive is underwriting domestic siloxane cracking investments, enabling backward integration into feedstock production.
- 3D-Printed Mold Convergence:Additive manufacturing of injection mold inserts is compressing prototype-to-production cycles for complex medical geometries, opening low-volume high-margin niches.
Industry Challenges
- Platinum Catalyst Sourcing:Refinery-grade platinum group metal supply constraints are compressing catalyst availability, forcing compounders to manage inventory cycles against spot price volatility.
- Cleanroom Compounding Scale-Up:Medical-grade LSR requires ISO 14644 Class 7 compounding environments, demanding capex intensity that fragments domestic capacity between commodity and specialty producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Liquid Silicon Rubber Market |
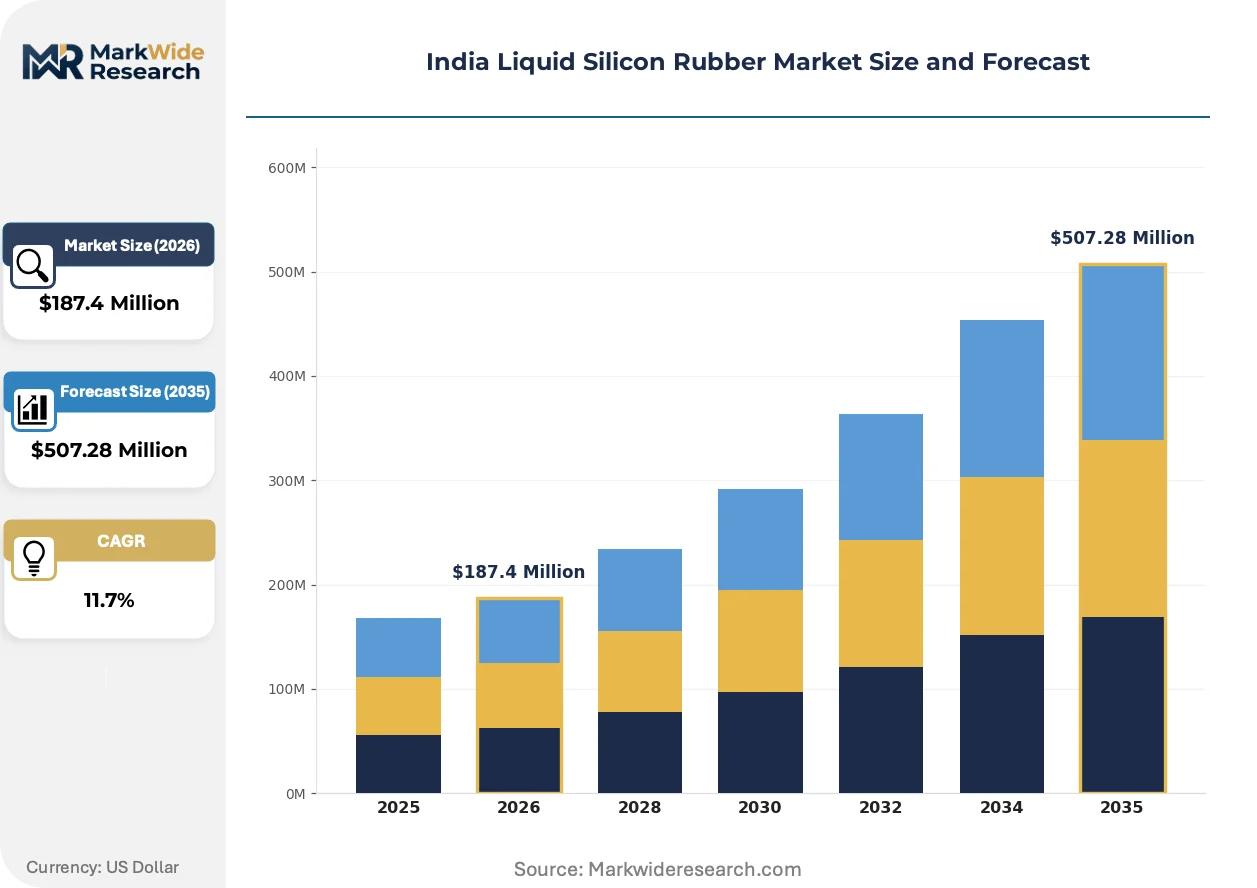
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condensation Cure, Addition Cure, High-Performance, Specialty End Use Industry: Automotive, Electronics, Medical Devices, Construction Application: Molding, Coating, Adhesives, Sealants Form: Liquid, Paste, Gel, Rubber Compound |
| Companies Covered | Shin-Etsu Chemical India Private Limited, NuSil Technology India Private Limited, Dow Corning India Private Limited, Stockwell Elastomerics India Private Limited, Silicones India Private Limited, Elkem Silicones India Private Limited, Wacker Chemicals India Private Limited, Specialty Silicone Products India Private Limited, Momentive Performance Materials India Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Liquid Silicon Rubber Market Shifts & Advancements
Self-adhesive LSR grades are eliminating secondary primer applications in automotive assembly, while optical-grade formulations for LED encapsulation are rewriting clarity specifications across electronics supply chains.
Self-adhesive liquid silicone rubber technology is rewriting bonding protocols in multi-material automotive assemblies. Maruti Suzuki and Mahindra suppliers in Pune are adopting primerless grades at compressed qualification cycles. This displacement of secondary surface treatment is compressing total applied cost while expanding design freedom for lighting and HVAC seal integration.
CDSCO's 2024 biocompatibility testing protocol updates are tightening cytotoxicity thresholds for implantable silicone devices. Domestic formulators must now submit extended rabbit intracutaneous reactivity studies, extending master file approval timelines. Respiratory mask manufacturers in Mumbai are responding by consolidating supplier bases to pre-qualified compounders with existing device dossiers.
Direct compounder-to-OEM contracting is displacing distributor intermediaries in high-volume automotive sealant procurement. Tier-1 suppliers in Chennai are negotiating annual volume agreements with Wacker and Dow Corning India facilities, extracting price transparency and technical service integration. This channel compression is most visible in Maharashtra's industrial corridor where procurement functions co-locate with engineering teams.
India Liquid Silicon Rubber Market Segmentation
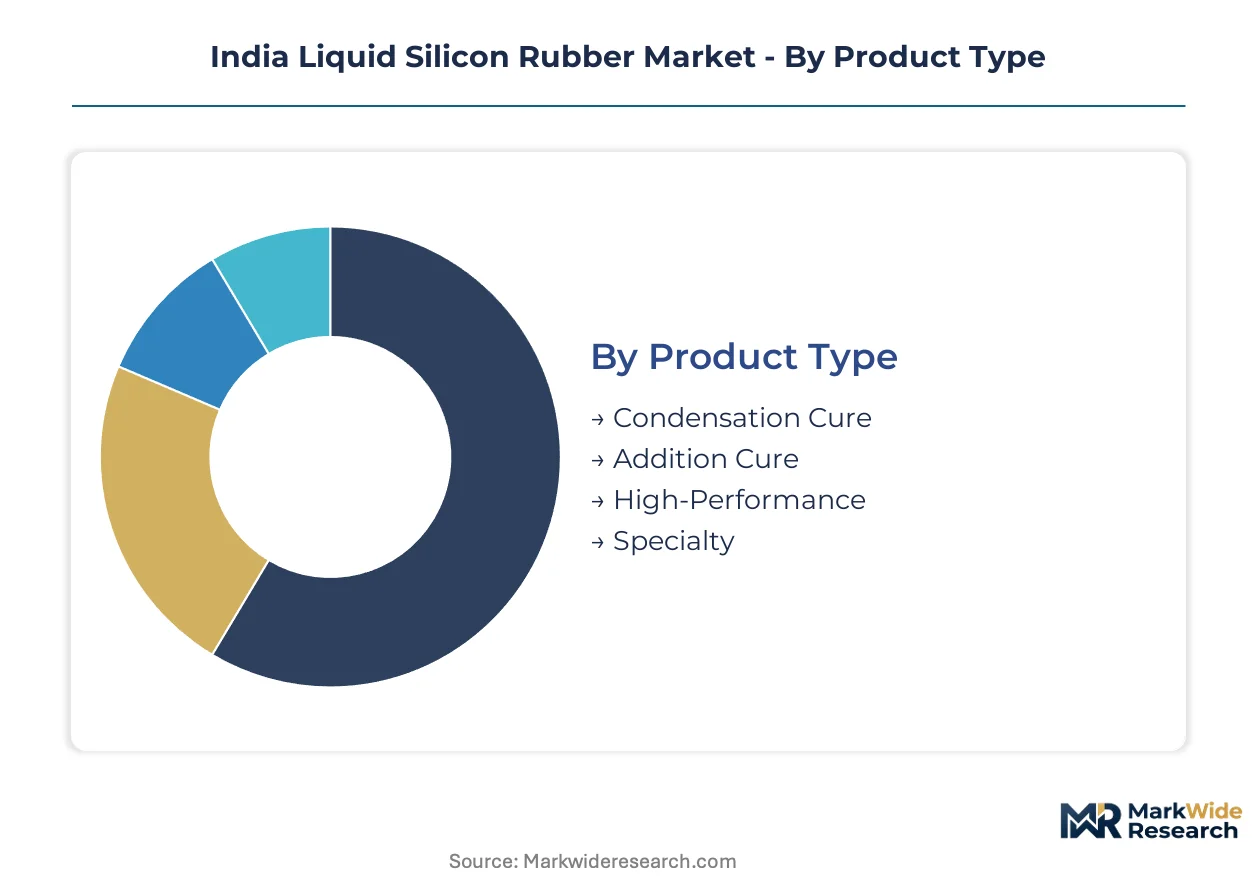
Segmentation in India's liquid silicone rubber market exposes a sharp divide between platinum-cured medical formulations commanding premium pricing and commodity condensation systems serving automotive volume plays. Formulators must align compounding investments with end-use certification requirements that vary dramatically across BIS, CDSCO, and OEM-specific protocols.
Product Type:
Platinum-cure chemistry versus condensation chemistry defines the technology frontier, with performance tiers separating implant-grade purity from industrial durability specifications.
- Addition Cure:Platinum-catalyzed crosslinking eliminates volatile byproducts, enabling zero-outgassing compliance for catheter components and respiratory masks manufactured in Pune's medical device corridor. CDSCO master file requirements favor pre-qualified compounders with existing biocompatibility dossiers.
- Condensation Cure:Tin-catalyzed systems release alcohol byproducts during cure, constraining use to non-medical applications where outgassing tolerance permits. Automotive sealant manufacturers in Chennai absorb the broadest volumes at compressed price points.
- High-Performance:Formulations engineered for extreme temperature cycling and chemical resistance serve aerospace gasketing and underhood automotive applications.
- Specialty:Self-adhesive and optical-grade variants eliminate secondary processing steps for LED encapsulation and primerless multi-material bonding.
Addition Cure leads on scale; Specialty gains share fastest through electronics corridor penetration.
End Use Industry:
Customer concentration patterns cluster around Maharashtra's industrial corridor, with procurement authority shifting from distributors to direct OEM contracting.
- Medical Devices:Catheter hubs, respiratory mask seals, and implantable components demand ISO 14644 Class 7 cleanroom compounding. CDSCO's tightened cytotoxicity thresholds extend qualification timelines, consolidating procurement among dossier-holding suppliers.
- Automotive:Pune and Chennai OEM ecosystems consume general-purpose sealant volumes across HVAC, lighting, and powertrain applications. Tier-1 suppliers negotiate annual volume agreements extracting technical service integration.
- Electronics:Bengaluru's semiconductor packaging and sensor encapsulation demand remains underpenetrated by localized compounders, creating white space for medical-grade crossovers.
- Construction:Joint sealants and weatherproofing membranes absorb commodity-grade volumes with lower certification barriers.
Automotive dominates volume throughput; Medical Devices commands the steepest margin expansion trajectory.
Application:
Process technology requirements separate injection-molding precision from manual-application flexibility across the value chain.
- Molding:Liquid injection molding of complex geometries with Shore A 3-80 hardness range serves medical device and automotive component production. Viscosity below 500,000 mPa·s enables thin-wall precision.
- Sealants:Room-temperature vulcanizing formulations dominate construction and automotive aftermarket applications with lower capital intensity.
- Coating:Thin-film protective layers for electronics substrates require optical clarity and dielectric stability specifications.
- Adhesives:Self-priming grades are displacing secondary surface treatment in multi-material automotive assemblies, compressing total applied cost.
Molding captures the deepest technology moats; Adhesives climbs fastest on primerless adoption.
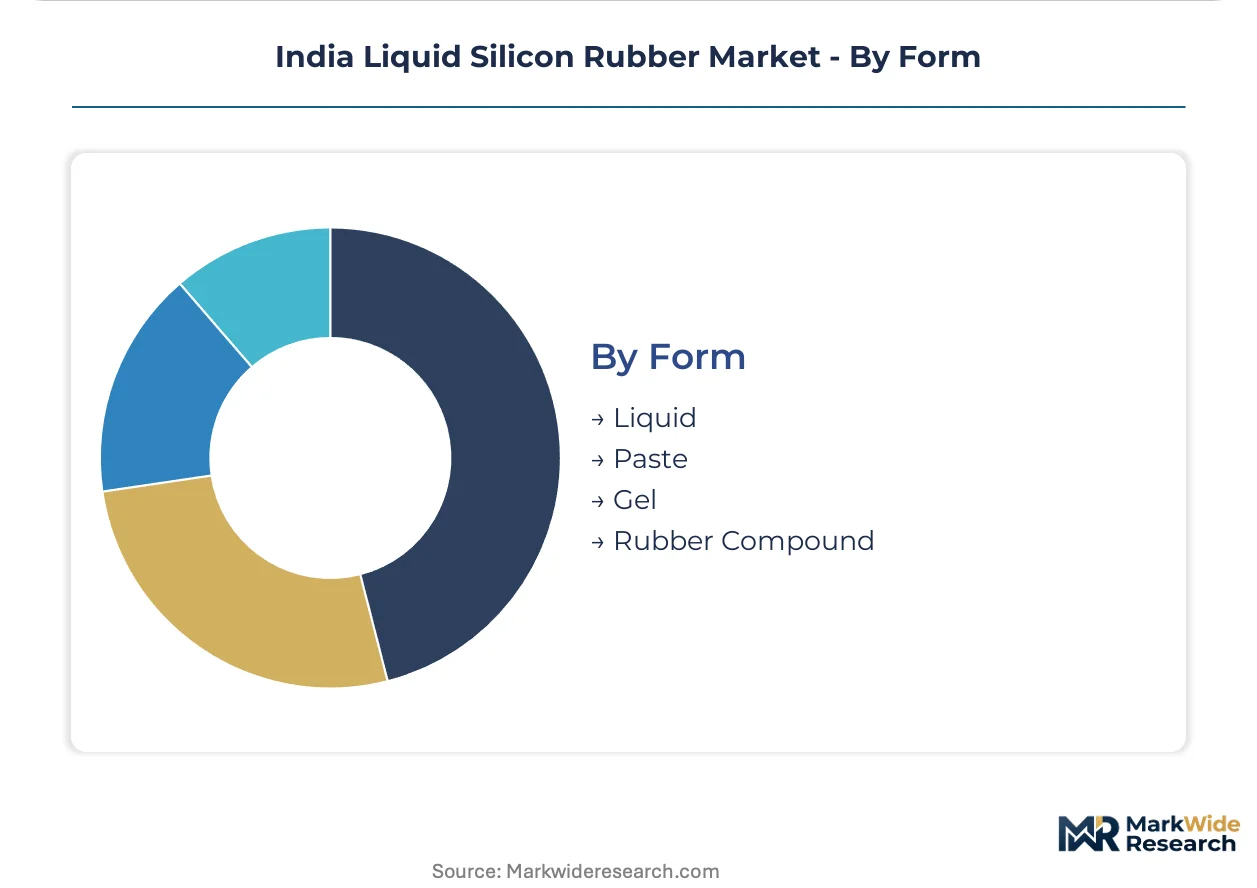
Form:
Physical state determines handling equipment, storage protocols, and supply chain configuration from compounder to end-user.
- Liquid:Two-part pumpable systems enable automated metering and mixing for high-volume injection molding operations. Maharashtra's automotive Tier-1s specify liquid form for production line integration.
- Rubber Compound:Pre-catalyzed solid formulations serve compression molding and extrusion applications with simpler processing infrastructure.
- Paste:Thixotropic consistency prevents sag in vertical joint applications across construction and automotive assembly.
- Gel:Ultra-soft Shore A below 10 formulations cushion medical devices and electronics against vibration and thermal cycling stress.
Liquid form anchors industrial scale; Gel expands most quickly through medical and electronics convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymer chemists and platinum catalyst specialists concentrate in Maharashtra's industrial corridor, anchoring India's liquid silicone rubber formulation capabilities. Gujarat's chemical engineering workforce supports upstream siloxane cracking investments. Karnataka's materials science talent pools drive electronics encapsulation demand.
Maharashtra
Medical device OEMs in Pune and Mumbai escalate procurement of implant-grade silicone components for catheter hubs and respiratory masks. BIS certification mandates for silicone rubber imports force domestic compounding investments across Mumbai-Pune industrial belt. The state's automotive Tier-1 suppliers negotiate direct annual volume agreements with compounders, extracting technical service integration.
Gujarat
PLI scheme disbursements for specialty chemicals concentrate domestic silicone intermediate capacity in Dahej and Vadodara chemical complexes. The state's refinery-grade platinum group metal processing infrastructure supports catalyst supply chains for addition-cure formulations. Gujarat's siloxane cracking investments reduce import dependence on Chinese dimethylcyclosiloxane feedstock.
Tamil Nadu
Chennai's automotive OEM ecosystem absorbs broad-base sealant volumes across HVAC and lighting applications. CDSCO master file requirements for medical-grade formulations extend qualification timelines, constraining unapproved local suppliers. The Sriperumbudur-Oragadam industrial corridor hosts Tier-1 suppliers specifying liquid form LSR for production line integration.
Karnataka
Bengaluru's semiconductor packaging and sensor encapsulation demand remains underpenetrated by localized compounders, creating white space for medical-grade crossovers. The state's electronics manufacturing clusters seek optical-grade formulations for LED encapsulation with clarity specifications. Karnataka's cleanroom infrastructure scarcity fragments domestic capacity between commodity and specialty producers.
Telangana
Hyderabad's pharmaceutical and medical device manufacturing base generates demand for biocompatible silicone formulations. The state's life sciences corridor attracts compounders seeking CDSCO pre-qualified supplier status. Genome Valley's device manufacturers consolidate procurement among dossier-holding suppliers to manage extended rabbit intracutaneous reactivity study requirements.
India Liquid Silicon Rubber Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across India's liquid silicone rubber market structure. Integrated siloxane-to-compound manufacturers anchor supply security through captive feedstock production. Specialty formulators concentrate margin capture in medical-grade segments requiring ISO 14644 Class 7 cleanroom infrastructure. The competitive arena shows dual pressure points: backward integration into dimethylcyclosiloxane cracking and forward integration into direct OEM contracting displacing distributor intermediaries.
Among Japan-based chemical conglomerates with Indian subsidiaries, Shin-Etsu Chemical India Private Limited exemplifies polymer synthesis expertise applied to high-purity medical segments. Dow Corning India Private Limited represents North American multinational positioning through siloxane feedstock backward integration. Wacker Chemicals India Private Limited anchors German chemical conglomerate strategy via localized compounding facilities serving automotive OEMs in Pune and Chennai.
| Leading Market Players |
|---|
| Shin-Etsu Chemical India Private Limited |
| NuSil Technology India Private Limited |
| Dow Corning India Private Limited |
| Stockwell Elastomerics India Private Limited |
| Silicones India Private Limited |
| Elkem Silicones India Private Limited |
| Wacker Chemicals India Private Limited |
| Specialty Silicone Products India Private Limited |
| Momentive Performance Materials India Private Limited |
| Others |
Supply & Pricing Matrix
CDSCO's tightened cytotoxicity thresholds for implantable silicone devices gate qualified supply and premium-tier pricing access, forcing respiratory mask manufacturers in Mumbai to consolidate procurement among dossier-holding compounders with extended rabbit intracutaneous reactivity studies.
Pricing Analysis
The bundled-vs-unbundled service split separates technical service integration from commodity-grade transactions across Maharashtra's industrial corridor. Three-tier pricing structure across implant-grade, automotive-grade, and construction-grade levels stratifies by certification intensity and cleanroom compounding requirements. Cost compression in general-purpose sealant tiers is intensifying because Tier-1 suppliers extract annual volume transparency through direct compounder contracting. Construction joint sealant buyers show highest price sensitivity; medical device OEMs in Pune demonstrate lowest sensitivity due to CDSCO master file switching costs.
Supply Chain Analysis
Single-source vulnerability sits with Chinese upstream capacity for dimethylcyclosiloxane feedstock, exposing formulators to freight volatility and currency fluctuation risks. Domestic silicone intermediate production concentrates in Gujarat and Maharashtra, while platinum catalyst supply rests on South African and Russian refinery-grade processing infrastructure. Raw material dependencies span dimethylcyclosiloxane monomer, platinum group metal catalysts, and specialized filler packages. Tariff exposure on Chinese feedstock imports compounds supply chain fragility. Distribution runs through direct compounder-to-OEM annual agreements displacing distributor intermediaries in high-volume automotive procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's liquid silicone rubber market offers margin-expansion potential as CDSCO qualification requirements consolidate procurement among pre-certified compounders, enabling premium-tier pricing power for dossier-holding suppliers.
For Market Incumbents: Hedge against fluorosilicone substitution in aggressive fuel-system applications by deepening backward integration into siloxane cracking investments under PLI scheme disbursements. Anchor supply security through captive dimethylcyclosiloxane production in Gujarat chemical complexes while defending medical-grade margin pools via ISO 14644 Class 7 cleanroom capacity expansion in Pune. For New Entrants and Emerging Players: Bengaluru's semiconductor packaging and sensor encapsulation demand represents an underserved buyer archetype with minimal localized compounder presence. Target optical-grade formulations for LED encapsulation with clarity specifications exceeding commodity-grade capabilities. Pursue medical-grade crossover positioning leveraging Karnataka's materials science talent pools and electronics manufacturing cluster density. For Investors and Strategic Acquirers: Roll-up economics work for specialty silicone formulators with CDSCO pre-qualified supplier status because regulatory qualification timelines create durable competitive moats. Five-to-ten-year viability hinges on consolidation of fragmented domestic capacity between commodity and specialty producers. Monitor PLI scheme disbursement velocity for specialty chemicals as the inflection signal for domestic feedstock independence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Cracking | PLI scheme capital channeling reduces Chinese dimethylcyclosiloxane import dependence for Gujarat compounders. |
| ISO 14644 Class 7 Cleanroom Certification | CDSCO master file requirements favor pre-qualified medical-grade suppliers with biocompatibility dossiers. |
| Direct OEM Contracting Displacement | Tier-1 automotive suppliers in Chennai extract price transparency through annual volume agreements. |
| Optical-Grade Formulation Development | Bengaluru semiconductor packaging demand creates white space for clarity-specification LED encapsulation. |
| Platinum Catalyst Inventory Hedging | Refinery-grade platinum group metal supply constraints force compounders to manage spot price volatility cycles. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Tamil Nadu, Karnataka, and Telangana, with primary inputs from each state's industrial corridor. Primary interviews with silicone compounding plant managers, procurement leads at medical device OEMs, automotive Tier-1 supplier technical directors, and CDSCO regulatory affairs specialists combined with secondary validation from BIS notification records, CDSCO device master file databases, PLI scheme disbursement filings, and customs trade data. Bottom-up volume modeling triangulated against top-down specialty chemicals industry benchmarks.
Granularity-level framing applied separate modeling tracks for platinum-cure versus condensation-cure chemistry, medical device versus automotive versus electronics end-use industries, and liquid versus gel versus paste physical forms across the projection horizon. CAGRs derived from regression analysis against silicone intermediate capacity additions, OEM procurement cycle timing, and regulatory approval velocity. Industry-specific forecast inputs incorporated CDSCO biocompatibility protocol update implementation timelines and PLI scheme capital deployment rates.
Underlying measurement precision varies by segment; medical device-grade formulations carry tighter precision than construction-grade commodity tiers due to CDSCO master file documentation requirements. Forecasts reflect assumptions regarding PLI disbursement continuity, BIS certification mandate enforcement, and Chinese feedstock tariff stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Global Silicone Market
Semiconductor Material
Electronic Ceramics Market
Semiconductor Material
Silicon Carbide Ceramics Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Silicon Dioxide Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Quartz Market
Semiconductor Material
Global Gallium Oxide Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Semiconductor PI Film Market
Semiconductor Material
North America Silicone Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
Ultra High Purity Silicon Carbide Market
Semiconductor Material
Global Thermal Paste Market