
 Monocrystalline Half-Chip Module Market | 2026-2036
Monocrystalline Half-Chip Module Market Size, Share, and Industry Trends Forecast 2026-2036
Monocrystalline Half-Chip Module Market Insights
High-efficiency module specifications above 600W is reorganizing procurement priorities across utility-scale developers. LONGi Green Energy leverages integrated wafer-to-module production to sustain cost leadership in premium efficiency tiers. JA Solar Technology anchors its competitive stance through aggressive capacity expansion in n-type TOPCon half-cell lines.
Monocrystalline half-chip modules split standard solar cells into two equal segments, reducing resistive losses and enabling higher fill factors through parallel circuit design. Bifacial modules capture growing share in utility and ground-mounted installations where albedo conditions justify dual-glass construction premiums. Specialty modules serving building-integrated applications command differentiated margins despite smaller volume pools.
China's MIIT enforces GB/T 9535 certification standards that mandate thermal cycling durability for grid-connected module deployments. India's CEA technical standards for solar photovoltaic systems prescribe minimum performance ratios that half-cell architectures satisfy more reliably than full-cell alternatives. Stakeholders must monitor evolving efficiency thresholds in national procurement tenders as module wattage benchmarks reset contract qualification criteria.
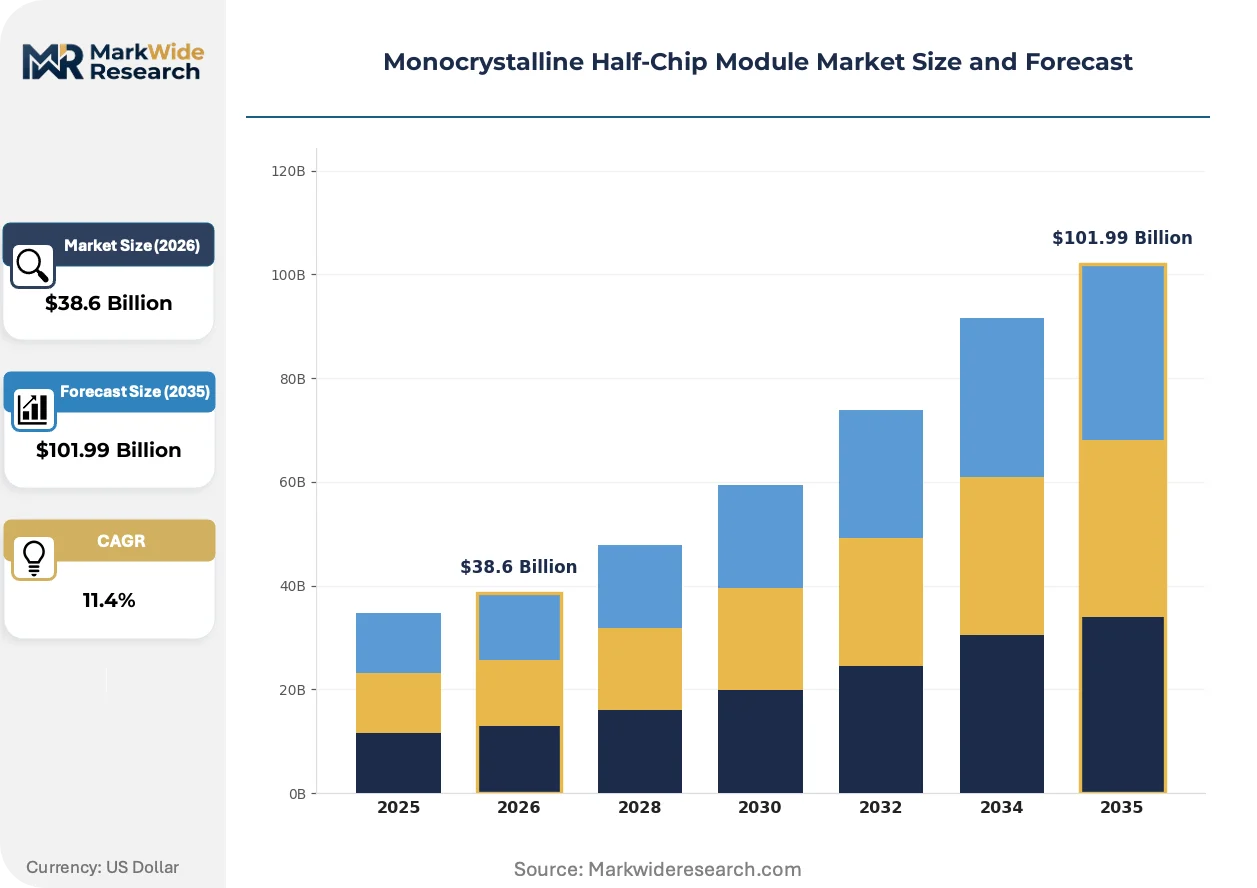
Market Dynamics
Utility-scale solar developers are reconfiguring procurement specifications around 600W-plus module thresholds, compressing contract qualification windows and forcing rapid manufacturing retooling across cell and module facilities.
Growth Catalysts
- GB/T 9535 Thermal Cycling Mandates:China's MIIT enforcement of durability certification for grid-connected deployments is disqualifying legacy full-cell architectures and accelerating half-chip qualification timelines.
- Albedo-Optimized Ground Mounts:Dual-glass bifacial construction is capturing expanded share in high-reflectivity installations across Rajasthan and Gujarat solar parks.
- N-type TOPCon Cell Migration:Wafer-level efficiency gains from tunnel oxide passivated contact structures are enabling half-cut designs to breach 22% module-level conversion thresholds.
Market Restraints
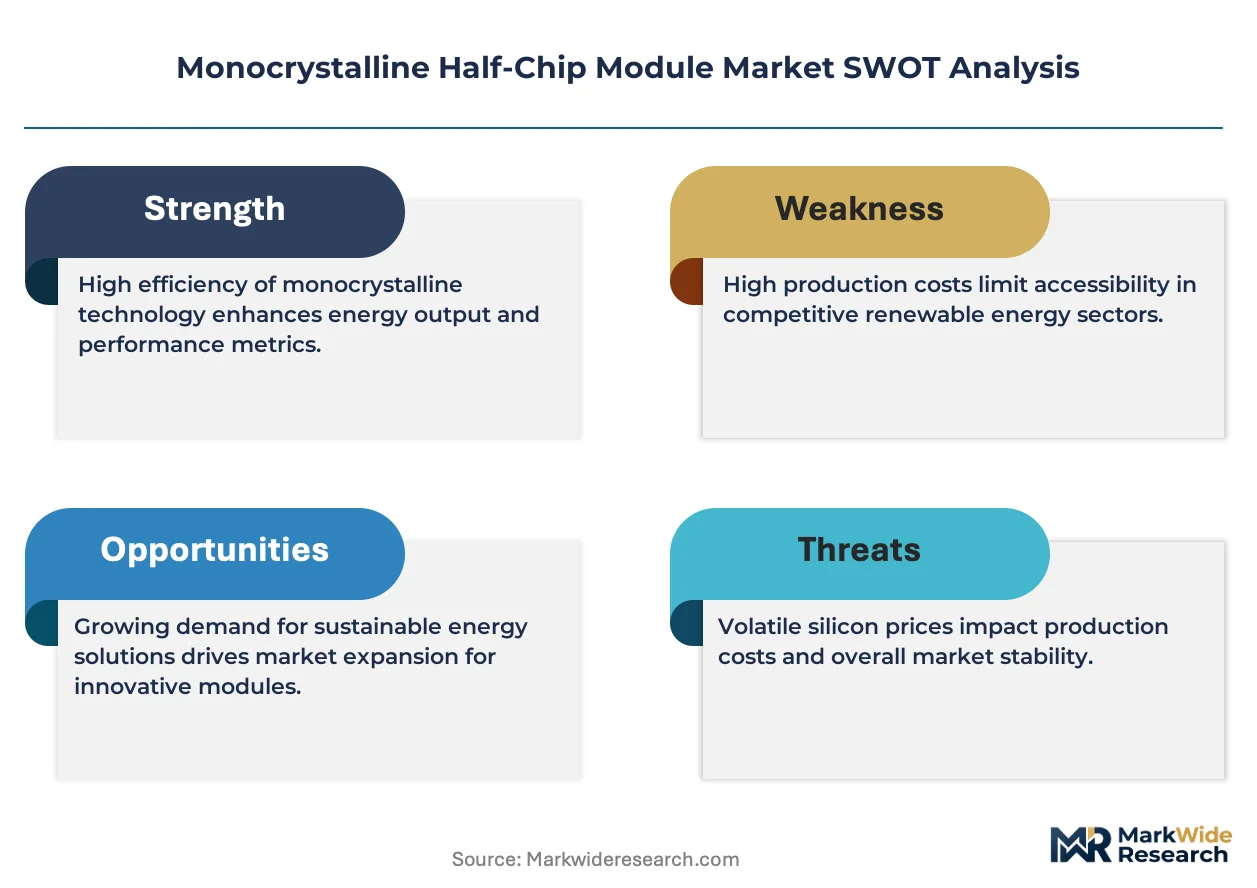
- Polysilicon Input Volatility:Metallurgical-grade silicon purification bottlenecks in Xinjiang and Inner Mongolia concentrate feedstock risk for wafer manufacturers.
- Silver Paste Cost Exposure:Screen-printed metallization on half-cut cells consumes 20-30% more silver per watt than full-cell alternatives due to doubled busbar requirements.
- Glass-Glass Weight Penalties:Bifacial dual-glass modules impose 15-20% higher logistics costs versus framed monofacial designs, constraining rooftop penetration.
Strategic Opportunities
- Building-Integrated Photovoltaics:Semi-transparent and colored half-cell modules command premium positioning in facade and skylight applications where aesthetic customization outweighs efficiency maximization.
- India PLI Scheme Capacity:Production-linked incentive disbursements for domestic module manufacturing are attracting greenfield half-cell line investments in Andhra Pradesh and Tamil Nadu.
- Agrivoltaic Dual-Use Arrays:Elevated mounting configurations with bifacial half-chip modules enable simultaneous crop cultivation and energy generation in water-stressed agricultural regions.
Industry Challenges
- Cell Sorting Precision Requirements:Halving cell dimensions doubles the population requiring current-matching within strings, demanding sub-0.1A binning tolerance that strains legacy testing infrastructure.
- Cross-Border Certification Stacking:India's CEA technical standards, IEC 61215/61730 sequences, and project-financer due diligence create overlapping compliance timelines that extend product qualification by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monocrystalline Half-Chip Module Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $101.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Modules, High-Efficiency Modules, Bifacial Modules, Specialty Modules End User: Residential, Commercial, Industrial, Utility Installation Method: Ground-Mounted, Roof-Mounted, Building-Integrated, Floating Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | LONGi Green Energy, Trinasolar, JA Solar Technology, JinkoSolar, Canadian Solar, Tongwei Solar, TCL Zhonghuan, Hanwha Q CELLS, Risen Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monocrystalline Half-Chip Module Market Trends and Innovations
Cell interconnection architectures and encapsulation materials are undergoing simultaneous revision as manufacturers pursue wattage gains without proportionate area expansion.
SMBB (multi-busbar) designs with 9-12 thin wires are displacing 3-5 busbar legacy configurations in half-cut cell assembly. European utility EPCs are specifying 9-busbar modules for 2025-2026 delivery slots to reduce resistive losses and enable thinner ribbon interconnection. This displacement is compressing equipment depreciation schedules for stringer-tabber machinery commissioned before 2022.
China's updated GB standards for photovoltaic module efficiency are tightening certification thresholds through MIIT-administered testing protocols. Module suppliers must now demonstrate 85% minimum performance retention after 200 thermal cycles versus prior 50-cycle requirements. Domestic developers in Shandong and Hebei provinces are rejecting tenders from manufacturers lacking updated GB/T 9535 documentation.
Direct offtake contracting between module manufacturers and utility-scale IPPs is consolidating procurement channels previously fragmented through distributor networks. LONGi Green Energy and JA Solar Technology have established dedicated utility account teams bypassing regional wholesalers for projects above 100MW. This channel compression is most visible in India's ultra-mega solar park auctions where developers negotiate frame specifications and warranty terms directly with cell and module engineering teams.
Monocrystalline Half-Chip Module Market Segmentation
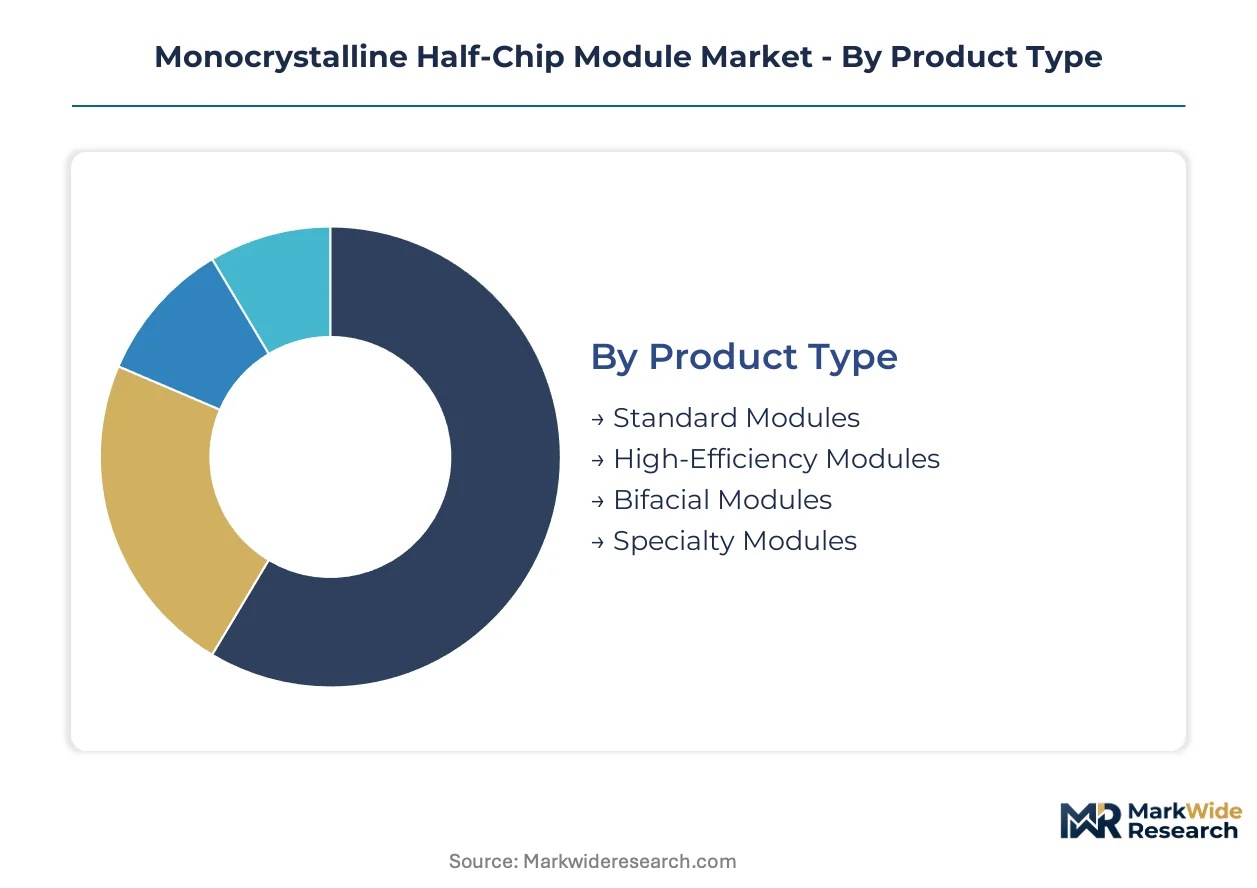
Module segmentation in this market reflects divergent cost structures and performance requirements across deployment contexts. Procurement specifications increasingly bifurcate between wattage-maximizing utility formats and aesthetic-constrained building applications.
Product Type:
Substitution pressure from n-type TOPCon and heterojunction architectures is compressing margins in legacy p-type segments while rewarding premium efficiency tiers.
- Standard Modules:Conventional p-type PERC half-cut cells deliver 540-600W in standard 72-cell footprints. Procurement concentrates in India's state-level tenders where Gujarat's DISCOMs specify minimum 545W thresholds for ground-mounted solar parks.
- High-Efficiency Modules:Tunnel oxide passivated contact (TOPCon) cell architectures breach 22.5% module efficiency through enhanced surface passivation. Demand clusters in China's Shandong province where MIIT's updated GB/T 9535 standards disqualify lower-tier imports from grid-connected projects.
- Bifacial Modules:Dual-glass construction captures rear-side irradiance in high-albedo installations across Rajasthan's desert solar parks.
- Specialty Modules:Semi-transparent and colored variants serve building-integrated facade applications where aesthetic specifications override pure efficiency metrics.
Standard modules anchor the volume base while high-efficiency modules gain share at the steepest rate.
End User:
Customer scale determines warranty structures, financing terms, and the feasibility of direct manufacturer relationships versus distributor intermediation.
- Residential:Rooftop installations favor 60-cell formats under 400W to accommodate structural load limits and inverter compatibility. China's Jiangsu province leads volume through distributed generation policies incentivizing self-consumption.
- Commercial:Behind-the-meter solar for manufacturing facilities and logistics centers drives 400-500W module procurement with 25-year performance guarantees. India's commercial and industrial consumers in Maharashtra bypass state utilities through open access regulations.
- Industrial:Captive power requirements for energy-intensive manufacturing favor high-wattage bifacial arrays with direct offtake contracting.
- Utility:Independent power producers negotiate frame specifications and cell binning tolerances directly with engineering teams for projects exceeding 100MW.
Utility procurement commands the largest transaction values while residential installations expand most quickly through distributed generation incentives.
Installation Method:
Mounting configuration dictates module construction—framed versus frameless, glass-backsheet versus dual-glass—and associated logistics costs.
- Ground-Mounted:Fixed-tilt and tracking systems accommodate 78-cell high-wattage formats exceeding 600W. Deployment concentrates in India's Rajasthan ultra-mega solar parks where single-axis trackers maximize bifacial gain.
- Roof-Mounted:Ballasted and penetrating systems require lighter framed modules with distributed load characteristics. China's Shandong distributed solar program mandates rapid shutdown compliance for rooftop fire safety.
- Building-Integrated:Curtain-wall and skylight installations demand custom dimensions, semi-transparency options, and structural glazing compatibility.
- Floating:Humidity-resistant encapsulation and corrosion-proof framing serve reservoir and coastal deployments where water surface cooling enhances performance.
Ground-mounted systems dominate capacity additions while floating solar climbs fastest from minimal base penetration.
Distribution Channel:
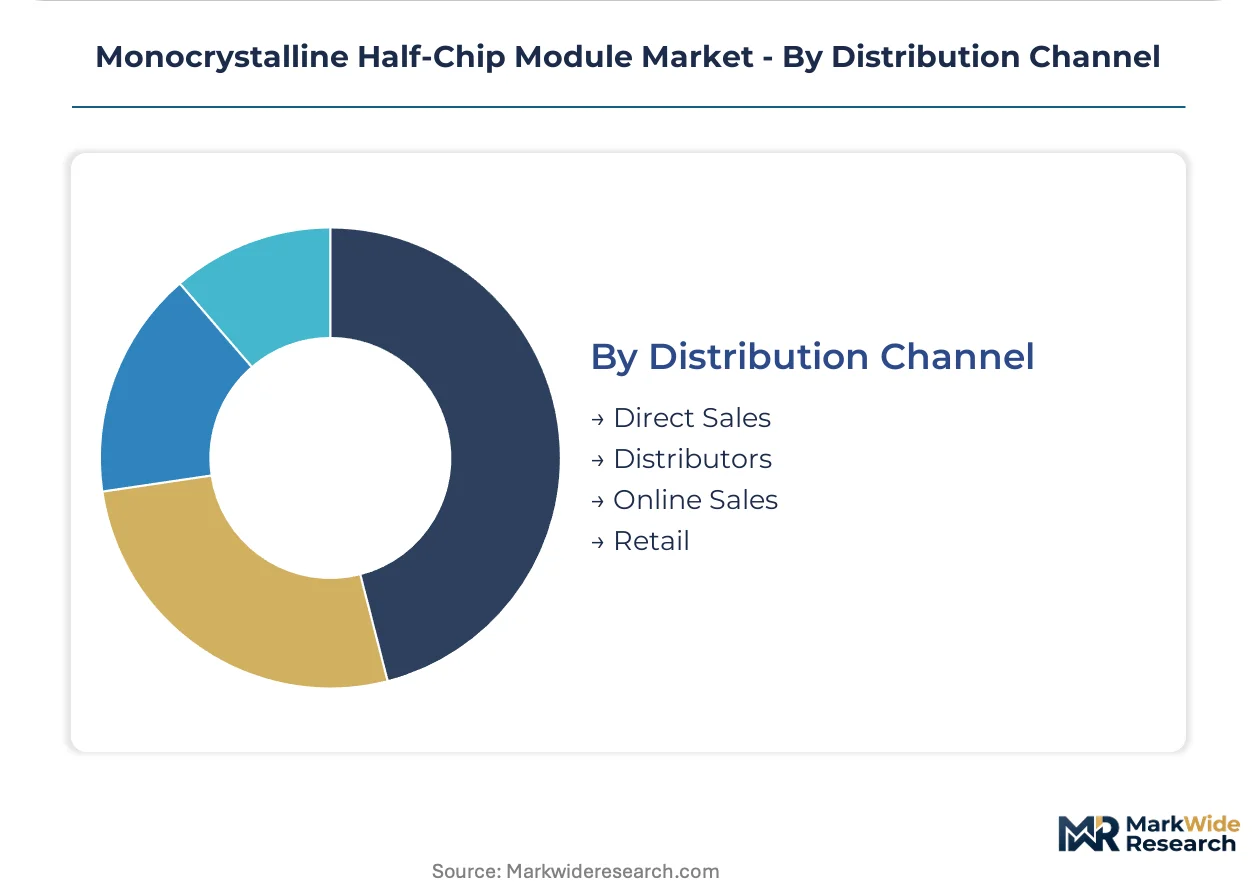
Channel structure reflects project scale, geographic concentration of demand, and the technical complexity of module specification.
- Direct Sales:Manufacturer-to-IPP contracting consolidates procurement for utility-scale developers above 100MW. LONGi and JA Solar maintain dedicated account teams for India's solar park auctions.
- Distributors:Regional wholesalers serve fragmented commercial and residential markets where project scale cannot justify direct engagement.
- Online Sales:Digital procurement platforms aggregate smaller commercial installers seeking transparent pricing and rapid fulfillment.
- Retail:Hardware and electrical supply channels reach residential DIY segments and small contractor networks.
Direct sales capture the highest-value transactions while distributor channels retain volume leadership in fragmented end markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export monocrystalline half-chip modules to utility-scale developers across India, the Middle East, and Southeast Asia, with shipment volumes tracking tender award cycles in destination markets.
China
Domestic utility procurement and export manufacturing concentrate module supply in Jiangsu and Anhui provinces. MIIT's GB/T 9535 certification mandates 200-cycle thermal durability testing that disqualifies legacy full-cell architectures from grid-connected projects. Shandong province's solar park developers now require updated documentation for all module deliveries.
India
Gujarat and Rajasthan host ultra-mega solar parks specifying 545W minimum thresholds for ground-mounted installations. The CEA technical standards prescribe performance ratios that half-cell architectures satisfy more reliably than alternatives. Andhra Pradesh attracts greenfield half-cell line investments through Production-Linked Incentive disbursements for domestic manufacturing.
United States
Utility-scale IPPs reconfigure procurement specifications around 600W-plus module thresholds, compressing contract qualification windows. The IRA manufacturing tax credits incentivize domestic module assembly capacity expansion. Texas and California utility auctions increasingly specify bifacial dual-glass construction for high-albedo installations.
Germany
European utility EPCs specify 9-12 busbar modules for 2025-2026 delivery slots to reduce resistive losses. The EU Green Deal's renewable energy targets accelerate replacement of aging solar fleets with higher-wattage half-chip designs. Bavaria's agricultural regions pilot agrivoltaic dual-use arrays with elevated bifacial mounting configurations.
Australia
Queensland and New South Wales utility-scale projects favor high-wattage monocrystalline designs to minimize balance-of-system costs. The country's national renewable energy regulator enforces module performance standards that align with IEC 61215 sequences. Western Australia's mining sector deploys captive solar with direct manufacturer contracting for projects exceeding 50MW.
Monocrystalline Half-Chip Module Market Competitive Landscape
Listed leaders compete with private specialists across capital access and manufacturing scale. The vendor base concentrates around integrated wafer-to-module producers and dedicated cell specialists, with tiered positioning based on RMB-denominated financing capacity and polysilicon input security. Three archetypes dominate: state-linked conglomerates with captive polysilicon supply, pure-play module houses with distributed global manufacturing, and emerging n-type cell specialists betting on TOPCon migration. Capacity expansion and backward integration into wafer production represent the dominant competitive moves reshaping cost structures.
Among Chinese-listed manufacturers, LONGi Green Energy and JA Solar Technology exemplify the integrated archetype, while JinkoSolar occupies a position bridging scale and technology transition. These three companies represent contrasting approaches to n-type cell migration and utility-direct contracting strategies.
| Leading Market Players |
|---|
| LONGi Green Energy |
| Trinasolar |
| JA Solar Technology |
| JinkoSolar |
| Canadian Solar |
| Tongwei Solar |
| TCL Zhonghuan |
| Hanwha Q CELLS |
| Risen Energy |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracting between module manufacturers and independent power producers locks in polysilicon supply access while providing price visibility across multi-year procurement cycles. China's MIIT-administered GB/T 9535 certification requirements and India's CEA technical standards create compliance cost layers that concentrate pricing power with integrated wafer-to-module producers.
Pricing Analysis
The n-type TOPCon-to-p-type PERC pricing gap compresses legacy margins while premium efficiency tiers command sustained premiums. Project-based contracting dominates utility-scale procurement, with price differentiation resting on certification tier and volume scale rather than brand alone. Cost compression in standard 540-600W modules intensifies as Chinese manufacturers expand n-type capacity. Residential rooftop installers exhibit highest price sensitivity due to inverter compatibility constraints and structural load limits.
Supply Chain Analysis
Port congestion along Shanghai-to-Mundra trade lanes elevates inbound logistics costs for Indian solar park developers sourcing from Jiangsu and Anhui manufacturing clusters. Supply concentrates in China, with secondary wafer processing in Vietnam and Malaysia diversifying tariff exposure. Polysilicon purification in Xinjiang and Inner Mongolia, silver paste metallization, and dual-glass encapsulation materials constitute critical input dependencies. Single-source vulnerability in metallurgical-grade silicon feedstock poses structural risk. Distribution runs through direct manufacturer-to-IPP channels for utility-scale projects above 100MW, with regional wholesalers serving fragmented commercial and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The monocrystalline half-chip module market is cycling through a capacity-led recovery as n-type TOPCon migration displaces legacy p-type architectures and procurement specifications reset around 600W-plus thresholds.
For Market Incumbents: Fortify captive polysilicon supply through backward integration into wafer production or long-term metallurgical-grade silicon offtake agreements. Accelerate GB/T 9535 and IEC 61215/61730 certification refresh cycles to disqualify import competition from grid-connected tenders. Defensive capacity positioning in Andhra Pradesh and Tamil Nadu leverages India's PLI scheme disbursements to anchor domestic manufacturing presence against emerging n-type specialists.
For New Entrants and Emerging Players: CEA technical standards fast-track offers qualification pathway for half-cell architectures satisfying India's performance ratio mandates in Gujarat and Rajasthan solar parks. Target building-integrated photovoltaics segments where semi-transparent and colored module variants command aesthetic premiums with limited incumbent specialization. Agrivoltaic dual-use arrays in water-stressed agricultural regions present white-space deployment with elevated mounting configurations favoring bifacial half-chip designs.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated wafer-to-module producers with secured polysilicon input and active n-type TOPCon migration programs. The five-to-ten year viability window favors manufacturers with RMB-denominated financing capacity and direct utility contracting relationships. Monitor silver paste cost trajectories and glass-glass logistics penalties as margin inflection indicators for bifacial penetration rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wafer Production | Captive polysilicon supply from Xinjiang and Inner Mongolia insulates margin pressure from feedstock volatility. |
| N-type TOPCon Capacity Expansion | Tunnel oxide passivated contact migration breaches 22.5% module efficiency thresholds demanded by MIIT's updated GB standards. |
| Direct IPP Contracting Bypass | Manufacturer-to-utility negotiation for 100MW-plus projects compresses distributor margins and consolidates procurement channels. |
| Dual-Glass Bifacial Certification | Dual-glass construction qualification for Rajasthan and Gujarat solar parks captures rear-side irradiance in high-albedo installations. |
| Agrivoltaic System Partnership | Elevated mounting configurations with bifacial half-chip modules enable simultaneous crop cultivation in water-stressed regions. |
Research Methodology
A spread of perspectives from IPP project developers, EPC contractors, module manufacturing executives, and grid operators converged on the working assumptions shaping this analysis. Primary field engagement combined with secondary validation from IEC certification databases, MIIT GB standard documentation, CEA technical circulars, and customs trade records. Bottom-up cell and module production estimates triangulated against top-down solar capacity installation forecasts across the analysis window.
Segmentation dimensions modeled span product type, end user scale, installation method, and distribution channel structure throughout the forecast period. CAGRs derive from fitted growth curves calibrated to tender award cycles, manufacturing capacity expansion timelines, and regulatory threshold implementations. Forecast inputs incorporate polysilicon price trajectories, silver paste consumption rates per watt, and logistics cost indices for glass-glass module transport.
Decision-makers should treat outputs as directional under assumptions of sustained n-type migration, stable GB/T 9535 enforcement, and continued PLI scheme disbursements; material deviation would warrant model refresh. Polysilicon purification bottlenecks, cross-border certification stacking delays, and albedo condition variability in ground-mounted installations constitute specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
Global Precision Parts Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
Multi-Chip Module (MCM) Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
COF (Chip-On-Film) Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
Metal-Semiconductor-Metal Photodetector Market
Semiconductor Devices
China Semiconductor Device Market
Semiconductor Devices
Power Transistor Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
China MLCC Market
Semiconductor Devices
Global Vacuum Capacitors Market
Semiconductor Devices
Japan Semiconductor Device in Consumer Industry Market
Semiconductor Devices
AIN DBC Ceramic Substrate Market