
 Polymethylhydrosiloxane Market | 2026-2036
Polymethylhydrosiloxane Market Size, Share, and Industry Trends Forecast 2026-2036
Polymethylhydrosiloxane Market Intelligence
Technical service contracts for hydrosilylation process optimization is broadening what buyers procure alongside base resin volumes. Wacker leverages its integrated siloxane chain from quartz to formulated intermediates to sustain European supply security for automotive sealant producers. Shin-Etsu Chemical anchors Asian electronics demand through captive production of high-purity grades in Niigata Prefecture. Dow competes on specification breadth across North American construction and aerospace formulators.
Polymethylhydrosiloxane is a linear organosilicon polymer bearing Si-H functional groups along its backbone, typically manufactured via acid-catalyzed hydrolysis of methyldichlorosilane with controlled condensation to achieve viscosities between 10 and 1000 cSt. Its primary commercial purpose is as a crosslinking agent and reducing intermediate in platinum-catalyzed addition reactions that cure silicone elastomers and modify mineral surfaces. The coatings segment within product type leads volume absorption due to hydrophobic treatment requirements in architectural and industrial finishes. Electronics application categories concentrate margin pools where semiconductor-grade purity commands specification premiums over construction-grade material. Liquid form dominates shipment volumes for ease of metering in continuous compounding operations, though paste consistency grows in medical-grade sealant niches.
EPA oversight of volatile siloxane emissions under the Toxic Substances Control Act constrains formulation choices for US-based adhesive producers. ECHA REACH Annex XVII restrictions on residual chlorosilane content shape import specifications for European compounders sourcing from Asian manufacturers. China's MEE enforcement of dual carbon goals pressures domestic producers toward closed-loop hydrochloric acid recovery in siloxane synthesis. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration investments with regional demand trajectories.
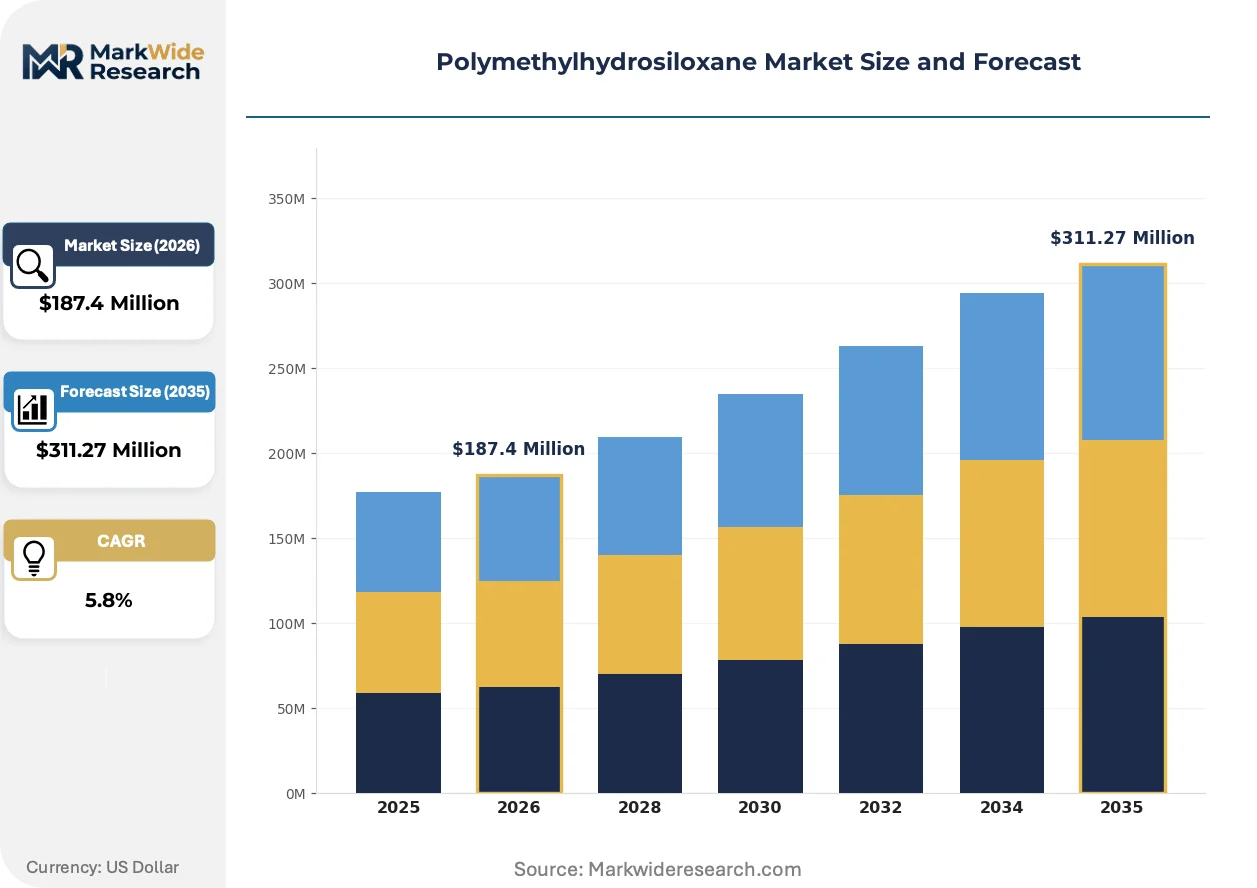
Market Dynamics
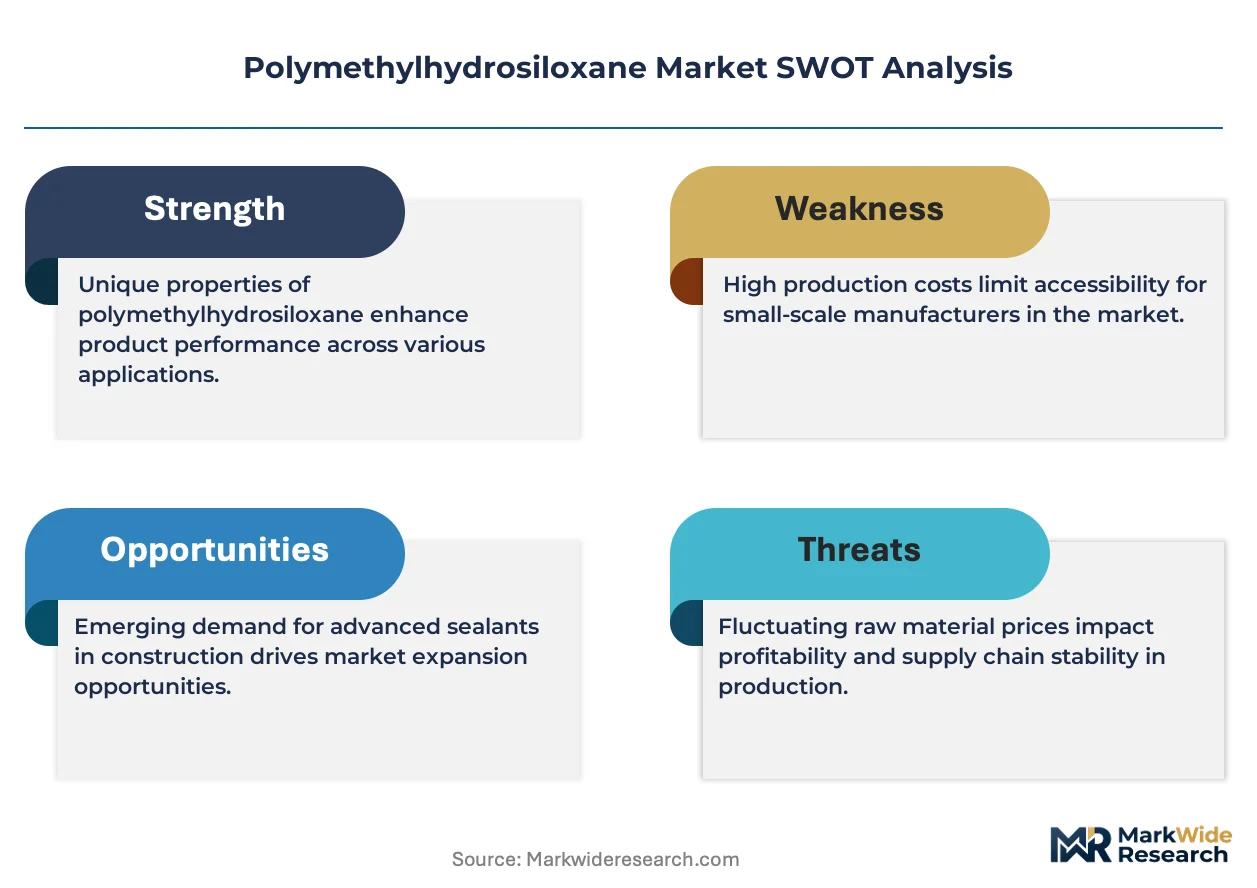
Platinum catalyst cost volatility and tightening purity mandates for electronics-grade material are compressing margin structures while forcing formulators toward long-term technical service partnerships with resin suppliers.
Growth Catalysts
- Automotive lightweighting mandates:Sealant producers in Germany and the United States consume hydrosilylation-cured elastomers for battery pack thermal management, expanding specification volumes for low-viscosity grades.
- REACH Annex XVII enforcement:ECHA restrictions on residual chlorosilanes in European imports drive demand for certified high-purity material from integrated siloxane producers with captive distillation capabilities.
- Semiconductor packaging expansion:Advanced flip-chip underfill applications require hydride-functional fluids with sub-ppm metallic contamination, pulling premium-grade consumption in Japan and South Korea.
Market Restraints
- Methyldichlorosilane feedstock concentration:Chinese producers control over 60 percent of global chlorosilane capacity, exposing non-integrated compounders to export quota volatility and freight cost spikes.
- Platinum group metal exposure:Hydrosilylation cure chemistry requires platinum catalyst loadings that track London Metal Exchange pricing, compressing formulation margins during commodity rallies.
- Fluorosilicone substitution in aerospace:Fuel-resistant sealant specifications in commercial aviation increasingly specify fluorinated elastomers over standard silicone hydride systems for tank access panel applications.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and mobile device assembly create first-mover positioning for high-purity PMHS suppliers establishing local blending operations.
- Closed-loop HCl recovery systems:China's MEE enforcement of dual carbon goals rewards domestic siloxane producers with carbon credit eligibility, creating regulatory arbitrage for low-carbon-intensity imports.
- Medical-grade paste consistency:Implantable device manufacturers in Switzerland and the United States specify thixotropic hydride resins for injection-molded seals, commanding triple-digit premiums over liquid construction grades.
Industry Challenges
- Semiconductor-grade contamination control:Metallic ion specifications below 10 ppb require dedicated production trains and analytical capabilities that mid-scale producers lack capital to replicate.
- Multi-jurisdiction registration timelines:Staggered EPA TSCA, ECHA REACH, and NMPA new chemical notification cycles delay market entry by 18-24 months for novel hydride-functional copolymers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymethylhydrosiloxane Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Adhesives, Sealants, Elastomers Application: Automotive, Electronics, Personal Care, Construction End Use Industry: Aerospace, Healthcare, Agriculture, Manufacturing Form: Liquid, Paste, Gel, Solid |
| Companies Covered | Wacker, KCC Basildon, Bluestar, Wynca, Hengyecheng, Dow, Shin-Etsu Chemical, Dongyue Chem, Momentive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymethylhydrosiloxane Market Strategic Shifts & Innovations
Process intensification in siloxane synthesis and digital specification management are compressing development cycles while fragmenting procurement patterns across construction and electronics verticals.
Continuous flow hydrosilylation reactor technology is consolidating batch-process capacity in European and Japanese manufacturing footprints. Automotive sealant formulators in Germany adopt these systems to reduce catalyst inventory and improve lot-to-lot consistency. The technology is consolidating regional supply positions by raising minimum efficient scale thresholds for new entrants.
ECHA REACH restriction proposals on cyclic siloxane emissions are tightening residual D4/D5 limits in cosmetic and personal care adjacent applications. European compounders reformulate away from traditional equilibrium polymerization routes toward anionic ring-opening processes that reduce cyclic content. Coatings segment buyers in Italy and France now require certificates of analysis documenting sub-1000 ppm cyclics.
Specification-driven procurement now dominates electronics-grade material sourcing, displacing spot-market purchasing for volumes above 50 metric tons annually. Semiconductor packaging houses in Taiwan and South Korea negotiate eighteen-month fixed-price contracts with technical service riders. This pattern concentrates purchasing power among the top five global electronics assemblers.
Polymethylhydrosiloxane Market Segmentation
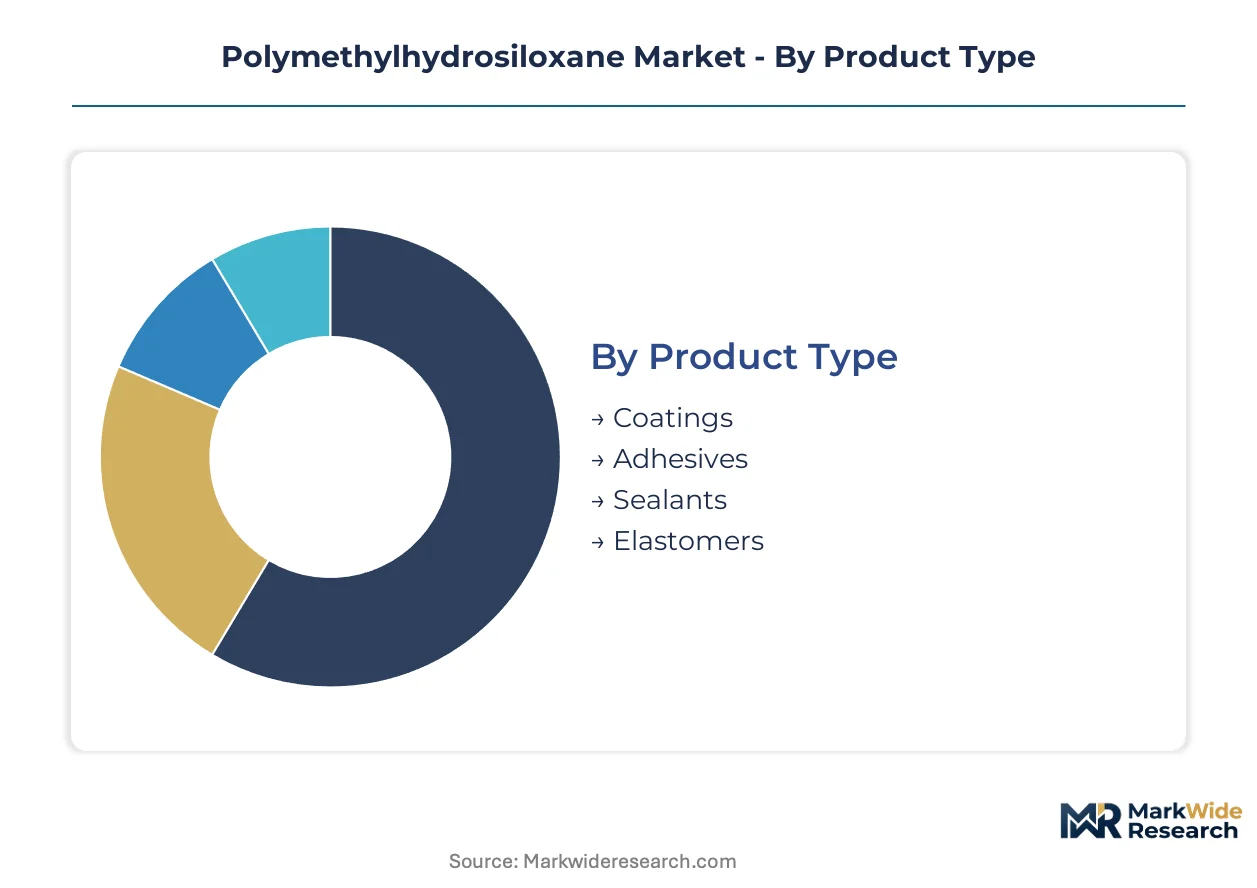
Segmentation in polymethylhydrosiloxane markets reflects divergent purity mandates and formulation requirements across end-use verticals. Electronics-grade specifications command sub-ppm metallic contamination thresholds while construction applications tolerate broader compositional ranges, creating tiered procurement patterns.
Product Type:
Coatings formulations require REACH Annex XVII compliance for residual chlorosilane limits, while elastomers face EPA TSCA scrutiny on volatile siloxane emissions in US-bound shipments.
- Coatings:Architectural and industrial hydrophobic surface treatments absorb the largest volume share of low-to-medium viscosity grades. German and Italian coatings manufacturers now mandate certificates of analysis documenting sub-1000 ppm cyclic siloxane content under tightening ECHA proposals. Leading the category by volume: Coatings. Growing fastest: Elastomers.
- Elastomers:Hydrosilylation-cured silicone rubber systems for automotive battery pack thermal management and industrial molding applications. Demand concentrates in German automotive sealant producers and Japanese electronics assemblers seeking platinum-catalyzed cure consistency with low compression set.
- Adhesives:Bonding intermediates for electronics assembly and construction panel lamination.
- Sealants:Caulking and joint-fill compounds for building envelope and transportation applications.
Margin structures compress from coatings through sealants as specification stringency decreases and spot-market purchasing displaces contract volumes.
Application:
Customer procurement patterns split between semiconductor packaging houses negotiating eighteen-month technical service contracts and construction formulators purchasing on quarterly price agreements.
- Electronics:Advanced flip-chip underfill and semiconductor potting compounds requiring hydride-functional fluids with metallic ion specifications below 10 ppb. Taiwan and South Korean packaging houses concentrate premium-grade consumption through fixed-price contracts with technical service riders.
- Automotive:Battery thermal management sealants and lightweighting adhesives for electric vehicle platforms. German and US automakers specify low-viscosity grades for automated dispensing lines in powertrain assembly plants.
- Construction:Building envelope waterproofing and structural glazing applications.
- Personal Care:Cosmetic-grade formulations with restricted cyclic siloxane content adjacent to ECHA-regulated product categories.
Electronics commands the steepest specification premiums; construction maintains the largest absolute tonnage offtake.
End Use Industry:
Regulatory jurisdiction determines viable supplier pools, with aerospace requiring FAA-compliant material traceability and healthcare demanding FDA or Swissmedic certification for implantable device applications.
- Healthcare:Implantable device manufacturers in Switzerland and the United States specify thixotropic hydride resins for injection-molded seals. Swissmedic and FDA quality system regulations command triple-digit premiums over liquid construction grades for paste-consistency medical formulations.
- Aerospace:Fuel-resistant sealant specifications in commercial aviation increasingly favor fluorinated systems for tank access panels, displacing standard silicone hydride chemistries in select applications.
- Manufacturing:General industrial compounding and mold-making across automotive supplier tiers.
- Agriculture:Silicone surfactant intermediates for agrochemical formulation.
Healthcare exhibits the most rigorous certification burden; manufacturing dominates shipment volumes through distributed construction and automotive supply chains.
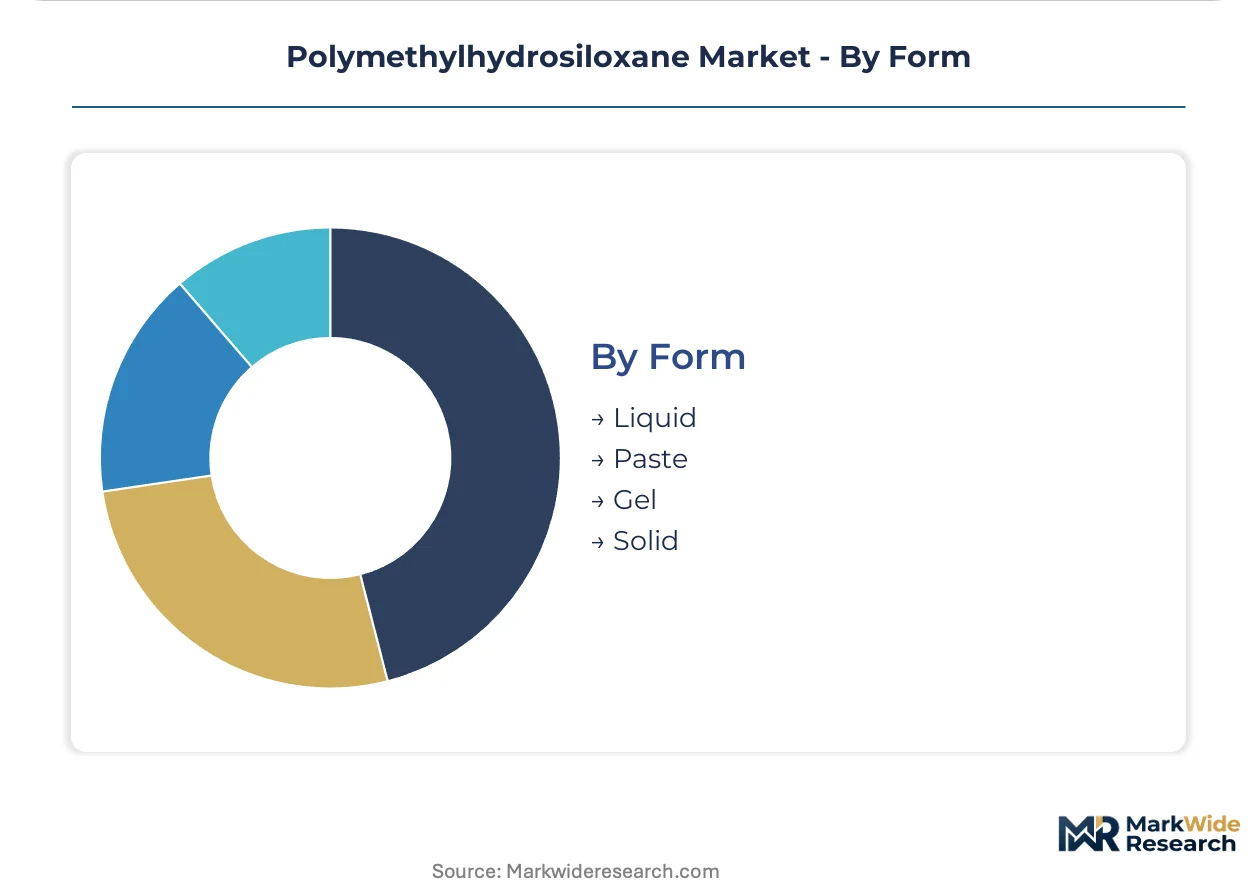
Form:
Processing equipment compatibility and metering precision requirements differentiate liquid and paste procurement, with medical device manufacturers investing in thixotropic handling systems unavailable to construction compounders.
- Liquid:Viscosities between 10 and 1000 cSt dominate shipment volumes for continuous compounding operations in coatings and electronics assembly. Ease of metering in automated dispensing equipment sustains liquid preference across German automotive and Taiwanese semiconductor packaging facilities.
- Paste:Thixotropic consistency grades for medical-grade sealant niches and vertical surface applications requiring non-sag properties.
- Gel:Soft, compliant formulations for cushioning and damping applications in electronics and healthcare.
- Solid:Masterbatch and pelletized forms for thermoplastic silicone blending operations.
Liquid form leads all categories by tonnage; paste commands the highest unit value through medical certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures over sixty percent of global chlorosilane feedstock yet consumes substantial volumes domestically for electronics and construction sealants. Germany and the United States import certified grades for automotive and aerospace specifications. Japan and South Korea concentrate semiconductor-grade demand through dedicated supply contracts.
China
Domestic electronics assemblers in Shenzhen and Dongguan pull high-purity hydride fluids for flip-chip packaging. The Ministry of Ecology and Environment enforces dual carbon goals that pressure siloxane producers toward closed-loop hydrochloric acid recovery. Yangtze River Delta chemical parks host integrated manufacturing clusters serving both domestic coatings compounders and export markets.
Germany
Automotive sealant producers in Stuttgart and Munich specify low-viscosity grades for battery thermal management in electric vehicle platforms. ECHA REACH Annex XVII restrictions on residual chlorosilanes shape import specifications toward certified high-purity material. Bavarian industrial corridors sustain demand through captive consumption by integrated silicone formulators supplying European OEMs.
United States
Construction and aerospace formulators in Texas and Michigan consume specification-broad material for structural glazing and fuel-resistant applications. EPA oversight under the Toxic Substances Control Act constrains formulation choices for adhesive producers regarding volatile siloxane emissions. Gulf Coast petrochemical corridors host blending operations serving North American automotive and electronics supply chains.
Japan
Semiconductor packaging houses in Niigata Prefecture anchor Asian demand for sub-ppm metallic contamination grades. METI industrial standards guide purity benchmarks for hydride-functional fluids in advanced electronics applications. Kanto region chemical producers maintain dedicated production trains for electronics-grade material with analytical capabilities exceeding mid-scale competitors.
South Korea
Memory and logic chip manufacturers in Gyeonggi Province negotiate eighteen-month fixed-price contracts with technical service riders. The Ministry of Food and Drug Safety and national chemical regulators align import specifications with semiconductor industry requirements. Busan-Ulsan industrial zones concentrate demand through packaging houses serving global electronics assemblers.
Polymethylhydrosiloxane Market Key Industry Players
Capital-heavy producers compete with asset-light designers across distinct capability tiers in polymethylhydrosiloxane supply. Integrated siloxane manufacturers with captive chlorosilane supply dominate premium-grade segments while specialty distributors serve construction and personal care formulators with broader specification tolerance. Three archetypes define competitive positioning: quartz-to-silicone integrated producers, regional compounders with formulation expertise, and import-dependent distributors serving price-sensitive coatings markets. Capacity expansion and technical service partnerships represent the dominant competitive moves as margin compression forces collaboration over spot-market rivalry.
Among integrated producers with upstream siloxane control, Wacker, Shin-Etsu Chemical, and Dow exemplify archetypes spanning European, Japanese, and North American supply bases. Wacker occupies a position within German automotive sealant supply chains through captive distillation capabilities. Shin-Etsu Chemical anchors Asian electronics demand through Niigata-based production of certified high-purity grades. Dow represents North American specification breadth across construction and aerospace verticals with formulation support infrastructure. These three entities illustrate how geographic production clustering aligns with regional end-use concentration rather than global undifferentiated supply.
| Leading Market Players |
|---|
| Wacker |
| KCC Basildon |
| Bluestar |
| Wynca |
| Hengyecheng |
| Dow |
| Shin-Etsu Chemical |
| Dongyue Chem |
| Momentive |
| Others |
Cost & Logistics Intelligence
Specialized hydrosilylation engineers concentrated in Germany's Bavarian chemical corridor and Japan's Niigata Prefecture create labor-cost differentials that widen pricing-tier spreads between electronics-grade certification and construction-grade commodity material. Platinum catalyst inventory carrying costs and REACH compliance certification burdens compound these spreads as formulators negotiate specification premiums.
Pricing Analysis
Cost-down pressure on mid-viscosity construction grades accelerates because Chinese chlorosilane producers leverage captive feedstock economics to undercut integrated European suppliers. Three-tier pricing structure across electronics-grade, automotive-certified, and construction-standard levels separates sub-ppm metallic purity from REACH Annex XVII compliance from basic hydrolysis-grade material. Specification-driven procurement in Taiwanese semiconductor packaging houses exhibits the lowest price sensitivity, while Italian coatings compounders purchasing on quarterly agreements show acute responsiveness to spot chlorosilane fluctuations.
Supply Chain Analysis
Single-source vulnerability sits with Chinese methyldichlorosilane capacity that feeds over sixty percent of global siloxane synthesis. Production draws from quartz mining clusters in Jiangxi Province, chlorine-alkali operations along the Yangtze River, and platinum catalyst supply anchored in South African refining. Tariff exposure on US-bound shipments of residual chlorosilane-containing material constrains sourcing flexibility under EPA TSCA scrutiny. Distribution runs through regional blending hubs in Germany's industrial corridors, Texas Gulf Coast petrochemical complexes, and Kanto region chemical parks serving just-in-time electronics assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous flow reactor technology is displacing batch-process hydrosilylation systems, compressing development cycles and raising minimum efficient scale thresholds that favor capital-rich incumbents over regional compounders.
For Market Incumbents: Deploy captive distillation capabilities to defend margin position against Chinese feedstock-integrated competitors flooding construction-grade segments. Expand technical service contracts with German automotive sealant producers to lock in eighteen-month offtake agreements before platinum volatility reshapes procurement patterns. Prioritize carbon credit eligibility under China's MEE dual carbon enforcement to capture regulatory arbitrage on low-carbon-intensity exports. For New Entrants and Emerging Players: Modular continuous flow reactor designs offer entry pathways without batch-process capital burdens. Target India's PLI-subsidized electronics manufacturing zones for first-mover positioning in high-purity blending operations ahead of semiconductor packaging demand maturation. Pursue medical-grade paste consistency certification through Swissmedic and FDA pathways to capture triple-digit premiums unavailable in liquid construction segments. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale regional compounders possessing formulation expertise but lacking upstream siloxane integration, given consolidation pressure from Wacker and Shin-Etsu capacity expansions. Long-term viability hinges on technical service bundling capabilities rather than commodity resin volumes. Watch for ECHA REACH restriction proposals on cyclic siloxane emissions as the inflection signal that accelerates anionic ring-opening process adoption and stranded batch capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Feedstock | Captive methyldichlorosilane supply insulates Wacker and Shin-Etsu from Chinese export quota volatility. |
| Continuous Flow Reactor Deployment | German automotive sealant formulators reduce catalyst inventory and improve lot-to-lot consistency through intensified processing. |
| Medical-Grade Paste Certification | Swissmedic and FDA quality system compliance commands triple-digit premiums over liquid construction grades for implantable device applications. |
| Closed-Loop HCl Recovery Systems | China's MEE dual carbon enforcement rewards domestic producers with carbon credit eligibility and regulatory arbitrage positioning. |
| Technical Service Contract Expansion | Taiwanese and South Korean semiconductor packaging houses concentrate purchasing power through eighteen-month fixed-price agreements with service riders. |
Research Approach
Document review covered ECHA REACH restriction proposals, EPA TSCA enforcement guidance, and SEC filings from integrated siloxane producers, complemented by interviews with plant managers at German automotive sealant compounders, procurement leads at Taiwanese electronics assemblers, and technical R&D directors at Japanese chemical producers. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, and METI industrial standards documentation. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments.
Segment-level value outputs across the projection horizon reflect modeled interactions between grade tier, end-use industry, and regional production hub configurations. The analytical framework incorporated platinum group metal price volatility, REACH Annex XVII compliance cost trajectories, and electronics-grade purity specification evolution as industry-specific forecast inputs. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization assumptions.
Several conditions sit outside the modeled scope, including abrupt regulatory divergence between EPA, ECHA, and NMPA notification cycles, and unanticipated fluorosilicone substitution rates in aerospace fuel-resistant applications. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Polysilicon Market
Semiconductor Material
Yttrium Oxide Market
Semiconductor Material
Global Strontium Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
Cadmium Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Global Semiconductor Microelectronics Materials Market
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
Semiconductor Glass Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market