
 Electronic Film Market | 2026-2036
Electronic Film Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Film Market Foresight
Multi-source procurement for high-performance polymer substrates is decoupling from traditional captive supply arrangements in the Electronic Film Market. Toray Industries leverages its polyester film expertise to anchor display supply chains across East Asia. DuPont sustains technology leadership in polyimide formulations for flexible circuit applications. Saint-Gobain competes through specialized glass film products serving sensor and photovoltaic segments.
Electronic film denotes thin-layer materials engineered with controlled thickness tolerances, dielectric constants, and optical transmittance properties for electrical insulation, signal transmission, or environmental protection in device assemblies. These films are manufactured through extrusion, sputtering, or chemical vapor deposition processes to achieve sub-micron precision required by semiconductor and display fabrication. Polymer film dominates current volume due to its processability in roll-to-roll manufacturing for flexible electronics, while glass film commands premium positioning in applications demanding thermal stability and hermetic sealing. Thin film technology leads growth trajectory as device miniaturization intensifies requirements for precisely deposited functional layers.
The EPA regulates per- and polyfluoroalkyl substance emissions affecting fluoropolymer film manufacturing in the United States. REACH restricts hazardous substance content in electronic films sold across European Union member states, compelling reformulation of certain adhesive and coating chemistries. Japan's METI promotes domestic advanced materials capabilities through standards alignment with IEC specifications for electronic component reliability. Stakeholders must monitor evolving substance restrictions and qualification protocols to maintain market access across major manufacturing destinations.
Market Dynamics
Polymer-based barrier film procurement is decoupling from traditional captive supply arrangements as flexible display manufacturers in South Korea and China diversify sourcing to reduce concentration risk. This structural shift is compressing margins for integrated material suppliers while creating entry points for specialized film converters.
Growth Catalysts
- REACH substance restrictions:Reformulation mandates for adhesive chemistries in European electronic films are accelerating demand for compliant polymer substrates certified through updated qualification protocols.
- Flexible OLED proliferation:Display manufacturers in Seoul and Shenzhen are expanding roll-to-roll processing capacity, driving volume procurement of high-barrier polymer films.
- Photovoltaic integration:Backsheet and encapsulant film demand from solar module assemblers is rising as dual carbon compliance deadlines tighten across East Asian manufacturing clusters.
Market Restraints
- Fluorinated polymer input volatility:The EU F-Gas Regulation is constraining feedstock availability for high-performance electronic substrates, elevating cost structures for barrier film producers dependent on fluoropolymer precursors.
- South Korean supply concentration:Advanced polymer film manufacturing clusters around Seoul and Suwon create geographic vulnerability for display supply chains seeking multi-source qualification.
- Glass film substitution ceiling:Hermetic sealing requirements in sensor and photovoltaic segments limit polymer film penetration despite flexibility advantages, preserving premium positioning for specialized glass substrates.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and display fabrication are attracting barrier film suppliers to establish local conversion capacity near emerging assembly clusters.
- Automotive interior displays:Curved and conformable screen integration in electric vehicle cockpits is creating specification demand for thermoformable polymer films with optical-grade surface finish.
- Japan METI standards alignment:IEC specification harmonization for electronic component reliability is opening qualification pathways for domestic advanced materials producers targeting export markets.
Industry Challenges
- Sub-micron deposition expertise:Chemical vapor deposition and sputtering process engineering talent scarcity constrains capacity expansion for thin film functional layer producers serving semiconductor fabrication.
- Cross-regional certification timelines:Simultaneous EPA emissions compliance, REACH substance registration, and METI reliability qualification create extended product launch cycles for multi-market film formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Film Market |
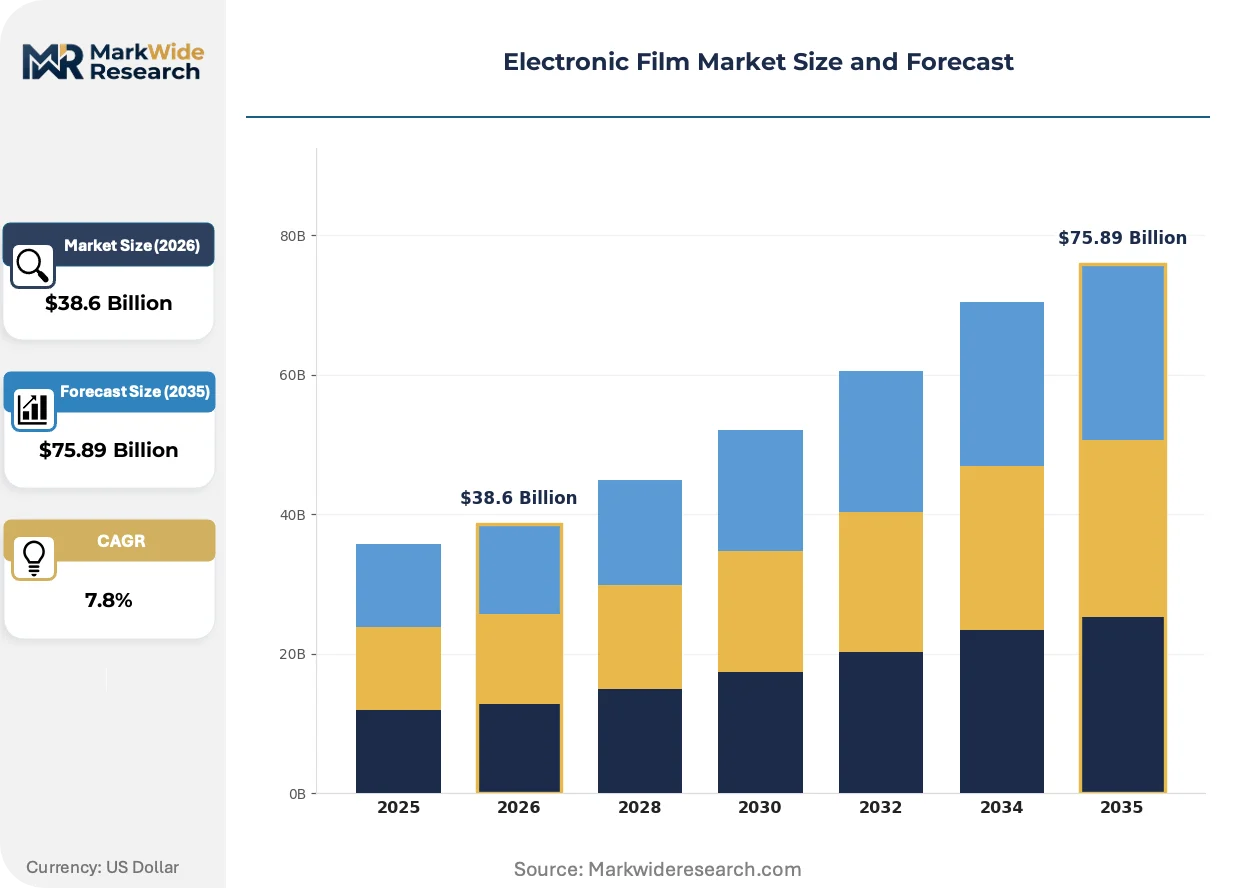
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $75.89 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Film, Glass Film, Metal Film, Composite Film Application: Display, Photovoltaic, Lighting, Sensors End User: Electronics, Automotive, Aerospace, Telecommunications Technology: Flexible Electronics, Organic Electronics, Printed Electronics, Thin Film Technology |
| Companies Covered | 3M, DuPont, Toray Industries, Saint-Gobain, Nitto Denko Corporation, TDK Corporation, Mitsubishi Chemical Holdings Corporation, The Chemours Company, Gunze, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Film Market Shifts & Advancements
Atomic layer deposition barrier technology is reshaping competitive positioning in high-performance electronic films. Material scientists and process engineers are converging on new manufacturing approaches that redefine performance thresholds.
Hybrid organic-inorganic multilayer barrier films are expanding into flexible electronics packaging applications previously served by glass or metal foil encapsulation. Wearable device manufacturers and foldable phone assemblers are adopting these films at accelerated qualification cycles. The technology is expanding into hermetic protection for moisture-sensitive organic semiconductors, compressing the addressable market for rigid encapsulation solutions.
The EPA regulates per- and polyfluoroalkyl substance emissions affecting fluoropolymer film manufacturing in the United States. This regulatory pressure is forcing reformulation of high-barrier substrate chemistries and accelerating migration to alternative polymer systems. Fluoropolymer-dependent segments in aerospace and medical device films are responding through supply chain requalification and extended supplier development timelines.
Display manufacturers are consolidating procurement authority through direct specification of film performance parameters rather than accepting converter-defined grades. Tier-one panel producers in South Korea and China now dictate barrier water vapor transmission rate targets, optical haze limits, and mechanical bend radius requirements directly to polymer resin suppliers and deposition equipment vendors. This pattern is most visible in Shenzhen and Seoul, where vertical integration into display assembly has shifted bargaining power upstream in the film value chain.
Electronic Film Market Segmentation
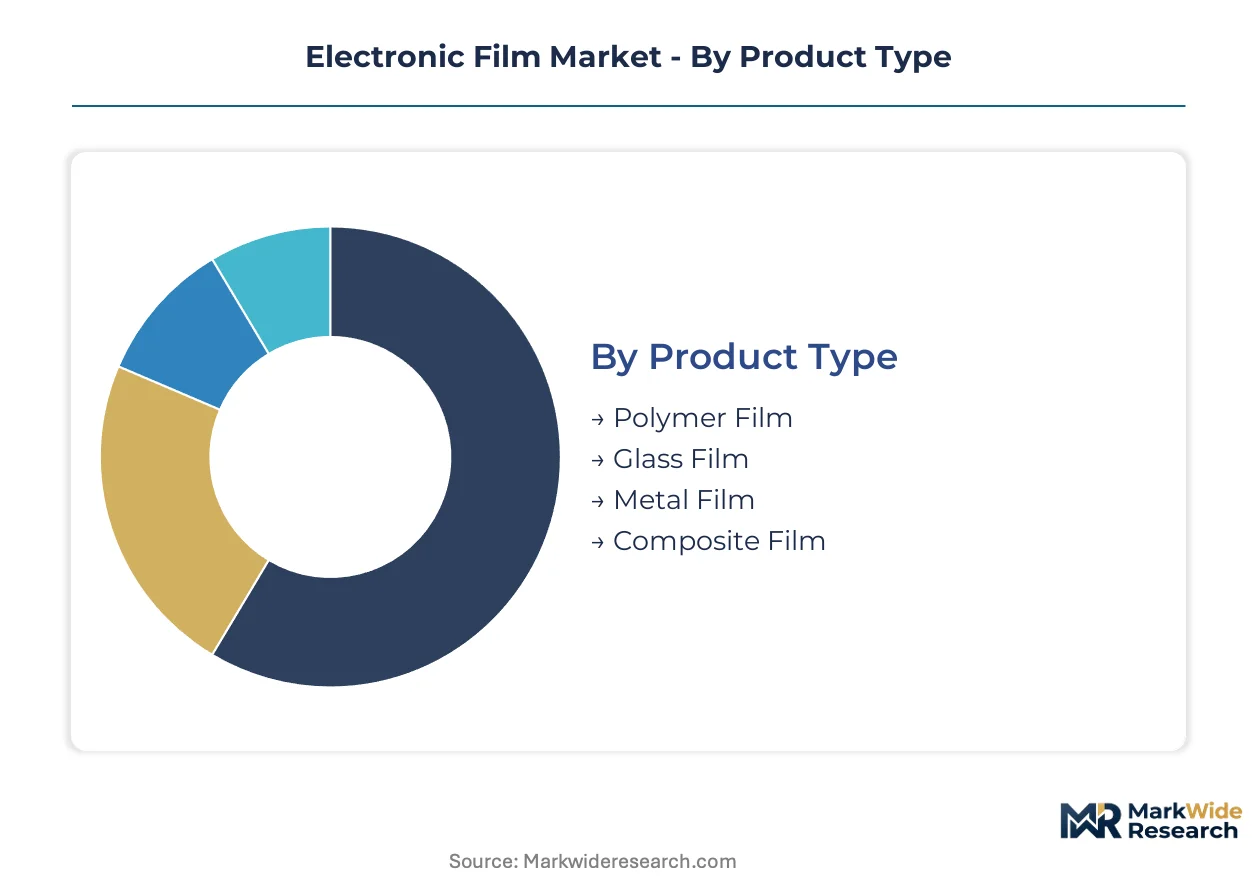
Electronic film manufacturers configure production assets around distinct technical specifications that govern dielectric performance, optical clarity, and barrier properties. Segment boundaries reflect capital allocation decisions between roll-to-roll polymer processing and precision deposition equipment for thin film architectures.
Product Type:
Capital intensity varies sharply across substrate categories, with glass film demanding the heaviest upfront investment in melting and polishing infrastructure.
- Polymer Film:Polyester and polyimide formulations dominate volume through extrusion and biaxial stretching lines optimized for roll-to-roll manufacturing. Seoul-based display assemblers specify water vapor transmission rates below 10⁻⁶ g/m²/day for flexible OLED encapsulation, compressing qualification timelines for barrier-grade suppliers.
- Glass Film:Borosilicate and alkali-free variants require float or fusion draw furnaces exceeding $200 million per production line. Shenzhen sensor manufacturers source chemically strengthened glass for hermetic MEMS packaging where thermal stability above 400°C overrides flexibility requirements.
- Metal Film:Aluminum and copper foils serve electromagnetic shielding and current collection in battery and photovoltaic assemblies.
- Composite Film:Hybrid organic-inorganic multilayers combine polymer substrates with ceramic or metallic functional coatings.
Most installed capacity flows through polymer film. Expansion is steepest in composite film.
Application:
Application segments diverge by specification stringency, with sensor films commanding the tightest thickness tolerances.
- Display:Flexible OLED and quantum dot enhancement films require optical-grade surface finish with haze below 1% and precise refractive index matching. South Korean panel producers in Suwon and Gumi are expanding procurement of thermoformable substrates for curved automotive interior screens.
- Photovoltaic:Backsheet and encapsulant films must withstand 25-year UV exposure and thermal cycling without delamination. East Asian module assemblers near Shanghai and Suzhou are qualifying fluoropolymer-free alternatives under tightening EU F-Gas Regulation constraints.
- Lighting:LED phosphor sheets and light guide plates prioritize luminous efficacy and color uniformity over barrier performance.
- Sensors:Hermetic packaging for pressure, gas, and image sensors demands atomic layer deposition barrier precision.
Display applications absorb the largest share of high-performance film value. Photovoltaic is gaining share fastest as dual carbon compliance deadlines accelerate module deployment.
End User:
End user concentration shapes qualification protocols, with aerospace imposing the lengthiest certification cycles.
- Electronics:Smartphone, tablet, and wearable device assemblers drive specification convergence around bend radius and cyclic fatigue performance. Foldable phone manufacturers in Shenzhen are qualifying films for 200,000+ fold cycles.
- Automotive:Curved cockpit displays and exterior sensor housings require UV-stable substrates with automotive-grade reliability under AEC-Q100 stress testing.
- Aerospace:Satellites and avionics demand radiation-hardened films with outgassing compliance per ASTM E595.
- Telecommunications:5G antenna substrates and base station components prioritize low dielectric loss at millimeter-wave frequencies.
Electronics manufacturers place the largest purchase orders by volume. Automotive is expanding most quickly as electric vehicle interior digitization accelerates.
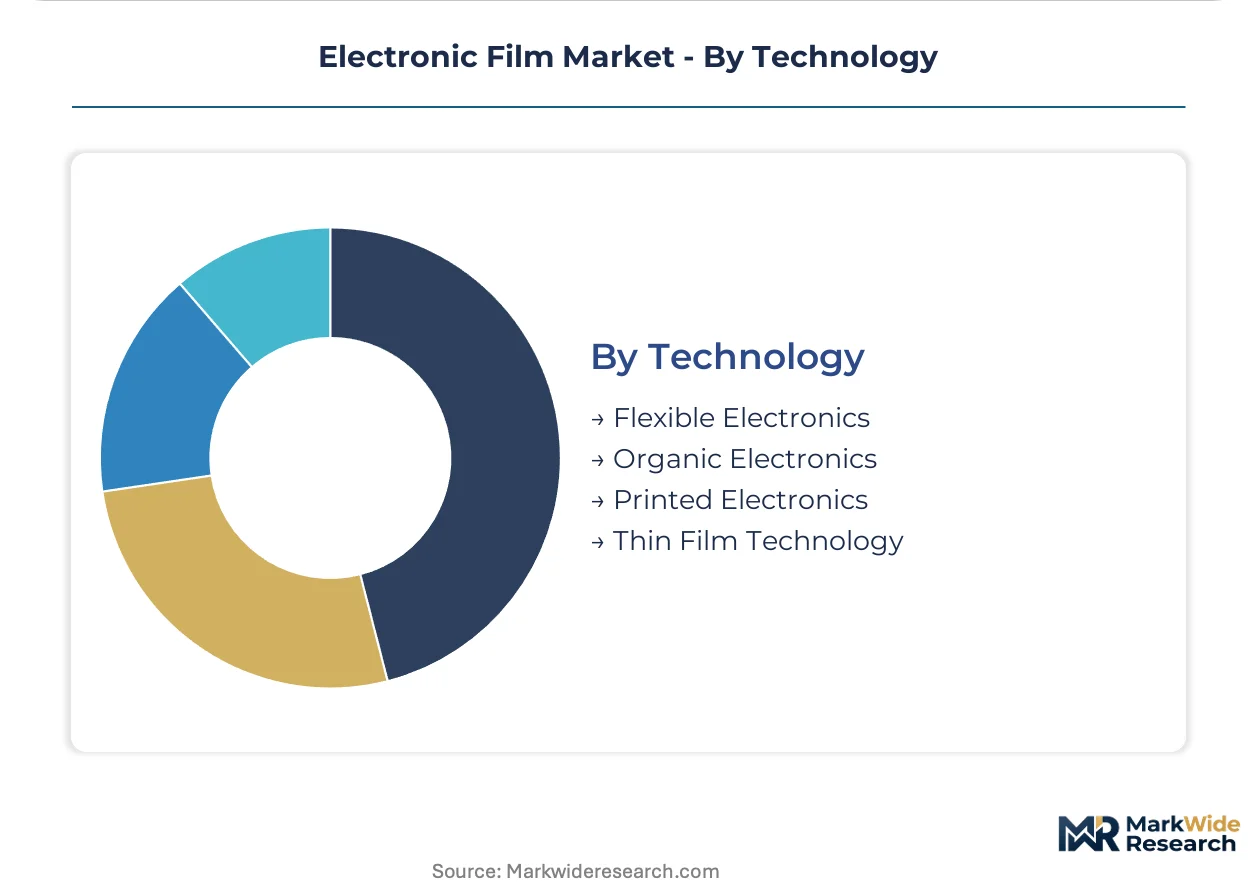
Technology:
Technology segments align with manufacturing process sophistication, with thin film deposition requiring the most specialized equipment.
- Flexible Electronics:Roll-to-roll processing of polymer substrates enables conformable circuits for wearable and foldable applications. Seoul display clusters are integrating in-house film conversion to secure barrier supply.
- Organic Electronics:Solution-processed organic semiconductors demand ultra-high barrier encapsulation to prevent moisture-induced degradation.
- Printed Electronics:Screen and inkjet deposition of conductive traces on film substrates serves cost-sensitive RFID and antenna applications.
- Thin Film Technology:Physical and chemical vapor deposition creates sub-micron functional layers with atomic precision for semiconductor and sensor fabrication.
Flexible electronics commands the broadest installed equipment base. Thin film technology is climbing the fastest as device miniaturization intensifies precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the dominant concentration of flexible display manufacturing, with procurement patterns radiating outward to material suppliers in Japan, China, and Southeast Asia. The Electronic Film Market distributes across three primary manufacturing corridors: East Asian display clusters, North American semiconductor fabrication zones, and European automotive electronics centers.
United States
Domestic semiconductor fabrication expansion drives barrier film demand for advanced packaging applications. EPA regulations on per- and polyfluoroalkyl substance emissions constrain fluoropolymer film production, forcing reformulation of high-performance substrates. Arizona and Texas host emerging fab clusters where material suppliers are establishing qualification laboratories.
South Korea
Suwon and Gumi-based panel producers specify water vapor transmission rates below 10⁻⁶ g/m²/day for flexible OLED encapsulation, compressing supplier timelines. MFDS alignment with IEC reliability standards governs medical device film applications. Seoul Capital Area manufacturers are integrating in-house film conversion to secure barrier supply against geographic concentration risk.
Japan
Domestic advanced materials producers leverage METI-promoted standards alignment to access export markets for electronic component films. Kanto and Kansai regions maintain precision deposition equipment clusters serving semiconductor and sensor fabrication. Nagoya-area automotive electronics assemblers source thermoformable substrates for curved cockpit displays.
China
Shenzhen and Suzhou manufacturing clusters absorb the largest volume of polymer barrier films for smartphone and photovoltaic module assembly. MIIT dual carbon compliance deadlines accelerate fluoropolymer-free backsheet qualification. Shanghai-area display fabs are expanding roll-to-roll processing capacity for foldable device substrates.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify UV-stable films with AEC-Q100 reliability for electric vehicle interior digitization. REACH substance restrictions compel adhesive chemistry reformulation across European electronic film supply chains. Dresden semiconductor fabrication centers source atomic layer deposition barrier precision for sensor packaging.
Electronic Film Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty deposition and hybrid material architectures. The Electronic Film Market structures around three capability tiers: integrated resin-to-film suppliers with captive polymer synthesis, specialized converters focused on barrier performance engineering, and equipment-integrated deposition service providers. Strategic moves concentrate on multi-source qualification partnerships and regional conversion capacity placement near emerging assembly clusters.
Within the integrated materials tier, Toray Industries and DuPont exemplify archetypal positions—Japanese and American chemical conglomerates leveraging polyester and polyimide expertise respectively. Saint-Gobain occupies a distinct specialist position as a European glass film producer serving hermetic sealing applications where thermal stability requirements override flexibility advantages.
| Leading Market Players |
|---|
| 3M |
| DuPont |
| Toray Industries |
| Saint-Gobain |
| Nitto Denko Corporation |
| TDK Corporation |
| Mitsubishi Chemical Holdings Corporation |
| The Chemours Company |
| Gunze |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap Japanese film converters anchor supply discipline through generational capital allocation that resists margin-eroding price wars while maintaining captive resin relationships with Toray and Mitsubishi Chemical. This ownership pattern concentrates pricing power among legacy producers who control polymer-grade certification pathways for Seoul and Shenzhen display assemblers.
Pricing Analysis
Fluoropolymer precursor cost pass-through dominates contract renegotiations as EU F-Gas Regulation constraints tighten feedstock availability. Three-tier pricing structure across barrier-grade, standard optical, and economy packaging levels separates display OEMs from photovoltaic assemblers from commodity converter buyers. Cost compression in barrier-grade tiers is intensifying because South Korean panel producers now specify water vapor transmission rate targets directly to resin suppliers. Photovoltaic module assemblers near Shanghai exhibit highest price sensitivity due to fluoropolymer-free reformulation mandates.
Supply Chain Analysis
Single-source vulnerability sits with Seoul Capital Area deposition equipment clusters serving flexible OLED encapsulation lines. Geographic supply concentration centers on South Korea, Japan, and China for polymer resin synthesis, precision coating equipment, and roll-to-roll conversion capacity. Raw material dependencies rest on high-purity polyester chips, polyimide monomers, and atomic layer deposition precursors. Tariff exposure on Japanese equipment imports into China creates qualification timeline risk for barrier film producers. Distribution runs through converter networks co-located with Shenzhen and Suwon display fab clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
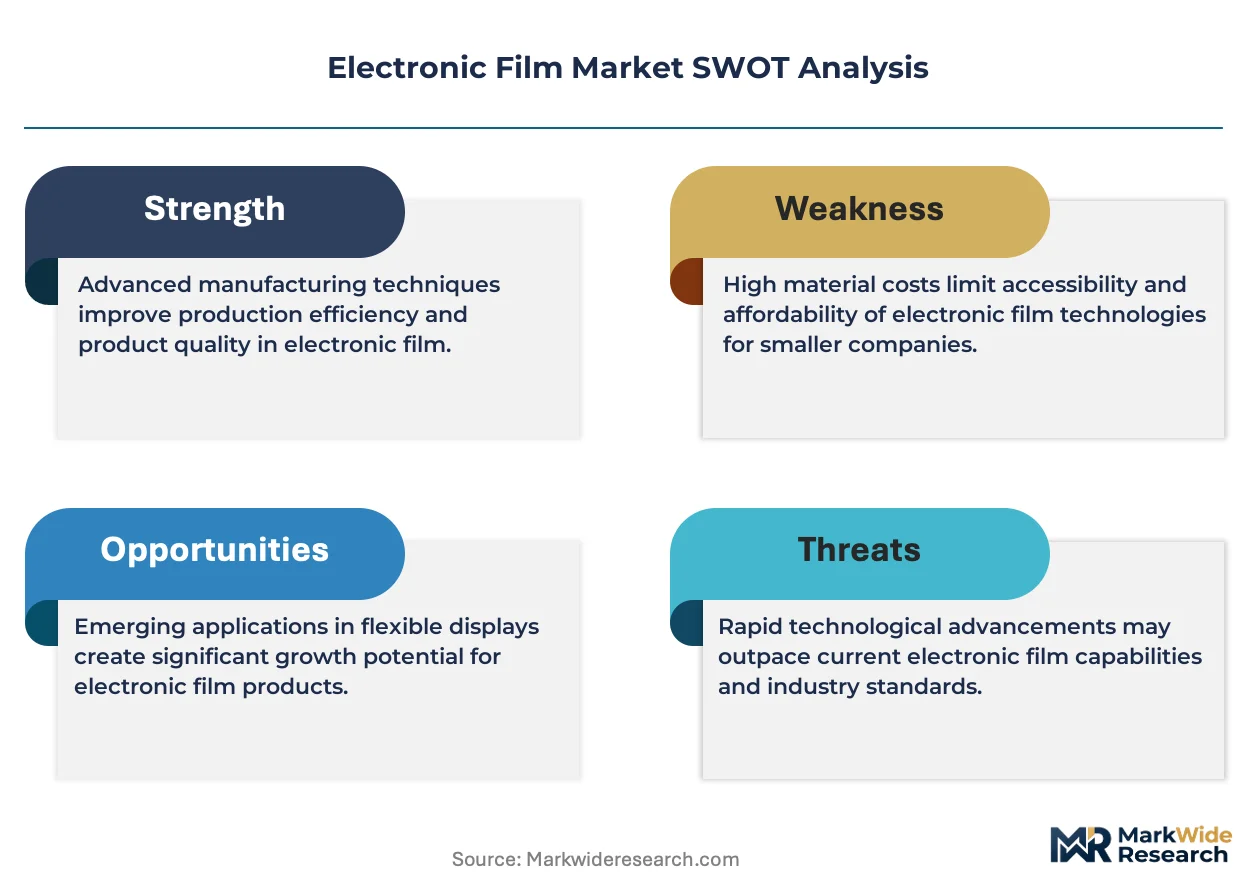
The Electronic Film Market functions as a geographic-arbitrage play where India PLI scheme incentives offset REACH compliance costs burdening European producers, enabling margin capture through regional conversion capacity placement.
For Market Incumbents: Cement barrier-grade certification authority by acquiring atomic layer deposition specialists in Japan's Kanto region before Seoul display producers integrate in-house conversion. Deepen backward integration into polyimide monomer production to defend against DuPont formulation patent pressure. Prioritize AEC-Q100 automotive qualification to capture electric vehicle cockpit display specifications ahead of Chinese converter entrants.
For New Entrants and Emerging Players: Enter via India's semiconductor packaging corridor near Gujarat and Tamil Nadu where PLI subsidies offset capital intensity for barrier film conversion plants. Target photovoltaic backsheet qualification for East Asian module assemblers seeking fluoropolymer-free alternatives under tightening EU F-Gas Regulation. Pursue joint development agreements with Shanghai-area display fabs requiring localized barrier supply.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap Japanese deposition equipment service providers with stranded capacity outside Seoul supply orbits. Long-term viability hinges on atomic layer deposition process expertise scarcity persisting through the next technology cycle. Watch for South Korean panel producer announcements of in-house film conversion as signal of converter margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | DuPont and Toray secure polyimide supply chains against feedstock volatility from fluoropolymer regulation. |
| Atomic Layer Deposition Capacity Expansion | Japanese equipment vendors capture Seoul display producer demand for sub-micron barrier precision. |
| India PLI-Aligned Conversion Facility | Barrier film suppliers establish local presence near Gujarat semiconductor packaging clusters. |
| Fluoropolymer-Free Formulation Partnership | Composite film producers collaborate with Shanghai photovoltaic assemblers on EU-compliant backsheets. |
| AEC-Q100 Automotive Certification Investment | Polymer film converters qualify thermoformable substrates for Bavarian electric vehicle cockpit displays. |
Research Methodology
Coverage spans East Asian display clusters, North American semiconductor fabrication zones, and European automotive electronics centers, with primary inputs from each. The research combines interviews with deposition equipment engineers, barrier film procurement managers at Seoul panel producers, polyimide R&D directors, and photovoltaic module supply chain leads with secondary validation through customs trade data, SEC chemical company filings, and METI advanced materials reports. Bottom-up capacity assessments triangulate against top-down demand modeling from display and photovoltaic shipment data.
Rate-of-change decomposition separates volume growth from mix-shift effects across the projection horizon. The analytical framework models segmentation across polymer, glass, metal, and composite film types; display, photovoltaic, sensor, and lighting applications; electronics, automotive, aerospace, and telecommunications end users; and flexible, organic, printed, and thin film technologies. CAGRs derive from equipment installation timelines, qualification cycle durations, and substitution elasticity between barrier technologies. Industry-specific inputs include water vapor transmission rate specification trajectories from Seoul display producers and fluoropolymer-free reformulation adoption curves under EU F-Gas Regulation.
Inputs from equipment vendors, resin suppliers, and display assemblers were available through the study window; gaps in proprietary atomic layer deposition process parameters introduce uncertainty bands around barrier film cost projections. Forecasts reflect assumptions about qualification timeline compression, regulatory enforcement intensity, and substitution thresholds between polymer and glass substrates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Semiconductor Glass Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
PP Capacitor Films Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
North America Silicone Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
EV Capacitor Films Market
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Tungsten Market
Semiconductor Material
Semiconductor Grade PTFE Market