
 Europium Market | 2026-2036
Europium Market Size, Share, and Industry Trends Forecast 2026-2036
Europium Market Analysis
The gap between high-purity europium for phosphor applications and lower-grade material for commodity glass additives is restructuring supply negotiations and contract structures. China Northern Rare Earth leverages its integrated mining-to-oxide pipeline to dominate technical-grade volumes. Lynas Corporation anchors non-Chinese supply security through its Malaysian processing circuit. Neo Performance Materials specializes in downstream rare-earth formulations for phosphor and magnet customers.
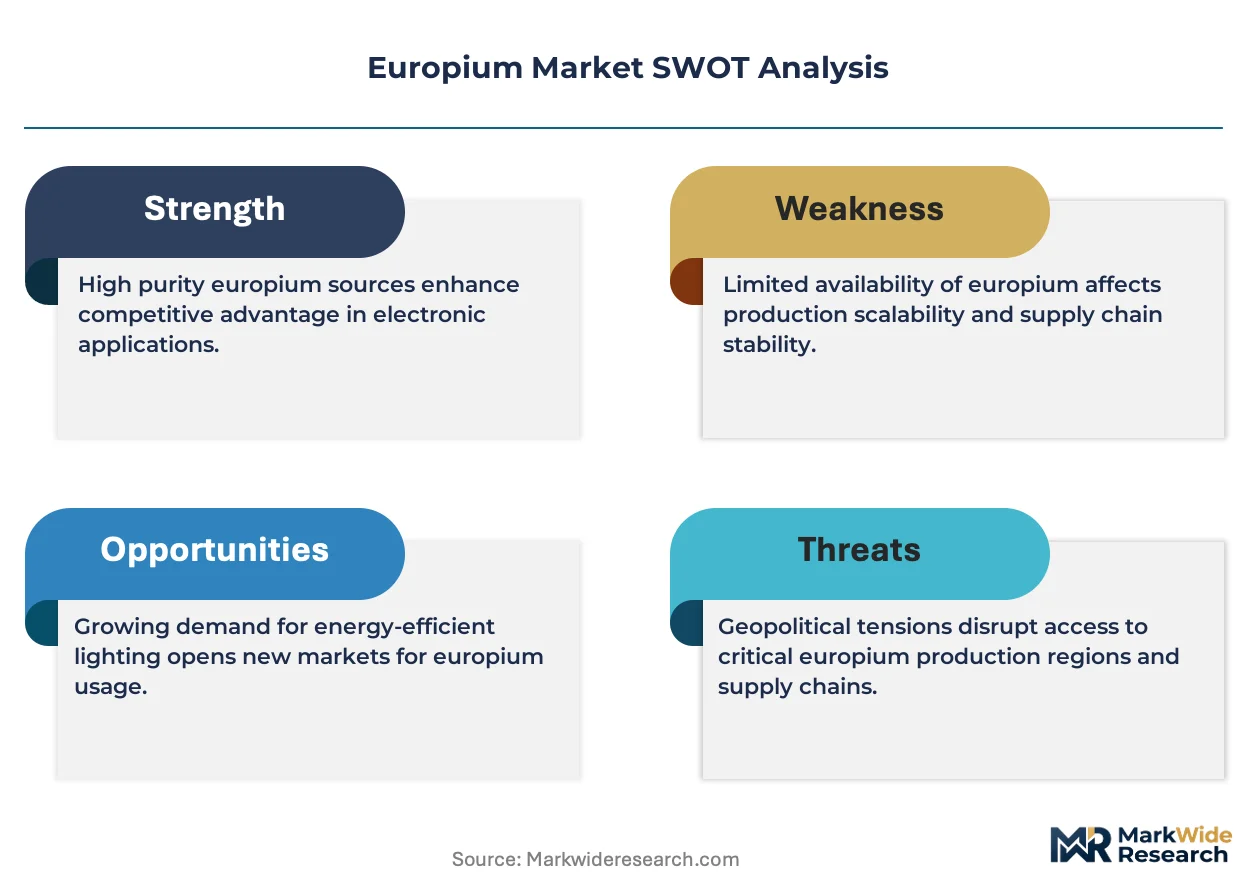
Europium is a lanthanide rare-earth element with atomic number 63, typically supplied as europium oxide with purity thresholds from 99% to 99.999% depending on phosphor or catalyst end-use; its primary commercial function centers on red-emitting phosphors for display screens and LED lighting systems. The phosphors segment leads value capture due to stringent purity requirements in television and monitor backlighting applications, while LED lighting represents the fastest-growing application channel as solid-state lighting displaces conventional sources. Technical-grade europium oxide occupies the highest volume tier, though high-purity grades command disproportionate margin pools from semiconductor and advanced display manufacturers.
China's Ministry of Industry and Information Technology governs production quotas and export licensing, directly constraining available volumes for non-domestic phosphor and magnet producers. The EU REACH regulation and RoHS directives impose substance restrictions and disclosure requirements that shape product formulations and market access conditions for europium-containing components. Stakeholders must monitor quota announcements from Beijing and traceability mandates from Brussels to secure supply continuity and compliance positioning.
Market Dynamics
China's MIIT production quota system concentrates rare-earth oxide supply in state-controlled pipelines, forcing phosphor and magnet manufacturers outside the country to secure long-term offtake agreements or develop alternative metallurgical circuits.
Growth Catalysts
- LED phosphor demand:Solid-state lighting manufacturers in Japan and South Korea are expanding red-emitting phosphor formulations for high-color-rendering displays.
- EU RoHS substance restrictions:Mercury-containing fluorescent lamp phase-outs are accelerating europium-activated phosphor substitution in backlighting assemblies.
- Malaysian processing capacity:Lynas Corporation's Mount Weld-to-Kuantan supply chain is anchoring non-Chinese security of supply for magnet and phosphor customers.
Market Restraints
- Input cost volatility:Rare-earth concentrate prices swing with China's quarterly quota announcements, compressing oxide converter margins.
- Supply concentration risk:Six state-owned mining groups control 85 percent of global europium-bearing bastnäsite and monazite extraction.
- Substitution threat:Manganese-activated phosphors are capturing cost-sensitive LED packaging segments where color purity requirements permit.
Strategic Opportunities
- Underpenetrated India:Domestic lighting manufacturers under the PLI scheme are localizing phosphor blending capacity for export-oriented LED assembly.
- Regulatory tailwind:Japan's METI rare-earth stockpiling mandate creates guaranteed offtake volumes for qualified foreign suppliers.
- Technology convergence:Quantum dot-enhanced LCD panels are integrating europium co-dopants to extend color gamut beyond conventional phosphor limits.
Industry Challenges
- Skill scarcity:Solvent extraction chemists with rare-earth separation expertise are concentrated in China's Bayan Obo and Jiangxi processing clusters.
- Certification timelines:REACH registration dossiers for high-purity europium oxide require 18-24 month toxicological study completion before EU market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europium Market |
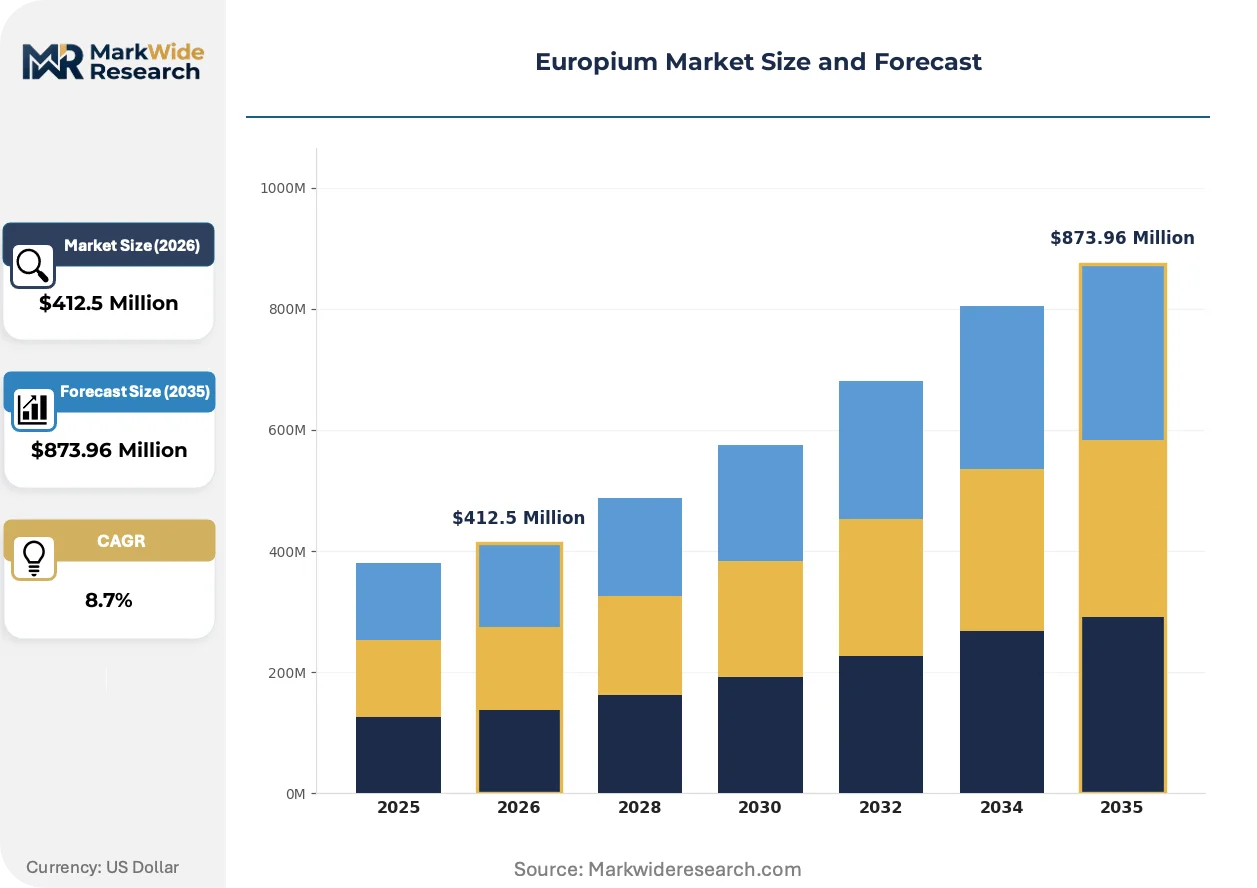
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Europium Oxide, Europium Metal, Europium Fluoride, Europium Iodide Application: Phosphors, Catalysts, Glass Additives, LED Lighting End User: Electronics, Automotive, Renewable Energy, Consumer Goods Grade: Technical Grade, Purity 99%, High Purity, Rare Earth Grade |
| Companies Covered | China Northern Rare Earth, China Minmetals Rare Earth, Lynas Corporation, Baotou Steel Rare-Earth, Neo Performance Materials, Avalon Advanced Materials, MP Materials, Shin-Etsu Chemical, Indian Rare Earths Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europium Market Emerging Trajectories
Phosphor formulation chemistry and regulatory chemistry are advancing in parallel, with purity thresholds tightening and alternative activation mechanisms competing for display and lighting sockets.
Mini-LED backlighting architectures are electrifying demand for narrow-band red emitters. Display panel manufacturers in Taiwan and South Korea are qualifying europium-doped nitride phosphors for 10,000-zone local dimming arrays. This specification shift is compressing tolerance bands for oxide feedstock purity from 99.99% to 99.999%.
EU REACH substance disclosure requirements are forcing reformulation transparency across the supply chain. Phosphor compounders must now document europium sourcing through conflict-mineral-style supply chain audits. Japanese magnet manufacturers are responding by demanding batch-level certificates of analysis from Malaysian and Australian oxide suppliers.
Long-term offtake contracting is displacing spot market purchasing for critical rare-earth inputs. LED packaging houses in Germany and the United States are locking in three-to-five-year supply agreements directly with oxide refiners. This procurement pattern shift is most visible in North American solid-state lighting assembly, where inventory carrying strategies now prioritize supply assurance over working capital efficiency.
Europium Market Segmentation
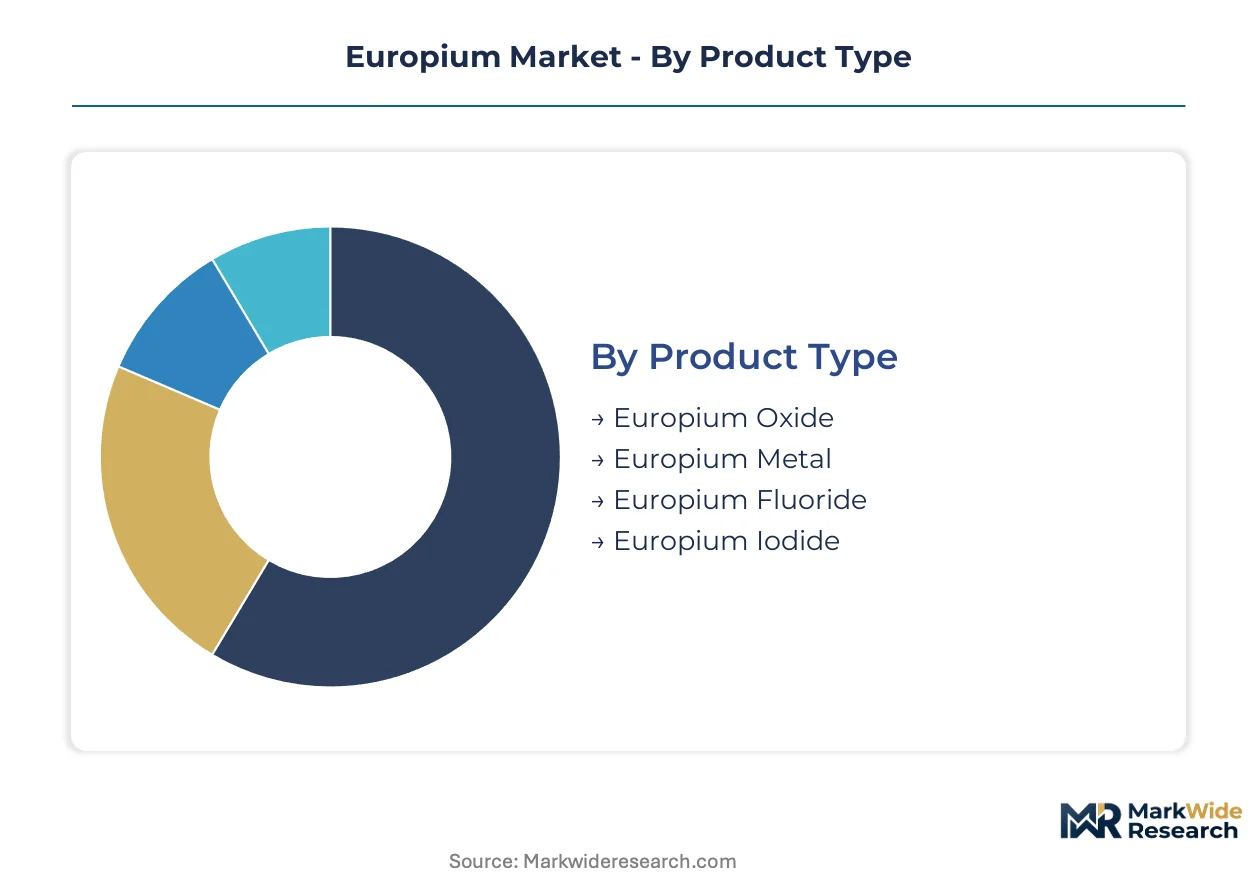
Europium supply chains fragment across chemical forms, purity thresholds, and end-use specifications. Each segment carries distinct metallurgical requirements and margin profiles that shape procurement strategies for phosphor compounders and magnet manufacturers.
Product Type:
Capital intensity escalates sharply from oxide conversion through metal reduction to halide synthesis, with fluoride and iodide production demanding specialized reactor infrastructure and inert atmosphere handling.
- Europium Oxide:Supplied as Eu₂O₃ in powder or granular form, this intermediate dominates commercial volumes through its role in phosphor precursor manufacturing. Japanese and South Korean display panel makers concentrate procurement around 99.99% purity thresholds for LED backlighting applications, with China's state-owned refiners controlling the bulk of oxide conversion capacity.
- Europium Metal:Produced via metallothermic reduction of oxide using lanthanum or mischmetal, metallic europium serves permanent magnet alloy formulations and specialized research applications. German and Japanese magnet manufacturers absorb the majority of non-Chinese metal supply, though production volumes remain constrained by reduction furnace scarcity outside China's Jiangxi province.
- Europium Fluoride:EuF₃ synthesis requires hydrofluoric acid handling infrastructure and corrosion-resistant reactor vessels, limiting qualified producers to integrated rare-earth groups with captive fluorine chemistry capabilities.
- Europium Iodide:High-purity EuI₃ production for scintillation crystal growth and optical applications occupies a niche tier with single-digit tonnage annually, sourced primarily from Russian and Chinese specialty chemical houses.
Europium oxide absorbs the bulk of installed capacity; europium metal is expanding most quickly as magnet alloy specifications tighten.
Application:
Application segmentation tracks directly to phosphor chemistry maturity, with established display technologies commanding predictable offtake while emerging LED architectures drive specification evolution.
- Phosphors:Red-emitting europium-activated yttrium oxysulfide and nitride phosphors constitute the dominant value pool, specified for television backlighting units and monitor displays. Taiwan-based panel manufacturers in Tainan and Taichung anchor demand concentration, with qualification protocols requiring 18-month stability testing before volume procurement authorization.
- LED Lighting:Solid-state lighting manufacturers in Germany and the United States are qualifying europium-doped phosphor blends for high-color-rendering index fixtures, with efficacy targets above 90 CRI driving substitution of cerium-doped alternatives in premium residential and commercial segments.
- Catalysts:Europium oxide serves as a promoter in automotive exhaust catalysis and petrochemical cracking, though loadings remain minimal compared to cerium and lanthanum.
- Glass Additives:Technical-grade europium oxide provides UV absorption and color stabilization in specialty optical glass, with German and Japanese optical manufacturers maintaining steady but modest offtake.
Phosphor applications retain the deepest volume base; LED lighting is climbing the fastest as mercury lamp phase-outs accelerate across EU member states.
End User:
End-user concentration reflects regional manufacturing specialization, with electronics clusters in East Asia consuming disproportionate shares of high-purity output.
- Electronics:Display panel fabrication, semiconductor manufacturing, and passive component production absorb the majority of high-purity europium oxide. South Korean and Japanese electronics conglomerates maintain strategic inventories through direct offtake contracts with Malaysian and Australian oxide refiners.
- Automotive:LED headlamp and interior lighting specifications are incorporating europium-activated phosphors for color consistency, with German and Japanese automakers driving qualification timelines.
- Renewable Energy:Wind turbine generator magnets utilize europium-bearing alloys in limited quantities, though neodymium and dysprosium dominate rare-earth magnet compositions.
- Consumer Goods:Premium flashlight and residential lighting products specify europium-doped phosphors for color quality differentiation, with North American and European brands sourcing through Taiwanese LED packaging houses.
Electronics commands the largest committed volumes; automotive is gaining share fastest as LED headlamp penetration deepens in European and Japanese vehicle platforms.
Grade:
Grade stratification creates tiered pricing architecture, with purity premiums expanding as semiconductor and advanced display specifications tighten tolerance bands.
- High Purity (99.999%):Five-nines europium oxide serves quantum dot co-doping applications and advanced phosphor formulations where trace lanthanide contamination degrades emission efficiency. South Korean display manufacturers in Suwon and Paju specify this grade for mini-LED backlighting arrays.
- Purity 99%:Standard technical-grade oxide supports glass additive and commodity catalyst applications, with Chinese state-owned refiners optimizing solvent extraction circuits for this volume tier.
- Technical Grade:Lower-purity oxide for industrial catalyst and bulk glass manufacturing, priced at significant discounts to high-purity material.
- Rare Earth Grade:Mixed rare-earth oxide streams containing europium as a by-product of neodymium and cerium production, requiring further separation for phosphor-grade utilization.
High purity grades capture the steepest margin premiums; 99% purity oxide handles the greatest tonnage throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo and Osaka anchor phosphor and magnet manufacturing demand for high-purity europium oxide, while regulatory frameworks in Beijing, Brussels, and Washington reshape supply security calculations for display and lighting manufacturers worldwide.
China
MIIT production quotas constrain rare-earth oxide availability for export markets, forcing Japanese and South Korean phosphor manufacturers to secure long-term offtake contracts. The dual carbon goals framework accelerates consolidation in Jiangxi and Inner Mongolia processing clusters. Bayan Obo mining complexes supply the bulk of europium-bearing bastnäsite feedstock to state-controlled separation circuits.
Japan
METI rare-earth stockpiling mandates create guaranteed absorption volumes for qualified foreign oxide suppliers, insulating domestic magnet and phosphor producers from supply disruptions. JIS standards tighten purity specifications for europium-doped nitride phosphors in mini-LED applications. Manufacturing clusters in Kansai and Kyushu concentrate LED packaging and display panel assembly operations.
South Korea
Suwon and Paju display fabrication complexes drive qualification of five-nines europium oxide for quantum dot co-doping in advanced backlighting arrays. The country's national industrial regulator enforces traceability requirements for rare-earth sourcing in electronics components. Domestic phosphor compounders are expanding solvent extraction partnerships with Malaysian oxide refiners.
Germany
EU REACH substance disclosure requirements and RoHS mercury lamp phase-outs accelerate europium-activated phosphor substitution in automotive LED headlamp specifications. German automakers in Bavaria and Baden-Württemberg mandate batch-level certificates of analysis from non-Chinese oxide suppliers. ECHA registration timelines for high-purity europium oxide extend 18-24 months, delaying market access for new entrants.
United States
EPA and OSHA frameworks govern rare-earth processing facility permitting, constraining domestic oxide conversion capacity expansion. LED packaging houses in Texas and California are locking in three-to-five-year supply agreements directly with Australian and Malaysian refiners. Defense stockpiling programs under the IRA create preferential offtake channels for magnet-grade rare-earth inputs.
Europium Market Vendor Landscape
Premium-margin players sit above commodity-margin players across purity-grade stratification, with five-nines oxide commanding disproportionate returns from semiconductor and advanced display manufacturers. State-controlled Chinese mining groups concentrate upstream extraction, while integrated non-Chinese processors anchor supply security for Japanese and South Korean customers. Three archetypes dominate: vertically integrated state-owned miners, standalone oxide refiners with Malaysian or Australian feedstock, and downstream phosphor compounders. Competitive moves center on long-term offtake contracting and solvent extraction capacity expansion.
Within the state-controlled tier, China Northern Rare Earth and China Minmetals Rare Earth occupy positions as volume anchors for technical-grade oxide supply. Lynas Corporation represents the non-Chinese security-of-supply archetype through its integrated Mount Weld-to-Kuantan pipeline. Neo Performance Materials exemplifies downstream specialization, focusing on rare-earth formulations for phosphor and magnet customers rather than upstream extraction.
| Leading Market Players |
|---|
| China Northern Rare Earth |
| China Minmetals Rare Earth |
| Lynas Corporation |
| Baotou Steel Rare-Earth |
| Neo Performance Materials |
| Avalon Advanced Materials |
| MP Materials |
| Shin-Etsu Chemical |
| Indian Rare Earths Limited |
| Others |
Supply Flow & Price Mechanics
Japan's METI stockpiling mandates and South Korean traceability requirements for five-nines oxide are compressing procurement flexibility for phosphor compounders, forcing supply chains to absorb certification premiums and redirect logistics through Malaysian processing corridors.
Pricing Analysis
Yield-anchored pricing tied to phosphor conversion efficiency dominates high-purity europium oxide contracts, with South Korean display manufacturers paying premiums for batch-level emission consistency certificates. Three-tier pricing structure across premium, standard, and economy levels separates five-nines quantum dot grades from 99.99% LED phosphor material and technical-grade glass additives. Cost compression in standard-purity tiers is intensifying because Chinese state-owned refiners are optimizing solvent extraction circuits for volume throughput. Commodity catalyst buyers exhibit highest price sensitivity, while mini-LED panel manufacturers accept steep premiums for traceability documentation.
Supply Chain Analysis
Japan's local-content rules for strategic rare-earth inventories are reshaping sourcing patterns, compelling phosphor manufacturers to qualify Malaysian and Australian oxide suppliers for METI stockpile eligibility. Feedstock draws from China's Bayan Obo bastnäsite complexes, Australian Mount Weld deposits, and Malaysian Kuantan separation circuits. Supply chain risk centers on single-source vulnerability in solvent extraction expertise concentrated in China's Jiangxi province. Distribution runs through long-term offtake contracts directly to Japanese and South Korean phosphor compounders, displacing spot market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around processing capabilities, with China's dual carbon goals and REACH registration timelines forcing smaller oxide converters into acquisition or exit.
For Market Incumbents: Anticipate manganese-activated phosphor substitution in cost-sensitive LED segments by locking three-to-five-year supply agreements with German and US lighting manufacturers. Secure backward integration into Malaysian or Australian feedstock through equity partnerships, insulating against MIIT quota volatility. Prioritize solvent extraction capacity expansion in non-Chinese jurisdictions to capture Japan's METI-mandated stockpiling volumes. For New Entrants and Emerging Players: Indian LED packaging houses under the PLI scheme represent the most penetrable buyer archetype, with domestic phosphor blending capacity localization creating demand for technical-grade oxide supply. Target automotive LED headlamp specifications in Germany and Japan, where europium-activated phosphor qualification timelines favor nimble suppliers with batch-level certification capabilities. Enter through toll-processing arrangements with existing Malaysian refiners to bypass REACH registration delays. For Investors and Strategic Acquirers: The window for entry favors integrated rare-earth processors with captive fluorine chemistry capabilities, as europium fluoride synthesis infrastructure scarcity widens margin capture. Mid-term viability hinges on positioning for quantum dot co-doping applications in mini-LED architectures. Monitor ECHA registration dossier completion rates for high-purity europium oxide as the inflection signal for EU market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks volume commitments from Japanese phosphor compounders facing METI stockpile mandates. |
| Backward Integration into Feedstock | Secures Mount Weld or Australian rare-earth concentrate for non-Chinese oxide conversion capacity. |
| Capacity Expansion | Adds solvent extraction circuits in Malaysia to capture South Korean five-nines qualification demand. |
| Joint Venture | Combines Chinese technical-grade oxide supply with Japanese phosphor formulation expertise for LED packaging. |
| Green Manufacturing Transition | Aligns with EU dual carbon goals and REACH substance disclosure requirements for market access. |
Methodological Framework
Multi-period observation of MIIT production quota announcements, phosphor formulation patent filings, and LED packaging capacity buildouts anchored the trend analysis, supplemented by interviews with solvent extraction chemists, phosphor compounder procurement leads, display panel manufacturing engineers, and rare-earth oxide refinery operations managers. Secondary validation drew from Chinese customs export data, Japanese METI rare-earth stockpile disclosures, ECHA REACH registration databases, and SEC filings of listed rare-earth processors. Bottom-up phosphor demand modeling and top-down rare-earth oxide supply estimates were triangulated for cross-verification.
Segment-weighting across product type, purity grade, application, and end-user dimensions structured the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted demand projections tied to LED backlighting unit shipments and mini-LED penetration curves. Forecast inputs incorporated phosphor formulation chemistry evolution, regulatory quota announcements from Beijing, and substitution threat assessment from manganese-activated alternatives.
Revisions become necessary when MIIT quota allocations diverge from seasonal patterns, ECHA accelerates or delays REACH registration timelines, or quantum dot phosphor formulations displace europium-doped nitride chemistries in display applications. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Semiconductor Glass Market
Semiconductor Material
PP Capacitor Films Market
Semiconductor Material
Wet Chemicals for Electronics and Semiconductor Application Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Tungsten Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Solar Silicon Ingots Market
Semiconductor Material
Global Thermal Paste Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
Quartz Market
Semiconductor Material
Global Electronic Materials Market
Semiconductor Material
Semiconductor Silicon Material Market