
 Vessel Traffic Management Market | 2026-2036
Vessel Traffic Management Market Size, Share, and Industry Trends Forecast 2026-2036
Vessel Traffic Management Market Intelligence
The IMO's e-navigation mandate is decoupling legacy radar-only installations from next-generation port eligibility. Wartsila Corporation leverages its integrated bridge systems to anchor long-term service contracts across Nordic and Baltic ports. Kongsberg Gruppen AS dominates high-fidelity sensor fusion for offshore energy corridors, while Saab AB specializes in coastal defense-grade traffic surveillance for dual-use installations.
Vessel Traffic Management denotes the coordinated hardware, software, and communication infrastructure that monitors, regulates, and optimizes maritime vessel movement through defined waterways, typically integrating radar returns, AIS transponder data, and meteorological feeds to maintain safe separation distances in congested channels. Automated Identification System deployments command the largest installed base among system types, though data analytics services are expanding fastest as ports shift from reactive traffic control to predictive berth optimization. Harbor deployment modes retain the densest sensor concentration, while offshore platform installations are gaining traction around floating LNG terminals and deep-water wind farms.
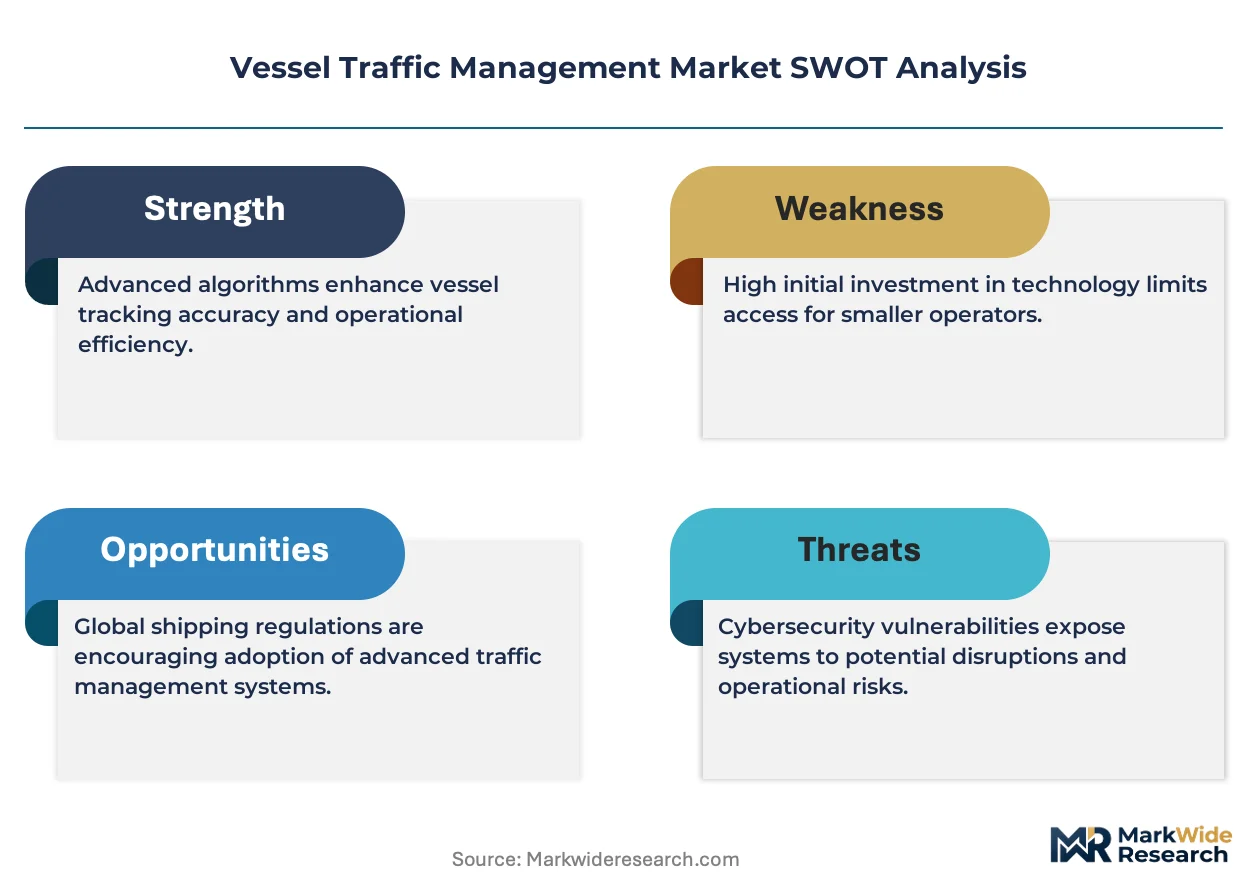
The International Maritime Organization, national coast guards, and port state control regimes collectively enforce carriage requirements for AIS transponders and VTS participation in controlled waters. The EU's Vessel Traffic Monitoring Directive and analogous national frameworks in Japan and South Korea mandate real-time data exchange with shore authorities, effectively embedding regulatory compliance into procurement specifications. Stakeholders must weigh the capital intensity of full VTS modernization against modular sensor upgrades that preserve legacy infrastructure while satisfying evolving interoperability standards.
Market Dynamics
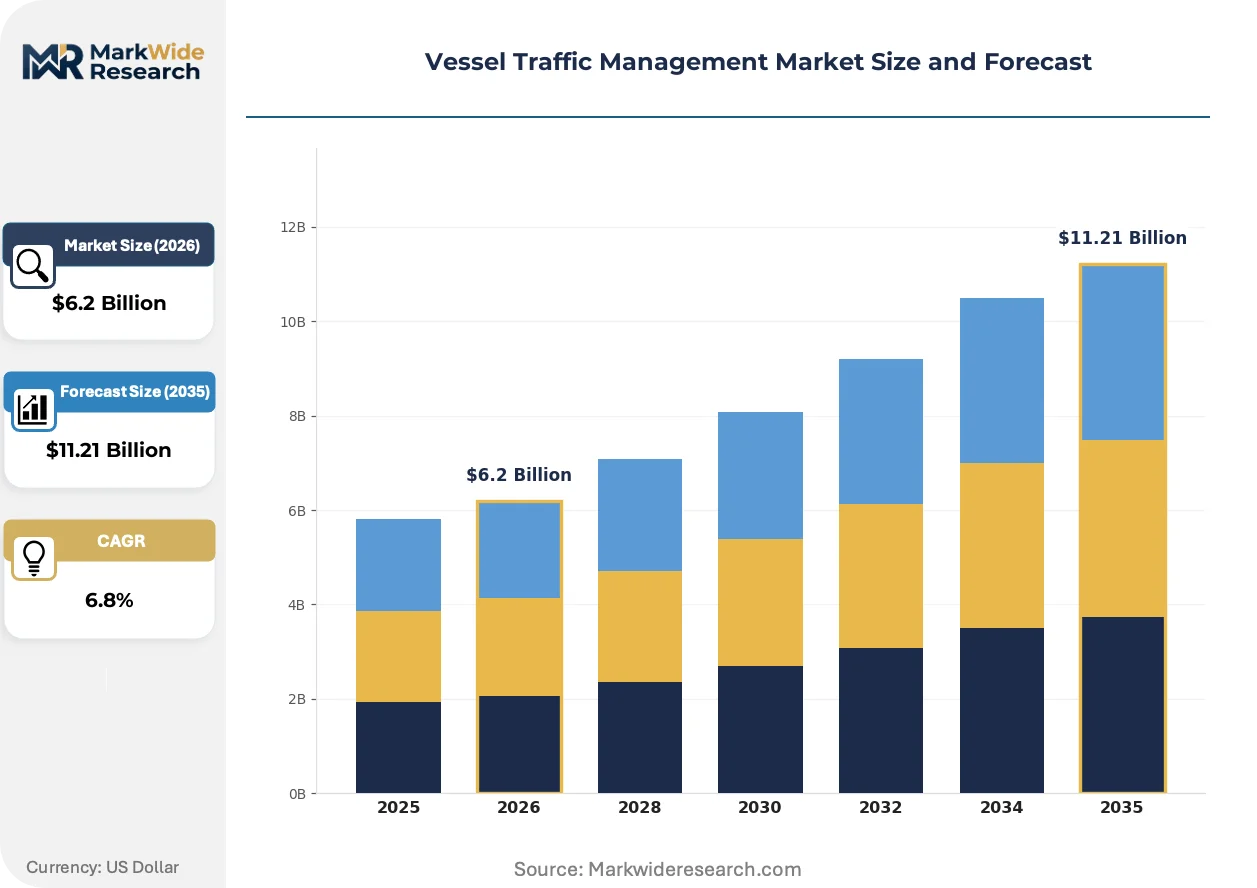
The IMO's e-navigation mandate is compressing upgrade cycles for port infrastructure worldwide, forcing a wholesale transition from standalone radar installations to integrated sensor networks that fuse AIS, meteorological, and satellite positioning feeds into unified traffic coordination platforms.
Growth Catalysts
- IMO e-navigation compliance deadlines:Port authorities in Singapore, Rotterdam, and Shanghai are accelerating VTS modernization to meet carriage requirements for integrated bridge systems in controlled waters.
- Floating LNG terminal proliferation:Offshore energy corridors in the Gulf of Mexico and Norwegian North Sea are deploying high-fidelity traffic management around cryogenic cargo transfer zones.
- Deep-water wind farm clustering:Construction vessel coordination needs in the North Sea and Baltic are driving demand for offshore platform-grade sensor networks.
Market Restraints
- Capital intensity of full VTS replacement:Harbor authorities face budget constraints when migrating from legacy radar to multi-sensor fusion architectures requiring fiber backhaul and redundant power.
- Specialized marine electronics supply concentration:High-precision radar magnetron and AIS transponder manufacturing concentrates among a limited supplier base in Northern Europe and East Asia.
- Interoperability standard fragmentation:Divergent national implementations of IALA VTS guidelines create integration friction for multinational shipping operators.
Strategic Opportunities
- Predictive berth optimization services:Data analytics platforms that forecast vessel arrival windows and tug allocation needs are displacing reactive traffic control in Singapore and Antwerp.
- Dual-use coastal surveillance:Civil-military sensor sharing agreements in Sweden and Finland are opening procurement channels for defense-grade traffic monitoring systems.
- Arctic corridor development:Ice-class vessel routing through Russia's Northern Sea Route is creating demand for satellite-AIS hybrid tracking beyond conventional radar range.
Industry Challenges
- Maritime cyber-physical security integration:VTS operators must harden sensor networks against GPS spoofing and AIS message injection attacks without degrading real-time traffic coordination.
- Legacy system protocol bridging:Ports with 1990s-era radar infrastructure struggle to extract usable data feeds for modern predictive analytics platforms.
- Certified VTS operator shortages:IALA training program throughput limits the pace at which control centers can staff expanded monitoring stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vessel Traffic Management Market |
| Market Size in 2026 | $6.2 Billion |
| Market Size in 2035 | $11.21 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Automated Identification System, Radar, Sonar, Vessel Monitoring System, Laser Surveillance Service Type: Real-time Tracking, Data Analytics, Risk Assessment, Alert Management, Communication Support Deployment Mode: Onshore, Offshore Platform, Harbor, Inland Waterways, Coastal Monitoring End User: Port Authorities, Maritime Security Agencies, Shipping Companies, Environmental Monitoring Organizations, Rescue Operations |
| Companies Covered | Wartsila Corporation, Leonardo S.p.A., Kongsberg Gruppen AS, Japan Radio Co. Ltd., Northrop Grumman Corporation, Thales Group, Saab AB, General Electric Co., L3Harris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vessel Traffic Management Market Strategic Shifts & Innovations
Sensor fusion architectures are absorbing functionality from discrete hardware layers, compressing the traditional separation between radar detection, AIS correlation, and decision support into unified software-defined platforms.
Machine learning-based anomaly detection is absorbing the pattern-recognition workload previously assigned to human VTS operators, enabling automated flagging of deviation from established traffic separation schemes. Major container terminals in Rotterdam and Hamburg are deploying these systems for 24/7 monitoring of approach channels. The technology is absorbing mid-tier port budgets that previously funded additional watchstander positions.
The EU Vessel Traffic Monitoring Directive is mandating real-time data exchange between shipborne AIS and shore-based authorities, embedding regulatory compliance into procurement specifications for newbuild vessels. This framework is forcing retrofit demand among older fleets trading in Community waters. Coastal states are responding by upgrading shore-side reception infrastructure to handle encrypted satellite-AIS feeds.
Service unbundling is fragmenting the traditional VTS procurement model, with port authorities separating sensor hardware purchase from software licensing and ongoing data analytics subscriptions. Terminal operators in Busan and Yokohama are piloting usage-based contracts for traffic coordination services rather than capital-intensive system ownership. This shift is most visible among mid-size harbors seeking to avoid stranded asset risk from rapid technology obsolescence.
Vessel Traffic Management Market Segmentation
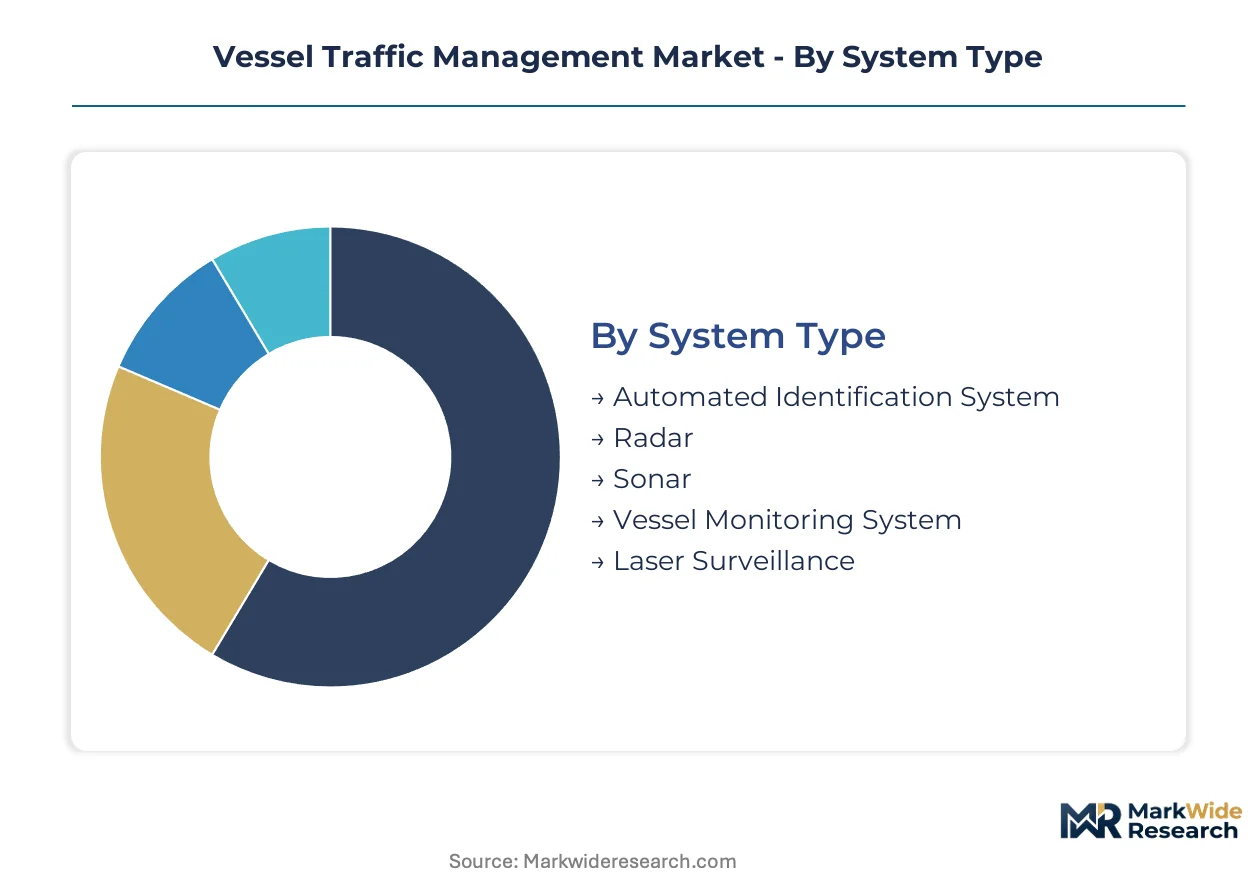
Vessel traffic management procurement follows distinct technical and operational logics across system architectures, service layers, and deployment environments. Buyers prioritize interoperability certifications, sensor fusion capabilities, and regulatory compliance pathways when evaluating segment alternatives.
System Type:
Procurement decisions hinge on legacy infrastructure compatibility and sensor density requirements for specific waterway risk profiles.
- Automated Identification System:Shipborne transponder networks broadcasting position, course, and vessel identity at VHF frequencies form the carriage-mandated backbone of traffic coordination. Singapore's Maritime and Port Authority mandates Class A AIS for all commercial vessels above 300 gross tonnage, driving dense shore-side receiver networks across the Strait of Malacca.
- Radar:X-band and S-band magnetron systems provide non-cooperative target detection independent of vessel transponder compliance. Rotterdam's port extension projects are specifying solid-state radar with doppler processing to resolve small craft amid container terminal clutter.
- Sonar:Underwater acoustic detection arrays monitor submerged traffic and seabed infrastructure integrity. Fixed installations protect LNG offloading buoys in the Norwegian North Sea against anchor-dragging incidents.
- Vessel Monitoring System:Satellite-linked position reporting for fisheries enforcement and exclusive economic zone patrol. Chile's national fisheries service deploys VM-S systems to monitor industrial trawler compliance with seasonal closure zones.
- Laser Surveillance:LIDAR-based ranging for precision docking assistance and berth approach monitoring. Pilot programs at Hamburg's Container Terminal Altenwerder validate millimeter-scale position accuracy for ultra-large container vessels.
Automated Identification System leads on scale; Laser Surveillance leads on momentum.
Service Type:
Service bundling patterns reflect port authority staffing constraints and the shift from reactive traffic control to predictive resource allocation.
- Real-time Tracking:Continuous position updates fused from multiple sensor streams enable immediate traffic separation enforcement. Shanghai's VTS center processes over 2,000 vessel movements daily through integrated radar-AIS correlation displays.
- Data Analytics:Machine learning platforms forecasting arrival windows, berth occupancy, and tug demand. Antwerp's port authority reduced average anchorage time by 23% after deploying predictive berth optimization algorithms.
- Risk Assessment:Dynamic collision probability modeling based on vessel maneuvering characteristics and environmental conditions. Pilots in the Turkish Straits rely on real-time CPA/TCPA calculations for two-way traffic in narrow channels.
- Alert Management:Automated deviation flagging when vessels breach traffic separation schemes or approach restricted zones. Busan VTS generates audible alarms for CPA violations below 0.5 nautical miles in the Jinhae approach.
- Communication Support:Integrated VHF voice and data link management for coordinated traffic advisories. Dubai's Harbor Control maintains dedicated channels for pilotage, port operations, and vessel traffic coordination.
Real-time Tracking commands the largest addressable base; Data Analytics shows the steepest expansion trajectory.
Deployment Mode:
Capital intensity and sensor density vary sharply across installation environments, with offshore platforms commanding premium pricing for redundancy requirements.
- Onshore:Land-based control centers with fiber-connected sensor masts covering approach channels and anchorage zones. The Kiel Canal's VTS centers in Brunsbüttel and Holtenau coordinate 90 daily transits through 34 automated radar stations.
- Offshore Platform:Self-contained traffic management for floating LNG terminals and production platforms. Prelude FLNG off Australia's northwest shelf operates an independent VTS with 12-nautical-mile radar coverage for cryogenic cargo transfers.
- Harbor:Densest sensor concentration with sub-meter positioning for precision docking. Rotterdam's Maasvlakte 2 extension integrates 47 radar heads with automatic identification system base stations for 24/7 container terminal approach monitoring.
- Inland Waterways:Reduced-complexity installations for river and canal systems with lower vessel speeds. The Rhine Commission coordinates VTS coverage from Rotterdam through Basel with harmonized reporting points.
- Coastal Monitoring:Wide-area surveillance for vessel traffic service areas beyond individual port jurisdictions. Sweden's Coast Guard maintains coastal radar chains spanning the Kattegat and Skagerrak for cross-border traffic coordination.
Harbor deployments absorb the majority of installed value; Offshore Platform installations are climbing the fastest.
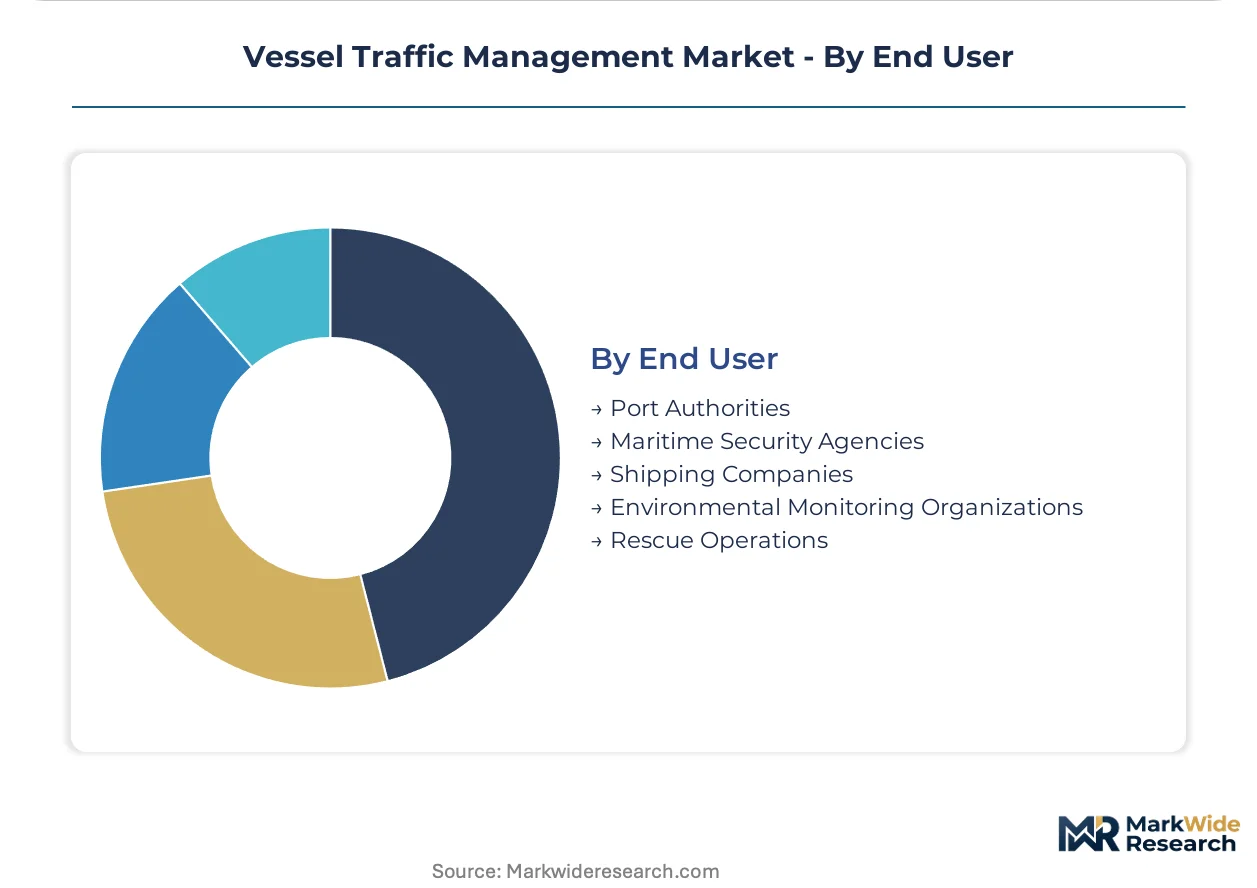
End User:
Budget authority and compliance drivers diverge across institutional buyers, with port authorities controlling infrastructure capital and shipping companies managing carriage equipment.
- Port Authorities:Shore-side VTS infrastructure owners responsible for traffic coordination in controlled waters. PSA International operates integrated traffic management across Singapore, Antwerp, and multiple global terminal concessions.
- Maritime Security Agencies:Coast guards and naval forces requiring dual-use surveillance for law enforcement and defense. Finland's Border Guard shares civil-military sensor networks with NATO BALTOPS exercise coordination.
- Shipping Companies:Fleet operators procuring bridge equipment and satellite communication services to satisfy port state control. Maersk Line mandates integrated bridge system certification for all newbuild vessels above 50,000 dwt.
- Environmental Monitoring Organizations:Agencies tracking vessel emissions and ballast water compliance through automatic identification system data. The European Maritime Safety Agency correlates satellite AIS with EU MRV reporting for carbon intensity verification.
- Rescue Operations:Search and rescue coordination centers requiring vessel position data for emergency response. Japan Coast Guard's 11 regional headquarters integrate VTS feeds with SAR mission planning systems.
Port Authorities dominate infrastructure procurement; Maritime Security Agencies are gaining share fastest through dual-use funding mechanisms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vessel traffic management systems trace their commercial origins to post-war port reconstruction in Northern Europe, where radar-based vessel traffic services first coordinated commercial shipping through the English Channel and North Sea approaches. The technology spread through colonial maritime networks and now concentrates in corridors handling the highest cargo volumes.
Singapore
The Maritime and Port Authority operates the world's densest vessel traffic service, processing over 1,000 daily transits through the Strait of Malacca. The port's Next Generation Vessel Traffic Management System mandate requires full sensor fusion by 2026, compressing upgrade timelines for terminal operators. PSA International's Tuas megaport development anchors procurement for integrated bridge and shore-side coordination platforms.
Netherlands
Rotterdam's port extension at Maasvlakte 2 drives demand for solid-state radar and automatic identification system base stations covering expanded container terminal approaches. The EU Vessel Traffic Monitoring Directive mandates real-time data exchange with vesselborne systems, embedding compliance into harbor infrastructure specifications. Rijkswaterstaat coordinates VTS coverage across the Scheldt delta with Belgian authorities.
Norway
Offshore energy corridors in the North Sea generate specialized demand for platform-grade traffic management around floating LNG terminals and subsea infrastructure. The Norwegian Coastal Administration maintains coastal radar chains spanning the fjord-indented coastline for cross-border coordination with Swedish and Danish authorities. Kongsberg Maritime anchors domestic supply for integrated sensor networks.
United States
The Coast Guard's Nationwide Automatic Identification System expansion targets full coverage of port security zones and marine sanctuaries by 2028. Gulf of Mexico offshore platforms handling cryogenic cargo transfers require independent vessel traffic services with redundant power and communications. Houston Pilots coordinate with Port Houston on precision docking systems for ultra-large container vessels.
Japan
The Japan Coast Guard's 11 regional headquarters integrate vessel traffic service feeds with search and rescue mission planning systems across congested domestic straits. The country's fisheries enforcement regime mandates satellite-linked vessel monitoring systems for industrial trawlers operating in distant-water fleets. Tokyo Bay's dense vessel concentration drives harbor-grade sensor density requirements.
Vessel Traffic Management Market Key Industry Players
The competitive structure tilts toward defense-electronics conglomerates with established maritime surveillance portfolios. Three to five Nordic and European industrial groups control premium-tier sensor fusion architectures, while Asian electronics manufacturers compete on automatic identification system transponder volume. The dominant archetypes comprise integrated bridge system providers, coastal defense contractors, and specialized marine electronics houses. Consolidation pressure operates through strategic partnerships for satellite-AIS data feeds and technology licensing for machine learning-based anomaly detection.
Within the defense-electronics tier, Northrop Grumman Corporation and Thales Group exemplify dual-use positioning across civil vessel traffic services and coastal surveillance programs. Kongsberg Gruppen AS occupies a specialist position in high-fidelity sensor integration for offshore energy applications. Leonardo S.p.A. represents Italian industrial participation in Mediterranean port modernization and naval traffic coordination systems.
| Leading Market Players |
|---|
| Wartsila Corporation |
| Leonardo S.p.A. |
| Kongsberg Gruppen AS |
| Japan Radio Co. Ltd. |
| Northrop Grumman Corporation |
| Thales Group |
| Saab AB |
| General Electric Co. |
| L3Harris Technologies, Inc. |
| Others |
Cost & Logistics Intelligence
Solid-state radar magnetron production is consolidating in Northern Europe and East Asia, simultaneously compressing component costs for tier-one integrators while concentrating pricing power among magnetron specialists serving harbor-grade installations. This dual shift forces mid-tier port authorities to choose between premium sensor fusion architectures and modular upgrade paths that preserve legacy infrastructure investments.
Pricing Analysis
The bundled-vs-unbundled service split is fragmenting procurement patterns across port authorities, with software-defined platforms commanding recurring subscription premiums while hardware-only transactions face commoditization pressure. Pricing stratifies across defense-grade certification tiers, fiber-backhaul redundancy specifications, and predictive analytics bundling. Cost compression in standalone radar replacement is intensifying because Asian electronics manufacturers are flooding the automatic identification system transponder market with volume production. Harbor authorities with constrained capital budgets exhibit the highest price sensitivity, while offshore energy operators prioritize redundancy over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for magnetron and AIS base station procurement are forcing port authorities to qualify suppliers across Norway, Finland, and Japan simultaneously. High-precision radar components draw from specialized foundries in Germany and South Korea, with fiber-optic sensor backhaul resting on submarine cable infrastructure concentrated in Singapore and the Netherlands. Single-source vulnerability in solid-state radar magnetron supply creates exposure to export licensing delays. Distribution runs through defense-electronics integrators with established maritime surveillance portfolios rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through predictive analytics tiering, where software subscriptions capture recurring revenue at gross margins substantially above hardware-only deployments. Service unbundling shifts buyer relationships from capital-intensive ownership to usage-based contracts, reducing customer acquisition costs while lengthening lifetime value.
For Market Incumbents: Lock in long-term service contracts by embedding machine learning-based anomaly detection into integrated bridge system offerings, neutralizing the threat from pure-play software entrants. Prioritize backward integration into satellite-AIS data feeds to control the information layer that predictive berth optimization algorithms require. Defend Nordic and Baltic port relationships through Kongsberg Maritime's established coastal radar maintenance networks.
For New Entrants and Emerging Players: The price-point gap between Wartsila's premium integrated bridge systems and economy-tier radar-only installations creates white-space opportunity for mid-market sensor fusion platforms targeting secondary harbors in Southeast Asia. Focus initial penetration on inland waterway authorities in the Rhine corridor, where harmonized reporting requirements reduce certification friction. Pursue partnership-based go-to-market models with established pilotage associations rather than direct port authority sales cycles.
For Investors and Strategic Acquirers: Roll-up economics work for specialized marine electronics houses because IALA certification requirements create customer switching costs that protect acquired revenue bases. The five-to-ten year viability window favors targets with established coastal defense contracts that can pivot toward civil port modernization. Watch for inflection in Arctic corridor traffic volumes through Russia's Northern Sea Route as the signal triggering accelerated satellite-AIS hybrid tracking investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Rotterdam's Maasvlakte 2 extension demonstrates unified radar-AIS correlation displacing standalone installations. |
| Predictive Analytics Service Launch | Antwerp's berth optimization algorithms reduced average anchorage time through machine learning deployment. |
| Dual-Use Coastal Surveillance Partnership | Sweden's civil-military sensor sharing agreements opened procurement channels for defense-grade systems. |
| Arctic Corridor Tracking Infrastructure | Ice-class vessel routing through Russia's Northern Sea Route demands satellite-AIS hybrid coverage. |
| Service Unbundling Transition | Busan and Yokohama pilots validate usage-based contracts reducing stranded asset risk for mid-size harbors. |
Research Approach
Coverage spans Singapore, the Netherlands, Norway, the United States, and Japan, with primary inputs from each region's port authority procurement directors, VTS center operators, integrated bridge system engineers, and maritime safety regulators. Secondary validation draws from IMO e-navigation mandate documentation, IALA VTS guideline publications, EU Vessel Traffic Monitoring Directive filings, and Coast Guard AIS expansion program disclosures. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across the analysis window.
Rate-of-change decomposition separates volume effects from price-mix shifts across system type, service layer, deployment mode, and end-user budget authority dimensions. CAGRs were derived from installed base evolution and replacement cycle compression under regulatory compliance deadlines. Forecast inputs incorporate floating LNG terminal proliferation timelines and deep-water wind farm construction vessel coordination requirements throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for machine learning-based anomaly detection would alter the outlook if regulatory certification lags behind software development cycles. Forecasts reflect assumptions regarding IMO e-navigation implementation uniformity and fiber backhaul infrastructure availability in secondary harbors. Deviation in Arctic corridor ice-class traffic volumes or satellite-AIS encryption standard adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Middle East Offshore Support Vessels Market
Maritime Equipment
Ship-To-Shore (STS) Container Cranes Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Air Compressors on Ships Market
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Latin America Offshore Support Vessels Market
Maritime Equipment
Europe Offshore Support Vessels Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
Very Large Gas Carrier Market