
 Traffic Monitoring Market | 2026-2036
Traffic Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Traffic Monitoring Market Analysis
High-definition video specification tiers is redrawing competitive boundaries in traffic monitoring hardware. Kapsch TrafficCom AG leverages its European installed base to sustain long-term service contracts. Teledyne FLIR LLC anchors its position through thermal imaging specialization in low-visibility detection. Yunex Traffic competes on integrated signal-control platforms that merge detection with adaptive timing.
Traffic monitoring encompasses the continuous acquisition, processing, and analysis of vehicular and pedestrian flow data using fixed and mobile sensors, typically operating at 30-60 frames per second with sub-100-millisecond latency for real-time signal response. Its primary purpose is to optimize intersection throughput, enforce traffic law, and feed predictive models for infrastructure planning. Integrated solutions command the deepest margin pools because bundled hardware-software contracts reduce procurement friction for transportation authorities. Machine learning and AI analytics segments are expanding fastest as agencies replace rule-based detection with neural networks that classify vehicle types and predict congestion patterns. Edge computing deployments are maturing in dense urban corridors where cloud latency conflicts with real-time safety requirements.
The Federal Highway Administration's MUTCD guidelines and the EU AI Act jointly shape product standards for automated enforcement and algorithmic transparency in public infrastructure. State-level departments of transportation in California, Texas, and New York layer additional procurement specifications that filter vendor eligibility. Stakeholders must monitor how emerging algorithmic accountability requirements alter liability structures for AI-generated traffic citations and incident alerts.
Market Dynamics
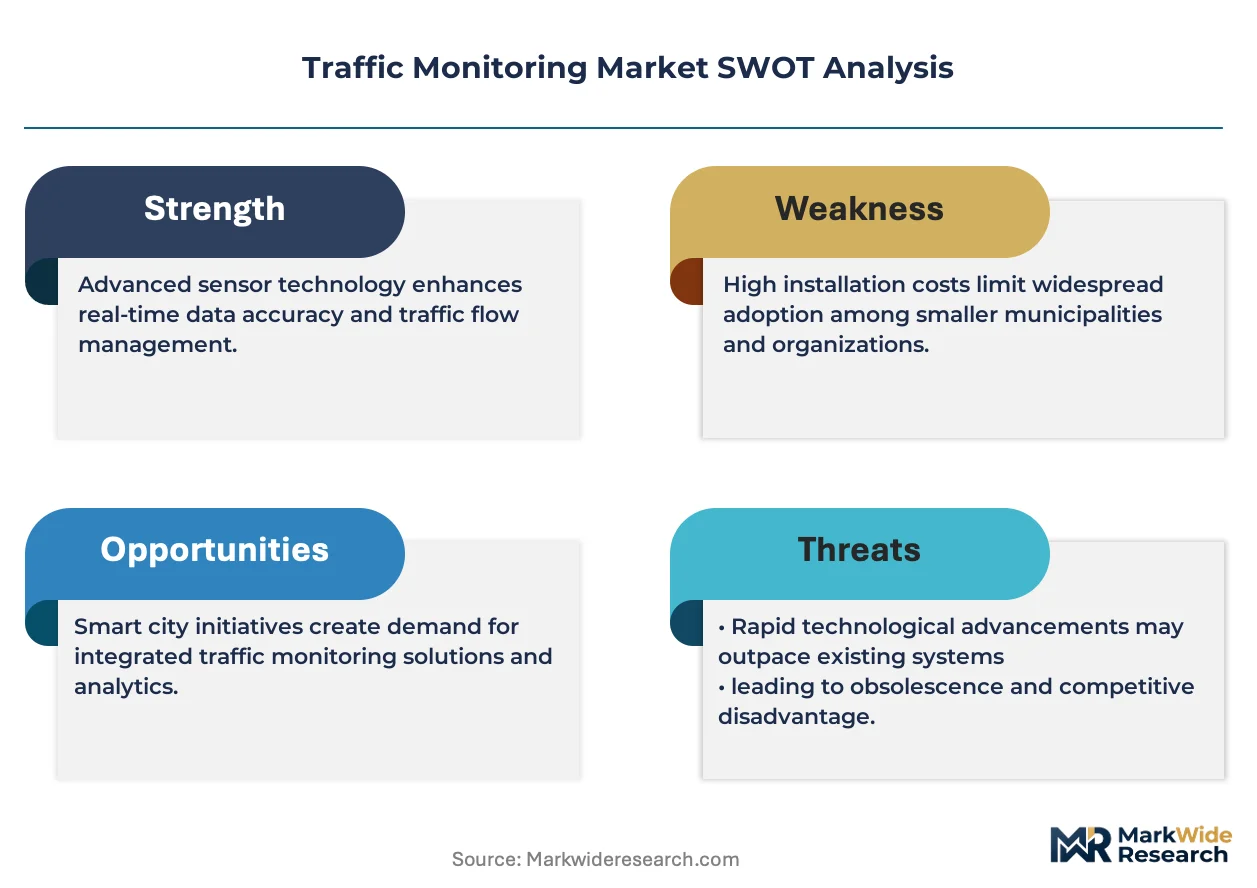
The convergence of edge AI processing with 5G backhaul is redrawing deployment economics for traffic infrastructure operators, compressing hardware refresh cycles from seven years to under four.
Growth Catalysts
- EU AI Act compliance mandates:Transportation authorities across Germany, France, and the Netherlands are procuring certified systems ahead of enforcement deadlines, creating pull-through demand for algorithmically transparent detection platforms.
- Thermal imaging integration:Low-visibility detection capabilities are penetrating fog-prone corridors in the Pacific Northwest and Alpine regions, expanding addressable incident-response scenarios.
- Singapore smart city procurement:The Land Transport Authority's sensor-dense district pilots are validating multi-modal analytics at scale, generating reference architectures for replication.
Market Restraints
- Semiconductor supply concentration:Edge AI chip fabrication relies on TSMC and Samsung foundries, exposing deployment timelines to geopolitical disruption in East Asian supply chains.
- GDPR-derived data localization:Cross-border cloud analytics face structural friction in EU member states requiring sovereign data storage, fragmenting platform architectures.
- Lidar cost floor:Solid-state alternatives remain above the economic threshold for mass intersection deployment, constraining high-precision spatial mapping adoption.
Strategic Opportunities
- India National Highways expansion:The NHAI's corridor development program lacks legacy detection infrastructure, enabling greenfield integrated platform deployment without retrofit constraints.
- V2X communication convergence:DSRC and C-V2X protocol maturation is creating white space for edge sensors that fuse roadside detection with connected vehicle telemetry.
- California SB 743 compliance:Vehicle miles traveled metrics are mandating granular traffic flow analytics for development impact assessments, expanding municipal data service contracts.
Industry Challenges
- Embedded systems firmware expertise:Real-time signal processing at 60 frames per second requires specialized engineering talent scarce outside aerospace and defense hiring pools.
- MUTCD certification timelines:Federal Highway Administration approval cycles for new detection modalities extend 18-24 months, compressing product launch windows.
- Interoperability with legacy signal controllers:NTCIP protocol variations across 1990s-era installations impose integration costs that erode margin on bundled contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traffic Monitoring Market |
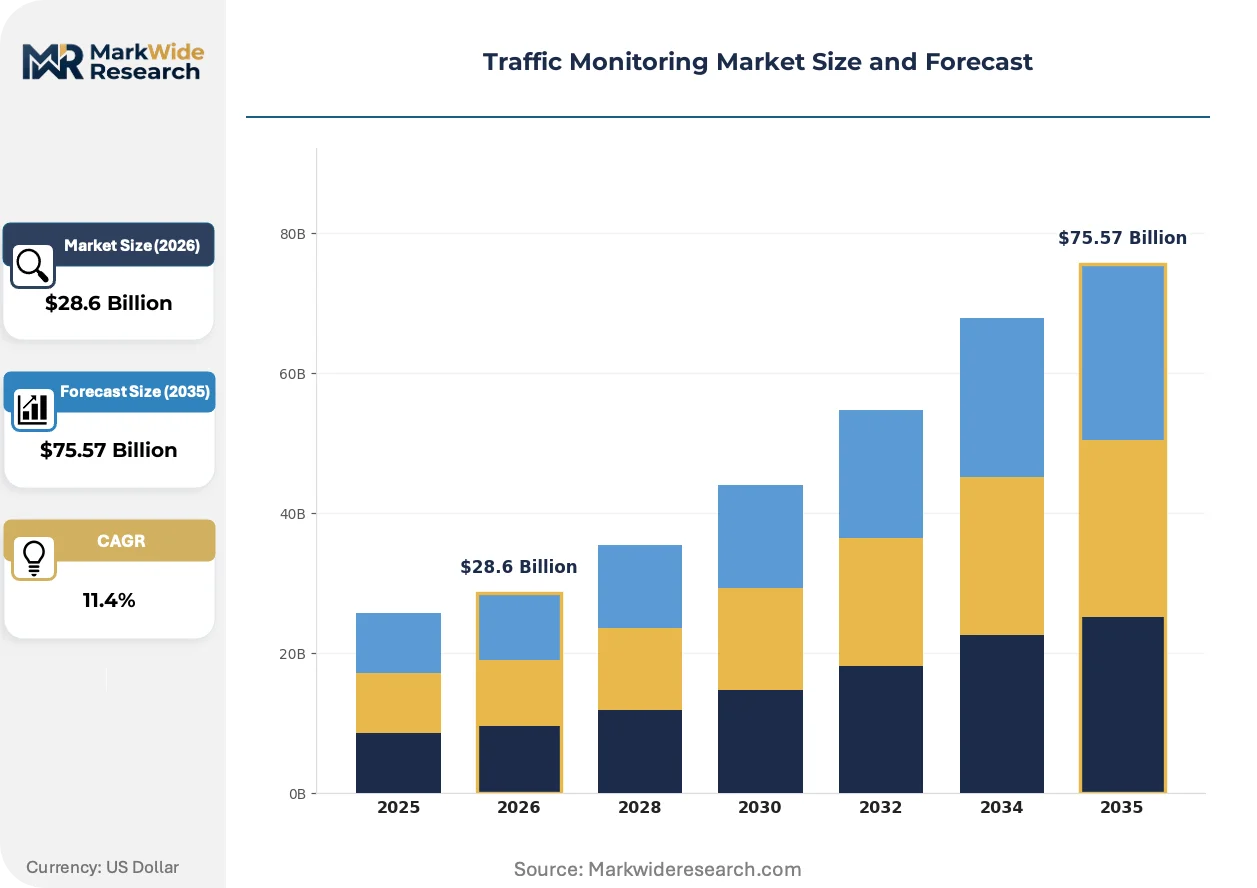
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Cameras, Mobile Cameras, Sensors, Integrated Solutions Technology: Machine Learning, AI Analytics, Cloud Computing, Edge Computing Application: Smart Cities, Fleet Management, Traffic Law Enforcement, Infrastructure Monitoring End User: Government Agencies, Transportation Authorities, Law Enforcement, Private Sector |
| Companies Covered | TE Connectivity, Miovision Technologies Incorporated, Kapsch TrafficCom AG, Transcore Inc., Yunex Traffic, SWARCO AG, Iteris, Inc., Conduent Transportation, Teledyne FLIR LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traffic Monitoring Market Emerging Trajectories
Traffic monitoring is pivoting from hardware-centric procurement to data-service subscriptions, with municipal buyers prioritizing predictive analytics over raw sensor acquisition.
Edge AI inference engines are decomposing the traditional centralized video analytics architecture. California DOT and Texas DOT pilot programs are deploying GPU-accelerated roadside units that process vehicle classification locally. This compression of compute geography is reducing backhaul bandwidth requirements by orders of magnitude while enabling sub-100-millisecond signal response.
REACH substance restrictions are forcing enclosure and cable manufacturers to reformulate halogen-free flame-retardant compounds. The industrial consequence extends beyond component costs to supply chain requalification timelines. German and Nordic procurement specifications are now screening for SVHC compliance, filtering vendor pools ahead of formal mandate expansion.
Municipal buyers are unbundling maintenance from initial capital expenditure, favoring ten-year availability contracts with performance guarantees. This displaces the traditional equipment-vendor relationship with systems integrators who absorb operational risk. The shift is most visible in Singapore and Dutch smart city frameworks, where uptime penalties now exceed hardware depreciation schedules.
Traffic Monitoring Market Segmentation
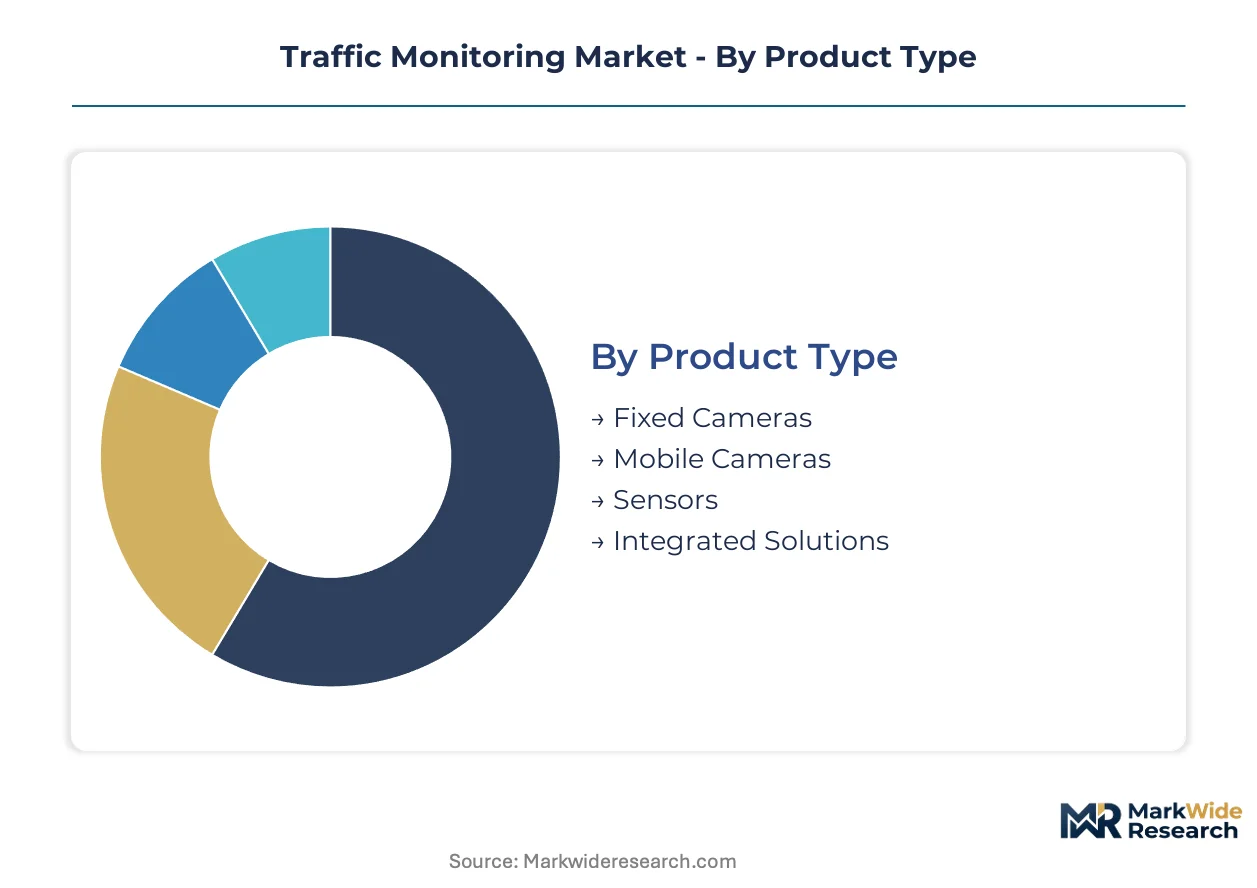
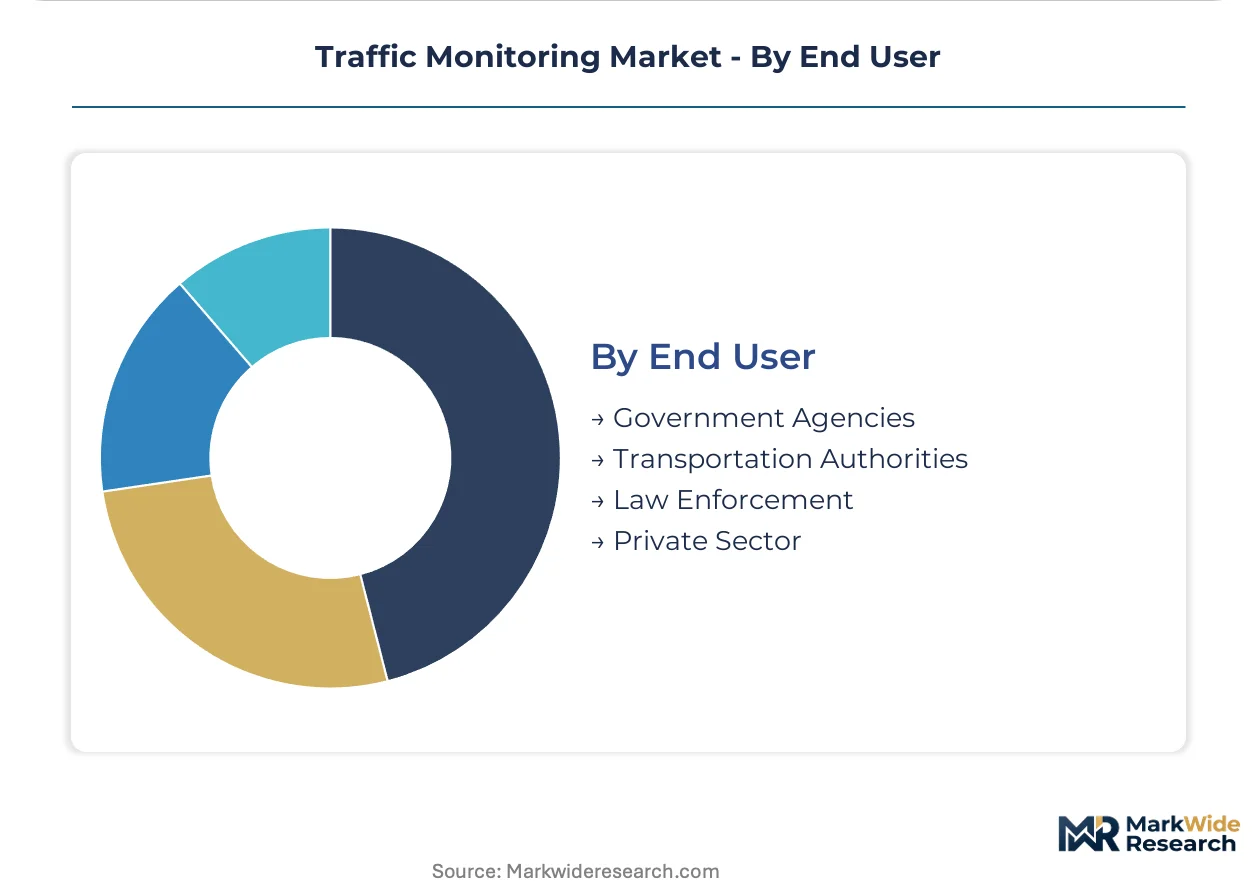
Segmentation in traffic monitoring reveals how procurement authority and technical architecture determine vendor access. Transportation authorities prioritize bundled solutions that compress deployment timelines, while technology choices increasingly hinge on latency requirements and data sovereignty constraints.
Product Type:
Fixed cameras face substitution pressure from mobile and sensor-fusion alternatives as agencies seek flexible coverage without permanent infrastructure investment.
- Fixed Cameras:Permanently mounted units operating at 30-60 frames per second with sub-100-millisecond latency for real-time signal response. Demand concentrates in Singapore and German smart city corridors where dense intersection coverage justifies capital-intensive installation. The EU AI Act certification requirements are filtering vendor pools for algorithmic transparency in automated enforcement applications.
- Integrated Solutions:Bundled hardware-software platforms combining edge sensors with cloud analytics and adaptive signal control. California DOT and Texas DOT procurement specifications favor these systems for reducing procurement friction and unifying maintenance accountability under single-vendor contracts.
- Mobile Cameras:Vehicle-mounted or portable units deployed for temporary enforcement and incident response scenarios.
- Sensors:Discrete detection devices including radar, lidar, and thermal units providing point-specific data streams.
Fixed cameras anchor the volume base while integrated solutions gain share at the steepest rate.
Technology:
Cost tier differentiation separates enterprise-grade neural network deployments from rule-based systems, with edge computing commanding premium positioning due to latency-sensitive safety applications.
- Edge Computing:GPU-accelerated roadside units processing vehicle classification and incident detection locally without cloud backhaul. Dense urban corridors in Singapore and the Netherlands deploy these systems where sub-100-millisecond response conflicts with cloud latency. 5G backhaul convergence is compressing hardware refresh cycles and expanding addressable deployment scenarios.
- AI Analytics:Neural network-based platforms replacing rule-based detection for vehicle type classification and congestion pattern prediction. German transportation authorities are procuring certified systems ahead of EU AI Act enforcement deadlines, creating pull-through demand for algorithmically transparent platforms.
- Machine Learning:Statistical pattern recognition systems for traffic flow optimization and predictive maintenance scheduling.
- Cloud Computing:Centralized processing architectures for historical data aggregation and long-range infrastructure planning analytics.
Cloud computing retains the largest installed base while edge computing expands most quickly as latency requirements harden.
Application:
Customer type concentration varies sharply across use cases, with government procurement dominating smart cities and enforcement while private fleet operators drive commercial telemetry demand.
- Smart Cities:Multi-modal sensor networks integrating vehicular, pedestrian, and public transit flow analytics. Singapore's Land Transport Authority district pilots are validating reference architectures for replication across urban corridors. Municipal buyers are unbundling maintenance from capital expenditure, favoring ten-year availability contracts with uptime penalties exceeding hardware depreciation schedules.
- Traffic Law Enforcement:Automated violation detection and evidence collection systems for speed, red-light, and lane discipline monitoring. California SB 743 compliance is mandating granular vehicle miles traveled metrics, expanding municipal data service contracts for development impact assessments.
- Fleet Management:Commercial vehicle tracking and route optimization platforms for logistics operators.
- Infrastructure Monitoring:Bridge, tunnel, and roadway condition assessment systems for asset lifecycle management.
Smart cities command the deepest margin pools while traffic law enforcement provides the most stable recurring revenue base.
End User:
Maturity differentiation separates legacy-equipped transportation authorities from greenfield deployers, with India National Highways expansion enabling integrated platform deployment without retrofit constraints.
- Government Agencies:Federal and state-level departments of transportation setting procurement specifications and funding allocation priorities. The Federal Highway Administration's MUTCD guidelines shape detection modality approval cycles extending 18-24 months, compressing product launch windows for vendors seeking federal eligibility.
- Transportation Authorities:Regional and municipal operators managing intersection signal control and corridor optimization. Dutch and Singaporean frameworks are pioneering performance-based contracting with uptime penalties, displacing traditional equipment-vendor relationships with systems integrators absorbing operational risk.
- Law Enforcement:Police departments and highway patrol units deploying automated enforcement and incident response capabilities.
- Private Sector:Commercial developers, logistics operators, and insurance providers accessing traffic data for risk assessment and route planning.
Transportation authorities anchor procurement volume while government agencies determine certification requirements that filter vendor eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in traffic monitoring hardware tilt toward net-import dependence in emerging economies while established markets sustain domestic manufacturing bases. Component trade flows concentrate in semiconductor-intensive edge AI modules. Regional procurement patterns diverge sharply between EU regulatory compliance markets and greenfield expansion zones.
United States
The Federal Highway Administration's MUTCD guidelines and California SB 743 vehicle miles traveled mandates are accelerating procurement of granular traffic flow analytics. State DOT specifications in Texas and New York filter vendor eligibility through additional certification layers. The Pacific Northwest corridor deploys thermal imaging for fog-prone incident response.
Germany
Transportation authorities in Germany are procuring EU AI Act-certified detection platforms ahead of enforcement deadlines. KBA vehicle safety standards intersect with algorithmic transparency requirements for automated enforcement systems. The Bavarian smart city corridor validates reference architectures for multi-modal sensor networks.
Singapore
The Land Transport Authority's sensor-dense district pilots are generating replication templates for urban traffic analytics at scale. Ten-year availability contracts with uptime penalties exceeding hardware depreciation displace traditional equipment-vendor relationships. Dense intersection coverage justifies capital-intensive fixed camera installation.
India
The NHAI corridor development program enables greenfield integrated platform deployment without retrofit constraints on legacy signal controllers. BIS certification requirements for intelligent transport systems are formalizing procurement specifications. Maharashtra and Gujarat highway expansions anchor initial demand concentration.
Netherlands
Dutch transportation frameworks pioneer performance-based contracting with systems integrators absorbing operational risk. GDPR-derived data localization mandates fragment cross-border cloud analytics architectures. The Randstad urban corridor deploys edge computing where sub-100-millisecond signal response conflicts with cloud latency.
Traffic Monitoring Market Vendor Landscape
Concentration sits with integrated platform providers who bundle hardware, software, and maintenance under unified contracts. The vendor base spans three tiers: multinational traffic infrastructure specialists, regional signal-control integrators, and component-focused sensor manufacturers. Strategic moves center on algorithmic certification for EU AI Act compliance and long-term service contract capture from municipal buyers unbundling maintenance from capital expenditure.
Within the multinational specialist tier, Kapsch TrafficCom AG and Teledyne FLIR LLC occupy distinct positioning archetypes. Kapsch TrafficCom AG exemplifies the European installed-base player leveraging long-term service relationships. Teledyne FLIR LLC represents thermal imaging specialization for low-visibility detection scenarios. Yunex Traffic sits within the integrated signal-control segment, merging detection hardware with adaptive timing platforms. These three anchors illustrate how competitive differentiation fragments across detection modality, geographic heritage, and bundling depth.
| Leading Market Players |
|---|
| TE Connectivity |
| Miovision Technologies Incorporated |
| Kapsch TrafficCom AG |
| Transcore Inc. |
| Yunex Traffic |
| SWARCO AG |
| Iteris, Inc. |
| Conduent Transportation |
| Teledyne FLIR LLC |
| Others |
Supply Flow & Price Mechanics
TSMC and Samsung foundry capacity utilization above ninety percent is compressing edge AI chip availability and elevating hardware price floors for traffic monitoring OEMs. Municipal procurement cycles extending to ten-year availability contracts absorb this cost pressure through bundled service pricing, while component scarcity filters vendor pools toward systems integrators with captive semiconductor relationships.
Pricing Analysis
Transportation authorities anchor pricing structures through long-term availability contracts that merge hardware depreciation with performance-guaranteed maintenance subscriptions. Price differentiation separates EU AI Act-certified platforms from uncertified alternatives, with algorithmic transparency mandates in Germany and France commanding premium positioning. Cost compression in standard-tier fixed camera systems is intensifying because mobile and sensor-fusion alternatives reduce permanent infrastructure commitment. State DOT procurement officers in California and Texas exhibit highest price sensitivity due to budget cycle constraints, while Singapore Land Transport Authority contracts show lowest sensitivity given uptime penalty structures that exceed hardware costs.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes is extending lead times for GPU-accelerated edge computing modules fabricated in Taiwan and South Korea. Semiconductor supply concentrates in TSMC foundries for inference engines and Samsung for memory components, with raw material dependencies spanning high-purity silicon wafers, rare-earth magnetics for thermal imaging assemblies, and halogen-free flame-retardant compounds facing REACH requalification. Single-source vulnerability in EUV lithography equipment exposes deployment timelines to geopolitical disruption. Distribution runs through systems integrators who absorb operational risk under performance-based contracting frameworks pioneered in Dutch and Singaporean smart city deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act enforcement deadlines are compressing vendor certification windows and accelerating procurement of algorithmically transparent detection platforms across German and French transportation authorities.
For Market Incumbents: Shield installed-base relationships through preemptive EU AI Act certification investment ahead of enforcement deadlines, while absorbing semiconductor cost volatility via backward integration into edge AI chip sourcing. Kapsch TrafficCom AG's European service contract density exemplifies defensible positioning against emerging platform competitors. For New Entrants and Emerging Players: Anchor in India's NHAI corridor expansion where greenfield deployment eliminates legacy signal controller interoperability costs. Target thermal imaging specialization for Pacific Northwest fog-prone corridors as the most penetrable detection modality segment, with go-to-market execution through systems integrator partnerships rather than direct municipal sales cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated platform providers bundling edge sensors with adaptive signal control software. Long-term viability hinges on ten-year service contract capture from transportation authorities unbundling maintenance from capital expenditure. Watch EU AI Act certification completion rates as the inflection signal separating viable acquisition targets from stranded hardware vendors.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Algorithmic transparency mandates in Germany and France filter vendor eligibility ahead of enforcement deadlines. |
| Edge AI Chip Supply Agreement | TSMC and Samsung foundry relationships secure GPU-accelerated roadside unit deployment timelines against geopolitical disruption. |
| Ten-Year Availability Contract Capture | Singapore and Dutch frameworks displace equipment-vendor relationships with systems integrators absorbing operational risk. |
| Thermal Imaging Product Line Extension | Low-visibility detection capabilities penetrate fog-prone corridors in the Pacific Northwest and Alpine regions. |
| India Greenfield Deployment Partnership | NHAI corridor development enables integrated platform installation without legacy NTCIP protocol integration costs. |
Methodological Framework
Operator-level perspectives from transportation authority procurement officers, systems integrator program managers, edge AI hardware engineers, and municipal traffic operations directors anchored the qualitative base. Primary interviews combined with secondary validation against Federal Highway Administration MUTCD guidelines, EU AI Act regulatory filings, Singapore Land Transport Authority procurement disclosures, and BIS intelligent transport system certification records. Bottom-up unit deployment estimates triangulated against top-down infrastructure spending allocations across the analysis window.
Sensitivity analysis tested forecast robustness across edge AI chip supply scenarios and regulatory compliance timeline variations. Segmentation dimensions modeled include product architecture, technology tier, application use case, and end-user procurement authority, with regional adoption patterns capturing EU AI Act enforcement, California SB 743 VMT mandates, and India NHAI expansion trajectories. CAGRs derived from S-curve penetration modeling against smart city infrastructure investment cycles, with edge computing deployment velocity and thermal imaging adoption curves as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained semiconductor supply concentration and EU AI Act enforcement adherence; material deviation would warrant model refresh. Forecasts reflect base-case infrastructure spending continuity and regulatory timeline adherence, with semiconductor supply disruption or algorithmic accountability litigation representing specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Global Smart Parking Market
Smart Transportation Solutions
North America Vehicle Tolling System Market
Smart Transportation Solutions
Road Weather Information Systems (RWIS) Market
Smart Transportation Solutions
Indonesia Ride Hailing Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Global Parking Meter Apps Market
Smart Transportation Solutions
Vehicle As a Service Market
Smart Transportation Solutions
Car Sharing Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
E-Bike Rental Market