
 Wire Mooring Ropes Market | 2026-2036
Wire Mooring Ropes Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Mooring Ropes Market Insights
Offshore platform operators is reorganizing the buyer landscape for wire mooring ropes as floating production storage and offloading vessels multiply in deepwater basins. WireCo WorldGroup leverages integrated steel wire and synthetic rope manufacturing to serve both legacy platform retrofits and next-generation floating wind moorings. Katradis Marine Ropes Industry anchors its position through specialized synthetic-fiber braiding capabilities tailored to Greek and Mediterranean shipping channels. Bridon-Bekaert Ropes Group competes on metallurgical consistency across high-carbon steel wire grades demanded by North Sea certification regimes.
Wire mooring ropes are engineered tensile systems combining stranded steel wires, synthetic high-modulus fibers, or hybrid constructions designed to secure floating structures against hydrodynamic loading, with break strengths typically ranging from 500 to 12,000 kilonewtons depending on diameter and material class. Their primary purpose is to maintain positional stability of vessels, platforms, and marine installations under variable sea states, wind shear, and tidal currents. Steel wire rope retains dominance in permanent offshore mooring where creep resistance and thermal tolerance outweigh weight penalties, while synthetic rope captures specification share in temporary vessel mooring and deepwater floating wind applications where handling efficiency and corrosion immunity reduce lifecycle cost. Composite rope occupies a narrow but expanding niche bridging the fatigue-performance gap in hybrid platform configurations.
DNV classification rules, API RP 2SK mooring design guidelines, and ISO 2307 fiber-rope testing standards collectively govern product qualification, installation protocol, and in-service inspection intervals across major offshore jurisdictions. These frameworks elevate barrier to entry by mandating third-party witnessed break testing and traceable manufacturing records, effectively filtering out uncertified suppliers from permanent installation contracts. Stakeholders must monitor evolving floating wind mooring specifications as classification societies draft dedicated standards for multi-line shared-anchor arrays.
Market Dynamics
Deepwater floating production systems are forcing specification upgrades across permanent mooring installations as operators push into harsher metocean environments. Classification societies are tightening break-load certification thresholds while synthetic-fiber technology matures, creating parallel demand tracks for steel wire and high-modulus fiber systems.
Growth Catalysts
- Floating wind pilot programs:North Sea and Norwegian basin developers are procuring hybrid mooring arrays for multi-turbine platforms, generating first-of-kind demand for fatigue-optimized rope configurations.
- DNV-RP-C203 fatigue standards:Updated guidance on spectral fatigue analysis for mooring lines is mandating enhanced inspection protocols that favor suppliers with integrated testing capabilities.
- Pre-salt basin expansion:Brazilian offshore operators are replacing aged wire rope on existing FPSO fleets while commissioning new units for Búzios and Mero field developments.
Market Restraints
- High-carbon steel wire volatility:Scrap metal price swings and European energy costs are compressing margin structures for steel wire rope manufacturers serving North Sea certification regimes.
- Synthetic fiber supply concentration:Ultra-high molecular weight polyethylene fiber production clusters in the Netherlands and United States, creating single-source vulnerability for deepwater synthetic mooring procurement.
- API RP 2SK compliance timelines:Extended third-party witnessed break testing and documentation requirements are extending qualification cycles for new rope constructions.
Strategic Opportunities
- Floating offshore wind in South Korea:Ulsan and Busan development zones are specifying shared-anchor multi-line arrays that reward suppliers with hybrid steel-synthetic design capabilities.
- Green hydrogen platform moorings:Offshore electrolyzer installations in the North Sea will require static mooring systems with 25-year design lives and minimal maintenance access.
- Digital twin integration:Real-time tension monitoring combined with predictive fatigue algorithms is enabling performance-guaranteed service contracts that shift revenue from product to outcome.
Industry Challenges
- Certified welding technician scarcity:Steel wire rope socket fabrication requires DNV-qualified welders, with training pipelines failing to match North Sea and West Africa project ramp rates.
- Legacy platform integration:Retrofitting synthetic rope into existing steel wire fairlead systems demands custom termination engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Mooring Ropes Market |
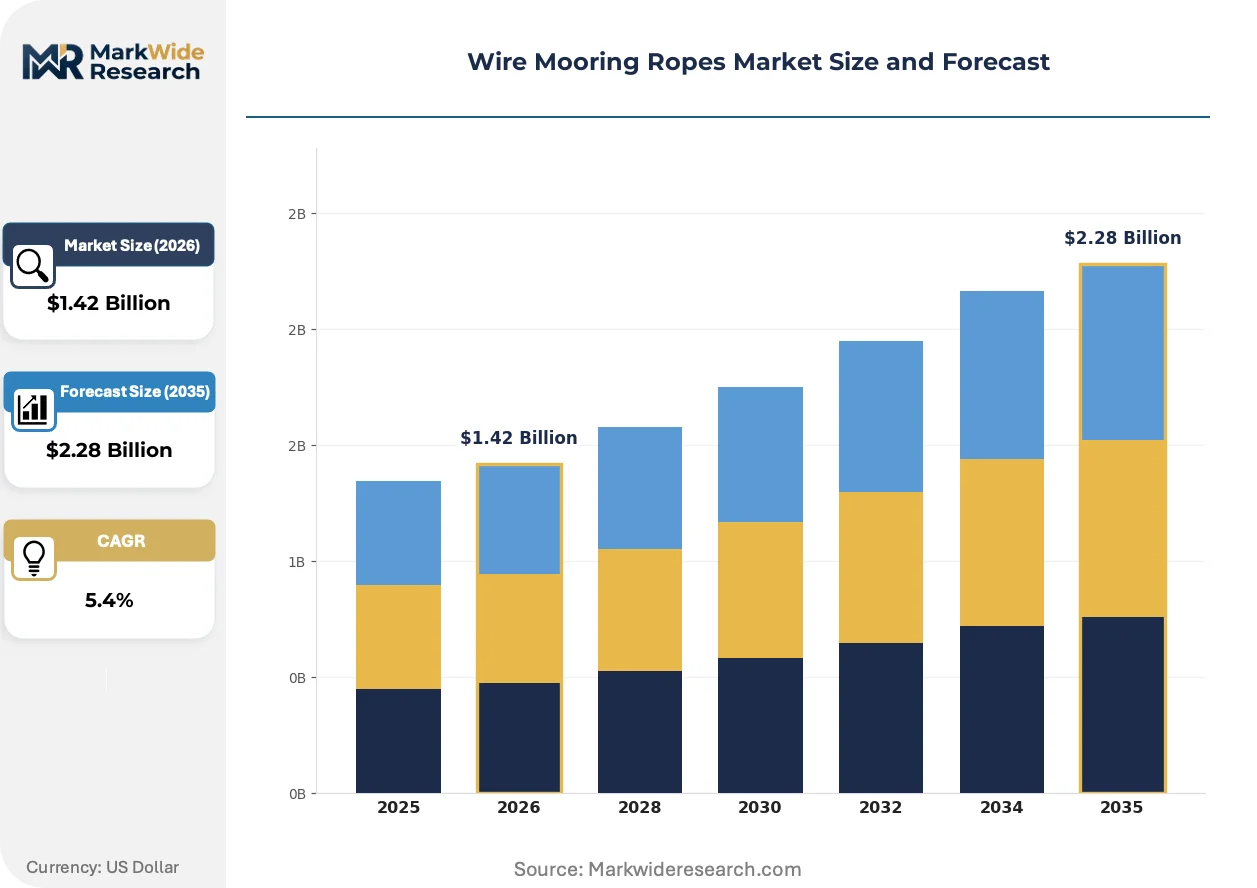
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Wire, Synthetic Rope, Composite Rope, Chain End User: Shipping Companies, Offshore Platforms, Marine Services, Fishing Fleets Application: Shore Mooring, Vessel Mooring, Port Operations, Anchoring Size: Small, Medium, Large, Extra Large |
| Companies Covered | WireCo WorldGroup, Katradis Marine Ropes Industry, Teufelberger, Lankhorst Ropes, Bridon-Bekaert Ropes Group, Cortland Limited, Dynamica Ropes, Marlow Ropes Ltd., Pfeifer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Mooring Ropes Market Trends and Innovations
Material science advances and digitalization are restructuring how mooring systems are specified, procured, and maintained across offshore basins. Three developments are reshaping competitive positioning.
High-modulus polyethylene fiber is bifurcating the deepwater mooring market. The material delivers corrosion immunity and handling efficiency at depths exceeding 1,500 meters. Petrobras and Equinor are specifying HMPE for temporary drilling unit moorings and pilot floating wind installations. Steel wire retains permanent platform share where thermal tolerance and creep resistance outweigh weight penalties, compressing synthetic adoption to mobile and renewable segments.
REACH substance restrictions on zinc-based coating chemistries are forcing metallurgical reformulation across European-sourced wire rope. Manufacturers are migrating to aluminum-zinc and polymer-matrix alternatives that maintain salt-spray performance without SVHC classification. North Sea operators are absorbing 8-12% material cost premiums to maintain CE-marked supply chains and avoid installation delays at Norwegian and UK ports.
Integrated mooring monitoring is displacing calendar-based inspection regimes. Tension-leg platform operators in the Gulf of Mexico and West Africa are procuring sensor-embedded rope with fiber-optic strain sensing that triggers condition-based replacement rather than fixed-interval swaps. This compresses aftermarket revenue for replacement rope while expanding long-term service contract attach rates for system integrators with offshore technician networks.
Wire Mooring Ropes Market Segmentation
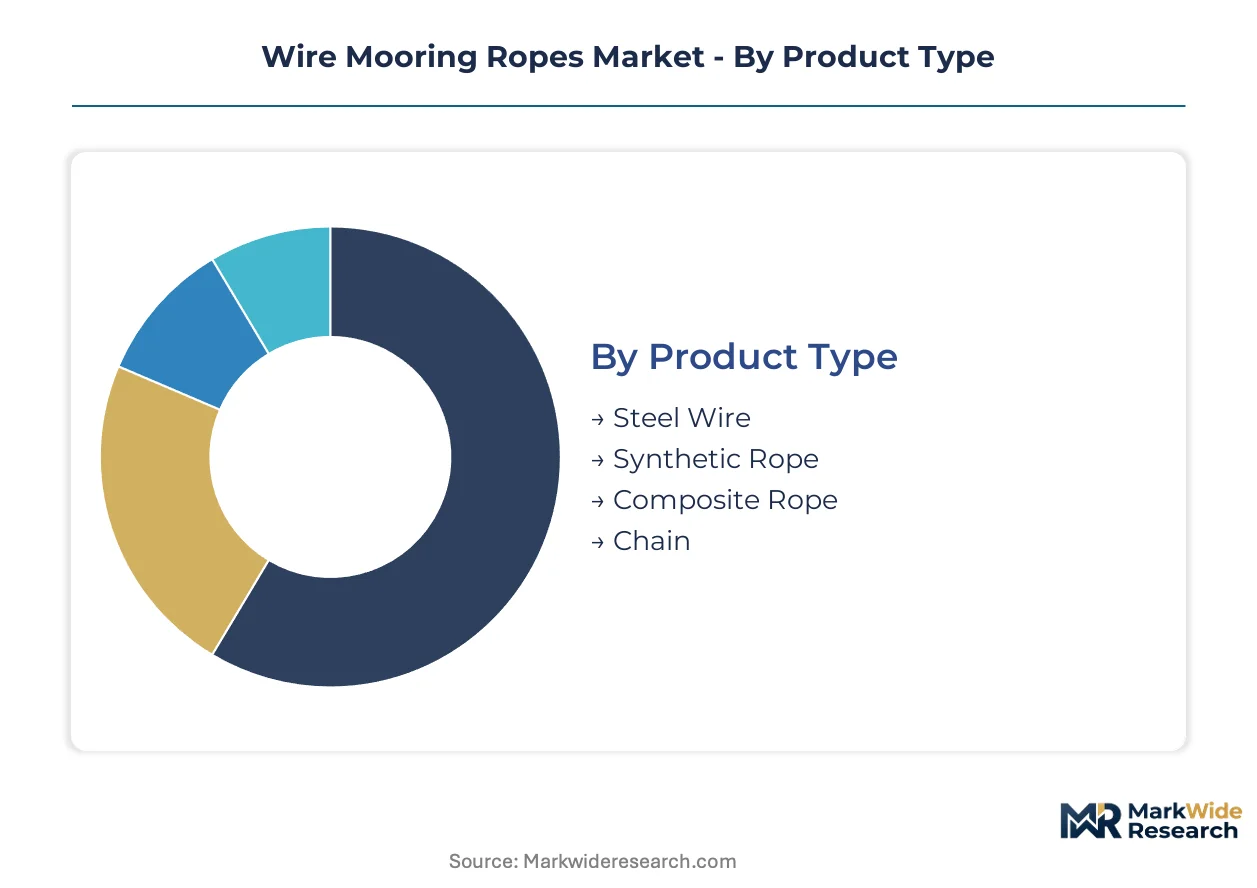
Wire mooring rope procurement splits across material technologies, operational environments, and structural scale requirements. Each dimension carries distinct certification burdens and lifecycle economics that reshape supplier priorities across offshore basins.
Product Type:
Steel wire faces substitution pressure from high-modulus synthetics in deepwater floating wind and mobile drilling applications, though permanent platform moorings resist material switching due to creep resistance requirements.
- Steel Wire:Stranded high-carbon steel constructions deliver creep resistance and thermal tolerance for permanent FPSO moorings in Brazilian pre-salt and North Sea basins. DNV break-load certification mandates and socket welding complexity favor established manufacturers with integrated metallurgical control.
- Synthetic Rope:Ultra-high molecular weight polyethylene and aramid fiber systems capture specification share in floating wind pilot arrays and temporary drilling unit moorings where handling efficiency and corrosion immunity offset higher unit costs. South Korean Ulsan developers specify HMPE for shared-anchor multi-line configurations.
- Composite Rope:Hybrid steel-synthetic constructions bridge fatigue-performance gaps in tension-leg platform retrofits and hybrid platform configurations.
- Chain:Stud-link and studless chain retain anchor segment dominance where mass and abrasion resistance outweigh deployment speed considerations.
Steel wire anchors the volume base while synthetic rope gains share at the steepest rate.
End User:
Cost tier differentiation separates capital-intensive offshore operators with 25-year design life requirements from merchant shipping fleets prioritizing replacement speed and procurement flexibility.
- Shipping Companies:Container and bulk carriers favor quick-deploy synthetic lines for routine port calls, with procurement decisions driven by charterer specifications and P&I club loss-prevention guidelines.
- Offshore Platforms:FPSO and semi-submersible operators mandate third-party witnessed break testing and traceable manufacturing records under API RP 2SK and DNV classification rules, filtering out uncertified suppliers from permanent installation contracts.
- Marine Services:Tug operators and salvage contractors require rapid rope replacement capabilities and modular termination systems for variable fleet deployment.
- Fishing Fleets:Trawler and longline operators prioritize abrasion resistance and salt-spray performance in deck handling applications with shorter capital recovery horizons.
Offshore platforms command the premium tier while shipping companies drive replacement volume.
Application:
Volume concentration in vessel mooring reflects merchant fleet scale, while anchoring applications carry the most stringent fatigue certification requirements.
- Shore Mooring:Fixed dolphins and bollard systems in Greek and Mediterranean shipping channels specify corrosion-resistant wire with aluminum-zinc coatings to satisfy REACH substance restrictions on legacy zinc chemistries.
- Vessel Mooring:Routine port operations across Brazilian Santos basin and Norwegian supply bases generate recurring demand for medium-diameter lines with standardized termination fittings.
- Port Operations:Automated mooring systems in Busan and Rotterdam terminals require sensor-embedded rope with fiber-optic strain sensing for condition-based maintenance protocols.
- Anchoring:Permanent pre-laid mooring arrays for floating production systems demand spectral fatigue analysis under DNV-RP-C203 guidelines with 25-year design life guarantees.
Vessel mooring generates the highest transaction frequency while anchoring commands the longest contract durations.
Size:
Supply concentration in large-diameter rope reflects specialized braiding equipment requirements and extended qualification cycles for new constructions.
- Small:Fishing fleet and small-craft applications favor standardized coils with quick-turn procurement through marine distributors.
- Medium:General cargo and coastal shipping segments dominate this tier with specification diversity across flag-state inspection regimes.
- Large:Deepwater FPSO mooring lines in the 2,000-6,000 kilonewton break strength range require custom socket fabrication by DNV-qualified welders, with training pipelines failing to match North Sea and West Africa project ramp rates.
- Extra Large:Multi-line shared-anchor arrays for floating wind platforms exceed 10,000 kilonewton specifications, with first-of-kind demand concentrated in North Sea and Norwegian basin pilot developments.
Large diameter ropes concentrate supplier margins while extra large segments show the steepest specification expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore platform operators in Norway, Brazil, and the United States command the dominant procurement volumes for high-performance mooring systems, with floating production expansion and floating wind pilot programs reshaping regional demand patterns.
Norway
Equinor's floating wind developments in the Norwegian basin are driving first-of-kind demand for hybrid steel-synthetic mooring arrays. DNV classification rules on break-load certification and spectral fatigue analysis under DNV-RP-C203 are tightening supplier qualification thresholds. Stavanger and Bergen clusters concentrate engineering procurement for North Sea pre-salt tiebacks and Hywind Tampen extensions.
Brazil
Petrobras is replacing aged wire rope on existing FPSO fleets while commissioning new units for Búzios and Mero field developments in the pre-salt basin. ANVISA and the national petroleum regulator enforce third-party witnessed break testing for permanent mooring installations. Rio de Janeiro and São Paulo states anchor the procurement decision-making for deepwater floating production systems.
United States
Gulf of Mexico tension-leg platform operators are procuring sensor-embedded rope with fiber-optic strain sensing for condition-based maintenance protocols. API RP 2SK mooring design guidelines and US Coast Guard inspection regimes govern product qualification and in-service intervals. Houston and New Orleans serve as the primary procurement hubs for deepwater drilling unit and platform mooring specifications.
United Kingdom
Aging North Sea platform infrastructure and Dogger Bank floating wind pilot projects are simultaneously driving replacement and specification upgrades. REACH substance restrictions on zinc-based coating chemistries are forcing metallurgical reformulation across European-sourced wire rope. Aberdeen and Great Yarmouth clusters concentrate offshore supply base activity for hybrid mooring system deployment.
South Korea
Ulsan and Busan development zones are specifying shared-anchor multi-line arrays for floating offshore wind installations. MFDS and the national maritime safety regulator oversee certification requirements for permanent mooring systems in Korean waters. The Ulsan metropolitan area anchors domestic manufacturing and engineering procurement for deepwater synthetic rope specifications.
Wire Mooring Ropes Market Competitive Landscape
Player mix skews toward integrated steel wire and synthetic fiber specialists with third-party certification capabilities. Market structure concentrates around established manufacturers with DNV-qualified welding technicians and traceable manufacturing records. Three archetypes dominate: integrated wire-to-rope conglomerates with metallurgical control, specialized synthetic-fiber braiders with corrosion-immune product lines, and hybrid system integrators with digital monitoring attach rates. Competitive moves center on capacity expansion for large-diameter braiding equipment and strategic partnerships with floating wind developers.
Within the integrated conglomerate tier, WireCo WorldGroup and Bridon-Bekaert Ropes Group occupy positions defined by steel wire manufacturing scale and North Sea certification regime compliance. Katradis Marine Ropes Industry represents the specialized synthetic-fiber braider archetype, with geographic positioning tied to Mediterranean and Greek shipping channel demand. Teufelberger sits within the premium-tier vector, exemplifying Austrian GmbH-structured manufacturing with fiber rope and steel wire hybrid capabilities. These three anchors illustrate how supplier positioning fragments across material technology specialization and regional certification proximity.
| Leading Market Players |
|---|
| WireCo WorldGroup |
| Katradis Marine Ropes Industry |
| Teufelberger |
| Lankhorst Ropes |
| Bridon-Bekaert Ropes Group |
| Cortland Limited |
| Dynamica Ropes |
| Marlow Ropes Ltd. |
| Pfeifer Group |
| Others |
Pricing and Supply Chain Analysis
High-modulus polyethylene fiber substitution for steel wire in deepwater floating wind moorings simultaneously shifts procurement geography toward Dutch and US fiber production clusters and compresses margin structures for European steel wire manufacturers facing energy cost volatility.
Pricing Analysis
Cost-plus contracts with steel scrap indexation dominate steel wire rope procurement for North Sea FPSO operators. Price differentiation separates DNV-certified permanent installation grades from temporary vessel mooring specifications, with certification tier and socket welding complexity as primary drivers. Cost compression in steel wire tiers is intensifying because European energy costs and scrap metal volatility squeeze manufacturer margins. Offshore platform operators show the least price sensitivity due to 25-year design life requirements, while merchant shipping fleets prioritize replacement speed over performance premiums.
Supply Chain Analysis
Strategic stockpiling of ultra-high molecular weight polyethylene fiber by South Korean floating wind developers contrasts with just-in-time steel wire procurement by North Sea platform operators. Supply concentrates in the Netherlands and United States for HMPE fiber, Belgium and Germany for high-carbon steel wire, and Greece for Mediterranean synthetic rope distribution. Raw material dependencies include scrap steel, petroleum-derived polyethylene, and aramid polymers. Single-source vulnerability in HMPE fiber production creates supply chain risk for deepwater synthetic mooring procurement. Distribution runs through offshore supply bases in Stavanger, Aberdeen, and Houston for certified installation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floating offshore wind classification standards represent a regulatory inflection that will bifurcate supplier viability between hybrid-capable integrators and single-material specialists.
For Market Incumbents: Secure DNV-qualified welding technician pipelines through apprenticeship partnerships with Norwegian technical institutes to address certified fabricator scarcity threatening North Sea project ramp rates. Backward integration into high-carbon steel wire production insulates margin pressure from European scrap and energy cost volatility. Synthetic rope entrants with HMPE braiding capabilities threaten permanent platform share unless steel wire suppliers develop hybrid steel-synthetic design competencies. For New Entrants and Emerging Players: Digital twin integration services for real-time tension monitoring represent a service-layer gap where incumbents under-serve with product-centric revenue models. Target South Korean Ulsan and Busan floating wind zones specifying shared-anchor multi-line arrays that reward hybrid design capabilities over legacy steel wire certification. Partner with sensor-embedded rope manufacturers to bundle predictive fatigue algorithms with installation contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed steel wire specialists lacking synthetic fiber braiding capabilities or digital monitoring attach rates. Five-to-ten-year viability hinges on classification society adoption of dedicated floating wind mooring standards that favor hybrid suppliers. Monitor DNV-RP-C203 fatigue standard revisions as the signal indicating accelerated specification turnover toward integrated testing and monitoring capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Steel-Synthetic Rope Development | Equinor and South Korean floating wind specifications reward suppliers bridging material fatigue-performance gaps. |
| DNV-Qualified Welder Training Pipeline | Socket fabrication certification scarcity constrains North Sea and West Africa project delivery capacity. |
| Sensor-Embedded Rope Manufacturing | Gulf of Mexico tension-leg operators procure fiber-optic strain sensing for condition-based replacement protocols. |
| REACH-Compliant Coating Reformulation | Aluminum-zinc and polymer-matrix alternatives maintain salt-spray performance without SVHC classification delays. |
| Shared-Anchor Multi-Line Array Engineering | Busan and Ulsan development zones specify configurations exceeding 10,000 kilonewton break strengths. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with FPSO procurement managers, DNV certification engineers, synthetic fiber R&D directors, and offshore supply base operators; and secondary validation through API RP 2SK documentation, DNV classification rule updates, customs trade data for steel wire and HMPE fiber, and SEC filings from listed marine equipment manufacturers. Bottom-up rope demand modeling by diameter class and break strength tier triangulated against top-down offshore platform capex forecasts.
Across the analysis window, value and volume projections incorporate material substitution elasticity between steel wire and synthetic fiber, certification lag effects for new rope constructions, and regional floating wind procurement timelines. Segmentation dimensions include material technology, end-user cost tier, application fatigue requirement, and diameter class. CAGRs derive from project-level mooring line specifications and replacement cycle analysis for aging North Sea infrastructure.
Forecasts assume regulatory continuity in DNV, API, and ISO mooring standards; material policy shifts such as expanded REACH substance restrictions or new floating wind certification regimes would require re-modeling. Revision becomes warranted when synthetic fiber production capacity expansion crosses thresholds that enable permanent platform substitution at scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market
Maritime Equipment
Saudi Arabia Offshore Support Vessel (OSV) Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Ship Plate Market
Maritime Equipment
Hong Kong Stevedoring and Marine Cargo Handling Market