
 Middle East Offshore Support Vessels Market | 2026-2036
Middle East Offshore Support Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Offshore Support Vessels Market Foresight
Buyer concentration among national oil companies is hardening across the Middle East offshore support vessel sector. ADNOC Logistics & Services leverages its captive demand from Abu Dhabi's upstream operations to dominate local charter volumes. Tidewater Inc. sustains a competitive position through its specialized AHTS fleet deployed across Saudi and Qatari fields. Maersk Supply Service anchors its regional presence with DP-3 capable vessels serving deepwater exploration contracts.
Offshore support vessels are purpose-built marine craft typically measuring 50-120 meters in length, equipped with dynamic positioning systems and deck cargo capacities exceeding 1,000 tonnes, designed to transport personnel, supplies, and equipment to offshore oil, gas, and renewable energy installations. The AHTS segment leads regional fleet utilization due to sustained anchor-handling demand from fixed-platform installations in Qatari and Saudi waters. PSV categories compete on fuel efficiency as charterers scrutinize operating costs amid volatile day-rate environments. Hybrid technology installations are accelerating fastest within the DP-2 and DP-3 classes, driven by charterer emissions requirements and port authority environmental compliance mandates.
ADNOC's marine standards, Saudi Aramco's offshore safety protocols, and the UAE's Federal Transport Authority collectively shape vessel specifications, crew certification thresholds, and environmental compliance benchmarks across the Middle East. The International Maritime Organization's carbon intensity regulations further constrain fleet eligibility for international operators serving regional national oil companies. Stakeholders must monitor charterer fleet modernization timelines and regulatory alignment between Gulf Cooperation Council maritime authorities to anticipate vessel replacement cycles and technology upgrade obligations.
Market Dynamics
Charterer consolidation among Arabian Gulf national oil companies is compressing the supplier base and mandating fleet-wide dynamic positioning upgrades. ADNOC, Saudi Aramco, and QatarEnergy now specify DP-2 or DP-3 capability as minimum entry thresholds for new vessel contracts.
Growth Catalysts
- SFDA marine safety mandates:Saudi Arabia's tightened vessel certification standards are forcing fleet modernization and creating replacement demand for older tonnage.
- Fixed-platform installation density:Sustained anchor-handling requirements from Qatar's North Field and Saudi Arabia's Marjan complex sustain AHTS utilization rates.
- Hybrid propulsion systems:Battery-hybrid installations in DP-2 and DP-3 classes are accelerating as charterers impose emissions clauses in long-term contracts.
Market Restraints
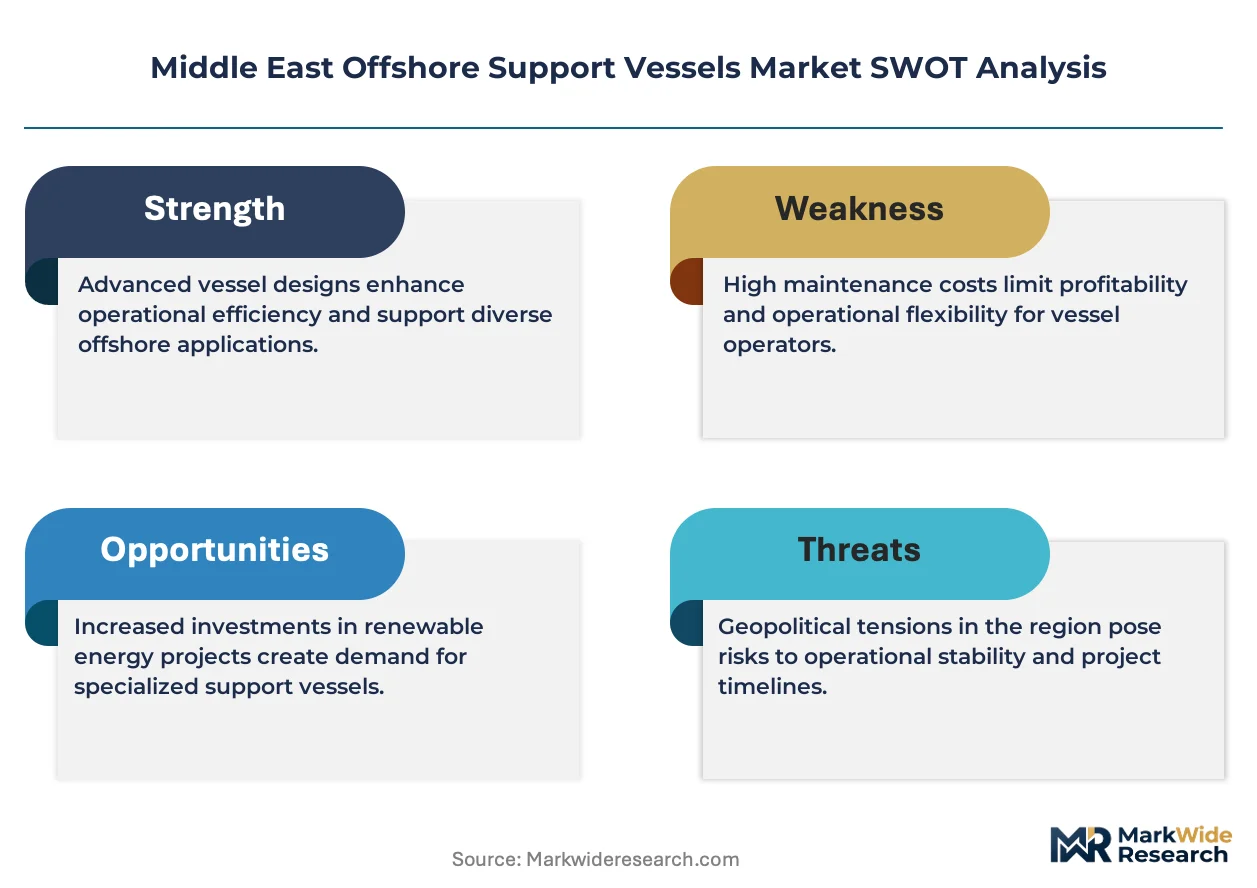
- Steel and marine equipment input volatility:Hull construction costs fluctuate with global steel pricing, compressing newbuild margins for regional yards.
- Fleet ownership concentration:A handful of UAE and Saudi-based operators control contracted vessel availability, limiting new entrant access to term charters.
- Dynamic positioning system technical limitations:DP-3 redundancy requirements demand specialized engineering expertise scarce in regional shipyards.
Strategic Opportunities
- Qatar's North Field expansion:Uncontracted vessel demand from this megaproject offers white space for operators with available DP-3 tonnage.
- Offshore wind support applications:Crew transfer vessel specifications from European developers are migrating to Gulf feasibility studies.
- Abu Dhabi port electrification mandates:Shore power requirements at Khalifa Port and Zayed Port are accelerating battery-hybrid retrofit orders.
Industry Challenges
- DP-3 systems engineering talent scarcity:Specialized automation and redundancy design skills are concentrated among European and Asian technical consultancies.
- SFDA and MOHAP certification timeline compression:Parallel safety approvals across Saudi and UAE jurisdictions extend vessel entry-to-service intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Offshore Support Vessels Market |
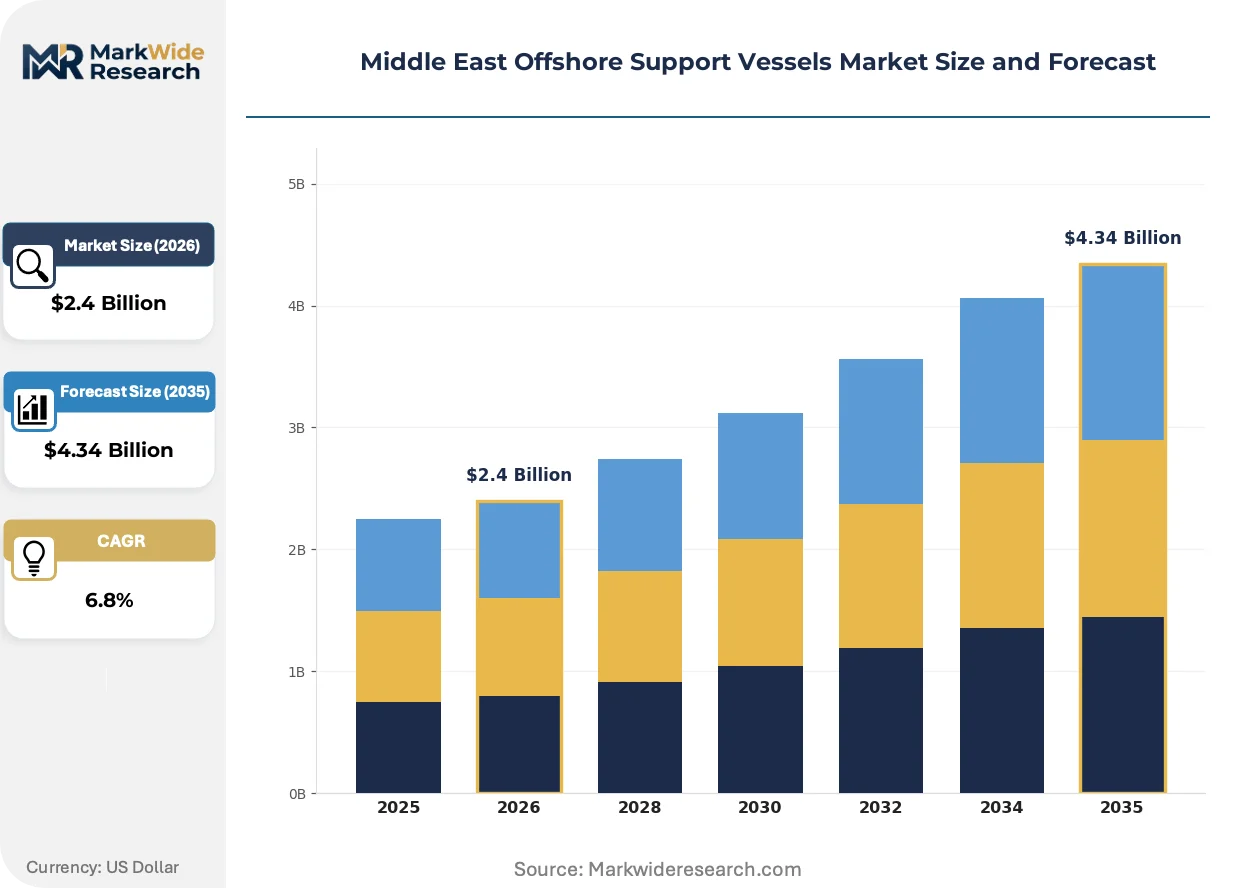
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: AHTS, PSV, OCV, DSV Service Type: Transport, Maintenance, Supply, Logistics End User: Oil & Gas, Renewable Energy, Mining, Fisheries Technology: DP-2, DP-3, Conventional, Hybrid |
| Companies Covered | Bourbon Corporation SA, P&O Maritime Logistics, Tidewater Inc., Offshore International (OFCO), Zakher Marine, ADNOC Logistics & Services, Zamil Offshore Services, Baltic Marine Services LLC, Maersk Supply Service, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Offshore Support Vessels Market Shifts & Advancements
Fleet decarbonization imperatives are colliding with charterer consolidation to reshape vessel specifications and contract structures across the Arabian Gulf. Technology roadmaps now prioritize emissions compliance alongside station-keeping reliability.
Battery-hybrid propulsion architectures are overtaking conventional diesel-mechanical systems in newbuild specifications. ADNOC and Saudi Aramco now embed emissions-reduction clauses in five-year charter agreements. This technology is overtaking standard configurations in the DP-2 and DP-3 segments, compressing residual values of non-hybrid tonnage.
MOHAP's environmental compliance mandates for vessels operating in UAE federal waters are tightening discharge and emissions thresholds. The regulations force charterers to reject older tonnage lacking exhaust after-treatment or shore-power compatibility. PSV operators serving Abu Dhabi's offshore cluster are responding fastest, accelerating fleet renewal cycles.
Term charter contracting is displacing spot-market fixtures as the dominant procurement mode among Arabian Gulf national oil companies. Master service agreements with fleet operators now span three to five years, squeezing independent vessel owners from premium rate tiers. This pattern is most visible in Saudi Aramco's Long Term Agreement program, where pre-qualified vessel pools secure exclusive deployment rights.
Middle East Offshore Support Vessels Market Segmentation
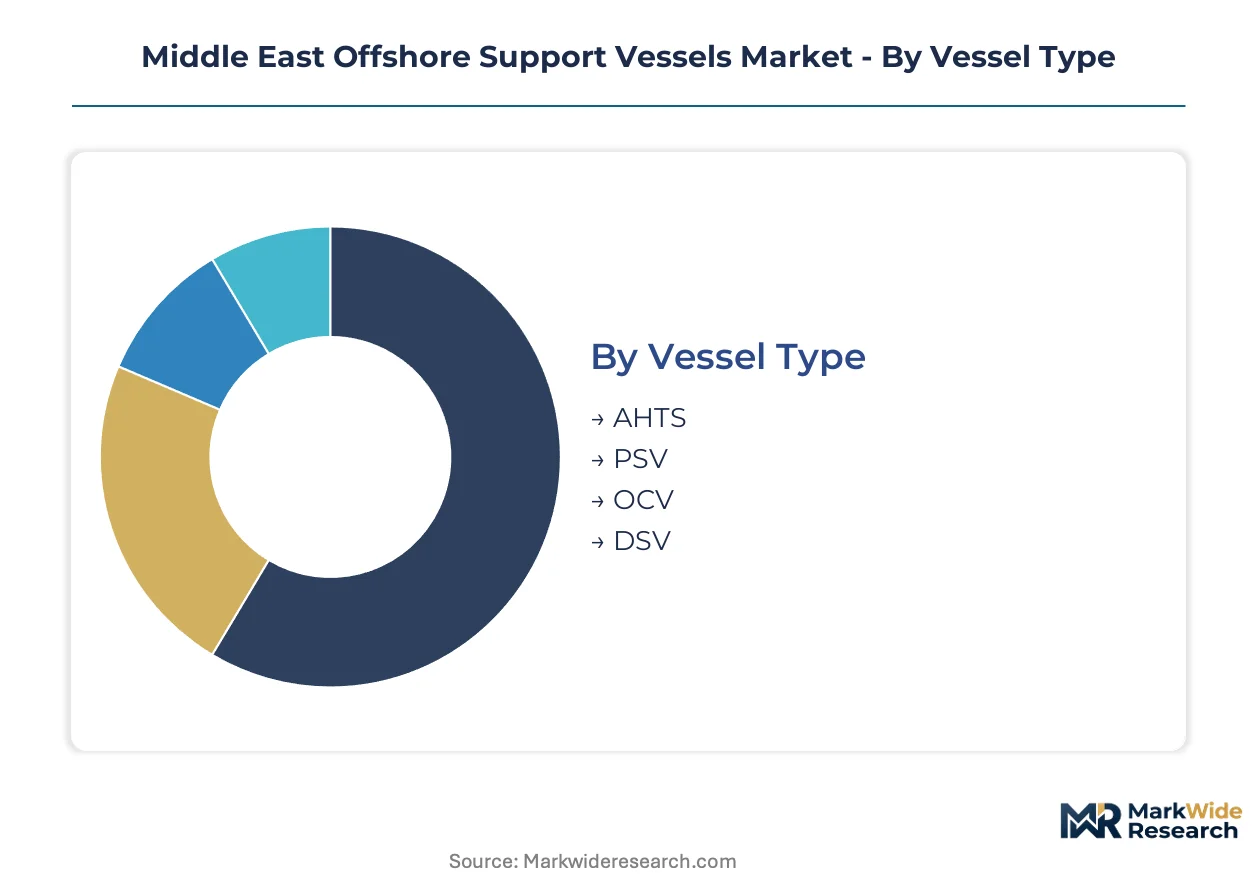
Offshore support vessel procurement across the Middle East Arabian Gulf follows distinct technical and operational hierarchies. Charterer specifications from ADNOC, Saudi Aramco, and QatarEnergy create tiered demand patterns that segment fleet deployment by capability class and service intensity.
Vessel Type:
Standardization dominates hull architecture while dynamic positioning sophistication drives customization premiums across this category.
- AHTS:Anchor-handling tug supply vessels integrate winch systems rated above 400 tonnes bollard pull with fire-fighting Class 1 notation. Qatar's North Field expansion and Saudi Arabia's Marjan complex sustain term charter demand for AHTS fleets with DP-2 redundancy.
- PSV:Platform supply vessels emphasize deck cargo density and fuel efficiency optimization. Abu Dhabi's offshore cluster consumes the largest PSV volumes as ADNOC Logistics & Services replaces older tonnage with hybrid-ready specifications.
- OCV:Offshore construction vessels support subsea installation campaigns with heavy-lift crane integration.
- DSV:Diving support vessels carry saturation diving systems for inspection and repair work on fixed platforms.
Leading the category by volume: PSV. Growing fastest: AHTS.
Service Type:
Revenue stability concentrates in long-term logistics contracts versus volatile spot-market maintenance call-outs.
- Transport:Personnel and cargo transfer operations require high reliability metrics with 99% schedule adherence thresholds. UAE federal waters see the densest transport vessel deployment around Abu Dhabi's Upper Zakum and Lower Zakum fields.
- Maintenance:Subsea intervention and platform upkeep services command premium day-rates tied to technician certification levels. Saudi Aramco's offshore safety protocols mandate specific maintenance vessel configurations for its Long Term Agreement program.
- Supply:Provisioning runs to fixed installations operate on fixed-schedule contracts with penalty clauses for delay.
- Logistics:Integrated supply chain management spans warehousing through last-mile offshore delivery.
Transport commands the largest contract value. Maintenance shows the steepest expansion trajectory as platform aging accelerates across Qatari and Saudi waters.
End User:
Capital deployment intensity separates hydrocarbon extraction from emerging offshore wind feasibility studies.
- Oil & Gas:National oil companies anchor procurement volumes with multi-year master service agreements. ADNOC, Saudi Aramco, and QatarEnergy collectively specify vessel requirements exceeding regional fleet replacement rates.
- Renewable Energy:European offshore wind developers are piloting crew transfer vessel specifications in Gulf feasibility studies. Abu Dhabi's port electrification mandates at Khalifa Port accelerate battery-hybrid compatibility requirements for future renewable logistics.
- Mining:Seabed mineral exploration generates intermittent demand for specialized survey vessel support.
- Fisheries:Artisanal and industrial fishing operations utilize smaller support craft outside NOC-contracted fleets.
Oil & Gas dominates absolute vessel demand. Renewable Energy is climbing the fastest as Gulf states diversify generation portfolios.
Technology:
DP certification tiers function as market entry barriers with DP-3 capability capturing premium contract tiers.
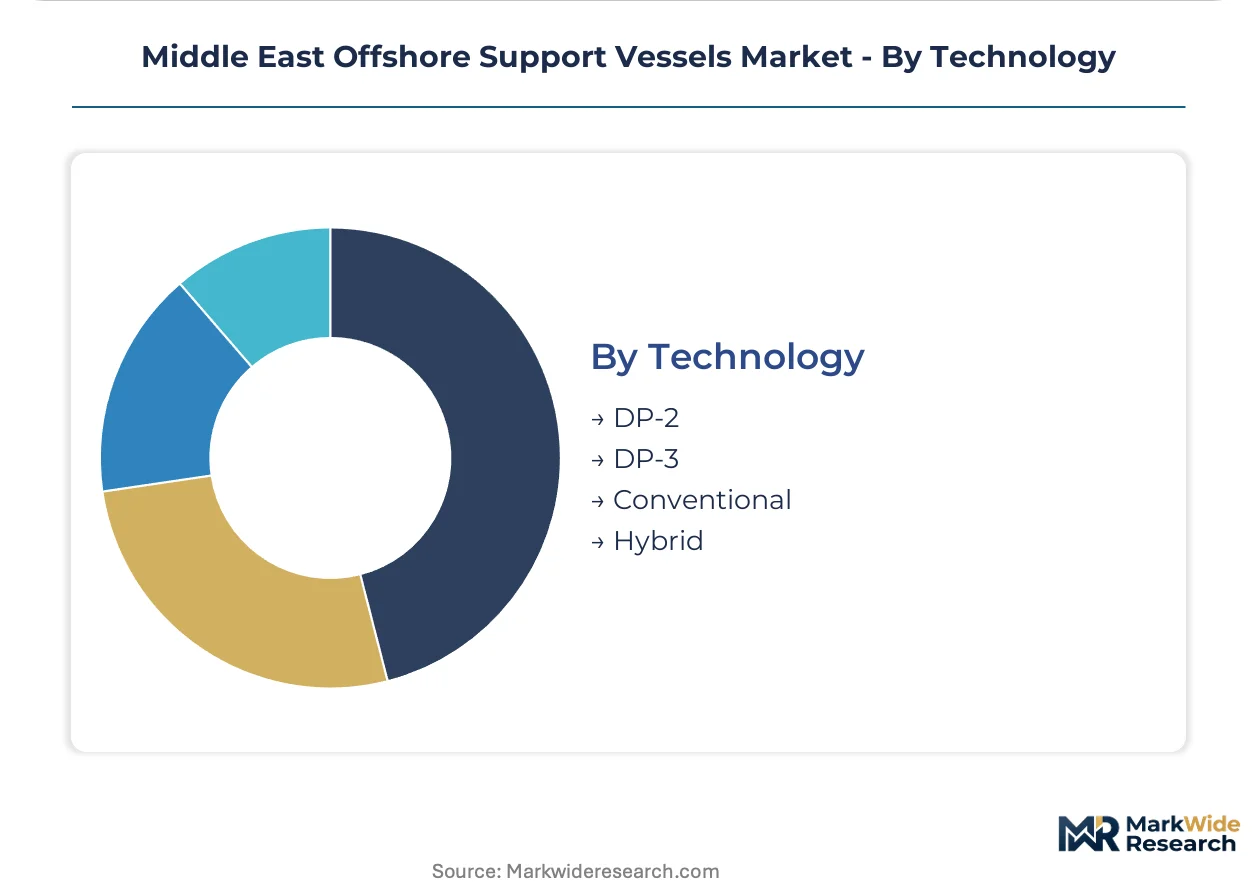
- DP-2:Dual-redundant dynamic positioning systems satisfy minimum entry thresholds for most Arabian Gulf term charters. SFDA marine safety mandates and MOHAP environmental compliance rules are accelerating DP-2 fleet modernization timelines.
- DP-3:Triple-redundant station-keeping with separated machinery spaces enables operations in proximity to live hydrocarbon infrastructure. QatarEnergy's North Field expansion creates uncontracted demand for available DP-3 tonnage.
- Conventional:Non-dynamically positioned vessels serve nearshore logistics with reduced technical complexity.
- Hybrid:Battery-hybrid propulsion architectures are overtaking diesel-mechanical configurations in newbuild specifications.
DP-2 leads fleet utilization by hull count. Hybrid technology is gaining share fastest as charterer emissions clauses harden across five-year agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Arabian Gulf national oil companies concentrate vessel demand through multi-year master service agreements. ADNOC, Saudi Aramco, and QatarEnergy collectively specify requirements exceeding regional fleet replacement capacity. Port electrification mandates and tightened safety certifications are reshaping vessel eligibility across coastal jurisdictions.
United Arab Emirates
ADNOC's Upper Zakum and Lower Zakum fields drive concentrated PSV demand through Abu Dhabi's offshore cluster. MOHAP environmental compliance mandates tighten discharge thresholds for vessels operating in federal waters. Khalifa Port and Zayed Port shore-power installations accelerate battery-hybrid retrofit orders among contracted operators.
Saudi Arabia
SFDA marine safety protocols mandate DP-2 or DP-3 capability as minimum entry for new vessel contracts. The Marjan complex and Long Term Agreement program compress supplier access to premium charter tiers. Dammam and Jubail industrial zones host maintenance yards serving Aramco's offshore safety specifications.
Qatar
QatarEnergy's North Field expansion generates uncontracted demand for available DP-3 tonnage. Anchor-handling requirements from fixed-platform density sustain AHTS utilization rates above regional averages. Ras Laffan industrial city anchors vessel mobilization for subsea installation campaigns.
Kuwait
Kuwait Oil Company offshore development plans are expanding exploration drilling in northern territorial waters. The country's maritime authority is aligning certification standards with GCC safety benchmarks. Al Ahmadi and Mina Al Ahmadi port complexes concentrate logistics support for offshore supply operations.
Middle East Offshore Support Vessels Market Competitive Landscape
UAE-based operators anchor one tier through captive demand from Abu Dhabi's upstream operations; European and Asian specialists hold premium capability positions through DP-3 engineering expertise. Market structure consolidates around national oil company pre-qualification lists, squeezing independent owners from term charter access. Three archetypes dominate: integrated logistics divisions of state energy companies, specialized AHTS fleet operators, and DP-capable deepwater service providers. Competitive moves center on fleet modernization cycles and hybrid propulsion retrofits to satisfy emissions clauses.
Within the state-affiliated tier, ADNOC Logistics & Services occupies a position reflecting integrated demand from Abu Dhabi's offshore cluster. Among specialized operators, Tidewater Inc. and Maersk Supply Service exemplify DP-capable fleet positioning for deepwater exploration contracts. These three companies represent distinct competitive vectors: captive logistics integration, regional AHTS specialization, and premium station-keeping technology.
| Leading Market Players |
|---|
| Bourbon Corporation SA |
| P&O Maritime Logistics |
| Tidewater Inc. |
| Offshore International (OFCO) |
| Zakher Marine |
| ADNOC Logistics & Services |
| Zamil Offshore Services |
| Baltic Marine Services LLC |
| Maersk Supply Service |
| Others |
Supply & Pricing Matrix
ADNOC's five-year emissions clauses and Saudi Aramco's DP-3 capability mandates are forcing fleet operators toward hybrid propulsion retrofits and specialized engineering consultancies, compressing margins on non-compliant tonnage while concentrating contract access among pre-qualified suppliers.
Pricing Analysis
Volume concentrates in term-charter agreements while margins fragment across capability tiers. Three-tier pricing structure across DP-3 premium, DP-2 standard, and conventional economy levels reflects station-keeping redundancy and emissions compliance. Price differentiation rests on hybrid propulsion certification and charterer pre-qualification status. Cost compression in the conventional tier is intensifying because SFDA and MOHAP environmental mandates are accelerating fleet obsolescence. Independent vessel owners show highest price sensitivity; state-affiliated operators with captive demand exhibit lowest.
Supply Chain Analysis
Freight costs for specialized DP-3 system components from European and Asian technical consultancies inflate newbuild delivery timelines. Hull construction draws from South Korean, Chinese, and UAE shipyard capacity. Steel plate, dynamic positioning automation packages, and battery-hybrid propulsion modules constitute critical input dependencies. Single-source vulnerability in DP-3 redundancy engineering creates procurement bottlenecks. Distribution runs through national oil company pre-qualification lists that filter vessel eligibility before charter award.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive logistics divisions of state energy companies are tightening control over contracted vessel availability to lock out independent competitors.
For Market Incumbents: Lock in charterer relationships through accelerated hybrid fleet renewal ahead of SFDA and MOHAP compliance deadlines. Secure exclusive deployment rights within Saudi Aramco's Long Term Agreement program and ADNOC's master service agreements. Backward integration into battery-hybrid system maintenance capabilities will defend margins against European engineering consultancies extracting premium technical support fees. For New Entrants and Emerging Players: Digital chartering platforms offering real-time vessel availability transparency represent the most viable entry route. QatarEnergy's North Field expansion generates uncontracted DP-3 demand that pre-qualified incumbents cannot fully serve. Target spot-market flexibility gaps in maintenance and subsea intervention services where term charter coverage remains incomplete. For Investors and Strategic Acquirers: The window for entry favors operators with available DP-3 tonnage and established MOHAP or SFDA certification pathways. Long-term viability hinges on fleet decarbonization readiness and national oil company relationship depth. Monitor QatarEnergy's vessel procurement announcements as the primary inflection signal for regional capacity absorption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Retrofit Program | SFDA emissions clauses and MOHAP mandates are rendering non-hybrid tonnage ineligible for term charters. |
| DP-3 Capability Acquisition | QatarEnergy's North Field expansion is creating unmet demand for triple-redundant station-keeping vessels. |
| Master Service Agreement Expansion | ADNOC Logistics & Services leverages captive demand to dominate Abu Dhabi's offshore cluster charter volumes. |
| Port Electrification Compliance | Khalifa Port and Zayed Port shore-power mandates are accelerating battery-hybrid newbuild specifications. |
| Technical Consultancy Partnership | European DP-3 engineering expertise scarcity forces regional operators into joint development arrangements. |
Research Methodology
Multi-period observation of charter rate movements, fleet utilization metrics, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with vessel operators, national oil company procurement officers, maritime safety regulators, and shipyard project managers. Secondary validation drew from Lloyd's List vessel tracking data, IMO carbon intensity disclosures, GCC maritime authority filings, and national oil company annual procurement reports. Bottom-up hull-by-hull fleet analysis triangulated against top-down regional demand aggregation.
Segment-weighting across vessel type, DP certification tier, service intensity, and end-use application shaped the analytical framework across the projection horizon. CAGRs were derived from regression analysis of historical charter rate trajectories and fleet replacement schedules. Hybrid technology adoption curves and national oil company fleet modernization timelines served as industry-specific forecast inputs.
The model holds under stable regulatory enforcement of SFDA and MOHAP mandates; deviation in carbon intensity regulation stringency or steel input cost volatility would shift vessel replacement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
Platform Supply Vessels (PSV) Market
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Global Maritime Safety Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Air Compressors on Ships Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Cargo Hold Coatings Market