
 Russia Used Car Market | 2026-2036
Russia Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Used Car Market Outlook
The Russian government's vehicle scrappage incentives and import substitution mandates is expanding the pool of domestic buyers seeking affordable mobility alternatives. Drom leverages its digital marketplace infrastructure to aggregate fragmented seller inventory across eighty-five federal subjects. ROLF anchors its premium positioning through certified pre-owned programs and service bundling. Avtomir competes by extending its dealership network into Siberian and Far Eastern regions where new vehicle supply remains constrained.
A used car denotes a previously registered automobile offered for resale through dealer, auction, or peer-to-peer channels, typically assessed via odometer verification, structural inspection, and ownership history tracing to determine residual value and roadworthiness. Its commercial purpose centers on providing accessible transportation while recycling automotive assets through secondary utilization. Sedan and SUV categories dominate transaction volume in Russia's used car channels, with SUVs capturing expanding share as consumers prioritize ground clearance and all-weather capability on deteriorating regional road networks. Electric and hybrid segments remain nascent due to sparse charging infrastructure beyond Moscow, while gasoline-powered inventory sustains liquidity across provincial markets where service ecosystems favor internal combustion expertise.
Russia's Technical Regulation of the Customs Union (TR CU 018/2011) mandates periodic vehicle inspection and emission compliance, shaping resale eligibility and pricing tiers for older model years. The country's central bank monitors auto lending standards, influencing credit availability for used vehicle purchases through regulated interest rate corridors. Stakeholders must monitor how evolving safety inspection protocols and localized parts availability constraints reshape competitive positioning across Russia's asymmetric regional markets.
Market Dynamics
Sanctions-driven import compression is restructuring Russia's automotive value chain, forcing buyers toward domestically circulating used inventory while elevating digital aggregation platforms over traditional dealer networks. This supply shock has hardened price discovery mechanisms and fragmented regional liquidity pools across the Federation's asymmetric markets.
Growth Catalysts
- Vehicle Scrappage Incentives:Federal programs subsidizing older vehicle retirement expand the addressable pool of replacement buyers seeking affordable alternatives in secondary markets.
- Digital Marketplace Infrastructure:Online platforms aggregate fragmented seller inventory across eighty-five federal subjects, compressing search costs and standardizing transaction transparency.
- Siberian Supply Constraints:Persistent new vehicle shortages in Russia's Far Eastern regions sustain elevated demand for durable used inventory with established service histories.
Market Restraints
- TR CU 018/2011 Compliance Burden:Mandatory periodic technical inspection and emission protocols disqualify older model years from resale eligibility, shrinking available supply.
- Central Bank Interest Rate Corridors:Regulated auto lending standards restrict credit availability for used vehicle purchases, particularly affecting thin-file borrowers in provincial markets.
- Charging Infrastructure Gaps:Sparse electric vehicle service networks beyond Moscow eliminate electrified segments from viable resale consideration outside capital-region corridors.
Strategic Opportunities
- Volga Federal District Expansion:Industrial cities in this corridor exhibit underpenetrated certified pre-owned penetration relative to transaction volume potential.
- Service Bundling Convergence:Integration of maintenance contracts with resale transactions captures lifetime value from risk-averse buyers seeking predictable ownership costs.
- Parts Localization Mandates:Import substitution policies create captive demand for vehicles with domestically serviceable component ecosystems.
Industry Challenges
- Structural Inspection Standardization:Inconsistent enforcement of TR CU 018/2011 protocols across regional inspection stations creates arbitrage opportunities and consumer trust deficits.
- Valuation Model Calibration:Ruble volatility and sanctions-driven parts scarcity complicate residual value forecasting for financing and leasing products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Used Car Market |
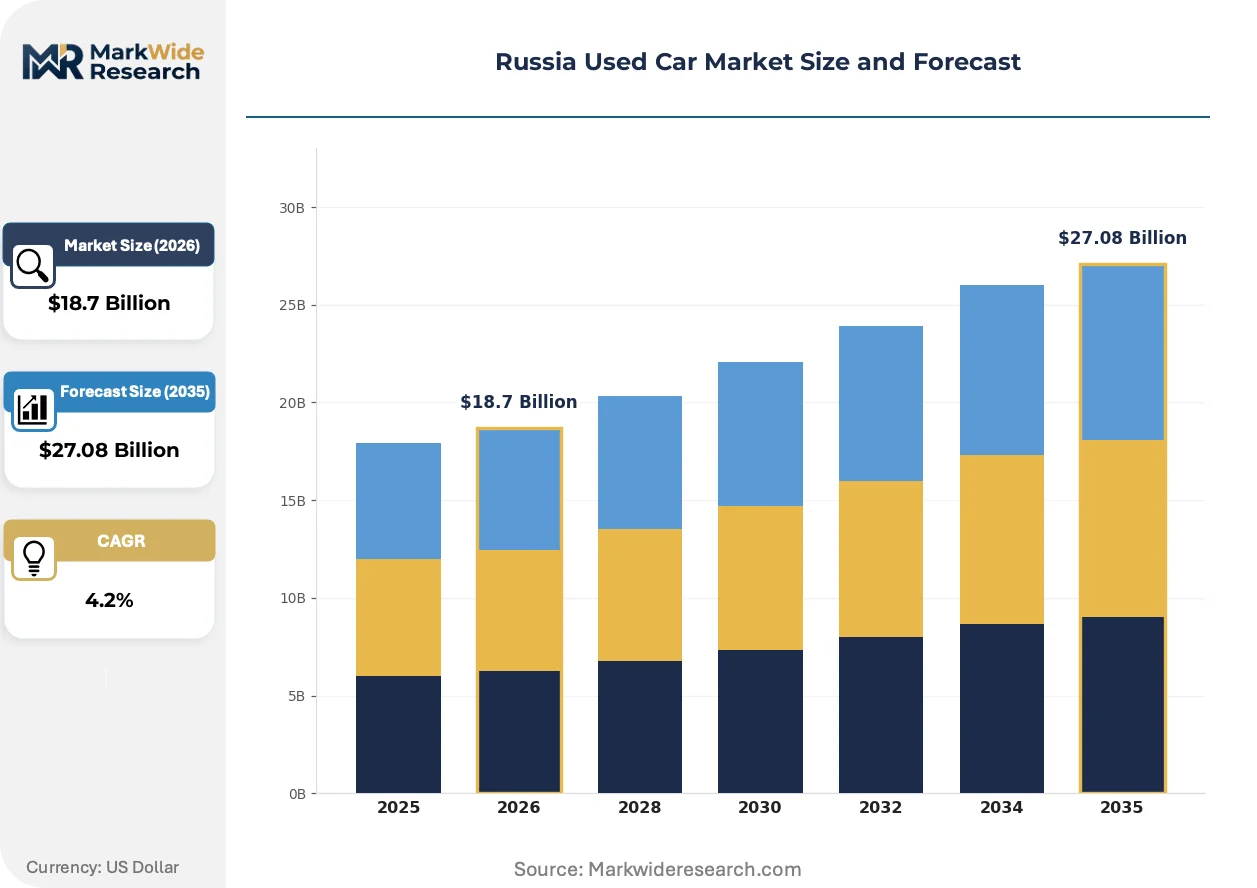
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Gasoline, Diesel, Electric, Hybrid Model Year: 2018, 2019, 2020, 2021 Condition: New, Like-New, Used, Certified Pre-Owned |
| Companies Covered | Drom, AvtoVAZ, ROLF, Avtomir, Inchcape Plc, Fresh Auto, Favorit Motors, JSC AVTOVAZ, Genser Auto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Used Car Market Strategic Shifts
Digital verification technologies and inspection automation are compressing information asymmetries between buyers and sellers, while regulatory pressure on vehicle roadworthiness accelerates quality-based market stratification.
Blockchain-based ownership history systems are automating title verification and accident record retrieval across Russia's fragmented registry infrastructure. Secondary market buyers in the Moscow-St. Petersburg corridor adopt these tools fastest, reducing due diligence cycles from days to hours. This transparency compression is automating price discovery and squeezing margins for dealers reliant on information advantages.
Russia's Technical Regulation of the Customs Union (TR CU 018/2011) tightens emission and safety inspection thresholds for older vehicle cohorts. Industrial consequence falls heaviest on pre-2012 inventory, which faces accelerated retirement or depressed pricing. Buyers in the Volga Federal District respond by migrating toward 2015-plus model years with cleaner compliance trajectories.
Peer-to-peer transaction platforms disintermediate traditional dealer networks by matching individual sellers directly with verified buyers. This channel shift concentrates among digitally fluent consumers in metropolitan markets, where platform escrow and inspection services substitute for dealership trust mechanisms. Geographic penetration remains deepest in Moscow, with secondary city adoption following platform marketing investment cycles.
Russia Used Car Market Segmentation
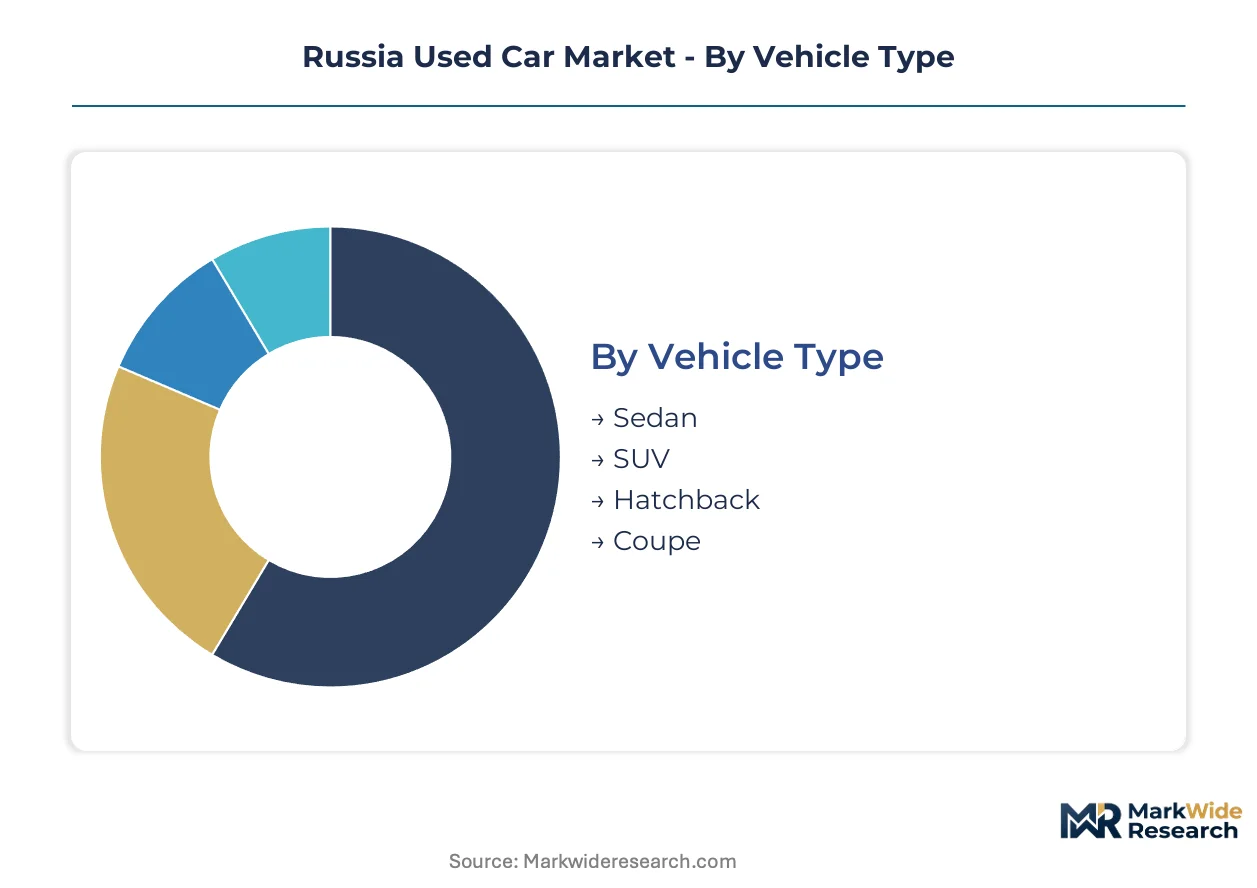
Russia's used car market segments reflect distinct liquidity profiles shaped by sanctions-driven supply constraints and regional infrastructure asymmetries. Buyers navigate trade-offs between vehicle age, fuel system reliability, and certification grade across Moscow's premium corridors and Siberian utility markets.
Vehicle Type:
Standardization dominates mass-market categories while customization concentrates in premium tiers with bundled service packages.
- Sedan:Three-box passenger cars with enclosed trunks sustain the highest transaction velocity across Russia's secondary cities. Demand clusters in the Volga Federal District's industrial centers where fuel efficiency and established service networks outweigh ground clearance requirements on deteriorating regional highways.
- SUV:Sport utility vehicles with elevated ride height and all-wheel-drive capability command expanding share as consumers prioritize winter performance and road condition tolerance. Moscow-St. Petersburg corridor buyers drive adoption of mid-size crossovers with documented maintenance histories.
- Hatchback:Compact two-box designs with rear cargo access dominate budget-conscious segments in provincial markets where parking constraints and maneuverability matter.
- Coupe:Two-door fixed-roof configurations with sport-tuned suspensions occupy niche positioning among performance-oriented buyers in capital-region metropolitan clusters.
Leading the category by volume: Sedan. Growing fastest: SUV.
Fuel Type:
Cost tier stratification separates proven internal combustion systems from emerging electrified alternatives with infrastructure dependencies.
- Gasoline:Spark-ignition internal combustion engines with port or direct fuel injection sustain market liquidity through ubiquitous service infrastructure and parts availability. Provincial buyers across the Far Eastern regions favor these powertrains where certified technician density supports long-term ownership.
- Diesel:Compression-ignition engines with torque-optimized output attract commercial utility buyers and long-distance operators in Siberian freight corridors.
- Electric:Battery-electric drivetrains with zero tailpipe emissions face demand suppression beyond Moscow due to sparse charging infrastructure and cold-climate range degradation.
- Hybrid:Parallel and series-parallel electrified powertrains with regenerative braking remain experimental in resale channels where battery replacement cost uncertainty deters risk-averse buyers.
Gasoline leads volume concentration. Hybrid systems show steepest expansion trajectory despite low base.
Model Year:
Application timeline separates compliance-ready recent inventory from depreciated older cohorts facing TR CU 018/2011 inspection thresholds.
- 2018:Six-year-old vehicles entering accelerated depreciation phase attract price-sensitive buyers in secondary cities where inspection compliance costs remain manageable.
- 2019:Five-year-old inventory with established reliability records balances acquisition cost against remaining service life in regional commercial fleets.
- 2020:Pandemic-year production with variable build quality commands scrutiny from buyers prioritizing documented maintenance over cosmetic condition.
- 2021:Four-year-old vehicles with modern safety architectures and emission-compliant powertrains dominate certified pre-owned programs in Moscow's premium channels.
2021 model years lead transaction value. 2019 cohorts gain share fastest in provincial price-sensitive segments.
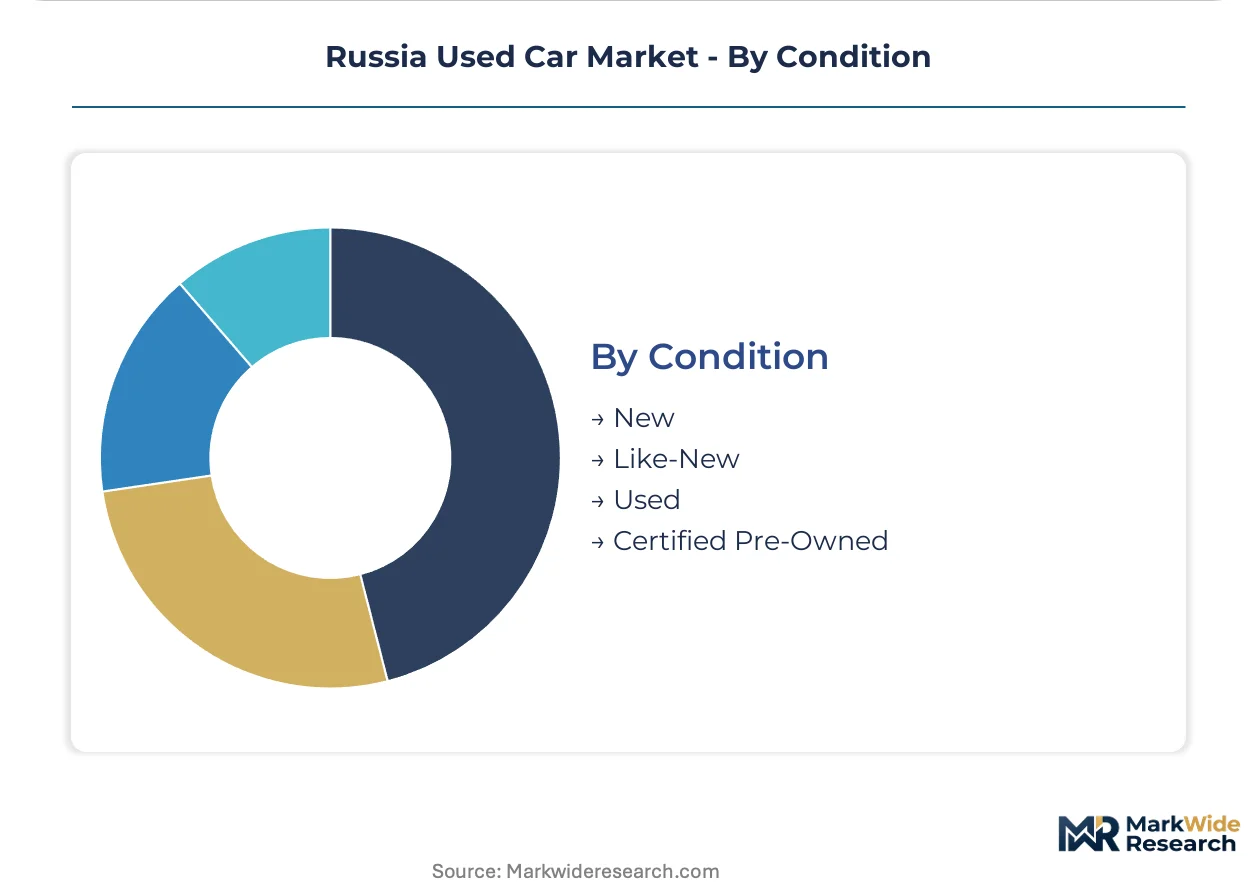
Condition:
Customer type segmentation separates institutional quality guarantees from peer-to-peer risk absorption with corresponding price differentials.
- New:Zero-mileage unregistered inventory with full manufacturer warranty coverage appears rarely in used channels through dealer demo programs and registration timing arbitrage.
- Like-New:Low-mileage vehicles under twelve months with minimal wear indicators attract buyers seeking warranty transferability without new-car premiums.
- Used:Standard resale inventory with variable maintenance documentation and unverified history dominates volume through digital marketplace aggregation.
- Certified Pre-Owned:Dealer-inspected vehicles with extended warranty coverage and structural verification command loyalty from risk-averse buyers in metropolitan corridors.
Used condition states lead absolute volume. Certified Pre-Owned programs expand most quickly in premium regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production capacity and import substitution imperatives are reshaping how vehicle inventory circulates across Russia's federal districts. Consumption clusters concentrate where sanctions have most severely disrupted new vehicle supply chains.
Moscow
Certified pre-owned programs and premium SUV demand dominate transaction value in the capital region. The central bank's regulated interest rate corridors constrain auto lending availability for thin-file borrowers seeking used vehicle financing. Digital marketplace penetration reaches its deepest point here, with blockchain-based ownership verification tools automating title searches across the Moscow-St. Petersburg corridor.
Volga Federal District
Industrial cities in this corridor exhibit underpenetrated certified pre-owned penetration relative to raw transaction volume potential. Federal vehicle scrappage incentives expand the addressable pool of replacement buyers in secondary markets like Kazan and Nizhny Novgorod. Parts localization mandates under import substitution policy create captive demand for vehicles with domestically serviceable component ecosystems.
Siberian Federal District
Persistent new vehicle shortages sustain elevated demand for durable used inventory with established service histories in Novosibirsk and Krasnoyarsk. TR CU 018/2011 technical inspection protocols face inconsistent enforcement across regional inspection stations, creating arbitrage opportunities. Gasoline-powered SUVs with all-wheel-drive capability command premium pricing for winter performance on deteriorating regional highways.
Far Eastern Federal District
Supply constraints from import compression hit hardest in Vladivostok and Khabarovsk, forcing buyers toward domestically circulating used inventory. Sparse charging infrastructure eliminates electrified segments from viable resale consideration outside capital-region corridors. Peer-to-peer transaction platforms disintermediate traditional dealer networks among digitally fluent consumers in metropolitan pockets.
Northwestern Federal District
St. Petersburg anchors the secondary pole of premium used vehicle demand alongside Moscow. Rouble volatility complicates residual value forecasting for financing products in this credit-dependent market. Service bundling convergence captures lifetime value from risk-averse buyers seeking predictable ownership costs through maintenance contract integration.
Russia Used Car Market Competitive Environment
The competitive structure tilts toward digital aggregation platforms over traditional dealer networks. Marketplace operators compress search costs across fragmented seller inventory while legacy dealer groups defend margin position through certified pre-owned certification and warranty bundling. Three archetypes dominate: pure-play digital marketplaces, vertically integrated dealer networks with service bundling, and manufacturer-affiliated remarketing channels. Consolidation pressure favors scale-driven operators with proprietary inspection infrastructure and captive financing arrangements.
Among platform-centric operators, Drom exemplifies the digital aggregation archetype through its marketplace infrastructure spanning eighty-five federal subjects. ROLF and Avtomir occupy positions within the integrated dealer network tier, with ROLF anchoring premium certified pre-owned positioning and Avtomir extending geographic reach into supply-constrained Siberian and Far Eastern regions. These three entities represent the dominant competitive configurations reshaping how Russian buyers discover, verify, and finance used vehicle transactions.
| Leading Market Players |
|---|
| Drom |
| AvtoVAZ |
| ROLF |
| Avtomir |
| Inchcape Plc |
| Fresh Auto |
| Favorit Motors |
| JSC AVTOVAZ |
| Genser Auto |
| Others |
Value Chain & Pricing Dynamics
Captive financing arrangements through dealer-affiliated lenders anchor both supply positioning and pricing power across Russia's fragmented used vehicle channels. This vertical integration pattern allows certified pre-owned operators to bundle warranty coverage with credit products, compressing buyer search costs while extracting margin from risk-averse metropolitan consumers.
Pricing Analysis
Margin tightening in the certified pre-owned tier reflects TR CU 018/2011 compliance cost absorption and ruble-denominated parts scarcity. Pricing stratifies across certified, standard, and economy tiers based on inspection grade and after-sales bundling intensity. Cost-down pressure on economy-segment inventory accelerates because provincial buyers face central bank interest rate corridor constraints. Thin-file borrowers in secondary cities exhibit highest price sensitivity, while Moscow-St. Petersburg corridor buyers accept premiums for blockchain-verified ownership histories.
Supply Chain Analysis
Dealer-to-dealer auction channels handle bulk inventory redistribution from Moscow's trade-in surplus toward Siberian and Far Eastern demand pockets. Geographic supply concentration in the Central Federal District and Volga Federal District feeds from domestic production clusters around Togliatti and Izhevsk. Parts dependencies rest on localized component ecosystems under import substitution mandates, with brake systems and electrical harnesses drawing from captive supplier networks. Single-source vulnerability in semiconductor-dependent engine management modules creates procurement risk. Distribution runs through digital marketplace aggregation with physical inspection nodes at regional logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's used car market is becoming a vertical-integration race where control over inspection infrastructure and captive financing determines survival. Players are pursuing downstream service bundling as the primary lever to lock in lifetime customer value.
For Market Incumbents: Anticipate regulatory tightening on TR CU 018/2011 enforcement standards by investing in proprietary inspection infrastructure before regional station consolidation. Defend against peer-to-peer platform disintermediation through exclusive warranty transferability tied to certified pre-owned programs. Deepen backward integration into parts localization supply chains to offset import substitution policy volatility. For New Entrants and Emerging Players: The mid-tier price gap between economy hatchbacks and certified SUVs in the Volga Federal District offers white-space penetration potential. Target underpenetrated industrial cities like Kazan and Nizhny Novgorod where scrappage incentive flows expand replacement demand. Pursue mobile inspection unit deployment as a go-to-market angle to bypass fixed dealership infrastructure requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-scale rollup opportunities among regional dealer networks with captive financing licenses. Long-term viability hinges on regulatory adaptation capacity rather than pure transaction volume scale across the analysis window. Acquisition target archetype: vertically integrated operators with proprietary inspection technology and ruble-hedged parts inventory. Watch central bank auto lending corridor adjustments as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Inspection Infrastructure Deployment | TR CU 018/2011 compliance automation creates defensible quality certification moats against peer-to-peer platforms. |
| Captive Financing License Acquisition | Central bank regulated interest rate corridors make licensed lending operations critical for margin capture in credit-constrained markets. |
| Parts Localization Supply Chain Integration | Import substitution mandates reward dealers with domestically serviceable component ecosystems and faster turnaround times. |
| Blockchain Ownership Verification Implementation | Moscow-St. Petersburg corridor buyers reduce due diligence cycles, compressing transaction friction and accelerating inventory velocity. |
| Mobile Inspection Unit Network Expansion | Siberian and Far Eastern supply constraints create arbitrage opportunities for on-site verification services in dealer-sparse regions. |
Study Parameters
Federal vehicle registration databases, customs import records, and central bank auto lending disclosures formed the secondary backbone for volume and value estimation. Primary interviews with dealership operations managers, digital marketplace platform engineers, and regional inspection station administrators validated demand assumptions. Bottom-up and top-down triangulation reconciled transaction-level data from Drom's marketplace aggregation with macroeconomic indicators including ruble volatility indices and scrappage program disbursement flows.
Bottom-up modeling anchored forecasts in vehicle age cohort depreciation curves and regional liquidity pool depth, while top-down cross-checks applied macroeconomic scenario stress-testing across the projection horizon. Segmentation dimensions included vehicle class, propulsion architecture, certification grade, and federal district production cluster. CAGRs were derived from fitted trend extrapolation with regulatory inflection point adjustments. Industry-specific inputs incorporated TR CU 018/2011 inspection threshold evolution and parts localization mandate implementation timelines.
Inputs from federal statistical agencies and platform transaction records were available through the study window; gaps in real-time regional price discovery introduce uncertainty bands around provincial market estimates. Forecasts reflect documented assumptions regarding sanctions persistence and import substitution policy continuity. Periodic stress-testing of base assumptions is recommended given central bank interest rate corridor volatility and evolving technical inspection protocol enforcement standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Vintage Car Market
Used Vehicles
Indonesia Used Car Market
Used Vehicles
Saudi Arabia Used Car Market
Used Vehicles
GCC Used Car Market
Used Vehicles
Ethiopia Used Car Market
Used Vehicles
Australia Used Car Market
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
Kenya Used Car Market
Used Vehicles
Netherlands Used Car Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
South Korea Used Car Market
Used Vehicles
Sri Lanka Used Car Market
Used Vehicles
Hong Kong Used Car Market
Used Vehicles
Spain Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
France Used Car Market