
 Europe Offshore Support Vessels Market | 2026-2036
Europe Offshore Support Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Offshore Support Vessels Market Intelligence
The EU Green Deal is hardening the cost-of-entry calculus for vessel operators across European waters. Maersk Supply Service leverages its integrated logistics platform to sustain fleet utilization in the North Sea. BOURBON anchors its competitive stance through specialized subsea service vessels purpose-built for harsh-environment operations. Solstad Offshore ASA differentiates via advanced dynamic positioning systems that reduce fuel consumption during precision maneuvers.
Offshore support vessels are purpose-built marine craft typically ranging from 50 to 150 meters in length, equipped with dynamic positioning systems, deck cranes rated to 100+ tonnes, and cargo capacities exceeding 1,000 square meters for transporting drilling supplies, personnel, and subsea equipment to fixed and floating offshore installations. Platform Supply Vessels dominate fleet composition due to recurring logistics demand from mature oil and gas basins, while Anchor Handling Tug Supply units command premium day-rates during offshore wind foundation installation campaigns. Crew Boats represent the fastest-expanding category as renewable energy providers scale turbine maintenance rotations across the North Sea and Baltic Sea lease areas.
EMA oversight of offshore worker safety standards, REACH compliance for anti-fouling coatings and marine lubricants, and the EU F-Gas Regulation governing refrigerated transport systems collectively elevate operational compliance burdens for European fleet operators. The International Maritime Organization's carbon intensity indicators, adopted into EU monitoring frameworks, now shape vessel chartering decisions by major energy companies. Stakeholders must track evolving tender specifications from national offshore wind auction rounds, as contract terms increasingly mandate hybrid-propulsion or shore-power compatibility as minimum fleet qualifications.
Market Dynamics
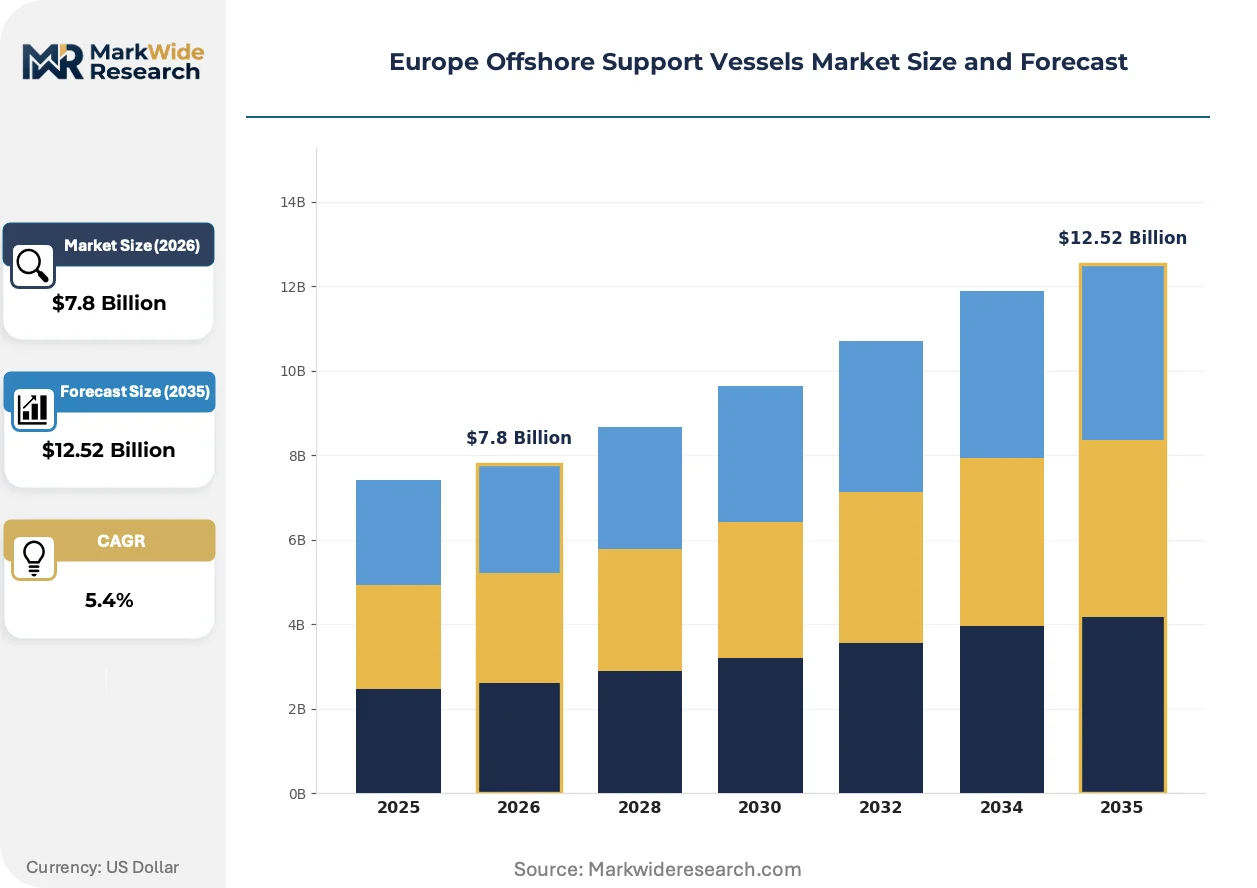
Hybrid-electric propulsion mandates from the EU Green Deal are restructuring charter economics across European offshore support fleets, forcing vessel operators to retire conventional tonnage ahead of depreciation schedules or absorb retrofit capital costs.
Growth Catalysts
- Offshore wind installation cycles:Foundation-laying campaigns in the North Sea and Baltic Sea are generating recurring demand for Anchor Handling Tug Supply vessels with bollard pull ratings exceeding 200 tonnes.
- EMA safety standard harmonization:Unified offshore worker certification protocols across EU member states are reducing cross-border crew transfer friction and expanding vessel deployment flexibility.
- Hydrogen bunkering pilots:Port of Rotterdam and Port of Antwerp-Bruges infrastructure investments are creating demand for dual-fuel vessel conversions and purpose-built hydrogen-ready newbuilds.
Market Restraints
- Steel plate and marine engine cost volatility:Korean and Chinese shipyard input pricing swings are compressing newbuild margins for European vessel owners commissioning at domestic yards.
- Specialized crew scarcity:Dynamic positioning operator certification backlogs at Norwegian and UK maritime academies are extending vessel mobilization timelines.
- REACH coating compliance:Anti-fouling biocide restrictions are eliminating established copper-based formulations and forcing fleet-wide hull maintenance protocol revisions without proven long-term alternatives.
Strategic Opportunities
- Polish and Baltic offshore wind lease rounds:Emerging turbine installation zones in Polish Exclusive Economic Zones lack established local vessel supply chains, creating first-mover positioning for mobile fleets.
- EU Emissions Trading System maritime inclusion:Carbon credit cost pass-through mechanisms in charter contracts favor early adopters of battery-hybrid systems with verified emissions monitoring.
- Subsea cable maintenance specialization:Interconnector expansion between UK, Norway, and continental grids is generating demand for cable-laying support vessels with integrated remotely operated vehicle capabilities.
Industry Challenges
- Dual-certification complexity:Vessels operating across UK and EU waters post-Brexit must maintain parallel compliance with Maritime and Coastguard Agency and EU flag state requirements, doubling documentation overhead.
- Shore power infrastructure gaps:Limited high-voltage onshore connection capacity at Scottish and Norwegian offshore supply bases restricts idle-time emissions reductions for battery-hybrid fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Offshore Support Vessels Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Platform Supply Vessels, Anchor Handling Tug Supply, Crew Boats, Multipurpose Support Vessels Service Type: Logistics Support, Inspection Services, Emergency Response, Subsea Services End User: Oil & Gas Companies, Renewable Energy Providers, Marine Contractors, Research Institutions Operation Mode: Dynamic Positioning, Conventional Anchoring, Hybrid Operations, ROV Operations |
| Companies Covered | Maersk Supply Service, Tidewater Inc., BOURBON, Solstad Offshore ASA, SEACOR Marine, Edison Chouest Offshore, Havila Shipping ASA, Østensjø Rederi, DOF Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Offshore Support Vessels Market Strategic Shifts & Innovations
Digital twin integration and predictive hull performance modeling are compressing maintenance intervals and reshaping how charterers evaluate vessel technical specifications during tender rounds.
Advanced battery-hybrid propulsion architectures are consolidating around standardized 2-4 MWh lithium-ion configurations with DC grid integration. Offshore wind farm operators with 10+ year service contracts are specifying hybrid vessels in 80% of new charter agreements. This standardization is consolidating supplier tiers around three dominant European marine battery system integrators and squeezing smaller pack assemblers from certified vendor lists.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transition timelines for offshore catering and medical cold-chain systems. Vessel operators face mandatory HFC replacement with CO2 or ammonia-based systems during scheduled dry-dockings. UK-flagged Platform Supply Vessels with extended North Sea deployment contracts are absorbing the highest retrofit cost exposure due to earlier compliance deadlines.
Charter contracting is migrating toward availability-based payment structures with performance penalties for fuel consumption exceedance. Major offshore wind developers in Danish and German lease areas are unbundling traditional day-rate agreements into separate vessel provision and fuel pass-through components. This restructuring concentrates price negotiation leverage with fleet operators possessing verified emissions monitoring infrastructure and transparent fuel accounting systems.
Europe Offshore Support Vessels Market Segmentation
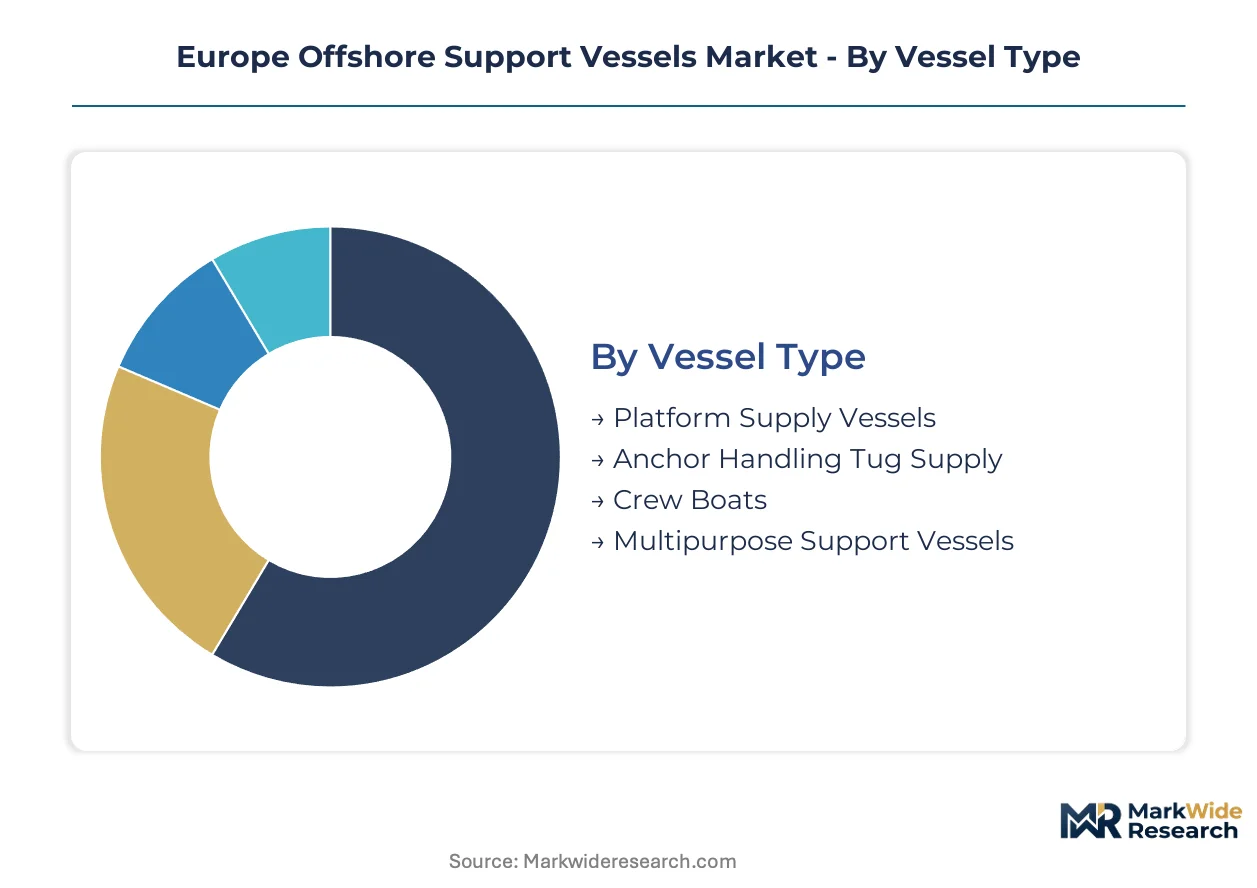
Vessel specifications and operational profiles diverge sharply across European offshore zones. Charter contract terms now embed emissions performance clauses that segment fleet deployment by technical capability.
Vessel Type:
Buyers differentiate by deck capacity requirements and station-keeping precision for specific mission profiles.
- Platform Supply Vessels:These 80-100 meter hulls carry drilling fluids, cement, and provisions to fixed installations. Norwegian and UK North Sea operators commission these for recurring supply runs to mature oil and gas platforms.
- Anchor Handling Tug Supply:Twin-engine configurations deliver 200+ tonne bollard pull for wind turbine foundation positioning. Danish and German lease areas in the North Sea generate concentrated demand during installation campaigns.
- Crew Boats:High-speed aluminum hulls transfer technicians to offshore wind arrays. Polish and Baltic Sea zones lack established fleets, creating mobilization opportunities.
- Multipurpose Support Vessels:Modular deck layouts accommodate ROV hangars and survey equipment. Research institutions and cable contractors charter these for interconnector route surveys between Norway and continental grids.
Platform Supply Vessels lead volumes today; Crew Boats are gaining share fastest.
Service Type:
Margin structures vary by contract duration and asset specialization intensity.
- Logistics Support:Recurring platform resupply contracts span 3-5 years with fuel-adjusted day-rates. UK and Norwegian basins sustain the largest contracted fleets.
- Inspection Services:Hull-mounted sensors and drone deployment systems verify turbine blade integrity. German BSH regulatory requirements mandate annual inspections for offshore wind assets.
- Emergency Response:Standby vessels with hospital facilities and fire-fighting capability carry premium standby rates. EMA safety directives require dedicated emergency capacity near manned installations.
- Subsea Services:ROV-equipped hulls perform cable burial and pipeline intervention. Interconnector expansion between UK, Norway, and Denmark drives specialized vessel demand.
Logistics Support commands the largest revenue pool; Subsea Services show the steepest expansion trajectory.
End User:
Procurement sophistication and emissions scrutiny intensity define buyer tiers.
- Oil & Gas Companies:Integrated majors charter long-term for North Sea production assets. Their procurement teams enforce EU ETS maritime compliance through fuel monitoring clauses.
- Renewable Energy Providers:Offshore wind developers specify hybrid-propulsion vessels in 80% of new tenders. Danish Ørsted and German RWE operations set fleet technical standards.
- Marine Contractors:Project-based chartering for installation campaigns concentrates in Baltic Sea lease rounds. Polish offshore wind zones lack established local supply chains.
- Research Institutions:Short-term charters for oceanographic surveys require specialized sensor integration. Norwegian research programs dominate this niche.
Oil & Gas Companies anchor current fleet utilization; Renewable Energy Providers are expanding charter volumes most rapidly.
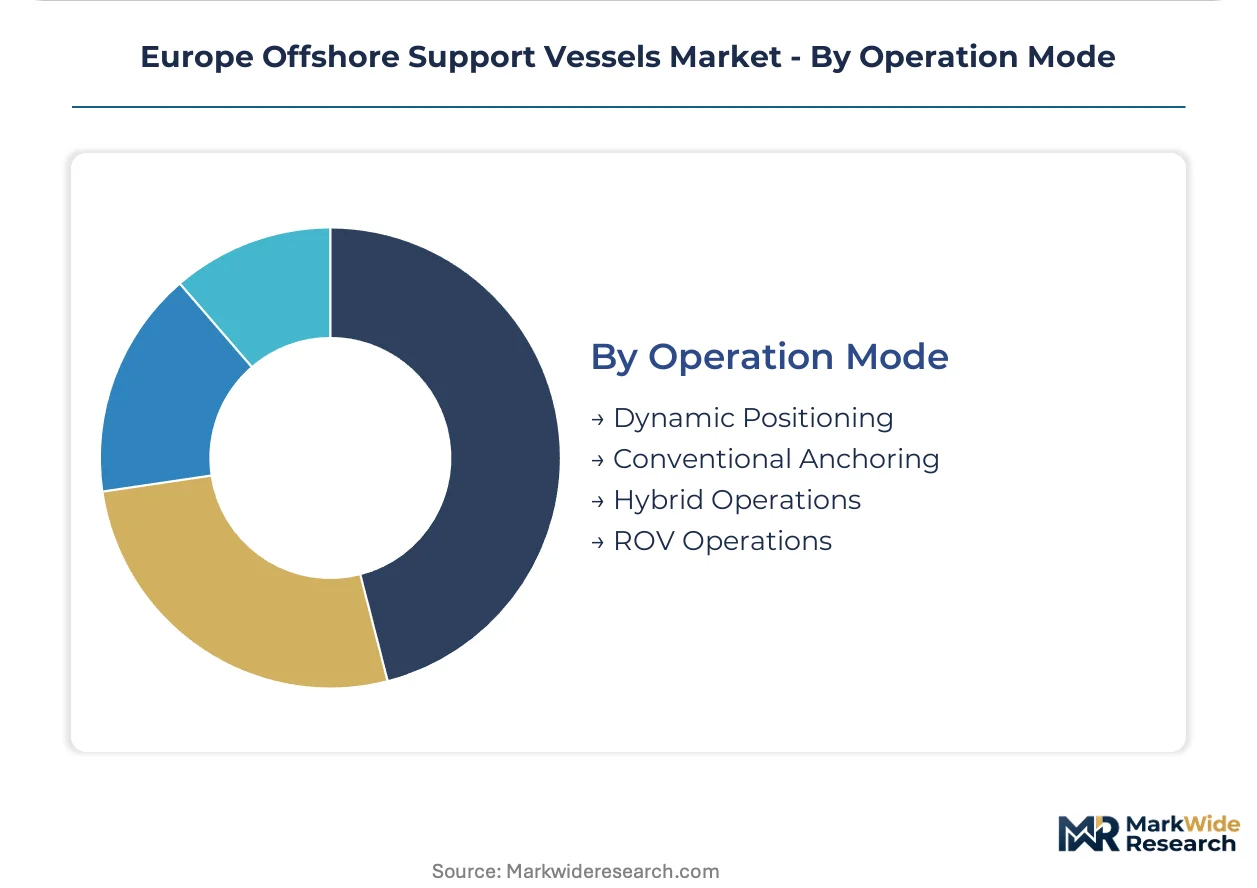
Operation Mode:
Technical certification requirements and fuel consumption profiles segment operational approaches.
- Dynamic Positioning:Computer-controlled thruster systems maintain station without anchoring. DP-2 and DP-3 certification is mandatory for North Sea wind turbine service.
- Conventional Anchoring:Wire and chain mooring systems suit shallow-water supply runs. Older tonnage faces accelerated retirement under EU Green Deal emissions standards.
- Hybrid Operations:Battery-electric systems reduce fuel burn during station-keeping. Port of Rotterdam and Port of Antwerp-Bruges infrastructure investments support shore power connection.
- ROV Operations:Tethered submersible deployment requires integrated launch and recovery systems. Cable maintenance contracts between UK and Norway specify dedicated ROV-capable hulls.
Dynamic Positioning dominates current fleet specifications; Hybrid Operations are climbing the fastest as charterers mandate emissions reductions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled maritime crews and certified dynamic positioning operators concentrate around North Sea supply bases. This workforce geography shapes where vessel operators station fleet assets and charter contracting decisions.
Norway
Stavanger and Bergen host the densest clusters of subsea service specialists and anchor handling expertise. Norwegian maritime academies maintain DP certification programs that feed crew supply across the North Sea. The country's offshore supply bases at Dusavik and Ågotnes support drilling logistics and wind turbine installation campaigns.
United Kingdom
Aberdeen anchors the UK's offshore vessel charter market with established supply chain relationships to North Sea oil and gas platforms. The Maritime and Coastguard Agency enforces post-Brexit certification requirements that run parallel to EU flag state rules. Scottish ports at Peterhead and Montrose face shore power infrastructure constraints that limit idle-time emissions reductions.
Denmark
Esbjerg functions as the primary marshalling port for North Sea wind turbine installation fleets. Danish offshore wind developers specify hybrid-propulsion vessels in tender documentation with increasing frequency. The port's quayside infrastructure supports heavy-lift component staging for Ørsted and RWE installation campaigns.
Germany
Cuxhaven and Bremerhaven concentrate vessel demand from Baltic Sea and North Sea wind lease areas. The German Federal Maritime and Hydrographic Agency mandates annual turbine blade inspections that sustain inspection vessel charter demand. Port infrastructure investments at Wilhelmshaven target offshore wind component manufacturing integration.
Poland
Polish Exclusive Economic Zones in the Baltic Sea lack established local vessel supply chains for planned offshore wind developments. Port of Gdynia and Port of Szczecin infrastructure investments aim to capture installation campaign logistics. The absence of incumbent fleet operators creates first-mover positioning for mobile North Sea vessels.
Europe Offshore Support Vessels Market Key Industry Players
The competitive structure tilts toward integrated logistics platforms with fleet scale advantages. Vessel operators cluster around three strategic tiers: diversified energy service conglomerates with cross-regional fleet networks, specialized subsea contractors with harsh-environment technical capabilities, and regional fleet operators with port-specific relationships. Competitive moves concentrate on hybrid propulsion retrofit programs and strategic positioning for Polish and Baltic wind lease rounds.
Among Nordic fleet operators, Maersk Supply Service, Solstad Offshore ASA, and Havila Shipping ASA occupy positions defined by fleet modernization trajectories and North Sea operational tenure. These companies exemplify the scale-specialist spectrum within European offshore support, with integrated logistics capabilities anchoring competitive differentiation against project-based charter competitors.
| Leading Market Players |
|---|
| Maersk Supply Service |
| Tidewater Inc. |
| BOURBON |
| Solstad Offshore ASA |
| SEACOR Marine |
| Edison Chouest Offshore |
| Havila Shipping ASA |
| Østensjø Rederi |
| DOF Group |
| Others |
Cost & Logistics Intelligence
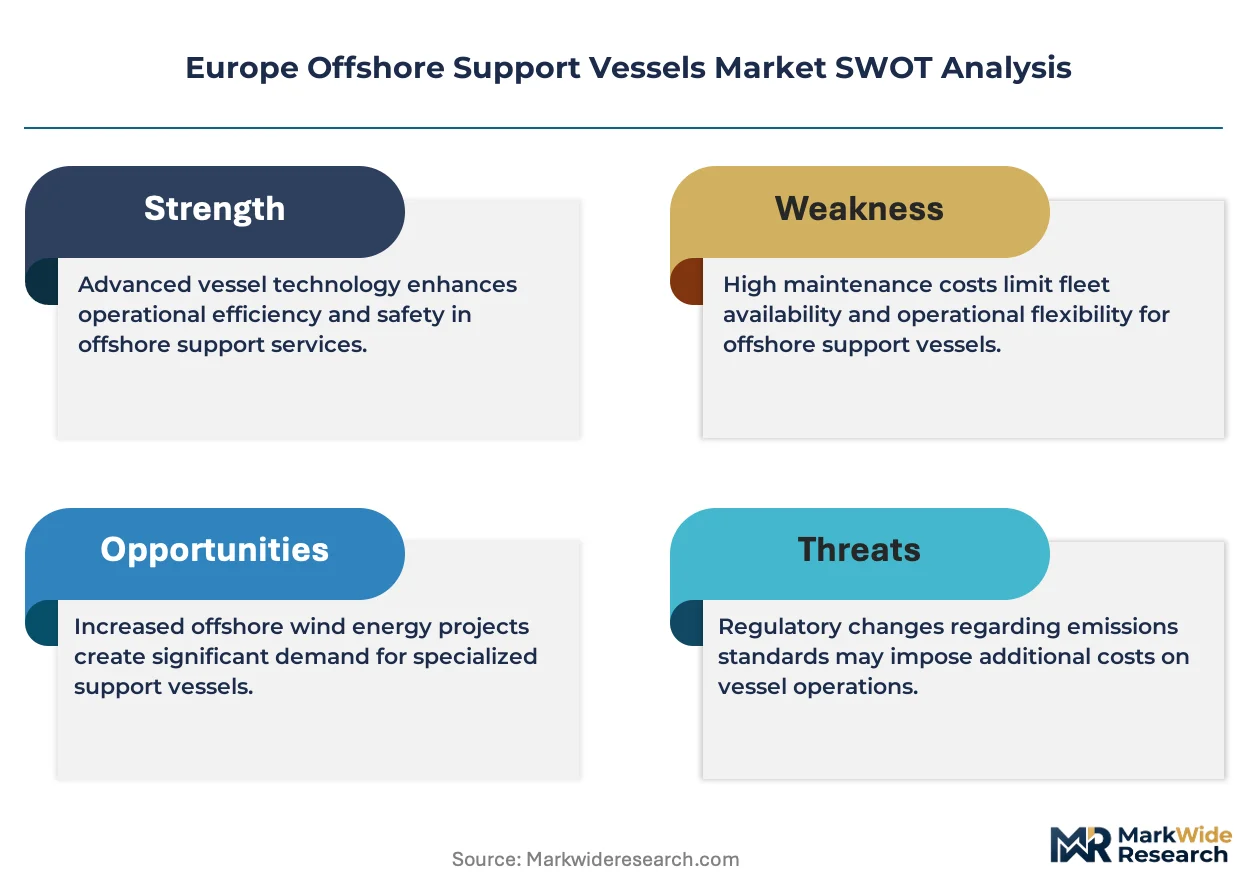
The EU Green Deal's hybrid-electric propulsion mandates gate qualified supply and premium-tier pricing access for European offshore support vessel operators, forcing charterers to pay availability-based premiums for battery-hybrid fleets with verified emissions monitoring while conventional tonnage faces accelerated depreciation and compressed day-rates.
Pricing Analysis
Bundled day-rate agreements are unbundling into separate vessel provision and fuel pass-through components across Danish and German lease areas. Premium-mid-economy pricing differentiation now stratifies by emissions certification tier, with DP-2 certified hybrid vessels commanding 40-60% rate premiums over conventional anchoring-dependent hulls. Cost compression in standard-tier conventional tonnage is intensifying because EU ETS maritime inclusion concentrates carbon credit liabilities on older fleet segments. Renewable energy providers demonstrate lowest price sensitivity due to 10+ year service contract structures, while marine contractors exhibit highest sensitivity during Polish and Baltic installation campaigns.
Supply Chain Analysis
Workforce availability constraints in Norwegian and UK maritime academies are extending vessel mobilization timelines and compressing newbuild delivery schedules for European fleet operators. Hull construction draws from Korean and Chinese shipyards for steel plate and marine engine inputs, while specialized DP certification programs rest on Stavanger and Bergen training infrastructure. Single-source vulnerability concentrates in lithium-ion battery system supply, where three dominant European marine integrators control certified vendor lists. Distribution runs through integrated logistics platforms with cross-regional fleet networks rather than fragmented spot-market brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a margin-expansion story as hybrid-electric retrofit programs unlock premium-tier charter access and EU ETS carbon credit pass-through mechanisms concentrate pricing power with early technology adopters.
For Market Incumbents: Deepen backward integration into shore power infrastructure partnerships at Scottish and Norwegian supply bases to defend against idle-time emissions penalties. Lock in long-term DP operator training pipelines with Bergen and Stavanger maritime academies to preempt crew scarcity bottlenecks that extend mobilization timelines.
For New Entrants and Emerging Players: Begin with Polish Exclusive Economic Zone positioning, where absent local vessel supply chains create first-mover charter contracting opportunities for mobile North Sea fleets. Target crew boat deployment specifically, as Baltic Sea turbine maintenance rotations outpace established fleet capacity.
For Investors and Strategic Acquirers: Roll-up economics work for specialized subsea contractors with harsh-environment technical capabilities because interconnector expansion between UK, Norway and Denmark generates recurring cable-laying support vessel demand with 5-10 year visibility. Monitor hydrogen bunkering pilot scale-up at Port of Rotterdam and Port of Antwerp-Bruges as inflection signal for dual-fuel conversion investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Retrofit Program | Battery-electric conversions unlock EU ETS compliance and premium charter tier access for North Sea operators. |
| DP Certification Pipeline Investment | Stavanger and Bergen academy partnerships secure crew supply for precision station-keeping operations. |
| Polish EEZ Fleet Mobilization | First-mover positioning captures Baltic Sea turbine installation campaign logistics before local supply chains mature. |
| Shore Power Infrastructure Partnership | Scottish and Norwegian base electrification reduces idle-time emissions for battery-hybrid fleet segments. |
| Subsea Cable Specialization | ROV-integrated capabilities target UK-Norway-Denmark interconnector maintenance contracts with decade-long visibility. |
Research Approach
Multiple input streams — vessel charter contract documentation, maritime regulatory filings, and fleet operator financial disclosures — were reconciled through structured primary interviews with offshore wind developers, platform supply vessel fleet managers, DP certification program directors, and subsea service contractors, validated against Lloyd's List intelligence, EU MRV emissions database extracts, and national offshore wind auction round specifications, with bottom-up charter rate aggregation cross-checked against top-down fleet capacity modeling.
Historical deployment patterns from mature North Sea oil and gas basins were cross-referenced against panel input from renewable energy procurement teams to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include vessel type, service category, end-user industry, and operational mode certification tier. CAGRs were derived from supply-demand balance modeling incorporating newbuild delivery schedules, retirement acceleration under EU Green Deal timelines, and charter contract duration shifts toward availability-based structures.
Several conditions sit outside the modeled scope, including unannounced national offshore wind lease round cancellations, abrupt REACH coating compliance deadline extensions, and Korean or Chinese shipyard input pricing volatility beyond historical bands. Material deviation in EU ETS carbon credit price trajectories or hydrogen bunkering infrastructure deployment schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
Barge Transportation Market
Maritime Equipment
Global Connected Ship Market
Maritime Equipment
Asia-Pacific Maritime Satellite Communication Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
Middle East Offshore Support Vessels Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Saudi Arabia Offshore Support Vessel (OSV) Market
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market