
 Marine Engine Monitoring System Market | 2026-2036
Marine Engine Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Engine Monitoring System Market Intelligence
The capability gap between integrated propulsion system providers and specialized component suppliers is reorganizing the competitive positioning for marine engine monitoring. Wärtsilä Corporation leverages its deep expertise in engine manufacturing to offer holistic monitoring solutions. Kongsberg Gruppen ASA specializes in comprehensive digital vessel ecosystems, integrating engine data with other operational systems. ABB Ltd. competes through its strength in automation and electrification platforms, providing advanced control and monitoring.
A marine engine monitoring system is an integrated network of real-time sensors, control units, and software that tracks the operational performance of a vessel's main and auxiliary engines. By measuring parameters like temperature, pressure, and vibration, its primary purpose is to enable predictive maintenance and optimize fuel efficiency. The adoption of predictive analytics and IoT connectivity is a key trend shaping technology choices. Demand from the commercial shipping application segment, driven by large fleet operators, constitutes the largest source of revenue.
Regulations from the International Maritime Organization (IMO), including the Energy Efficiency Existing Ship Index (EEXI), are a primary market catalyst. Standards from the U.S. EPA and policies within the EU Green Deal also mandate stringent engine performance tracking. Consequently, integrating diverse sensor data into a single, verifiable reporting platform is becoming a critical differentiator for system providers.
Market Dynamics
The regulatory imperative for decarbonization, led by the International Maritime Organization, is the central force shaping the marine engine monitoring system market. This pressure compels vessel operators to move beyond basic compliance and invest in advanced data platforms for verifiable performance optimization.
Growth Catalysts
- Regulatory Mandates:The IMO's Carbon Intensity Indicator (CII) and Energy Efficiency Existing Ship Index (EEXI) require continuous data collection, making engine monitoring systems essential for compliance and favorable vessel ratings.
- Predictive Maintenance Adoption:The integration of IoT sensors and predictive analytics allows fleet operators to shift from scheduled to condition-based maintenance, reducing unplanned downtime and cutting operational costs for commercial shipping.
- Hub-Based Demand:Concentrated demand from large fleet operators in major maritime hubs, including Singapore and Rotterdam, accelerates technology adoption and establishes regional best practices for operational efficiency.
Market Restraints
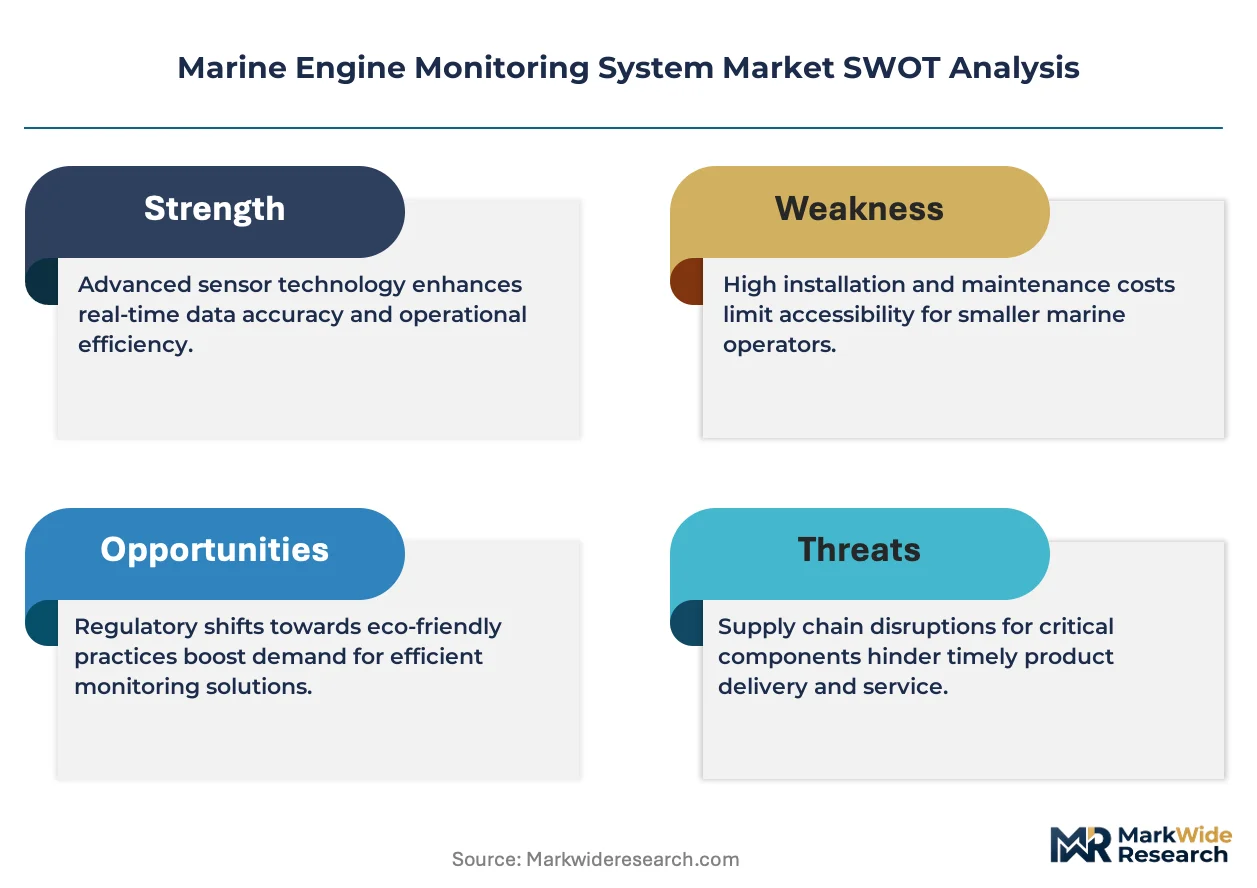
- High Installation Costs:The significant capital expenditure required to retrofit older vessels with comprehensive sensor networks and integrated software platforms presents a major adoption barrier for smaller fleet owners.
- System Integration Complexity:Integrating new monitoring systems with a vessel's existing, often proprietary and multi-vendor, automation and control hardware creates significant technical and interoperability hurdles.
- Cybersecurity Concerns:The increased connectivity of vessel operational technology systems introduces vulnerabilities, with shipowners expressing concerns over potential cyber threats that could compromise engine control or data integrity.
Strategic Opportunities
- Auxiliary System Monitoring:Expanding monitoring capabilities beyond main propulsion engines to include auxiliary machinery, such as generators, scrubbers, and ballast water treatment systems, offers a significant new revenue stream.
- Data-as-a-Service (DaaS) Models:Offering subscription-based access to analytics platforms and reporting tools provides a recurring revenue model and lowers the initial adoption cost for budget-conscious operators.
- Inland and Coastal Fleets:Targeting the largely underpenetrated market of inland waterway barges, coastal freighters, and fishing fleets with scalable, lower-cost monitoring solutions represents a key growth vector.
Industry Challenges
- Data Skill Gaps:A shortage of crew members and onshore technical staff with the expertise to analyze engine performance data and implement data-driven operational changes limits the return on investment for system deployments.
- Interoperability Standards:The absence of a unified data standard across marine equipment manufacturers complicates the aggregation of performance data from different engine components into a single coherent platform.
- Legacy Equipment Integration:The practical difficulty of installing modern sensors and data loggers on older, mechanically controlled engines without extensive and costly modifications remains a persistent operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Engine Monitoring System Market |
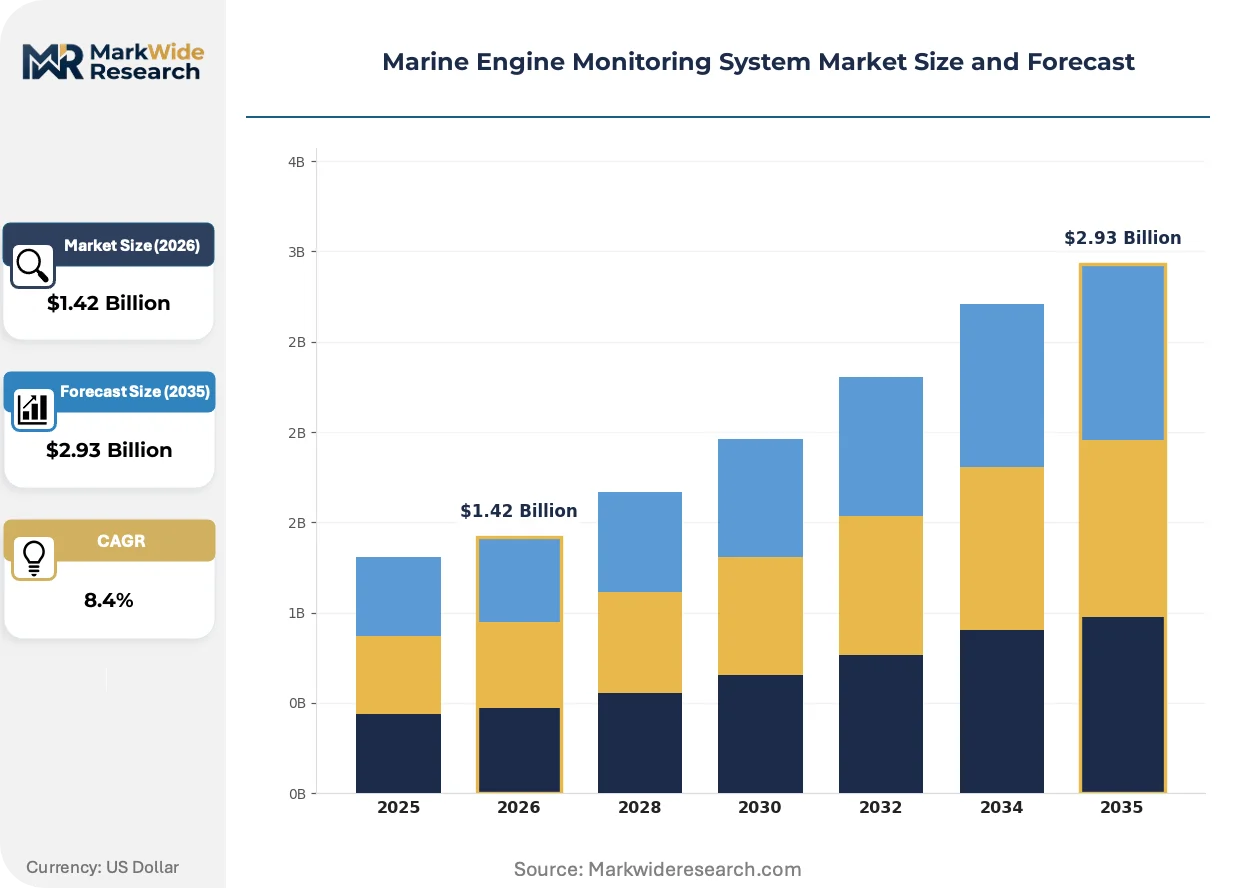
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real-Time Sensors, Diagnostic Software, Control Units, Display Interfaces, Data Loggers Technology: IoT Connectivity, Wireless Monitoring, Predictive Analytics, Remote Access, Cloud Integration Application: Commercial Shipping, Fishing Vessels, Offshore Platforms, Leisure Yachts, Research Boats End User: Fleet Operators, Vessel Maintenance Services, Marine OEMs, Ship Management Firms, Repair Workshops |
| Companies Covered | Wärtsilä Corporation, ABB Ltd., Rolls-Royce plc, Kongsberg Gruppen ASA, Caterpillar Inc., Cummins Inc., Emerson Electric Co., MAN Energy Solutions, CMR Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Engine Monitoring System Market Strategic Shifts & Innovations
The market's evolution is defined by a technological shift from reactive alarm systems to proactive, intelligent platforms that optimize vessel performance. This transition is driven by the convergence of advanced sensor technology, cloud computing, and stringent environmental performance standards.
Wireless, self-powered sensor nodes are a critical enabling technology, designed to capture parameters like vibration and surface temperature without requiring extensive onboard wiring. Commercial fleet operators are steadily adopting these for retrofitting older vessels where cabling is impractical or cost-prohibitive. This technology is miniaturizing the data acquisition footprint and reducing installation complexity, making it feasible to monitor a wider array of ancillary equipment in the engine room.
The International Maritime Organization's framework for reducing greenhouse gas emissions, specifically the Energy Efficiency Existing Ship Index (EEXI), serves as a powerful market accelerator. This regulation mandates technical improvements for existing ships to meet specific efficiency benchmarks. Consequently, the commercial shipping segment is compelled to install verifiable monitoring systems to prove compliance and secure a favorable operational profile, directly linking regulatory adherence to technology investment.
A notable behavioral change is the move from one-time hardware sales toward ongoing contracts for analytics and compliance reporting services. This subscription model displaces the traditional capital expenditure purchase with an operational expense, aligning vendor revenue with customer outcomes. This trend is most advanced among large, publicly-listed shipping companies in Europe and Asia that are under intense pressure from investors to demonstrate ESG performance and operational efficiency.
Marine Engine Monitoring System Market Segmentation
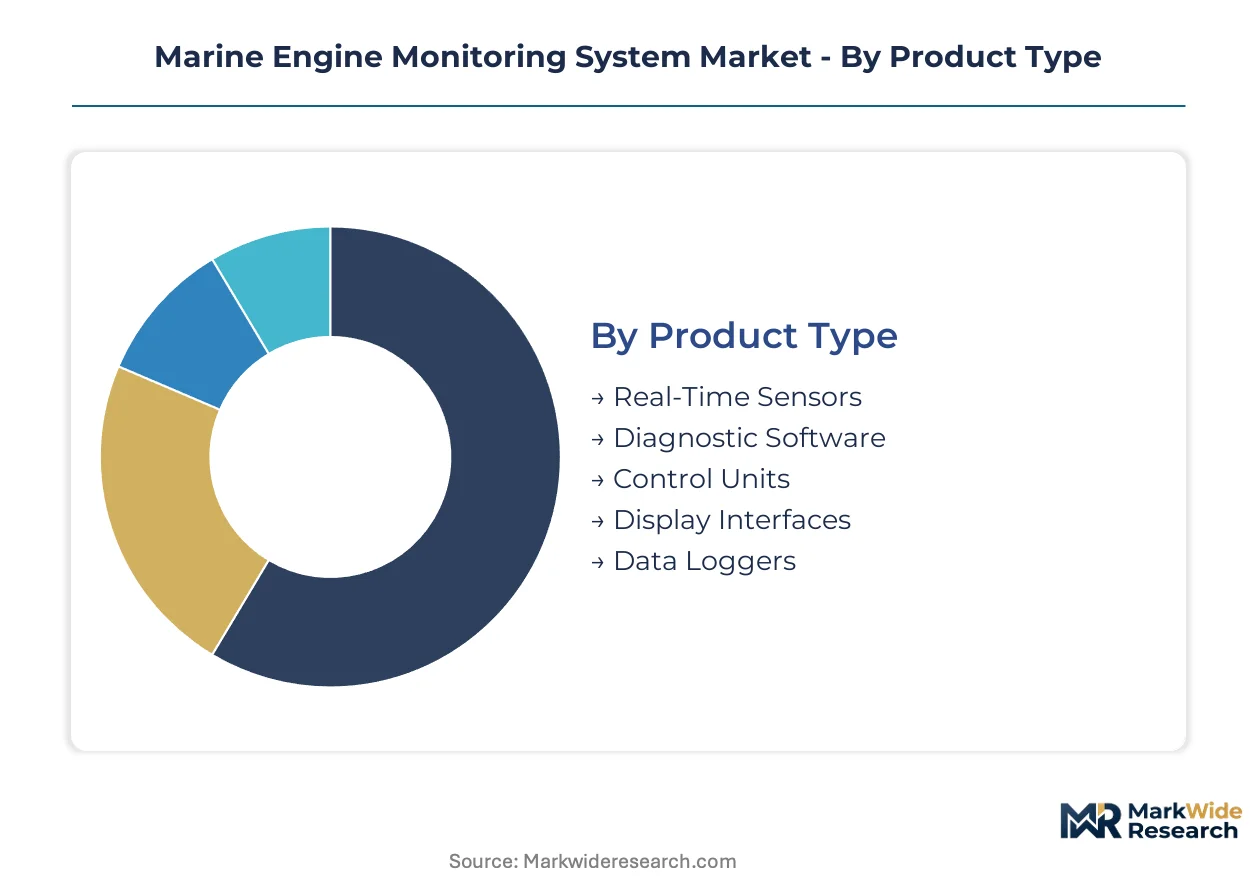
The marine engine monitoring system market is precisely segmented to reflect the diverse operational requirements and technological preferences across the maritime industry. Understanding these distinct segments is crucial for identifying targeted growth opportunities and addressing specific challenges faced by various vessel types and end-users. This granular view enables providers to tailor solutions that maximize efficiency and regulatory compliance.
Product Type:
Margin pools within the product type category are heavily influenced by the complexity and intellectual property embedded in software solutions and advanced sensor technologies.
- Real-Time Sensors:These devices continuously measure critical engine parameters such as temperature, pressure, and vibration, converting physical data into electrical signals. Commercial shipping fleets use these sensors extensively to ensure continuous operational feedback and adherence to performance benchmarks set by the IMO.
- Diagnostic Software:This software analyzes sensor data to identify anomalies, predict potential failures, and recommend maintenance actions, leveraging advanced algorithms and machine learning. Fleet operators rely on diagnostic software to implement predictive maintenance strategies, reducing unplanned downtime and optimizing vessel uptime.
- Control Units:Control units process sensor inputs and manage engine operations, often integrating with a vessel's broader automation system.
- Display Interfaces:These provide visual representations of engine performance data and alerts to crew members on the bridge or in the engine room.
- Data Loggers:Data loggers record engine performance over time for later analysis, compliance reporting, and incident investigation.
The dominant share belongs to Real-Time Sensors, while Diagnostic Software is closing the gap fastest.
Technology:
Demand patterns for technology solutions are primarily shaped by the application requirements of vessel operators and the push for greater operational transparency.
- Predictive Analytics:This technology employs statistical algorithms and historical data to forecast future engine performance issues, enabling proactive maintenance scheduling. Commercial shipping companies prioritize predictive analytics to minimize operational costs and improve fuel efficiency across large fleets.
- IoT Connectivity:IoT connectivity facilitates the seamless transmission of engine data from onboard sensors to cloud platforms for remote monitoring and analysis. Large fleet operators adopt IoT connectivity to enable Data-as-a-Service models and centralized fleet management.
- Wireless Monitoring:Wireless sensor networks reduce installation complexity and cost, particularly for retrofitting older vessels and monitoring auxiliary systems.
- Remote Access:This allows onshore personnel to monitor and diagnose engine performance from anywhere, supporting expert analysis and rapid decision-making.
- Cloud Integration:Cloud platforms provide scalable storage and processing power for vast amounts of engine data, enabling advanced analytics and collaboration.
Predictive Analytics solutions command significant investment, with IoT Connectivity experiencing the steepest expansion trajectory.
Application:
Volume demand within the application segment is overwhelmingly driven by the scale of fleet operations and the stringent regulatory environment governing commercial maritime activities.
- Commercial Shipping:This segment includes container ships, tankers, bulk carriers, and general cargo vessels, characterized by large engines and continuous operation. Commercial shipping operators are compelled by IMO regulations and fuel cost pressures to invest in advanced monitoring for efficiency and compliance.
- Fishing Vessels:These vessels utilize engine monitoring to ensure reliable operation during extended voyages and to optimize fuel consumption for economic viability.
- Offshore Platforms:Engine monitoring on offshore platforms ensures the continuous, safe operation of power generation and propulsion systems in harsh environments.
- Leisure Yachts:Owners of larger leisure yachts deploy monitoring systems for performance optimization, safety, and preventative maintenance.
- Research Boats:Scientific research vessels use engine monitoring to maintain operational integrity during critical missions and to track environmental impact.
Commercial Shipping maintains the largest share, and Offshore Platforms are gaining share most quickly.
End User:
Customer type preferences dictate procurement strategies, influencing the adoption of specialized monitoring services and integrated system packages.
- Fleet Operators:These entities manage multiple vessels and are primarily concerned with operational efficiency, regulatory compliance, and cost reduction across their entire fleet. Fleet operators are key purchasers of comprehensive monitoring systems that offer centralized data management and analytics.
- Vessel Maintenance Services:These third-party providers specialize in the upkeep and repair of marine engines, utilizing monitoring data for condition-based maintenance and diagnostics. These services leverage monitoring systems to offer predictive maintenance contracts and optimize service schedules for their clients.
- Marine OEMs:Original equipment manufacturers integrate monitoring capabilities directly into new engines and propulsion systems before vessel delivery.
- Ship Management Firms:These companies handle the technical and operational management of vessels on behalf of owners, using monitoring data for performance reporting.
- Repair Workshops:Local repair facilities use basic monitoring tools for troubleshooting and verifying engine performance after maintenance.
Fleet Operators represent the largest end-user group, while Vessel Maintenance Services are expanding their utilization rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies across marine engine monitoring system buyers, influencing regional market dynamics. Some fleet operators prioritize cost-effective compliance solutions, while others seek advanced data platforms for competitive operational gains. This dichotomy shapes regional adoption patterns across major maritime nations.
Singapore
Demand for marine engine monitoring systems in Singapore stems from its status as a major global shipping hub with extensive fleet operations. The Maritime and Port Authority of Singapore (MPA) actively promotes digitalization and decarbonization initiatives for local and international vessels. Singapore's highly concentrated maritime cluster drives rapid adoption of advanced monitoring technologies.
Netherlands
The Netherlands experiences strong demand for engine monitoring systems due to its significant commercial shipping fleet and the port of Rotterdam. EU Green Deal policies and stringent local environmental regulations compel vessel operators to invest in verifiable performance tracking. Rotterdam, as Europe's largest port, serves as a key innovation center for maritime digital solutions.
United States
United States demand for engine monitoring systems is driven by a large domestic fleet and increasing environmental scrutiny. The U.S. Environmental Protection Agency (EPA) mandates strict emissions reporting for marine engines operating in U.S. waters. Major ports along the Gulf Coast and East Coast are implementing advanced monitoring for operational efficiency and regulatory compliance.
China
China's vast commercial shipping fleet and ambitious environmental targets contribute significantly to the demand for engine monitoring technology. The Ministry of Ecology and Environment (MEE) implements policies to reduce shipping emissions, requiring robust data collection. Shanghai, a global shipping hub, is a focal point for technology deployment and maritime innovation.
Germany
Germany's maritime sector, known for its technological prowess, generates substantial demand for advanced marine engine monitoring systems. European Union regulations, including those stemming from the EU Green Deal, push for enhanced energy efficiency and emissions reduction. Hamburg, a prominent port city, hosts numerous shipping companies and maritime technology providers.
Marine Engine Monitoring System Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the marine engine monitoring market. The market exhibits a tiered structure, with established industrial conglomerates offering integrated solutions alongside specialized software and sensor providers. Strategic partnerships for technology co-development and targeted acquisitions of analytics firms are dominant competitive moves.
Integrated propulsion system providers, such as Wärtsilä Corporation, exemplify a holistic approach, leveraging their deep engine manufacturing expertise to offer comprehensive monitoring solutions that often extend across the entire vessel lifecycle. Kongsberg Gruppen ASA occupies a significant position as a specialist in comprehensive digital vessel ecosystems, effectively integrating engine data with broader operational systems for overall fleet management and optimization. Additionally, ABB Ltd. represents a major automation and electrification platform provider, delivering advanced control and monitoring capabilities that span diverse marine applications and contribute to wider vessel automation.
| Leading Market Players |
|---|
| Wärtsilä Corporation |
| ABB Ltd. |
| Rolls-Royce plc |
| Kongsberg Gruppen ASA |
| Caterpillar Inc. |
| Cummins Inc. |
| Emerson Electric Co. |
| MAN Energy Solutions |
| CMR Group |
| Others |
Cost & Logistics Intelligence
Project-based procurement for complex integrated systems, common among large fleet operators, locks in both long-term supply access and price visibility for advanced marine engine monitoring solutions. This contract structure mitigates volatility in component sourcing.
Pricing Analysis
Ongoing service contracts and subscription-based analytics platforms drive significant lifetime value in the marine engine monitoring market. The dominant pricing model is a hybrid structure, combining initial hardware sales with recurring software and service fees. Price differentiation stems from the level of customization required for integration with legacy systems and the sophistication of predictive analytics capabilities. Pricing softness impacts basic sensor installations due to increased competition, while advanced diagnostic software commands premium pricing. Smaller fleet owners exhibit higher price sensitivity compared to large commercial shipping operators.
Supply Chain Analysis
The sourcing of specialized electronic components, crucial for advanced sensors and control units, relies heavily on manufacturing hubs in China and Southeast Asia. Key raw material dependencies include rare earth elements for sensor fabrication and microprocessors for diagnostic software. A significant supply chain risk involves potential geopolitical disruptions affecting semiconductor production and global shipping routes. Distribution of marine engine monitoring systems primarily runs through direct sales channels to large fleet operators and maritime OEMs, complemented by a network of specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, driven by the accelerating penetration of advanced monitoring technologies across commercial shipping fleets. Regulatory mandates from the International Maritime Organization serve as a powerful tailwind for technology adoption.
For Market Incumbents: Shield core market share by deepening integration capabilities for auxiliary systems beyond main engines, anticipating expanding regulatory scope. Consolidate expertise in data analytics to counter emerging specialized software providers, who pose a threat with focused AI solutions. Invest in robust cybersecurity frameworks to protect proprietary operational technology, a critical lever for customer trust and data integrity.
For New Entrants and Emerging Players: Differentiate on ease of installation and interoperability, targeting the underpenetrated inland and coastal fleets with scalable, lower-cost solutions. Focus on developing open-architecture platforms that seamlessly integrate with diverse legacy equipment, addressing system integration complexity. A data-as-a-service model, offering subscription-based analytics and compliance reporting, presents a strong go-to-market angle for budget-conscious vessel operators.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized software firms offering advanced predictive analytics and AI-driven diagnostic capabilities, which promise long-term viability in maritime digitalization. Seek acquisition targets that possess strong intellectual property in wireless sensor technology or comprehensive data integration platforms. The increasing stringency of IMO decarbonization targets and the expansion of DaaS models serve as key signals to watch for accelerating market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Predictive Analytics Firm | Enables market incumbents to enhance diagnostic software capabilities and offer more sophisticated data-driven insights to fleet operators. |
| Expansion into Auxiliary System Monitoring | Unlocks new revenue streams by applying monitoring expertise to generators and ballast water systems, driven by operational efficiency demands. |
| Development of Open-Architecture Integration Kits | Addresses system integration complexity for vessel operators, facilitating easier adoption of advanced monitoring solutions across diverse fleets. |
| Launch of Data-as-a-Service Subscription Tiers | Lowers initial adoption barriers for budget-conscious customers, converting capital expenditure into recurring operational expense for fleet managers. |
| Targeted Solutions for Inland Waterway Fleets | Penetrates a largely underserved market segment with scalable, cost-effective monitoring systems tailored to smaller vessel requirements. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation through public data sources. Primary research involved discussions with marine engineers, fleet operations managers, maritime technology developers, and regulatory compliance officers. Secondary data sources included maritime industry reports, official publications from the International Maritime Organization, company annual reports, and technical journals. This approach facilitated both bottom-up market sizing and top-down validation of market trends.
The analytical framework projects market performance across the analysis window, modeling growth trajectories for key segments. Segmentation dimensions modeled included product type, technology, application (e.g., commercial shipping, offshore platforms), end-user, and regional maritime hubs. Compound Annual Growth Rates were derived from historical data analysis and projected market drivers. Industry-specific forecast inputs included projected new vessel deliveries and anticipated regulatory compliance timelines.
Material uncertainties — such as unforeseen shifts in global trade volumes or rapid advancements in alternative propulsion technologies — sit outside the modeled envelope, influencing long-term market dynamics. Forecasts reflect assumptions regarding regulatory enforcement and technological adoption rates. Practitioners should keep alternative scenarios live as geopolitical stability and decarbonization mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Marine Hatch Covers Market
Maritime Equipment
Middle East Offshore Support Vessels Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Europe Inland Water Freight Transport Market
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Ship Anchor Market