
 Persian Gulf Offshore Support Vessels (OSV) Market | 2026-2036
Persian Gulf Offshore Support Vessels (OSV) Market Size, Share, and Industry Trends Forecast 2026-2036
Persian Gulf Offshore Support Vessels (OSV) Market Analytics
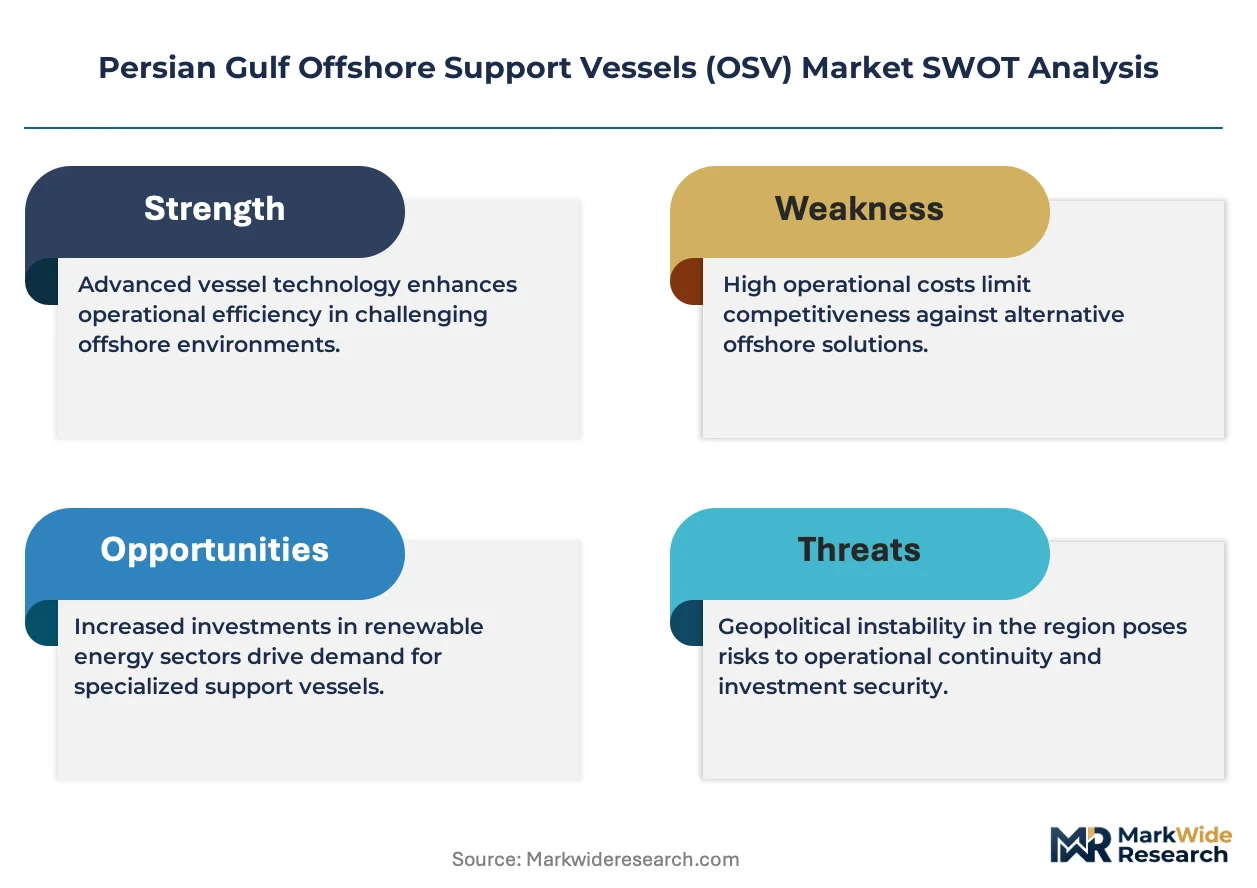
Saudi Arabia's King Salman International Maritime Industries Complex is reconfiguring regional build capacity for large-tonnage OSV construction. Zamil Offshore Services Co. anchors its position through backward integration into ship repair and fabrication yards across Dammam and Jubail. Tidewater Inc sustains competitive relevance by leveraging its standardized global fleet architecture for rapid redeployment into Persian Gulf charter markets. Maersk Supply Service differentiates through advanced dynamic positioning systems purpose-built for harsh-environment platform supply operations.
Offshore Support Vessels are purpose-built marine craft typically ranging from 50 to 150 meters in length, powered by diesel-electric or hybrid propulsion systems, designed to transport personnel, equipment, and supplies to offshore oil and gas installations while maintaining station-keeping capability in sea states up to 5 meters significant wave height. Platform Supply Vessels dominate current fleet deployment due to their versatility in dry bulk and liquid cargo transfer, while Anchor Handling Tug Supply Vessels command premium day rates reflecting their specialized winch and bollard pull specifications for mobile offshore drilling unit positioning. Crew Boats represent the fastest-growing vessel category as marginal field developments and remote platform clusters multiply, though margin pools remain thinner than on larger tonnage.
The International Maritime Organization's MARPOL Annex VI sulfur caps, enforced by port state control authorities in Kuwait, Bahrain, and the UAE, mandate exhaust gas cleaning systems or low-sulfur fuel switching that elevates both newbuild costs and retrofit obligations for existing fleets. Saudi Arabia's Saudi Standards, Metrology and Quality Organization and the UAE's Federal Transport Authority jointly enforce safety of life at sea protocols that shape crew accommodation standards and emergency response equipment fitment. Classification society rules from Lloyd's Register and DNV further constrain hull design and machinery redundancy for operations above the Qatar North Field and Iran's South Pars complex. Stakeholders must weigh charter duration commitments against impending emissions compliance deadlines and the capital intensity of dual-fuel engine investments.
Market Dynamics
Fleet renewal mandates under Saudi Vision 2030 industrial localization requirements are compressing charter contract durations while elevating local content thresholds for vessel construction and crew sourcing across the Persian Gulf.
Growth Catalysts
- Abu Dhabi Offshore Megaprojects:ADNOC's expansion of the Lower Zakum and Umm Shaif fields is generating sustained demand for platform supply vessels with enhanced cargo capacity specifications.
- MARPOL Annex VI Enforcement:Port state control authorities in Kuwait, Bahrain, and the UAE are accelerating exhaust gas cleaning system retrofits that favor newer tonnage in charter selection.
- Hybrid Propulsion Maturation:Diesel-electric and battery-hybrid systems are reducing fuel consumption profiles for crew boat operations serving remote platform clusters.
Market Restraints
- Steel and Specialized Equipment Costs:Hull-grade steel plate and dynamic positioning system components face price volatility tied to global metallurgical supply chains.
- Regional Build Concentration:King Salman International Maritime Industries Complex and limited alternative yards in Ras Al Khair create single-point vulnerability for large-tonnage construction.
- Crew Accommodation Standards:Saudi Standards, Metrology and Quality Organization and UAE Federal Transport Authority protocols mandate space and amenity specifications that elevate newbuild costs disproportionately for smaller operators.
Strategic Opportunities
- Qatar North Field Expansion:The world's largest non-associated gas field development is creating demand for anchor handling tug supply vessels with 200+ tonne bollard pull ratings.
- Remote Platform Cluster Servicing:Marginal field developments off Iran's South Pars complex require fast crew boat turnaround protocols that favor operators with distributed port access.
- Dual-Fuel Engine Incentives:LNG-ready propulsion investments align with impending IMO carbon intensity indicator deadlines and attract preferential charter terms from NOC sustainability procurement frameworks.
Industry Challenges
- Marine Engineer Shortage:Specialized training for dynamic positioning system maintenance and hybrid power management exceeds regional vocational pipeline output.
- Classification Timeline Compression:Lloyd's Register and DNV hull certification queues for harsh-environment rating extensions are extending vessel deployment schedules.
- Legacy Fleet Retrofit Coordination:Existing platform supply vessels require synchronized exhaust gas cleaning installation with charter renewal cycles to avoid revenue interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Persian Gulf Offshore Support Vessels (OSV) Market |
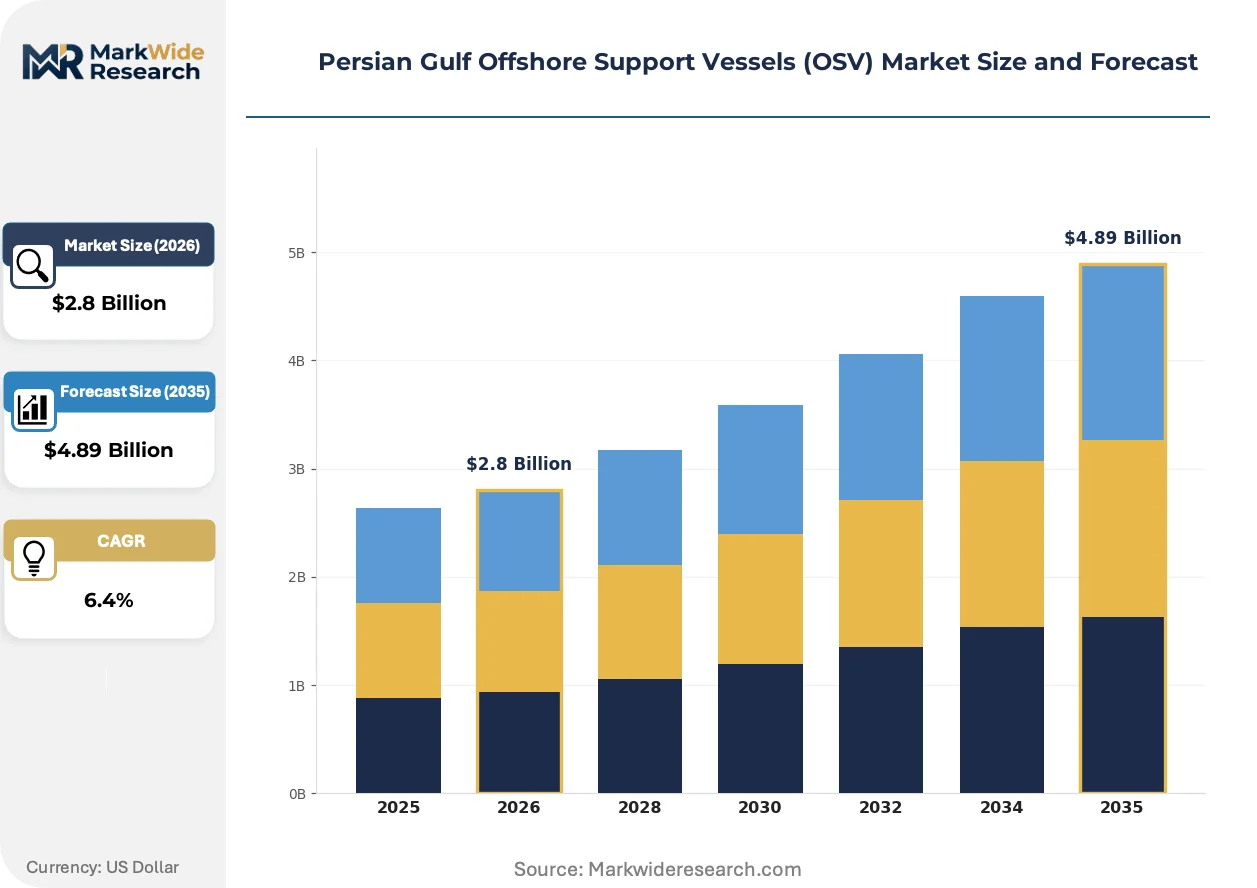
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Platform Supply Vessels, Anchor Handling Tug Supply Vessels, Crew Boats, Multipurpose Support Vessels Service Type: Logistics Support, Well Intervention, Survey Services, Diving Support End User: Oil & Gas Companies, Marine Contractors, Government Agencies, Renewable Energy Firms Maintenance Type: Preventive Maintenance, Predictive Maintenance, Reactive Maintenance, Overhaul Services |
| Companies Covered | Vortex Offshore Group, Zamil Offshore Services Co., Tidewater Inc, Bourbon Corporation SA, Maersk Supply Service, Seacor Marine Holdings Inc, MMA Offshore Limited, Baltic Marine Services LLC, Abu Dhabi National Oil Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Persian Gulf Offshore Support Vessels (OSV) Market Evolving Landscape
Propulsion architecture and charter contracting models are undergoing simultaneous transformation as emission compliance deadlines and operator cost pressures converge across Persian Gulf offshore operations.
Hybrid diesel-electric systems are migrating from niche demonstration projects to standard specification for newbuild platform supply vessels above 80 meters length. ADNOC and QatarEnergy chartering departments now require hybrid readiness in tender documentation for contracts exceeding five years duration. This technology migration is compressing residual values of pure diesel tonnage and accelerating scrapping decisions for pre-2010 fleet segments.
Saudi Arabia's Vision 2030 industrial localization mandates are reshaping vessel construction eligibility criteria for state-linked charter contracts. The Saudi Standards, Metrology and Quality Organization now enforces minimum local fabrication content thresholds that disqualify pure import builds from Aramco-affiliated tenders. This regulatory shift is forcing European and Asian shipyards into joint venture structures with Ras Al Khair-based facilities.
Long-term bareboat charter arrangements are fragmenting into shorter-term contracts with performance-linked rate adjustment clauses. NOC procurement departments favor two-to-three year agreements with fuel efficiency benchmarks over traditional decade-long fixtures. This contracting evolution is most visible in Abu Dhabi, where ADNOC Logistics Services has piloted indexed-rate structures tying day rates to documented carbon intensity performance.
Persian Gulf Offshore Support Vessels (OSV) Market Segmentation
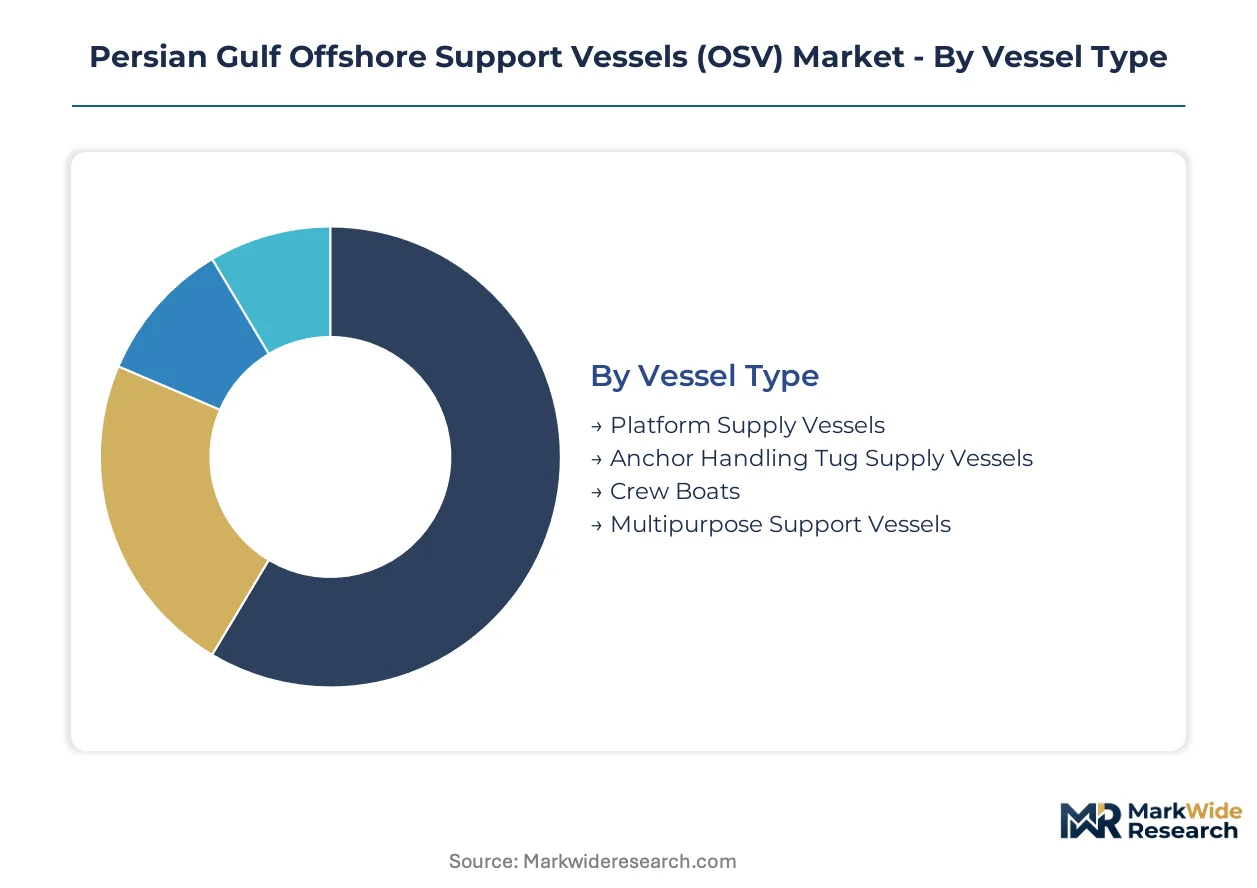
Vessel configuration and service intensity directly shape aftermarket revenue capture across Persian Gulf offshore operations. Charter contract structures now embed maintenance obligation clauses that segment service providers by technical capability tiers.
Vessel Type:
After-sales service intensity escalates with vessel complexity and propulsion system sophistication across the four primary hull categories.
- Platform Supply Vessels:Diesel-electric and hybrid propulsion architectures dominate newbuild specifications above 80 meters length. ADNOC's Lower Zakum and Umm Shaif field expansions are concentrating demand for enhanced cargo capacity variants with integrated dynamic positioning systems.
- Anchor Handling Tug Supply Vessels:Specialized winch systems and 200+ tonne bollard pull ratings command premium technical support contracts. Qatar North Field development is driving specifications for harsh-environment station-keeping capability in sea states approaching 5 meters significant wave height.
- Crew Boats:Fast turnaround protocols for marginal field clusters favor distributed port access models over centralized maintenance hubs.
- Multipurpose Support Vessels:Modular deck configurations accommodate ROV deployment and light construction duties across Abu Dhabi's offshore megaprojects.
Platform Supply Vessels hold the largest share; momentum sits with Crew Boats as remote platform multiplication accelerates.
Service Type:
Cost tier differentiation separates commodity logistics from specialized intervention services requiring certified equipment and personnel.
- Logistics Support:Dry bulk and liquid cargo transfer operations constitute baseline charter revenue with thinner margin profiles. Saudi Aramco's procurement frameworks now require carbon intensity documentation for contracts exceeding five years duration.
- Well Intervention:Coiled tubing and wireline deployment from dynamically positioned vessels commands day rate premiums reflecting equipment redundancy requirements. QatarEnergy's tender documentation increasingly mandates hybrid readiness for intervention fleet contracts.
- Survey Services:Seabed mapping and pipeline inspection contracts tie vessel availability to seasonal weather windows in the Gulf's summer heat.
- Diving Support:Saturation diving systems require hyperbaric chamber certification queues that extend deployment schedules through Lloyd's Register and DNV protocols.
Logistics Support dominates charter volume; steepest expansion trajectory belongs to Well Intervention as brownfield optimization intensifies.
End User:
Customer type determines contract duration, local content compliance thresholds, and technical specification rigor across procurement frameworks.
- Oil & Gas Companies:NOC chartering departments in Abu Dhabi and Qatar anchor fleet utilization with multi-year agreements. ADNOC Logistics Services pilots indexed-rate structures tying day rates to documented fuel efficiency performance.
- Marine Contractors:Project-specific fixtures for drilling unit positioning concentrate demand around Ras Al Khair and Dammam port clusters.
- Government Agencies:Border patrol and search-and-rescue mandates generate stable utilization for smaller tonnage in Kuwaiti and Bahraini waters.
- Renewable Energy Firms:Offshore wind foundation installation support remains nascent in Persian Gulf waters but attracts pilot charter interest from European contractors.
Oil & Gas Companies command the greatest fleet share; Renewable Energy Firms are climbing the fastest as Gulf states diversify generation portfolios.
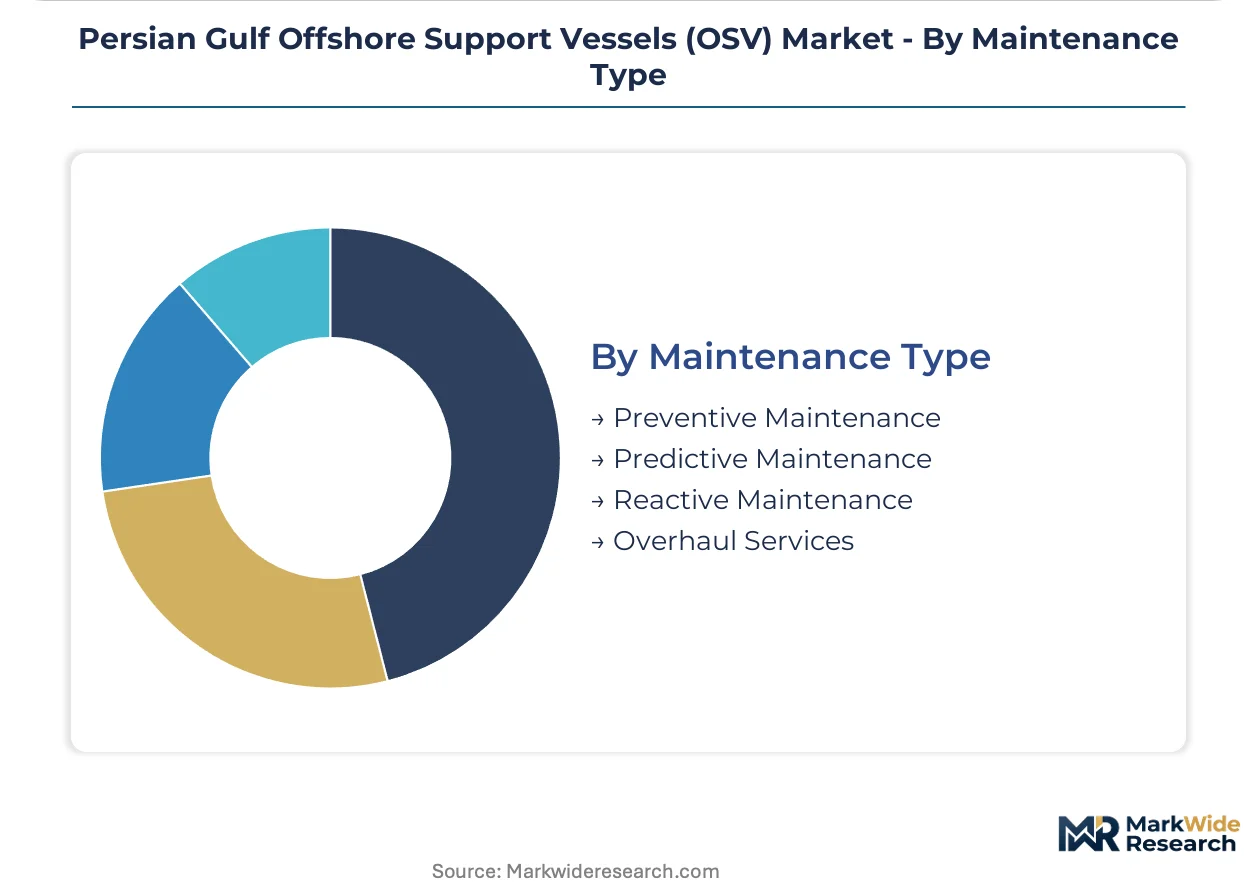
Maintenance Type:
Maturity gradients separate legacy reactive approaches from predictive systems enabled by sensor proliferation and remote diagnostics.
- Preventive Maintenance:Scheduled dry-docking and machinery overhauls align with charter renewal cycles to minimize revenue interruption. Saudi Standards, Metrology and Quality Organization protocols mandate inspection intervals that shape fleet deployment planning.
- Predictive Maintenance:Vibration monitoring and oil analysis for main engines and thruster systems reduce unplanned downtime. Classification society digitalization initiatives from Lloyd's Register enable remote survey credit for vessels with continuous condition monitoring.
- Reactive Maintenance:Breakdown response remains prevalent for pre-2010 fleet segments facing residual value compression.
- Overhaul Services:Exhaust gas cleaning system retrofits and dual-fuel engine conversions concentrate demand at King Salman International Maritime Industries Complex and limited alternative yards.
Preventive Maintenance retains the greatest service volume; Predictive Maintenance is gaining share fastest as sensor costs decline and charterers prioritize availability guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA and MOHAP enforcement of MARPOL Annex VI sulfur caps across Kuwaiti and Bahraini port state control jurisdictions is compressing fleet deployment schedules for operators serving Saudi and Emirati offshore fields.
Saudi Arabia
ADNOC's Lower Zakum expansion and QatarEnergy's North Field development are generating parallel demand for platform supply vessels with enhanced cargo specifications. Saudi Standards, Metrology and Quality Organization mandates local fabrication content thresholds that reshape Aramco-affiliated tender eligibility. Ras Al Khair industrial city anchors large-tonnage construction capacity through King Salman International Maritime Industries Complex.
United Arab Emirates
Abu Dhabi's Umm Shaif offshore megaproject concentrates charter demand for dynamically positioned supply vessels above 80 meters length. Federal Transport Authority protocols enforce crew accommodation standards that elevate newbuild costs disproportionately for smaller operators. Jebel Ali and Mina Zayed port clusters serve as primary logistics hubs for UAE offshore operations.
Qatar
QatarEnergy's North Field expansion is creating specialized demand for anchor handling tug supply vessels with 200+ tonne bollard pull ratings. MOHAP-aligned safety of life at sea protocols shape emergency response equipment fitment requirements. Ras Laffan industrial city hosts the primary fabrication and deployment infrastructure for Qatari offshore fleet operations.
Kuwait
Kuwait Oil Company's shallow field development programs sustain baseline demand for crew boat operations with fast turnaround protocols. Port state control authorities enforce MARPOL Annex VI compliance that accelerates exhaust gas cleaning system retrofits. Al Ahmadi and Mina Al Ahmadi port facilities concentrate vessel maintenance and crew transfer operations.
Bahrain
Bahrain Petroleum Company's offshore maintenance programs generate stable utilization for smaller platform supply vessels in the Gulf's northern waters. National regulations align with IMO sulfur cap enforcement through coordinated port state control measures. Askar and Sitra industrial areas host limited but strategic vessel support infrastructure for Bahraini offshore operations.
Persian Gulf Offshore Support Vessels (OSV) Market Competitive Landscape
State-affiliated operators and international fleet managers split the market along charter contract duration and local content compliance vectors. Consolidation pressure concentrates around multi-year NOC procurement frameworks that favor established relationships over new entrants. Three archetypes dominate: vertically integrated national champions with captive fabrication capacity, global fleet standardization specialists with rapid redeployment capability, and regional service providers with distributed port access. Competitive moves center on joint venture structuring with Saudi build yards and hybrid propulsion technology licensing for five-year charter eligibility.
Within the national champion tier, Zamil Offshore Services Co. and Abu Dhabi National Oil Company exemplify backward integration into fabrication and repair infrastructure. Among international operators, Tidewater Inc and Maersk Supply Service occupy positions shaped by standardized fleet architectures and harsh-environment operational specialization. Bourbon Corporation SA and Seacor Marine Holdings Inc represent the mid-scale international segment competing on regional port coverage and charter flexibility.
| Leading Market Players |
|---|
| Vortex Offshore Group |
| Zamil Offshore Services Co. |
| Tidewater Inc |
| Bourbon Corporation SA |
| Maersk Supply Service |
| Seacor Marine Holdings Inc |
| MMA Offshore Limited |
| Baltic Marine Services LLC |
| Abu Dhabi National Oil Company |
| Others |
Value Network & Pricing Analysis
Hull-grade steel plate concentration in South Korean and Japanese metallurgical supply chains directly determines where margin pools accumulate across Persian Gulf OSV construction. Charter rate premiums for hybrid-ready tonnage reflect this upstream bottleneck, while retrofit obligations compress residual values for pure diesel fleets.
Pricing Analysis
Day rate spreads between Ras Al Khair-built and Far East-imported vessels now exceed fifteen percentage points across five-year fixtures. Three-tier pricing structure across harsh-environment premium, standard DP-2, and economy non-DP specifications reflects bollard pull ratings and hybrid readiness tiers. Pricing pressure stems from Saudi Standards, Metrology and Quality Organization local content mandates that disqualify pure import builds from Aramco-linked tenders. International operators with standardized global fleets exhibit lowest price sensitivity; smaller regional contractors face acute margin compression on legacy diesel tonnage.
Supply Chain Analysis
Export control regimes governing dynamic positioning system software and hybrid power management electronics constrain technology flows into Ras Al Khair fabrication yards. Supply concentrates in South Korea, Japan, and Germany for specialized winch systems, thruster units, and exhaust gas cleaning components. Steel plate and DP system dependencies create single-source vulnerability for large-tonnage construction schedules. Distribution runs through King Salman International Maritime Industries Complex and limited alternative facilities in Jubail, with charter contract synchronization determining dry-docking queue priority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid propulsion mandates and MARPOL Annex VI enforcement deadlines are compressing fleet renewal cycles across Persian Gulf offshore operations. This regulatory-technology inflection creates asymmetric opportunity for operators with LNG-ready newbuild capacity.
For Market Incumbents: Pre-empt residual value collapse by accelerating scrapping decisions for pre-2010 pure diesel tonnage before IMO carbon intensity indicator deadlines harden charter eligibility. Secure captive fabrication slots at Ras Al Khair through joint venture structures with Zamil Offshore Services Co. to defend position against Saudi local content thresholds.
For New Entrants and Emerging Players: Marginal field crew boat operations off Iran's South Pars complex represent the most penetrable entry point, given distributed port access requirements and thinner incumbent concentration. Fast turnaround protocols favor operators with multi-point hub strategies over centralized maintenance models; partner with Bahrain Petroleum Company maintenance programs to establish initial utilization.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale operators with hybrid-ready orderbooks and established NOC relationships across the five-to-ten year viability window. Acquisition targets should demonstrate Lloyd's Register or DNV certification queues already in progress. Watch for ADNOC Logistics Services indexed-rate pilot expansion as signal of carbon-linked charter standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture with Saudi Fabrication Yards | Saudi Standards, Metrology and Quality Organization local content thresholds now mandate Ras Al Khair participation for Aramco tender eligibility. |
| Hybrid Propulsion Technology Licensing | ADNOC and QatarEnergy charter documentation now requires hybrid readiness for contracts exceeding five years duration. |
| Exhaust Gas Cleaning Retrofit Coordination | Synchronized installation with charter renewal cycles minimizes revenue interruption for legacy platform supply vessel fleets. |
| Distributed Port Access Expansion | Remote platform cluster multiplication off South Pars and Lower Zakum favors fast crew boat turnaround capabilities. |
| Dynamic Positioning Certification Acceleration | Lloyd's Register and DNV queue compression for harsh-environment ratings extends deployment schedules for unqueued tonnage. |
Research Methodology
Operator-level perspectives from chartering managers at ADNOC Logistics Services, QatarEnergy marine procurement, and Zamil Offshore fleet operations anchored the qualitative base. Secondary validation drew from Lloyd's Register classification records, DNV vessel databases, and Saudi Standards, Metrology and Quality Organization regulatory filings. Bottom-up vessel deployment tallies across Abu Dhabi, Qatar, and Saudi fields were triangulated against top-down fleet capacity estimates from port authority manifests.
Scenario-bracketing around MARPOL Annex VI enforcement timelines and Saudi Vision 2030 localization milestones shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vessel type, propulsion architecture, service intensity tier, and end-user procurement framework. CAGRs were derived from charter rate trajectory analysis and newbuild delivery schedules, with fuel efficiency benchmarking and carbon intensity documentation requirements serving as key forecast inputs.
Practitioners should monitor IMO carbon intensity indicator implementation pace and Saudi Aramco local content threshold adjustments for early signals of forecast revision. Cross-checking against Lloyd's Register and DNV vessel orderbook disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Green Ship Recycling Market
Maritime Equipment
LNG Carrier Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Container Docking Stations Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Marine Steering Gear Systems Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
Europe Offshore Support Vessels Market