
 Very Large Gas Carrier Market | 2026-2036
Very Large Gas Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Very Large Gas Carrier Market Analytics
Multi-source chartering from integrated energy majors is pivoting toward longer-term contracts with independent vessel owners. BW Group leverages its scale across dual-fuel newbuild programs to secure decade-long offtake agreements. Mitsui O.S.K. Lines anchors its position through ammonia carrier R&D partnerships with Japanese engine builders. Dynagas competes by specializing in ice-class VLGC deployments for Baltic and Arctic routes.
A very large gas carrier denotes a liquefied gas transport vessel typically exceeding 80,000 cubic meters in cargo tank capacity, employing either membrane or independent spherical containment systems designed for thermal insulation and structural integrity at cryogenic temperatures. These vessels serve the intercontinental movement of liquefied petroleum gas, liquefied natural gas, and emerging ammonia cargoes from export terminals to import-receiving markets. Membrane-type vessels dominate newbuild orderbooks due to superior volumetric efficiency and lower steel weight, while Moss-type configurations retain niche demand for high-boil-off cargo trades. Fuel-type segmentation shows liquefied natural gas propulsion gaining yard slots as shipowners anticipate EU ETS carbon cost exposure, though liquefied petroleum gas remains the dominant revenue payload.
International Maritime Organization MARPOL Annex VI regulations, EU Emissions Trading System maritime inclusion, and South Korean Green New Deal shipyard subsidies collectively mandate carbon-intensity reductions and alternative-fuel readiness in new VLGC construction. Classification societies DNV and Lloyd's Register have issued provisional ammonia-fuel rules that now shape owner-engineyard negotiations. Stakeholders must monitor which containment system and fuel pairing achieves commercial scale first, as this choice will lock in fleet competitiveness for twenty-plus year asset lifecycles.
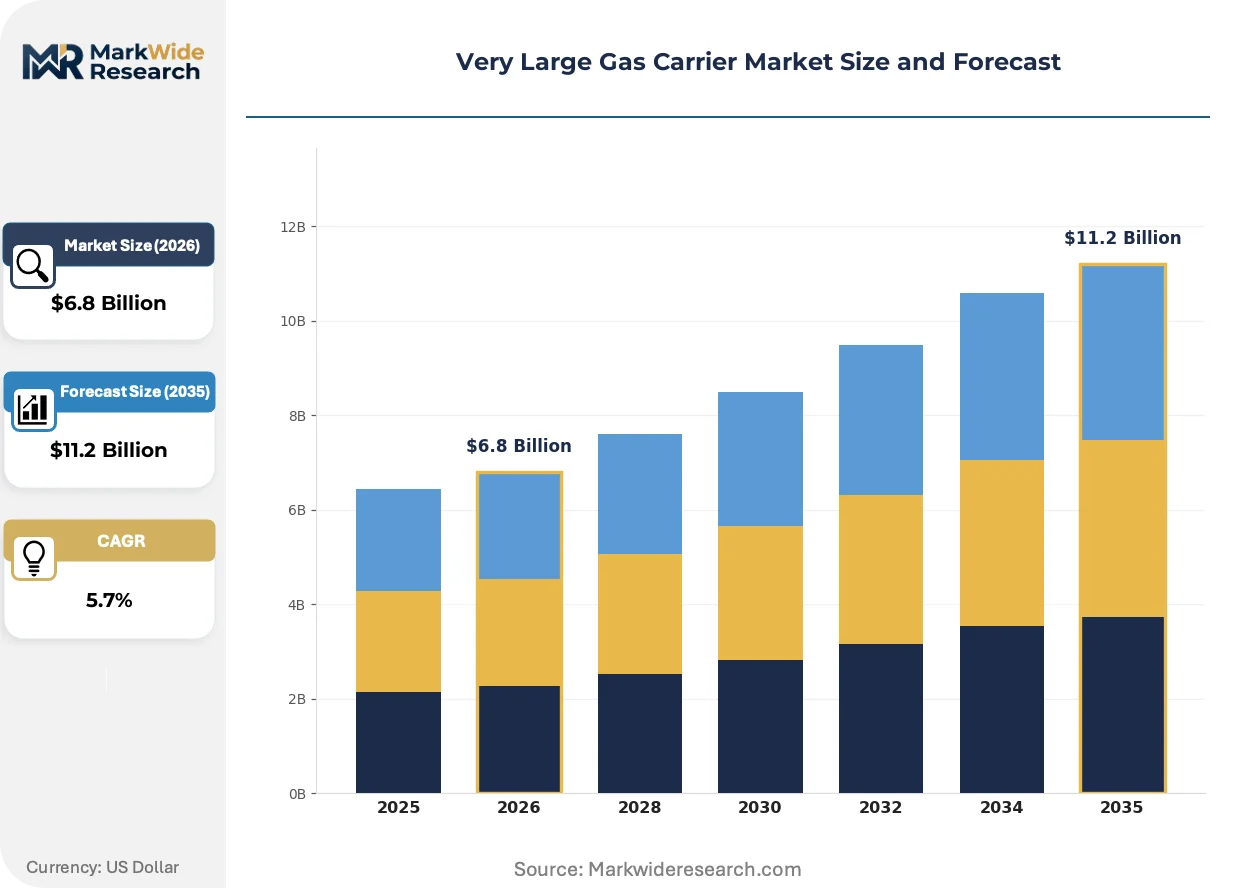
Market Dynamics
Ammonia-ready engine specifications and dual-fuel propulsion systems are forcing a generational replacement cycle across the VLGC fleet. Shipowners face binary technology bets that will lock in competitiveness for twenty-plus year asset lifecycles.
Growth Catalysts
- EU ETS Maritime Inclusion:Carbon pricing exposure accelerates LNG dual-fuel newbuild orders as owners hedge against compliance costs.
- Qatari Liquefaction Expansion:North Field East and West projects concentrate export volumes requiring dedicated long-haul tonnage.
- Membrane Containment Systems:Superior volumetric efficiency drives yard slot allocation away from Moss-type spherical tanks.
Market Restraints
- Stainless Steel Input Volatility:Cryogenic-grade 304L and 316L alloy prices swing with nickel market turbulence, squeezing newbuild margins.
- South Korean Yard Concentration:Hyundai Heavy, Samsung Heavy, and Daewoo control over seventy percent of VLGC construction capacity, creating bottleneck risk.
- Ammonia Fuel Toxicity Limits:Provisional DNV and Lloyd's Register rules restrict engine-room configuration options pending full certification.
Strategic Opportunities
- Japanese Ammonia Carrier R&D:METI-funded partnerships between engine builders and shipowners position first-movers for hydrogen economy logistics.
- Arctic Route Ice-Class Demand:Northern Sea Route year-round operations require strengthened hull specifications currently underserved by standard fleet.
- Retrofit-Ready Contracting:Ammonia-capable LNG dual-fuel newbuilds preserve optionality for fuel pivot without full replacement.
Industry Challenges
- Cryogenic Welding Certification:Qualified 9% nickel steel welders remain scarce relative to yard expansion timelines.
- Containment System Conversion Complexity:Membrane-to-Moss retrofits face structural incompatibility blocking second-hand market flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Very Large Gas Carrier Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Membrane, Moss, Semi-Membrane, Converted Fuel Type: Liquefied Natural Gas, Liquefied Petroleum Gas, Hydrogen, Biofuel Operation Mode: Fully Automated, Manually Operated, Semi-Automated, Remote Controlled Customer Type: LNG Exporters, Shipping Companies, Port Authorities, Energy Providers |
| Companies Covered | Maran Gas Maritime, MISC Berhad, BW Group, Dynagas, Seapeak, Mitsui O.S.K. Lines, GasLog, Navios Maritime Partners, NYK Line, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Very Large Gas Carrier Market Evolving Landscape
Propulsion technology, regulatory carbon accounting, and charter contract structures are simultaneously rewriting fleet economics. Each shift demands coordinated responses across engineering, finance, and operations functions.
Ammonia dual-fuel engine development is rewriting the competitive hierarchy among engine licensors. MAN Energy Solutions and WinGD accelerate ammonia injection system testing as Korean yards demand fuel-flexible specifications. First-mover shipowners securing ammonia-ready tonnage gain preferential access to emerging hydrogen carrier trades.
IMO MARPOL Annex VI carbon intensity indicators now enforce annual efficiency ratio compliance with escalating stringency. Shipowners failing CII grade thresholds face operational restrictions in EU and Chinese ports. The regulation compresses asset lifecycles for older steam-turbine vessels while accelerating demolition of non-compliant tonnage.
Charterers in East Asian petrochemical feedstock procurement consolidate volume commitments into decade-long contracts with independent owners. This displaces spot-market exposure that dominated post-2015 trade patterns. Japanese and Korean industrial buyers lead this structural preference for supply security over price flexibility.
Very Large Gas Carrier Market Segmentation
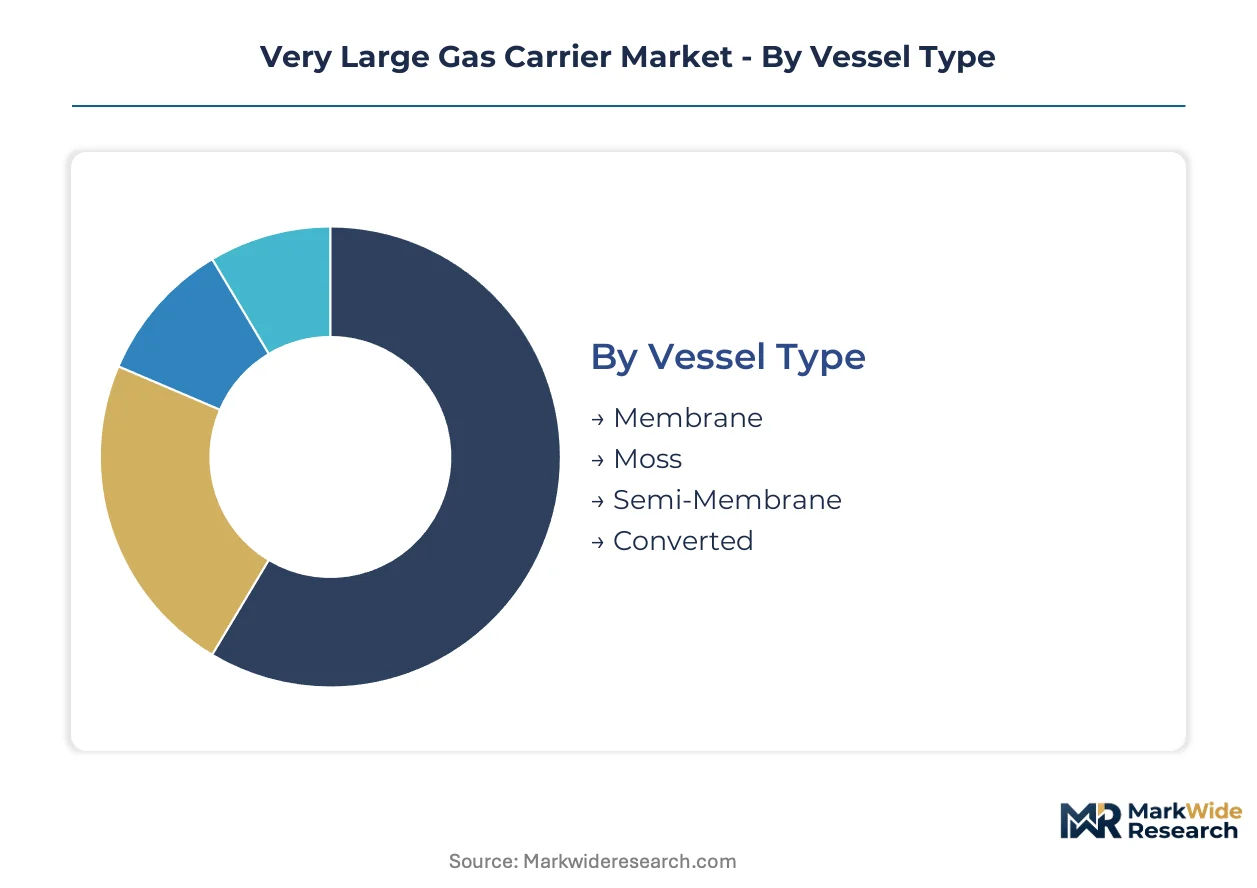
VLGC fleet economics hinge on containment technology and fuel system pairing. Each segment choice locks in twenty-year asset competitiveness against evolving carbon regulations and cargo specifications.
Vessel Type:
Containment architecture determines volumetric efficiency, boil-off rates, and yard construction economics.
- Membrane:GTT Mark III and NO96 systems employ thin stainless steel corrugated membranes with perlite insulation. QatarEnergy and Japanese trading houses concentrate newbuild orders here for North Field export volumes, prioritizing cargo density over structural redundancy.
- Moss:Independent aluminum or 9% nickel steel spheres withstand higher internal pressures. Niche demand persists from operators handling high-boil-off ethylene cargoes on shorter-haul routes where thermal efficiency matters less than tank integrity.
- Semi-Membrane:Hybrid designs blend membrane efficiency with partial structural independence. Korean yards offer this configuration for mid-size orders where owners seek cost flexibility.
- Converted:Tanker-to-VLGC modifications extend asset lifecycles. Chinese repair yards dominate this segment for owners deferring newbuild capital commitments.
Mature deployment sits with Moss. Newer deployment is concentrated in Membrane.
Fuel Type:
Propulsion selection now anticipates EU ETS carbon cost exposure and ammonia fuel readiness.
- Liquefied Natural Gas:Dual-fuel ME-GI and X-DF engines reduce tank-to-wake CO2 by approximately twenty percent versus conventional fuel oil. BW Group and other major owners specify this for decade-long charter coverage.
- Liquefied Petroleum Gas:LPG-burning propulsion leverages cargo boil-off without reliquefaction. This remains the baseline specification for spot-market exposed tonnage.
- Hydrogen:Prototype fuel cell and combustion concepts are advancing through METI-funded Japanese consortia. Commercial deployment awaits storage density breakthroughs.
- Biofuel:Drop-in renewable diesel and bio-LNG offer compliance pathway without engine modification. Singapore and Rotterdam bunkering hubs are building biofuel supply chains.
LPG propulsion anchors existing fleet operations. LNG dual-fuel represents the fastest-growing trajectory in current orderbooks.
Operation Mode:
Automation levels reflect labor cost pressures and safety regulatory evolution.
- Fully Automated:Integrated cargo control and engine management systems reduce crew complements. Norwegian-flagged vessels lead adoption under NMA remote monitoring frameworks.
- Manually Operated:Conventional watch-standing persists where flag state requirements and union agreements resist reduction. Older tonnage retains this profile.
- Semi-Automated:Selective automation of cargo handling while retaining manual navigation oversight. This configuration dominates newbuild specifications as a risk-mitigation compromise.
- Remote Controlled:Shore-based operation from control centers remains experimental. DNV classification rules for remote-controlled vessels are advancing through pilot programs.
Manual operation dominates legacy fleet. Semi-automated systems are expanding most quickly in Korean and Chinese yard output.
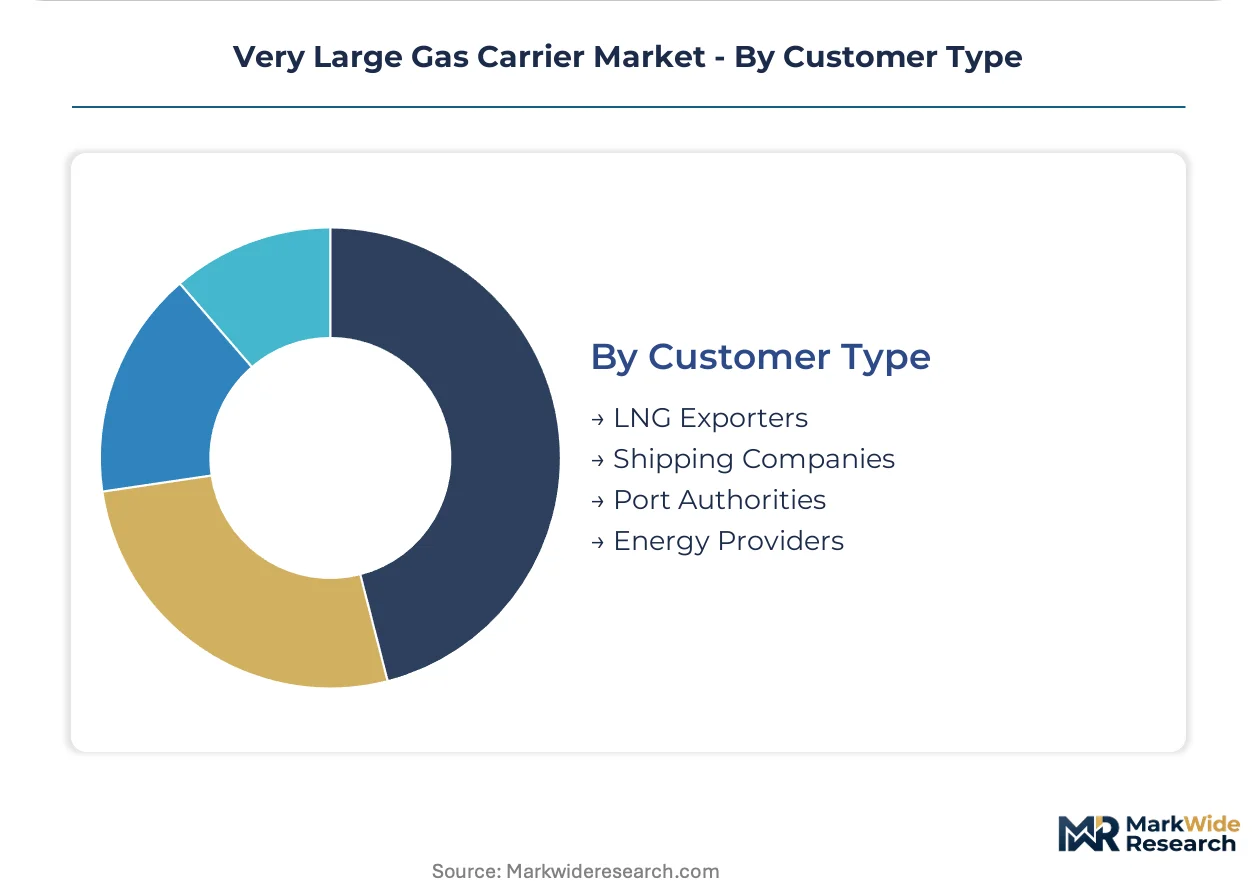
Customer Type:
End-user procurement strategies diverge between integrated energy majors and independent vessel operators.
- LNG Exporters:QatarEnergy and similar entities charter dedicated fleets for liquefaction terminal offtake. They demand fuel-flexible specifications aligned with carbon-neutral cargo marketing.
- Shipping Companies:Independent owners like Dynagas and Avance Gas balance spot exposure against term charter coverage. Their fleet renewal decisions track forward freight agreement curves.
- Port Authorities:Municipal and state port operators acquire specialized vessels for bunkering and emergency response. Singapore MPA and Rotterdam Port Authority lead this niche.
- Energy Providers:Utility and trading houses charter VLGCs as logistics arms for power generation feedstock. Japanese electric utilities concentrate demand here.
Shipping companies control mature fleet capacity. LNG exporters are driving newbuild specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's North Field expansion anchors liquefaction export volumes requiring dedicated VLGC tonnage. South Korean yards concentrate newbuild construction capacity. Chinese import terminals absorb expanding petrochemical feedstock flows.
Qatar
North Field East and West liquefaction projects concentrate export volumes requiring long-haul tonnage. QatarEnergy charters dedicated fleets under fuel-flexible specifications aligned with carbon-neutral cargo marketing. Ras Laffan Industrial City hosts the world's largest LNG export complex with dedicated VLGC loading infrastructure.
South Korea
Hyundai Heavy, Samsung Heavy, and Daewoo control over seventy percent of global VLGC construction capacity. The Green New Deal shipyard subsidies mandate carbon-intensity reductions in newbuild specifications. Geoje and Ulsan industrial clusters concentrate cryogenic welding expertise and membrane containment system manufacturing.
China
Petrochemical feedstock buyers in East Asia expand fleet charters to secure supply chain reliability. MIIT dual carbon goals pressure domestic yards to adopt alternative-fuel readiness standards. Yangtze River Delta ports including Shanghai and Ningbo absorb expanding LPG and ammonia import volumes.
Japan
METI-funded partnerships between engine builders and shipowners position first-movers for hydrogen economy logistics. The national shipping regulator advances ammonia-fuel certification frameworks through classification society collaboration. Kansai and Chubu industrial corridors concentrate petrochemical demand from integrated refining complexes.
Singapore
The Maritime and Port Authority builds bio-LNG bunkering infrastructure supporting dual-fuel fleet operations. Singapore-flagged vessels lead adoption of integrated cargo control automation under remote monitoring frameworks. The port's position astride East-West shipping lanes concentrates VLGC transshipment and crew change logistics.
Very Large Gas Carrier Market Competitive Landscape
Long-term charter contracting dominates the current landscape as integrated energy majors pivot from spot-market exposure. The market structure concentrates around independent vessel owners securing decade-long offtake agreements against QatarEnergy terminal expansions. Two strategic archetypes define competitive positioning: scale-driven dual-fuel newbuilders and specialized ice-class operators. M&A consolidation and ammonia-ready technology licensing represent the dominant competitive moves reshaping fleet ownership patterns.
Within the scale-driven tier, BW Group and Mitsui O.S.K. Lines exemplify owners leveraging dual-fuel newbuild programs to secure preferential charter access. Dynagas occupies a specialized position representing ice-class capability for Baltic and Arctic route deployments. These three entities anchor the competitive hierarchy through differentiated technology bets on fuel flexibility versus route specialization.
| Leading Market Players |
|---|
| Maran Gas Maritime |
| MISC Berhad |
| BW Group |
| Dynagas |
| Seapeak |
| Mitsui O.S.K. Lines |
| GasLog |
| Navios Maritime Partners |
| NYK Line |
| Others |
Value Network & Pricing Analysis
Qualified 9% nickel steel welders concentrated in South Korea's Geoje and Ulsan industrial clusters command wage premiums that widen spreads between premium membrane newbuilds and economy-tier converted tonnage. Labor-cost differentials in cryogenic welding certification directly amplify pricing-tier stratification across vessel specifications.
Pricing Analysis
Warranty and service-bundling arrangements separate premium membrane newbuilds with decade-long classification society backing from unbundled economy conversions lacking yard guarantees. Three-tier pricing structure across premium, standard, and economy levels tracks containment system complexity and fuel-flexibility specifications. Cost compression in the economy tier intensifies because Chinese repair yards compete aggressively on conversion timelines. Spot-market exposed charterers exhibit highest price sensitivity, while QatarEnergy-linked term charterers accept premium positioning for supply security.
Supply Chain Analysis
Single-source vulnerability sits with South Korean yards controlling over seventy percent of membrane containment system manufacturing capacity. Hyundai Heavy, Samsung Heavy, and Daewoo in South Korea, plus emerging Chinese builders in Shanghai and Dalian, anchor global construction. Raw material inputs draw from cryogenic-grade 304L and 316L stainless steel, perlite insulation, and GTT-licensed membrane technology. Tariff exposure on nickel alloy imports threatens margin stability. Distribution runs through direct yard-to-owner contracting with minimal intermediary structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EU ETS carbon cost exposure forces subscale owners toward demolition or sale. Regulatory compliance thresholds favor capital-rich operators capable of dual-fuel newbuild programs.
For Market Incumbents: Hedge fleet competitiveness by securing ammonia-ready engine slots at Korean yards before certification bottlenecks tighten. Backward integration into cryogenic welding training programs mitigates workforce scarcity threatening delivery timelines. Prioritize decade-long charter coverage with QatarEnergy to lock in utilization against spot-market volatility.
For New Entrants and Emerging Players: The price-point gap between premium ammonia-ready tonnage and economy LPG-fuelled vessels offers entry latitude. Target ice-class specifications for Baltic and Arctic routes where Dynagas lacks direct competition. Pursue retrofit-ready contracting as a go-to-market angle, preserving fuel pivot optionality without full newbuild capital exposure.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale independent owners holding term charter backlog given Qatar's North Field expansion catalyst. Five-to-ten year viability hinges on fuel-flexibility positioning rather than spot-market exposure. Monitor DNV and Lloyd's Register ammonia-fuel certification timelines as the inflection signal distinguishing stranded assets from future-proofed tonnage.
| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia-Ready Newbuild Contracting | First-mover owners gain preferential access to hydrogen carrier trades under METI-funded partnerships. |
| Backward Integration into Welding Certification | Captive training programs at Korean yards reduce delivery risk from scarce 9% nickel steel welders. |
| Ice-Class Hull Specification Investment | Strengthened designs capture year-round Northern Sea Route volumes underserved by standard fleet. |
| Long-Term Charter Consolidation | Decade-long offtake agreements with QatarEnergy displace spot-market exposure for supply security. |
| Membrane Containment System Licensing | GTT Mark III and NO96 technology partnerships lock in volumetric efficiency advantages over Moss-type rivals. |
Research Methodology
Document review covered Lloyd's Register and DNV classification rule filings, IMO MARPOL Annex VI regulatory texts, and Korean Green New Deal subsidy documentation, complemented by interviews with shipyard procurement directors, independent vessel owner fleet managers, QatarEnergy chartering executives, and GTT membrane technology specialists. Secondary validation drew from customs trade data, SEC filings of listed shipping companies, and Lloyd's List intelligence. Bottom-up vessel-by-vessel fleet analysis and top-down trade flow modeling enabled triangulation across data sources.
Installed base projections and newbuild orderbook valuations were generated across the analysis window by segmenting on containment architecture, fuel system pairing, and automation tier. CAGRs were derived from regression against liquefaction terminal expansion timelines and carbon pricing trajectory assumptions. Industry-specific forecast inputs incorporated boil-off rate differentials between membrane and Moss systems, plus EU ETS carbon cost pass-through elasticity to charter rates.
Inputs from Korean yard production schedules and QatarEnergy contracting disclosures were available through the study window; gaps in Chinese repair yard conversion cost data introduce uncertainty bands around economy-tier pricing estimates. Forecasts reflect assumptions on ammonia-fuel certification timing and nickel alloy price stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Global Spar Beacon Buoys Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Reefer Container Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Hong Kong Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Ship Stabilizers Market
Maritime Equipment
Asia-Pacific Maritime Satellite Communication Market
Maritime Equipment
China Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
Ship-To-Shore (STS) Container Cranes Market
Maritime Equipment
Global Digital Shipyard Market