
 Military Marine Engine Market | 2026-2036
Military Marine Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Military Marine Engine Market Foresight
Defense procurement channels for marine propulsion systems is fragmenting as national governments diversify supplier bases beyond traditional single-source contracts. Rolls-Royce Holdings plc leverages its integrated power and propulsion portfolio to anchor long-term naval service agreements. MAN Energy Solutions SE sustains dominance in large-bore diesel systems for frigate and destroyer programs. General Electric Company competes through advanced gas turbine offerings optimized for high-speed combatant vessels.
A military marine engine is a purpose-built propulsion system engineered to deliver sustained power output in saltwater combat environments, typically constructed from nickel-aluminum-bronze alloys and corrosion-resistant steels to withstand cavitation and shock loading. These engines integrate redundant cooling, filtration, and electronic control subsystems to maintain operational continuity under battle damage or extreme thermal stress. Diesel configurations retain the largest installed base across patrol and auxiliary fleets due to fuel availability and mechanical simplicity, while hybrid architectures represent the fastest-expanding segment as navies seek reduced acoustic signatures and improved fuel efficiency for littoral operations. The above 2000 HP power band captures concentrated investment from combat ship programs where integrated electric propulsion and high-speed gas turbine combinations command premium engineering margins.
The International Maritime Organization, the U.S. Environmental Protection Agency, and the EU Green Deal framework collectively tighten emissions benchmarks and fuel-quality mandates for naval operations in territorial waters and exclusive economic zones. Compliance with these overlapping standards now shapes engine architecture decisions, certification timelines, and retrofit obligations for legacy fleet operators. Stakeholders must monitor evolving defense procurement localization requirements and emissions enforcement thresholds to align R&D roadmaps with sovereign contracting preferences.
Market Dynamics
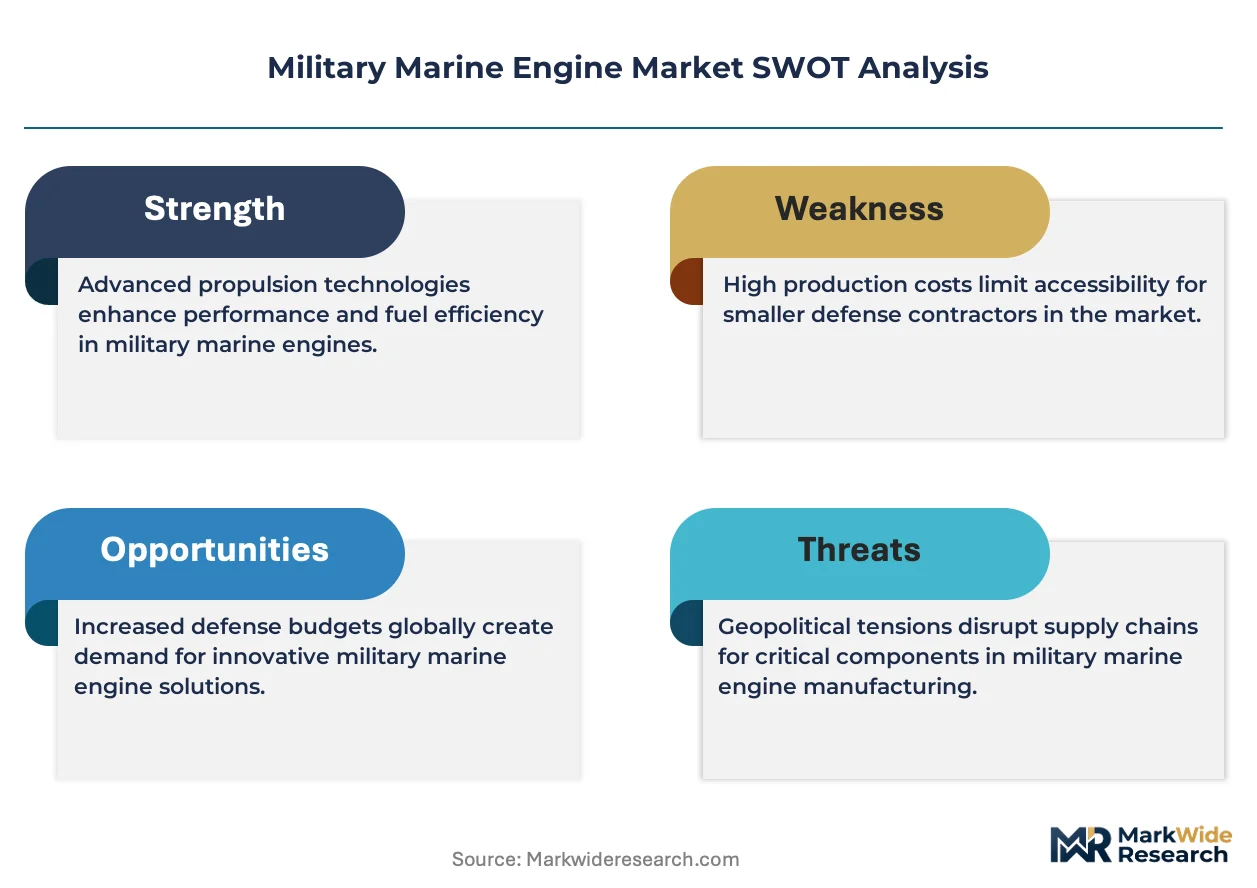
Naval procurement is pivoting toward hybrid-electric architectures as NATO fleets modernize for littoral dominance, compressing traditional diesel-gas turbine supply chains while elevating systems integrators over component vendors.
Growth Catalysts
- IMO Emissions Mandates:The International Maritime Organization's tightening fuel-quality standards for territorial waters are accelerating defense agency investment in cleaner-burning propulsion architectures and exhaust after-treatment systems.
- Indigenous Manufacturing Policies:Sovereign production requirements in the United States, the United Kingdom, and Japan are redirecting procurement toward domestic engine foundries and captive supply chains.
- Integrated Electric Propulsion:High-power-density motor and generator sets are displacing mechanical drivelines in combatant vessels, enabling distributed power architectures that improve survivability and acoustic stealth.
Market Restraints
- Nickel-Aluminum-Bronze Supply Concentration:Foundry capacity for corrosion-resistant propeller alloys concentrates in a handful of specialized suppliers, exposing programs to raw material volatility and extended lead times.
- Dual-Certification Burden:Engine architectures must satisfy both military shock-resistance standards and civilian emissions protocols, multiplying test cycles and compliance costs without performance gain.
- Long Asset Replacement Cycles:Warship hull lifespans exceeding thirty years lock legacy mechanical systems in service, delaying fleet-wide adoption of hybrid architectures and fragmenting maintenance logistics.
Strategic Opportunities
- Unmanned Surface Vessel Proliferation:Autonomous patrol and mine-countermeasure craft require compact, modular powerpacks that favor new entrants over incumbent marine engine suppliers.
- EU Green Deal Naval Provisions:The European Union's defense sustainability framework is creating preferential contracting terms for propulsion systems demonstrating measurable carbon-intensity reductions.
- Digital Twin Integration:Convergence of physics-based modeling with real-time sensor telemetry is enabling predictive maintenance contracts that extend OEM revenue streams beyond initial equipment sales.
Industry Challenges
- Naval Architect Talent Scarcity:The specialized intersection of thermodynamics, shock engineering, and corrosion metallurgy commands premium compensation and extended recruitment timelines.
- Legacy System Integration Complexity:Hybrid retrofits into existing hulls require mechanical and electrical interface reconciliation that strains shipyard capacity and extends drydock periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Marine Engine Market |
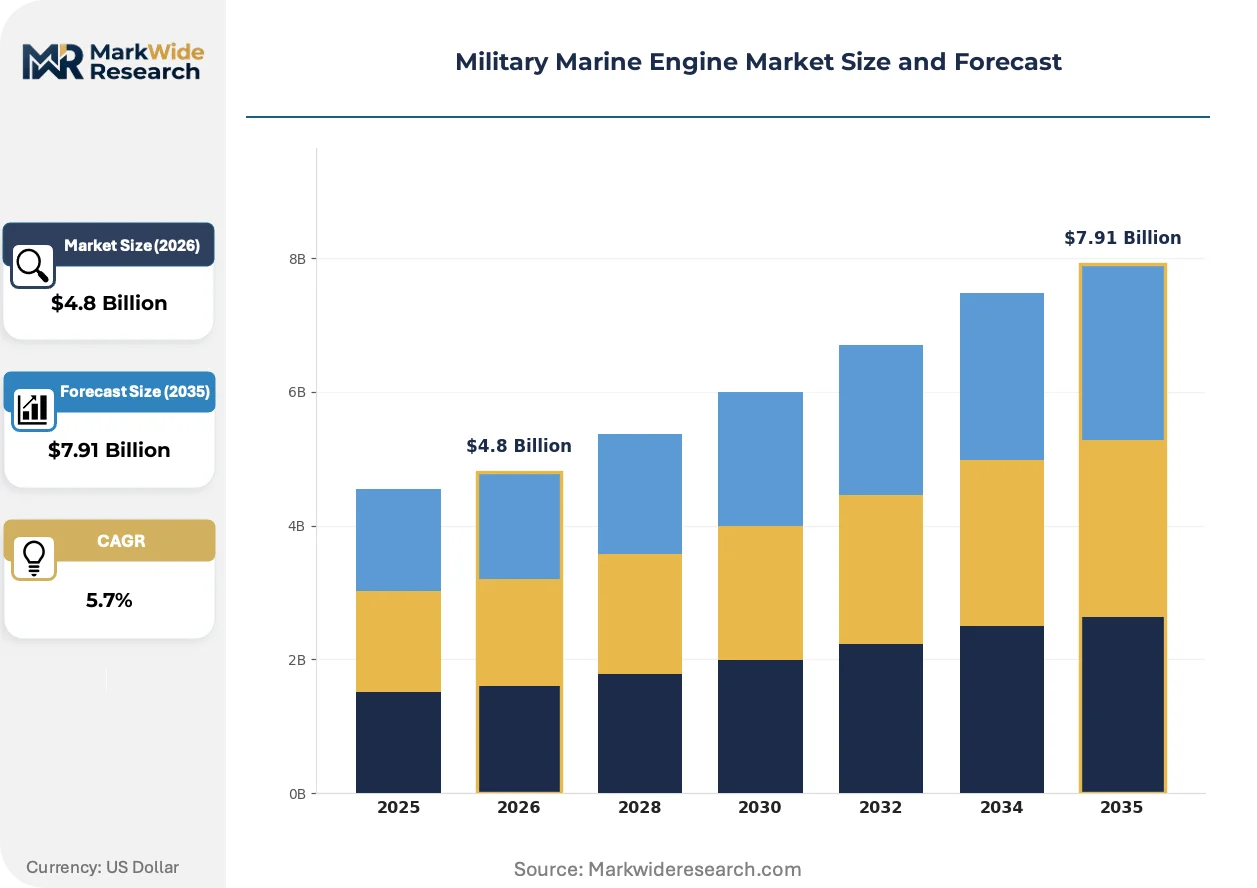
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Engine Type: Diesel, Gasoline, Hybrid, Electric Deployment Model: Surface Fleet, Submarine Fleet, Auxiliary Vessels, Support Crafts Power Output: Below 500 HP, 500-1000 HP, 1000-2000 HP, Above 2000 HP Application: Patrol Vessels, Combat Ships, Support Ships, Research Vessels |
| Companies Covered | MAN Energy Solutions SE, STX Engine Co., Ltd., Rolls-Royce Holdings plc, Mitsubishi Heavy Industries Ltd, STEYR MOTORS Betriebs GmbH, General Electric Company, Caterpillar Inc., Volvo Penta, Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Marine Engine Market Shifts & Advancements
Propulsion engineering is converging with information technology as navies prioritize energy management over raw power output, embedding software-defined control layers throughout mechanical systems.
Condition-based monitoring systems are digitizing maintenance workflows across surface combatant fleets. These sensor networks track vibration signatures, oil particulate levels, and thermal gradients in real time. The U.S. Navy's destroyer programs are deploying them at scale. This capability is digitizing traditional time-based overhaul schedules into predictive interventions that compress lifecycle costs.
The EU Green Deal framework is mandating lifecycle emissions accounting for vessels operating in European territorial waters. This policy requires engine manufacturers to document carbon intensity from foundry through scrapping. Frigate programs in France, Germany, and Italy face the steepest compliance curves. Suppliers are responding with modular architectures that permit field-upgradable power components.
Defense procurement offices are unbundling propulsion system acquisition from long-term service agreements. Traditional prime contractors now compete against independent service specialists for maintenance revenue. The United Kingdom's Type 26 frigate program exemplifies this split. Japan's defense procurement agency is piloting similar disaggregation for auxiliary vessel classes.
Military Marine Engine Market Segmentation
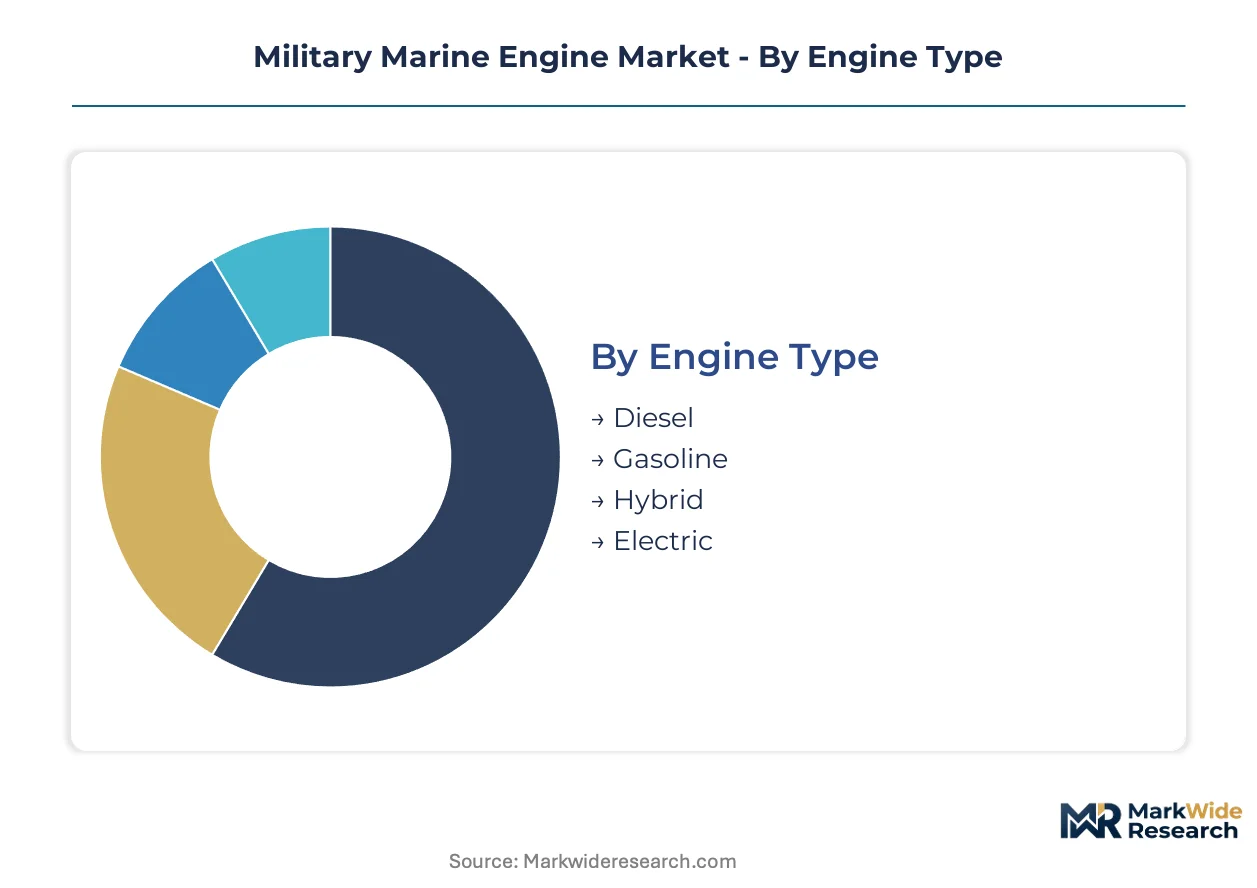
Segmentation in military marine propulsion reveals divergent engineering priorities across fleet categories. Replacement cycles vary dramatically between auxiliary diesel systems and advanced combatant hybrid architectures. Understanding these temporal patterns guides supplier resource allocation and R&D investment sequencing.
Engine Type:
Cycle times compress fastest in electric and hybrid segments as naval electrification accelerates, while diesel platforms turn over slowest due to embedded fleet infrastructure and mechanical simplicity.
- Diesel:Compression-ignition architectures built from nodular cast iron blocks and hardened steel crankshafts deliver thermal efficiency above 45% at sustained load. Patrol and auxiliary fleets in the United States, the United Kingdom, and Japan retain diesel dominance due to fuel logistics compatibility and depot maintenance familiarity. Legacy system integration burdens and thirty-year hull lifespans constrain upgrade velocity.
- Hybrid:Combined diesel-electric and gas turbine-electric configurations integrate lithium-ion or solid-state battery buffers with synchronous motor drives. NATO littoral modernization programs and Japanese indigenous manufacturing policies are channeling procurement toward these architectures for acoustic signature reduction. The segment climbs fastest as emissions mandates from the IMO and EPA tighten operational constraints in territorial waters.
- Gasoline:Spark-ignition powerpacks serve specialized applications requiring rapid throttle response and minimal cold-start latency. Small craft and rapid-interdiction platforms employ these systems where weight minimization outweighs fuel efficiency.
- Electric:Battery-dominant propulsion eliminates combustion machinery entirely, enabling distributed motor placement and zero-emission port operations. Experimental patrol craft and autonomous surface vessels are piloting these configurations.
Diesel dominates installed base. Hybrid is where expansion concentrates.
Deployment Model:
Cost tiers stratify sharply between submarine propulsion requiring nuclear or air-independent credentials versus surface auxiliaries using commercial-derivative engines.
- Surface Fleet:Destroyers, frigates, and corvettes deploy combined gas turbine and diesel (CODAG) or integrated electric propulsion. The U.S. Navy's destroyer programs and the United Kingdom's Type 26 frigate program anchor demand for high-power-density systems.
- Submarine Fleet:Nuclear pressurized-water reactors and air-independent propulsion (AIP) fuel cells demand specialized containment engineering and shock-hardened mounting. France, the United Kingdom, and Japan sustain indigenous development for strategic autonomy.
- Auxiliary Vessels:Replenishment oilers, hospital ships, and transport craft utilize commercial-marine engine derivatives with military-grade control overlays. Lower certification burdens and shorter procurement cycles accelerate fleet refresh.
- Support Crafts:Tugs, barges, and harbor vessels operate at lower power bands with standardized mechanical drivelines. Maintenance disaggregation and independent service contracts are penetrating this segment fastest.
Surface Fleet captures premium engineering margins. Auxiliary Vessels offer volume accessibility for commercial-derivative suppliers.
Power Output:
Volume concentrates in mid-range bands where patrol and auxiliary programs overlap, while margins expand at extremes where combatant requirements demand bespoke engineering.
- Above 2000 HP:High-speed gas turbines and integrated electric motor-generator sets propel combat ships requiring sprint speeds above 30 knots. The U.S. Navy and Royal Navy frigate programs specify these systems for carrier escort and independent strike roles. Shock resistance certification and cavitation-hardened alloys multiply unit costs.
- Below 500 HP:Compact diesel and gasoline powerpacks serve rigid-hull inflatable boats, unmanned surface vessels, and harbor patrol craft. Autonomous mine-countermeasure programs in the United Kingdom and Japan are expanding this segment.
- 500-1000 HP:Coastal patrol boats and fast-attack craft employ medium-speed diesels with mechanical or hybrid-electric transmission options.
- 1000-2000 HP:Offshore patrol vessels and mine warfare ships balance endurance and speed in this transitional band, often specifying modular architectures for field upgrade.
Above 2000 HP commands development priority. Below 500 HP is expanding most quickly through unmanned platform proliferation.
Application:
Customer maturity varies across mission profiles, with combat ship procurement following decades-long development cycles while research vessels adopt experimental technologies on compressed timelines.
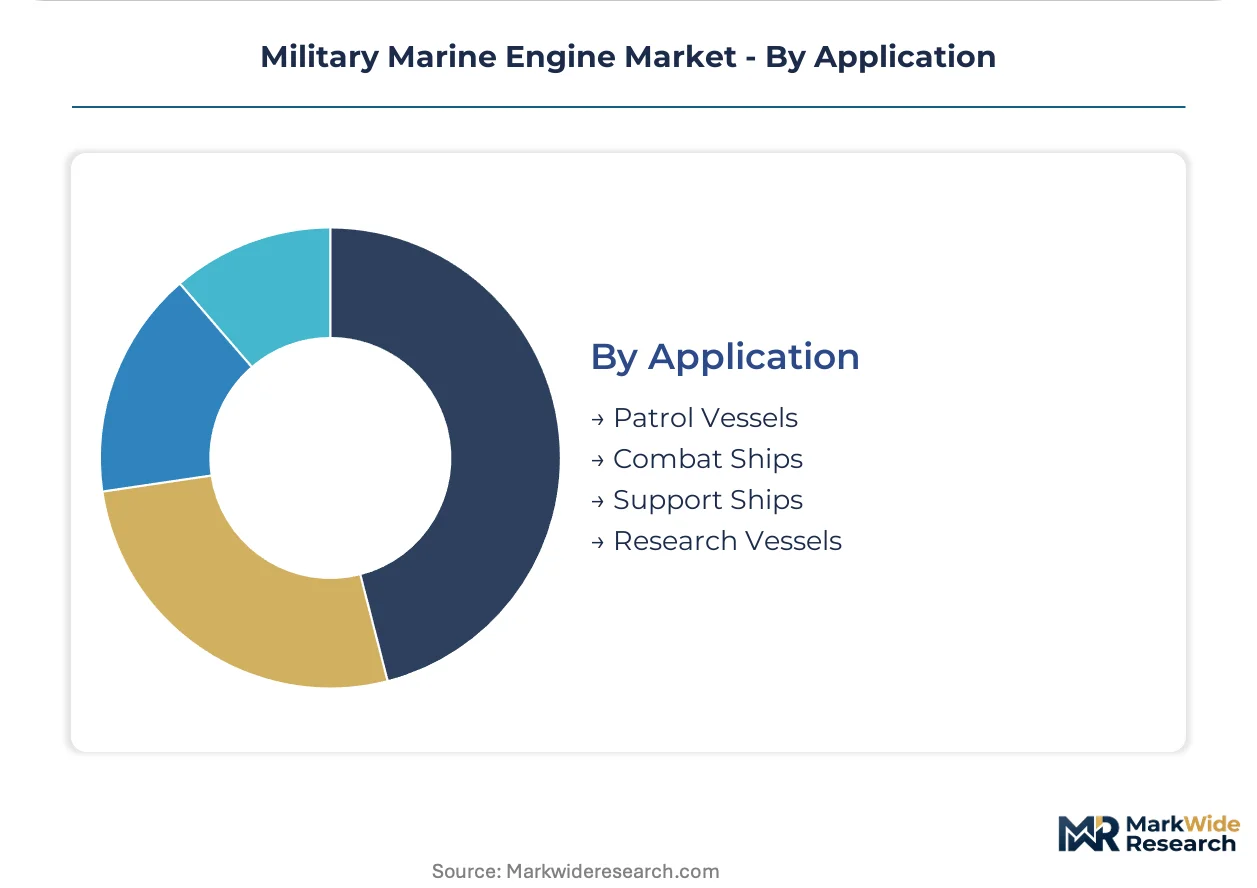
- Combat Ships:Frigates, destroyers, and littoral combatants integrate redundant propulsion trains with battle-damage isolation capabilities. The U.S. Navy, Royal Navy, and Japan Maritime Self-Defense Force programs specify indigenous content requirements that reshape supplier qualification.
- Research Vessels:Oceanographic and hydrographic platforms prioritize acoustic quieting and precision station-keeping over speed. Hybrid-electric architectures and azimuth thruster integration are standard.
- Patrol Vessels:Exclusive economic zone enforcement and coastal security missions drive demand for fuel-efficient, long-endurance systems. Cost constraints favor commercial-marine derivatives with military communications overlays.
- Support Ships:Fleet replenishment and logistics vessels emphasize reliability and cargo-handling power take-off rather than propulsion performance. Integrated electric architectures enable cargo pump and crane electrification.
Combat Ships dominate program value. Research Vessels serve as technology insertion pathways for emerging propulsion concepts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Norfolk Naval Shipyard in Virginia anchors American naval propulsion infrastructure, while the Clyde shipbuilding corridor in Scotland and the Kure Naval Arsenal legacy in Japan concentrate specialized foundry capacity for combatant-grade marine engines.
United States
The U.S. Navy's destroyer modernization and Columbia-class submarine programs drive sustained demand for high-power-density propulsion systems. EPA emissions mandates for territorial waters operations tighten fuel-quality requirements for coastal patrol fleets. Consolidated manufacturing clusters in Connecticut and Virginia integrate turbine assembly with naval reactor servicing.
United Kingdom
Royal Navy Type 26 frigate procurement and Dreadnought submarine construction anchor indigenous propulsion requirements. The EU Green Deal naval provisions impose lifecycle emissions accounting on vessels operating in European waters. Glasgow and Barrow-in-Furness retain concentrated marine engineering talent pools for shock-hardened system integration.
Japan
Japan Maritime Self-Defense Force indigenous manufacturing policies redirect procurement toward domestic engine foundries for strategic autonomy. METI industrial security guidelines mandate captive supply chains for critical propulsion components. Kobe and Nagasaki harbor specialized nickel-aluminum-bronze foundry capacity for cavitation-resistant propeller alloys.
Germany
Bundesmarine frigate programs and submarine export contracts sustain demand for air-independent propulsion systems. REACH chemical regulations and EU emissions frameworks shape exhaust after-treatment system specifications. Kiel and Hamburg concentrate diesel-electric engineering expertise for littoral combatant applications.
France
Naval Group submarine and surface combatant programs drive investment in nuclear and conventional propulsion architectures. ANSM defense procurement localization requirements prioritize domestic foundry capacity for strategic hull systems. Cherbourg and Lorient maintain integrated reactor and battery propulsion assembly lines.
Military Marine Engine Market Competitive Landscape
On the supply side, the industry is consolidating around integrated power and propulsion portfolios that bundle hardware with long-term service agreements. Tier-one suppliers anchor combatant programs through sovereign contracting relationships, while commercial-marine specialists capture auxiliary vessel volume. Three strategic archetypes dominate: full-system integrators with captive foundry capacity, component specialists licensing technology across multiple hull programs, and commercial-marine adaptors applying civilian engine architectures to military specifications. Competitive moves center on disaggregating propulsion acquisition from maintenance contracts and establishing predictive maintenance revenue streams through digital twin integration.
Within the full-system integrator tier, Rolls-Royce Holdings plc and General Electric Company exemplify the premium-engineering archetype that anchors high-power combatant programs. MAN Energy Solutions SE occupies a distinct position among European fabricators specializing in large-bore diesel architectures. STX Engine Co., Ltd. represents Korean industrial capacity serving export-oriented naval construction.
| Leading Market Players |
|---|
| MAN Energy Solutions SE |
| STX Engine Co., Ltd. |
| Rolls-Royce Holdings plc |
| Mitsubishi Heavy Industries Ltd |
| STEYR MOTORS Betriebs GmbH |
| General Electric Company |
| Caterpillar Inc. |
| Volvo Penta |
| Cummins Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in nickel-aluminum-bronze foundries across Japan and the United Kingdom is compressing supplier bargaining power while elevating raw material pass-through clauses in long-term naval procurement contracts. This utilization squeeze tightens pricing discipline at the component tier and accelerates dual-sourcing mandates among NATO defense procurement offices.
Pricing Analysis
Volume-discount tiering structures in military marine propulsion separate combatant-grade integrated electric systems from commercial-derivative auxiliary engines. Price differentiation rests on shock-resistance certification grade and sovereign content requirements. Cost compression in the auxiliary vessel tier is intensifying because commercial-marine adaptors are underbidding legacy defense contractors. Patrol and support craft programs exhibit highest price sensitivity, while nuclear submarine propulsion commands premium engineering margins with minimal buyer elasticity.
Supply Chain Analysis
Upstream feedstock for corrosion-resistant propulsion alloys draws from specialized nickel mining operations in Indonesia and Russia, with refining concentration in China and Canada. Critical dependencies include nickel-aluminum-bronze ingots, high-grade nodular cast iron, and shock-hardened steel crankshafts. Single-source vulnerability in Japanese and Korean foundry capacity exposes programs to extended lead time volatility. Distribution runs through sovereign defense procurement channels with captive maintenance agreements rather than open commercial marine markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military marine propulsion sits in early-cycle expansion as NATO littoral modernization and unmanned surface vessel proliferation create dual adoption tailwinds for hybrid-electric architectures.
For Market Incumbents: Insulate core combatant programs through captive nickel-aluminum-bronze foundry investments in the United Kingdom or Japan, countering raw material supply concentration risk. Deepen predictive maintenance platform penetration to lock in service revenue streams as defense procurement offices disaggregate hardware acquisition from long-term support contracts. For New Entrants and Emerging Players: Build out modular powerpack offerings for unmanned surface vessels and autonomous mine-countermeasure craft, the most penetrable segment where incumbent marine engine suppliers retain weakest positioning. Pursue direct contracting relationships with naval research laboratories rather than competing for prime integrator slots. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-system integrators with embedded digital twin platforms and sovereign maintenance agreements. Long-term viability favors acquisition targets combining captive foundry capacity with integrated electric propulsion engineering depth. Watch for inflection in EU Green Deal naval procurement provisions as a signal for carbon-intensity reduction premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Capacity Expansion | Backward integration into nickel-aluminum-bronze casting secures supply continuity for shock-hardened propulsion components. |
| Digital Twin Platform Deployment | Predictive maintenance contracts with the U.S. Navy and Royal Navy extend OEM revenue beyond initial equipment sales. |
| Hybrid-Electric Architecture Certification | IMO emissions compliance for territorial waters operations opens preferential contracting terms in EU defense procurement. |
| Unmanned Vessel Powerpack Development | Compact modular systems for autonomous mine-countermeasure programs bypass incumbent supplier lock-in. |
| Sovereign Supply Chain Localization | METI and ANSM localization mandates redirect procurement toward domestic engine foundries for strategic autonomy. |
Research Methodology
The analysis maps diesel, hybrid, gas turbine, and electric propulsion architectures, each validated through naval program managers, shipyard procurement directors, defense agency contracting officers, and marine engineering consultants. Primary fieldwork combined structured interviews with secondary validation against U.S. Navy budget submissions, UK Ministry of Defence equipment plans, Japan Ministry of Defense white papers, and EU defense procurement directives. Bottom-up segment sizing triangulated against top-down fleet modernization forecasts.
Assumptions held fixed include NATO member defense spending commitments, IMO emissions enforcement timelines, and indigenous manufacturing policy continuity across the United States, United Kingdom, and Japan. Variables stress-tested included nickel price volatility, foundry capacity expansion rates, and unmanned platform adoption curves. CAGRs derived from segment-level fleet replacement modeling across engine type, deployment model, power output, and application dimensions. Industry-specific inputs incorporated hull lifespan assumptions, drydock availability constraints, and shock-resistance certification timelines.
Stress conditions across raw material cost bands, procurement localization stringency, and hybrid architecture penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about sovereign content requirements and emissions enforcement trajectories. Cross-checking against national defense budget authorization trends and shipyard order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Hybrid Fishing Boats Market
Marine
Marine Spreader Lights Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Global Submarine Market
Marine
Marine Chronometers Market
Marine
Yacht Painting and Maintenance Market
Marine
Marine Chartplotter Market
Marine
Pneumatic Marine Fender Market
Marine
Azimuth Thrusters Market
Marine
Marine Big Data Market
Marine
Boat Console Market
Marine
Marine Trenchers Market
Marine
Global Foldable Inflatable Boats Market
Marine
Global Discount-Marine Trenchers Market
Marine
Marine AIS Monitoring System Market
Marine
Trim Tabs Market