
 Latin America Offshore Support Vessels Market | 2026-2036
Latin America Offshore Support Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Offshore Support Vessels Market Foresight
Buyer concentration among Latin American national oil companies is decoupling from traditional international charter patterns. Edison Chouest Offshore leverages its integrated Gulf of Mexico-Brazil logistics network to sustain long-term contracts with Petrobras. Tidewater Inc. anchors its regional position through Brazilian-flagged fleet capacity and port infrastructure partnerships. CBO dominates local content-compliant construction and crew boat operations in Campos and Santos basins.
Offshore support vessels are purpose-built marine craft typically ranging from 50 to 140 meters in length, designed to transport personnel, supplies, and equipment to offshore platforms while maintaining dynamic positioning capability in sea states up to Beaufort scale 6. Platform supply vessels lead the vessel type segment due to steady replenishment cycles at Brazil's pre-salt installations, while anchor handling tug supply units command premium day rates in deepwater deployment zones. Crew boats face margin compression from oversupply in Mexican nearshore waters, contrasting with maintenance support vessels where specialized subsea crane specifications protect pricing power.
Brazil's ANP local content requirements and Mexico's ASEA environmental compliance standards shape hull construction sourcing and emission control technology adoption across regional yards. IMO Tier III regulations and the EU-Mercosur Green Deal alignment discussions are forcing fleet renewal timelines for older diesel-mechanical propulsion systems. Stakeholders must weigh charter rate visibility against capital commitments for hybrid-electric retrofits as carbon intensity indicators enter contract renewal negotiations.
Market Dynamics
ANP local content mandates and IMO Tier III emission standards are forcing fleet operators to reconfigure vessel specifications and sourcing strategies across Brazilian deepwater basins.
Growth Catalysts
- Pre-salt field expansion:Petrobras and international consortiums are commissioning platform supply vessels for sustained replenishment cycles at ultra-deepwater installations in Santos and Campos basins.
- Hybrid-electric propulsion adoption:Battery-diesel hybrid systems are reducing carbon intensity indicators for charter renewal negotiations in Brazil's ANP-regulated waters.
- Guyana-Suriname basin development:ExxonMobil-led consortia are stimulating anchor handling tug supply demand for floating production storage and offloading support.
Market Restraints
- Steel plate cost volatility:Hull construction material price swings are compressing margins for Brazilian yard operators building local content-compliant vessels.
- Engine supply concentration:Caterpillar and Wärtsilä dominate medium-speed diesel propulsion systems, creating procurement bottlenecks for Tier III retrofit timelines.
- Dynamic positioning system technical limitation:DP-3 redundancy requirements for pre-salt operations exclude older vessel generations from premium charter tiers.
Strategic Opportunities
- Mexico Gulf deepwater expansion:Pemex and private operators are tendering platform supply contracts for Perdido Fold Belt developments requiring enhanced dynamic positioning capability.
- EU-Mercosur Green Deal alignment:Carbon border adjustment mechanisms are creating regulatory tailwinds for low-emission vessel retrofits in Brazilian-flagged fleets.
- Remote operations center convergence:Satellite telemetry and autonomous navigation systems are enabling shore-based vessel monitoring for reduced crewing requirements.
Industry Challenges
- Marine engineer skill scarcity:Specialized training for hybrid-electric propulsion maintenance is outpacing Brazilian maritime academy output.
- ANP certification timeline compression:Local content compliance documentation is extending vessel delivery schedules by 8-14 months.
- Legacy diesel-mechanical integration complexity:Retrofitting battery systems into existing platform supply vessels requires hull structural modifications and stability recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Offshore Support Vessels Market |
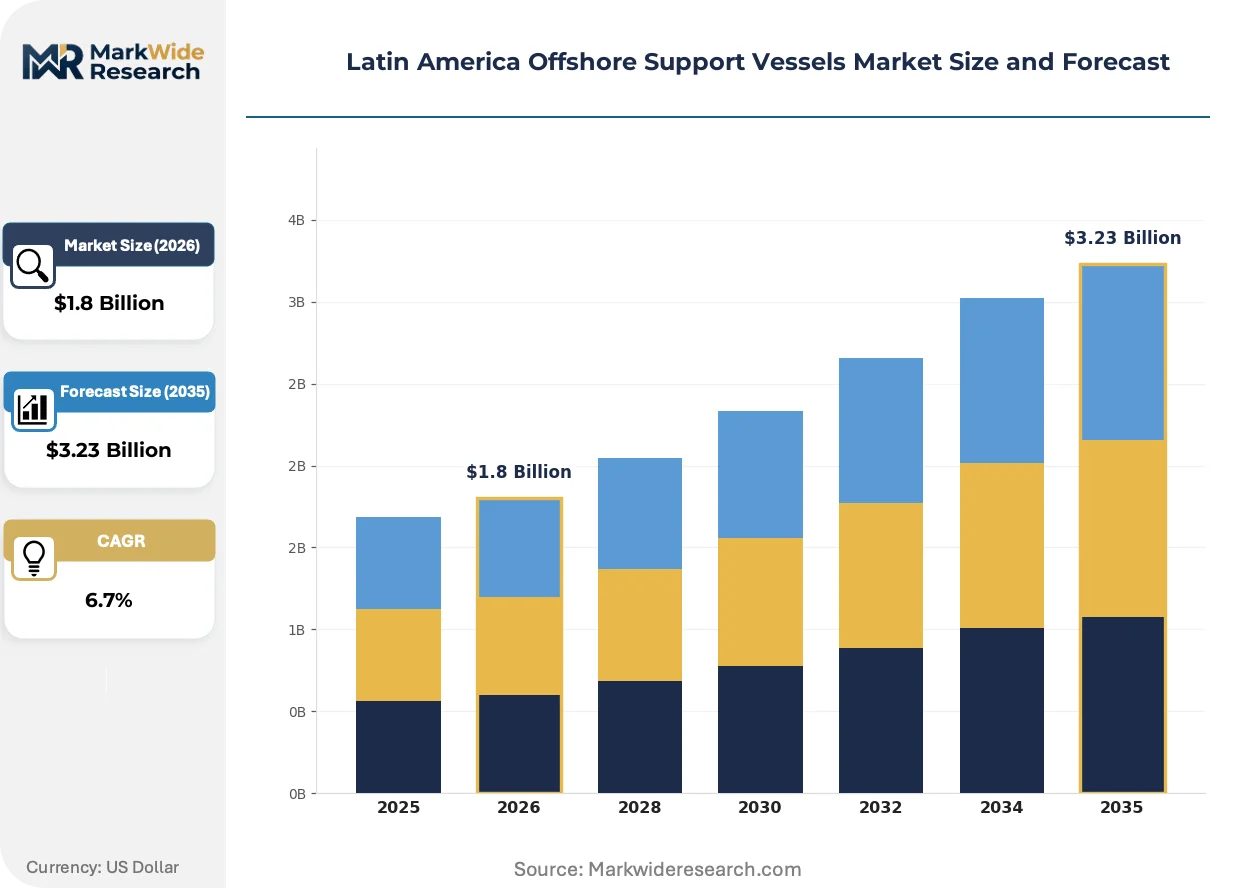
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Platform Supply Vessels, Anchor Handling Tug Supply, Crew Boats, Maintenance Support Vessels End User: Oil & Gas Companies, Renewable Energy Firms, Government Agencies, Environmental Services Deployment Model: Onshore, Offshore, Nearshore, Deepwater Service Type: Logistics Support, Waste Management, Surveying, Emergency Response |
| Companies Covered | SEACOR Marine Holdings Inc., Siem Offshore Inc., Edison Chouest Offshore, Great Eastern Shipping Company Ltd, AP Moeller Maersk A/S Class B, Tidewater Inc., Bourbon Corp, Companhia Brasileira de Offshore (CBO), GulfMark Offshore, Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Offshore Support Vessels Market Shifts & Advancements
Digital twin technology and shore-based remote monitoring are compressing operational response times while regulatory emission thresholds accelerate propulsion system replacement cycles.
Autonomous collision avoidance systems are automating dynamic positioning station-keeping functions in high-traffic offshore installation corridors. Petrobras and international charterers are mandating these systems for newbuild platform supply vessels entering Santos basin service. This capability is automating bridge crew requirements and compressing insurance premium differentials for advanced-technology vessels versus conventional tonnage.
ANP Resolution 847 local content thresholds are forcing hull construction sourcing shifts toward Brazilian shipyards with established steel-fabrication partnerships. The regulation requires minimum domestic value-added percentages for vessel charter eligibility in pre-salt block concessions. Anchor handling tug supply operators are responding by consolidating yard relationships at Estaleiro Atlântico Sul and Jurong Aracruz to secure compliant delivery slots.
Charter contracting is compressing from multi-year fixtures toward shorter-cycle agreements with performance-indexed rate adjustments. National oil companies in Brazil and Mexico are unbundling vessel provision from integrated logistics packages, directly negotiating with fleet operators rather than through international brokers. This pattern is most visible in Petrobras platform supply tenders, where day rate transparency and fuel consumption guarantees now dominate supplier selection criteria.
Latin America Offshore Support Vessels Market Segmentation
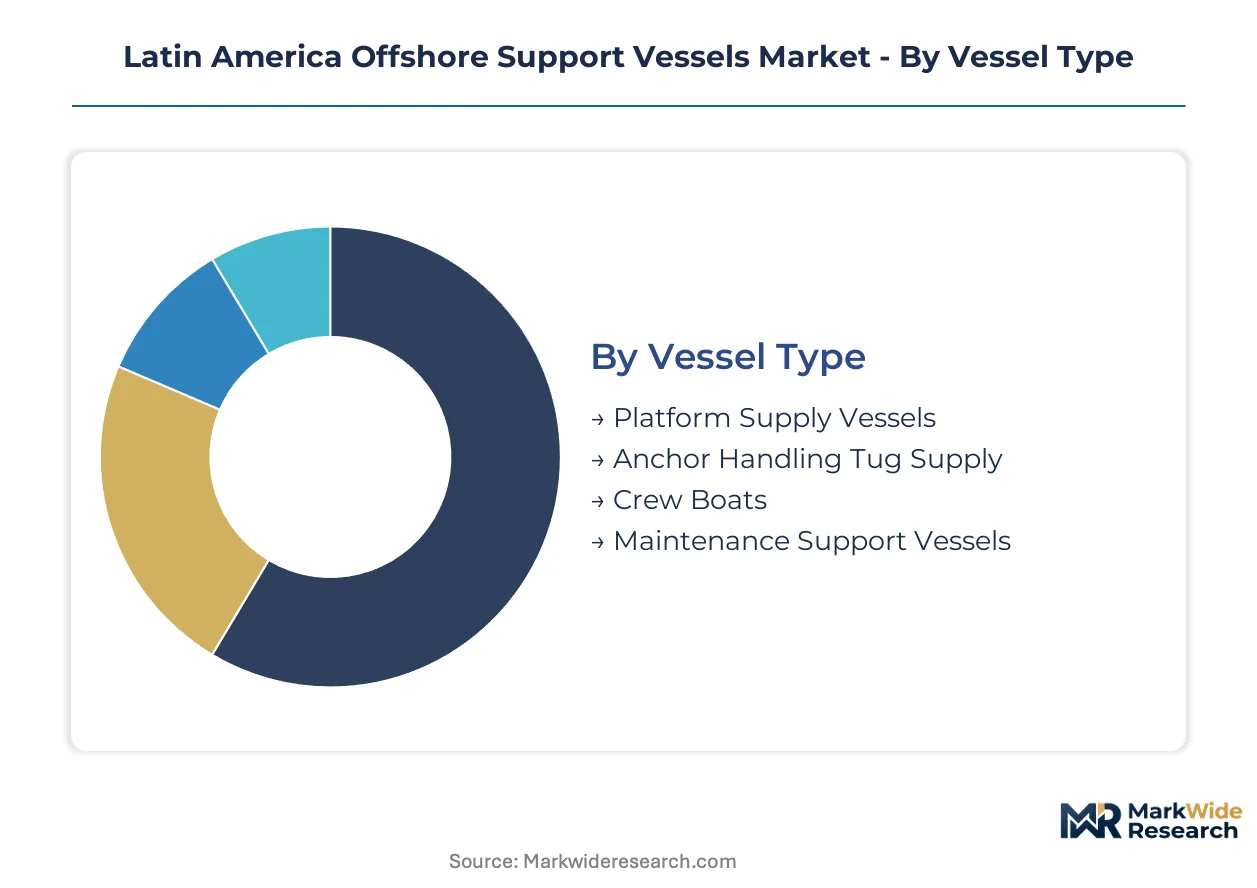
Vessel specification and deployment depth determine charter rate tiers and regulatory compliance requirements across Brazilian, Mexican, and Guyanese offshore basins. Understanding segment boundaries clarifies where hybrid-electric retrofits and ANP local content mandates apply most stringently.
Vessel Type:
Platform supply vessels operate as standalone replenishment systems, while anchor handling units embed within integrated rig-moving operations requiring DP-3 redundancy certification.
- Platform Supply Vessels:These 80-100 meter vessels transport drilling fluids, cement, and provisions to pre-salt installations. Demand concentrates in Brazil's Santos basin where Petrobras mandates fuel consumption guarantees and carbon intensity disclosures for charter renewals.
- Anchor Handling Tug Supply:Twin-engine vessels exceeding 15,000 brake horsepower manage rig positioning and mooring installation. Premium day rates apply in Guyana-Suriname deepwater zones where ExxonMobil-led consortia require bollard pull specifications above 200 metric tons.
- Crew Boats:Fast aluminum-hull craft under 40 meters transfer personnel to nearshore Mexican platforms. Pemex tenders favor vessels with motion-compensated gangway systems for safety compliance in Campeche Bay operations.
- Maintenance Support Vessels:Crane-equipped units perform subsea intervention and ROV deployment. Specialized heave-compensated crane specifications protect pricing power against generic platform supply competition in Brazilian Campos basin maintenance campaigns.
Platform supply vessels lead volumes today; anchor handling tug supply units are gaining share fastest.
End User:
Customer procurement authority determines contract structure, with national oil companies favoring direct negotiation over broker-mediated fixtures.
- Oil & Gas Companies:Petrobras, Pemex, and private operators in Brazil and Mexico unbundle vessel provision from integrated logistics packages. Direct tendering compresses rate transparency and imposes fuel efficiency penalties on underperforming tonnage.
- Renewable Energy Firms:Offshore wind developers in Brazilian northeastern waters require jack-up barge support and crew transfer vessels. ANP environmental licensing for floating wind pilots is stimulating demand for hybrid-electric crew boats with reduced acoustic signatures.
- Government Agencies:Brazil's navy and maritime authority charter patrol and research vessels. Local content requirements apply less stringently to sovereign missions than to pre-salt commercial concessions.
- Environmental Services:Oil spill response organizations contract standby vessels with dispersant spray systems. Mexico's ASEA mandates dedicated emergency response capacity for deepwater operators in Perdido Fold Belt concessions.
Oil and gas companies dominate contract value; renewable energy firms are expanding most quickly.
Deployment Model:
Water depth thresholds separate vessel generations, with older diesel-mechanical tonnage excluded from deepwater premium tiers.
- Onshore:Port-based vessel management and maintenance operations. Brazilian yards at Suape and Niterói concentrate hull construction and Tier III retrofit capacity for ANP-compliant fleets.
- Offshore:Platform-proximity operations within 50 nautical miles of installations. Crew boats and platform supply vessels rotate through Santos basin pre-salt fields on 14-day replenishment cycles.
- Nearshore:Shallow-water Mexican Gulf activities in depths under 200 meters. Oversupply of legacy crew boats compresses margins in Campeche Bay despite steady Pemex production maintenance demand.
- Deepwater:Ultra-deepwater basins exceeding 1,500 meters in Brazil and Guyana. DP-3 dynamic positioning redundancy requirements exclude pre-2010 vessel generations from ExxonMobil and Petrobras charter tiers.
Offshore deployment commands the largest fleet allocation; deepwater operations are climbing the fastest.
Service Type:
Service bundling patterns are unbundling as national oil companies disaggregate integrated logistics contracts.
- Logistics Support:Core vessel functions encompassing cargo transport, personnel transfer, and platform standby. Petrobras tenders now separate fuel provision from hull charter, exposing operators to bunker price volatility.
- Waste Management:Produced water, drilling cuttings, and hazardous material transport. ANP Resolution 847 mandates Brazilian-flagged vessels with certified tank cleaning systems for pre-salt block operators.
- Surveying:Seismic support and bathymetric mapping operations. Specialist vessels with acoustic positioning arrays serve Guyana-Suriname exploration campaigns.
- Emergency Response:Standby rescue and oil spill containment duties. Mexico's ASEA requires dedicated emergency response vessels with fire-fighting capacity above 10,000 liters per minute for deepwater production licenses.
Logistics support anchors revenue today; waste management services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands deepwater vessel demand through Petrobras-led pre-salt expansion, while Mexico's Pemex tenders concentrate nearshore crew boat requirements in the Gulf. Argentina, Chile, and Colombia occupy secondary positions with basin-specific deployment patterns.
Brazil
Petrobras pre-salt field development in the Santos and Campos basins drives anchor handling tug supply and platform supply vessel procurement. ANP Resolution 847 mandates local content thresholds for charter eligibility, forcing hull construction sourcing toward domestic yards. Estaleiro Atlântico Sul in Pernambuco and Jurong Aracruz in Espírito Santo anchor compliant vessel delivery capacity.
Mexico
Pemex production maintenance in Campeche Bay and emerging Perdido Fold Belt deepwater tenders stimulate platform supply and crew boat demand. ASEA environmental compliance standards govern emission control technology adoption for Gulf of Mexico operations. Ciudad del Carmen in Campeche concentrates vessel management infrastructure for nearshore logistics.
Argentina
Vaca Muerta shale development generates intermittent offshore support requirements for Atlantic coastal logistics. The country's national oil company YPF tenders vessel services through seasonal drilling campaigns rather than sustained fixtures. Mar del Plata anchors the limited offshore vessel support infrastructure for southern basin exploration.
Chile
Magallanes Basin gas development and offshore exploration licensing stimulate specialized supply vessel demand in southern waters. The Ministry of Energy's hydrocarbon exploration rounds impose environmental licensing requirements for vessel operators. Punta Arenas concentrates logistics coordination for Tierra del Fuego offshore campaigns.
Colombia
Caribbean offshore licensing rounds and existing Gulf of Mexico adjacent operations generate maintenance support vessel requirements. The National Hydrocarbons Agency environmental guidelines shape vessel specifications for deepwater exploration blocks. Barranquilla anchors port infrastructure for offshore supply base operations.
Latin America Offshore Support Vessels Market Competitive Landscape
Gulf of Mexico integrated operators anchor one tier; Brazilian-flagged specialists hold the regional compliance tier. Market structure concentrates around national oil company direct tendering patterns that bypass traditional international charter brokers. Three archetypes dominate: integrated logistics networks spanning multiple basins, local content-compliant domestic operators, and hybrid-electric technology specialists. Competitive moves center on yard partnership consolidation for ANP certification and hybrid propulsion retrofit capacity expansion.
Within the integrated logistics tier, Edison Chouest Offshore and Tidewater Inc. exemplify cross-basin operational scale. CBO occupies a position as the dominant local content-compliant constructor in Brazilian waters. SEACOR Marine Holdings Inc. and Siem Offshore Inc. represent specialized anchor handling and platform supply expertise. Bourbon Corp and GulfMark Offshore, Inc. sit within the maintenance support vessel segment with crane-equipped specifications.
| Leading Market Players |
|---|
| SEACOR Marine Holdings Inc. |
| Siem Offshore Inc. |
| Edison Chouest Offshore |
| Great Eastern Shipping Company Ltd |
| AP Moeller Maersk A/S Class B |
| Tidewater Inc. |
| Bourbon Corp |
| Companhia Brasileira de Offshore (CBO) |
| GulfMark Offshore, Inc. |
| Others |
Supply & Pricing Matrix
Steel plate procurement from Brazilian mills cascades through hull construction costs to charter rate floors in Santos basin operations, with ANP local content mandates locking sourcing to domestic fabricators and amplifying price volatility transmission.
Pricing Analysis
Capacity additions in Brazilian shipyards are reshaping price floors for platform supply vessels as Estaleiro Atlântico Sul and Jurong Aracruz expand delivery slots. Three-tier pricing structure across DP-3 certified premium tonnage, standard diesel-mechanical vessels, and legacy crew boats reflects dynamic positioning redundancy and fuel efficiency guarantees. Pricing pressure stems from oversupply of pre-2010 diesel-mechanical tonnage excluded from deepwater charter tiers. Pemex nearshore operations exhibit highest price sensitivity due to unbundled logistics tenders, while Petrobras pre-salt contracts prioritize carbon intensity performance over rate minimization.
Supply Chain Analysis
Marine engineer availability constraints in Pernambuco and Espírito Santo shipyard clusters are extending vessel delivery timelines and compressing yard utilization rates. Hull construction draws from Brazilian steel plate producers, Caterpillar and Wärtsilä engine supply chains, and Kongsberg dynamic positioning system integrators. Single-source vulnerability concentrates in Tier III engine procurement where dual suppliers dominate medium-speed diesel propulsion. Distribution runs through integrated logistics networks spanning Gulf of Mexico and Brazilian basin operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America offshore support vessels function as a geographic-arbitrage play where Mexican nearshore rate compression contrasts with Brazilian deepwater premium tiers, exploiting regulatory divergence between ANP local content mandates and ASEA environmental compliance standards.
For Market Incumbents: To counter hybrid-electric technology specialists capturing Petrobras charter renewals, incumbent operators should secure backward integration into Brazilian battery system retrofit partnerships and accelerate DP-3 certification acquisition for legacy tonnage. Yard relationship consolidation at ANP-compliant facilities protects delivery slot access against local content timeline compression.
For New Entrants and Emerging Players: Offshore wind developers in Brazilian northeastern waters represent an underserved buyer archetype with distinct vessel specifications and reduced local content stringency compared to pre-salt oil and gas concessions. Targeting hybrid-electric crew boat demand for floating wind pilots enables technology differentiation without competing against established platform supply incumbents. Direct tender participation with ANP environmental licensing authorities bypasses broker-mediated charter patterns.
For Investors and Strategic Acquirers: Consolidation pressure builds where ANP certification backlog exceeds yard capacity and specialized marine engineering labor scarcity constrains hybrid-electric retrofit execution. Long-term viability centers on fleet operators with captive Brazilian yard relationships and proven local content compliance documentation. Monitor Petrobras carbon intensity disclosure requirements as the inflection signal for accelerated diesel-mechanical obsolescence.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Retrofit Program | Battery-diesel integration reduces carbon intensity indicators for ANP-regulated charter renewals in Santos basin. |
| Brazilian Yard Partnership Consolidation | Exclusive relationships with Estaleiro Atlântico Sul secure local content-compliant delivery slots against timeline compression. |
| Remote Operations Center Deployment | Satellite telemetry enables shore-based vessel monitoring for reduced crewing requirements in deepwater zones. |
| DP-3 Redundancy Certification Drive | Dynamic positioning upgrades exclude older tonnage from premium ExxonMobil and Petrobras charter tiers. |
| Offshore Wind Vessel Specification Development | Reduced acoustic signature crew boats capture Brazilian northeastern floating wind pilot demand. |
Research Methodology
Direct dialogue with Petrobras chartering executives, Pemex logistics coordinators, Brazilian shipyard operations managers, and ANP certification officers grounded qualitative findings in procurement authority patterns and regulatory enforcement timelines. Secondary validation drew from ANP Resolution 847 documentation, ASEA environmental compliance filings, IMO Tier III technical circulars, and customs hull construction import records. Bottom-up vessel deployment counts across Brazilian, Mexican, and Guyanese basins triangulated against top-down national oil company capital expenditure disclosures.
Market size outputs derived from day rate benchmarking across vessel type segments, utilization rate assumptions by water depth tier, and fleet composition modeling through the projection horizon. Segmentation dimensions encompassed vessel specification, deployment depth threshold, end-user procurement structure, and service unbundling patterns. CAGRs emerged from charter rate trajectory analysis, fleet renewal timelines tied to emission regulation phase-ins, and pre-salt field development cadence.
Inputs from ANP certification databases and Petrobras tender documentation were available through the study window; gaps in private operator rate disclosure introduce uncertainty bands around Mexican Gulf volume estimates. Forecasts reflect assumptions on IMO enforcement consistency and Brazilian local content threshold stability. Material deviation in ANP timeline compression or hybrid-electric technology cost curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Air Compressors on Ships Market
Maritime Equipment
LNG Carrier Market
Maritime Equipment
Global Connected Ship Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
North America Container Terminal Operations Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Ship Plate Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market
Maritime Equipment
Barge Transportation Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
Ship Anchor Market