
 Europe Maritime Information Market | 2026-2036
Europe Maritime Information Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Maritime Information Market Intelligence
North Sea and Baltic port operators is hardening demand for real-time vessel tracking and traffic coordination systems. Kongsberg Maritime leverages its sonar and dynamic positioning heritage to dominate hydroacoustic data layers for subsea mapping. BAE Systems Plc sustains defense-grade encryption capabilities that anchor its position in naval maritime intelligence contracts. Thales Group competes through integrated radar-AIS fusion platforms that extend across French and Mediterranean coastal installations.
Europe Maritime Information encompasses the collection, processing, and distribution of vessel position data, meteorological conditions, port status, and regulatory compliance metrics through satellite, terrestrial, and cloud-based architectures. These systems integrate Automatic Identification System transponder feeds, synthetic aperture radar returns, and meteorological buoy networks to enable collision avoidance, route optimization, and emissions verification across commercial and governmental fleets. Navigation Services and Vessel Tracking command the largest installed base due to mandatory SOLAS carriage requirements, while Cloud Computing infrastructure represents the fastest-expanding technology layer as port authorities migrate from on-premise legacy servers to distributed maritime data exchanges. Shipping Companies constitute the most technically demanding end-user segment, driving integration of AIS, radar, and weather feeds into single-voyage optimization platforms.
EMA's maritime safety directives, the EU Green Deal's MRV monitoring framework, and national implementations of the IMO's Data Collection System shape product certification pathways and create compliance-driven procurement cycles across member states. CE marking requirements for marine electronics constrain market access for non-conforming suppliers while accelerating standardization of sensor interoperability protocols. Stakeholders must weigh the capital intensity of satellite constellation ownership against the margin compression from commoditized AIS data feeds when allocating R&D budgets.
Market Dynamics
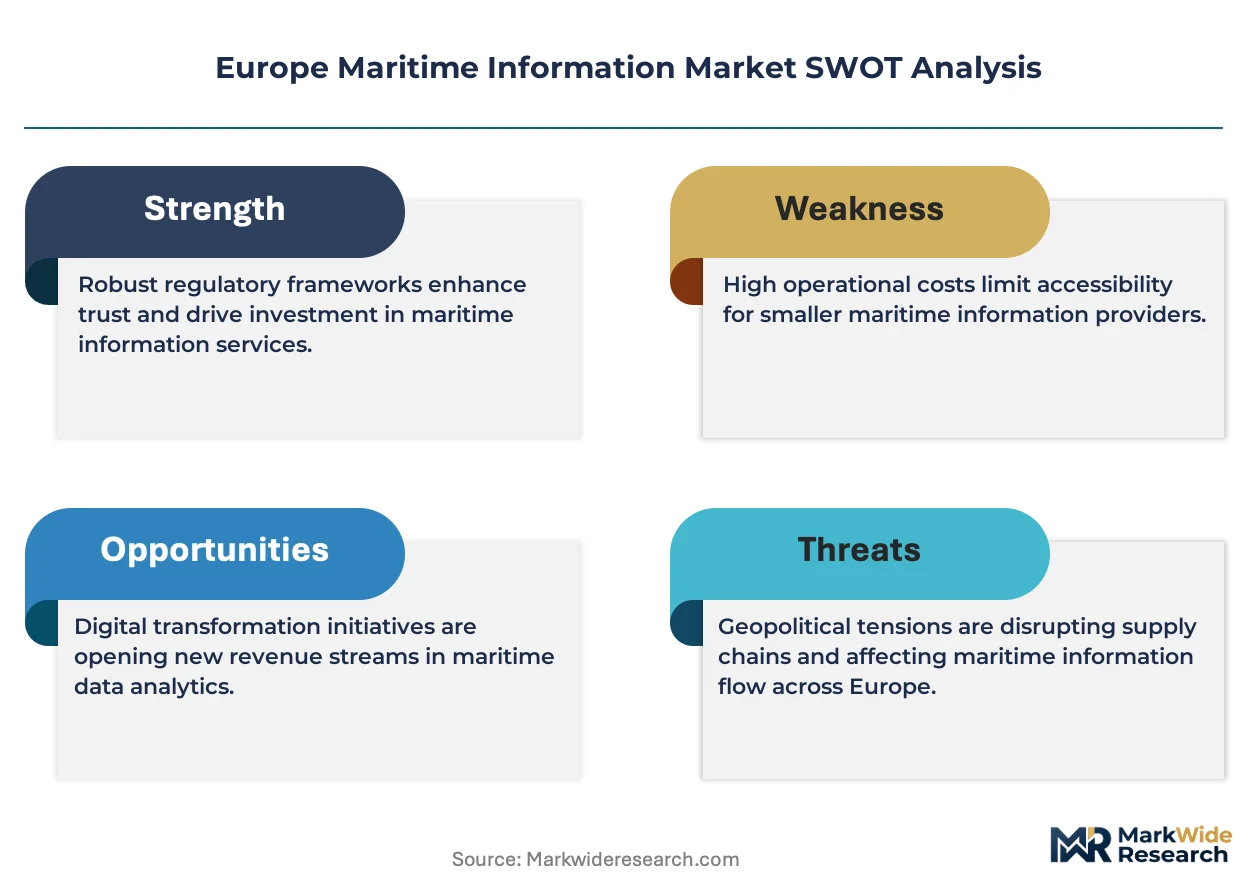
Port authorities across Northern Europe are consolidating vessel traffic management under unified digital platforms, compressing procurement timelines for integrated maritime data systems while fragmenting legacy hardware vendor relationships.
Growth Catalysts
- EU Green Deal MRV framework:Mandatory emissions verification for vessels above 5,000 gross tonnage is forcing shipping operators to install certified fuel consumption monitoring and automated reporting infrastructure.
- Cloud migration:Hamburg and Bremerhaven port authorities are replacing on-premise legacy servers with distributed maritime data exchanges, accelerating demand for API-integrated vessel tracking services.
- SOLAS carriage mandates:Automatic Identification System transponder requirements for collision avoidance continue to expand the installed base of navigation and vessel tracking hardware across European commercial fleets.
Market Restraints
- Satellite constellation capital intensity:The cost of owning and maintaining proprietary AIS satellite networks compresses margins for data providers competing against commoditized terrestrial feeds.
- CE marking compliance friction:Marine electronics certification requirements constrain market access for non-conforming sensor suppliers and delay product launch timelines.
- Legacy system lock-in:Port authorities in older European maritime clusters face high switching costs when migrating from decades-old radar installations to integrated radar-AIS fusion platforms.
Strategic Opportunities
- Baltic Sea corridor expansion:Polish and Estonian port operators remain underpenetrated for real-time hydroacoustic subsea mapping services used in Northern European hubs.
- Meteorological buoy network integration:Convergence of satellite AIS feeds with coastal weather sensor arrays creates new subscription revenue models for route optimization platforms.
- CSRD disclosure alignment:The EU Corporate Sustainability Reporting Directive's maritime transport scope creates compliance-driven procurement cycles for emissions verification software among listed shipping companies.
Industry Challenges
- Cybersecurity certification timelines:Defense-grade encryption standards for naval maritime intelligence contracts require multi-year accreditation processes that strain vendor cash flows.
- Sensor interoperability gaps:Fragmented protocols between synthetic aperture radar returns, AIS transponder feeds, and meteorological data streams complicate single-voyage optimization platform development.
- Specialized talent scarcity:Shortages of maritime data engineers familiar with both naval architecture and cloud-native distributed systems limit R&D velocity for integrated port management upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Maritime Information Market |
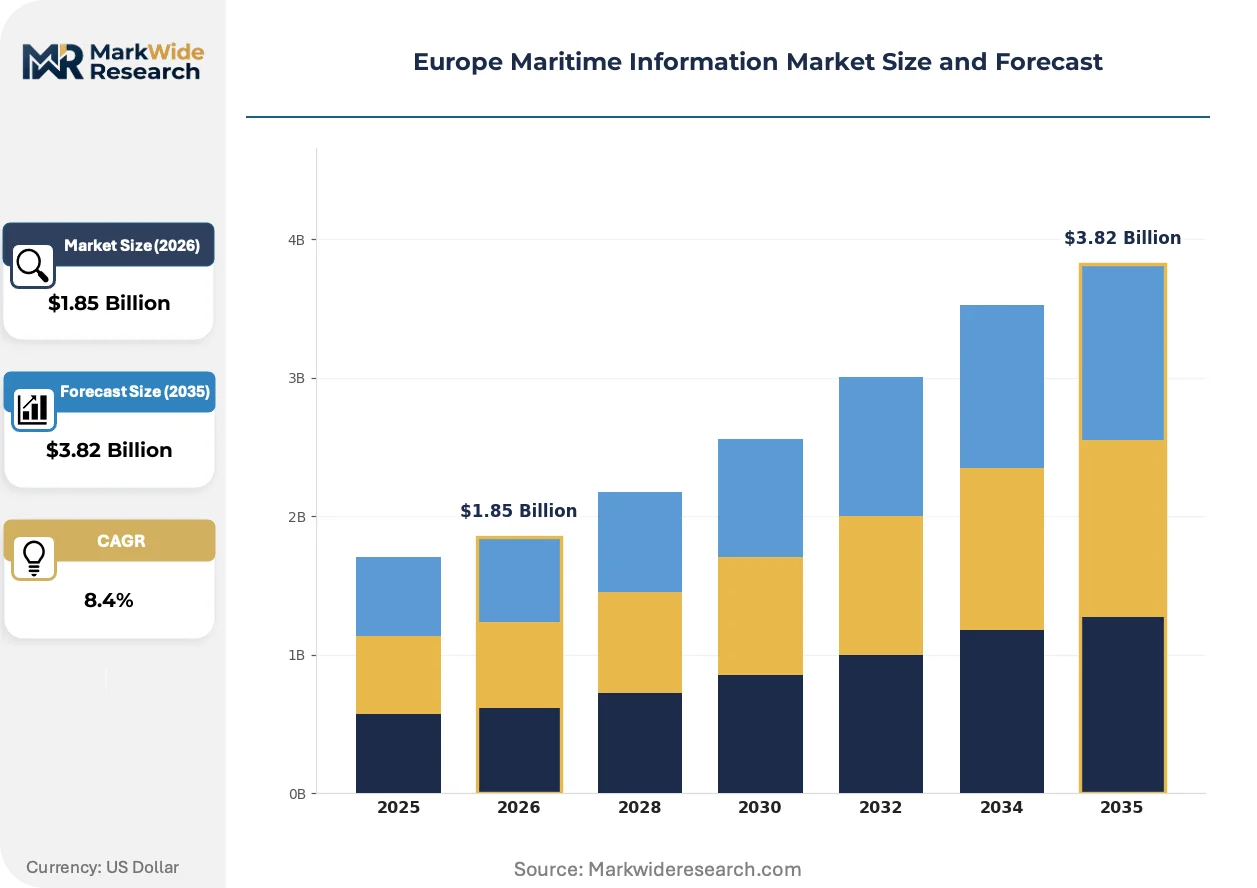
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Navigation Services, Weather Forecasting, Vessel Tracking, Port Management Technology: Satellite Communication, AIS, Radar Systems, Cloud Computing End User: Shipping Companies, Port Authorities, Fishermen, Logistics Providers Application: Traffic Management, Search & Rescue, Cargo Operations, Compliance Monitoring |
| Companies Covered | Northrop Grumman Corp, ORBCOMM Inc., BAE Systems Plc, Kongsberg Maritime, Spire Global, Thales Group, Saab AB, Windward Ltd, Lockheed Martin Corp, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Maritime Information Market Strategic Shifts & Innovations
Maritime information architectures are pivoting from hardware-centric vessel tracking toward software-defined data fusion layers that aggregate multi-source feeds into actionable voyage intelligence.
Edge computing nodes deployed directly on vessels are rewriting how position and fuel consumption data gets processed, eliminating latency-heavy shore-side aggregation. Shipping companies operating North Sea routes are adopting these distributed architectures fastest, compressing the competitive window for traditional satellite-only data providers.
The EU AI Act's risk classification framework for autonomous maritime decision systems is tightening validation requirements for collision avoidance algorithms. French and Mediterranean coastal installations face the steepest compliance ramps, driving demand for certified radar-AIS fusion platforms that document explainability trails.
Charterers are unbundling after-sales service from hardware procurement, preferring metered data subscriptions over capital-intensive system ownership. This consumption-pattern shift is most visible among German container lines, which now treat vessel tracking as an operating expense rather than a fleet asset.
Europe Maritime Information Market Segmentation
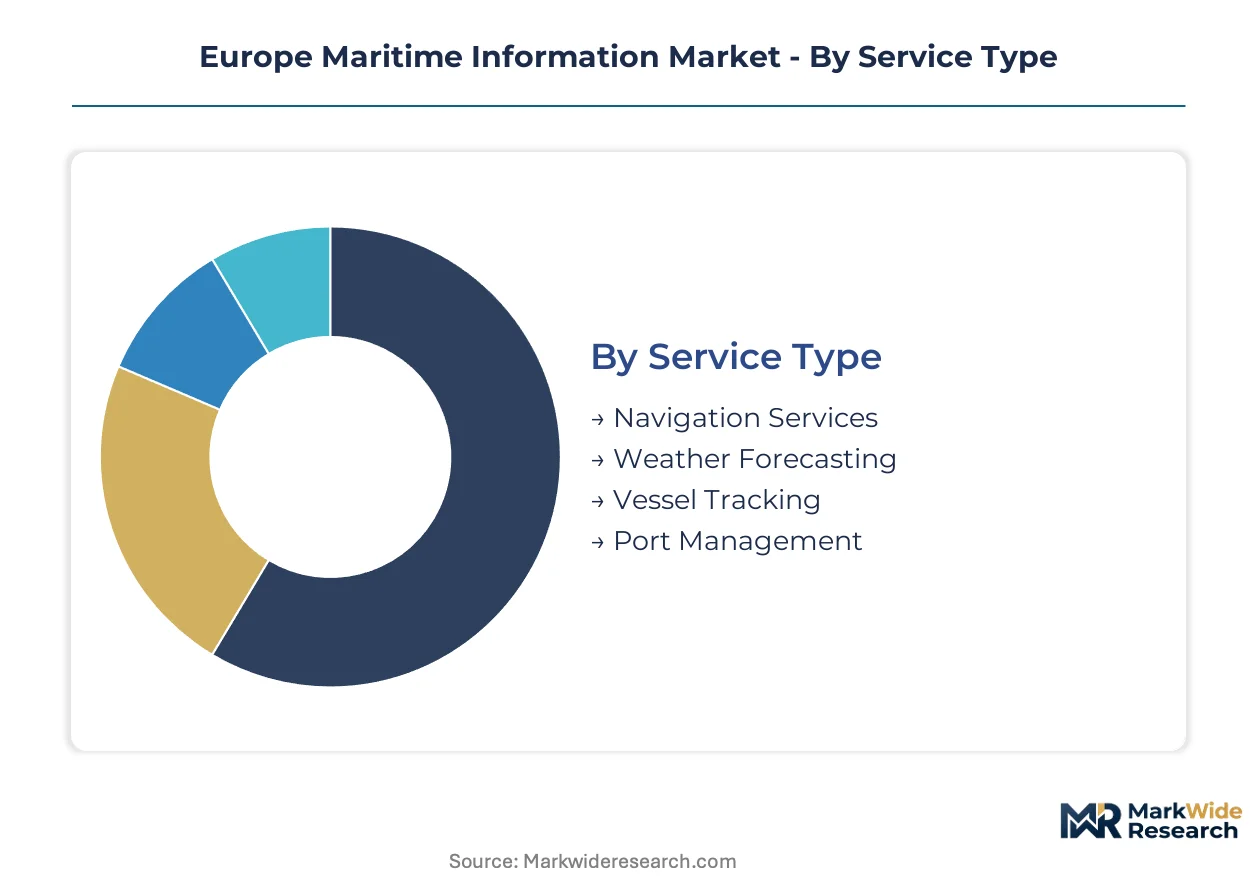
Segmentation in the Europe Maritime Information Market reflects divergent technical requirements across vessel operators, port authorities, and regulatory bodies. Service architectures must reconcile SOLAS-mandated carriage rules with voluntary optimization platforms, creating distinct procurement patterns across customer tiers.
Service Type:
Technical specifications determine integration complexity and recurring revenue potential across maritime data services.
- Navigation Services:SOLAS-mandated collision avoidance systems integrate GPS positioning, electronic chart displays, and gyrocompass feeds into unified bridge architectures. German and Dutch commercial fleets drive replacement cycles as ECDIS standards tighten certification requirements for voyage data recorders.
- Vessel Tracking:Real-time position reporting combines satellite AIS transponders with terrestrial base station triangulation for coastal coverage redundancy. North Sea operators demand sub-minute update frequencies for traffic coordination, compressing margins for providers relying solely on legacy satellite refresh rates.
- Weather Forecasting:Meteorological routing services synthesize buoy network data with satellite imagery for voyage optimization.
- Port Management:Integrated terminal operating systems consolidate berth scheduling, cargo handling, and customs documentation workflows.
Mature deployment sits with Navigation Services. Newer deployment is concentrated in Port Management.
Technology:
Cost tier differentiation separates capital-intensive infrastructure ownership from subscription-based data access models.
- Cloud Computing:Distributed maritime data exchanges replace on-premise legacy servers, enabling API-integrated vessel tracking and emissions verification workflows. Hamburg and Bremerhaven port authorities accelerated migration timelines, creating demand spikes for hybrid cloud architectures that bridge classified naval zones with commercial freight corridors.
- AIS:Automatic Identification System transponders transmit vessel identity, position, course, and speed via VHF radio to shore stations and satellite constellations. Baltic Sea corridors exhibit the steepest installation growth as Polish and Estonian operators modernize traffic management infrastructure.
- Satellite Communication:L-band and Ku-band constellations provide beyond-line-of-sight connectivity for deep-water fleets.
- Radar Systems:Synthetic aperture and X-band coastal radars detect non-AIS-equipped vessels in high-density traffic zones.
Legacy hardware concentration persists in Radar Systems. Cloud Computing climbs the fastest among technology layers.
End User:
Application intensity varies sharply between commercial fleet operators and public maritime authorities.
- Shipping Companies:Container lines and bulk carriers demand single-voyage optimization platforms integrating AIS, weather, and fuel consumption feeds for route planning. German operators lead technical sophistication, treating vessel tracking as metered operating expenses rather than capital assets.
- Port Authorities:Vessel traffic service centers coordinate pilotage, tug allocation, and berth assignment through real-time data fusion platforms. Northern European hubs consolidate procurement under unified digital architectures, fragmenting legacy vendor relationships.
- Logistics Providers:Freight forwarders and supply chain managers track container positioning across multimodal networks.
- Fishermen:Small-scale operators utilize basic AIS transponders and mobile weather applications for safety compliance.
Established penetration characterizes Port Authorities. Shipping Companies represent the steepest expansion trajectory for integrated platform adoption.
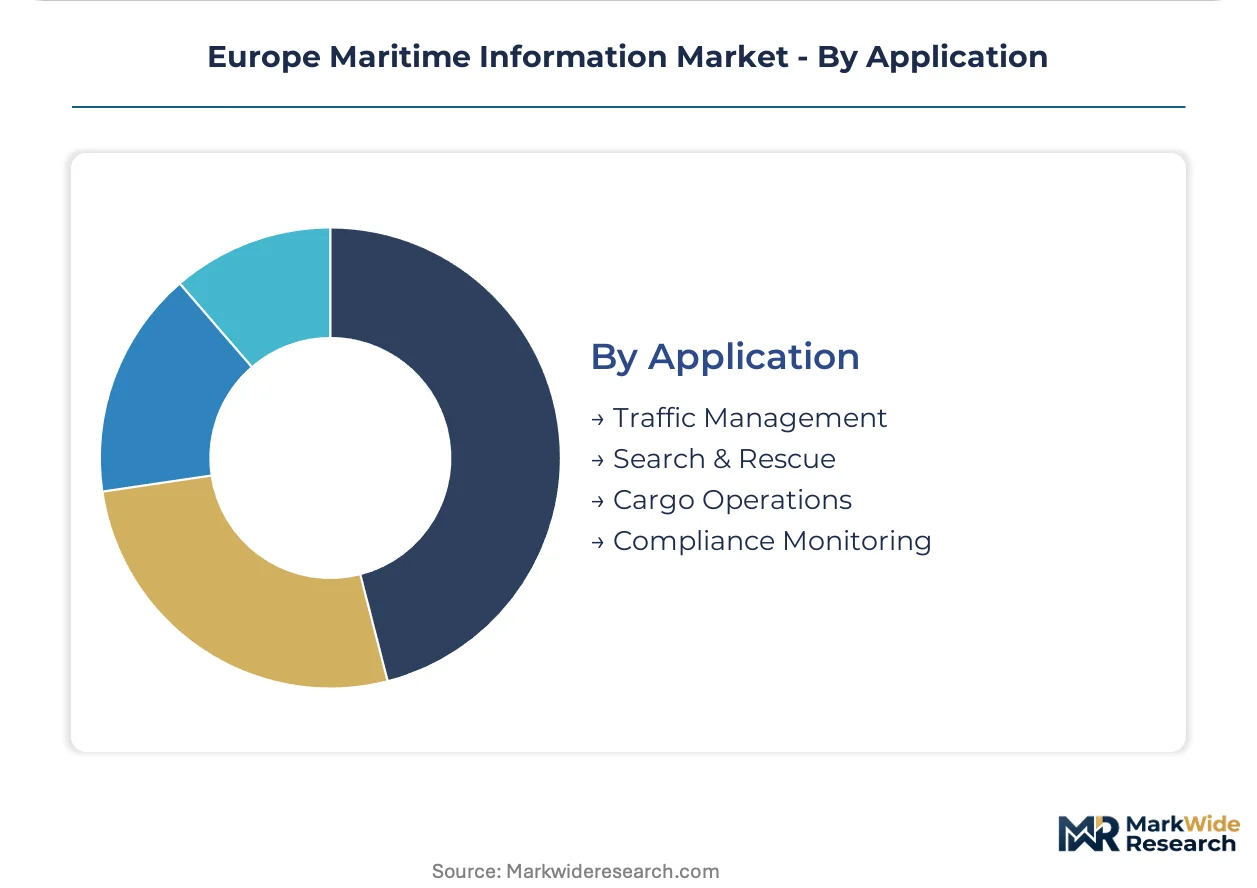
Application:
Regulatory compliance intensity shapes procurement urgency across operational use cases.
- Compliance Monitoring:EU MRV and IMO Data Collection System mandates require automated fuel consumption logging and emissions reporting for vessels above 5,000 gross tonnage. French and Mediterranean coastal installations face accelerated validation timelines as CSRD disclosure rules expand maritime transport scope.
- Traffic Management:Real-time vessel coordination prevents collisions in constrained waterways and port approaches. North Sea and Baltic operators harden demand for radar-AIS fusion platforms that resolve sensor conflicts in high-density shipping lanes.
- Cargo Operations:Terminal efficiency optimization matches vessel arrival times with berth availability and stevedore scheduling.
- Search & Rescue:Coast guard and naval authorities coordinate emergency response using drift modeling and asset positioning systems.
Institutionalized deployment anchors Traffic Management. Compliance Monitoring gains share fastest as regulatory frameworks tighten verification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea hydrocarbon basins and Baltic shipping corridors supply the geographic foundation for maritime data infrastructure deployment across the continent.
Germany
Hamburg and Bremerhaven port authorities drive demand for integrated vessel traffic management platforms. The EU Green Deal MRV framework mandates emissions verification systems for container fleets operating from German terminals. Northern German maritime clusters concentrate procurement for cloud-based port operating systems that consolidate berth scheduling with customs workflows.
United Kingdom
North Sea offshore energy operators require real-time subsea positioning data for platform maintenance logistics. The UK Maritime and Coastguard Agency enforces SOLAS carriage standards for collision avoidance systems in high-density shipping lanes. Aberdeen and Scottish coastal installations anchor demand for hydroacoustic mapping services tied to oil and gas decommissioning programs.
France
Mediterranean port operators at Marseille-Fos invest in radar-AIS fusion platforms for traffic coordination in constrained waterways. The EU AI Act risk classification framework tightens validation requirements for autonomous maritime decision systems deployed in French waters. Côte d'Azur coastal surveillance installations exemplify accelerated compliance ramps for certified collision avoidance algorithms.
Netherlands
Rotterdam Europoort complex generates concentrated demand for terminal operating systems that synchronize vessel arrivals with stevedore scheduling. REACH chemical handling regulations intersect with port safety protocols for hazardous cargo tracking. Dutch maritime engineering clusters specialize in meteorological routing integration for North Sea container routes.
Poland
Gdańsk and Gdynia port authorities modernize traffic management infrastructure with real-time vessel tracking systems. National implementation of IMO Data Collection System standards accelerates fuel consumption monitoring procurement for Baltic Sea operators. Polish maritime clusters represent underpenetrated territory for hydroacoustic subsea mapping services established in Northern European hubs.
Europe Maritime Information Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue satellite constellation and edge computing architectures. The vendor base organizes around three strategic archetypes: defense contractors with encryption-accredited naval intelligence capabilities, maritime technology specialists leveraging sonar and positioning heritage, and satellite data providers competing on refresh rate and geographic coverage. Consolidation pressures intensify as port authorities unify procurement under single-platform contracts. Competitive moves center on API integration partnerships with port operating systems and backward integration into proprietary sensor networks.
Among defense-accredited contractors, BAE Systems Plc and Thales Group exemplify the encryption-tier archetype for naval maritime intelligence applications. Kongsberg Maritime anchors the hydroacoustic specialization segment with heritage positioning in subsea mapping and dynamic positioning systems. Spire Global and ORBCOMM Inc. occupy the satellite data provider tier, competing on constellation density and terrestrial coverage redundancy for real-time AIS feeds.
| Leading Market Players |
|---|
| Northrop Grumman Corp |
| ORBCOMM Inc. |
| BAE Systems Plc |
| Kongsberg Maritime |
| Spire Global |
| Thales Group |
| Saab AB |
| Windward Ltd |
| Lockheed Martin Corp |
| Others |
Cost & Logistics Intelligence
Satellite transponder hardware and VHF radio components flow from specialized Nordic and Asian manufacturing clusters through CE-certified assembly tiers, with cloud-native software layers commanding recurring subscription premiums that decouple from sensor capital costs.
Pricing Analysis
After-sales service unbundling from hardware procurement reshapes commercial terms across German container lines and Northern European port authorities. Three-tier pricing structure across defense-accredited, commercial-grade, and economy sensor tiers separates encryption-certified naval contracts from commoditized AIS data feeds. Pricing pressure stems from terrestrial network densification compressing margins for satellite-only providers. Port authorities exhibit lowest price sensitivity due to compliance-driven procurement cycles, while small-scale fishing operators resist premium tier upgrades.
Supply Chain Analysis
CE marking and SOLAS certification requirements gate market access for marine electronics suppliers, constraining component sourcing to accredited fabrication facilities. Sensor manufacturing concentrates in Germany, Norway, and South Korea, with specialized sonar arrays drawing from Nordic subsea technology clusters. Gallium nitride semiconductors, precision gyrocompass assemblies, and hardened marine-grade enclosures constitute critical input dependencies. Single-source vulnerability sits with proprietary AIS satellite constellation operators. Distribution runs through systems integrators serving defense and commercial maritime verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures intensify as Hamburg and Bremerhaven port authorities unify procurement under single-platform contracts, forcing subscale hardware vendors into exit or acquisition pathways.
For Market Incumbents: Extend API integration partnerships with terminal operating systems to deepen platform stickiness against emerging edge computing entrants. Acquire specialized meteorological buoy network operators to capture route optimization subscription revenues. CE marking accreditation investments anchor defensive positioning as regulatory verification timelines lengthen. For New Entrants and Emerging Players: Edge computing nodes deployed directly on vessels offer a technology-first wedge into North Sea shipping routes where latency compression commands premium positioning. Polish and Estonian Baltic corridor ports represent the most penetrable geography for hydroacoustic subsea mapping services. Metered data subscription models bypass capital-intensive fleet sales cycles. For Investors and Strategic Acquirers: Hamburg port authority cloud migration completion is the leading indicator that hybrid maritime data exchanges have crossed technical validation thresholds. Five-to-ten year viability favors satellite constellation operators with terrestrial coverage redundancy and defense encryption accreditation. Watch for Polish port modernization tender announcements as inflection signals for Baltic Sea corridor expansion.| Strategic Initiative | Industry Significance |
|---|---|
| API Integration Partnership | Port authority unified procurement demands seamless data exchange with Hamburg and Bremerhaven terminal systems. |
| Backward Integration into Sensor Networks | Proprietary AIS satellite ownership reduces dependency on commoditized terrestrial feed competitors. |
| Defense Encryption Accreditation | BAE Systems and Thales Group anchor naval intelligence contracts through multi-year cybersecurity certification. |
| Edge Computing Node Deployment | Vessel-mounted processing eliminates shore-side latency for North Sea route optimization platforms. |
| Meteorological Buoy Network Acquisition | Convergence with satellite AIS feeds creates differentiated subscription revenue for route planning services. |
Research Approach
Independent corroboration across port authority procurement officers, maritime data platform engineers, and naval systems integrators underwrites the qualitative findings. Vessel traffic service center directors, shipping company fleet managers, and marine electronics certification specialists provided primary perspective. Secondary validation drew from EU MRV regulatory filings, port authority annual infrastructure reports, SOLAS carriage requirement updates, and Automatic Identification System deployment databases. Bottom-up segment sizing triangulates against top-down European maritime trade volume correlations.
Comparable historical reference periods anchor the projection framework across the analysis window. Segmentation models disaggregate by service architecture, technology layer, end-user sophistication tier, and regulatory compliance intensity. CAGRs derive from fitted growth curves calibrated to cloud migration adoption rates and emissions verification mandate implementation phases. Satellite constellation capex cycles and port digitalization budget trajectories constitute industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including classified naval intelligence contract values and speculative autonomous vessel regulatory frameworks. Forecasts reflect documented assumptions regarding EU Green Deal enforcement consistency and SOLAS standard revision timelines. A model refresh is warranted upon material change in MRV verification audit failure rates or Polish port modernization acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Marine Hatch Covers Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Global Connected Ship Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Asia-Pacific Maritime Satellite Communication Market
Maritime Equipment
Green Ship Recycling Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Offshore Support Vessel Service Market
Maritime Equipment
Marine Lubrication System Market