
 Stevedoring and Marine Cargo Handling Market | 2026-2036
Stevedoring and Marine Cargo Handling Market Size, Share, and Industry Trends Forecast 2026-2036
Stevedoring and Marine Cargo Handling Market Analytics
The International Maritime Organization's carbon intensity regulations is consolidating capital requirements for new terminal concessions, forcing smaller stevedoring contractors to surrender licenses or merge. DP World leverages its Jebel Ali and London Gateway assets to sustain integrated logistics corridors across three continents. APM Terminals anchors its competitive position through automated stacking crane deployments in Rotterdam and Algeciras. Hamburger Hafen und Logistik differentiates via its rail-linked container terminals that control hinterland access across Northern Europe.
Stevedoring and marine cargo handling encompasses the physical transfer of goods between vessels and shoreside infrastructure, utilizing gantry cranes with lifting capacities exceeding 65 tonnes, straddle carriers, and automated guided vehicles to manage containerized, bulk, and breakbulk flows through port interfaces. Container handling dominates service-type revenue pools due to standardized box movements enabling automation scale, while breakbulk operations retain premium pricing for project cargo requiring specialized lashings and heavy-lift coordination. Automated systems within the technology dimension attract the fastest capital deployment as ports pursue berth productivity targets, though manual loading persists in developing economies where labor arbitrage offsets mechanization costs.
The European Union's F-Gas Regulation and the EPA's marine diesel engine standards in the United States jointly constrain equipment procurement choices, compelling terminal operators to source electric or hybrid cargo handling machinery to maintain operating licenses. China's MIIT enforces domestic emission standards for port machinery that shape supplier qualification lists for Asia-Pacific concessions. Port authorities and shipping lines must monitor regulatory divergence across jurisdictions to avoid stranded asset risk in their stevedoring equipment portfolios.
Market Dynamics
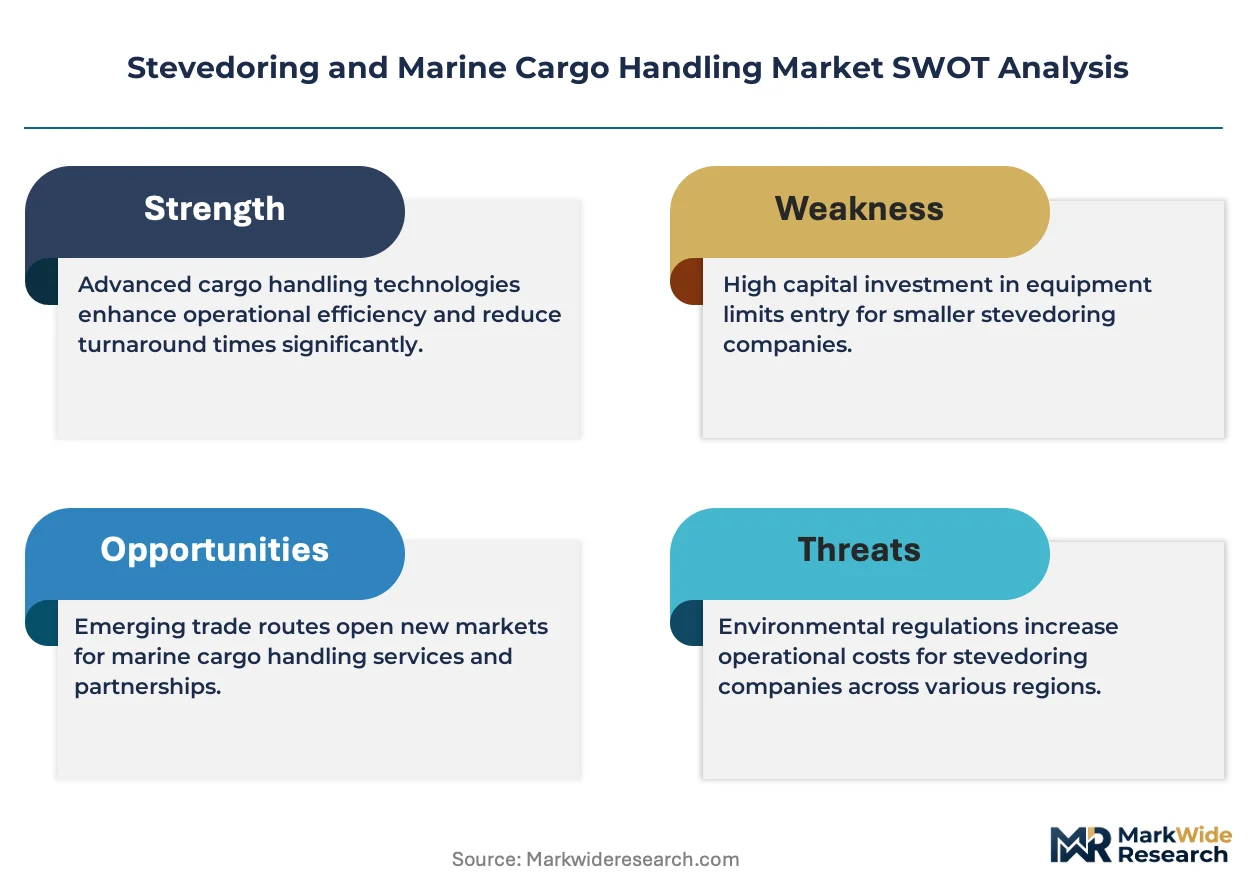
Vessel upsizing to 24,000 TEU Ultra Large Container Ships concentrates berth demand at deep-water terminals, forcing port authorities to dredge channels and extend quay walls while smaller facilities lose transshipment calls.
Growth Catalysts
- IMO Carbon Intensity Regulations:Terminal operators in Singapore, Rotterdam, and Shanghai must electrify gantry cranes and retrofit diesel equipment, creating sustained demand for shore power infrastructure and battery-hybrid handling systems.
- East Asian Transshipment Clustering:Mega-ports in Busan, Kaohsiung, and Tanjung Pelepas compete for intermodal throughput leadership, driving automation investments that compress vessel turnaround times below eighteen hours.
- Automated Guided Vehicles:AGV deployments at Algeciras and Rotterdam eliminate manned container transport between quay and yard, reducing labor costs per move while enabling twenty-four-hour operations.
Market Restraints
- Steel Price Volatility:Gantry crane fabrication depends on high-tensile steel plate, with input cost swings compressing equipment manufacturer margins and delaying terminal concession bids.
- European Equipment Supply Concentration:Three German and Dutch crane builders control seventy percent of super-post-Panamax crane output, creating procurement bottlenecks for Asian port authorities.
- Electrification Infrastructure Gaps:Grid capacity limitations at Indonesian and Vietnamese terminals block shore power installation, forcing continued reliance on auxiliary diesel engines and threatening IMO compliance timelines.
Strategic Opportunities
- Vietnamese Deep-Water Greenfield Sites:Lach Huyen and Cai Mep terminals offer undeveloped berth frontage for automated terminals serving manufacturing relocation from China.
- Rail-Linked Inland Depots:Hamburger Hafen und Logistik's model of controlling hinterland access via dedicated rail corridors can replicate at Genoa, Barcelona, and Gdansk to capture containerized cargo.
- EU F-Gas Regulation Phase-Down:Terminal operators must replace refrigerants in reefer container infrastructure, creating retrofit contracts for cold chain handling equipment.
Industry Challenges
- Crane Operator Certification Bottlenecks:Remote-controlled and automated stacking crane systems require new competency frameworks that maritime training institutes have not yet standardized.
- Legacy TOS Integration:Terminal operating systems at older facilities use proprietary data formats that resist API connectivity with new automated equipment fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stevedoring and Marine Cargo Handling Market |
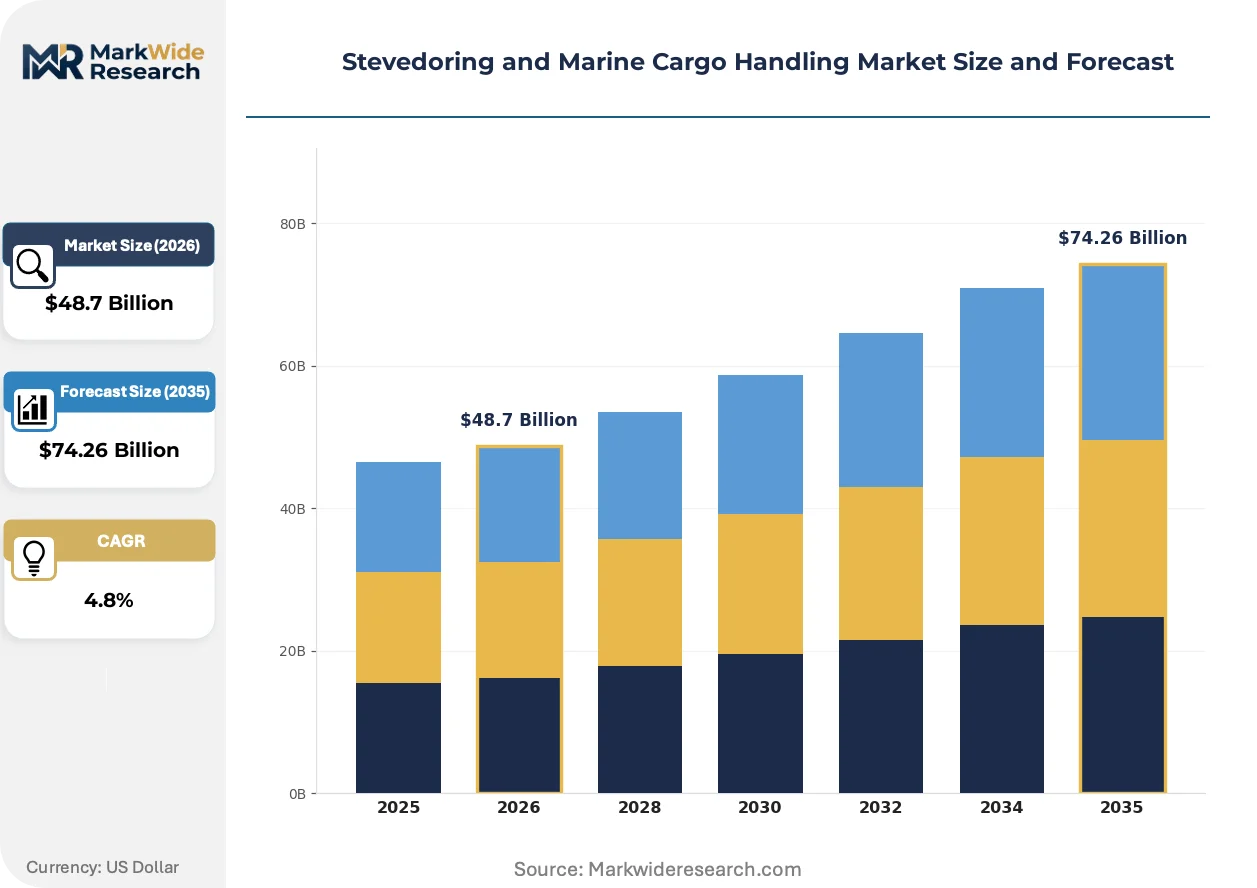
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $74.26 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Container Handling, Bulk Cargo, Breakbulk Operations, Ro-Ro Services Technology: Automated Systems, Manual Loading, Cranes, Forklifts End User: Shipping Lines, Freight Forwarders, Port Authorities, Logistics Providers Operation Mode: Onshore, Offshore, Terminal Operations, Dockside Activities |
| Companies Covered | DP World, Hamburger Hafen und Logistik, APM Terminals, International Container Terminal Services (ICTSI), Royal Boskalis Westminster, Ports America, CMA CGM, SAAM, Irish Continental Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stevedoring and Marine Cargo Handling Market Evolving Landscape
Digital twin technology and predictive maintenance algorithms are compressing equipment downtime windows while regulatory emission mandates force propulsion system redesigns across cargo handling fleets.
Artificial intelligence-based berth allocation software is converging with real-time vessel tracking data to optimize quay crane deployment. Major container terminals in Singapore and Rotterdam deploy these systems to reduce idle crane hours. The technology is converging with automated yard planning to synchronize vessel arrival windows with hinterland truck and rail schedules.
The European Union's F-Gas Regulation mandates phased reduction of hydrofluorocarbon refrigerants in reefer container handling equipment. Terminal operators must retrofit or replace cooling infrastructure at cold storage facilities to maintain operating licenses. Mediterranean and Baltic ports face accelerated compliance timelines due to stricter national implementation schedules.
Shipping lines now bundle stevedoring contracts with multi-year berth priority agreements, displacing spot market arrangements. Container carriers at Jebel Ali, Colombo, and Tanjung Pelepas negotiate guaranteed crane intensity minimums. This procurement consolidation concentrates service provider selection among vertically integrated terminal operators with balance sheet capacity for automation capex.
Stevedoring and Marine Cargo Handling Market Segmentation
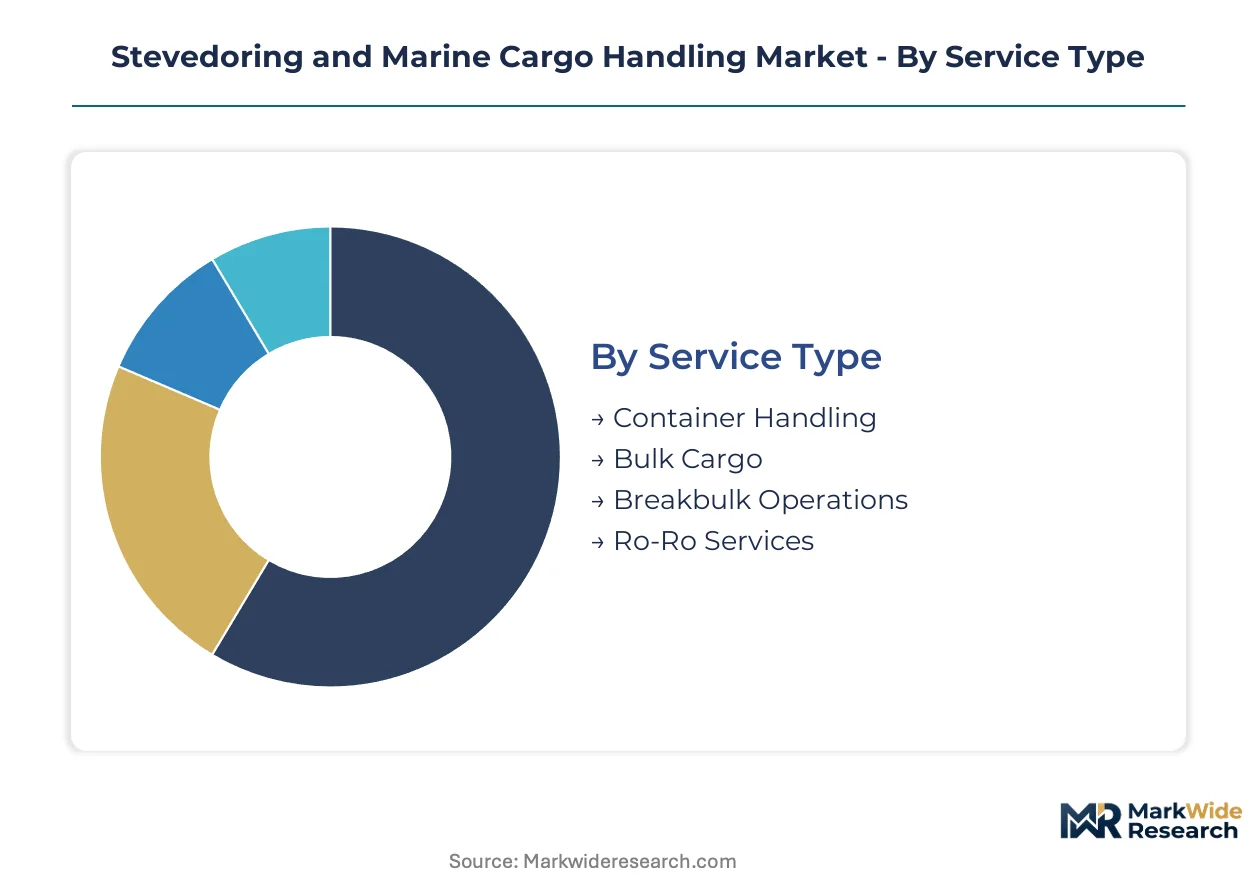
Segmentation in stevedoring and marine cargo handling reveals how procurement decisions split between automation-intensive mega-terminals and labor-dependent regional facilities. Service buyers prioritize different capability bundles based on vessel size profiles, cargo mix, and hinterland connectivity requirements.
Service Type:
Buyers differentiate by cargo standardization and handling complexity, with automation economics varying sharply across containerized versus non-containerized flows.
- Container Handling:Standardized twenty-foot and forty-foot box movements enable gantry crane automation and yard stacking optimization. Demand concentrates at Singapore, Rotterdam, and Shanghai where 24,000 TEU vessel calls require berth productivity above thirty moves per crane hour.
- Bulk Cargo:Grain, coal, and iron ore flows utilize grab cranes and conveyor systems with lower labor substitution potential. Indonesian and Australian terminals dominate volume as mining and agricultural exports drive dedicated bulk handling infrastructure investments.
- Breakbulk Operations:Project cargo requiring specialized lashings and heavy-lift coordination commands premium pricing at Hamburg and Antwerp.
- Ro-Ro Services:Vehicle and wheeled cargo handling at Zeebrugge and Bremerhaven supports automotive supply chain integration.
Container handling leads volumes today; breakbulk operations is gaining share fastest as offshore wind component logistics expands.
Technology:
Equipment selection hinges on labor cost arbitrage versus capital recovery timelines, with electrification mandates now overriding pure economic calculus.
- Automated Systems:Automated guided vehicles and remote-controlled stacking cranes eliminate manned container transport between quay and yard. Rotterdam's Maasvlakte terminals and Singapore's Pasir Panjang complex deploy these systems to sustain twenty-four-hour operations with reduced headcount.
- Manual Loading:Human-operated forklift and sling operations persist at Vietnamese and Bangladeshi terminals where wage differentials offset mechanization capex. Port authorities in Ho Chi Minh City and Chittagong prioritize employment over automation in concession renewals.
- Cranes:Ship-to-shore and rubber-tyred gantry cranes remain the dominant capital equipment category across all terminal scales.
- Forklifts:Internal combustion and electric forklift fleets handle breakbulk and Ro-Ro cargo at secondary terminals.
Automated systems leads capital deployment today; electrified crane retrofits is climbing the fastest as IMO carbon intensity deadlines approach.
End User:
Procurement authority has shifted toward shipping lines with balance sheet capacity for long-term berth commitments.
- Shipping Lines:Container carriers at Jebel Ali, Colombo, and Tanjung Pelepas negotiate multi-year stevedoring contracts bundling guaranteed crane intensity minimums with priority berth access. Maersk and MSC vertical integration into terminal operations concentrates service provider selection among operators matching their automation investment scale.
- Freight Forwarders:NVOCCs and logistics intermediaries purchase stevedoring as part of port-to-port service bundles at secondary hubs.
- Port Authorities:Government-owned terminal landlords in China and the UAE set equipment standards and emission compliance frameworks.
- Logistics Providers:DHL and Kuehne+Nagel contract stevedoring at integrated supply chain nodes.
Shipping lines leads contract value today; logistics providers is expanding most quickly as door-to-door service integration deepens.
Operation Mode:
Physical location determines equipment specification and regulatory jurisdiction, with offshore activities facing distinct environmental compliance burdens.
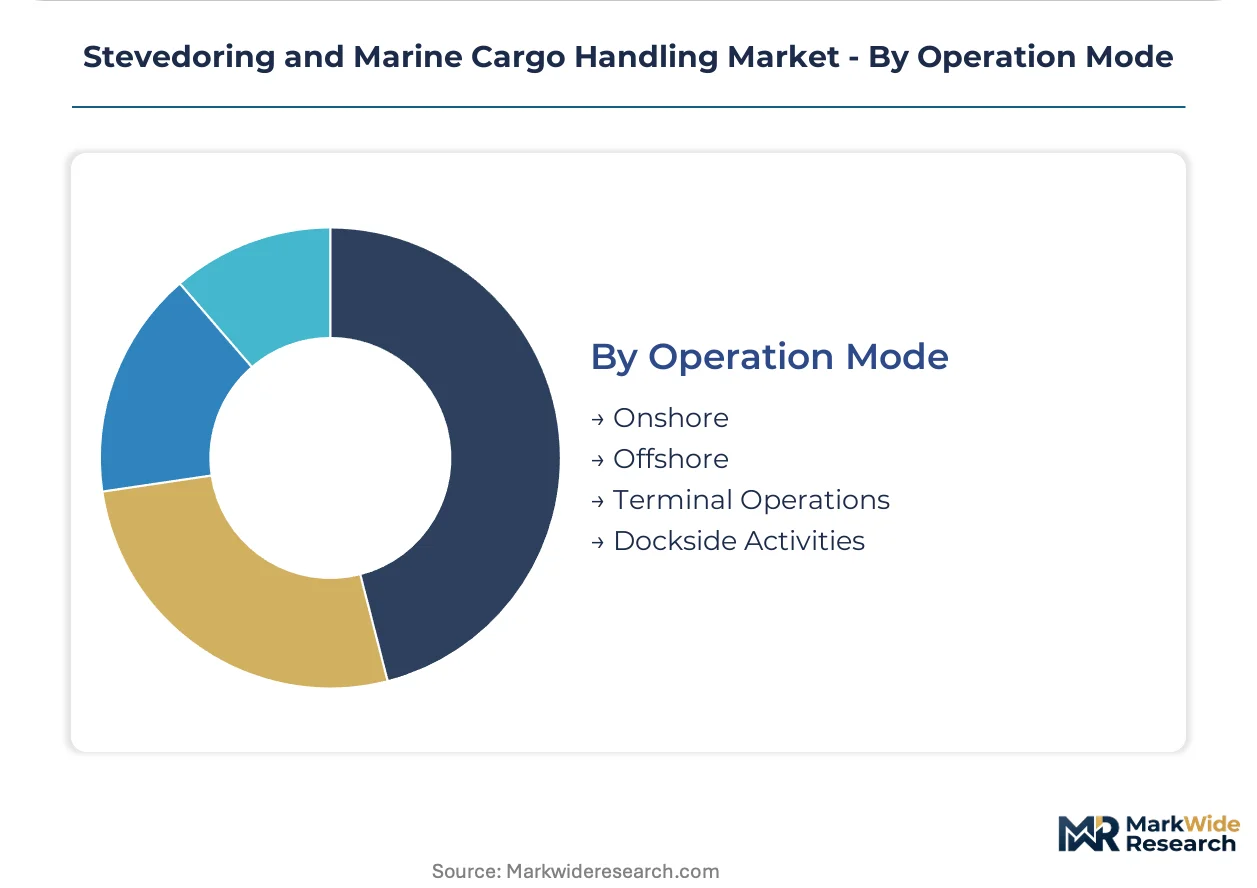
- Onshore:Quayside and yard operations at deep-water terminals handle the majority of container throughput. Busan and Kaohsiung compete for transshipment volume through onshore automation investments compressing vessel turnaround below eighteen hours.
- Offshore:Single-point mooring and lighterage operations at Nigerian and Brazilian crude export terminals require specialized floating cranes. Deepwater loading systems at Djeno and Espirito Santo bypass congested port infrastructure for VLCC direct transfer.
- Terminal Operations:Dedicated container, bulk, and multipurpose terminals operate under concession agreements with defined cargo mix obligations.
- Dockside Activities:Vessel provisioning, crew change logistics, and bunkering support occur alongside cargo operations.
Terminal operations leads revenue concentration today; offshore activities is gaining share fastest as pre-export crude blending expands at deepwater moorings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized crane operators and marine logistics engineers concentrate in port-adjacent industrial zones across Singapore, Rotterdam, and Shanghai. These talent clusters anchor terminal automation deployment and vessel turnaround optimization.
Singapore
Transshipment throughput at the Port of Singapore drives demand for ultra-large container vessel handling capacity. The Maritime and Port Authority enforces emission standards for cargo handling equipment that accelerate electrification timelines. The Tuas mega-port development consolidates container operations into a single automated complex with deep-water berths exceeding twenty meters.
Germany
Hamburger Hafen und Logistik controls rail-linked terminal infrastructure serving Northern European manufacturing supply chains. The EU F-Gas Regulation mandates refrigerant phase-downs in reefer container handling systems at Bremerhaven and Hamburg. The Hamburg-Altona and Bremerhaven container clusters compete for Baltic and North Sea transshipment volume through intermodal rail connectivity.
China
Shanghai Yangshan and Ningbo Zhoushan terminals handle the world's largest container vessel calls. MIIT emission standards for port machinery shape equipment procurement lists for Asia-Pacific concessions. The Yangtze River Delta port cluster integrates automated stacking systems with inland waterway feeder networks.
Netherlands
Rotterdam's Maasvlakte terminals deploy automated guided vehicles to sustain twenty-four-hour operations with reduced labor intensity. The EU Green Deal carbon neutrality targets force terminal operators to retrofit diesel-powered gantry cranes with shore power connections. The Rotterdam-Drechtsteden industrial corridor anchors European container distribution through dedicated rail and barge terminals.
United Arab Emirates
Jebel Ali Port secures multi-year berth priority contracts from major shipping lines through integrated logistics corridor investments. The UAE's national climate targets accelerate port electrification mandates for cargo handling equipment. Dubai South and Khor Fakkan terminals compete for Indian Ocean transshipment volume through automation scale and free zone adjacency.
Stevedoring and Marine Cargo Handling Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across concession-based terminal operations. The market structure concentrates among vertically integrated port operators with balance sheet capacity for automation capital expenditure and long-term berth commitments. Three strategic archetypes dominate: global terminal operators controlling multi-continent networks, regional specialists with rail-linked hinterland access, and shipping line captive terminals securing priority berth windows. Competitive dynamics center on concession renewal negotiations and automation deployment speed rather than price competition.
Within the global network operator tier, DP World and APM Terminals represent scale-driven archetypes with automated terminal deployments across multiple continents. Hamburger Hafen und Logistik anchors the regional specialist category through its integrated rail corridor control in Northern Europe. These three entities exemplify divergent strategic postures: network breadth versus hinterland depth versus shipping line integration.
| Leading Market Players |
|---|
| DP World |
| Hamburger Hafen und Logistik |
| APM Terminals |
| International Container Terminal Services (ICTSI) |
| Royal Boskalis Westminster |
| Ports America |
| CMA CGM |
| SAAM |
| Irish Continental Group |
| Others |
Value Network & Pricing Analysis
Shipping lines with multi-year berth priority contracts dominate procurement authority and anchor contract-based long-term pricing models across major transshipment hubs. Their balance sheet capacity for automation capex creates tiered service differentiation between integrated terminal operators and spot-market stevedoring contractors.
Pricing Analysis
Bundled service contracts bundling guaranteed crane intensity minimums with priority berth access displace unbundled spot arrangements at Jebel Ali, Colombo, and Tanjung Pelepas. Three-tier pricing structure across premium automation-intensive terminals, standard mechanized facilities, and economy labor-dependent ports reflects crane productivity differentials and emission compliance tiers. Price differentiation hinges on vessel size accommodation capacity and shore power infrastructure availability. Cost compression in economy-tier manual loading segments is intensifying because port authorities in Vietnam and Bangladesh prioritize employment quotas over mechanization in concession renewals. Regional bulk cargo handlers exhibit highest price sensitivity due to commodity-linked revenue volatility, while shipping line captives show lowest sensitivity given berth priority premiums.
Supply Chain Analysis
Refurbishment flows for diesel-powered gantry cranes and battery-hybrid retrofits create reverse logistics channels from European and East Asian terminals to specialized component remanufacturers. Equipment fabrication draws from high-tensile steel plate suppliers in Germany, South Korea, and Japan, with super-post-Panamax crane assembly concentrating at Dutch and German yards. Control systems and automation software rest on semiconductor inputs from Taiwan and sensor modules from Japan. Single-source vulnerability runs through the three German and Dutch crane builders controlling seventy percent of super-post-Panamax output. Distribution runs through port authority concession tenders and direct procurement by vertically integrated terminal operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification capex requirements and automation scale economies are compressing margins for non-compliant operators while rewarding premium-tier terminal investments with concession renewal security.
For Market Incumbents: Hedge stranded asset exposure by accelerating shore power infrastructure deployment ahead of IMO carbon intensity deadlines. Secure hinterland rail corridor control to defend against regional specialists replicating Hamburger Hafen und Logistik's Northern Europe model. Prioritize API-compatible terminal operating system upgrades to resolve legacy TOS integration bottlenecks blocking automated equipment fleet expansion. For New Entrants and Emerging Players: Port authorities in Indonesia and Vietnam present the most penetrable entry points given grid capacity limitations delaying incumbent electrification timelines. Target Vietnamese deep-water greenfield sites at Lach Huyen and Cai Mep where manufacturing relocation from China drives demand for automated terminal services. Pursue joint venture structures with domestic construction conglomerates to navigate concession bidding requirements. For Investors and Strategic Acquirers: Shipping lines are the most active acquirer in this space, consolidating captive terminal capacity to secure berth priority windows. Five-to-ten year viability favors operators with demonstrated automation deployment speed and existing multi-continent network scale. Monitor crane operator certification framework standardization progress at maritime training institutes as inflection indicator for labor substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Shore Power Infrastructure Deployment | Rotterdam's Maasvlakte terminals leverage shore connections to meet EU Green Deal carbon neutrality compliance timelines. |
| Automated Stacking Crane Integration | APM Terminals sustains competitive positioning through remote-controlled crane deployments at Algeciras and Rotterdam. |
| Rail-Linked Inland Depot Expansion | Hamburger Hafen und Logistik controls Northern European hinterland access via dedicated rail corridors from Hamburg. |
| Terminal Operating System Modernization | Singapore's Pasir Panjang complex resolves legacy TOS integration barriers to synchronize AGV fleets with vessel tracking data. |
| Reefer Container Infrastructure Retrofit | Mediterranean and Baltic ports face accelerated EU F-Gas Regulation compliance timelines for hydrofluorocarbon refrigerant phase-downs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement included terminal operations directors, port authority concession managers, shipping line fleet procurement officers, and maritime equipment manufacturer sales executives. Secondary validation drew from IMO regulatory filings, EU F-Gas Regulation implementation schedules, EPA marine diesel engine standard updates, and customs trade data on crane and port machinery imports. Bottom-up equipment deployment tallies and top-down terminal revenue estimates underwent cross-referencing to establish segmentation splits.
Segment-weighting approaches modeled service type, technology tier, end user category, and operation mode dimensions across the projection horizon. CAGRs derived from equipment investment pipelines, concession renewal calendars, and vessel upsizing trajectories. Forecast inputs incorporated 24,000 TEU vessel call frequency projections and shore power infrastructure buildout schedules at priority transshipment hubs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel price volatility, crane fabrication lead times, and regulatory divergence across IMO, EU, and national emission frameworks. Practitioners should monitor grid capacity expansion timelines at Indonesian and Vietnamese terminals and crane operator certification standardization progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
Very Large Gas Carrier Market
Maritime Equipment
North America Container Terminal Operations Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Asia-Pacific Maritime Satellite Communication Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Global Maritime Safety Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Latin America Offshore Support Vessels Market
Maritime Equipment
United States Maritime Information Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Hong Kong Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Ship Plate Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market