
 Ship-To-Shore (STS) Container Cranes Market | 2026-2036
Ship-To-Shore (STS) Container Cranes Market Size, Share, and Industry Trends Forecast 2026-2036
Ship-To-Shore (STS) Container Cranes Market Intelligence
Modular crane configurations with plug-in automation kits is expanding buyer flexibility across greenfield and retrofit port projects. Shanghai Zhenhua Heavy Industries Co., Ltd. (ZPMC) leverages its integrated steel fabrication and shipyard logistics to dominate ultra-large crane deliveries. Liebherr-International AG anchors European demand through specialized super post-panamax designs with advanced anti-sway systems. Konecranes differentiates via its software-integrated crane management platforms that extend equipment lifecycle value.
Ship-to-shore container cranes are rail-mounted portal structures designed to lift containers from vessel decks to terminal quays, typically spanning 30-70 meters with lifting capacities exceeding 65 tons under spreader. These systems employ trolley traverse mechanisms and hoist assemblies to maintain throughput exceeding 35 moves per hour at major terminals. Super post-panamax crane type commands the premium tier as vessel sizes exceed 24,000 TEU capacity. Electric and hybrid drive technology segments are capturing accelerated interest as ports face decarbonization mandates and volatile fuel cost structures. Deep-sea terminals represent the mature revenue base, while specialized terminals handling refrigerated and project cargo offer concentrated margin pools.
Federal Maritime Commission oversight in the United States shapes terminal operator procurement timelines through infrastructure investment review processes. European Union Green Deal emissions benchmarks and IMO carbon intensity indicators are forcing port authorities to specify hybrid or fully electric crane architectures in public tenders. Stakeholders must monitor evolving MEPC efficiency standards and regional port authority electrification mandates to align capital deployment with compliance timelines.
Market Dynamics
IMO 2023 carbon intensity regulations are compressing procurement timelines as port authorities face hard electrification deadlines. Terminal operators must now specify hybrid or fully electric crane architectures in public tenders, fundamentally reshaping vendor qualification criteria and capital allocation priorities across the sector.
Growth Catalysts
- EU Green Deal emissions benchmarks:European port authorities are mandating hybrid-electric crane specifications in tender documents, accelerating fleet replacement cycles at deep-sea terminals.
- Manufacturing supply chain diversification:Vietnam, Indonesia, and the Philippines are expanding automated terminal capacity to capture container volumes shifting from China.
- Plug-in automation kits:Modular crane configurations are expanding buyer flexibility across both greenfield port projects and brownfield retrofit installations.
Market Restraints
- Specialized steel supply concentration:Ultra-large crane fabrication depends on captive shipyard logistics and integrated steel supply chains concentrated in East Asian manufacturing clusters.
- High-voltage shore power infrastructure:Grid connection requirements for fully electric cranes demand substantial civil works and utility coordination that extends project timelines.
- Anti-sway system technical complexity:Advanced motion control systems for super post-panamax designs require specialized engineering expertise that limits vendor pool depth.
Strategic Opportunities
- Refrigerated cargo specialization:Specialized terminals handling reefer containers offer concentrated margin pools as cold chain logistics expand across Southeast Asian manufacturing hubs.
- Project cargo handling:Breakbulk and heavy-lift applications at secondary ports represent underpenetrated demand for customized crane configurations.
- Software-integrated lifecycle management:Crane management platforms that extend equipment service life are creating new recurring revenue streams for vendors.
Industry Challenges
- Automation engineering talent scarcity:Terminal operators face acute shortages of technicians capable of maintaining trolley traverse mechanisms and hoist assemblies in automated environments.
- Federal Maritime Commission review timelines:Infrastructure investment oversight in the United States shapes procurement schedules through extended approval processes for terminal expansions.
- Legacy system integration complexity:Retrofitting existing quay cranes with electrification packages requires coordination with terminal operating systems that were not designed for real-time power management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship-To-Shore (STS) Container Cranes Market |
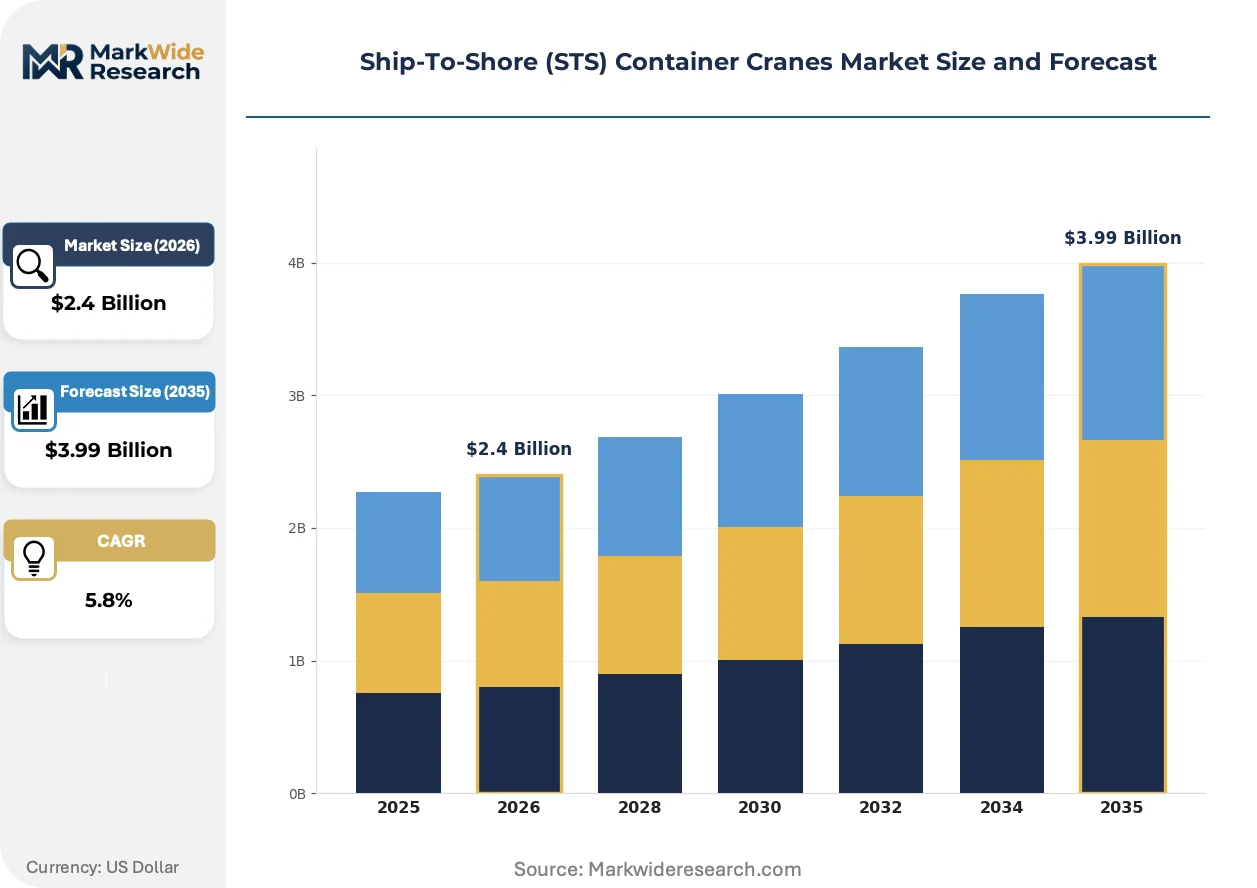
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Crane Type: Panamax, Post-Panamax, Super Post-Panamax, Rubber-Tyred Gantry, Automatic Stacking Drive Technology: Electric, Diesel-Electric, Hybrid, Hydraulic, Manual Port Operation: Deep-Sea Terminals, Inland Container Depots, River Ports, Specialized Terminals End User: Terminal Operators, Stevedores, Shipping Lines, Logistics Providers, Freight Forwarders |
| Companies Covered | Shanghai Zhenhua Heavy Industries Co., Ltd. (ZPMC), Liebherr-International AG, Sany Group, Konecranes, Doosan Corporation, Cargotec (Kalmar), PACECO CORP., Henan Weihua Heavy Machinery Co., Ltd., Hyundai Samho Heavy Industries Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship-To-Shore (STS) Container Cranes Market Strategic Shifts & Innovations
Electrification and digitalization are converging to redefine crane architecture, procurement models, and operational economics. Terminal operators now evaluate equipment through total-cost-of-ownership lenses that prioritize energy efficiency and predictive maintenance capabilities over upfront capital expenditure.
Digital twin technology is unifying physical crane operations with virtual simulation environments. Major terminal operators in Singapore and Rotterdam are deploying these systems to optimize maintenance scheduling and reduce unplanned downtime. This convergence is compressing the traditional separation between equipment procurement and lifecycle service contracts.
EU Green Deal emissions benchmarks are forcing explicit carbon accounting in port infrastructure tenders. Terminal operators must now document lifecycle emissions for crane equipment, including embedded carbon in steel fabrication and operational emissions under varying load profiles. Deep-sea terminals in Hamburg and Antwerp are responding by specifying fully electric architectures with regenerative braking systems.
Buyer concentration among global terminal operators is consolidating procurement leverage. Large port authorities in Dubai, Singapore, and Los Angeles are unbundling after-sales service from initial equipment contracts, creating competitive pressure on traditional full-service vendors. This shift is most visible in long-term maintenance agreements where operators now demand performance-based pricing tied to crane availability metrics.
Ship-To-Shore (STS) Container Cranes Market Segmentation
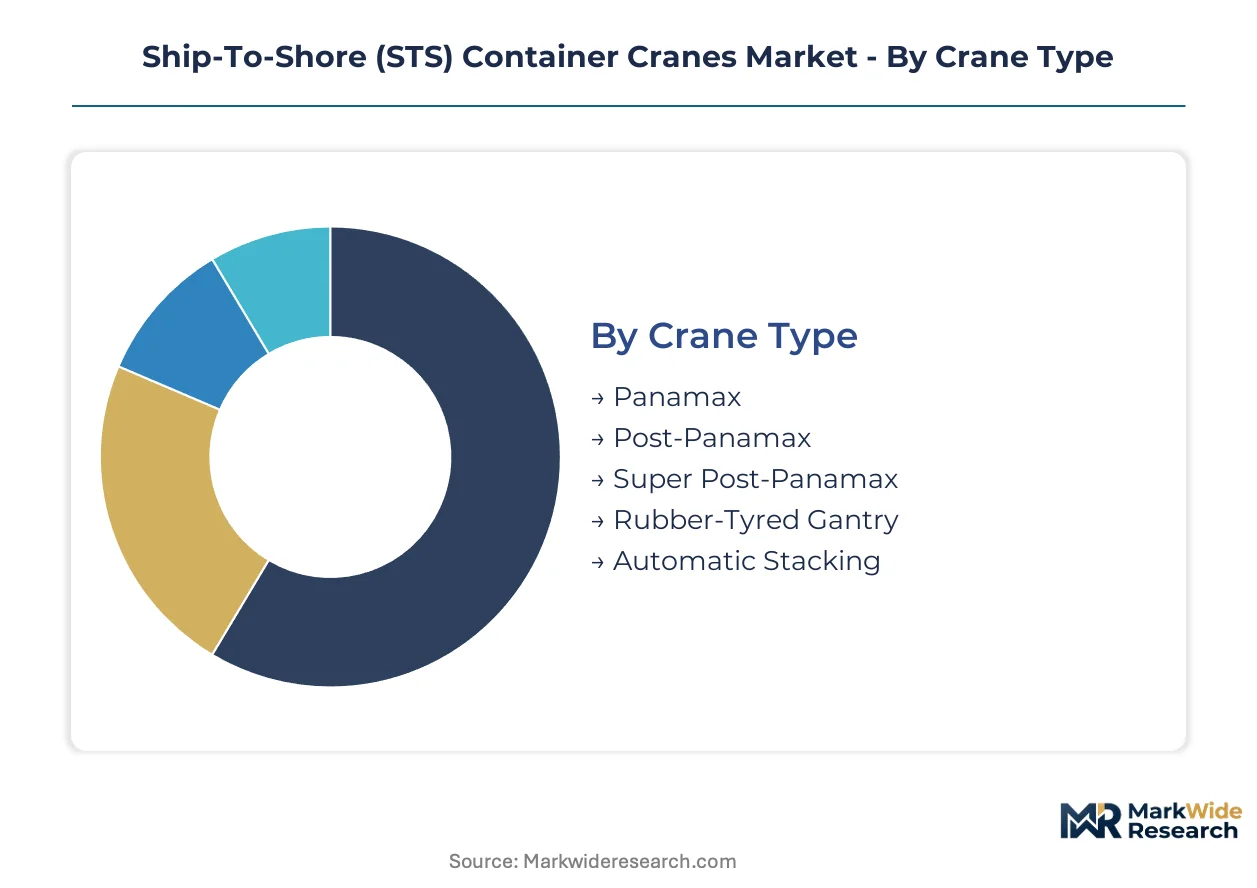
Segmentation in the STS container crane market reveals how procurement patterns diverge across vessel size classes, energy architectures, and terminal operational models. Crane type and drive technology decisions cascade through port infrastructure planning, determining electrification investment scope and automation integration depth.
Crane Type:
Standalone quay-side configurations dominate deep-water terminals, while embedded yard crane systems integrate with broader terminal automation platforms.
- Panamax:These cranes span up to 35 meters across vessel beams, serving feeder vessels and secondary port calls with lifting capacities around 40 tons. Demand concentrates in Vietnam and Indonesia as manufacturing supply chains diversify beyond China, driven by port authorities modernizing mid-sized terminals without full super post-panamax investment.
- Post-Panamax:Spanning 40-50 meters with 65-ton capacity under spreader, these units bridge legacy infrastructure and mega-vessel accommodation. Procurement timelines compress in the Philippines and Malaysia where IMO 2023 carbon intensity regulations force fleet replacement decisions at terminals handling 8,000-14,000 TEU vessels.
- Super Post-Panamax:Spanning 60-70 meters with dual-lift capability exceeding 100 tons, purpose-built for 24,000+ TEU vessels. ZPMC and Liebherr dominate deliveries through integrated steel fabrication and specialized anti-sway engineering.
- Rubber-Tyred Gantry:Mobile yard cranes operating without fixed rail infrastructure, offering deployment flexibility for temporary capacity expansion and greenfield sites with uncertain throughput trajectories.
- Automatic Stacking:Fully automated rail-mounted yard systems integrated with terminal operating software, eliminating cabin operators through laser positioning and collision avoidance systems.
Volume placements concentrate in Post-Panamax configurations; the faster expansion belongs to Super Post-Panamax as vessel size escalation continues.
Drive Technology:
Cost tier stratification separates mature hydraulic architectures from electrification premiums, with hybrid systems capturing procurement attention amid volatile fuel cost structures.
- Electric:Grid-connected systems with regenerative braking recover kinetic energy during lowering operations, reducing net power consumption. EU Green Deal emissions benchmarks in Hamburg and Antwerp mandate fully electric specifications for new terminal tenders.
- Diesel-Electric:Generator sets power electric motors without shore connection dependency, serving terminals lacking high-voltage grid infrastructure in Indonesian and Philippine secondary ports.
- Hybrid:Battery-buffered systems enabling peak shaving and zero-emission operation during vessel alongside periods. Singapore and Rotterdam terminal operators specify hybrid architectures to comply with IMO carbon intensity indicators while maintaining operational flexibility.
- Hydraulic:Legacy drive systems with high maintenance intensity and fluid leakage risks, concentrated in aging crane fleets at South American and African terminals with limited capital replacement budgets.
- Manual:Human-powered or mechanically assisted systems restricted to emergency operations and maintenance access, negligible in commercial container handling.
Procurement volume clusters in diesel-electric for infrastructure-constrained terminals; hybrid systems are climbing the fastest as electrification deadlines harden.
Port Operation:
Customer type differentiation separates capital-intensive deep-sea terminals from asset-light logistics providers seeking flexible handling arrangements.
- Deep-Sea Terminals:High-throughput facilities handling 2+ million TEU annually with dedicated quay lines and automated yard stacks. These terminals concentrate in Singapore, Dubai, and Los Angeles where global terminal operators unbundle after-sales service from equipment contracts.
- Inland Container Depots:Dry ports and intermodal transfer facilities connecting maritime terminals to hinterland distribution networks. Expansion accelerates in Vietnam and Thailand as manufacturing supply chains diversify beyond China.
- River Ports:Barge-handling facilities on inland waterways with draft limitations restricting vessel size to 1,500 TEU capacity. These operations favor Panamax and smaller crane configurations with modular automation retrofit potential.
- Specialized Terminals:Reefer-dedicated and project cargo facilities handling temperature-controlled containers and breakbulk lifts. Cold chain logistics expansion across Southeast Asian manufacturing hubs drives concentrated margin pools in this segment.
Revenue concentration remains in deep-sea terminals; specialized terminals handling refrigerated cargo are gaining share fastest as cold chain infrastructure proliferates.
End User:
Margin structure varies sharply between integrated terminal operators capturing equipment lifecycle value and fragmented freight forwarders purchasing handling services.
- Terminal Operators:Port authority and global terminal operating company entities owning quay infrastructure and crane assets. These buyers demand software-integrated crane management platforms extending equipment service life through predictive maintenance.
- Stevedores:Labor contractors providing vessel loading and unloading services, typically leasing crane capacity from terminal operators rather than owning equipment.
- Shipping Lines:Container carriers operating dedicated terminals or securing preferential berthing agreements, influencing crane specifications through vessel size deployment decisions.
- Logistics Providers:Third-party supply chain managers contracting terminal handling services, indirect crane demand through volume commitments rather than direct procurement.
- Freight Forwarders:Intermediaries consolidating cargo and arranging transport, minimal direct crane interaction except through negotiated handling rates at contracted terminals.
Procurement authority concentrates with terminal operators; shipping lines are expanding their fastest through dedicated terminal investments and long-term concession agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Vietnam and Indonesia are concentrating crane procurement as manufacturing supply chains relocate from China. These designated economic corridors offer tariff exemptions and accelerated customs processing that reduce terminal operator capital recovery periods.
China
Yangshan Deep Water Port in Shanghai is expanding automated terminal capacity to accommodate 24,000 TEU vessel calls. MIIT industrial equipment standards are mandating energy efficiency benchmarks for new crane installations at state-owned port operators. ZPMC's integrated steel fabrication facilities in Nantong anchor ultra-large crane production for export markets.
Vietnam
Cai Mep-Thi Vai deep-water terminals are procuring super post-panamax configurations as manufacturing supply chains diversify beyond China. The Ministry of Transport's port masterplan prioritizes electrification infrastructure for vessels at berth. Hai Phong's Lach Huyen International Gateway Terminal is deploying hybrid-drive cranes to meet IMO carbon intensity indicators.
Singapore
Tuas Mega Port automation programs are specifying software-integrated crane management platforms extending equipment lifecycle value. Maritime and Port Authority regulations mandate shore power availability for vessels at berth by 2025. PSA Singapore's terminal operating company is unbundling after-sales service contracts from initial equipment procurement.
Germany
Hamburg's Container Terminal Altenwerder is retrofitting existing quay cranes with fully electric architectures under EU Green Deal emissions benchmarks. The F-Gas Regulation is phasing out hydraulic drive systems in favor of regenerative braking technologies. Liebherr's specialized anti-sway engineering capabilities anchor European demand for super post-panamax designs.
United States
Los Angeles and Long Beach port complexes face Federal Maritime Commission oversight extending procurement timelines for terminal expansion projects. EPA emissions standards are accelerating diesel-electric and hybrid crane specifications at Pacific Northwest terminals. Georgia Ports Authority's Savannah expansion is procuring post-panamax configurations for 14,000 TEU vessel accommodation.
Ship-To-Shore (STS) Container Cranes Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across crane fabrication and automation integration. The market structure consolidates around integrated steel fabricators with captive shipyard logistics and specialized engineering houses with proprietary motion control systems. Three archetypes dominate: Asian heavy industrial conglomerates with backward integration into steel supply, European precision engineering specialists with advanced anti-sway IP, and automation-software vendors extending into equipment lifecycle services. Competitive moves center on geographic expansion into Southeast Asian mega-port developments and strategic partnerships for shore power infrastructure integration.
Among Asian fabricators, Shanghai Zhenhua Heavy Industries Co., Ltd. exemplifies the integrated conglomerate archetype through its Nantong manufacturing base. Liebherr-International AG occupies the European precision engineering tier with specialized super post-panamax capabilities. Konecranes represents the software-integrated service extension model, anchoring recurring revenue streams through crane management platforms.
| Leading Market Players |
|---|
| Shanghai Zhenhua Heavy Industries Co., Ltd. (ZPMC) |
| Liebherr-International AG |
| Sany Group |
| Konecranes |
| Doosan Corporation |
| Cargotec (Kalmar) |
| PACECO CORP. |
| Henan Weihua Heavy Machinery Co., Ltd. |
| Hyundai Samho Heavy Industries Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Global terminal operators concentrated in Singapore, Dubai, and Los Angeles command project-based contract structures that bundle equipment procurement with long-term service agreements, compressing margins for vendors lacking integrated lifecycle platforms. This buyer concentration forces pricing stratification across premium, standard, and economy tiers based on automation depth and electrification architecture.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as port authorities face IMO carbon intensity deadlines that compress tender-to-delivery windows. Three-tier pricing structure across premium, standard, and economy levels separates fully electric super post-panamax configurations with regenerative braking from diesel-electric hybrids and legacy hydraulic retrofits. Price differentiation hinges on automation integration depth and shore power compatibility certification. Pricing pressure stems from buyer unbundling of after-sales service contracts, with global terminal operators demanding performance-based maintenance pricing. Mid-tier regional port authorities in Vietnam and Indonesia exhibit highest price sensitivity due to constrained capital budgets, while mega-port operators in Singapore and Rotterdam prioritize total-cost-of-ownership over upfront expenditure.
Supply Chain Analysis
CE marking and ISO 3834 welding certification requirements gate entry for European and Middle Eastern tenders, filtering fabrication capacity toward qualified Asian heavy industrial conglomerates. Supply concentrates in China, South Korea, and Germany, with integrated steel fabrication and captive shipyard logistics anchoring ultra-large crane production. Raw material dependencies center on specialized high-strength steel plate, precision bearings for trolley traverse mechanisms, and high-voltage electrical components for drive systems. Single-source vulnerability runs through East Asian steel supply chains concentrated in Nantong and Ulsan manufacturing clusters. Distribution runs through direct vendor-to-terminal-operator contracting for greenfield projects, with aftermarket parts flowing through regional service hubs in Rotterdam, Singapore, and Los Angeles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with integrated steel fabrication and software-integrated service platforms, with IMO electrification mandates forcing capital-constrained regional fabricators toward exit or acquisition.
For Market Incumbents: Extend software-integrated lifecycle management capabilities to capture recurring revenue streams as global terminal operators unbundle after-sales service from initial equipment contracts. Deepen backward integration into high-strength steel supply to defend margin position against raw material volatility. Threat substitution from modular plug-in automation kits demands certification investment in shore power compatibility to maintain tender qualification. For New Entrants and Emerging Players: Capture project cargo handling opportunities at secondary ports in the Philippines and Indonesia where customized crane configurations face limited competition from established super post-panamax specialists. White-space exists in refrigerated cargo terminal electrification as cold chain logistics expand across Southeast Asian manufacturing hubs. Go-to-market leverage rests on partnerships with regional engineering firms possessing local civil works expertise for high-voltage grid coordination. For Investors and Strategic Acquirers: The window for entry favors automation-software vendors with crane management platforms that can extend into equipment lifecycle services. Long-term viability centers on vendors bridging the gap between fabrication and predictive maintenance capabilities. Acquisition target archetype: mid-tier European engineering houses with proprietary anti-sway IP but limited balance sheet for electrification R&D. Signal to watch: terminal operator consolidation in Vietnam and Indonesia triggering bundled procurement mandates that favor full-service vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Shore Power Infrastructure Partnership | Grid connection capabilities unlock EU Green Deal-compliant tender participation at Hamburg and Antwerp terminals. |
| Modular Automation Retrofit Program | Plug-in kits expand addressable market to brownfield terminals in Indonesia and Philippines facing IMO deadlines. |
| Reefer Terminal Specialization | Cold chain logistics expansion across Vietnam and Thailand creates concentrated margin pools in temperature-controlled handling. |
| Digital Twin Platform Development | Virtual simulation environments at Singapore and Rotterdam terminals compress maintenance scheduling and reduce unplanned downtime. |
| High-Strength Steel Backward Integration | Captive supply of specialized plate material defends fabrication margins against commodity volatility in East Asian clusters. |
Research Approach
Multi-period observation of vessel size deployment patterns, terminal automation adoption rates, and electrification infrastructure buildouts anchored the trend analysis, supplemented by interviews with port authority procurement directors, terminal operating company engineering heads, crane manufacturer sales executives, and aftermarket service managers. Secondary validation drew from IMO MEPC efficiency standard filings, EU Green Deal emissions benchmark documentation, Federal Maritime Commission infrastructure investment review records, and customs trade data on steel plate imports. Bottom-up equipment deployment tracking triangulated against top-down port capacity expansion announcements.
Input-output matrices mapped crane type, drive technology, and port operation segments across the projection horizon, with CAGRs derived from regression analysis of historical procurement cycles and forward-looking tender pipelines. Segmentation dimensions modeled included vessel size class accommodation, energy architecture compliance tier, terminal throughput scale, and regional regulatory framework stringency. Forecast inputs incorporated IMO carbon intensity indicator enforcement timelines and EU F-Gas Regulation phase-out schedules for hydraulic systems.
The model holds under stable regulatory enforcement trajectories and continued manufacturing supply chain diversification beyond China; deviation in electrification infrastructure buildout pace or steel supply disruption would shift equipment procurement timelines. Forecasts reflect assumptions regarding terminal operator consolidation patterns and vendor qualification criteria evolution. A model refresh is warranted upon material change in IMO MEPC efficiency standards or regional port authority electrification mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Middle East Offshore Support Vessels Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
United States Maritime Information Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Barge Transportation Market
Maritime Equipment
Europe Inland Water Freight Transport Market