
 Maritime Communication System Market | 2026-2036
Maritime Communication System Market Size, Share, and Industry Trends Forecast 2026-2036
Maritime Communication System Market Insights
Satellite service distribution is rewriting how maritime connectivity reaches vessels at sea. Inmarsat leverages its L-band constellation to sustain global coverage for merchant fleets operating beyond terrestrial range. KVH Industries anchors the recreational and commercial fishing segment through compact VSAT terminals. Iridium Communications competes in the polar regions where geostationary satellites cannot maintain line-of-sight.
A maritime communication system comprises transmitters, receivers, antennas, and network infrastructure enabling voice, data, and distress signaling between vessels and shore stations, typically operating across VHF (156-174 MHz), MF/HF (300 kHz-30 MHz), and satellite L/Ku/Ka-band frequencies to ensure continuous connectivity regardless of vessel position. Satellite communication terminals dominate value capture given their essential role in offshore operations and regulatory compliance, while IP-based networks represent the fastest-expanding technology layer as fleet operators digitize cargo monitoring and predictive maintenance. Terrestrial radio systems retain volume leadership in coastal navigation and port approaches where latency-sensitive collision avoidance demands localized transmission.
The International Maritime Organization's Global Maritime Distress and Safety System framework, enforced by national maritime authorities including the US Coast Guard and Japan's Maritime Bureau, mandates carriage requirements for DSC-equipped VHF and MF/HF radios, directly shaping equipment procurement cycles across the merchant fleet. The EU's Radio Equipment Directive and IEC 61097 standards further constrain market access to type-approved products, elevating compliance costs for new entrants. Stakeholders must monitor spectrum reallocation debates at the ITU World Radiocommunication Conferences, as maritime broadband frequencies face encroachment from terrestrial 5G and satellite mega-constellation filings.
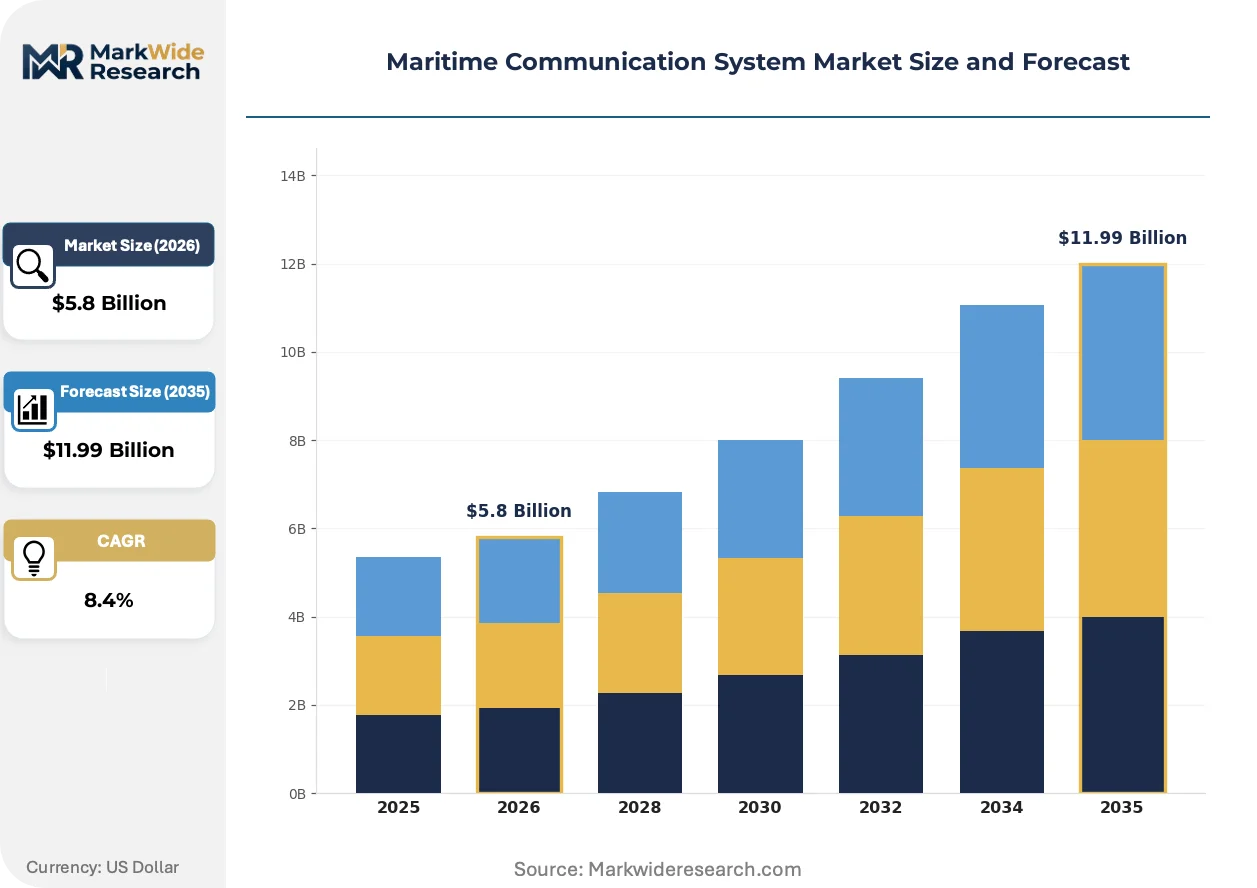
Market Dynamics
Satellite mega-constellation deployment is compressing bandwidth costs and forcing legacy VSAT providers to restructure service models around software-defined terminals. This orbital infrastructure expansion redistributes competitive advantage toward antenna manufacturers capable of multi-orbit interoperability.
Growth Catalysts
- IMO GMDSS modernization:The International Maritime Organization's updated Global Maritime Distress and Safety System framework mandates next-generation distress signaling equipment, forcing fleet-wide hardware refresh cycles across cargo and passenger vessels.
- Offshore energy logistics:North Sea oil and gas platform decommissioning programs and floating wind farm construction drive continuous broadband demand from Norway's specialized offshore vessel cluster.
- LEO constellation maturation:Low Earth orbit satellite networks are virtualizing traditional maritime connectivity architectures by enabling direct-to-vessel broadband without geostationary relay infrastructure.
Market Restraints
- RF component supply concentration:Gallium nitride power amplifier fabrication depends on a concentrated Taiwanese and South Korean supplier base, creating vulnerability to regional semiconductor export controls.
- Spectrum licensing friction:ITU World Radiocommunication Conference proceedings delay Ka-band maritime allocation approvals, freezing terminal certification timelines for multi-frequency capable hardware.
- Terrestrial 5G encroachment:Coastal cellular network densification threatens VHF and L-band service economics in port approaches and inland waterways where hybrid connectivity alternatives exist.
Strategic Opportunities
- Arctic route commercialization:Northern Sea Route ice-class vessel traffic creates addressable demand for Iridium and emerging polar-orbiting LEO services beyond geostationary coverage limits.
- Predictive maintenance integration:Convergence of VSAT terminals with engine telemetry and hull sensor networks enables equipment-as-a-service business models for commercial fishing operators.
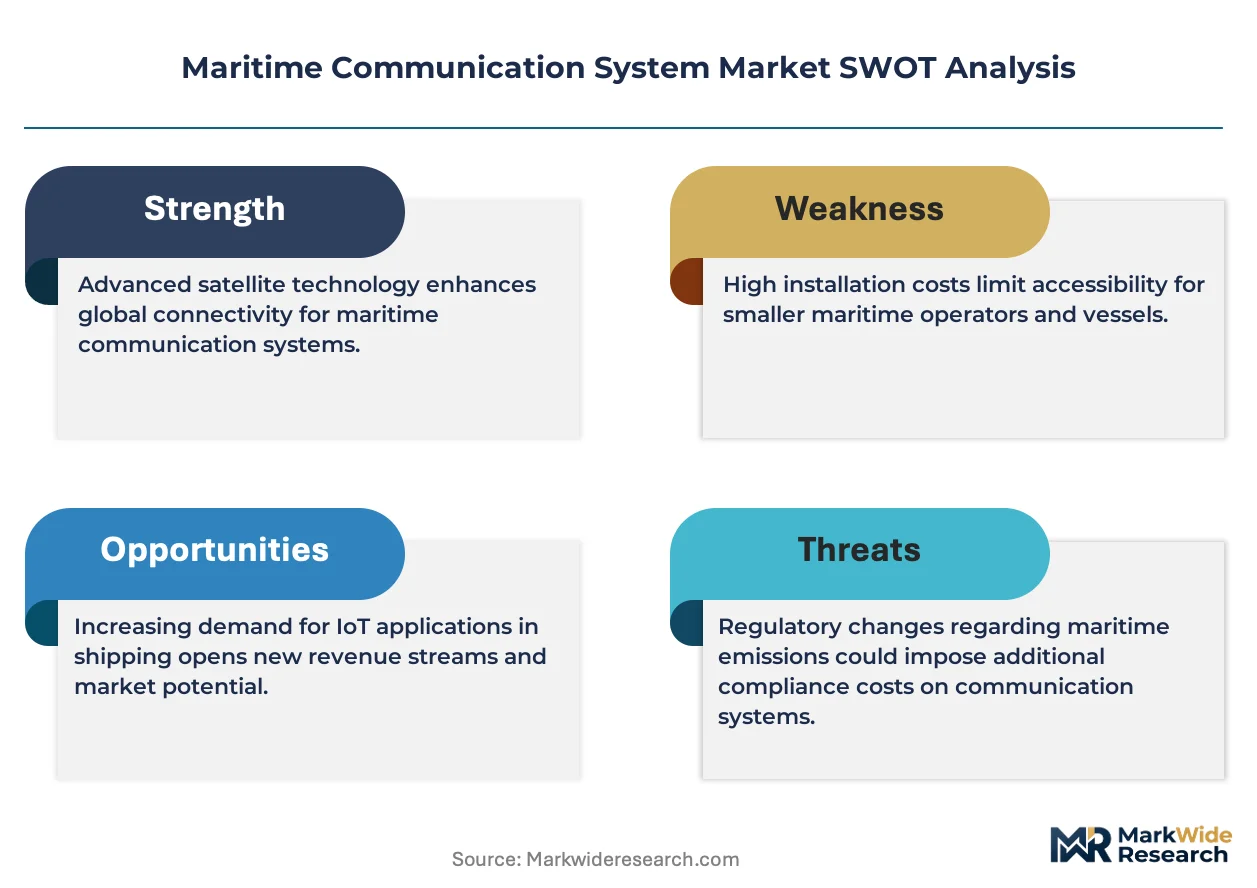
- EU Green Deal alignment:European Union emissions monitoring mandates for maritime transport create regulatory tailwinds for connectivity solutions supporting real-time fuel consumption optimization and route efficiency analytics.
Industry Challenges
- Embedded systems cybersecurity certification:IEC 62443 compliance for satellite terminal firmware requires specialized maritime-IT security expertise that shipyards and fleet operators struggle to source.
- Multi-orbit antenna integration complexity:Hybrid LEO-GEO-MEO terminal architectures demand RF engineering capabilities distinct from legacy parabolic dish specialization, compressing vendor development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maritime Communication System Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VHF Radios, Satellite Communication Terminals, AIS Transponders, MF/HF Radios, DSC Equipment Technology: Satellite Communication, Terrestrial Radio, IP-Based Networks, Digital Selective Calling, Broadband Communication Application: Navigation Assistance, Emergency Distress, Vessel Tracking, Weather Forecasting, Fleet Coordination End User: Merchant Shipping Operators, Offshore Platforms, Maritime Authorities, Cruise Operators, Fishing Enterprises |
| Companies Covered | Inmarsat, Iridium Communications, KVH Industries, Marlink, Speedcast, Cobham, Thales Group, Intellian Technologies, NSSL Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maritime Communication System Market Trends and Innovations
Software-defined radio architectures and flat-panel antenna designs are dissolving the hardware-software boundary in maritime connectivity, enabling vessel operators to reconfigure communication profiles without physical equipment swaps.
Flat-panel electronically steered arrays are virtualizing maritime antenna infrastructure by eliminating mechanical azimuth-elevation positioning systems. Offshore supply vessel operators in the North Sea are adopting these solid-state terminals to maintain connectivity during dynamic positioning operations. This virtualization compresses installation footprints and enables retrofitting of smaller deck spaces previously unsuitable for parabolic dishes.
The European Union's Radio Equipment Directive now mandates cybersecurity conformity assessments for satellite communication terminals, extending CE marking requirements beyond traditional electromagnetic compatibility. Equipment manufacturers must demonstrate secure boot capabilities and encrypted firmware update channels. Commercial fishing fleets operating in EU waters face compressed procurement timelines as older terminals lose market access.
Charter-party connectivity clauses are restructuring how shipping lines contract bandwidth, with cargo owners now specifying minimum data throughput requirements in voyage agreements. Container lines serving Asia-Europe trades are unbundling communication services from vessel management contracts. This shift concentrates purchasing power with beneficial cargo owners and forces terminal providers toward direct commercial relationships with commodity traders.
Maritime Communication System Market Segmentation
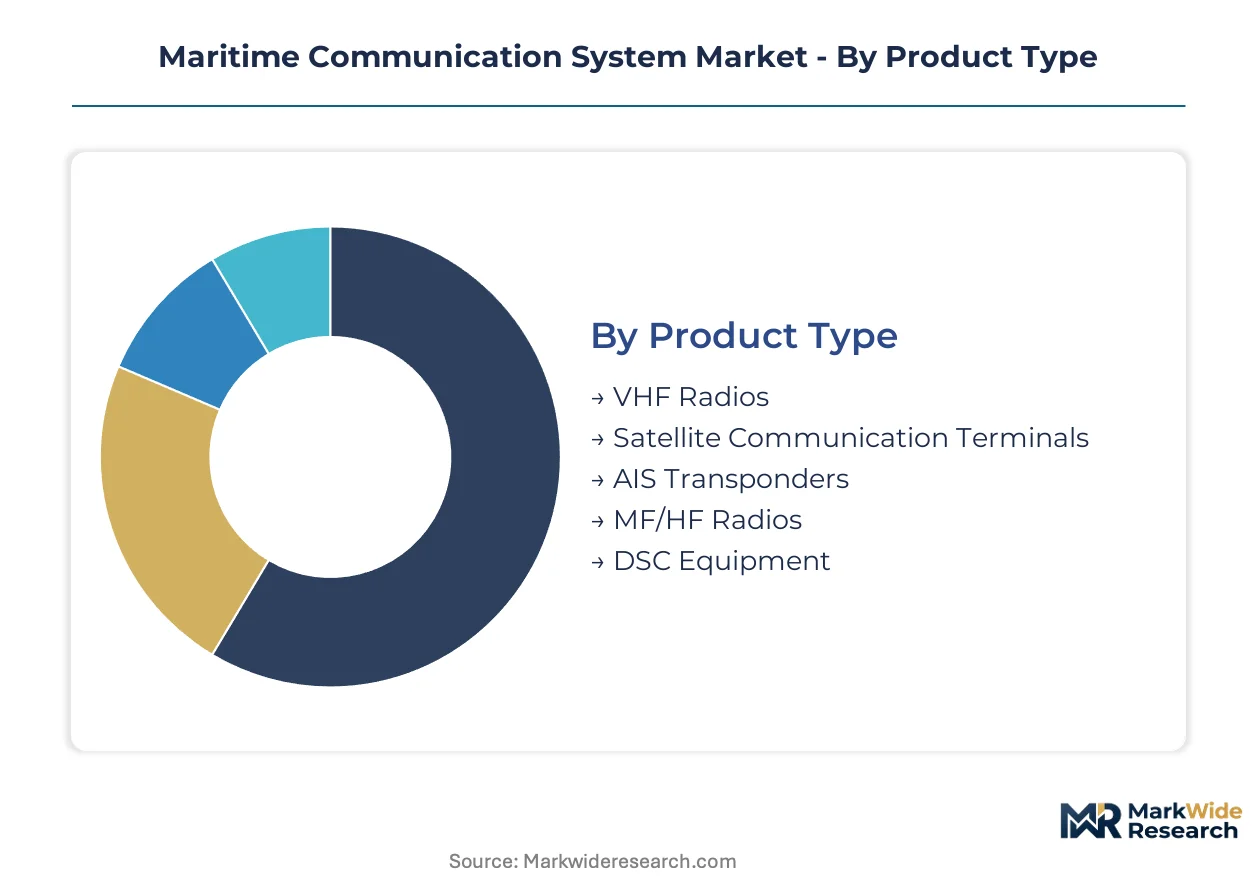
Maritime communication systems fragment across multiple technical and operational dimensions, with equipment specifications varying sharply between coastal fishing fleets and deep-sea merchant vessels. Understanding these segment boundaries clarifies where satellite infrastructure investments concentrate versus where legacy radio systems retain procurement priority.
Product Type:
Mature distress-signaling equipment coexists with emerging broadband terminals across fleet modernization cycles.
- VHF Radios:Very High Frequency transceivers operating between 156-174 MHz remain mandatory for short-range ship-to-ship and ship-to-shore voice communication. Norwegian coastal fishing fleets and Baltic Sea ferry operators sustain replacement demand as IEC 61097-3 standards enforce DSC integration for collision avoidance in congested waterways.
- Satellite Communication Terminals:L-band, Ku-band, and emerging flat-panel VSAT systems enable broadband data transmission beyond terrestrial range. North Sea offshore supply vessels drive adoption of multi-orbit capable terminals to maintain connectivity during dynamic positioning operations near oil platforms and floating wind installations.
- AIS Transponders:Automatic Identification System equipment broadcasts vessel position, course, and identity to shore stations and nearby ships.
- MF/HF Radios:Medium and High Frequency systems cover 300 kHz-30 MHz for long-range distress signaling and ocean-area communications where satellite coverage proves uneconomical.
- DSC Equipment:Digital Selective Calling controllers automate distress alert transmission across VHF and MF/HF bands per IMO GMDSS carriage requirements.
VHF Radios retain volume leadership across coastal fleets; Satellite Communication Terminals hold the steepest expansion curve as offshore digitization accelerates.
Technology:
Cost stratification separates legacy hardware from software-defined architectures transforming maritime connectivity economics.
- Satellite Communication:Geostationary, MEO, and LEO constellation services deliver global broadband coverage independent of terrestrial infrastructure. Arctic route commercialization creates addressable demand for Iridium and emerging polar-orbiting networks beyond geostationary line-of-sight limits.
- Terrestrial Radio:VHF and MF/HF ground-based transmission systems provide low-latency coastal navigation support.
- IP-Based Networks:Internet Protocol architectures virtualize traditional circuit-switched maritime communications, enabling voice-over-IP and encrypted data transmission through satellite backhaul.
- Digital Selective Calling:Automated distress signaling protocol embedded within VHF and MF/HF radios per SOLAS convention mandates.
- Broadband Communication:High-throughput satellite services and coastal 5G integration support video surveillance, telemedicine, and crew welfare applications.
Terrestrial Radio dominates installed base economics; IP-Based Networks are climbing the fastest as fleet operators digitize cargo monitoring and predictive maintenance workflows.
Application:
Customer type dictates whether regulatory compliance or operational efficiency drives procurement specifications.
- Navigation Assistance:Position reporting, route optimization, and pilot coordination systems reduce grounding incidents in confined waters.
- Emergency Distress:GMDSS-mandated alerting and search-and-rescue coordination functions represent non-discretionary equipment categories.
- Vessel Tracking:Real-time position monitoring supports supply chain visibility and sanctions compliance for commodity traders.
- Weather Forecasting:Meteorological data reception enables route optimization and severe weather avoidance.
- Fleet Coordination:Inter-vessel communication and shore-side logistics synchronization improve port turnaround times.
Emergency Distress anchors regulatory-mandated spending; Fleet Coordination is expanding most quickly as charter-party connectivity clauses restructure commercial shipping contracts.
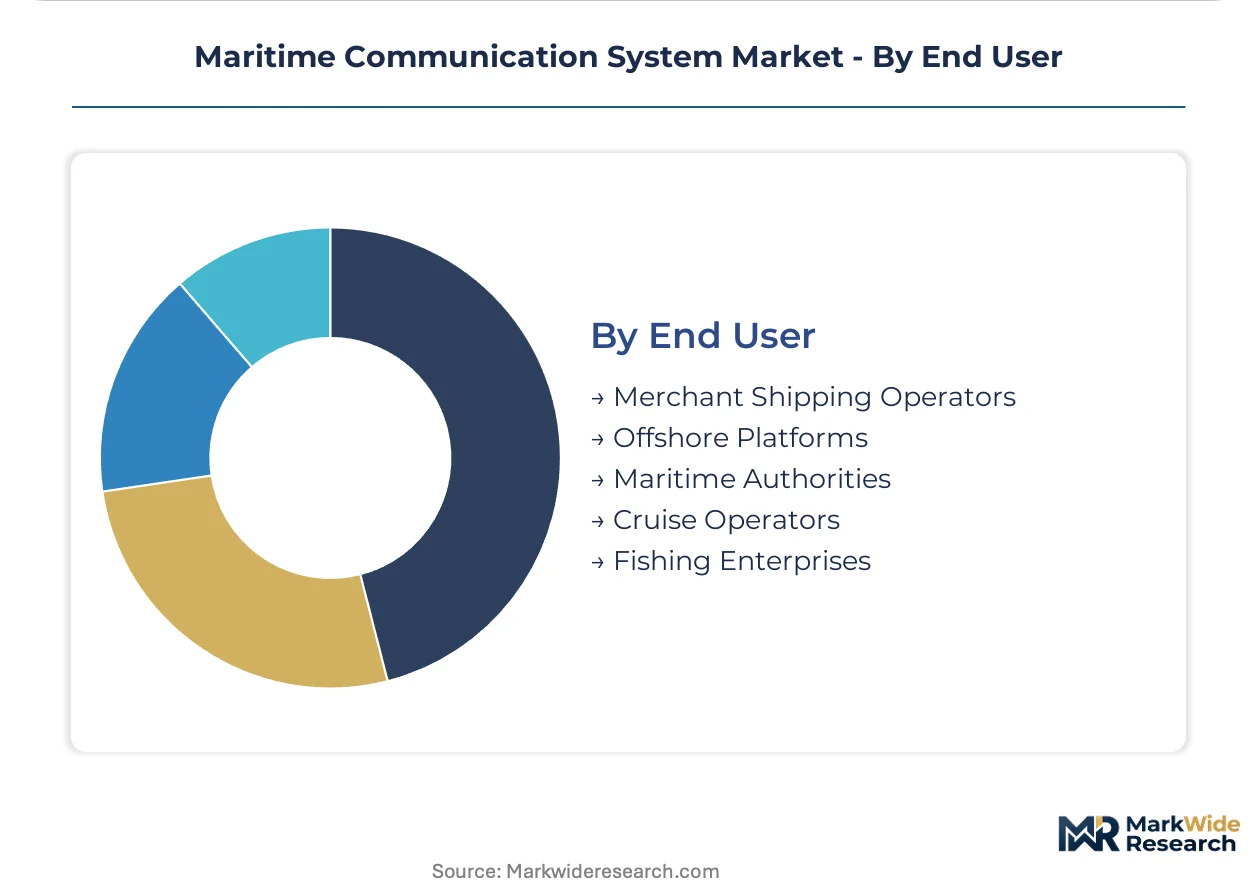
End User:
Volume concentration sits with merchant fleets while margin capture favors specialized offshore operators.
- Merchant Shipping Operators:Container lines, bulk carriers, and tanker fleets constitute the largest equipment procurement segment. Asia-Europe trade lane operators face compressed procurement timelines as EU Radio Equipment Directive cybersecurity mandates disqualify legacy terminals from CE marking eligibility.
- Offshore Platforms:Oil and gas production facilities and emerging floating wind farms demand continuous high-bandwidth connectivity. North Sea decommissioning programs and Norwegian floating offshore wind construction sustain specialized vessel communication requirements distinct from merchant fleet specifications.
- Maritime Authorities:Coast guard, port state control, and search-and-rescue organizations operate dedicated communication infrastructure.
- Cruise Operators:Passenger vessel fleets prioritize crew welfare and passenger broadband over minimum regulatory compliance.
- Fishing Enterprises:Commercial fishing fleets balance cost-sensitive VHF installations with emerging satellite monitoring mandates for catch documentation.
Merchant Shipping Operators retain volume leadership; Offshore Platforms hold the steepest expansion curve as floating wind infrastructure scales beyond oil and gas decommissioning cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Maasvlakte port complex anchors European maritime connectivity demand through its automated container handling systems and vessel traffic management infrastructure.
United States
Container traffic through the Ports of Los Angeles and Long Beach drives VSAT terminal procurement for cargo visibility and emissions monitoring compliance. The US Coast Guard enforces GMDSS carriage requirements through its Commercial Regulations Standards program. Gulf Coast offshore supply bases in Louisiana sustain specialized communication equipment demand for oil platform service vessels.
Norway
North Sea floating offshore wind construction and oil platform decommissioning programs generate continuous broadband connectivity requirements from specialized vessel operators. The Norwegian Maritime Authority implements IMO GMDSS modernization through its national seaworthiness inspection regime. Bergen and Stavanger host Europe's densest cluster of offshore vessel communication system integrators serving energy logistics operators.
China
Shanghai Yangshan automated port operations and expanding coast guard fleet modernization sustain domestic equipment procurement volumes. MIIT type-approval requirements and GB standards constrain market access for foreign satellite terminal manufacturers. Ningbo-Zhoushan port's vessel traffic service system represents the largest coastal AIS infrastructure deployment in the Asia-Pacific region.
Japan
Tokyo Bay vessel traffic congestion and strait navigation safety requirements sustain coastal VHF and MF/HF radio replacement cycles. The Japan Maritime Bureau enforces SOLAS convention mandates through its ship inspection organization certification system. Yokohama and Kobe port authorities are piloting integrated port community systems linking vessel communication terminals with customs and logistics platforms.
Singapore
The Port of Singapore's vessel traffic information system and bunkering operations support high-frequency communication equipment turnover in Southeast Asian shipping lanes. The Maritime and Port Authority mandates AIS carriage for all vessels exceeding 300 gross tonnage through its port state control regime. Tuas mega-port construction is driving next-generation terminal communication infrastructure investment for automated vessel berthing coordination.
Maritime Communication System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in antenna and RF module fabrication. The vendor structure concentrates around satellite service operators with orbital infrastructure assets and hardware manufacturers with maritime certification expertise. Three archetypes dominate: constellation operators bundling bandwidth with terminal leases, antenna specialists supplying multi-orbit capable hardware, and systems integrators managing fleet-wide communication portfolios. Competitive dynamics center on strategic partnerships linking constellation access with installation service networks, and portfolio diversification into cybersecurity-certified terminal firmware.
Within the constellation operator tier, Inmarsat and Iridium Communications exemplify vertically integrated service models spanning orbital assets through vessel-mounted terminals. Among antenna hardware specialists, Intellian Technologies occupies a position representing flat-panel and parabolic dish specialization for commercial fleet retrofit programs. Thales Group sits within the defense-industrial segment, anchoring dual-use communication system supply for coast guard and naval vessel programs where cybersecurity certification requirements exceed commercial standards.
| Leading Market Players |
|---|
| Inmarsat |
| Iridium Communications |
| KVH Industries |
| Marlink |
| Speedcast |
| Cobham |
| Thales Group |
| Intellian Technologies |
| NSSL Global |
| Others |
Pricing and Supply Chain Analysis
Asia-Europe container lane freight cost volatility compresses terminal procurement budgets while concentrating purchasing power among fleet operators with multi-vessel deployment scales, forcing hardware vendors to stratify pricing across certification-grade tiers and volume-commitment brackets.
Pricing Analysis
Volume-discount tiering structures separate IEC 62443 cybersecurity-certified terminals from baseline GMDSS-compliant equipment, with offshore supply vessel operators absorbing premium pricing for multi-orbit flat-panel arrays while coastal fishing fleets prioritize economy-tier VHF installations. Price differentiation hinges on certification grade and after-sales service bundling, with EU Radio Equipment Directive compliance adding substantial cost premiums. Cost compression in the standard tier intensifies as Taiwanese RF component suppliers expand gallium nitride amplifier fabrication capacity. Coastal fishing enterprises exhibit highest price sensitivity; North Sea offshore operators demonstrate lowest sensitivity given operational continuity requirements.
Supply Chain Analysis
Export-control regimes targeting gallium nitride semiconductor technology constrain power amplifier flows from Taiwanese and South Korean fabrication facilities to Chinese terminal assembly operations. Manufacturing concentrates in China, South Korea, and Taiwan for RF components, with Norway and Germany hosting specialized antenna integration facilities. Raw material dependencies include rare earth elements for antenna substrates, high-purity gallium for amplifiers, and specialized marine-grade aluminum alloys. Single-source vulnerability in Taiwanese GaN foundry capacity presents structural risk. Distribution runs through constellation operator-direct fleet contracts and maritime systems integrators serving regional vessel clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maritime connectivity is shifting toward platform-economics structures as software-defined terminals enable service virtualization, with flat-panel antenna interoperability creating ecosystem lock-in effects analogous to mobile operating systems.
For Market Incumbents: Harden terminal firmware security architectures against IEC 62443 certification requirements before EU market access deadlines eliminate non-compliant legacy inventory. Deepen backward integration into gallium nitride amplifier supply through captive offtake agreements with Taiwanese foundries, insulating against export-control disruption. Consolidate installation service networks in Norway's offshore vessel cluster to defend against emerging LEO constellation entrants.
For New Entrants and Emerging Players: Arctic route vessel traffic above 70°N latitude represents underpenetrated addressable demand beyond geostationary coverage limits, where Iridium's polar-orbiting architecture has not fully saturated ice-class shipping requirements. Commercial fishing fleets in Southeast Asian waters face compressed procurement timelines as catch-documentation satellite mandates expand, creating white-space for cost-optimized L-band terminals. Pursue direct commercial relationships with commodity traders specifying charter-party connectivity clauses, bypassing established vessel management company procurement channels.
For Investors and Strategic Acquirers: Antenna hardware specialists with multi-orbit RF engineering capabilities and maritime certification expertise represent the most defensible acquisition target archetype, given hybrid LEO-GEO-MEO terminal complexity compressing vendor development timelines. Long-term viability favors constellation-agnostic hardware platforms over vertically integrated service bundling as orbital infrastructure commoditizes. Watch for ITU World Radiocommunication Conference Ka-band allocation rulings as inflection indicators for multi-frequency terminal certification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Orbit Terminal Certification | IEC 61097 type-approval for hybrid LEO-GEO architectures unlocks North Sea offshore vessel procurement. |
| Cybersecurity Firmware Hardening | EU Radio Equipment Directive secure boot capabilities extend CE marking eligibility for satellite terminals. |
| Arctic Route Service Deployment | Polar-orbiting LEO coverage beyond geostationary limits captures ice-class vessel traffic growth. |
| Software-Defined Radio Integration | Reconfigurable communication profiles eliminate physical equipment swaps for fleet operators. |
| Charter-Party Direct Contracting | Bypassing vessel management companies concentrates purchasing power with beneficial cargo owners. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations managers, satellite terminal procurement officers, maritime systems integrators, and regulatory compliance specialists at classification societies, then refined through secondary validation against IMO GMDSS carriage requirement filings, EU Radio Equipment Directive implementation guidance, ITU World Radiocommunication Conference proceedings, and Norwegian Maritime Authority inspection protocols. Bottom-up vessel fleet equipment counts triangulated with top-down satellite service provider revenue disclosures.
Demand-supply-balance framing across the analysis window modeled equipment procurement cycles against orbital constellation capacity expansion, with segmentation across product type, technology layer, application function, and end-user category. CAGRs were derived from equipment replacement timelines tied to SOLAS convention enforcement phases and offshore energy logistics expansion curves. Forecast inputs incorporated North Sea floating wind construction pipelines and Arctic route ice-class vessel registration trends.
Practitioners should monitor ITU spectrum allocation proceedings, Taiwanese semiconductor export-control rulings, and EU cybersecurity mandate enforcement intensity for early signals requiring forecast reassessment. Material shifts in Ka-band maritime licensing timelines or gallium nitride foundry capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
Offshore Support Vessel Service Market
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
Passenger Ferries Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market
Maritime Equipment
Ship Plate Market
Maritime Equipment
Ship Galley Equipment Market
Maritime Equipment
Europe Offshore Support Vessels Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Ship-To-Shore (STS) Container Cranes Market