
 Marine Lubrication System Market | 2026-2036
Marine Lubrication System Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Lubrication System Market Analytics
The capital-intensity divergence between integrated oil majors and regional blenders is rotating competitive dynamics across marine lubrication supply. Shell plc leverages its global bunkering network to sustain volume leadership in high-viscosity engine oils for two-stroke marine engines. TotalEnergies SE anchors its position through dedicated marine laboratories in Rotterdam and Singapore that formulate cylinder oils for low-sulfur fuel compatibility. BP plc competes by extending its Castrol Marine brand through port-based technical service teams that control fleet operator relationships in Mediterranean and Asian hubs.
Marine lubrication systems encompass the complete infrastructure for storing, transferring, filtering, and injecting lubricants into propulsion engines, auxiliary machinery, and deck equipment aboard seagoing vessels. These systems typically operate with oil conditioning temperatures between 40°C and 60°C and incorporate centrifugal separators achieving purification efficiencies down to 0.5% water content to prevent bearing corrosion and catalytic fines damage. Engine oil formulations dominate product value pools due to their specialized alkaline additive packages neutralizing sulfuric acid from residual fuel combustion, while hydraulic fluids for steering gear and deck cranes represent the fastest-growing category as vessel automation intensifies. Cargo ships generate the largest application volume, though yacht segments command premium pricing through superyacht owners demanding synthetic ester-based products with extended drain intervals.
The International Maritime Organization enforces MARPOL Annex VI sulfur caps that mandate lubricant reformulation for scrubber-fitted and LNG-fueled vessels, while the EU Green Deal's FuelEU Maritime initiative progressively tightens greenhouse-garbon intensity benchmarks affecting lubricant lifecycle assessments. Classification societies including DNV and Lloyd's Register now incorporate lubrication system monitoring within their predictive maintenance notations, creating compliance-linked demand for sensor-integrated oil circulation units. Stakeholders must monitor how ammonia and methanol engine trials alter base oil compatibility requirements and filter specifications before committing to long-term supply contracts or system redesigns.
Market Dynamics
Container fleet operators are accelerating lubrication system upgrades as IMO 2020 sulfur caps force compatibility between cylinder oil formulations and scrubber-fitted or LNG-fueled propulsion architectures, compressing procurement cycles for high-alkaline additive packages.
Growth Catalysts
- FuelEU Maritime initiative:The EU Green Deal's progressive greenhouse-gas intensity benchmarks are forcing lifecycle assessments of lubricant formulations, driving demand for synthetic ester-based products with extended drain intervals in European-flagged vessels.
- Container fleet expansion:Major shipping lines operating through Singapore, Rotterdam, and Shanghai are retrofitting oil circulation units with sensor-integrated monitoring to meet classification society predictive maintenance notations.
- Low-sulfur fuel compatibility:Specialized alkaline additive packages neutralizing sulfuric acid from residual fuel combustion are becoming mandatory as MARPOL Annex VI enforcement tightens in Mediterranean and Asian bunkering hubs.
Market Restraints
- Base oil supply concentration:API Group II and Group III base stock production clusters in the US Gulf Coast and Middle East, exposing blenders to freight cost volatility and geopolitical disruption in Strait of Hormuz transit routes.
- Additive package cost structure:Magnesium and calcium detergent precursors face mining supply constraints from Chinese and Turkish extraction operations, compressing margins for mid-tier lubricant compounders.
- Scrubber washwater treatment:Open-loop exhaust gas cleaning systems face port state control bans in California, Germany, and China, creating regulatory friction that delays lubricant formulation standardization for dual-fuel vessels.
Strategic Opportunities
- Ammonia engine trials:MAN Energy Solutions and WinGD testbed programs in Denmark and Switzerland are revealing base oil incompatibility with ammonia combustion byproducts, opening formulation partnerships for polar lubricant chemistries.
- Superyacht synthetic demand:Monaco and Fort Lauderdale berth operators are specifying polyol ester hydraulic fluids for steering gear and deck cranes, commanding 40-60% price premiums over mineral-based alternatives.
- Port-based technical service:Mediterranean and Asian hub operators are unbundling after-sales support from product supply, creating standalone advisory revenue streams for viscosity-grade optimization and drain interval extension.
Industry Challenges
- Tribology specialization gap:Marine engineering programs at Southampton, Delft, and Shanghai Maritime University produce insufficient graduates versed in elastohydrodynamic lubrication theory for two-stroke crosshead bearing design.
- Classification society coordination:DNV, Lloyd's Register, and Bureau Veritas maintain divergent notations for oil conditioning temperature ranges and centrifugal separator efficiency thresholds, forcing redundant system certification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Lubrication System Market |
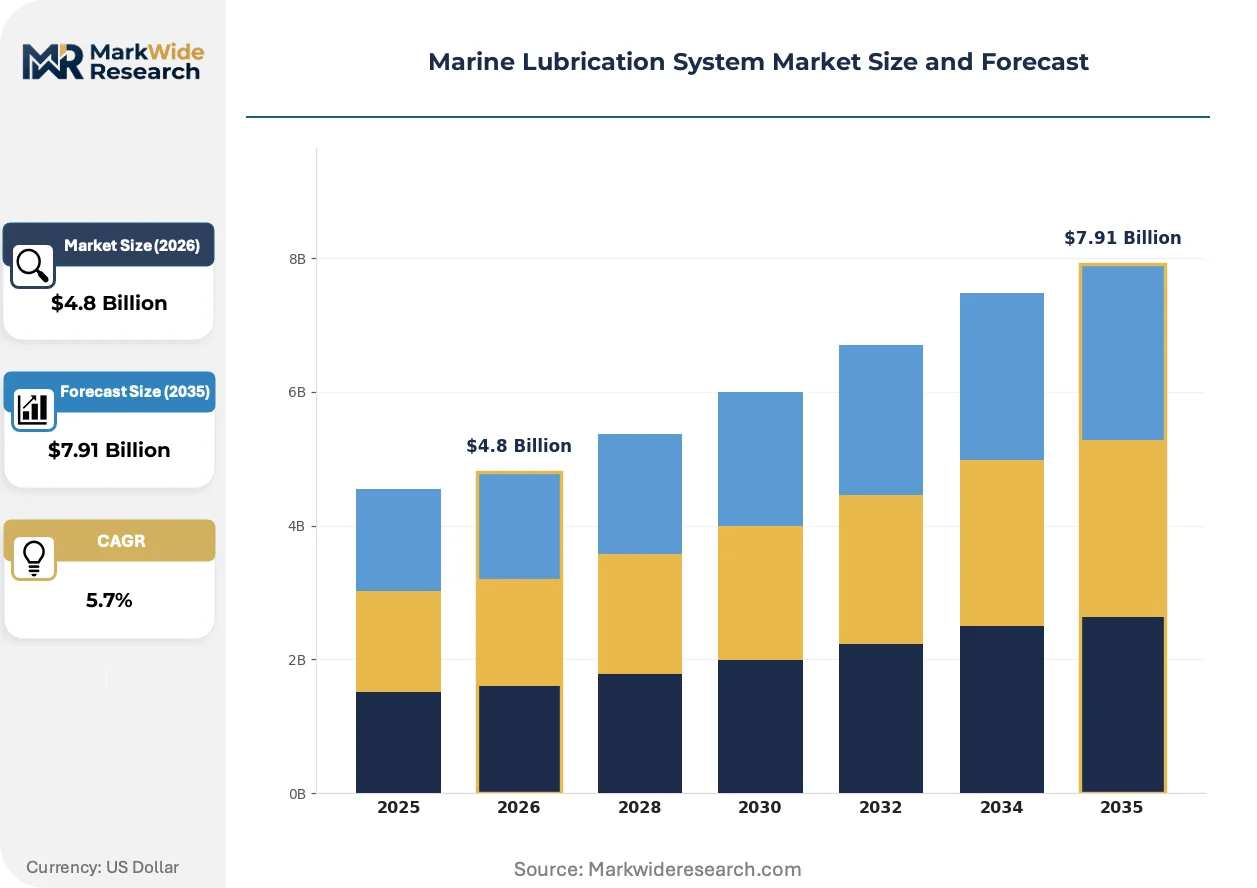
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Hydraulic Fluid, Grease, Detergent Application: Commercial Vessels, Fishing Boats, Yachts, Cargo Ships Delivery Mode: Bulk Delivery, Drums, Pails, Sacks End User: Shipyards, Fleet Operators, Maintenance Providers, Ship Owners |
| Companies Covered | Shell plc, Exxon Mobil Corporation, Chevron Corporation, TotalEnergies SE, BP plc, LUKOIL, China Petroleum & Chemical Corporation, Petronas, ENEOS Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Lubrication System Market Evolving Landscape
Digital oil condition monitoring and synthetic formulation chemistry are converging to redefine how vessel operators manage lubricant lifecycle costs and predictive maintenance protocols across deep-sea and coastal fleets.
Sensor-integrated oil circulation units with real-time particle counting and moisture detection are supplanting scheduled laboratory analysis for main engine crankcase systems. Container lines operating Asia-Europe routes are adopting these units at retrofit rates exceeding 30% of fleet tonnage annually. The technology is compressing lubricant consumption forecasting from quarterly bulk orders to algorithm-driven just-in-time bunkering.
REACH Annex XVII restrictions on zinc dialkyldithiophosphate (ZDDP) content are compelling reformulation of anti-wear hydraulic fluids for deck machinery. European blenders are substituting ashless phosphorus-sulfur compounds that meet biodegradability thresholds for accidental marine discharge. Offshore supply vessels operating North Sea platforms face the steepest compliance costs due to combined EU and Norwegian regulatory overlap.
Fleet operators are consolidating lubricant procurement through integrated technical management contracts that bundle product supply with condition monitoring and used oil analysis. Third-party ship managers based in Singapore and Hamburg are displacing direct supplier relationships that dominated the 2010s. Greek and German container and tanker owners have been earliest adopters of this bundled service model.
Marine Lubrication System Market Segmentation
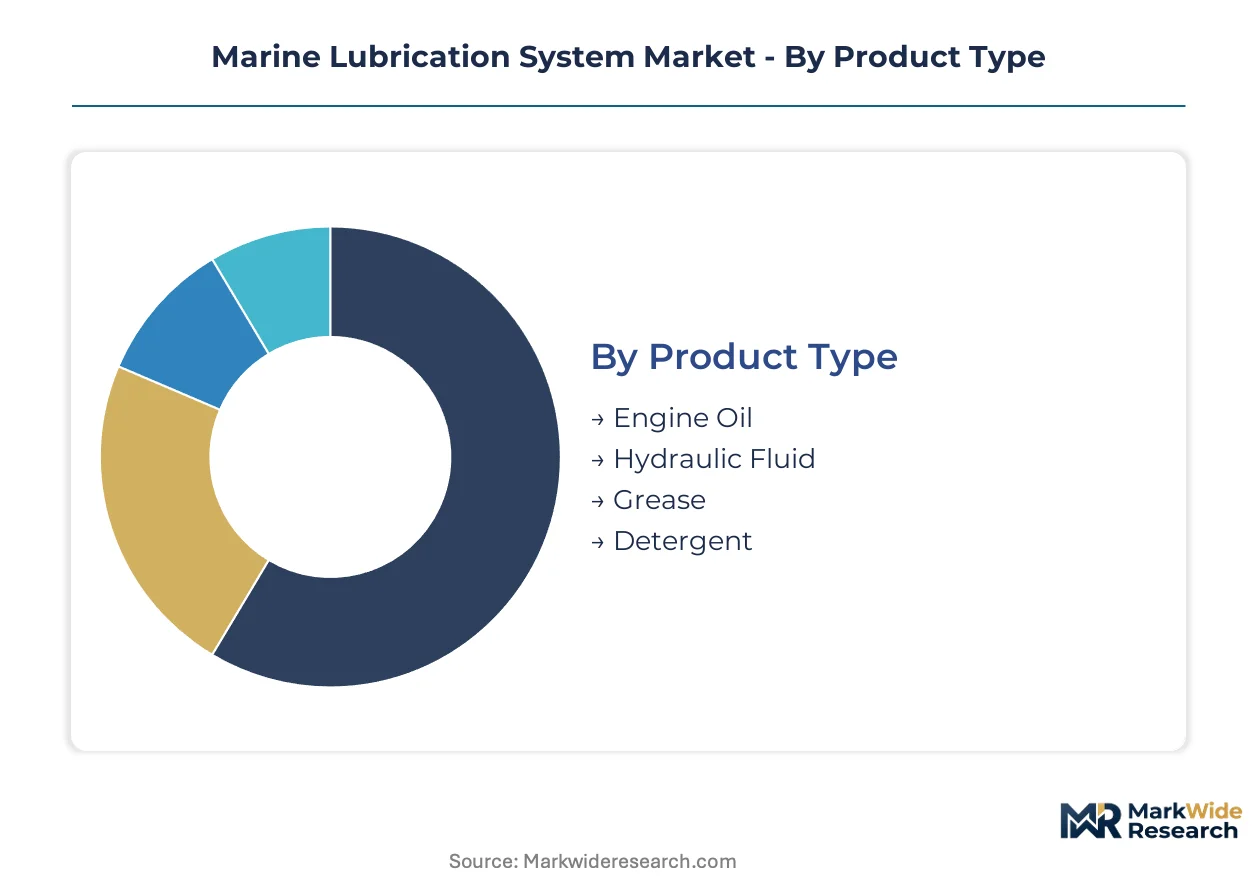
Marine lubrication system segmentation reveals how value pools concentrate in high-specification formulations versus commodity supply infrastructure. Product chemistry, vessel architecture, and procurement channel each govern distinct margin structures and competitive entry barriers.
Product Type:
Margin pools concentrate in alkaline additive packages where formulation chemistry determines compatibility with residual fuel sulfur content and engine metallurgy.
- Engine Oil:Cylinder and crankcase formulations carry specialized detergent packages neutralizing sulfuric acid from heavy fuel oil combustion. Container lines operating scrubber-fitted two-stroke engines in Singapore and Rotterdam anchor demand for high-BN (base number) variants.
- Hydraulic Fluid:Steering gear and deck crane systems require anti-wear chemistries meeting ISO 6743 specifications. REACH Annex XVII restrictions on zinc dialkyldithiophosphate are forcing European-flagged vessels toward ashless phosphorus-sulfur alternatives.
- Grease:Calcium sulfonate and lithium complex thickeners serve winch bearings and propeller shaft seals.
- Detergent:Fuel system cleaning additives prevent injector nozzle coking in medium-speed auxiliary engines.
Engine Oil holds installed capacity. Hydraulic Fluid is rotating up the share rankings.
Application:
Volume distribution tracks fleet composition, with premium pricing concentrated where vessel automation and superyacht specifications command synthetic ester chemistry.
- Cargo Ships:Bulk carriers and tankers consume the largest lubricant volumes through main engine crankcase and crosshead bearing systems. Classification society predictive maintenance notations from DNV and Lloyd's Register are mandating sensor-integrated oil conditioning units on newbuilds.
- Yachts:Superyacht segments in Monaco and Fort Lauderdale specify polyol ester hydraulic fluids with extended drain intervals. Berth operators are unbundling technical advisory from product supply, creating standalone service revenue streams.
- Commercial Vessels:Ferries and offshore supply vessels face combined EU and Norwegian regulatory overlap on biodegradability thresholds.
- Fishing Boats:Smaller fleet operators in Mediterranean and Asian coastal zones rely on mineral-based formulations with shorter service intervals.
Cargo Ships dominate tonnage throughput. Yachts command the steepest price premiums per liter.
Delivery Mode:
Supply chain configuration separates just-in-time bunkering hubs from scheduled maintenance port calls.
- Bulk Delivery:Pipeline and barge transfers serve Singapore, Rotterdam, and Fujairah bunkering terminals. Algorithm-driven consumption forecasting is compressing procurement cycles from quarterly to voyage-based replenishment.
- Drums:200-liter steel containers support shipyard newbuild commissioning and major overhauls.
- Pails:20-liter units serve maintenance providers performing deck machinery servicing.
- Sacks:Grease cartridges in 400g and 5kg formats supply manual lubrication points.
Bulk Delivery captures hub economics. Drums retain shipyard channel control.
End User:
Procurement authority is consolidating through third-party technical managers displacing direct supplier relationships.
- Fleet Operators:Container lines and tanker owners are bundling lubricant supply with condition monitoring and used oil analysis. Greek and German owners have adopted integrated technical management contracts fastest.
- Shipyards:Newbuild specifications determine initial fill volumes and system architecture for 20-25 year vessel lifecycles. Chinese and South Korean yards are specifying centrifugal separator efficiency thresholds above 0.5% water content.
- Maintenance Providers:Port-based technical service teams control viscosity-grade optimization and drain interval extension advisory.
- Ship Owners:Independent operators retain direct procurement for smaller fleets outside integrated management structures.
Fleet Operators concentrate contract value. Shipyards lock in long-term system specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for marine lubrication systems varies sharply by geography. Fleet operators in Singapore and Rotterdam accept premium formulations for regulatory compliance, while Mediterranean and Southeast Asian coastal operators prioritize cost-minimization in mineral-based procurement.
Singapore
Container lines and tanker fleets drive demand for high-BN cylinder oils compatible with scrubber-fitted two-stroke engines. The Maritime and Port Authority enforces strict bunkering standards that elevate formulation requirements. Jurong Island's integrated refining and blending complex anchors Asia-Pacific supply concentration for Group II and Group III base stocks.
Germany
Ship managers in Hamburg bundle lubricant supply with predictive maintenance services under integrated technical management contracts. The Federal Maritime and Hydrographic Agency implements port state control bans on open-loop scrubber washwater, forcing dual-fuel vessel lubricant reformulation. The Port of Hamburg's shipyard cluster specifies centrifugal separator efficiency thresholds above 0.5% water content for newbuilds.
China
State-owned shipping lines operating through Shanghai and Ningbo-Zhoushan are retrofitting sensor-integrated oil circulation units to meet classification society notations. The Ministry of Ecology and Environment enforces MARPOL Annex VI sulfur caps with increasing stringency in coastal emission control areas. Dalian and Qingdao shipyards lock in long-term system specifications that determine 20-25 year vessel lubrication architectures.
United States
Gulf Coast refineries concentrate API Group II and Group III base stock production, exposing blenders to freight cost volatility. The Environmental Protection Agency coordinates with California's Air Resources Board on scrubber washwater discharge restrictions in Los Angeles and Long Beach. Superyacht segments in Fort Lauderdale command polyol ester hydraulic fluid premiums for steering gear and deck crane systems.
Netherlands
Rotterdam's bunkering terminals algorithmically compress procurement cycles from quarterly to voyage-based replenishment. The EU Green Deal's FuelEU Maritime initiative drives lifecycle assessments of synthetic ester formulations for European-flagged vessels. TotalEnergies SE operates dedicated marine laboratories in Rotterdam that formulate cylinder oils for low-sulfur fuel compatibility.
Marine Lubrication System Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the marine lubrication system market. Integrated oil majors leverage global bunkering networks and captive base oil supply, while regional blenders compete on formulation agility and port-based technical service proximity. The structure separates into three archetypes: vertically integrated majors with laboratory capabilities, mid-tier compounders with regional hub concentration, and specialized synthetics suppliers serving superyacht niches. Dominant competitive moves include backward integration into additive package production and geographic expansion through port-based technical service teams.
Among integrated oil majors, Shell plc, TotalEnergies SE, and BP plc occupy positions that exemplify divergent strategic emphases. Shell plc represents the network-scale archetype through global bunkering infrastructure. TotalEnergies SE anchors the formulation-specialist position with dedicated marine laboratories in Rotterdam and Singapore. BP plc sits within the service-integrated tier, extending brand presence through port-based technical teams controlling fleet operator relationships in Mediterranean and Asian hubs.
| Leading Market Players |
|---|
| Shell plc |
| Exxon Mobil Corporation |
| Chevron Corporation |
| TotalEnergies SE |
| BP plc |
| LUKOIL |
| China Petroleum & Chemical Corporation |
| Petronas |
| ENEOS Holdings, Inc. |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for alkaline additive packages concentrate pricing power among integrated blenders with captive Group II and Group III base stock access, while spot buyers face volatility from magnesium and calcium detergent precursor shortages.
Pricing Analysis
After-sales technical advisory and condition monitoring contracts now drive lifetime value beyond product margins. Three-tier pricing structure across premium synthetic esters, standard mineral formulations, and economy bulk supply dominates procurement, with differentiation hinging on certification grade and port-based service bundling. Cost compression in mid-tier compounder segments is intensifying because Chinese and Turkish mining constraints on detergent precursors squeeze margins. Coastal fishing operators in Mediterranean and Southeast Asian zones exhibit highest price sensitivity, while superyacht segments in Monaco and Fort Lauderdale accept 40-60% premiums for polyol ester specifications.
Supply Chain Analysis
The United States Gulf Coast and Middle East anchor API Group II and Group III base stock production, with Singapore and Rotterdam serving as downstream formulation and bunkering hubs. Marine lubricant supply draws from magnesium and calcium mining operations, alkaline additive package manufacturing, and centrifugal separator component fabrication. Single-source vulnerability concentrates in Strait of Hormuz transit routes, exposing blenders to geopolitical disruption. Distribution runs through pipeline and barge transfers at Singapore, Rotterdam, and Fujairah terminals, with algorithm-driven voyage-based replenishment displacing quarterly bulk orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine lubrication systems function as a service-attach opportunity where port-based technical advisory and predictive maintenance contracts expand faster than hardware supply, rewarding players who bundle condition monitoring with product formulation.
For Market Incumbents: Compound defensive positioning by deepening captive supply of alkaline additive packages and locking shipyard specifications at Chinese and South Korean newbuild yards. Synthetic ester specialists threaten premium segment margins; incumbents should tighten centrifugal separator efficiency certifications above 0.5% water content thresholds to raise switching costs. For New Entrants and Emerging Players: Anchor in superyacht synthetic formulations for Monaco and Fort Lauderdale berth operators, where polyol ester demand outstrips specialized supply. Mediterranean and Asian coastal fishing fleets present underpenetrated volume pools receptive to unbundled technical advisory services. Go-to-market execution should lead with drain interval optimization software rather than commodity product substitution. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because MARPOL Annex VI sulfur caps and FuelEU Maritime benchmarks tighten formulation requirements irreversibly. Acquisition targets should display laboratory capabilities in Rotterdam or Singapore paired with sensor-integrated oil circulation unit partnerships. Watch ammonia engine trial results from MAN Energy Solutions and WinGD as inflection signals for base oil chemistry obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Production | Magnesium and calcium detergent precursor supply security buffers margin compression from Chinese and Turkish mining constraints. |
| Port-Based Technical Service Expansion | Mediterranean and Asian hub operators unbundle advisory from product supply, creating standalone revenue streams. |
| Synthetic Ester Laboratory Investment | Rotterdam and Singapore facilities formulate low-sulfur compatible cylinder oils meeting FuelEU Maritime lifecycle benchmarks. |
| Sensor-Integrated System Partnerships | Classification society predictive maintenance notations from DNV and Lloyd's Register mandate oil circulation unit retrofits. |
| Shipyard Specification Lock-In | Chinese and South Korean newbuild yards determine 20-25 year vessel lubrication architectures through initial fill contracts. |
Research Methodology
Initial hypotheses were tested against primary input from marine engineering directors, fleet procurement managers, port-based technical service heads, and classification society surveyors and refined through secondary validation. Primary fieldwork drew from Singapore bunkering terminals, Rotterdam blending facilities, and Hamburg ship management clusters. Secondary sources encompassed MARPOL Annex VI enforcement records, EU Green Deal FuelEU Maritime regulatory filings, customs trade data for base stock flows, and SEC disclosures from integrated oil majors. Bottom-up volume builds across vessel segments and top-down macroeconomic anchors were triangulated for convergence.
Variance decomposition separated volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled encompassed product chemistry tiers, vessel architecture categories, procurement channel structures, and regional regulatory clusters. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs included scrubber-fitted fleet penetration assumptions, ammonia engine trial timelines, and superyacht synthetic ester adoption curves.
Decision-makers should treat outputs as directional under base assumptions of sustained MARPOL Annex VI enforcement and no disruptive base oil chemistry shifts; material deviation would warrant model refresh. Forecasts embed assumptions regarding sulfur cap compliance trajectories, additive precursor supply continuity, and classification society notation harmonization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Ship Breaking Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Singapore Maritime Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Passenger Ferries Market
Maritime Equipment
Global Connected Ship Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Reefer Container Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
Global Maritime Safety Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Tugboat Operation Market