
 Traffic Management System Market | 2026-2036
Traffic Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Traffic Management System Market Analysis
India's national smart cities mission is rewriting procurement patterns for urban traffic infrastructure. Siemens leverages its signaling portfolio to anchor large-scale metro projects across South Asia. Kapsch TrafficCom sustains its position through captive tolling-system expertise on European corridors. Cisco Systems competes by extending edge-networking hardware into connected vehicle deployments.
Traffic management systems integrate sensor arrays, centralized computing platforms, and actuator networks to regulate vehicular flow, reduce intersection delay, and enhance roadway safety through real-time data processing with sub-100-millisecond response thresholds. Adaptive Traffic Control and Traffic Signal Control dominate current installation value, while Incident Detection systems command premium pricing due to computer-vision hardware requirements. Cloud-Based deployment is expanding fastest among mid-size municipalities seeking to avoid capital-intensive on-premises infrastructure.
The U.S. DOT, the European Commission through its F-Gas Regulation and EU Green Deal framework, and India's Ministry of Urban Development collectively shape equipment standards, emissions benchmarks, and procurement timelines for traffic infrastructure upgrades. Compliance with these overlapping mandates requires manufacturers to maintain multi-jurisdiction certification capacity. Stakeholders must monitor which regulatory body tightens connected-vehicle cybersecurity requirements first, as this will determine competitive positioning in the next procurement cycle.
Market Dynamics
Edge computing integration at intersection controllers is compressing response latency thresholds and forcing incumbent suppliers to re-architect hardware portfolios around sub-100-millisecond processing capabilities.
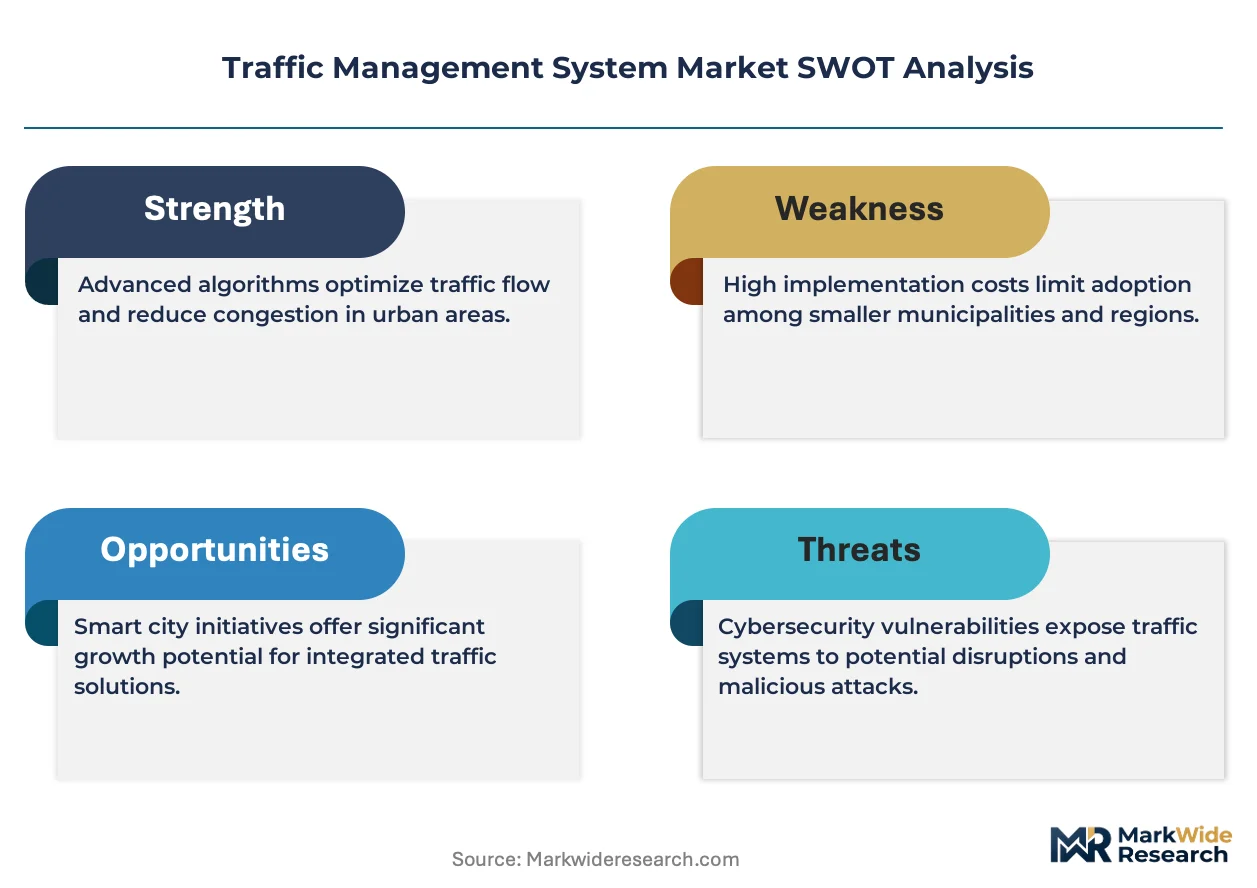
Growth Catalysts
- EU Green Deal mobility mandates:Municipal corporations across Germany, France, and the United Kingdom are expanding procurement of adaptive signal control networks under emissions-reduction frameworks.
- India's national smart cities mission:Urban infrastructure budgets are redirecting toward integrated traffic management platforms in metro corridors and secondary cities.
- Edge-networking hardware:United States DOT agencies are prioritizing real-time congestion mitigation through distributed computing deployments at signalized intersections.
Market Restraints
- Computer-vision hardware costs:Incident Detection systems command premium pricing due to specialized sensor arrays and GPU-intensive processing requirements.
- Multi-jurisdiction certification burden:Manufacturers must maintain parallel compliance capacity across U.S. DOT, EU F-Gas Regulation, and India's Ministry of Urban Development standards.
- Cloud infrastructure dependency:Mid-size municipalities adopting Cloud-Based deployment face recurring operational expenditure exposure and vendor lock-in risk.
Strategic Opportunities
- Connected vehicle deployments:V2X communication infrastructure creates new equipment categories at the intersection of automotive and municipal procurement budgets.
- Adaptive signal control retrofit:Aging fixed-timing installations across Eastern European and Southeast Asian cities present hardware replacement cycles.
- Cybersecurity mandate convergence:The first regulatory body to tighten connected-vehicle security requirements will determine competitive positioning in subsequent procurement cycles.
Industry Challenges
- Sub-100-millisecond engineering talent:Real-time embedded systems expertise for edge controllers remains concentrated among defense and telecommunications sectors.
- Legacy actuator network integration:New centralized computing platforms must interface with decades-old signal hardware and proprietary municipal protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traffic Management System Market |
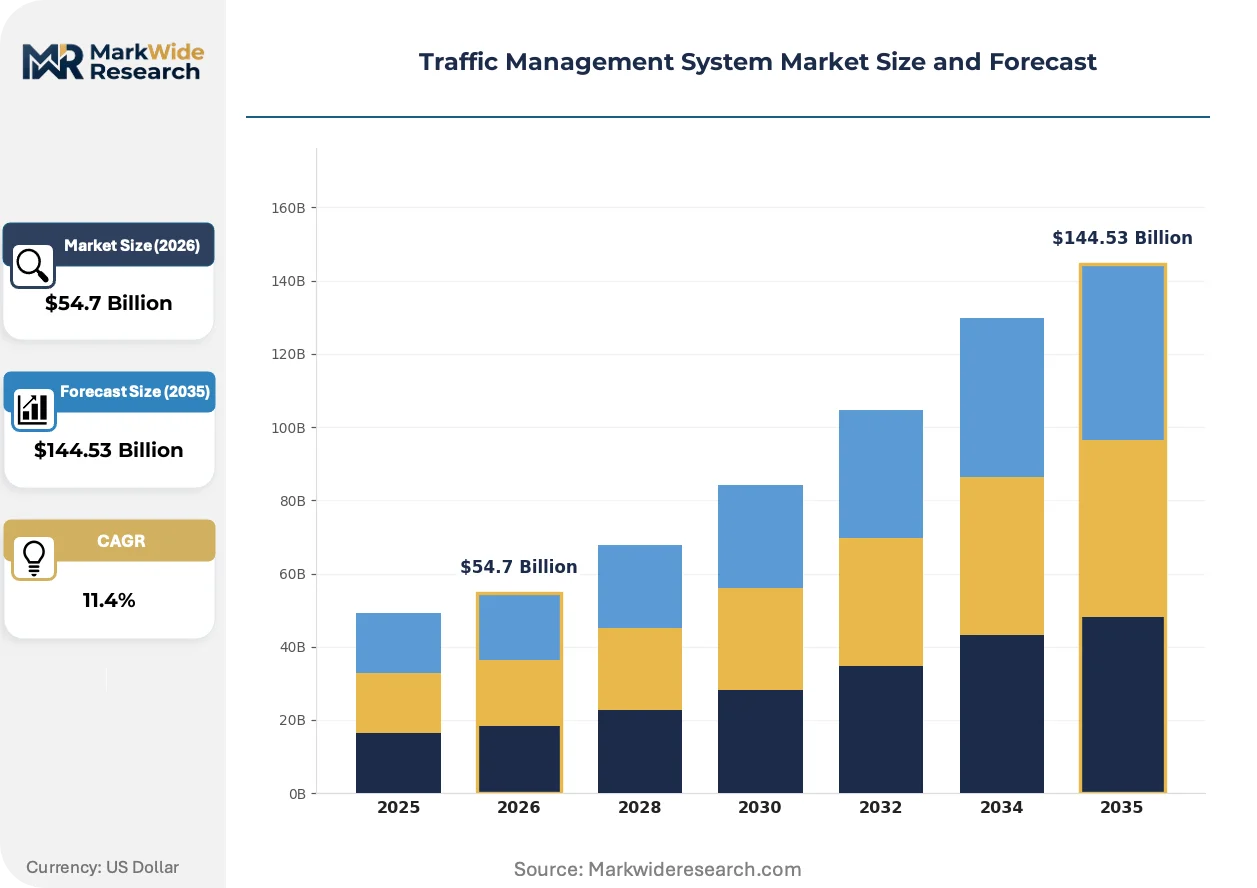
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $144.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Adaptive Traffic Control, Traffic Signal Control, Incident Detection, Traveler Information Systems Application: Public Transport, Emergency Services, Fleet Management, Highway Management End User: Municipal Corporations, Transportation Authorities, Commercial Users, Private Operators Deployment: Cloud-Based, On-Premises, Hybrid, Mobile |
| Companies Covered | Siemens, Thales, IBM, Cubic, Kapsch TrafficCom, Transcore, Teledyne FLIR, TomTom, Cisco Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traffic Management System Market Emerging Trajectories
Traffic management architecture is migrating from centralized command centers toward distributed edge nodes, compressing decision loops and enabling autonomous intersection operation without continuous cloud connectivity.
Edge computing is collapsing the traditional hierarchy between field devices and backhaul infrastructure. Intersection controllers now execute adaptive algorithms locally using GPU-accelerated processing units. State DOT agencies in Texas and California are piloting these architectures on high-volume corridors. The structural consequence is collapsing reliance on fiber backhaul for real-time signal optimization.
The EU AI Act's risk classification framework is reshaping procurement specifications for automated traffic enforcement systems. Computer-vision platforms deployed on public roadways face heightened conformity assessment requirements. European corridor operators are front-loading compliance documentation to secure framework contract eligibility under tightened liability provisions.
Municipal buyers are unbundling hardware procurement from long-term maintenance agreements. Cloud-Based deployment models allow finance departments to shift capital expenditure to operational budgets. This pattern is most visible in mid-size German and French cities where municipal debt constraints intersect with Green Deal implementation timelines.
Traffic Management System Market Segmentation
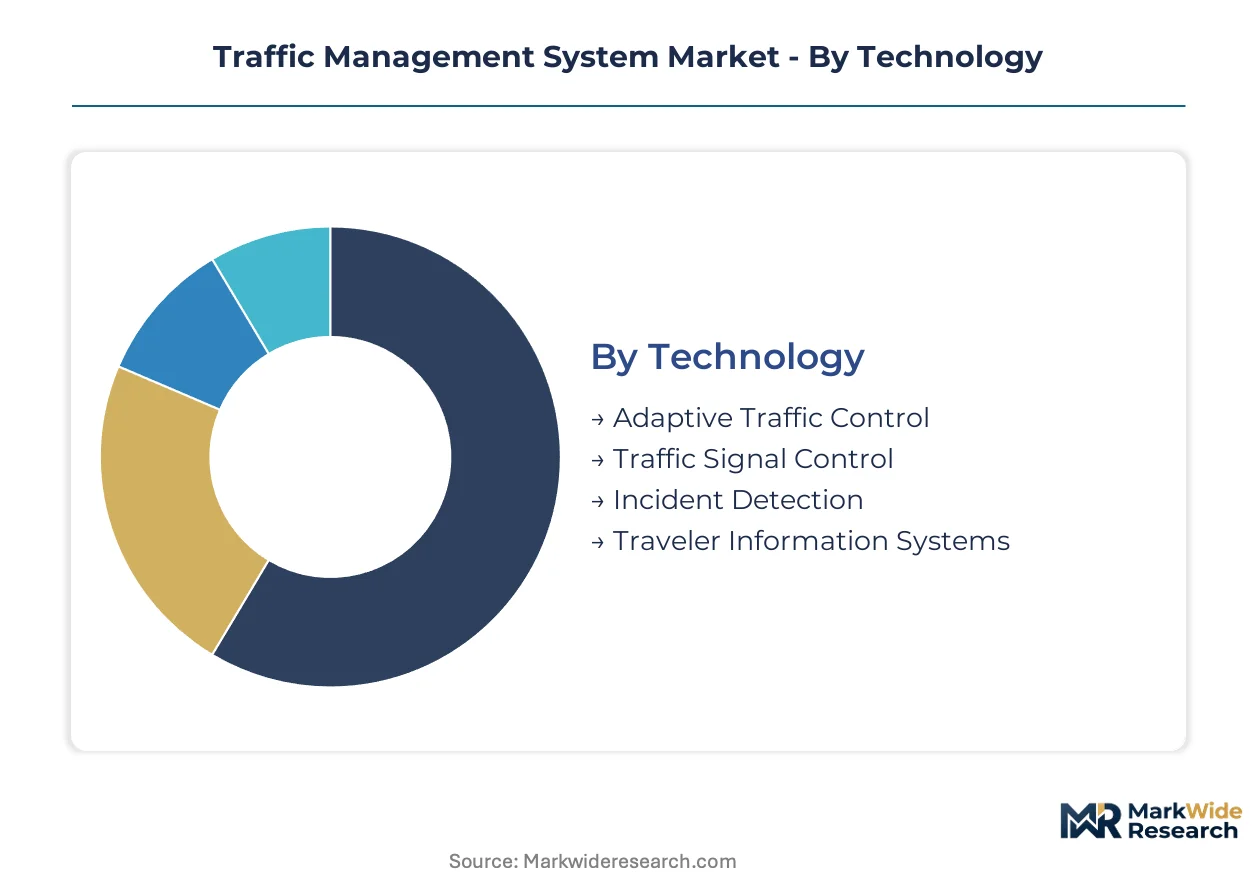
Traffic management procurement fragments across four intersecting dimensions. Technology choices determine hardware architecture and response latency. Deployment models reshape municipal finance structures and vendor lock-in exposure.
Technology:
Use-case spectrum spans routine flow optimization to emergency incident response, with each technology tier demanding distinct sensor density and processing architectures.
- Adaptive Traffic Control:Real-time signal timing algorithms adjust cycle lengths based on detector inputs from vehicle loops, radar, or video analytics. German municipal corporations under EU Green Deal mandates dominate procurement for corridor-wide synchronization projects.
- Traffic Signal Control:Fixed-time and actuated controllers manage intersection phasing through centralized or distributed command structures. Aging installations across Eastern European cities drive replacement demand as legacy electromechanical systems reach end-of-life.
- Incident Detection:Computer-vision and acoustic sensor arrays identify collisions, debris, or stalled vehicles for rapid dispatch coordination. GPU-intensive processing requirements elevate capital costs relative to other technology tiers.
- Traveler Information Systems:Dynamic message signs, mobile applications, and broadcast feeds convey congestion data to motorists. Integration with connected vehicle platforms is expanding deployment scope beyond traditional roadside infrastructure.
Established volume favors Traffic Signal Control; emerging adoption favors Adaptive Traffic Control.
Application:
Cost tier differentiation separates capital-intensive highway deployments from software-centric fleet optimization platforms.
- Public Transport:Signal priority systems and dedicated lane management reduce bus dwell times and improve schedule adherence. Transit agencies in India's smart cities mission corridors represent concentrated procurement demand.
- Emergency Services:Preemption systems grant green-light progression to ambulances and fire apparatus through GPS or optical emitter activation. Integration with dispatch software determines competitive positioning among vendors.
- Fleet Management:Commercial operators utilize route optimization and congestion avoidance to minimize fuel consumption and driver hours. Cloud-Based deployment models lower entry barriers for mid-size logistics providers.
- Highway Management:Ramp metering, variable speed limits, and lane control systems regulate mainline throughput. State DOT agencies in Texas and California pilot edge-computing architectures for sub-100-millisecond response on high-volume corridors.
Highway Management commands premium pricing; Fleet Management expands most quickly through SaaS delivery.
End User:
Customer type determines procurement authority, budget cycle, and compliance burden across overlapping regulatory jurisdictions.
- Municipal Corporations:City traffic engineering departments manage intersection grids and neighborhood traffic calming. Green Deal implementation timelines in France and the United Kingdom accelerate adaptive signal retrofits.
- Transportation Authorities:Regional or state-level agencies oversee corridor coordination and multimodal integration. Multi-jurisdiction certification requirements across U.S. DOT, EU F-Gas Regulation, and Indian standards complicate vendor qualification.
- Commercial Users:Retail developers, stadium operators, and logistics hubs deploy private traffic systems for facility access management. Capital constraints favor Cloud-Based deployment with operational expenditure treatment.
- Private Operators:Toll road concessionaires and parking facility managers leverage traffic data for revenue optimization. Kapsch TrafficCom sustains positioning through captive tolling-system expertise on European corridors.
Transportation Authorities concentrate legacy infrastructure spend; Commercial Users drive Cloud-Based volume.
Deployment:
Maturity gradient separates proven on-premises architectures from emerging edge-native and mobile delivery models.
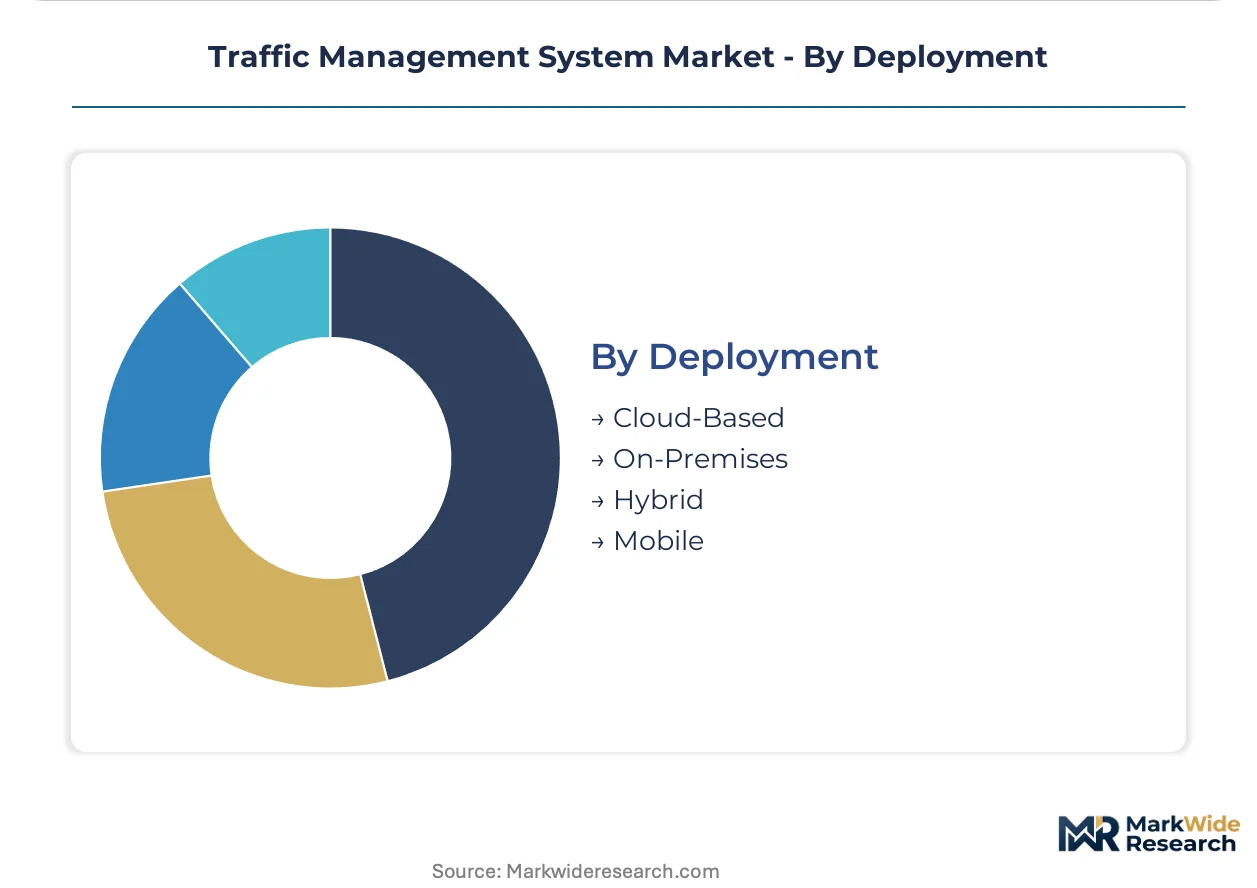
- Cloud-Based:Centralized software platforms eliminate on-site server infrastructure and enable remote system management. Mid-size German and French municipalities adopt this model to shift capital expenditure to operational budgets under debt constraints.
- On-Premises:Local computing hardware maintains signal operation during network outages and satisfies stringent cybersecurity requirements. Defense and critical infrastructure applications mandate air-gapped architectures.
- Hybrid:Edge controllers handle real-time signal execution while cloud platforms manage analytics and remote monitoring. Texas DOT pilots demonstrate reduced fiber backhaul dependency for adaptive optimization.
- Mobile:Smartphone-based traveler information and crowd-sourced congestion reporting supplement fixed infrastructure. Integration with connected vehicle deployments creates new equipment categories at the automotive-municipal procurement intersection.
On-Premises retains safety-critical mandates; Hybrid architectures gain share fastest among state DOT modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Department of Transportation anchors procurement standards for real-time congestion mitigation, while the EU Green Deal and India's smart cities mission create parallel demand centers with distinct certification requirements.
United States
State DOT agencies in Texas and California pilot edge-computing architectures for sub-100-millisecond response thresholds on high-volume corridors. The Federal Highway Administration's Every Day Counts program accelerates adaptive signal deployment timelines. Municipal procurement concentrates in metropolitan clusters across the Sun Belt and Pacific Coast.
Germany
Municipal corporations under EU Green Deal mandates dominate corridor-wide synchronization projects for adaptive signal control networks. The KBA enforces stringent electromagnetic compatibility standards for roadside equipment. Industrial concentration sits with automation specialists headquartered in Bavaria and Baden-Württemberg.
India
Transit agencies in smart cities mission corridors represent concentrated procurement demand for integrated traffic management platforms. The Ministry of Urban Development channels infrastructure budgets toward metro and secondary city deployments. Siemens leverages its signaling portfolio to anchor large-scale projects across South Asian urban clusters.
United Kingdom
Transport for London and regional combined authorities expand adaptive signal retrofits under Green Deal implementation timelines. The Department for Transport coordinates interoperability standards with EU frameworks during post-Brexit transition periods. Procurement activity clusters in Greater London, West Midlands, and Greater Manchester.
France
Mid-size municipalities adopt Cloud-Based deployment models to shift capital expenditure to operational budgets under municipal debt constraints. ANSM and CNIL oversight extends to connected vehicle data governance specifications. Equipment demand concentrates in Île-de-France, Auvergne-Rhône-Alpes, and Provence-Alpes-Côte d'Azur.
Traffic Management System Market Vendor Landscape
Capability concentration sits with defense and telecommunications heritage suppliers possessing sub-100-millisecond embedded systems expertise; scale advantage sits with diversified industrial conglomerates with multi-jurisdiction certification infrastructure. The vendor base separates into three strategic archetypes: signaling heritage specialists, networking hardware extenders, and captive tolling-system operators. Consolidation pressure favors M&A activity targeting edge-computing engineering talent, while geographic expansion focuses on EU Green Deal and India smart cities procurement windows.
Within the signaling heritage tier, Siemens and Thales exemplify industrial conglomerates with municipal infrastructure anchoring positions. Kapsch TrafficCom occupies a distinct position through captive tolling-system expertise on European corridor concessions. Cisco Systems represents networking hardware extenders migrating edge-computing portfolios into connected vehicle deployment categories. These three archetypes illustrate competitive positioning strategies without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Siemens |
| Thales |
| IBM |
| Cubic |
| Kapsch TrafficCom |
| Transcore |
| Teledyne FLIR |
| TomTom |
| Cisco Systems |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's escalating logistics costs cascade through traffic management hardware supply chains, concentrating pricing power among Bavarian automation specialists while forcing tier-two vendors toward Cloud-Based deployment models to escape capital-intensive on-premises competition.
Pricing Analysis
Price spreads between German-engineered edge controllers and Asian-manufactured signal hardware exceed three-to-one ratios across EU procurement frameworks. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Cost compression in mid-tier adaptive signal controllers is intensifying because municipal debt constraints favor operational expenditure models. Fleet Management SaaS buyers exhibit highest price sensitivity; Highway Management DOT agencies demonstrate lowest.
Supply Chain Analysis
Semiconductor feedstock for GPU-accelerated edge processors draws from Taiwan, South Korea, and USA fabrication capacity. German KBA electromagnetic compatibility testing, Chinese radar sensor manufacturing, and Indian software development centers anchor component sourcing. Single-source vulnerability concentrates in advanced node GPU supply. Distribution runs through systems integrators with captive municipal relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward Transportation Authorities consolidating corridor-wide procurement, fragmenting vendor access as multi-jurisdiction certification requirements raise qualification barriers for specialized suppliers.
For Market Incumbents: Build switching-cost moats through captive maintenance agreements and proprietary municipal protocol integration. Deepen backward integration into edge-computing semiconductor sourcing to offset GPU supply volatility. Invest in EU AI Act conformity documentation ahead of tightened automated enforcement liability provisions. Threat: Cloud-native entrants disintermediating hardware attach rates. For New Entrants and Emerging Players: Establish a beachhead in India's smart cities mission corridors where Siemens' signaling dominance leaves white space in Cloud-Based analytics layers. Target mid-size French municipalities under Green Deal debt constraints seeking operational expenditure treatment. Go-to-market: Partner with regional systems integrators possessing existing municipal engineering relationships. For Investors and Strategic Acquirers: Edge-computing engineering boutiques with defense sector heritage represent the priority acquisition archetype. Long-term viability hinges on sub-100-millisecond embedded systems talent scarcity persisting across the analysis window. Signal to monitor: Which regulatory body—U.S. DOT, EU Commission, or India's Ministry of Urban Development—tightens connected-vehicle cybersecurity mandates first.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Hardware Development | Texas DOT pilots demonstrate reduced fiber backhaul dependency for real-time optimization. |
| EU AI Act Compliance Front-Loading | European corridor operators secure framework contract eligibility under tightened liability provisions. |
| Cloud-Based Deployment Expansion | Mid-size German municipalities shift capital expenditure to operational budgets under debt constraints. |
| Connected Vehicle Infrastructure Partnership | V2X equipment categories emerge at the intersection of automotive and municipal procurement budgets. |
| Adaptive Signal Retrofit Programs | Eastern European cities drive replacement demand as legacy electromechanical systems reach end-of-life. |
Methodological Framework
A standing panel of municipal traffic engineering directors, state DOT procurement officers, edge-computing platform architects, and systems integration project managers provided ongoing calibration across primary interview cycles. Secondary validation drew from U.S. Federal Highway Administration Every Day Counts program disclosures, EU Green Deal implementation timelines, Indian Ministry of Urban Development smart cities mission documentation, and KBA electromagnetic compatibility certification records. Bottom-up installation forecasts triangulated against top-down infrastructure budget allocations.
Scenario-bracketing around EU F-Gas Regulation compliance timelines and U.S. DOT connected-vehicle mandate trajectories bounded the projection horizon. Segmentation modeling spanned technology tier, deployment architecture, end-user procurement authority, and regional regulatory cluster dimensions. CAGRs derived from infrastructure budget growth rates intersected with equipment replacement cycle analysis. Edge-computing penetration assumptions and Cloud-Based deployment adoption curves served as primary forecast sensitivities.
Macroeconomic conditions sit as an overlay; deviation in municipal debt financing costs and semiconductor supply availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation pacing and infrastructure stimulus continuity. Cross-checking against state DOT capital improvement plan disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Air Taxi Market
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
Global Intelligent Traffic Management System Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Cellular Vehicle-To-Everything (C-V2X) Market
Smart Transportation Solutions
Asia Pacific Hyperloop Technology Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
North America Passenger Information System Market
Smart Transportation Solutions
Smart Car Digital Key System Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
Fleet Management Software Market