
 Voyage Data Recorder (VDR) Market | 2026-2036
Voyage Data Recorder (VDR) Market Size, Share, and Industry Trends Forecast 2026-2036
Voyage Data Recorder (VDR) Market Analytics
The International Maritime Organization's revised VDR performance standards is hardening certification requirements for bridge electronics. Kongsberg Maritime leverages its integrated bridge systems portfolio to anchor premium retrofit contracts across Nordic-flagged fleets. Danelec Marine specializes in simplified VDR configurations that compete aggressively on total cost of ownership for mid-size cargo operators.
A Voyage Data Recorder is a ruggedized black-box system that captures bridge audio, radar images, ECDIS data, and sensor feeds using tamper-resistant solid-state storage rated for deep-sea recovery. Its primary purpose is to provide accident investigators with reconstructible event sequences following maritime incidents. Marine VDR systems dominate installed base value due to SOLAS-mandated coverage on oceangoing vessels, while Float-Free VDR demand is accelerating fastest among newbuilds as shipyards integrate survival craft requirements earlier in design cycles. Digital Recording technology leads technology segmentation, though Hybrid Systems are gaining share where operators seek backward compatibility with legacy analog sensor networks.
The IMO, IEC 61996 standard, and national maritime safety administrations such as the US Coast Guard and China's Maritime Safety Administration collectively shape product specifications, type-approval pathways, and inspection intervals. Compliance timelines for next-generation VDR performance standards are tightening certification windows and concentrating procurement among pre-approved vendors. Stakeholders must monitor flag-state implementation variance, as enforcement pacing will determine regional replacement cycle intensity.
Market Dynamics
IMO's revised VDR performance standards are compressing replacement cycles as commercial fleets face mandatory compliance deadlines, forcing ship operators to retire legacy analog systems ahead of scheduled obsolescence.
Growth Catalysts
- SOLAS Chapter V Mandates:The International Maritime Organization's Safety of Life at Sea regulations require VDR installation on all oceangoing passenger ships and cargo vessels above specific tonnage thresholds, creating baseline demand.
- China's State-Owned Shipbuilding:Domestic yards in Dalian, Shanghai, and Guangzhou are expanding newbuild output, concentrating procurement among pre-approved VDR vendors serving state-contracted fleets.
- Float-Free Survival Integration:Shipyards are embedding VDR capsules into survival craft designs earlier in construction cycles, accelerating specification of marine-grade protected data recorders.
Market Restraints
- Specialized Component Supply:Deep-sea rated solid-state storage modules and tamper-resistant housings depend on limited semiconductor foundry capacity, creating input bottlenecks.
- Flag-State Implementation Variance:The US Coast Guard, China's Maritime Safety Administration, and EU member state maritime authorities enforce IMO standards on staggered timelines, fragmenting certification windows.
- Legacy Analog Sensor Networks:Existing vessel instrumentation using NMEA 0183 protocols resists seamless digital integration, prolonging hybrid system dependency.
Strategic Opportunities
- Retrofit-First Fleets:Nordic-flagged shipping lines operating aging tonnage present concentrated demand for bridge electronics upgrades ahead of 2024-2026 compliance deadlines.
- ECDIS-VDR Convergence:Electronic chart display and information system data streams are merging with VDR capture protocols, enabling unified bridge data architectures.
- Remote Diagnostic Channels:Satellite-linked maintenance monitoring is displacing port-based technician visits, opening subscription revenue models for equipment suppliers.
Industry Challenges
- Marine Electronics Certification:IEC 61996 type-approval processes require extensive environmental testing, compressing product development timelines.
- Bridge System Integration Complexity:VDR installation demands synchronization with radar, gyrocompass, and autopilot feeds, straining vessel downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voyage Data Recorder (VDR) Market |
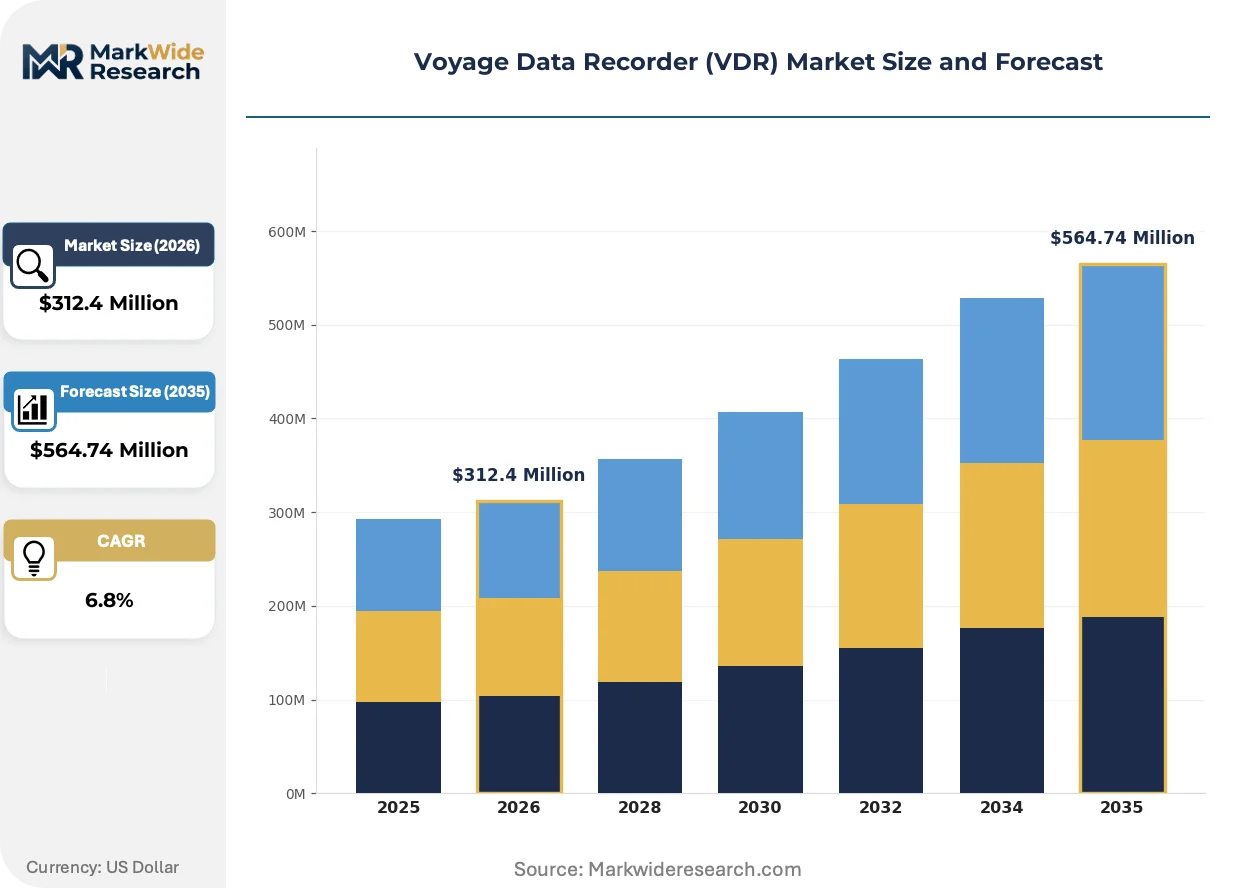
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Marine VDR, Simplified VDR, Float-Free VDR, Legacy VDR End User: Shipping Companies, Offshore Operators, Research Institutions, Maritime Authorities Technology: Digital Recording, Analog Recording, Hybrid Systems, Wireless Communication Installation Type: Onboard, Retrofit, Maintenance Services, Integrated Solutions |
| Companies Covered | Kongsberg Maritime, Furuno Electric Co., Ltd., Danelec Marine, Japan Radio Co., Ltd., Wärtsilä Voyage, Netwave Systems B.V., Raytheon Technologies, Thales Group, Beijing Highlander Digital Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voyage Data Recorder (VDR) Market Evolving Landscape
Bridge data architectures are converging around unified capture platforms that dissolve traditional boundaries between navigation, communication, and recording systems.
Solid-state storage arrays with marine-grade encryption are unifying sensor feed aggregation, audio capture, and image logging within single ruggedized housings. Container lines operating high-frequency Asia-Europe routes are specifying these integrated units to reduce bridge footprint and cabling complexity. This unification is compressing supplier margins on standalone VDR hardware while expanding service contract attach rates.
The EU's updated Marine Equipment Directive is tightening electromagnetic compatibility and environmental testing protocols for bridge electronics type-approval. Shipyards serving European-flagged owners are demanding pre-certified module configurations to accelerate yard delivery schedules. Nordic classification societies are responding with streamlined approval pathways for integrated bridge systems that bundle VDR functionality.
Fleet managers are consolidating supplier relationships around full-bridge integrators rather than standalone VDR specialists. Mid-size cargo operators in particular are shifting procurement toward single-source contracts covering ECDIS, radar, and data recording. This concentration is most visible among German and Greek shipowners managing mixed fleets of bulk carriers and tankers.
Voyage Data Recorder (VDR) Market Segmentation
VDR procurement patterns diverge sharply across vessel types, compliance deadlines, and fleet modernization cycles. Segment-level demand concentrates where SOLAS mandates intersect with shipyard output and retrofit urgency.
Product Type:
Replacement cycles are compressing as IMO performance standards force fleet-wide system upgrades ahead of certification deadlines.
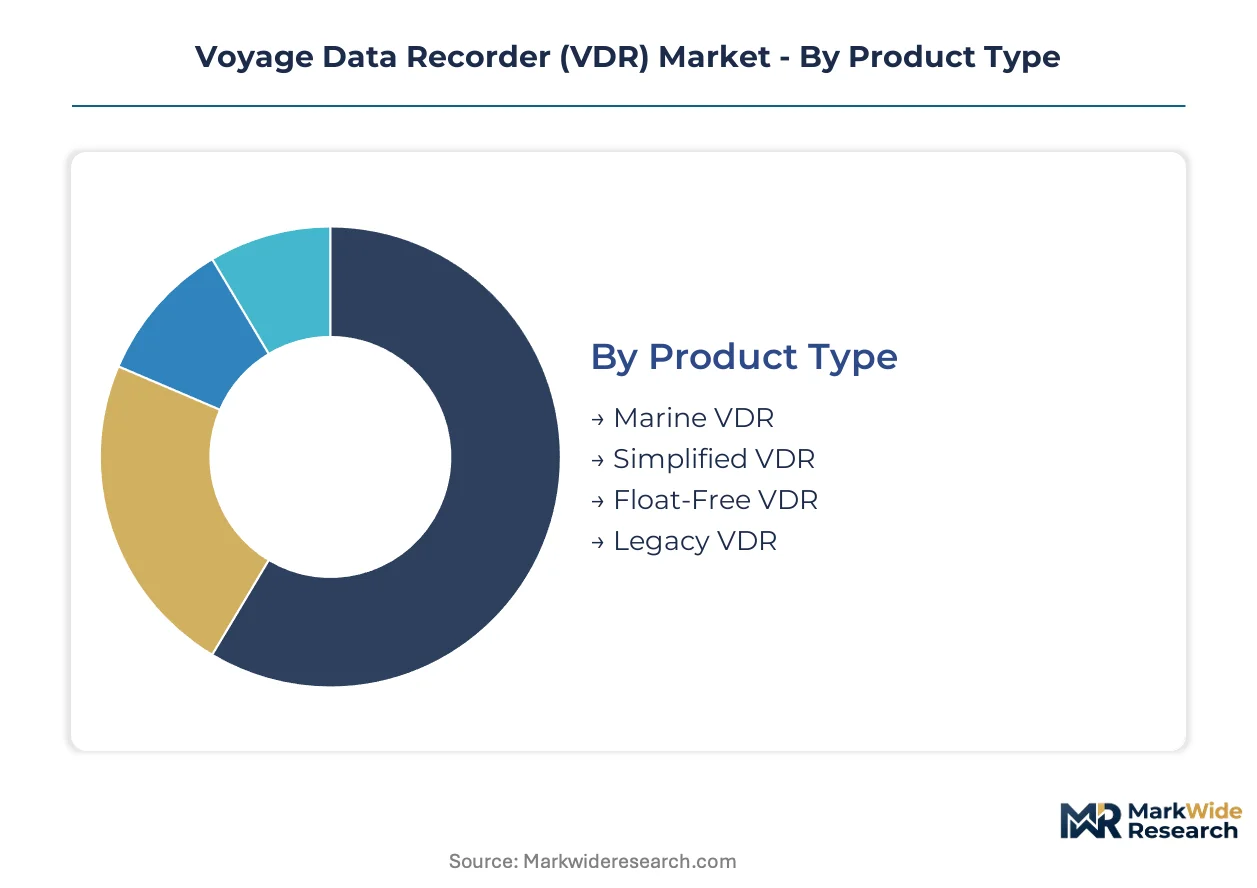
- Marine VDR:Full-function systems capture bridge audio, radar images, ECDIS feeds, and sensor data using deep-sea rated solid-state storage. SOLAS-mandated coverage on oceangoing cargo vessels and passenger ships sustains baseline procurement volumes across commercial fleets.
- Float-Free VDR:Protected capsules deploy automatically with survival craft, embedding hardened recorders into lifeboat and liferaft designs. Shipyards in China, South Korea, and Japan are specifying these units earlier in newbuild construction cycles to satisfy survival craft integration requirements.
- Simplified VDR:Compact configurations target smaller cargo operators with reduced sensor feed requirements and lower total cost of ownership.
- Legacy VDR:Aging analog and early digital systems face accelerated retirement as flag-state inspectors enforce revised IEC 61996 certification windows.
Marine VDR sits at the top of the volume ranking, with Float-Free VDR climbing the fastest.
End User:
Customer procurement authority concentrates where fleet scale meets regulatory enforcement intensity.
- Shipping Companies:Container lines, bulk carriers, and tanker operators dominate installed base value. German and Greek shipowners managing mixed fleets are consolidating supplier relationships around full-bridge integrators covering ECDIS, radar, and data recording under single contracts.
- Offshore Operators:Oil and gas support vessels, offshore construction ships, and wind farm service craft require enhanced environmental ruggedization. North Sea and Gulf of Mexico fleets are upgrading systems to satisfy heightened safety case requirements from national petroleum regulators.
- Research Institutions:Oceanographic vessels and academic fleets specify extended recording durations and supplementary environmental sensor integration.
- Maritime Authorities:Coast guard, naval, and border enforcement vessels procure specialized configurations with classified data handling protocols and enhanced tamper resistance.
Shipping Companies anchor the revenue base, while Offshore Operators are expanding most quickly.
Technology:
Technology selection tracks the pace of bridge sensor network modernization and backward compatibility requirements.
- Digital Recording:Solid-state arrays with marine-grade encryption unify sensor aggregation, audio capture, and image logging within single housings. High-frequency Asia-Europe container routes are specifying these integrated units to reduce bridge footprint and cabling complexity.
- Hybrid Systems:Dual-mode architectures bridge legacy NMEA 0183 analog networks with modern digital feeds. Fleets with staggered electronics refresh cycles depend on these configurations to avoid wholesale bridge replacement.
- Analog Recording:Tape-based and early solid-state systems face mandatory retirement as IEC 61996 type-approval expires.
- Wireless Communication:Satellite-linked diagnostic channels enable remote maintenance monitoring, displacing port-based technician visits and opening subscription revenue models for equipment suppliers.
Digital Recording commands the largest share, with Hybrid Systems gaining ground fastest among retrofit-first fleets.
Installation Type:
Installation mode reflects vessel age distribution and yard capacity constraints.
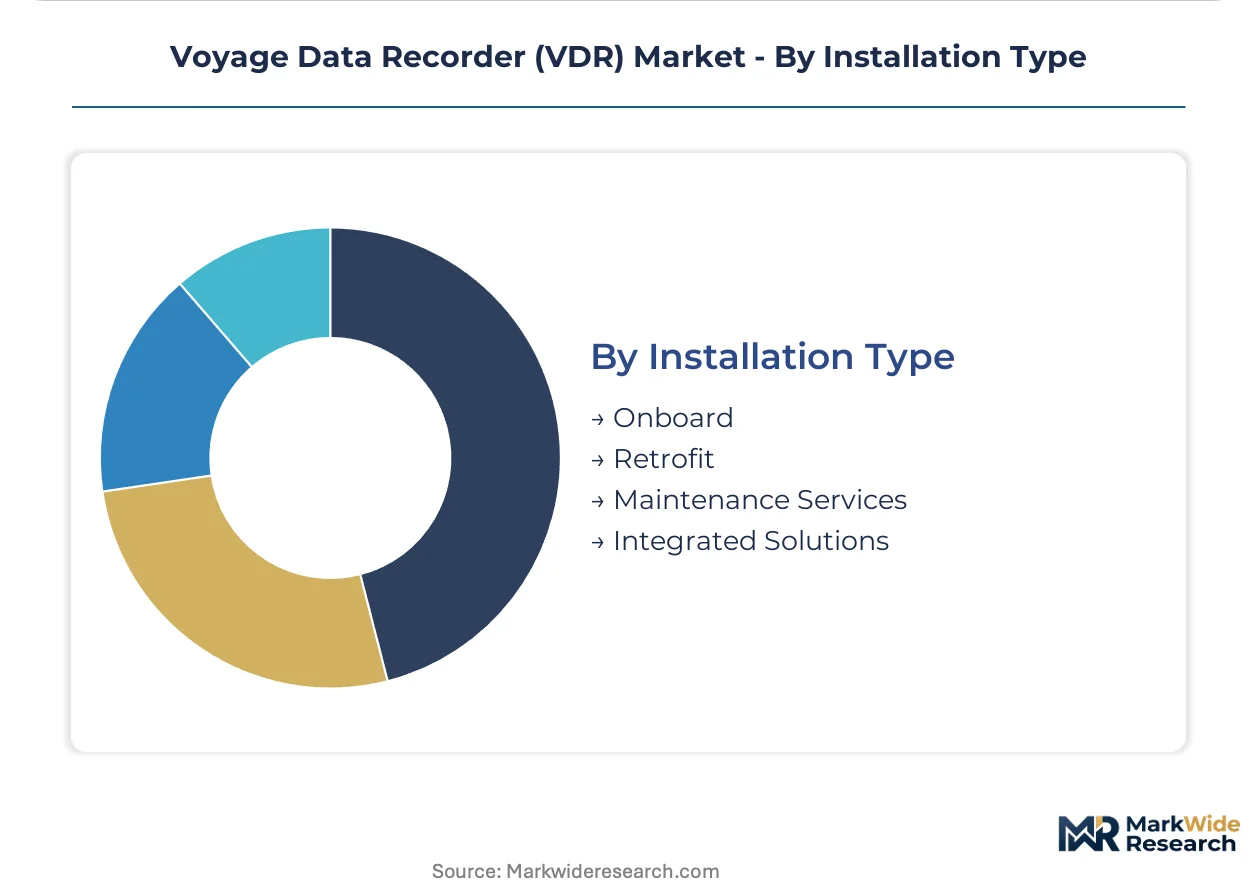
- Retrofit:Bridge electronics upgrades on aging tonnage concentrate in Nordic-flagged fleets facing compressed compliance deadlines. Kongsberg Maritime and Danelec Marine are anchoring premium and mid-market retrofit contracts respectively.
- Onboard:Newbuild specifications at Chinese state-owned yards in Dalian, Shanghai, and Guangzhou are concentrating procurement among pre-approved vendors serving state-contracted fleets.
- Maintenance Services:Extended service contracts attach to hardware sales as suppliers seek recurring revenue streams.
- Integrated Solutions:Full-bridge packages bundle VDR functionality with ECDIS, radar, and autopilot systems under single-source contracts.
Onboard installation leads by volume, though Retrofit activity is accelerating most sharply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maritime engineering talent clusters in Nordic port cities, Chinese shipbuilding hubs, and Japanese electronics centers anchor regional VDR procurement patterns. These workforce concentrations determine where type-approval expertise, yard integration capacity, and fleet modernization cycles intersect most intensively.
China
Dalian, Shanghai, and Guangzhou shipyards are expanding state-contracted newbuild output ahead of IMO compliance deadlines. China's Maritime Safety Administration enforces staggered certification windows that compress procurement timelines for domestic yards. The Yangtze River Delta concentration of pre-approved VDR vendors is capturing concentrated demand from state-owned fleet operators.
Norway
Nordic-flagged shipping lines operating aging tonnage present retrofit-first demand for bridge electronics upgrades. The Norwegian Maritime Authority coordinates closely with DNV classification society on IEC 61996 type-approval pathways. Kongsberg Maritime leverages its Kongsberg-based integrated bridge systems portfolio to anchor premium retrofit contracts across Scandinavian fleets.
Japan
Japanese electronics manufacturers supply solid-state storage modules and marine-grade encryption components to global VDR assemblers. METI oversees domestic industrial standards alignment with IEC 61996 revisions. The Kanto region's precision manufacturing cluster around Tokyo Bay feeds specialized component supply into both domestic and export markets.
United States
The US Coast Guard enforces SOLAS Chapter V mandates on staggered timelines that fragment replacement cycle intensity across American-flagged fleets. Gulf of Mexico offshore operators are upgrading VDR systems to satisfy heightened safety case requirements from the Bureau of Safety and Environmental Enforcement. Houston's offshore support vessel concentration drives demand for enhanced environmental ruggedization.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries yards in Ulsan and Geoje are integrating float-free VDR capsules earlier in newbuild construction cycles. The Korea Maritime Safety Tribunal coordinates accident investigation protocols that influence recorder specification requirements. Busan's classification society presence streamlines approval pathways for integrated bridge systems bundling VDR functionality.
Voyage Data Recorder (VDR) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated bridge system providers, standalone VDR specialists, and defense-electronics diversifiers. Consolidation pressure is intensifying as fleet managers shift procurement toward full-bridge single-source contracts. Competitive moves center on M&A to acquire type-approval portfolios and strategic partnerships to secure semiconductor foundry capacity for deep-sea rated storage modules.
Within the integrated bridge tier, Kongsberg Maritime and Wärtsilä Voyage exemplify Nordic-based conglomerates leveraging navigation systems portfolios to anchor premium positioning. Danelec Marine occupies a focused specialist position competing aggressively on total cost of ownership for mid-size cargo operators. Furuno Electric Co., Ltd. and Japan Radio Co., Ltd. represent Japanese electronics manufacturers supplying core components and finished systems across multiple maritime electronics categories. Beijing Highlander Digital Technology Co., Ltd. anchors Chinese domestic supply serving state-contracted shipbuilding programs.
| Leading Market Players |
|---|
| Kongsberg Maritime |
| Furuno Electric Co., Ltd. |
| Danelec Marine |
| Japan Radio Co., Ltd. |
| Wärtsilä Voyage |
| Netwave Systems B.V. |
| Raytheon Technologies |
| Thales Group |
| Beijing Highlander Digital Technology Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between IEC 61996 type-approved systems and pre-certified module configurations splits the market into premium retrofit contracts and commoditized newbuild supply, with this divergence mapping directly onto concentrated Nordic bridge electronics integration versus dispersed Chinese yard procurement channels.
Pricing Analysis
Bundled service contracts versus unbundled hardware-only sales define the dominant pricing structure, with integrated bridge system providers commanding premium positioning through ECDIS-VDR-radar packages while standalone VDR specialists compete on unit economics. Price differentiation rests on IEC 61996 certification tier and after-sales service attach rates, with flag-state inspection intensity as the key quality signal. Pricing pressure intensifies in the mid-size cargo operator segment as Danelec Marine and comparable specialists drive cost compression through simplified configurations. Shipping companies managing mixed fleets show lowest price sensitivity, prioritizing single-source accountability; small independent operators exhibit highest sensitivity, deferring upgrades until mandatory compliance deadlines force action.
Supply Chain Analysis
China's local-content requirements for state-contracted shipbuilding programs are reshaping sourcing patterns, compelling foreign VDR assemblers to establish domestic module production or partner with pre-approved indigenous vendors. Component supply concentrates in Japan, South Korea, and China, with Tokyo Bay precision manufacturers feeding solid-state storage modules and marine-grade encryption components to global assemblers. Deep-sea rated semiconductor foundry capacity and tamper-resistant housing alloys constitute critical input dependencies. Single-source vulnerability in specialized storage module supply creates structural risk, particularly where IMO compliance deadlines compress procurement windows. Distribution runs through shipyard-integrated procurement channels and maritime electronics distributors serving retrofit-first fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VDR market functions as a stable compounder anchored by SOLAS-mandated replacement cycles that generate predictable demand regardless of shipping rate volatility.
For Market Incumbents: Cement type-approval portfolio depth by acquiring smaller specialists with dormant IEC 61996 certifications, defending against emerging Chinese domestic vendors leveraging local-content rules. Prioritize backward integration into solid-state storage module production to secure foundry capacity ahead of compliance deadline crunches. Channel control through shipyard-integrated procurement relationships offers the strongest defensive lever against price erosion. For New Entrants and Emerging Players: Enter via simplified VDR configurations targeting mid-size Greek and German cargo operators with staggered fleet modernization cycles, the most penetrable segment where incumbent bundling strategies leave service gaps. Remote diagnostic subscription models present a distinct go-to-market angle, displacing port-based technician visits with satellite-linked maintenance monitoring. Geographic white space exists in Southeast Asian retrofit markets where flag-state enforcement timelines lag European and Chinese pacing. For Investors and Strategic Acquirers: Consolidation pressure builds where type-approval expertise concentrates among aging specialist founders approaching exit windows. The market reads as a 5-10 year compounder with defensive characteristics, suitable for infrastructure-style capital deployment. Acquisition target archetype: mid-cap VDR specialists with dormant certification portfolios and established shipyard relationships in second-tier maritime clusters. The signal to watch is flag-state implementation variance, where accelerated enforcement in major jurisdictions would compress replacement cycles and revalue installed base assets.| Strategic Initiative | Industry Significance |
|---|---|
| Type-Approval Portfolio Acquisition | Consolidating dormant IEC 61996 certifications accelerates market access for new product lines. |
| Backward Integration into Storage Modules | In-house production of deep-sea rated solid-state arrays secures supply against foundry bottlenecks. |
| Remote Diagnostic Platform Launch | Satellite-linked maintenance monitoring displaces port-based technician visits with recurring subscription revenue. |
| Shipyard Integration Partnership | Embedded procurement relationships at Chinese state-owned yards capture concentrated newbuild demand. |
| Simplified VDR Configuration Development | Reduced sensor feed targeting opens mid-market cargo operator segments bypassed by premium bundling strategies. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with shipyard procurement officers, fleet technical managers, maritime electronics distributors, and classification society surveyors with secondary validation from IMO circulars, IEC 61996 standard documentation, flag-state enforcement notices, and customs trade records. Bottom-up vessel-by-vessel installation tracking and top-down fleet modernization cycle analysis were triangulated to anchor market size estimates.
Comparable-period anchoring to historical SOLAS implementation waves informed the projection framework, with segmentation across product type, end user, technology, and installation mode modeled throughout the forecast period. CAGRs were derived from regression analysis of replacement cycle intensity against compliance deadline proximity, incorporating shipyard output forecasts and flag-state enforcement pacing as industry-specific inputs.
Inputs from primary fieldwork and secondary regulatory documentation were available through the study window; gaps in real-time fleet upgrade tracking and flag-state inspection intensity data introduce uncertainty bands around near-term replacement cycle timing. Forecasts reflect documented assumptions regarding IMO standard implementation trajectories and shipyard capacity expansion plans. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Global Connected Ship Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Green Ship Recycling Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Asia-Pacific Stevedoring and Marine Cargo Handling Market
Maritime Equipment
North America Container Terminal Operations Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Offshore Support Vessel Service Market
Maritime Equipment
Chemical Tanker Market