
 Ballast Water Management Market | 2026-2036
Ballast Water Management Market Size, Share, and Industry Trends Forecast 2026-2036
Ballast Water Management Market Analysis
Project finance leasing for ballast water treatment retrofits is rewriting competitive access, allowing smaller fleet operators to spread capital outlays across operating budgets rather than absorbing upfront equipment costs. Wärtsilä leverages its integrated marine propulsion and environmental systems portfolio to bundle treatment installations with engine overhauls. Alfa Laval anchors its position through extensive port service networks that reduce vessel downtime during retrofit windows. Optimarin specializes in compact UV-based systems engineered for tanker vessels with constrained engine room footprints.
Ballast water management encompasses the treatment, filtration, and disinfection of water transferred between ports to prevent invasive species migration, with systems typically processing 200–10,000 cubic meters per hour depending on vessel class and pump configuration. The primary purpose is biological neutralization to meet discharge standards without compromising ship stability or operational schedules. UV Treatment leads installed base volume due to lower chemical handling requirements and reduced crew training burdens, while Hybrid Systems represent the fastest-growing product category as operators seek redundancy against variable water quality conditions. Chemical Disinfection retains margin concentration in regions with high turbidity ports where UV transmittance falls below regulatory thresholds.
The International Maritime Organization's Ballast Water Management Convention shapes equipment demand through phased implementation deadlines tied to vessel renewal surveys. The US Coast Guard enforces separate type-approval standards that exclude several IMO-certified systems from US waters, fragmenting supplier certification investments. The EU Marine Strategy Framework Directive adds regional ecological targets that pressure member state port authorities toward stricter monitoring protocols. Stakeholders must track divergence between IMO and USCG testing protocols when selecting systems with multi-jurisdiction operational profiles.
Market Dynamics
The International Maritime Organization's phased compliance deadlines are compressing procurement cycles, forcing fleet operators to accelerate retrofit schedules while suppliers scramble to expand installation capacity ahead of renewal survey windows.
Growth Catalysts
- IMO Convention Enforcement:Mandatory installation timelines tied to vessel renewal surveys are pulling forward equipment demand across container and tanker fleets.
- Singapore Hub Concentration:Dense vessel traffic through the port cluster generates concentrated retrofit volumes for treatment system providers.
- UV Technology Maturation:Lower chemical handling requirements and reduced crew training burdens are expanding UV treatment adoption among operators with limited technical staff.
Market Restraints
- USCG Type-Approval Fragmentation:Separate certification standards that exclude IMO-certified systems from US waters force suppliers to duplicate testing investments.
- High-Turbidity Port Limitations:UV transmittance failures in regions with sediment-heavy waters restrict system effectiveness and require costly hybrid configurations.
- Specialized Installation Labor Scarcity:Qualified marine engineers capable of integrating treatment systems during compressed dry-dock windows remain concentrated in Northern European and East Asian shipyard clusters.
Strategic Opportunities
- Project Finance Leasing Penetration:Smaller fleet operators are spreading capital outlays across operating budgets rather than absorbing upfront equipment costs.
- Hybrid System Category Expansion:Redundancy-seeking operators facing variable water quality conditions are driving fastest-growing product segment demand.
- EU Marine Strategy Framework Directive:Regional ecological targets pressure member state port authorities toward stricter monitoring protocols and upgraded equipment specifications.
Industry Challenges
- Divergent Testing Protocol Navigation:Stakeholders must track divergence between IMO and USCG certification requirements when selecting systems with multi-jurisdiction operational profiles.
- Legacy Vessel Integration Complexity:Retrofit installations in aging tankers with constrained engine room footprints demand compact system configurations that limit technology options.
- Compressed Dry-Dock Scheduling:Treatment system installation must coordinate with engine overhauls and hull maintenance within narrow port windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ballast Water Management Market |
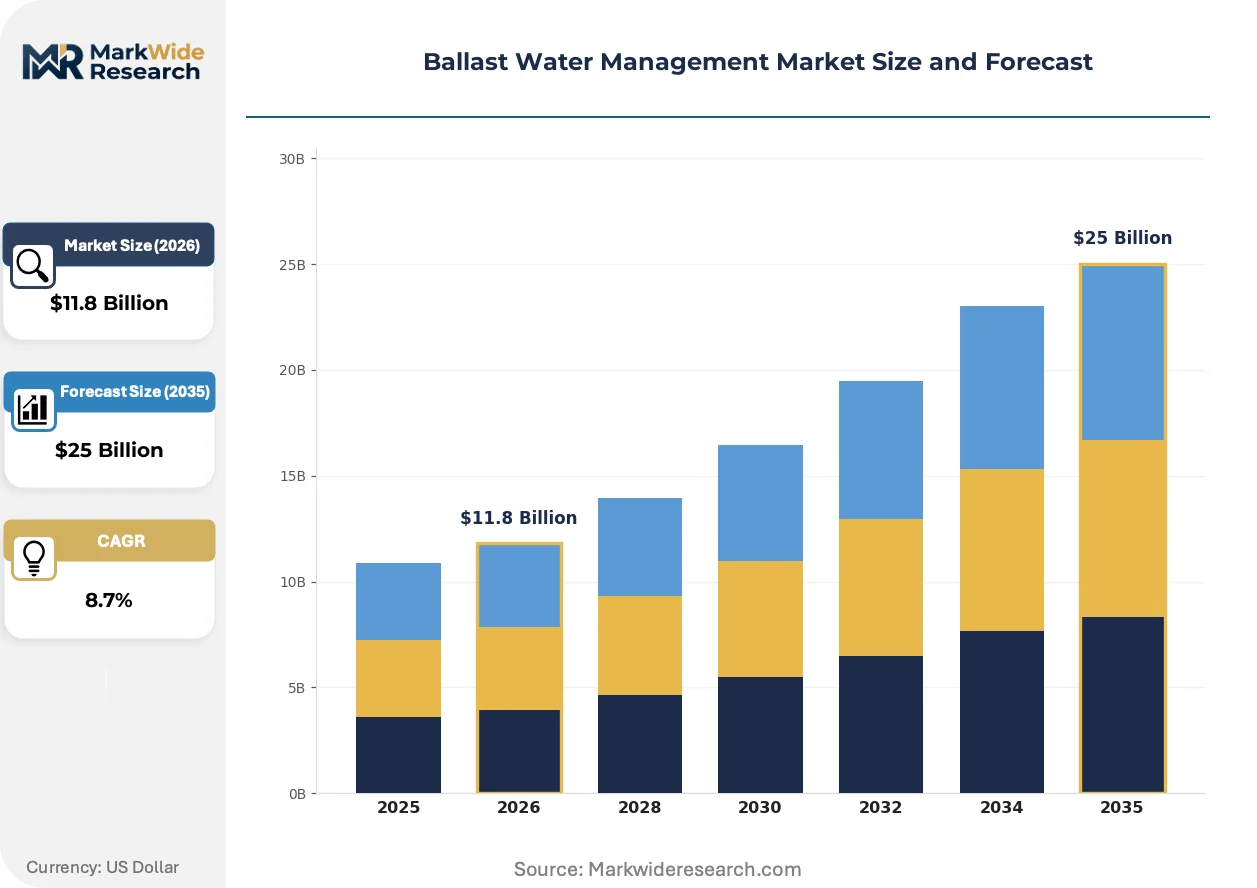
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $25 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtration Systems, Chemical Treatment, UV Treatment, Hybrid Systems End User: Shipping Companies, Port Authorities, Regulatory Bodies, Environmental Agencies Technology: Filtration Technology, Chemical Disinfection, UV Technology, Electrodialysis Installation Type: Retrofit, New Build, Modular Systems, Integrated Solutions |
| Companies Covered | Alfa Laval, Wärtsilä, Veolia Water Technologies, Evoqua Water Technologies, Optimarin, Ecochlor, Hyde Marine, PanAsia Co., Ltd., Headway Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballast Water Management Market Emerging Trajectories
Digital integration of treatment monitoring with fleet management platforms is reshaping how operators demonstrate compliance and optimize system performance across dispersed vessel networks.
Real-time water quality sensors paired with automated UV intensity adjustment are digitizing compliance documentation for port state control inspections. Container lines with centralized fleet operations centers are adopting these systems fastest, with several major operators completing rollouts across their owned tonnage. The shift is digitizing what was previously manual sampling and logbook maintenance, compressing administrative burden while tightening discharge standard adherence.
The EU Marine Strategy Framework Directive is tightening ecological targets that pressure member state port authorities toward enhanced monitoring protocols. This regulatory pressure is forcing treatment system suppliers to integrate data logging capabilities that satisfy both IMO discharge standards and emerging EU-specific reporting requirements. Chemical disinfection providers serving Mediterranean and Baltic ports are responding with upgraded dosing control systems.
Leasing-based procurement models are displacing traditional equipment purchase structures among mid-size fleet operators. Third-party lessors are absorbing upfront capital requirements and embedding service contracts that guarantee system uptime. Greek and Singapore-based shipowners with fragmented vessel ownership structures are driving this shift, seeking to preserve liquidity for core fleet expansion rather than environmental compliance hardware.
Ballast Water Management Market Segmentation
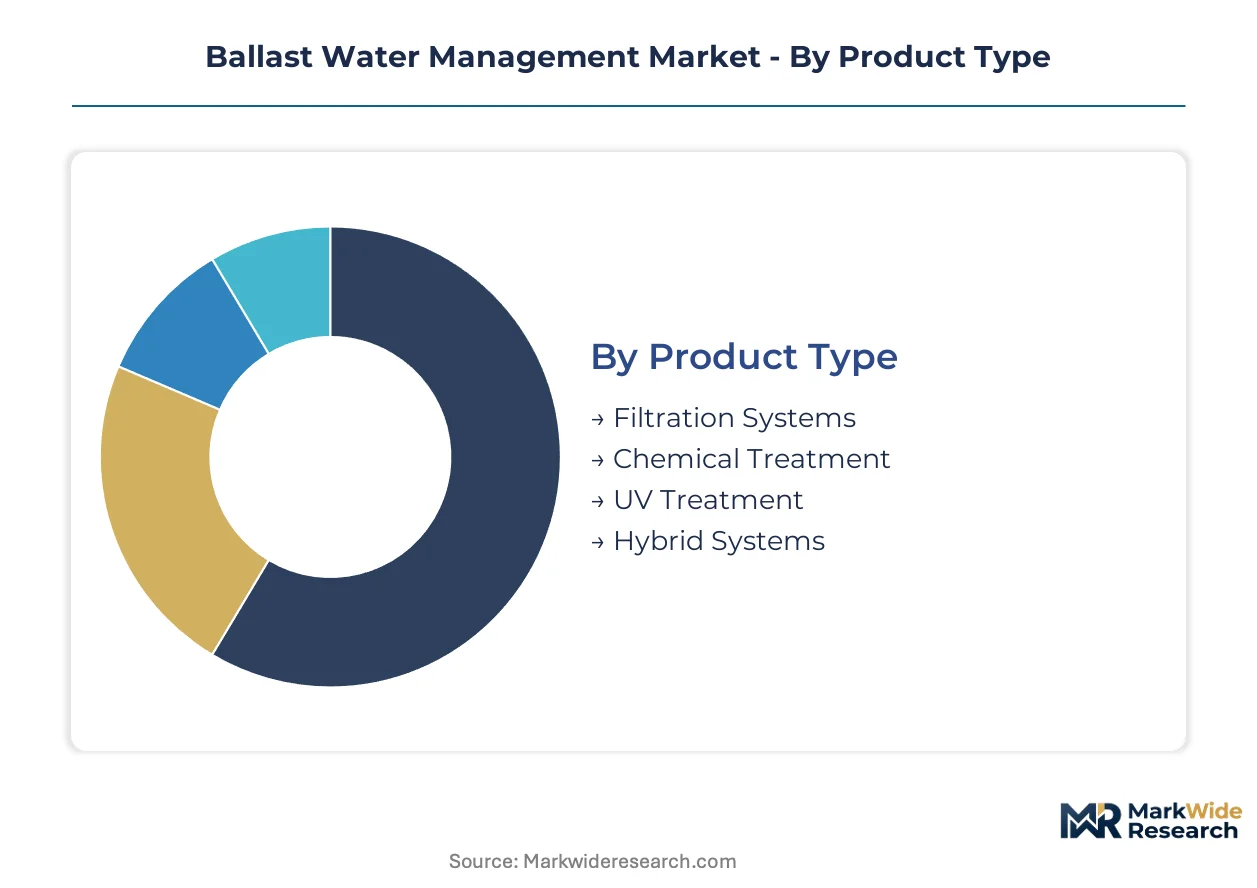
Segmentation in ballast water management reflects divergent compliance pathways across vessel ages, operational profiles, and port-state enforcement intensity. Treatment system selection varies sharply between container fleets with centralized procurement and single-vessel operators navigating fragmented ownership structures.
Product Type:
Mature UV and chemical platforms dominate current installed base, while emerging hybrid configurations address reliability gaps in variable water quality environments.
- Filtration Systems:Physical separation units remove suspended solids and organisms above 50 microns through mesh or hydrocyclone configurations. Bulk carriers operating out of sediment-heavy ports in Indonesia and Brazil specify these as primary stages to protect downstream treatment components.
- Chemical Treatment:Biocide dosing systems neutralize organisms through chlorine-based or peracetic acid solutions, requiring storage tanks and neutralization capabilities. Tanker fleets with generous engine room volume and established chemical handling protocols favor this approach for its independence from water clarity conditions.
- UV Treatment:Ultraviolet irradiation disrupts organism DNA without residual chemical discharge, minimizing port-state documentation burdens.
- Hybrid Systems:Combined filtration-UV or filtration-chemical configurations provide operational redundancy when single-technology performance degrades.
UV Treatment retains volume leadership; Hybrid Systems hold the steepest expansion curve.
End User:
Cost tier differentiation separates capital-intensive fleet operators from regulatory enforcement entities with monitoring mandates but limited procurement authority.
- Shipping Companies:Container lines, tanker operators, and bulk carriers bear direct compliance costs and system performance risk. Singapore-based and Greek fleet owners with dispersed vessel registries face the most complex multi-jurisdiction certification requirements.
- Port Authorities:Hub terminals including Rotterdam, Singapore, and Houston deploy shore-based testing infrastructure to verify incoming vessel compliance. Their investment concentrates in sampling equipment and laboratory capacity rather than shipboard treatment hardware.
- Regulatory Bodies:IMO, US Coast Guard, and EU member state maritime agencies set certification standards and inspection protocols without direct equipment procurement.
- Environmental Agencies:National and regional ecological monitors track invasive species introduction patterns to validate regulatory effectiveness.
Shipping Companies absorb the dominant share of capital deployment; Port Authorities command the most concentrated procurement timelines around enforcement phase-ins.
Technology:
Application context determines technology selection, with vessel route profiles and source water characteristics driving specification divergence.
- Filtration Technology:Strainer and cyclone systems operate without consumables, suiting routes with predictable sediment loads. Operators on fixed liner services with consistent ballast source ports specify these for minimal crew intervention.
- Chemical Disinfection:Active substance dosing achieves biological neutralization independent of UV transmittance, critical for vessels calling at turbid river mouths.
- UV Technology:Medium-pressure lamp arrays deliver dose-calibrated irradiation with automated intensity adjustment based on flow rate and water quality sensors.
- Electrodialysis:Electrically driven ion separation removes salt and organisms simultaneously, though energy consumption limits adoption to vessels with surplus generating capacity.
UV Technology captures the broadest vessel-type applicability; Electrodialysis climbs the fastest among alternative approaches seeking footprint advantages.
Installation Type:
Customer type and vessel age distribution shape installation modality, with fragmented ownership structures complicating retrofit coordination.
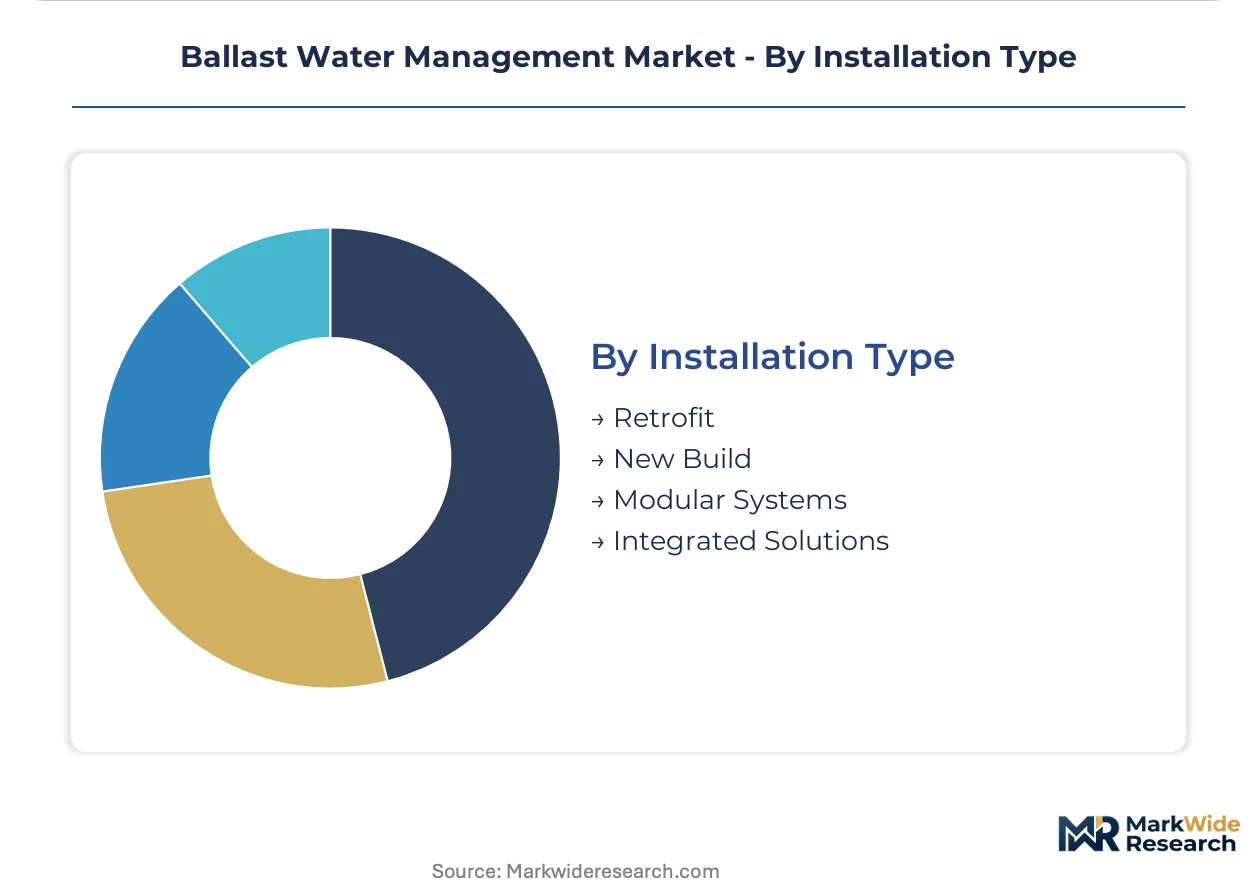
- Retrofit:Installation aboard existing vessels during scheduled dry-dock windows, demanding compact configurations for engine room constraints. Aging tankers with limited access routes require the most customized engineering solutions.
- New Build:Factory-integrated treatment systems specified at construction contract, allowing optimal component placement and reduced installation cost. Korean and Chinese shipyards with high container vessel output dominate this channel.
- Modular Systems:Pre-assembled skid-mounted units minimize shipyard integration time, critical for operators facing compressed port windows. Leasing providers favor these for rapid deployment and redeployment flexibility.
- Integrated Solutions:Treatment hardware bundled with propulsion, automation, or environmental control systems from single suppliers.
Retrofit commands current volume concentration; New Build gains share fastest as orderbook composition shifts toward post-Convention construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IMO compliance deadlines are compressing procurement cycles across major maritime economies, with port-state enforcement intensity determining regional equipment demand patterns. Vessel traffic density and dry-dock capacity constraints shape installation feasibility in each market.
Singapore
Port of Singapore Authority mandates accelerate retrofit volumes for tankers and container vessels calling at the world's busiest transshipment hub. The Maritime and Port Authority of Singapore enforces strict ballast water sampling protocols that exceed baseline IMO requirements. Jurong shipyard clusters concentrate installation capacity, with dry-dock queues extending six months ahead of renewal survey windows.
United States
US Coast Guard type-approval standards exclude several IMO-certified systems, forcing fleet operators to maintain dual-certification inventories for US water access. The EPA administers vessel general permit requirements that layer discharge monitoring obligations atop federal maritime rules. Gulf Coast ports from Houston to New Orleans generate concentrated demand for chemical treatment systems suited to high-turbidity Mississippi River mouth operations.
Germany
Hamburg and Bremerhaven port authorities coordinate EU Marine Strategy Framework Directive compliance with national ballast water inspection regimes. The Federal Maritime and Hydrographic Agency enforces documentation standards that favor UV treatment systems with integrated data logging capabilities. Northern German shipyards specialize in retrofit engineering for aging European tanker fleets facing compressed installation timelines.
China
Ministry of Transport implementation rules for the BWM Convention drive equipment demand across the world's largest shipowning registry. China Maritime Safety Administration inspectors verify treatment system commissioning certificates during port state control examinations. Yangtze River Delta shipyards dominate new-build integration, while Dalian and Guangzhou facilities handle retrofit volumes for domestic-flagged bulk carriers.
Greece
Fragmented vessel ownership structures among Piraeus-based operators complicate fleet-wide compliance coordination for the world's largest tanker registry. The Hellenic Ministry of Maritime Affairs aligns national enforcement with IMO survey schedules while accommodating EU reporting requirements. Aegean and Mediterranean port calls subject Greek-managed fleets to multi-jurisdiction certification demands that favor hybrid system redundancy.
Ballast Water Management Market Vendor Landscape
Channel-controlling players compete with product-specialist players for positioning across installation, service, and equipment procurement touchpoints. Market structure shows moderate consolidation around integrated marine engineering groups with port service networks, while UV technology specialists and chemical treatment providers occupy distinct technology lanes. Two strategic archetypes dominate: full-service marine integrators bundling treatment with propulsion overhauls, and compact-system specialists targeting constrained engine room footprints. Competitive moves center on project finance leasing partnerships and hybrid system portfolio expansion.
Within the integrated systems tier, Wärtsilä and Alfa Laval represent channel-controlling players leveraging established marine service networks. Optimarin occupies a position among compact-system specialists. These three companies exemplify the divergence between full-service bundling strategies and focused technology specialization.
| Leading Market Players |
|---|
| Alfa Laval |
| Wärtsilä |
| Veolia Water Technologies |
| Evoqua Water Technologies |
| Optimarin |
| Ecochlor |
| Hyde Marine |
| PanAsia Co., Ltd. |
| Headway Technology Group |
| Others |
Supply Flow & Price Mechanics
Jurong shipyard clusters in Singapore concentrate retrofit installation capacity, with six-month dry-dock queues compressing procurement timelines and amplifying pricing power for qualified marine engineering firms serving IMO compliance deadlines.
Pricing Analysis
Certification level (IMO/USCG dual-approval versus single-jurisdiction) creates the primary spread between system tiers, with USCG-type-approved units commanding substantial premiums over IMO-only configurations. Project-based pricing dominates as operators bundle treatment installations with scheduled dry-dock maintenance, while leasing providers embed service guarantees into operating-expense structures. Price erosion runs through standard UV systems as Chinese manufacturers expand certified product portfolios. Small fleet operators with fragmented vessel registries exhibit highest price sensitivity, whereas major container lines prioritize uptime guarantees over capital cost minimization.
Supply Chain Analysis
Tariff exposure between China and major shipowning jurisdictions dominates supply chain risk planning for UV lamp arrays and filtration membranes. Component sourcing concentrates in China, Germany, and South Korea, with medium-pressure UV lamps and titanium-grade filtration housings drawing from specialized electrochemical and precision manufacturing clusters. Single-source vulnerability persists for USCG-certified control systems with limited qualified suppliers. Distribution runs through shipyard-integrated procurement channels and third-party lessors with rapid-deployment logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation among Greek and Singapore-based shipowners concentrates procurement authority, shifting bargaining power toward volume buyers and squeezing margin structures for undifferentiated equipment suppliers.
For Market Incumbents: Pre-empt leasing-provider encroachment by embedding performance guarantees into direct equipment sales, converting transactional revenue into recurring service streams. Secure backward integration into UV lamp manufacturing to defend margin position against Chinese component suppliers. Expand Jurong and Hamburg service depot capacity ahead of renewal survey peaks. For New Entrants and Emerging Players: Modular skid-mounted systems for compressed dry-dock windows represent the most penetrable entry point, targeting mid-size tanker operators with aging fleets and constrained engine room footprints. Partner with third-party lessors to bypass capital-intensive direct sales cycles and accelerate fleet penetration through operating-lease structures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among leasing providers with embedded service contracts and port-based maintenance networks. Long-term viability favors acquisition targets with USCG-type-approved hybrid system portfolios spanning multiple vessel classes. Monitor IMO renewal survey completion rates as the inflection indicator for installation capacity utilization.| Strategic Initiative | Industry Significance |
|---|---|
| Project Finance Leasing Expansion | Third-party lessors absorb upfront capital requirements for Greek and Singapore-based fleet operators. |
| Hybrid System Portfolio Development | Combined filtration-UV configurations address variable water quality across Mediterranean and Baltic routes. |
| USCG Type-Approval Investment | Dual-certification unlocks access to Gulf Coast ports with high-turbidity Mississippi River operations. |
| Port Service Network Densification | Jurong and Hamburg depot expansion reduces vessel downtime during compressed retrofit windows. |
| Digital Compliance Integration | Real-time sensor platforms automate documentation for EU Marine Strategy Framework Directive reporting. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of IMO type-approval databases, USCG certification registries, and port state control inspection records. Primary interviews engaged fleet technical managers, shipyard procurement officers, classification society surveyors, and leasing provider risk officers across Singapore, Hamburg, and Piraeus. Secondary sources included Lloyd's List vessel tracking data, Maritime and Port Authority of Singapore enforcement statistics, and EU Marine Strategy Framework Directive implementation reports. Bottom-up equipment deployment estimates triangulated against top-down fleet compliance projections.
Forecast inputs include vessel renewal survey schedules, dry-dock capacity utilization at major shipyard clusters, and phased IMO enforcement timelines across flag state registries. Segmentation modeling spans product type, vessel class, installation modality, and regional regulatory cluster. CAGRs derive from equipment procurement cycle compression and new-build orderbook composition shifts. Industry-specific inputs incorporate ballast water discharge standard stringency indices and port state control detention rates for non-compliant vessels.
Macroeconomic conditions sit as an overlay; deviation in marine freight rates, shipyard labor costs, or stainless steel commodity prices would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement continuity and type-approval protocol stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Engines Market
Marine
Marine Turbocharger Market
Marine
Marine Chronometers Market
Marine
Marine Lighting Market
Marine
Ship/Boat Keel Market
Marine
North Sea Offshore Support Vessels Market
Marine
Marine Exhaust Systems Market
Marine
North America Naval Vessels Market
Marine
Hydraulic Marine Cranes Market
Marine
Boat Steering Systems Market
Marine
Steel Ship Plate Market
Marine
Submarine Propulsion Systems Market
Marine
Yacht Shell Doors Market
Marine
Ship Rudders Market
Marine
Electric Ship Market
Marine
Unmanned Marine Vehicles Market