
 Air Compressors on Ships Market | 2026-2036
Air Compressors on Ships Market Size, Share, and Industry Trends Forecast 2026-2036
Air Compressors on Ships Market Insights
Multi-source procurement for marine compressed air systems is broadening as fleet operators reduce dependency on single OEM service networks. Sauer Compressors leverages its German engineering heritage to dominate naval and specialized vessel segments. Atlas Copco sustains global reach through distributed service hubs near major shipping lanes. Kaeser competes on energy efficiency metrics that align with rising fuel cost pressures.
An air compressor on ships is a mechanical device that pressurizes atmospheric air to deliver compressed air for starting diesel engines, operating pneumatic control systems, and powering deck machinery; rotary screw compressors typically achieve discharge pressures of 30 bar for main engine starting applications. Rotary screw compressors lead the product type category due to continuous duty cycles and minimal vibration profiles suited to engine room constraints. Cargo handling systems represent the fastest-growing application segment as automated container cranes and pneumatic conveying systems expand on newbuild vessels. Fixed mount installations anchor the installation type mix, though bulkhead mounted units gain share in space-optimized naval architectures.
The International Maritime Organization enforces MARPOL Annex VI emission standards that compel engine upgrades requiring compatible starting air systems. ISO 8573 air quality classes govern oil and moisture content for instrumentation air, while classification societies including Lloyd's Register and DNV GL certify compressor installations for seaworthiness. Stakeholders must monitor how ammonia and methanol dual-fuel engine architectures alter compressed air demand profiles for fuel injection and purge systems.
Market Dynamics
Fleet decarbonization mandates are forcing compressed air system redesigns as dual-fuel ammonia and methanol engines demand higher-pressure purge and injection air circuits.
Growth Catalysts
- IMO 2020 Sulfur Regulations:EEDI compliance deadlines accelerate vessel replacement cycles, expanding newbuild compressor installations across container and tanker fleets.
- Subsea Operations:Offshore support vessels now require 300-bar high-pressure systems for well intervention and ROV deployment, lifting specification floors.
- South Korean Shipbuilding:Hyundai Heavy Industries and Samsung Heavy Industries concentrate global newbuild output, anchoring compressor procurement volumes.
Market Restraints
- Specialized Alloy Costs:Corrosion-resistant materials for seawater-cooled intercoolers face nickel and titanium price volatility, pressuring margin structures.
- Single-Source Dependencies:Precision screw rotor machining capacity concentrates in German and Japanese tool shops, creating supply bottlenecks.
- Air Quality Certification Friction:ISO 8573 Class 0 oil-free compliance requires redundant filtration stages that extend commissioning timelines.
Strategic Opportunities
- Indian Ship Repair Hubs:Alang-Sosiya and Cochin Shipyard expansion creates aftermarket retrofit demand for legacy starting air systems.
- Digital Condition Monitoring:Vibration and oil-analysis telemetry convergence enables predictive maintenance contracts with fleet operators.
- EU Green Deal Funding:Innovation grants for zero-emission vessels subsidize electric compressor retrofits on short-sea shipping routes.
Industry Challenges
- Marine Refrigeration Technician Shortage:Specialized compressor overhaul skills gap lengthens mean-time-to-repair in remote port locations.
- Legacy Pneumatic Integration:Hybrid automation architectures struggle to synchronize new variable-speed compressors with existing 30-bar receiver networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Compressors on Ships Market |
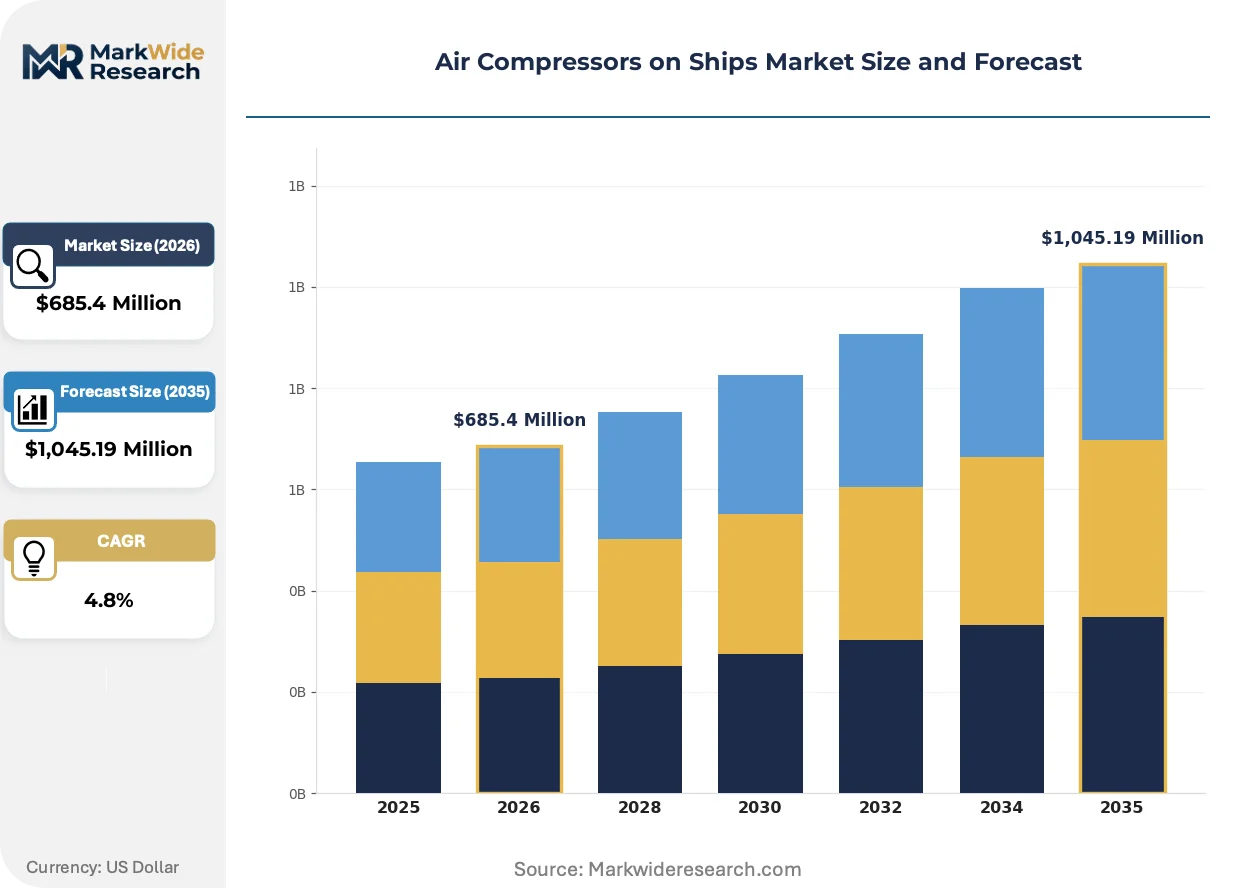
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Compressors, Rotary Screw Compressors, Centrifugal Compressors, Diaphragm Compressors Application: Engine Starting, Cargo Handling Systems, Ballast Operations, Shipboard Maintenance Installation Type: Fixed Mount, Portable Units, Deck Mounted, Bulkhead Mounted End User: Shipyards, Offshore Support Vessels, Passenger Liner Operators, Freight Vessel Companies |
| Companies Covered | Sauer Compressors, Atlas Copco, Kaeser, Ingersoll Rand, Sperre, Tanabe, Hatlapa (MacGregor), Kobelco, Burckhardt Compression, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Compressors on Ships Market Trends and Innovations
Compressed air technology is bifurcating between ultra-high-pressure subsea applications and energy-optimized variable-speed systems for dual-fuel engine support.
Permanent magnet motor technology is electrifying rotary screw compressor drivetrains by eliminating gearbox losses and enabling precise pressure modulation. Container lines including Maersk and MSC specify these units for methanol-ready newbuilds to cut electrical load peaks. The shift is compressing demand for traditional fixed-speed induction motor packages in the 75-250 kW range.
REACH chemical restrictions on per- and polyfluoroalkyl substances are phasing out fluoropolymer compressor coatings used in oil-free scroll designs. Equipment manufacturers reformulate rotor chamber surfaces with ceramic plasma sprays to maintain wear resistance. European compressor OEMs face compressed certification timelines as ECHA substance evaluations accelerate.
Ship operators now unbundle compressor maintenance from OEM service contracts, procuring spare parts and technical labor through independent marine engineering firms. Greek and Singapore-based fleet managers lead this disintermediation, establishing direct relationships with component suppliers for valve kits and separator elements. The pattern concentrates in the Mediterranean and Southeast Asia hub ports where third-party technical services cluster.
Air Compressors on Ships Market Segmentation
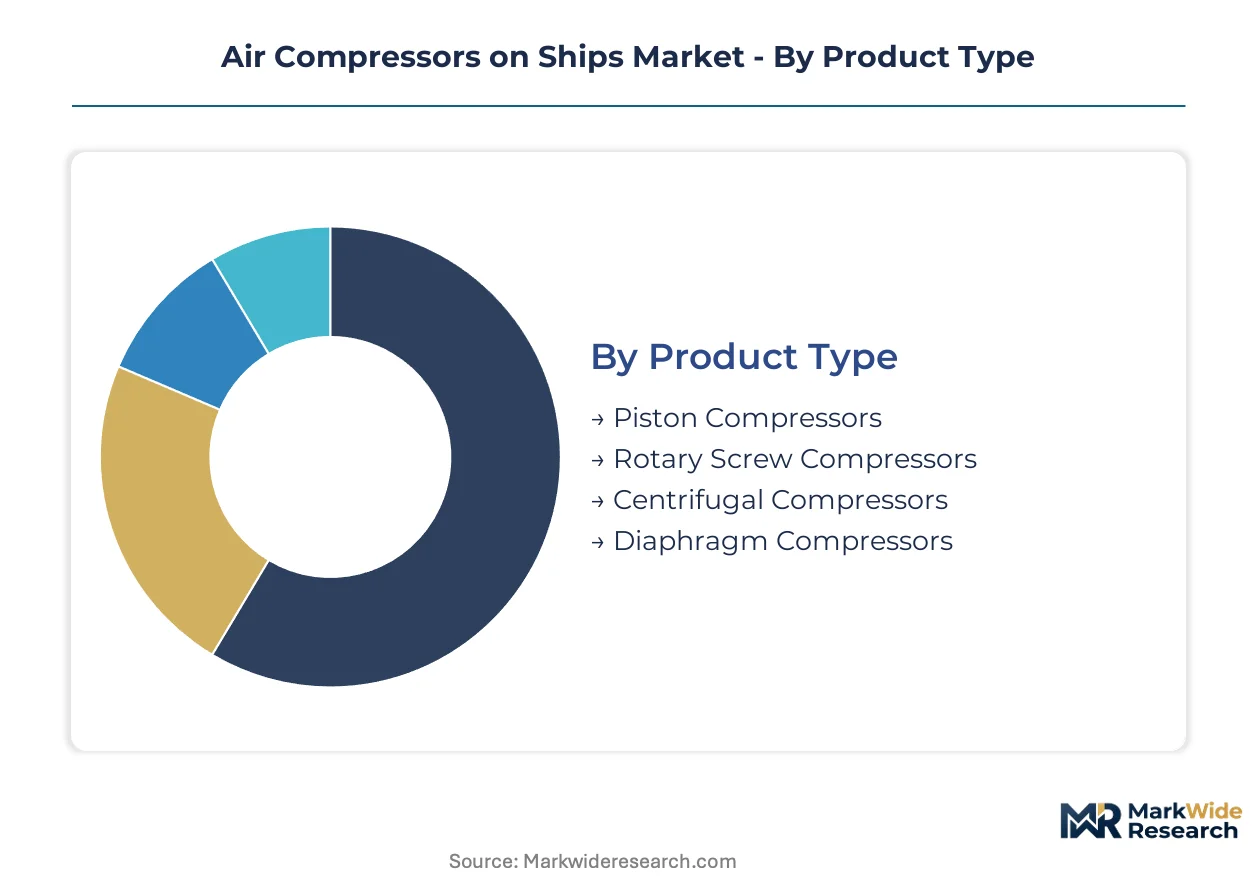
Compressed air system specifications diverge sharply across vessel types and operational profiles. Ship operators configure compressor architectures around duty cycles, space constraints, and regulatory compliance tiers that vary by trade route and flag state.
Product Type:
Capital intensity peaks with centrifugal and high-pressure diaphragm systems requiring precision-machined components and exotic alloys.
- Rotary Screw Compressors:Continuous-duty helical rotors deliver 30 bar discharge pressures with minimal vibration, suiting engine room installations where space is constrained. Container lines including Maersk specify these for methanol-ready newbuilds to manage electrical load profiles.
- Piston Compressors:Reciprocating designs dominate legacy fleet retrofits and smaller coastal vessels where intermittent duty cycles suffice. Greek and Singapore-based fleet managers source spare parts through independent marine engineering firms to bypass OEM service contracts.
- Centrifugal Compressors:Dynamic compression suits large LNG carriers and cruise ships with high-volume, oil-free air demands for instrumentation systems.
- Diaphragm Compressors:Hermetically sealed designs serve chemical tankers and gas carriers where contamination risks preclude lubricated alternatives.
Rotary screw compressors absorb the bulk of installed capacity; diaphragm compressors are expanding most quickly on specialized gas carriers.
Application:
Operational criticality varies by whether compressed air failure triggers propulsion loss or merely delays cargo operations.
- Engine Starting:High-pressure 30 bar systems represent the most capital-intensive installation, requiring redundant receivers and automatic sequencing controls. IMO MARPOL Annex VI engine upgrade mandates force compatibility verification with existing starting air architectures.
- Cargo Handling Systems:Automated container cranes and pneumatic conveying systems on newbuild vessels drive specification floors for flow rate and pressure stability. South Korean yards anchor procurement volumes for these integrated systems.
- Ballast Operations:Lower-pressure compressed air powers ballast water treatment system backflushing and tank stripping on bulk carriers.
- Shipboard Maintenance:General service air for pneumatic tools and painting operations commands the lowest specification tier across all vessel categories.
Engine starting retains the largest installed base; cargo handling systems command the steepest expansion trajectory as automation spreads.
Installation Type:
Mounting configurations trade service accessibility against structural integration and shock resistance.
- Fixed Mount:Bolted installations with dedicated foundations dominate commercial shipping where machinery spaces permit permanent allocation. These configurations simplify piping runs and vibration isolation.
- Portable Units:Mobile compressors serve shipyard construction phases and emergency redundancy requirements on offshore support vessels.
- Deck Mounted:Weatherized enclosures expose equipment to salt spray but free interior volume for revenue-generating cargo or passenger spaces.
- Bulkhead Mounted:Space-optimized naval architectures and specialized research vessels favor this configuration to maximize machinery density.
Fixed mount installations anchor the current fleet; bulkhead mounted units gain share in space-constrained designs.
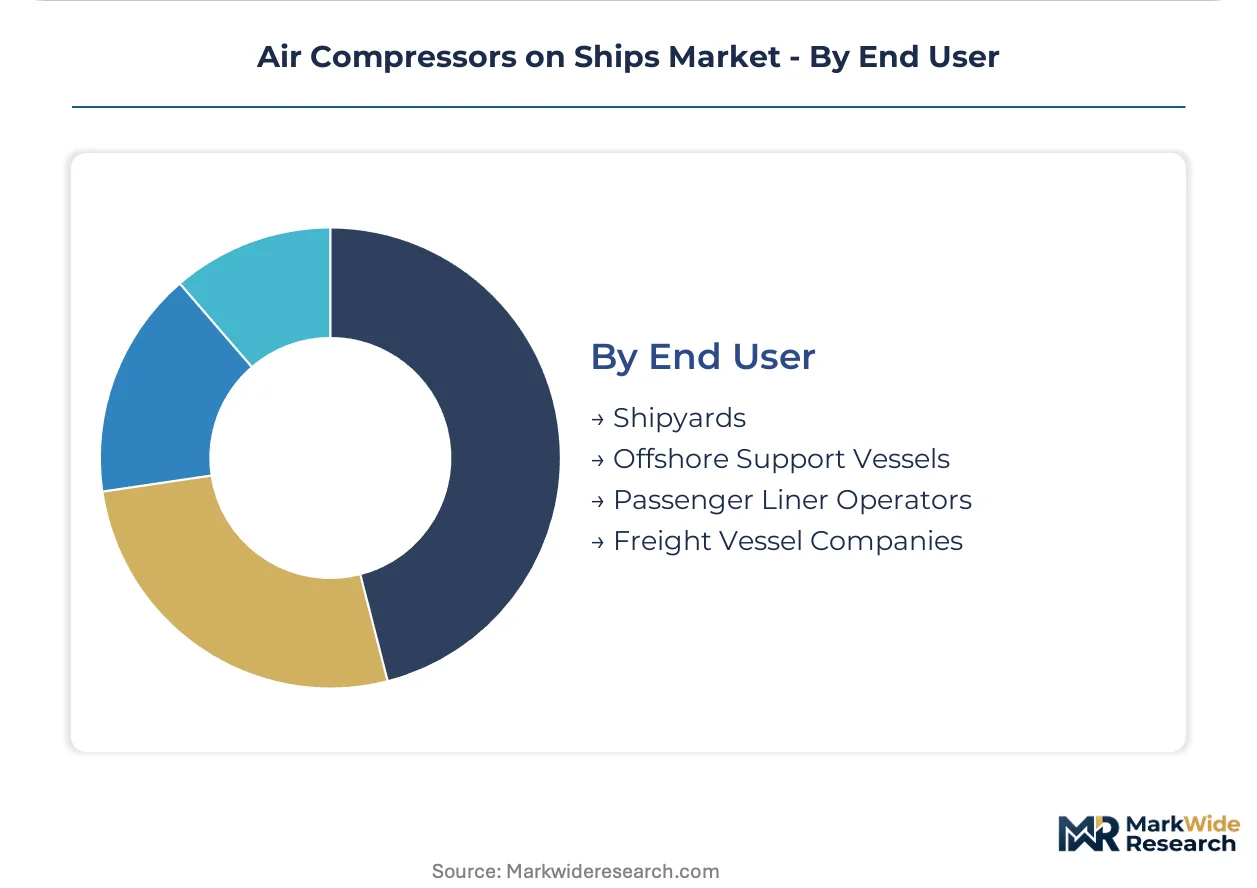
End User:
Procurement authority and lifecycle cost horizons diverge between asset owners and construction yards.
- Shipyards:Hyundai Heavy Industries and Samsung Heavy Industries concentrate newbuild specification authority, driving standardization toward rotary screw architectures with integrated control systems.
- Freight Vessel Companies:Container and tanker operators prioritize energy efficiency metrics that align with rising fuel cost pressures and EEDI compliance deadlines.
- Offshore Support Vessels:Well intervention and ROV deployment demand 300-bar high-pressure systems that lift specification floors beyond conventional merchant marine practice.
- Passenger Liner Operators:Cruise lines emphasize redundancy and noise attenuation to maintain guest experience standards during compressor maintenance windows.
Shipyards control newbuild procurement volumes; offshore support vessels drive the fastest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipbuilding output concentrates in South Korea, where Hyundai Heavy Industries and Samsung Heavy Industries anchor global newbuild compressor procurement volumes. Fleet renewal cycles and EEDI compliance mandates drive specification escalation across major maritime economies.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries concentrate global newbuild output, anchoring rotary screw compressor procurement for methanol-ready container vessels. The Korea Register of Shipping certifies starting air systems under its naval architecture rules. Ulsan and Geoje shipbuilding clusters integrate high-pressure compressed air architectures for dual-fuel ammonia engines.
China
State-owned shipyards expand LNG carrier and offshore support vessel construction, lifting demand for centrifugal and high-pressure diaphragm systems. MIIT enforces GB standards for marine machinery emissions that cascade into compressor efficiency requirements. Shanghai and Dalian maritime clusters retrofit legacy fleets with variable-speed electric compressors to meet port emission control area rules.
Japan
Japanese shipbuilders specialize in gas carriers and chemical tankers requiring hermetically sealed diaphragm compressors for contamination-sensitive cargo operations. METI subsidizes zero-emission vessel development through its Green Innovation Fund. Nagoya and Kobe industrial corridors concentrate precision machining capacity for screw rotor components.
Germany
German engineering heritage dominates naval and specialized vessel compressor segments through precision-machined screw rotor technology. ECHA REACH restrictions on fluoropolymer coatings force ceramic plasma spray reformulation in oil-free scroll designs. Hamburg and Bremen port clusters unbundle maintenance contracts, enabling independent marine engineering firms to source valve kits and separator elements directly.
United States
Offshore support vessel operators in the Gulf of Mexico deploy 300-bar high-pressure systems for well intervention and ROV deployment. EPA marine diesel engine standards drive compatibility verification between upgraded propulsion systems and existing starting air architectures. Houston and New Orleans service hubs concentrate aftermarket retrofit demand for legacy pneumatic control networks.
Air Compressors on Ships Market Competitive Landscape
Capacity expansion dominates the current landscape as compressor OEMs establish distributed service hubs near major shipping lanes. The vendor base stratifies across three tiers: German-engineered specialists serving naval contracts, Scandinavian-heritage suppliers with offshore equipment expertise, and diversified industrial conglomerates with global aftermarket networks. Two strategic archetypes define positioning: precision-machining specialists controlling screw rotor supply chains, and energy-efficiency optimizers targeting EEDI compliance deadlines. Geographic expansion and technology licensing represent the dominant competitive moves, with particular emphasis on Indian and Southeast Asian ship repair hubs.
Among German-engineered specialists, Sauer Compressors and Burckhardt Compression exemplify the precision-machining archetype, anchoring naval and high-pressure subsea segments where rotor tolerances determine reliability. Atlas Copco occupies a position as the diversified industrial conglomerate, sustaining global reach through service density rather than manufacturing concentration. Kaeser represents the energy-efficiency optimization vector, competing on metrics that align with rising fuel cost pressures and electrical load management requirements for dual-fuel newbuilds.
| Leading Market Players |
|---|
| Sauer Compressors |
| Atlas Copco |
| Kaeser |
| Ingersoll Rand |
| Sperre |
| Tanabe |
| Hatlapa (MacGregor) |
| Kobelco |
| Burckhardt Compression |
| Others |
Pricing and Supply Chain Analysis
Permanent magnet motor electrification of rotary screw drivetrains is compressing cost structures for variable-speed compressor architectures while simultaneously concentrating procurement leverage among South Korean shipyards that specify these systems for methanol-ready newbuilds. This technological shift tightens margin structures for fixed-speed induction motor suppliers and redirects supply chain investment toward precision-machined rotor components.
Pricing Analysis
Warranty and aftermarket service bundling now separates premium OEM contracts from unbundled procurement patterns led by Greek and Singapore-based fleet managers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and geographic delivery cost variation. Cost compression in the standard tier is intensifying because REACH chemical restrictions force ceramic plasma spray reformulation investments. Freight vessel companies exhibit the highest price sensitivity due to EEDI compliance cost burdens, while naval contractors accept premium pricing for traceability and redundant filtration stages.
Supply Chain Analysis
Precision screw rotor machining capacity rests on German and Japanese specialty tool shops, creating single-source vulnerability for this critical input. Nickel and titanium for corrosion-resistant intercooler alloys draw from concentrated mining jurisdictions, while ceramic plasma spray feedstocks feed from European chemical suppliers. Distribution runs through shipyard-integrated procurement channels at Hyundai Heavy Industries and Samsung Heavy Industries, with independent marine engineering firms capturing growing aftermarket share in Mediterranean and Southeast Asian hub ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH chemical restrictions and ISO 8573 Class 0 certification requirements force capital-constrained competitors toward exit or acquisition.
For Market Incumbents: Lock in rotor machining capacity through long-term tool shop partnerships or captive supply arrangements to defend against Japanese precision component suppliers. Deepen backward integration into ceramic plasma spray coating technology before ECHA substance evaluations accelerate. Control service network density near Alang-Sosiya and Cochin Shipyard to capture Indian retrofit demand before independent marine engineering firms consolidate this channel. For New Entrants and Emerging Players: EU Green Deal funding in European short-sea shipping routes opens a window for electric compressor retrofit specialists lacking legacy fixed-speed induction motor portfolios. Target offshore support vessel high-pressure segments where 300-bar specification floors exceed capabilities of diversified industrial conglomerates. Enter through predictive maintenance software partnerships with fleet operators seeking to unbundle OEM service contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking naval and specialized vessel segment exposure. Five-to-ten year viability favors precision-machining specialists with captive rotor supply and energy-efficiency optimizers with permanent magnet motor integration. Watch ammonia dual-fuel engine architecture adoption rates as the inflection signal for compressed air demand profile shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Machining | Captive screw rotor production insulates Sauer Compressors and Burckhardt Compression from Japanese tool shop bottlenecks. |
| Permanent Magnet Motor Platform Launch | Atlas Copco and Kaeser target methanol-ready newbuild specifications at Hyundai Heavy Industries and Samsung Heavy Industries. |
| Indian Ship Repair Hub Expansion | Alang-Sosiya and Cochin Shipyard aftermarket presence captures legacy fleet retrofit demand from Greek and Singapore-based operators. |
| Predictive Maintenance Software Partnership | Vibration telemetry convergence enables fleet operator disintermediation of OEM service contracts in Mediterranean ports. |
| Ceramic Plasma Spray Certification | ECHA REACH compliance investment separates oil-free scroll suppliers from fluoropolymer-dependent competitors facing phase-out. |
Research Methodology
Multi-period observation of shipyard order backlogs, fleet renewal cycles, and compressor specification trends anchored the trend analysis, supplemented by interviews with marine engineering directors, shipyard procurement managers, fleet technical superintendents, and classification society surveyors. Secondary validation drew from Lloyd's Register and DNV GL certification databases, Korea Register of Shipping naval architecture rules, IMO MARPOL Annex VI filings, and customs records of marine machinery imports. Bottom-up vessel-type demand modeling and top-down shipbuilding output triangulation cross-verified market sizing.
Segment-weighting across product type, application, installation configuration, and end-user category structured the analytical framework over the projection horizon. Rotary screw, piston, centrifugal, and diaphragm compressor architectures were modeled separately with diverging duty cycle and pressure specifications. CAGRs derived from shipbuilding output correlations with EEDI compliance deadline clustering and dual-fuel engine adoption curves. Forecast inputs incorporated South Korean yard concentration, nickel price volatility coefficients, and technician shortage impact on mean-time-to-repair assumptions.
The model assumes a particular technology adoption path; alternative pathways for ammonia fuel injection air demand would alter the outlook if methanol architectures dominate dual-fuel newbuilds instead. Forecasts reflect assumptions about REACH enforcement timelines and classification society certification harmonization. Regulatory acceleration in EU Green Deal funding or IMO sulfur regulation tightening represents specific revision triggers. A small set of named triggers—ammonia engine architecture adoption rates, Indian ship repair hub expansion velocity, and fluoropolymer coating phase-out compliance costs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Offshore Support Vessel Service Market
Maritime Equipment
Marine Hatch Covers Market
Maritime Equipment
United States Maritime Information Market
Maritime Equipment
Asia-Pacific Maritime Satellite Communication Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Latin America Offshore Support Vessels Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
Saudi Arabia Offshore Support Vessel (OSV) Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Ship Anchor Market