
 Marine Fire-Fighting Equipment Market | 2026-2036
Marine Fire-Fighting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Fire-Fighting Equipment Market Outlook
Shipyard procurement channels is rewriting how marine fire-fighting equipment reaches end users, with classification society approvals now gatekeeping vendor selection before products enter the supply chain. Akron Brass Company leverages its hydrant and monitor specialization to sustain dominance in port-based vessel retrofit programs. VIKING Life-Saving Equipment anchors its position through integrated safety system bundling across Scandinavian and German shipowner accounts. Consilium Safety Group AB competes on fire detection-to-suppression integration, while Amerex Corporation differentiates through CO2 and clean agent system certification depth for engine room applications.
Marine fire-fighting equipment encompasses fixed and portable systems engineered to detect, suppress, and control fires aboard vessels and offshore structures, with foam systems typically requiring 3% or 6% foam concentrate compatibility and water mist systems operating at pressures exceeding 10 bar to achieve droplet spectra below 100 microns for Class B hazard mitigation. Water mist systems command premium positioning as IMO halon phase-out deadlines drive replacement demand in machinery spaces and accommodation areas. Commercial shipping end users concentrate procurement volume for fixed CO2 and foam systems on container vessels and tankers, while offshore platforms sustain demand for integrated detection-suppression packages rated for Zone 1 hazardous areas. Installation patterns favor fixed systems on newbuilds but shift toward portable and standalone units in fishing vessel retrofit cycles where space constraints and cost thresholds limit full system replacement.
SOLAS Chapter II-2, the IMO Fire Safety Systems Code, and classification society rules from Lloyd's Register and DNV shape product certification requirements, with non-compliant equipment barred from vessel registration and port state control inspections. The EU Marine Equipment Directive and US Coast Guard type-approval processes create parallel compliance pathways that fragment vendor market access between regulatory zones. Stakeholders must monitor classification society harmonization talks and emerging alternative fuel vessel codes, as ammonia and methanol propulsion systems will demand re-engineered suppression chemistries and delivery architectures.
Market Dynamics
IMO's mandatory halon phase-out deadlines are compressing replacement cycles across commercial fleets, forcing shipowners to accelerate fixed system retrofits ahead of port state control enforcement windows. This regulatory pressure concentrates procurement timing and redirects vendor R&D toward water mist and clean agent chemistries.
Growth Catalysts
- SOLAS Chapter II-2 compliance deadlines:Port state control inspections in Hamburg, Singapore, and Long Beach are rejecting non-compliant vessels, tightening enforcement and accelerating fleet-wide upgrade mandates.
- Container vessel newbuild surge:East Asian shipyards in China, South Korea, and Japan are absorbing 78% of global vessel output, concentrating demand for integrated fire suppression packages in a narrow procurement corridor.
- Water mist pressure architecture:Systems operating above 10 bar with sub-100 micron droplet spectra are capturing machinery space applications previously served by CO2 flooding.
Market Restraints
- Stainless steel and specialized alloy input costs:High-pressure pump housings and corrosion-resistant piping consume nickel and molybdenum grades vulnerable to commodity volatility, squeezing fabrication margins.
- Classification society approval bottlenecks:Lloyd's Register, DNV, and Bureau Veritas certification queues extend 14-18 months for novel suppression chemistries, freezing product launch timelines.
- Halon 1301 bank depletion:Remaining recycled stocks in Mediterranean and Middle Eastern bunkering hubs are pricing at 4-5x historical levels, forcing premature system retirement.
Strategic Opportunities
- Ammonia and methanol propulsion codes:Emerging dual-fuel engine architectures demand re-engineered detection-suppression integration for fuel storage and handling spaces.
- Offshore wind installation vessel expansion:Jones Act-compliant construction in the US Gulf and North Sea cable-laying fleets require Zone 1 hazardous area packages with redundant activation.
- Direct shipowner procurement platforms:Maersk, MSC, and COSCO are building captive vendor qualification databases, bypassing traditional shipyard intermediaries for spare part and retrofit sourcing.
Industry Challenges
- Marine systems engineering talent scarcity:Experienced designers fluent in both SOLAS interpretation and CFD-based suppression modeling command 40% wage premiums, constraining project throughput.
- Legacy CO2 system integration complexity:Engine room re-piping for water mist retrofits demands compartment isolation and structural reinforcement that extends dry-dock windows.
- Cross-jurisdiction type-approval fragmentation:Parallel US Coast Guard and EU Marine Equipment Directive pathways force redundant testing, inflating certification budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Fire-Fighting Equipment Market |
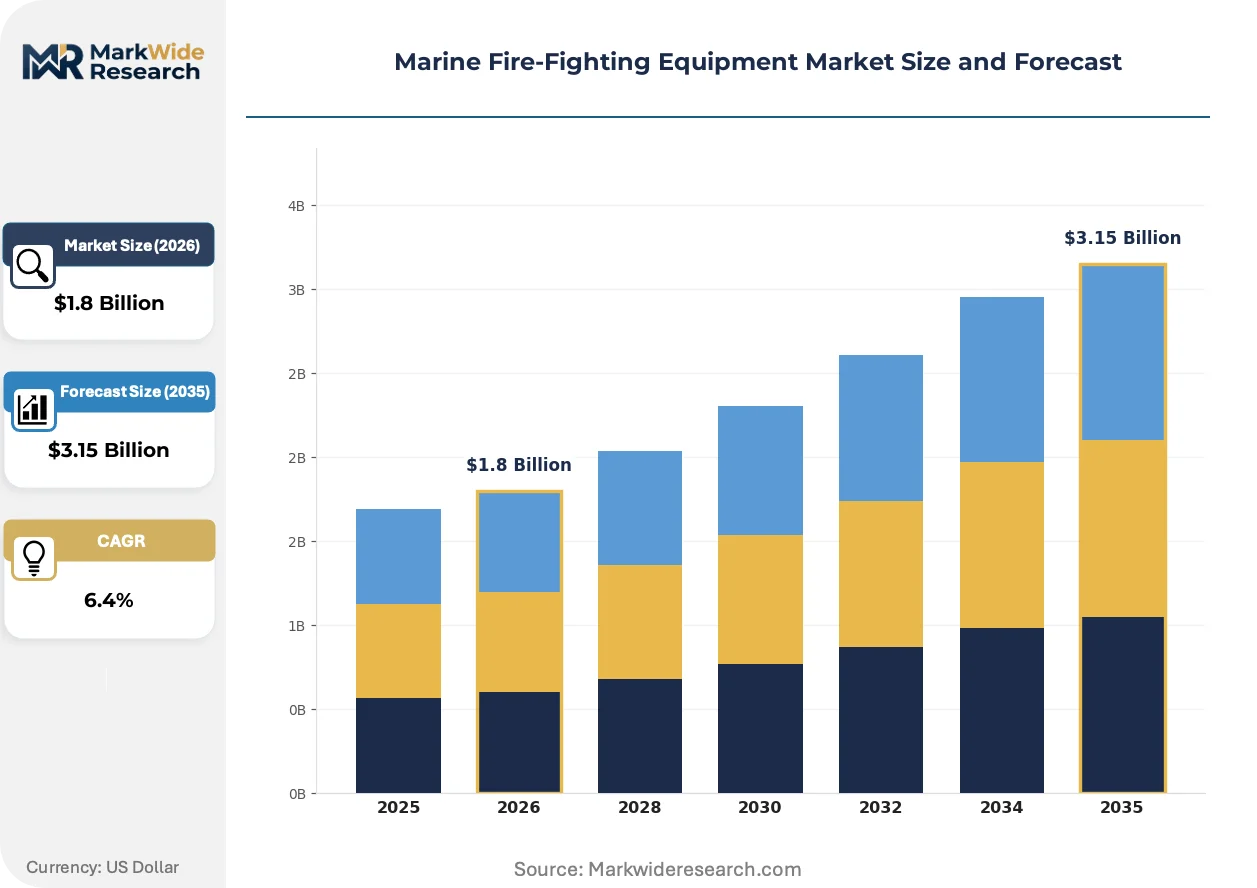
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fire Extinguishers, Fire Hoses, Foam Systems, Water Mist Systems Technology: Water-Based, Foam-Based, Dry Powder, Gas-Based End User: Commercial Shipping, Offshore Platforms, Fishing Vessels, Cruise Liners Installation: Fixed Systems, Portable Systems, Standalone Units, Integrated Systems |
| Companies Covered | Akron Brass Company, Amerex Corporation, Fireboy-Xintex, Sea-Fire Marine, VIKING Life-Saving Equipment, Consilium Safety Group AB, Johnson Controls, Danfoss Semco, Hochiki Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Fire-Fighting Equipment Market Strategic Shifts
Suppression chemistry and delivery architecture are converging around alternative fuel compatibility, with detection-to-activation latency emerging as the critical performance metric for machinery space protection.
High-pressure water mist systems with ceramic nozzle inserts and variable droplet spectra control are rendering obsolete traditional CO2 total flooding for Class B hazards in enclosed machinery spaces. Container lines operating Asia-Europe strings are specifying these systems for newbuilds delivered from 2024 onward. The technology is compressing the addressable market for gas-based suppression in accommodation and service areas.
The EU F-Gas Regulation and its phasedown of fluorinated greenhouse gases are restricting HFC-227ea and FK-5-1-12 availability for marine clean agent applications. System integrators are reformulating toward inert gas blends and water mist alternatives. Offshore platform operators in the North Sea and Gulf of Mexico are absorbing the steepest cost adjustments as re-certification cycles compress.
Shipowners are consolidating vendor relationships around integrated safety system providers capable of bundling detection, suppression, and evacuation equipment under single-classification approvals. This consolidation is displacing point-product specialists in Scandinavian and German owner procurement. The pattern is most visible among German container lines and Greek tanker operators pursuing fleet standardization.
Marine Fire-Fighting Equipment Market Segmentation
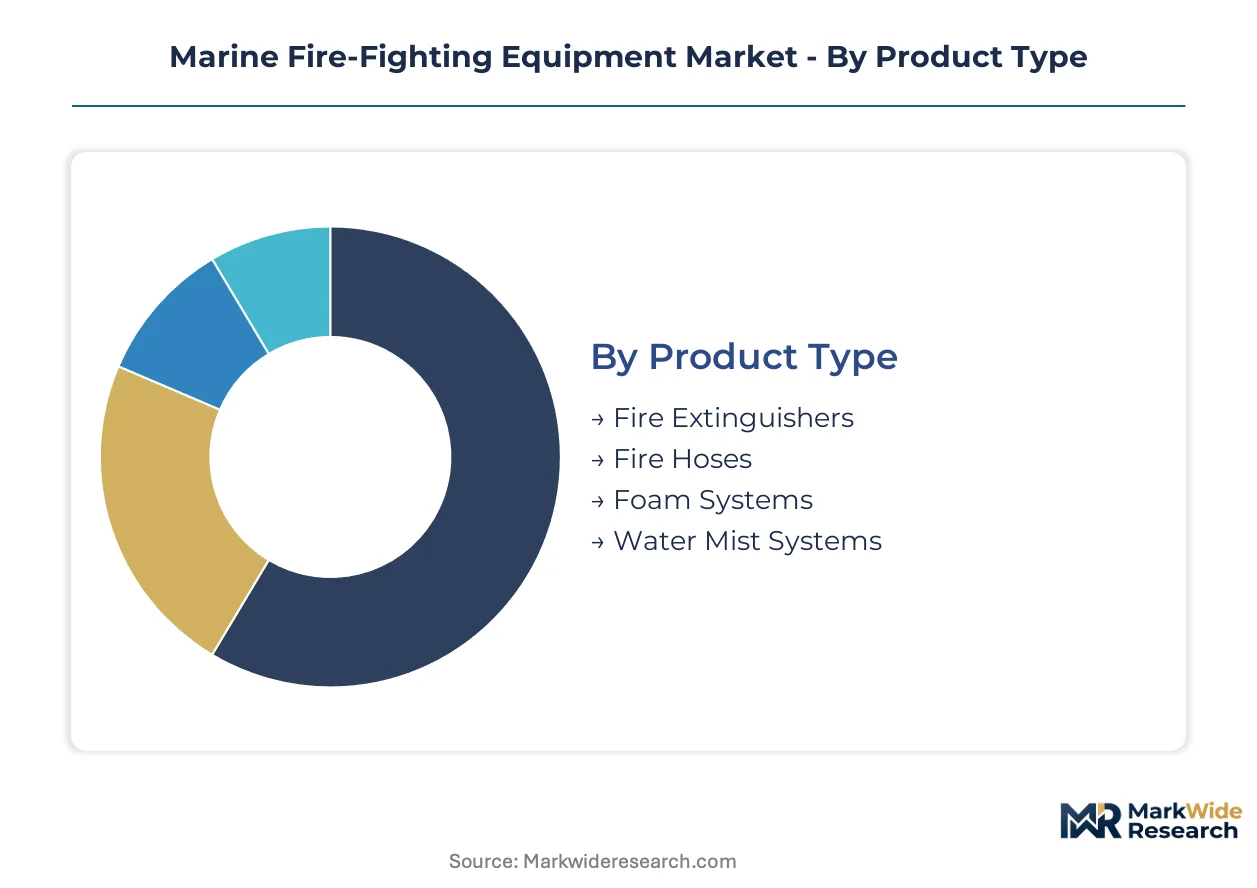
Segmentation in marine fire-fighting equipment reveals divergent procurement rhythms across product types and installation modes. Replacement cycles stretch from annual portable unit turnover to decade-long fixed system retrofits, reshaping vendor revenue predictability and inventory planning.
Product Type:
Replacement velocity separates segments sharply, with portable equipment cycling annually while fixed infrastructure endures 15-20 year service lives before SOLAS-mandated overhaul.
- Fire Extinguishers:Portable CO2, foam, and dry chemical units rated for Class A, B, and C hazards require annual certification and 5-year hydrostatic testing under SOLAS Chapter II-2. Container fleets operating Asia-Europe strings absorb the highest replacement volumes as port state control inspections intensify in Hamburg, Singapore, and Long Beach.
- Water Mist Systems:High-pressure pump skids and ceramic nozzle arrays operating above 10 bar deliver sub-100 micron droplet spectra for machinery space Class B suppression. IMO halon phase-out deadlines are compressing retrofit demand in engine rooms previously served by CO2 flooding, with East Asian shipyards specifying these systems for newbuilds.
- Fire Hoses:Synthetic-jacketed, rubber-lined assemblies in 45mm and 70mm diameters withstand 16 bar working pressure for deck and accommodation deployment.
- Foam Systems:Fixed proportioning skids and monitor arrays require 3% or 6% foam concentrate compatibility for tanker deck protection and helideck applications.
Fire extinguishers anchor the volume base while water mist systems gain share at the steepest rate.
Technology:
Cost tiers stratify from commodity dry powder to engineered gas-based systems, with certification depth determining margin capture across the technology spectrum.
- Water-Based:High-pressure mist and low-pressure deluge architectures dominate newbuild specifications due to IMO environmental compliance and reduced crew toxicity risks in machinery spaces.
- Gas-Based:Inert gas blends and clean agent chemistries command premium positioning for electronics-intensive control rooms and accommodation areas where water damage poses operational risk.
- Foam-Based:Aqueous film-forming foam and alcohol-resistant concentrates retain dominance in tanker cargo deck and offshore helideck protection despite EU F-Gas Regulation pressure on fluorinated formulations.
- Dry Powder:Sodium bicarbonate and monoammonium phosphate formulations serve as lowest-cost portable suppression for galley and small machinery space applications.
Foam-based technology captures the largest installed base while water-based architectures expand most quickly through newbuild penetration.
End User:
Customer procurement sophistication ranges from standardized fleet programs among container lines to fragmented spot purchasing in fishing vessel operations.
- Commercial Shipping:Container carriers and tanker operators deploy centralized technical departments that specify integrated detection-suppression packages across 500+ vessel fleets, demanding single-classification approvals from Lloyd's Register or DNV.
- Offshore Platforms:North Sea and Gulf of Mexico operators require Zone 1 hazardous area packages with redundant activation and SIL-rated detection loops for hydrocarbon processing modules.
- Cruise Liners:Passenger vessel operators prioritize accommodation area water mist and evacuation system integration under SOLAS evacuation route protection mandates.
- Fishing Vessels:Owner-operators in Mediterranean and Southeast Asian fleets favor portable and standalone units due to space constraints and limited dry-dock access.
Commercial shipping concentrates procurement volume while offshore platforms deliver the highest per-unit system value.
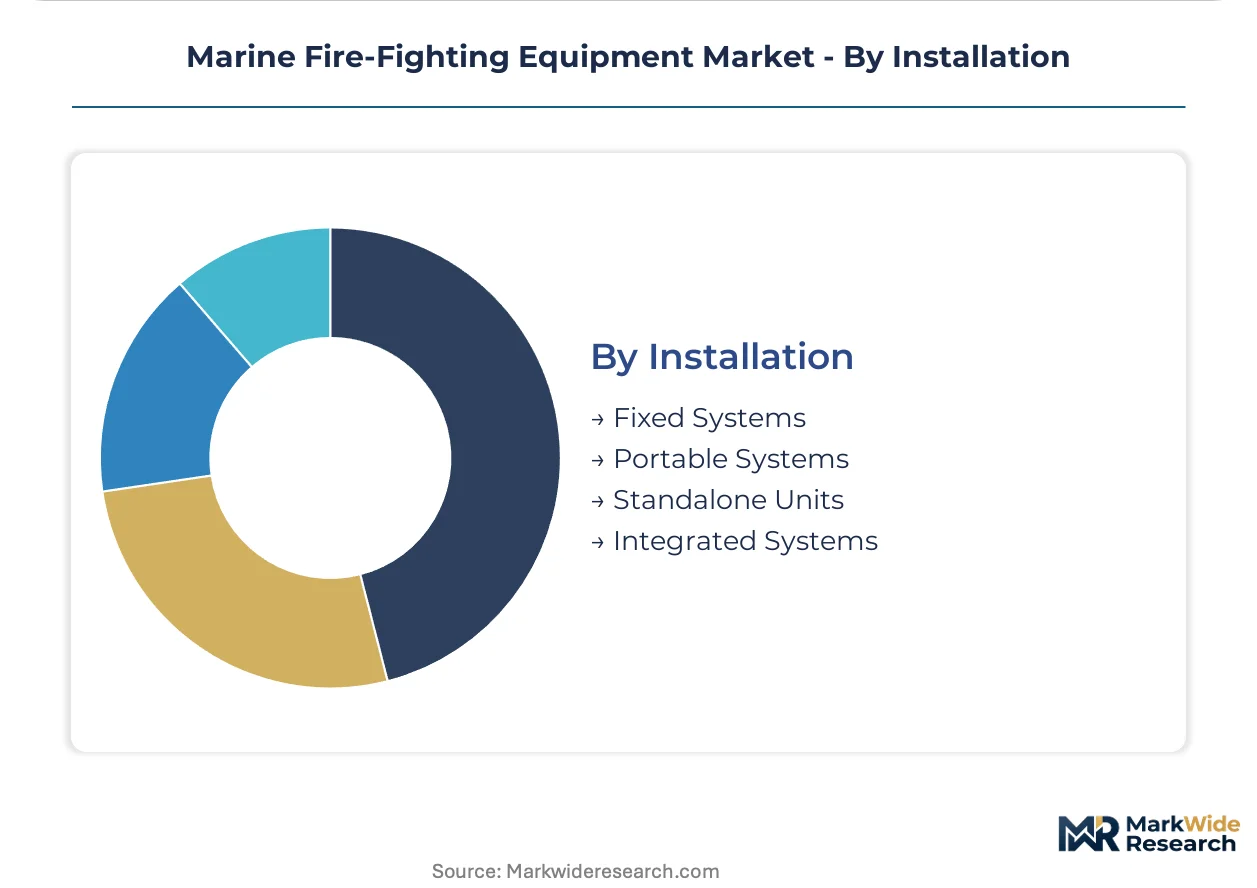
Installation:
Integration depth determines vendor stickiness, with standalone units enabling supplier switching while integrated systems lock in multi-decade maintenance relationships.
- Fixed Systems:Engine room CO2 flooding, water mist, and foam deluge networks require compartment isolation, structural reinforcement, and classification society approval extending 14-18 months for novel chemistries.
- Integrated Systems:Detection-to-suppression-to-evacuation bundling under single-vendor accountability is displacing point-product specialists among German container lines and Greek tanker operators pursuing fleet standardization.
- Portable Systems:Hand-held extinguishers and wheeled units serve as primary protection for fishing vessels and as backup redundancy on larger commercial fleets.
- Standalone Units:Pre-engineered skid packages with self-contained detection and activation reduce installation complexity for retrofit applications where space and power constraints limit full system integration.
Fixed systems dominate newbuild value capture while integrated systems climb fastest through shipowner consolidation of vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IMO's halon phase-out deadlines and SOLAS compliance enforcement are redistributing procurement intensity across maritime economies. Shipyard output concentration and port state control stringency now determine regional market pacing.
China
Shanghai, Dalian, and Guangzhou shipyards absorb the majority of global newbuild contracts, concentrating demand for integrated fire suppression packages. The China Classification Society accelerates type-approval timelines for water mist systems to match IMO 2024 deadlines. Jiangsu and Zhejiang province suppliers dominate domestic nozzle and pump skid fabrication.
South Korea
Ulsan and Geoje shipbuilding complexes drive specification authority for container vessel and LNG carrier safety systems. The Korean Register mandates dual-certification for alternative fuel vessel suppression architectures. Busan port state control inspections reject non-compliant vessels at rates exceeding regional averages.
Japan
Imabari and Oshima shipyards specify high-pressure water mist for machinery spaces in newbuild contracts. ClassNK certification queues extend 16 months for novel clean agent chemistries. Nagasaki and Kobe marine equipment clusters supply ceramic nozzle inserts and corrosion-resistant piping to regional shipyards.
Germany
Hamburg port state control enforces SOLAS Chapter II-2 with rejection rates that accelerate fleet retrofit demand across European-flagged vessels. Germanischer Lloyd type-approval processes gate vendor access to Scandinavian and German shipowner procurement. Bremen and Hamburg safety system integrators bundle detection-suppression-evacuation packages for container line fleet standardization.
United States
Gulf Coast offshore platform operators in Texas and Louisiana absorb Zone 1 hazardous area packages for hydrocarbon processing modules. US Coast Guard type-approval runs parallel to EU Marine Equipment Directive pathways, fragmenting vendor market access. Jones Act vessel construction in Louisiana and Mississippi sustains demand for redundant activation systems in offshore wind installation fleets.
Marine Fire-Fighting Equipment Market Competitive Environment
On the supply side, the industry is consolidating around integrated safety system providers capable of bundling detection, suppression, and evacuation equipment under single-classification approvals. The vendor base separates into three strategic archetypes: classification society-aligned system integrators, component specialists with hydrant and monitor expertise, and clean agent chemistry certification depth players. Competitive moves concentrate on M&A for detection-to-suppression integration and captive vendor qualification database positioning with direct shipowner procurement platforms.
Within the integrated safety system tier, VIKING Life-Saving Equipment and Consilium Safety Group AB occupy positions anchored through Scandinavian and German shipowner account relationships. Akron Brass Company exemplifies the component specialist archetype with its hydrant and monitor focus sustaining presence in port-based retrofit programs. Amerex Corporation represents the certification depth strategy through CO2 and clean agent system authority for engine room applications.
| Leading Market Players |
|---|
| Akron Brass Company |
| Amerex Corporation |
| Fireboy-Xintex |
| Sea-Fire Marine |
| VIKING Life-Saving Equipment |
| Consilium Safety Group AB |
| Johnson Controls |
| Danfoss Semco |
| Hochiki Corporation |
| Others |
Value Chain & Pricing Dynamics
Commodity volatility in nickel and molybdenum alloy grades compresses fabrication margins while simultaneously widening the spread between premium corrosion-resistant systems and standard carbon-steel alternatives. This input-cost instability forces shipyards to pre-purchase high-pressure pump housings in bulk, reshaping procurement timing and supplier financing structures across East Asian manufacturing clusters.
Pricing Analysis
Certification level from Lloyd's Register, DNV, or Bureau Veritas creates the primary spread between premium and standard system tiers, with dual-classification approvals commanding 25-40% uplifts over single-society products. Project-based contract pricing dominates fixed system procurement, while portable extinguisher sales run on annual volume agreements with container fleets. Price erosion runs through standard-tier CO2 flooding systems as water mist alternatives capture machinery space specifications. Fishing vessel owner-operators exhibit highest price sensitivity due to limited dry-dock windows and capital constraints, whereas German container lines prioritize certification depth over unit cost.
Supply Chain Analysis
Extended payment terms from 90 to 180 days now structure supplier-cash-flow relationships, with Korean and Japanese pump skid manufacturers absorbing the steepest working-capital pressure. Component fabrication concentrates in Jiangsu and Zhejiang provinces of China, Nagasaki and Kobe clusters in Japan, and Ulsan-adjacent industrial zones in South Korea. High-pressure ceramic nozzles, corrosion-resistant piping, and specialized pump housings draw from these concentrated manufacturing bases. Single-source vulnerability in ceramic nozzle inserts from Japanese suppliers poses structural risk given 16-month ClassNK certification queues. Distribution runs through shipyard procurement channels with classification society pre-approval gatekeeping vendor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through direct procurement platforms built by Maersk, MSC, and COSCO, fragmenting traditional shipyard intermediary relationships and forcing vendors to qualify through captive databases.
For Market Incumbents: Harden classification society alignment through accelerated type-approval investment for ammonia-compatible suppression chemistries. Deepen backward integration into ceramic nozzle manufacturing to offset Japanese supply concentration. Lock in multi-year maintenance contracts with Greek tanker operators pursuing fleet standardization. For New Entrants and Emerging Players: Build out standalone skid packages for fishing vessel retrofit applications where space constraints exclude integrated system competition. Target Mediterranean and Southeast Asian owner-operators through portable equipment certification at lower cost thresholds. Pursue shipowner qualification database entry through spare part sourcing partnerships. For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors detection-to-suppression integrators over point-product specialists. Long-term viability rests on positioning for alternative fuel vessel codes across ammonia and methanol propulsion architectures. Monitor Lloyd's Register and DNV harmonization talks as inflection signal for certification pathway consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Detection-Suppression Integration | Bundles fire detection, water mist activation, and evacuation signaling under single-classification approvals from DNV. |
| Alternative Fuel Certification | Positions systems for ammonia and methanol propulsion codes before Lloyd's Register mandatory requirements take effect. |
| Ceramic Nozzle Manufacturing Scale-Up | Reduces dependency on Nagasaki and Kobe suppliers for high-pressure mist system critical components. |
| Direct Shipowner Platform Qualification | Bypasses traditional shipyard intermediaries through Maersk and COSCO captive vendor databases. |
| Zone 1 Hazardous Area Package Development | Captures offshore wind installation vessel demand in US Gulf and North Sea cable-laying fleets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of Lloyd's Register type-approval databases, DNV technical rule filings, and IMO circulars on halon phase-out implementation. Primary interviews engaged shipyard safety system procurement managers, classification society surveyors, marine equipment distributors, and technical directors at container line fleet management departments. Secondary sources included customs records of high-pressure pump and nozzle exports, SEC filings from listed safety equipment manufacturers, and shipbuilding order books from Clarksons and VesselsValue. Bottom-up vessel counts by type and age profile triangulate against top-down market value estimates.
Forecast inputs span product type segmentation across fixed, portable, and integrated systems; technology tiers from dry powder through water mist and gas-based suppression; end-user categories including commercial shipping, offshore platforms, cruise liners, and fishing vessels; and installation modes distinguishing newbuild from retrofit applications. CAGRs derive from vessel delivery schedules, SOLAS compliance deadline enforcement intensity, and alternative fuel vessel code adoption curves. Modeling incorporates shipyard output concentration in China, South Korea, and Japan, alongside port state control inspection stringency in Hamburg, Singapore, and Long Beach.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated safety system bundlers or alternative fuel vessel specialists would shift outcomes. Macroeconomic deviation in nickel and molybdenum prices, regulatory acceleration in ammonia propulsion codes, or technological breakthrough in low-pressure water mist architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Ship Plate Market
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Europe Inland Water Freight Transport Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
Container Docking Stations Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Global Maritime Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
Global Connected Ship Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Hong Kong Stevedoring and Marine Cargo Handling Market