
 Automotive Active Health Monitoring System Market | 2026-2036
Automotive Active Health Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Active Health Monitoring System Market Analysis
The EU General Safety Regulation is repositioning the cost-of-entry calculus for active health monitoring suppliers, forcing module-level compliance investments before vehicles reach type approval. Bosch leverages its cross-domain sensor portfolio to anchor integrated cockpit-health architectures. Qualcomm Technologies competes through high-performance edge-computing platforms that process biometric and vehicular data streams simultaneously. Continental dominates European OEM supply relationships with validated safety-system integration capabilities.
Automotive active health monitoring systems comprise embedded sensor arrays, biometric capture interfaces, and real-time analytics engines that track driver physiological states alongside vehicle mechanical condition. These systems typically integrate photoplethysmography sensors, steering-wheel-integrated electrodes, and cabin-mounted infrared monitors to detect fatigue, cardiac events, or cognitive impairment before operational failure occurs. Real-time Monitoring Systems lead current revenue contribution due to mandatory fleet telematics installations across commercial transport segments. Predictive Maintenance Solutions represent the fastest-expanding category as machine learning models trained on aggregated vehicle-health datasets improve failure-forecast accuracy and reduce unplanned downtime for fleet operators.
NHTSA guidelines in the United States and the EU General Safety Regulation collectively establish biometric monitoring as a foreseeable compliance pathway for enhanced driver-assistance architectures. Japan's METI has issued interoperability standards that pressure suppliers toward open-data frameworks and cloud-agnostic platform designs. Stakeholders must monitor whether regulatory convergence on health-data privacy creates divergent certification burdens across major automotive markets.
Market Dynamics
Fleet telematics mandates are compressing procurement cycles for commercial vehicle operators, forcing Tier-1 suppliers to validate biometric sensor modules before type approval rather than post-launch retrofit.
Growth Catalysts
- EU General Safety Regulation:Mandates driver-monitoring systems in new vehicle categories, creating guaranteed demand pull for steering-wheel-integrated photoplethysmography sensors across commercial transport platforms.
- Machine learning model refinement:Aggregated vehicle-health datasets from connected fleets now enable cardiac-event prediction accuracy sufficient for insurance premium reduction, accelerating fleet-operator adoption.
- Germany:OEM and Tier-1 supplier co-location around Stuttgart and Munich clusters compresses development-to-validation timelines for integrated cockpit-health architectures.
Market Restraints
- Silicon photonics component shortages:Near-infrared sensor arrays depend on specialized foundry capacity concentrated in Taiwan, exposing module suppliers to allocation volatility.
- GDPR health-data classification:Biometric monitoring triggers enhanced consent frameworks, forcing cloud-agnostic platform redesigns that extend certification timelines by 8-14 months.
- Electrochemical sweat sensors:Lower-cost alternatives for hydration and stress monitoring threaten premium photoplethysmography positioning in economy vehicle segments.
Strategic Opportunities
- Japan METI interoperability standards:Open-data frameworks create first-mover advantage for suppliers offering API-accessible health-monitoring stacks that port across OEM infotainment systems.
- Predictive maintenance convergence:Integration of driver biometrics with powertrain telemetry enables unified downtime forecasting, a service bundle fleet operators currently source from separate vendors.
- Subscription-based fleet health analytics:Channel innovation displaces capital-equipment sales with per-vehicle-month pricing, reducing customer acquisition friction for mid-size logistics operators.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 certification for driver-monitoring systems requires specialized talent pools concentrated at Bosch, Continental, and a handful of consultancies.
- Legacy CAN bus integration:Real-time biometric data streaming demands bandwidth reallocation that conflicts with established vehicle-network hierarchies in platforms designed before 2020.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Active Health Monitoring System Market |
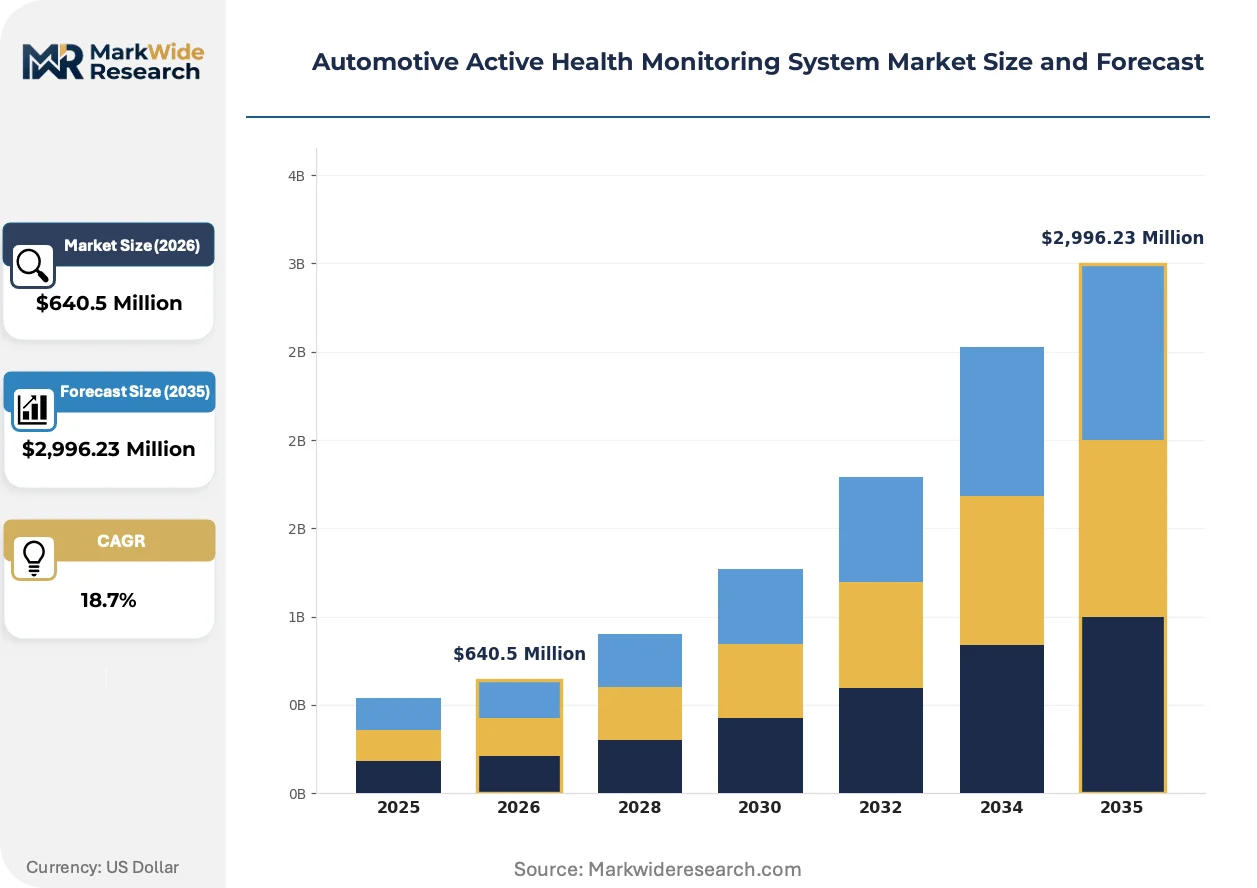
| Market Size in 2026 | $640.5 Million |
| Market Size in 2035 | $2,996.23 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tools, Predictive Maintenance Solutions, Real-time Monitoring Systems, Data Analytics Platforms Technology: Telematics, IoT Sensors, Machine Learning, Cloud Computing End User: OEMs, Fleet Operators, Aftermarket Service Providers, Vehicle Owners Application: Vehicle Health Monitoring, Fuel Efficiency Management, Safety Systems, Driver Behavior Analysis |
| Companies Covered | Visteon Corporation, Qualcomm Technologies, Bosch, NXP Semiconductors, Tata Elxsi, Continental, ZF Friedrichshafen, Faurecia, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Active Health Monitoring System Market Emerging Trajectories
Edge-computing architectures are displacing cloud-dependent processing for latency-sensitive driver impairment detection, while regulatory pressure on data residency accelerates on-vehicle analytics deployment.
Photoplethysmography sensor fusion with steering-wheel capacitive electrodes is rewriting the accuracy benchmarks for non-invasive cardiac monitoring in moving vehicles. Commercial fleet operators in long-haul trucking are adopting these dual-modality systems within 18-month replacement cycles. The technology is rewriting competitive positioning by enabling insurance partnerships that were previously blocked by false-positive rates.
The EU AI Act's risk-classification framework for biometric inference systems imposes conformity assessment requirements that parallel medical-device pathways. Module suppliers must now maintain technical documentation and quality management systems previously unnecessary for automotive Tier-2 components. Heavy-duty commercial vehicle platforms face the steepest compliance burden, with German OEMs accelerating supplier audits ahead of 2025 enforcement windows.
Fleet procurement departments now bundle driver-health monitoring with existing telematics contracts rather than sourcing through separate safety-equipment channels. This consolidation disadvantages standalone health-monitoring specialists while favoring integrated platform vendors with established fleet relationships. The pattern is most visible in Germany and the Netherlands, where logistics operator consolidation has concentrated buying power among ten major fleet management companies.
Automotive Active Health Monitoring System Market Segmentation
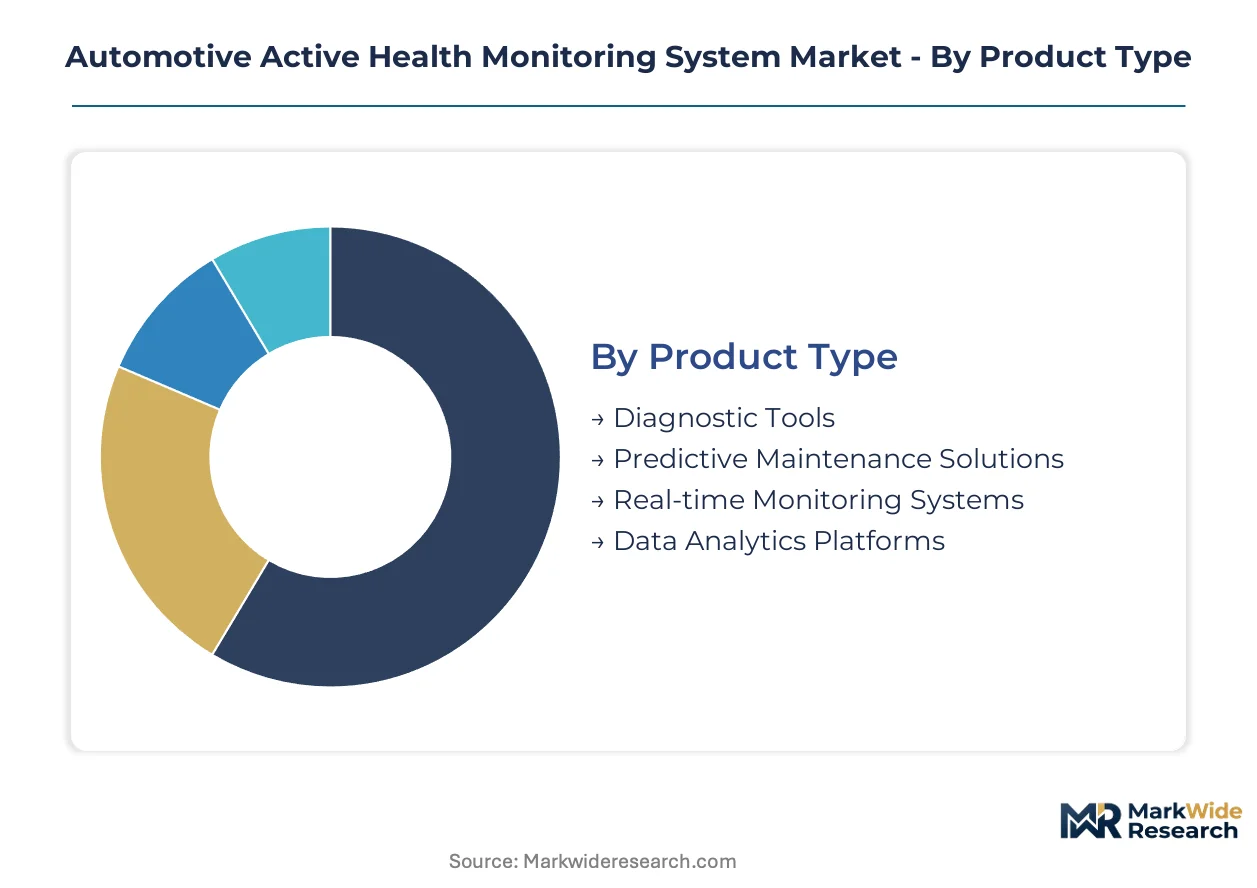
Procurement patterns across the automotive active health monitoring ecosystem diverge sharply by customer type and regulatory exposure. Fleet operators prioritize integrated telematics bundles over standalone modules, while OEMs demand pre-validated architectures that compress type-approval timelines.
Product Type:
Fleet procurement departments weight total cost of ownership against unplanned downtime reduction when evaluating system categories.
- Real-time Monitoring Systems:Embedded sensor arrays stream driver biometric and vehicle mechanical data to fleet control centers with sub-second latency. German logistics operators mandate these systems under EU General Safety Regulation compliance schedules, compressing replacement cycles to 18 months for long-haul platforms.
- Predictive Maintenance Solutions:Machine learning models trained on aggregated vehicle-health datasets forecast powertrain and component failures before operational degradation. Fleet operators in the Netherlands bundle these with existing telematics contracts, displacing capital-equipment purchases with per-vehicle-month pricing.
- Diagnostic Tools:Portable or fixed equipment for post-fault analysis and repair verification in workshop environments.
- Data Analytics Platforms:Cloud-agnostic software layers processing normalized health telemetry across mixed fleet compositions.
Volume sits with Real-time Monitoring Systems; growth tilts toward Predictive Maintenance Solutions.
Technology:
Technology selection follows bandwidth constraints in legacy vehicle architectures and data-residency requirements under GDPR and Japan METI frameworks.
- Telematics:Integrated cellular and satellite communication modules transmitting encrypted health data to fleet management systems. Commercial vehicle platforms in Germany and the Netherlands deploy these as mandatory infrastructure under logistics operator consolidation.
- IoT Sensors:Photoplethysmography arrays, steering-wheel capacitive electrodes, and cabin-mounted infrared monitors capturing non-invasive biometric signals. Near-infrared sensor production concentrates in Taiwan, exposing module suppliers to foundry allocation volatility.
- Machine Learning:Edge-deployed inference engines classifying driver impairment patterns without cloud dependency.
- Cloud Computing:Centralized processing infrastructure for fleet-wide health analytics and insurance partnership data feeds.
Telematics commands current deployment volume; machine learning at the edge is expanding most quickly as latency requirements tighten.
End User:
Customer scale determines procurement channel structure and pricing model flexibility.
- Fleet Operators:Consolidated buyers across German and Dutch logistics markets sourcing integrated health-monitoring through existing telematics vendors. Ten major fleet management companies now control procurement for mid-size operators, favoring platform vendors with established relationships.
- OEMs:Vehicle manufacturers requiring ISO 26262-validated modules for type approval under EU General Safety Regulation and NHTSA guidelines. Bosch and Continental anchor European supply relationships through cross-domain sensor portfolios and safety-system integration capabilities.
- Aftermarket Service Providers:Independent installers and retrofit specialists serving vehicle owners outside warranty coverage.
- Vehicle Owners:Individual consumers accessing health-monitoring features through premium trim packages or subscription services.
Fleet operators dominate transaction volume; OEM integration contracts offer the steepest expansion trajectory.
Application:
Application prioritization reflects regulatory pressure sequencing and insurance market development.
- Safety Systems:Driver-monitoring architectures detecting fatigue, cardiac events, and cognitive impairment before operational failure. EU AI Act risk-classification frameworks impose conformity assessments paralleling medical-device pathways for these biometric inference systems.
- Driver Behavior Analysis:Pattern recognition linking physiological states to vehicle control inputs for risk scoring and premium adjustment. German insurers now accept cardiac-event prediction accuracy from dual-modality systems as sufficient for rate reduction.
- Vehicle Health Monitoring:Powertrain and chassis telemetry aggregation for mechanical condition assessment.
- Fuel Efficiency Management:Correlation of driver state with consumption patterns for optimization coaching.
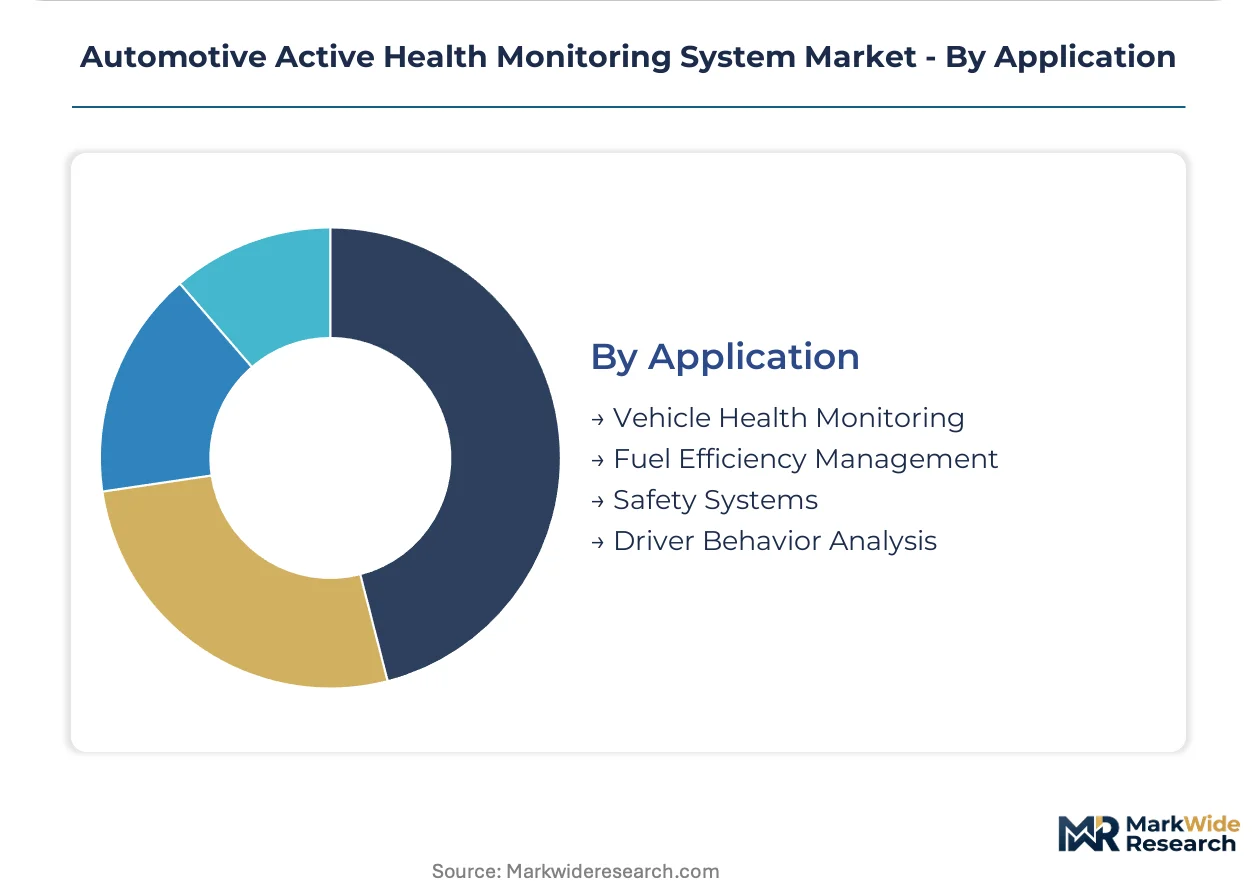
Safety Systems anchor current regulatory-driven deployment; Driver Behavior Analysis is gaining share fastest as insurance partnerships mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German free-trade zones and Stuttgart's automotive cluster concentrate Tier-1 supplier co-location, compressing development-to-validation timelines for integrated cockpit-health architectures across European OEM platforms.
Germany
Stuttgart and Munich host overlapping OEM and supplier engineering centers where ISO 26262 certification workflows run in parallel. The EU General Safety Regulation mandates driver-monitoring systems for commercial vehicles, accelerating photoplethysmography sensor validation before type approval. Bosch anchors cross-domain sensor portfolios here, while Continental maintains validated safety-system integration relationships with domestic OEMs.
United States
NHTSA guidelines establish biometric monitoring as a compliance pathway for enhanced driver-assistance architectures, pulling demand from commercial fleet operators. The Department of Transportation coordinates with insurance regulators to accept cardiac-event prediction accuracy for premium reduction. Michigan and California development centers focus on edge-computing architectures that process biometric data without cloud dependency.
Japan
METI interoperability standards pressure suppliers toward open-data frameworks and cloud-agnostic platform designs. Nagoya and Tokyo clusters concentrate edge-computing specialists refining machine learning inference engines for driver impairment detection. Domestic OEMs demand API-accessible health-monitoring stacks that port across infotainment systems without vendor lock-in.
Netherlands
Logistics operator consolidation in Rotterdam and Amsterdam has concentrated procurement power among ten major fleet management companies. EU General Safety Regulation compliance schedules compress replacement cycles to 18 months for long-haul platforms. Fleet operators here bundle predictive maintenance with existing telematics contracts, displacing capital-equipment purchases with per-vehicle-month pricing.
China
Domestic OEMs integrate health monitoring into premium electric vehicle platforms targeting fleet electrification mandates. MIIT standards for connected vehicle data residency accelerate on-vehicle analytics deployment. Shenzhen and Shanghai clusters concentrate photoplethysmography module suppliers seeking to reduce dependence on Taiwan foundry capacity for near-infrared sensor arrays.
Automotive Active Health Monitoring System Market Vendor Landscape
German producers anchor the premium tier through validated safety-system integration; American and Japanese specialists hold positions in edge-computing and semiconductor platforms. The market structures around three strategic archetypes: cross-domain sensor portfolio vendors, high-performance computing platform suppliers, and fleet-focused integrated telematics providers. Dominant competitive moves include backward integration into specialized foundry relationships and strategic partnerships with insurance underwriters to validate biometric prediction accuracy.
Among Germany-based Tier-1 suppliers, Bosch and Continental exemplify the cross-domain sensor portfolio archetype, anchoring European OEM supply relationships through ISO 26262-validated module integration. Qualcomm Technologies occupies a position within the high-performance edge-computing tier, competing through platforms that process biometric and vehicular data streams simultaneously. Denso Corporation represents Japanese specialist positioning in open-data framework compliance under METI interoperability standards.
| Leading Market Players |
|---|
| Visteon Corporation |
| Qualcomm Technologies |
| Bosch |
| NXP Semiconductors |
| Tata Elxsi |
| Continental |
| ZF Friedrichshafen |
| Faurecia |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
ISO 26262 certification tiering bifurcates module suppliers into premium-validated and commodity-aspirant camps, with the former commanding pre-approval pricing power through Continental and Bosch supply relationships while the latter face spot-market volatility for unvalidated photoplethysmography arrays. This divergence concentrates procurement leverage among fleet operators in Germany and the Netherlands who bundle health-monitoring into multi-year telematics contracts, forcing uncertified competitors toward per-unit transactional models with compressed margins.
Pricing Analysis
Short-lead-time premiums attach to ISO 26262-validated modules as German OEMs accelerate supplier audits ahead of EU AI Act enforcement windows. The dominant pricing structure runs through subscription-based fleet health analytics with per-vehicle-month tiers, though spot purchases persist for aftermarket retrofit channels. Price differentiation rests on functional safety certification grade and steering-wheel integration complexity, with electrochemical sweat-sensor alternatives intensifying cost compression in economy vehicle segments. Fleet operators in long-haul trucking exhibit highest price sensitivity due to thin operating margins, while premium electric vehicle OEMs absorb certification premiums without volume negotiation.
Supply Chain Analysis
Functional safety engineer scarcity in Stuttgart and Munich clusters constrains module validation throughput for Tier-1 suppliers dependent on Bosch and Continental certification workflows. Near-infrared sensor production concentrates in Taiwan, South Korea, and Japan, with photoplethysmography arrays and steering-wheel capacitive electrodes drawing from specialized foundry capacity exposed to allocation volatility. Single-source vulnerability runs through Taiwan semiconductor fabrication for silicon photonics components. Distribution runs through integrated telematics vendors with established fleet management company relationships in Germany and the Netherlands, displacing standalone health-monitoring specialists from procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-classification framework for biometric inference systems erects a compliance moat that favors incumbent suppliers with medical-device pathway experience, elevating cost-of-entry beyond reach for unvalidated module vendors.
For Market Incumbents: Lock in backward integration into Taiwan foundry relationships for near-infrared sensor arrays, securing allocation priority against silicon photonics shortages that threaten Continental and Bosch module delivery schedules. Deepen ISO 26262 certification talent pools through targeted acquisition of Stuttgart-area functional safety consultancies, defending against emerging edge-computing specialists like Qualcomm Technologies who threaten cockpit-health architecture dominance through high-performance inference platforms. For New Entrants and Emerging Players: Launch via API-accessible health-monitoring stacks compatible with Japan METI interoperability standards, exploiting open-data framework pressure that disadvantages proprietary Continental and Bosch architectures. Target aftermarket service providers in China seeking to reduce Taiwan foundry dependence for domestic premium electric vehicle platforms, where MIIT data residency rules accelerate on-vehicle analytics deployment absent cloud dependency. For Investors and Strategic Acquirers: Re-rating potential sits with edge-computing platform specialists given EU GDPR health-data classification forcing cloud-agnostic redesigns that extend certification timelines for legacy suppliers. Long-term viability favors suppliers with captive functional safety engineering capacity and validated OEM integration relationships across the 5-10 year regulatory convergence horizon. Monitor Taiwan foundry allocation announcements as inflection indicator for module supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | API-accessible health-monitoring stacks under Japan METI standards reduce OEM vendor lock-in. |
| Backward Integration | Captive near-infrared sensor production mitigates Taiwan foundry allocation volatility for Tier-1 suppliers. |
| Software-Defined Vehicle Investment | Edge-computing architectures process biometric data without cloud dependency under GDPR constraints. |
| Geographic Manufacturing Footprint | Stuttgart and Munich co-location compresses ISO 26262 validation timelines for EU General Safety Regulation compliance. |
| Charging Infrastructure Partnership | Integration of driver biometrics with powertrain telemetry enables unified downtime forecasting for fleet operators. |
Methodological Framework
Document review covered EU General Safety Regulation implementation timelines, NHTSA guideline evolution, and Japan METI interoperability standards, complemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, fleet management company operations heads, and functional safety certification consultants. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive technology suppliers, and Taiwan semiconductor foundry capacity disclosures. Bottom-up module shipment estimates triangulated against top-down fleet telematics adoption projections.
Historical biometric sensor deployment patterns cross-referenced against expert panel inputs on EU AI Act compliance timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user scale, and application priority, with vehicle class and regional regulatory cluster as automotive-specific layers. CAGRs derived from regression analysis of fleet operator procurement cycles and OEM type-approval schedules, incorporating machine learning model refinement trajectories for predictive maintenance solution adoption.
The model assumes a particular technology adoption path; alternative pathways for electrochemical sweat sensors displacing photoplethysmography in economy segments would alter the outlook for premium module supplier pricing power. Forecasts embed assumptions regarding Taiwan foundry capacity allocation, GDPR consent framework enforcement intensity, and fleet operator consolidation velocity in German and Dutch logistics markets. Material deviation in EU AI Act audit timelines or NHTSA biometric monitoring guideline finalization warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Europe Pedestrian Detection Systems Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Driving Helmet Market
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Automotive Brake System Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Automotive Airbags Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Automotive Speed Limiter Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
Traffic Jam Assist (TJA) Market