
 Marine Vessel Market | 2026-2036
Marine Vessel Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Vessel Market Intelligence
The capability gap between high-specification vessels and standard commodity carriers is expanding, creating distinct value tiers. A.P. Moller-Maersk positions itself in the premium tier by investing in methanol-powered container ships to meet sustainability goals. In contrast, COSCO Shipping Lines leverages its scale to compete on cost in the standard cargo segment. CMA CGM Group differentiates through a mixed fleet, balancing advanced LNG-powered vessels with conventional ships to serve diverse routes.
A marine vessel is a self-propelled watercraft engineered for navigation on oceans, seas, or inland waterways. Construction involves complex naval architecture and adherence to specific load line conventions which dictate the maximum operational draft. While cargo ships constitute the largest segment by volume, specialized offshore support vessels for energy projects command higher charter rates. Within propulsion, the transition from legacy diesel engines to hybrid systems and alternative fuels like LNG is a defining market shift.
The International Maritime Organization (IMO) sets primary global standards for safety, security, and environmental performance. National and regional regulations, such as the EU's emissions trading system and China's dual carbon goals, further influence vessel design and fuel choices. Shipowners must now decide on long-term capital investments in either newbuilds compliant with future regulations or retrofitting existing assets to maintain competitiveness.
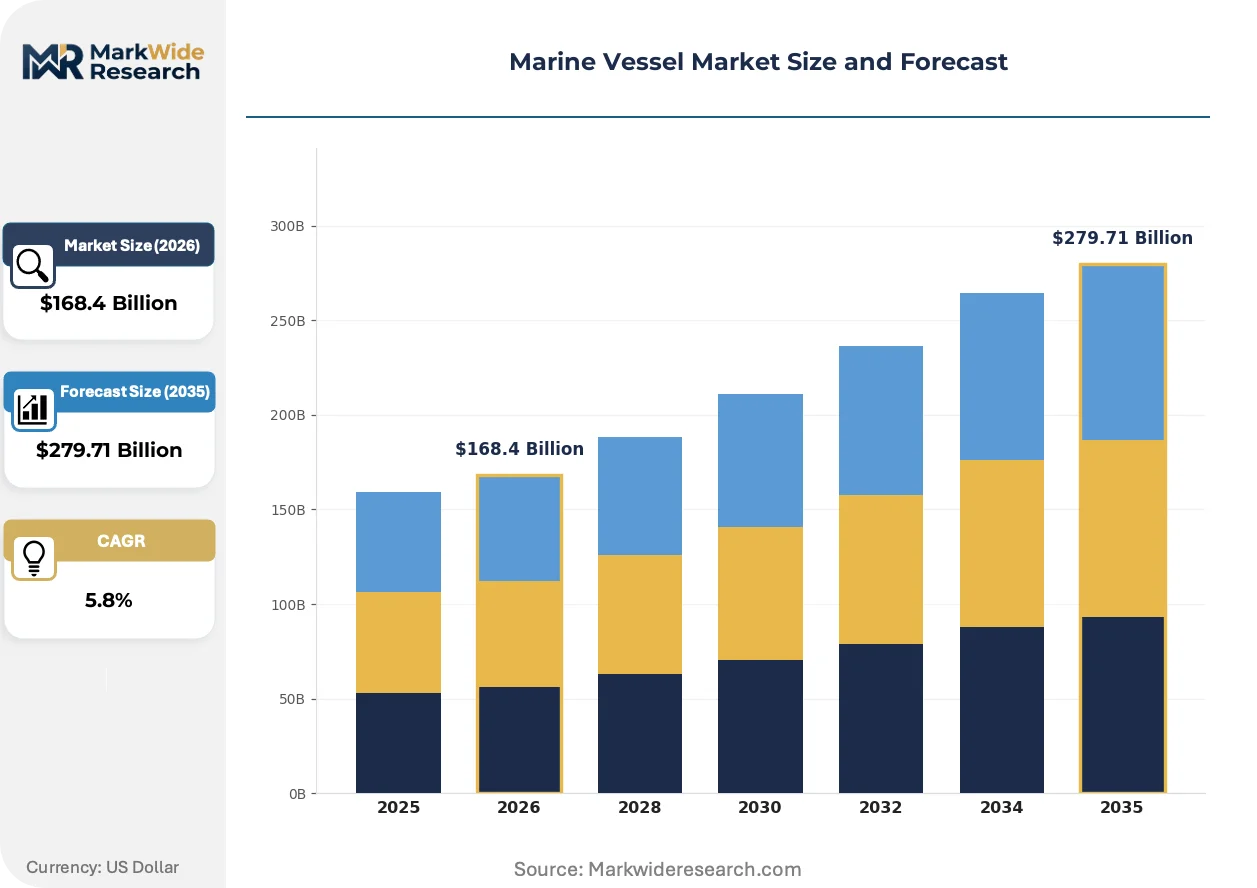
Market Dynamics
The imperative for decarbonization, driven by stringent International Maritime Organization regulations, is the central force shaping the market. This compels a massive capital expenditure cycle focused on fleet renewal and adopting alternative fuel technologies.
Growth Catalysts
- Regulatory Mandates:Stricter IMO emissions standards, including the Energy Efficiency Existing Ship Index (EEXI), accelerate the retirement of older vessels and stimulate newbuild orders for compliant designs.
- E-commerce Growth:Expanding containerized trade, particularly from manufacturing hubs in Asia, requires larger and more efficient vessels to service global supply chains.
- Propulsion Technology:The commercial viability of LNG and methanol dual-fuel engines provides shipowners a clear pathway to reduce emissions, boosting investment in these systems.
Market Restraints
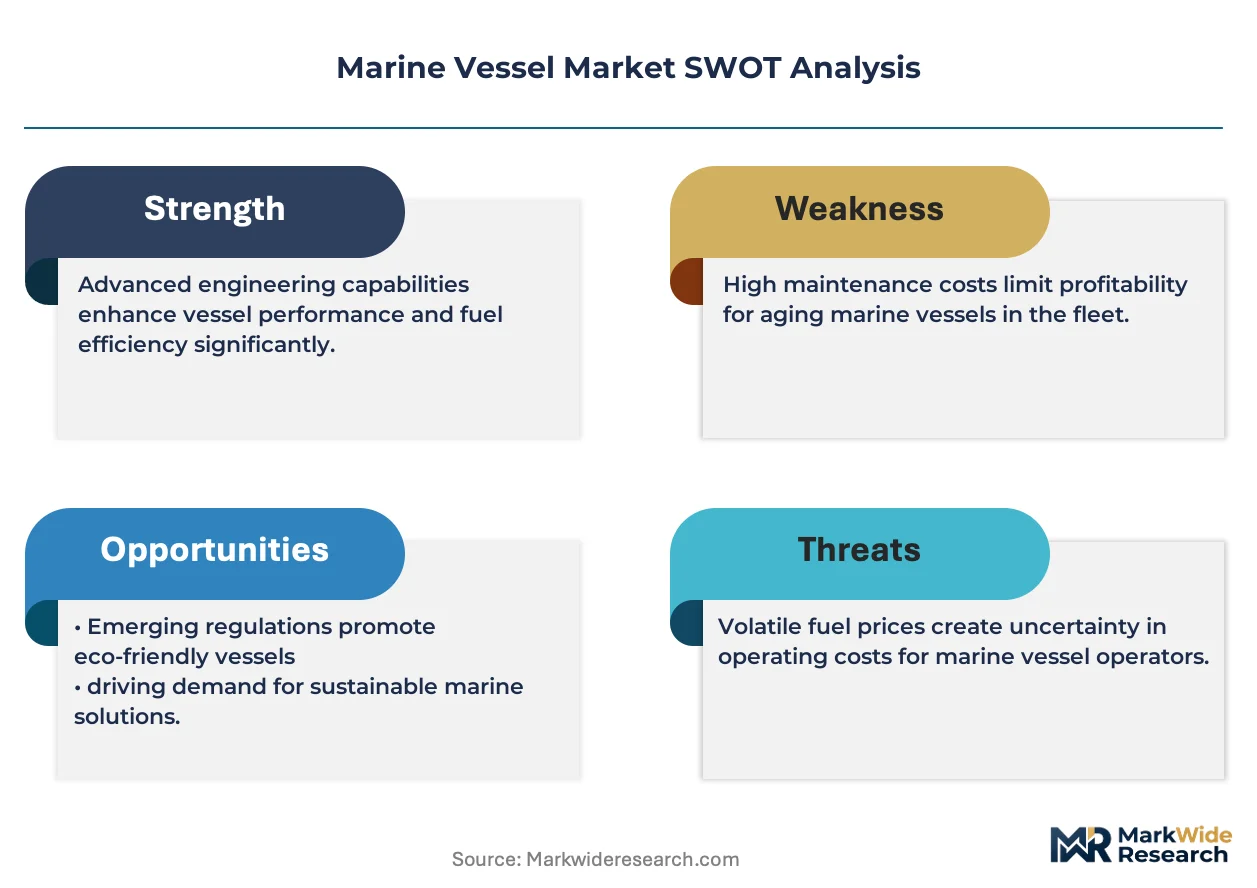
- Input Cost Volatility:Fluctuating prices for high-grade steel plate, a primary shipbuilding material, create significant cost uncertainty and can erode project margins for shipyards.
- Shipyard Concentration:The consolidation of complex vessel construction in South Korea, China, and Japan leads to production bottlenecks and extended delivery timelines for high-specification ships.
- Fuel Infrastructure Gaps:A lack of widespread bunkering availability for next-generation fuels like ammonia and hydrogen remains a major barrier to their adoption on key global trade routes.
Strategic Opportunities
- Retrofit Technologies:Onboard carbon capture systems offer a significant opportunity to upgrade mid-life vessels, extending their operational lifespan and compliance with future emissions rules.
- Offshore Wind Expansion:Growth in offshore wind farm construction in the North Sea and along the U.S. Atlantic coast creates new demand for specialized installation and service vessels.
- Green Shipping Corridors:Policy-driven initiatives to establish low-emission maritime routes, supported by incentives under frameworks like the EU Green Deal, can de-risk investment in zero-emission ships.
Industry Challenges
- Specialized Skills Gap:A shortage of crew and engineers qualified to operate and maintain complex dual-fuel engines and advanced digital navigation systems presents a growing operational risk.
- High Capital Intensity:The immense investment needed for newbuilds with alternative fuel systems or for complex retrofits strains the financial capacity of smaller, independent shipowners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Vessel Market |
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $279.71 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Cargo Ships, Passenger Ships, Fishing Vessels, Offshore Support Vessels, Research Vessels Propulsion: Diesel Engines, Gas Turbines, Electric Motors, Hybrid Systems, Steam Turbines Application: Commercial Shipping, Maritime Transport, Aquaculture, Oceanographic Research, Naval Operations End User: Shipping Companies, Leasing Firms, Marine Research Institutions, Defense Organizations, Fisheries |
| Companies Covered | COSCO Shipping Lines, Evergreen Marine Corporation, Mediterranean Shipping Company, Hyundai Merchant Marine, Ocean Network Express, A.P. Moller-Maersk, Hapag-Lloyd, Yang Ming Marine Transport Corporation, CMA CGM Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Vessel Market Strategic Shifts & Innovations
Digitalization and decarbonization are the twin pressures altering marine asset management. These forces influence vessel design, operational efficiency, route optimization, and long-term investment strategies for shipowners.
Dual-fuel propulsion systems allow vessels to operate on conventional fuels and alternatives like LNG or methanol. Shipowners in container and tanker segments are adopting this technology for newbuilds to ensure future compliance. This fuel-flexible approach is overtaking the legacy single-fuel engine design as the standard for high-value maritime assets.
The International Maritime Organization’s Carbon Intensity Indicator (CII) establishes a mandatory operational efficiency rating for vessels. This rule creates commercial incentives for improvement, as charterers favor ships with higher ratings. The container and bulk carrier segments are most affected, integrating CII performance into voyage planning and investment decisions.
Charterers and cargo owners are increasingly selecting vessels based on verified emissions performance, not just cost. This disrupts traditional spot market dynamics, creating a premium for greener ships. The shift is most visible on trade routes into Europe, where regulations like the EU ETS amplify the financial impact of emissions.
Marine Vessel Market Segmentation
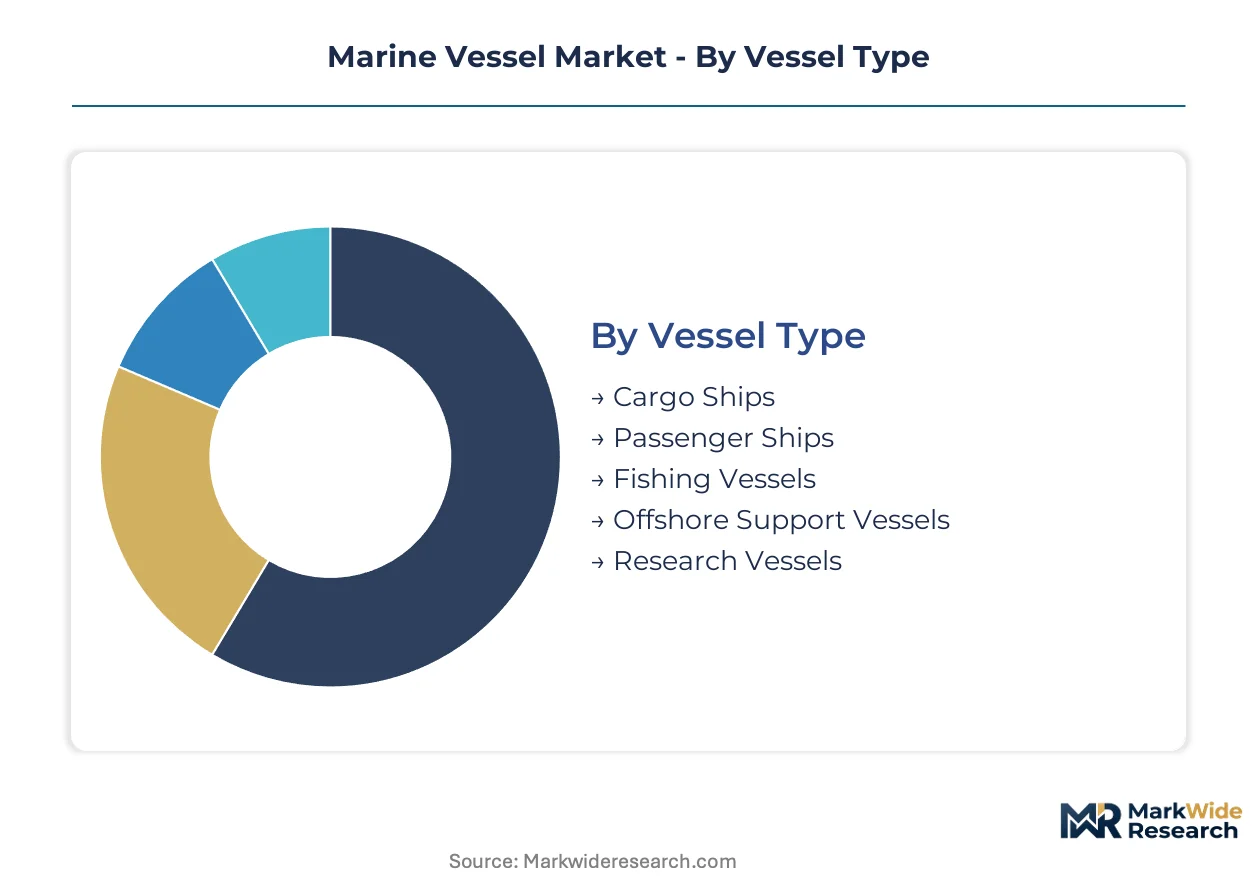
Segmentation within the marine vessel market highlights the diverse operational needs and technological preferences shaping investment decisions. Understanding these distinct segments allows stakeholders to identify specific growth areas and allocate capital effectively for fleet modernization and expansion.
Vessel Type:
Buyers of marine vessels differentiate significantly based on their operational requirements and cargo capacity needs.
- Cargo Ships:These vessels transport goods across oceans, encompassing bulk carriers, tankers, and container ships. Demand concentrates in global trade lanes, driven by e-commerce expansion and the need for efficient containerized logistics.
- Offshore Support Vessels:Specialized ships provide services to offshore oil, gas, and wind energy installations, including platform supply vessels and anchor handling tugs. Demand is concentrating in new offshore wind farm construction in the North Sea and along the U.S. Atlantic coast.
- Passenger Ships:This category includes cruise liners, ferries, and high-speed catamarans designed for transporting people.
- Fishing Vessels:These ships are equipped for commercial fishing activities, ranging from trawlers to longliners.
- Research Vessels:Specialized ships conduct scientific studies, oceanographic surveys, and marine exploration.
Cargo Ships lead volumes today; Offshore Support Vessels are gaining share fastest.
Propulsion:
Technological maturity and operational expenditure drive propulsion system selection for newbuilds and retrofits.
- Diesel Engines:These conventional internal combustion engines remain the most widespread propulsion system due to their proven reliability and established bunkering infrastructure. Demand persists among cost-sensitive operators seeking established technology for their fleets.
- Hybrid Systems:Combining conventional diesel engines with electric motors and battery storage, these systems offer improved fuel efficiency and reduced emissions in varying operational profiles. Investment is concentrating in vessels requiring flexible power delivery and emissions compliance, particularly in coastal and port operations.
- Electric Motors:These systems provide zero-emission propulsion for shorter routes, powered by batteries or shore connections.
- Gas Turbines:Utilized for high-speed vessels and specialized naval applications, these engines offer compact power density.
- Steam Turbines:Primarily found in older vessels and specialized applications like LNG carriers, these systems use steam generated from boilers.
Technological advancements are shifting preferences towards cleaner and more efficient propulsion systems.
Application:
The intended mission profile dictates the specific design and equipping of marine vessels.
- Commercial Shipping:This application involves the global transport of goods and commodities, forming the backbone of international trade and supply chains. Demand concentrates in containerized trade routes connecting manufacturing hubs in Asia with consumer markets worldwide.
- Naval Operations:This segment includes military vessels, coast guard ships, and patrol boats designed for defense, security, and maritime surveillance. Investment is concentrating in advanced frigates, submarines, and support vessels to address evolving geopolitical security requirements.
- Maritime Transport:Encompasses passenger ferries, coastal cargo services, and regional shipping routes.
- Aquaculture:This application involves vessels used for fish farming, harvesting, and support services in marine environments.
- Oceanographic Research:Dedicated vessels conduct scientific exploration, environmental monitoring, and data collection in oceans.
Commercial applications dominate vessel demand; specialized uses like naval operations drive innovation.
End User:
Vessel ownership models and operational mandates define distinct end-user segments.
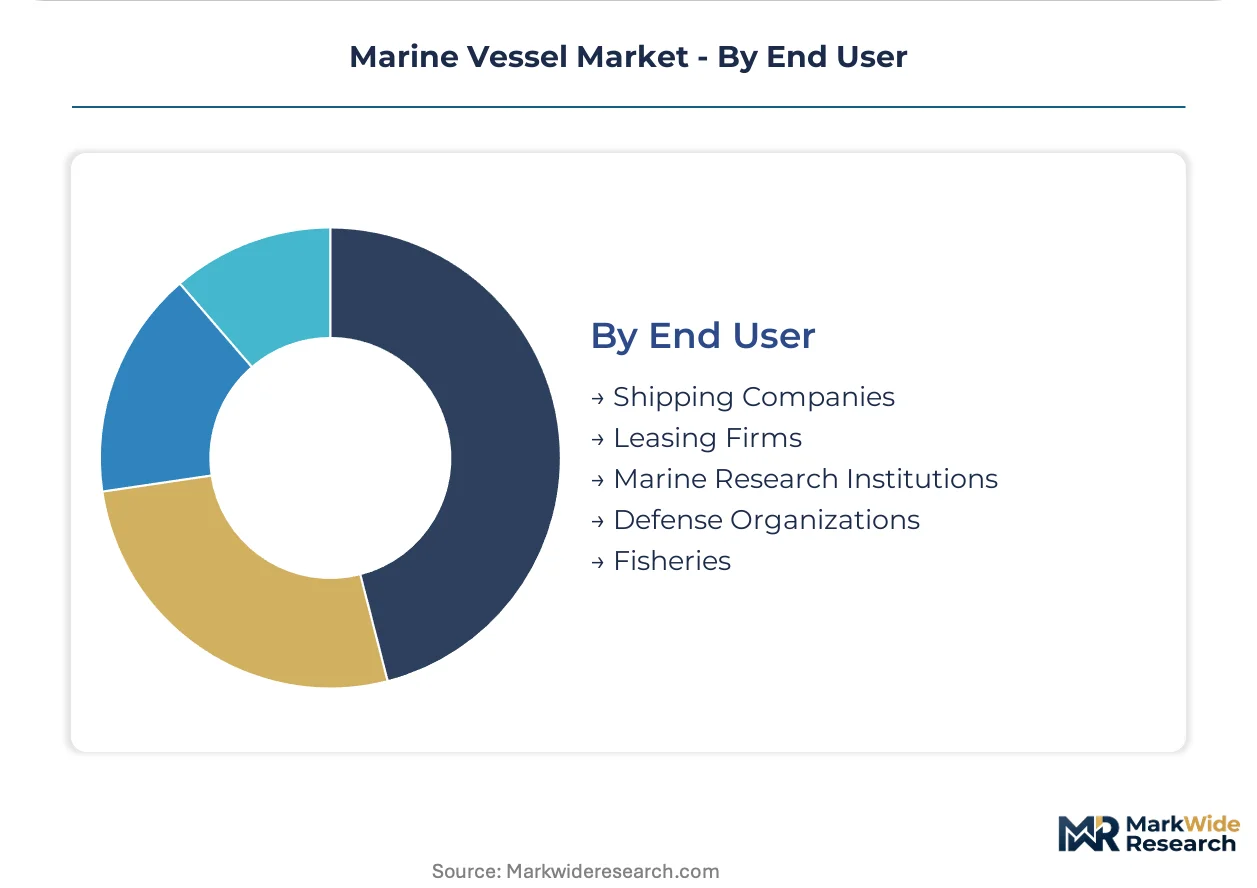
- Shipping Companies:These entities directly own and operate fleets of vessels for various cargo and passenger services, managing all aspects of vessel deployment. Demand for newbuilds and retrofits is concentrating as these companies seek to comply with IMO decarbonization mandates and modernize their assets.
- Leasing Firms:These financial institutions provide capital for vessel acquisition, offering bareboat charters and other leasing structures to shipping companies. Demand is concentrating from shipowners requiring flexible financing options for high-capital-intensity newbuilds and complex retrofits.
- Marine Research Institutions:These organizations utilize specialized vessels for scientific research and environmental studies.
- Defense Organizations:National navies and coast guards are primary end-users for military and security-related marine vessels.
- Fisheries:Commercial fishing operations and individual fishermen constitute this end-user group, operating various types of fishing vessels.
Shipping companies remain the largest end-user group; leasing firms offer critical capital solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled naval architects and experienced shipyard workforces anchor regional development within the global marine vessel market. These concentrations of engineering talent and manufacturing drive innovation in vessel design. Investment flows towards regions with established maritime infrastructure and decarbonization commitments.
China
China's manufacturing output drives demand for container ships and bulk carriers in global trade lanes. The nation's dual carbon goals influence shipbuilding with incentives for green vessel technologies. Major shipyards in the Yangtze River Delta, particularly around Shanghai, build dual-fuel vessels for international clients.
South Korea
South Korea's advanced shipbuilding industry benefits from strong orders for high-specification LNG carriers and methanol-powered ships. The Ministry of Oceans and Fisheries supports R&D into zero-emission propulsion. Ulsan and Geoje Island remain global centers for complex vessel construction, attracting significant capital.
Japan
Japanese shipping lines prioritize fleet modernization, spurring demand for energy-efficient vessels and specialized carriers. METI's Green Innovation Fund provides subsidies for developing next-generation maritime technologies. Imabari and Nagasaki continue as key shipbuilding hubs, focusing on high-quality, advanced vessel types.
Germany
German maritime clusters focus on specialized vessel segments, including cruise ships and offshore support vessels. The EU Green Deal and its emissions trading system accelerate alternative fuel transitions. Hamburg and Rostock serve as important centers for maritime engineering and port logistics innovation.
United States
United States domestic shipping and offshore energy projects generate demand for Jones Act compliant vessels and specialized support craft. The Inflation Reduction Act (IRA) encourages investment in offshore wind infrastructure. Shipyards along the Gulf Coast are expanding capabilities for naval and commercial newbuilds.
Marine Vessel Market Key Industry Players
Capital-intensive fleet owners investing in high-specification newbuilds compete with operators leveraging asset-light models or focusing on standardized carriers. The marine vessel market exhibits a tiered structure, with premium players prioritizing advanced technology and sustainability. Strategic archetypes include global liner services, specialized offshore support providers, and regional commodity transporters. Dominant competitive moves involve significant capital expenditure for fleet renewal and strategic partnerships for alternative fuel infrastructure development.
On the premium-tier vector, A.P. Moller-Maersk, a Danish-headquartered shipping giant, exemplifies commitment to decarbonization through investments in methanol-powered container ships and sustainable logistics solutions. In contrast, China-based COSCO Shipping Lines represents a scale-driven approach, leveraging vast fleet capacity to compete on cost within the standard cargo segment. French shipping group CMA CGM Group occupies a position balancing advanced LNG-powered vessels with conventional ships, demonstrating a mixed fleet strategy to serve diverse global routes and adapt to varying regulatory landscapes.
| Leading Market Players |
|---|
| COSCO Shipping Lines |
| Evergreen Marine Corporation |
| Mediterranean Shipping Company |
| Hyundai Merchant Marine |
| Ocean Network Express |
| A.P. Moller-Maersk |
| Hapag-Lloyd |
| Yang Ming Marine Transport Corporation |
| CMA CGM Group |
| Others |
Cost & Logistics Intelligence
High-grade steel plate costs significantly influence newbuild vessel pricing, where shipyard concentration determines margin capture across premium and standard tiers. This cost component traces its path from upstream raw material suppliers through vessel construction to final delivery, impacting pricing power downstream.
Pricing Analysis
Bundled service agreements often accompany high-specification newbuild vessels, contrasting with transactional per-unit pricing for standard commodity carriers. Pricing stratifies across premium, standard, and economy tiers based on advanced propulsion technology and sustainability certifications like IMO compliance. Pricing softness stems from intense competition among shipyards for volume orders in the standard cargo segment. Shipping companies operating in spot markets exhibit the highest price sensitivity, while long-term charterers for specialized vessels are less sensitive.
Supply Chain Analysis
Direct shipyard sales channels handle the majority of new marine vessel deliveries to shipping companies and leasing firms. Vessel construction concentrates in South Korea, China, and Japan, which collectively source high-grade steel plate, complex engine components, and advanced navigation systems. Single-source vulnerability for specialized equipment presents a structural supply chain risk. Leasing firms and shipping companies rely on these concentrated shipbuilding hubs for fleet renewal and expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine vessel market presents a geographic-arbitrage opportunity, as manufacturing costs for high-specification newbuilds differ significantly between South Korean and Chinese shipyards. This differential influences procurement strategies for global shipping lines seeking optimal capital deployment.
For Market Incumbents:To counter margin erosion from new entrants in standard cargo segments, incumbent shipping companies should invest in advanced digital fleet management systems for operational efficiency. Consolidate purchasing power for alternative fuels like methanol to secure long-term supply contracts. Strategic partnerships for green shipping corridor development reinforce compliance with EU emissions trading system regulations.
For New Entrants and Emerging Players:Capture demand in specialized offshore wind support vessels, particularly in the North Sea and U.S. Atlantic coast, where infrastructure buildout requires unique capabilities. Focus on retrofitting existing mid-life vessels with carbon capture technologies, offering a cost-effective compliance solution. A direct-to-owner sales approach emphasizing rapid deployment and certified emissions reduction provides a strong go-to-market angle.
For Investors and Strategic Acquirers:Consolidation pressure builds where capital intensity for decarbonization mandates strains smaller, independent shipowners. Over the next decade, long-term viability favors entities with diversified fleets and access to green financing. Target mid-sized shipping companies with strong regional route networks and an existing order book for dual-fuel newbuilds. The signal to watch is the accelerated retirement rate of non-compliant older vessels.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Modernization with Dual-Fuel Vessels | Ensures compliance with IMO emissions standards for container and tanker segments. |
| Investment in Offshore Wind Support Fleet | Captures new demand from expanding offshore wind farms in the North Sea. |
| Development of Carbon Capture Retrofit Solutions | Extends the operational lifespan of mid-life vessels for independent shipowners. |
| Strategic Partnerships for Alternative Fuel Bunkering | De-risks investment in zero-emission ships by addressing fuel infrastructure gaps. |
| Digitalization of Vessel Operations | Improves operational efficiency and CII ratings for bulk carrier segments. |
Research Approach
Coverage spans Asia-Pacific, Europe, and North America, with primary inputs from each region validating market dynamics. Interviews included naval architects, shipyard executives, shipping company fleet managers, and port authorities. Secondary sources comprised IMO reports, national maritime administration data, and trade association publications. This approach ensured robust bottom-up and top-down triangulation for market sizing.
Rate-of-change decomposition models underpinned the forecast framework, projecting market evolution across the analysis window. Segmentation dimensions included vessel type, propulsion, application, and end-user, alongside regional trade lane activity. Compound annual growth rates were derived from historical trends and projected future demand. Key inputs included newbuild order books and alternative fuel adoption rates.
Geopolitical instability, commodity price volatility, and unforeseen regulatory shifts are the dominant revision risks for market forecasts. Forecasts reflect assumptions regarding global trade growth and decarbonization timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Marine Lubrication System Market
Maritime Equipment
Europe Offshore Support Vessels Market
Maritime Equipment
United States Maritime Information Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Ship Anchor Market
Maritime Equipment
Middle East Offshore Support Vessels Market
Maritime Equipment
Ship Plate Market
Maritime Equipment
Global Digital Shipyard Market
Maritime Equipment
Marine Fire-Fighting Equipment Market
Maritime Equipment
Barge Transportation Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Container Docking Stations Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Saudi Arabia Offshore Support Vessel (OSV) Market