
 Vessel Tracking System Market | 2026-2036
Vessel Tracking System Market Size, Share, and Industry Trends Forecast 2026-2036
Vessel Tracking System Market Analysis
IMO SOLAS amendments are realigning the cost-of-entry calculus for vessel tracking providers. L3Harris Technologies leverages its defense-electronics heritage to dominate encrypted AIS transponder supply for naval fleets. Kongsberg Gruppen anchors Nordic market share through integrated bridge systems that bundle tracking with dynamic positioning. Spire Global competes via its satellite-constellation density, offering commercial shippers global coverage without terrestrial infrastructure dependency.
A vessel tracking system comprises hardware-software architectures that acquire, process, and disseminate positional telemetry from maritime assets, typically integrating GPS receivers, AIS transceivers, and satellite communication modems operating across VHF marine bands and L-band frequencies. These systems serve commercial and governmental operators by preventing collision, optimizing route efficiency, and enforcing territorial compliance. Satellite communication technology captures premium margin pools due to coverage advantages in open-ocean corridors beyond terrestrial AIS range. Cloud-based deployment is displacing on-premise installations among logistics companies seeking scalable fleet analytics without capital-intensive infrastructure. Government agencies remain tethered to hybrid architectures balancing cybersecurity control with remote accessibility.
The International Maritime Organization mandates AIS carriage for vessels exceeding gross tonnage thresholds, while national regulators including the US Coast Guard and Maritime and Port Authority of Singapore enforce port-state control inspections that verify transponder functionality. The EU MRV Regulation and impending FuelEU Maritime standards are extending tracking data requirements into emissions-accounting domains, compelling operators to retrofit systems with fuel-flow monitoring integration. Stakeholders must evaluate whether their current technology stacks can absorb these layered compliance obligations without fragmenting data architectures.
Market Dynamics
The Vessel Tracking System Market pivots on the collision between open-ocean satellite coverage mandates and port-authority demands for terrestrial AIS granularity. Operators now face dual-stack architecture requirements that fuse L-band satellite modems with VHF coastal receivers.
Growth Catalysts
- IMO SOLAS carriage requirements:The International Maritime Organization's updated Safety of Life at Sea protocols tighten automatic identification system mandates for vessels above gross tonnage thresholds, forcing fleet-wide retrofits.
- EU MRV and FuelEU Maritime:European emissions-accounting regulations extend tracking data requirements into fuel-flow monitoring domains, compelling integrated sensor deployments.
- East Asian shipping corridor density:Concentrated traffic between Shanghai, Busan, and Kaohsiung generates collision-avoidance demand that outstrips legacy radar capabilities.
Market Restraints
- Neodymium magnet supply concentration:Rare-earth dependency for GPS receiver components concentrates in Chinese processing facilities, exposing hardware manufacturers to input volatility.
- Encrypted military-grade AIS fragmentation:Naval fleets operate non-interoperable frequency bands that commercial providers cannot access, segmenting addressable demand.
- L-band spectrum licensing friction:National telecom regulators impose orbital slot coordination delays that extend satellite constellation deployment timelines.
Strategic Opportunities
- Cloud-native fleet analytics:Logistics operators are abandoning on-premise installations for scalable subscription architectures that eliminate capital-intensive infrastructure.
- Indonesian archipelago coverage gaps:Terrestrial AIS infrastructure remains sparse across the country's 17,000 islands, creating demand for satellite-dependent tracking solutions.
- Dynamic positioning convergence:Integration of vessel tracking with automated station-keeping systems opens bridge-system bundling opportunities for Nordic equipment suppliers.
Industry Challenges
- Cybersecurity certification timelines:Government agencies demand hybrid architectures balancing remote accessibility with classified network isolation, extending procurement cycles.
- Legacy radar integration complexity:Retrofitting satellite-AIS fusion onto existing bridge electronics requires custom middleware development that strains systems integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vessel Tracking System Market |
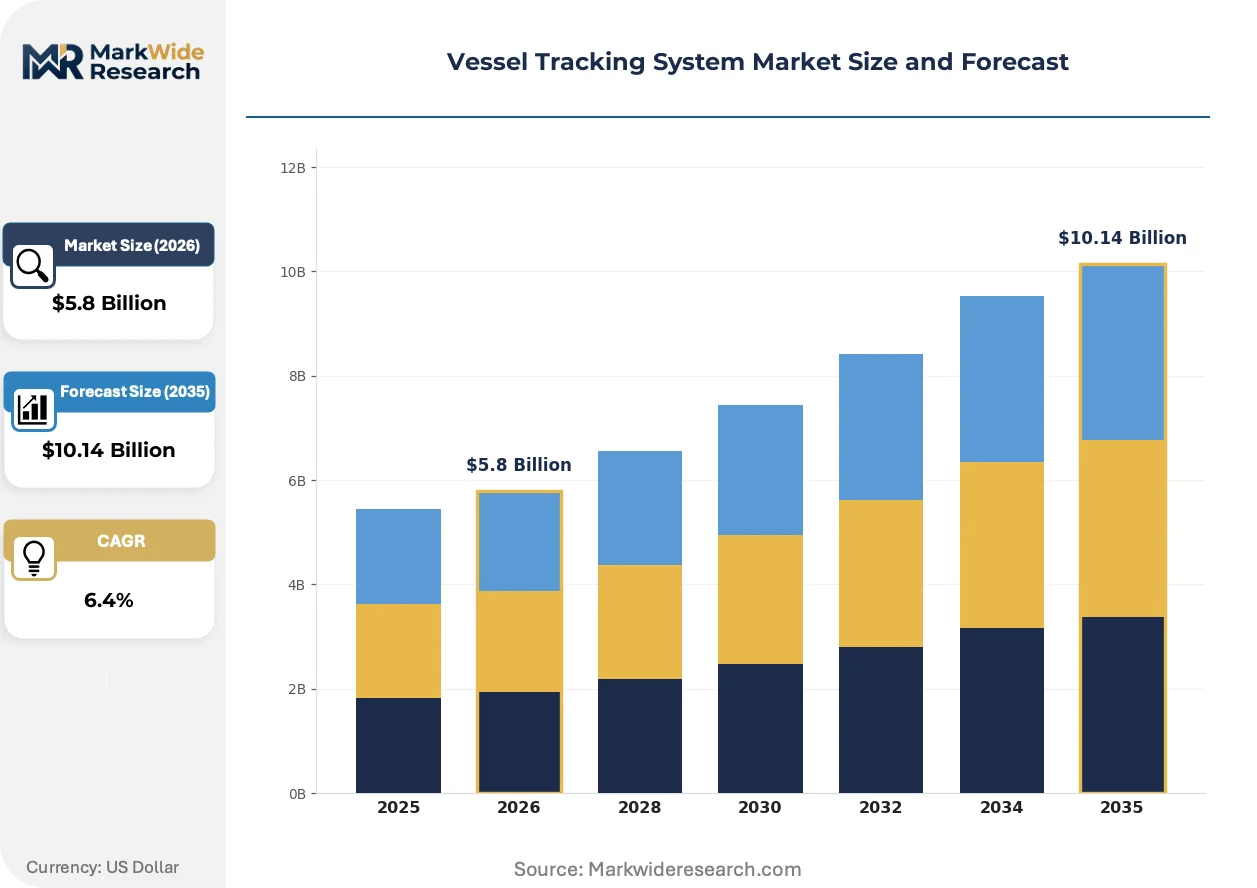
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, AIS, RFID, Satellite Communication Application: Commercial Shipping, Fishing Industry, Naval Operations, Recreational Boating End User: Logistics Companies, Port Authorities, Shipping Operators, Government Agencies Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | L3Harris Technologies, Inc., Garmin Ltd., ORBCOMM Inc., Indra Sistemas, MarineTraffic, Kongsberg Gruppen ASA, Spire Global / exactEarth, Windward, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vessel Tracking System Market Emerging Trajectories
Real-time telemetry architectures are bifurcating between cloud-scalable commercial deployments and hardened governmental hybrids. Three forces are compressing vendor margins while expanding functional requirements.
Low-earth-orbit satellite constellations are absorbing the coverage burden previously shouldered by geostationary relays. Commercial shippers operating trans-Pacific routes now demand continuous position reporting beyond coastal VHF range. This technology is absorbing the premium pricing power that terrestrial infrastructure once commanded in open-ocean corridors.
REACH chemical substance restrictions and impending EU AI Act classifications are reshaping hardware material compliance. Transponder manufacturers must now document supply-chain provenance for circuit-board substrates and antenna coatings. European port-state control inspections have intensified documentation verification, forcing suppliers to requalify component vendors.
Charterers now unbundle tracking-data access from vessel-hire agreements, purchasing telemetry subscriptions directly from satellite operators. This disintermediation severs the traditional link between shipowners and analytics providers. The pattern is most pronounced in Singapore-registered fleets, where commodity traders demand independent cargo-position verification.
Vessel Tracking System Market Segmentation
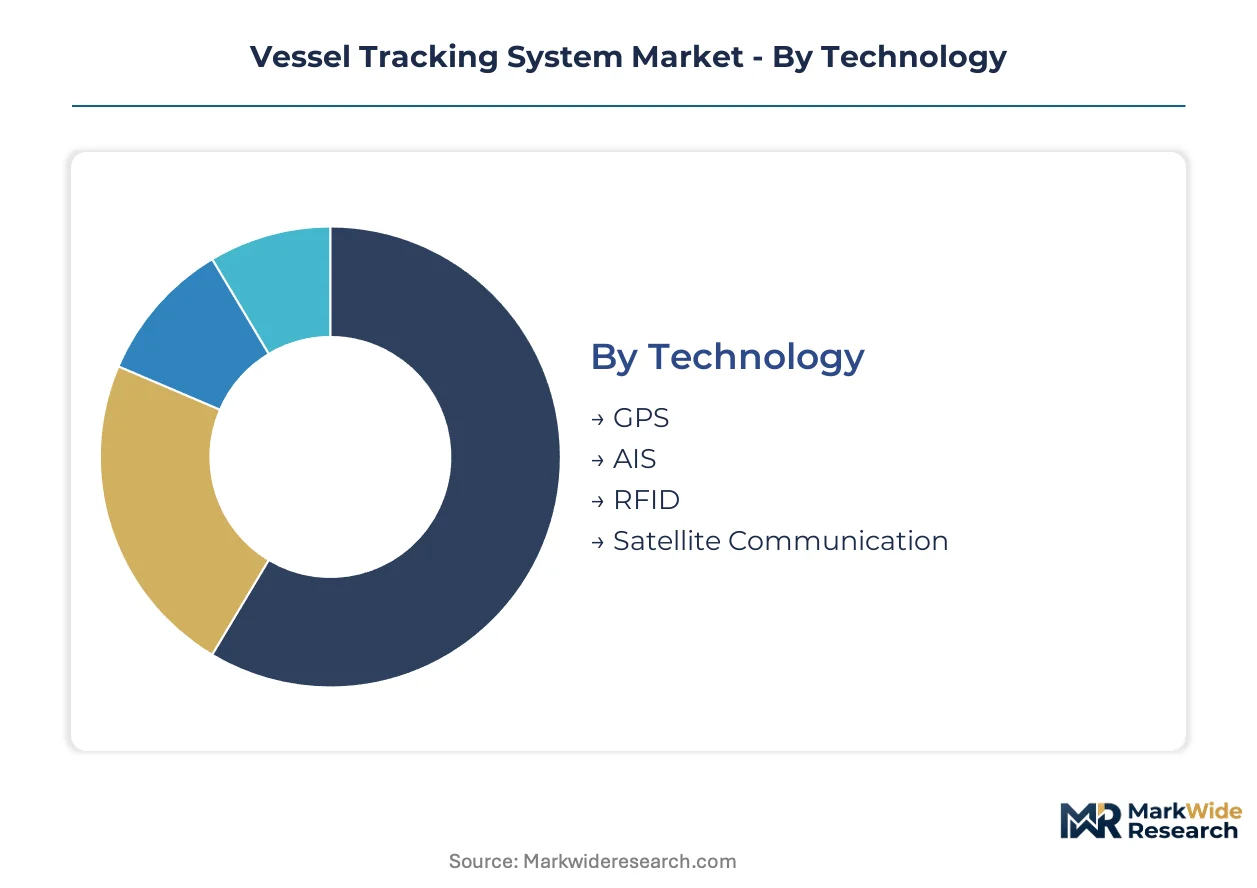
Vessel tracking architectures fragment across certification requirements that vary by maritime domain. IMO SOLAS mandates, EU MRV compliance, and national port-state control regimes each impose distinct technical specifications that segment procurement patterns across fleet operators.
Technology:
IMO SOLAS mandates AIS carriage for vessels above gross tonnage thresholds, while EU MRV and FuelEU Maritime extend certification into emissions-accounting sensor integration. GPS and satellite communication modules face additional FCC and CE marking requirements for radio frequency equipment.
- AIS:Automatic Identification Systems transmit vessel identity, position, course, and speed via VHF marine bands. Port authorities in Rotterdam and Singapore mandate real-time AIS granularity for port entry clearance, driving dual-stack architectures that fuse coastal VHF receivers with satellite backhaul.
- Satellite Communication:L-band and VSAT modems deliver continuous position reporting beyond terrestrial AIS range in open-ocean corridors. Commercial shippers operating trans-Pacific routes demand this capability for cargo-position verification independent of vessel-hire agreements.
- GPS:Global Positioning System receivers provide foundational positional telemetry for integrated bridge systems. Neodymium magnet supply concentration in Chinese processing facilities exposes hardware manufacturers to input volatility.
- RFID:Radio-frequency identification tags enable short-range asset tracking for container inventory and port-yard logistics. Terminal operators in Busan and Kaohsiung deploy RFID for automated gate processing and yard-stack verification.
Leading the category by volume: AIS. Expanding most quickly: Satellite Communication.
Application:
Cost tier differentiation separates capital-intensive naval retrofits from subscription-based commercial deployments. Fishing industry operators face distinct regulatory burdens under regional fisheries management organization mandates.
- Commercial Shipping:Container lines and bulk carriers require continuous global coverage for route optimization and fuel-flow monitoring. EU MRV and impending FuelEU Maritime standards compel integrated sensor deployments that track emissions-accounting data alongside positional telemetry.
- Naval Operations:Military fleets operate encrypted AIS transponders on non-interoperable frequency bands that commercial providers cannot access. This segmentation limits addressable demand to defense-electronics specialists with classified network certification.
- Fishing Industry:Regional fisheries management organizations mandate vessel monitoring systems for quota enforcement and illegal fishing interdiction. Indonesian archipelago coverage gaps create demand for satellite-dependent tracking solutions among distant-water fleets.
- Recreational Boating:Leisure craft operators seek portable or mobile-integrated solutions for coastal navigation safety. US Coast Guard carriage requirements apply to vessels above specified length thresholds, creating tiered compliance obligations.
Dominant by revenue: Commercial Shipping. Steepest expansion trajectory: Naval Operations.
End User:
Customer type determines procurement cycle length and cybersecurity architecture requirements. Government agencies demand hybrid deployments balancing remote accessibility with classified network isolation.
- Shipping Operators:Fleet managers retrofit bridge electronics with satellite-AIS fusion systems to satisfy port-state control inspections. Legacy radar integration complexity strains systems integrators with custom middleware development requirements.
- Government Agencies:Coast guards and maritime safety administrations enforce territorial compliance through hybrid architectures. Cybersecurity certification timelines extend procurement cycles beyond commercial procurement patterns.
- Logistics Companies:Third-party logistics providers abandon on-premise installations for scalable cloud-native fleet analytics. Subscription architectures eliminate capital-intensive infrastructure while enabling real-time cargo-position verification.
- Port Authorities:Terminal operators in Shanghai and Singapore expand real-time fleet visibility mandates for collision avoidance. VHF coastal receiver density requirements drive infrastructure investment in East Asian shipping corridors.
Highest procurement volume: Shipping Operators. Gaining share fastest: Logistics Companies.
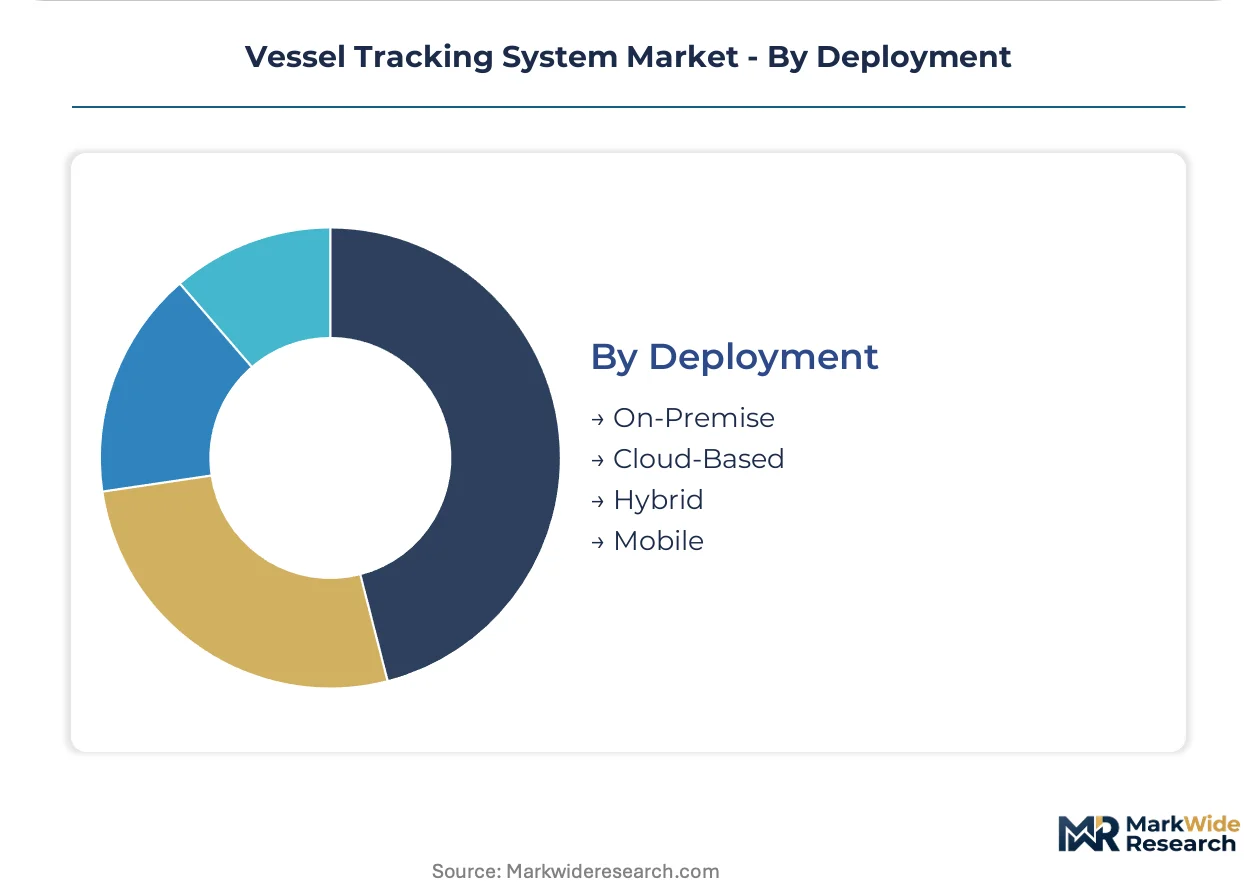
Deployment:
Supply concentration in cloud infrastructure providers is reshaping vendor competitive positioning. On-premise installations retain foothold among operators with stringent data sovereignty requirements.
- Cloud-Based:Scalable subscription architectures enable logistics operators to access fleet analytics without capital-intensive infrastructure. Spire Global and satellite operators offer commercial shippers global coverage through constellation density without terrestrial dependency.
- Hybrid:Government agencies balance cybersecurity control with remote accessibility through mixed on-premise and cloud architectures. This deployment mode captures premium margin pools due to extended certification timelines.
- On-Premise:Dedicated server installations serve operators with classified network isolation requirements or data sovereignty constraints. Nordic equipment suppliers bundle hybrid deployments with integrated bridge systems.
- Mobile:Smartphone and tablet applications provide recreational boaters with portable navigation assistance. Limited functionality relative to dedicated transponder hardware constrains adoption in commercial maritime domains.
Current volume leader: Hybrid. Climbing the fastest: Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Singapore and Rotterdam anchor vessel tracking demand concentration. Port authorities in both jurisdictions enforce real-time fleet visibility mandates that drive dual-stack architecture procurement. These regulatory environments create tiered compliance obligations that ripple through connected shipping corridors.
United States
The US Coast Guard enforces port-state control inspections that verify AIS transponder functionality for vessels entering domestic waters. FCC certification requirements for L-band satellite modems extend deployment timelines for hardware manufacturers. Houston and Long Beach port complexes generate concentrated demand for collision-avoidance systems as container traffic volumes strain legacy radar capabilities.
Singapore
The Maritime and Port Authority mandates real-time AIS granularity for port entry clearance across Southeast Asian shipping lanes. National regulations require dual-stack architectures fusing coastal VHF receivers with satellite backhaul for continuous coverage. The Tuas Port expansion and adjacent anchorage zones drive infrastructure investment for terminal operators managing dense vessel traffic.
Germany
The Hamburg Port Authority enforces emissions-accounting data collection under EU MRV Regulation for vessels calling Northern European hubs. REACH chemical substance restrictions reshape hardware material compliance for transponder manufacturers supplying the market. The Elbe River corridor concentrates shipyard retrofit activity as fleet operators prepare for impending FuelEU Maritime standards.
China
Shanghai International Shipping Institute coordinates port digitalization initiatives that integrate vessel tracking with automated terminal operations. MIIT radio frequency equipment certification governs GPS receiver and satellite modem deployments for domestic fleet operators. The Yangtze River Delta shipping corridor generates collision-avoidance demand that outstrips terrestrial AIS infrastructure capacity.
Netherlands
Rotterdam Port Authority mandates real-time fleet visibility for vessels navigating Europe's largest container hub. CE marking requirements for radio frequency equipment impose additional compliance layers on hardware suppliers serving Dutch terminals. The Maasvlakte expansion zones drive investment in VHF coastal receiver density for precision traffic management.
Vessel Tracking System Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the vessel tracking system market. Tier-one defense-electronics conglomerates leverage classified network certification to capture naval fleet contracts, while satellite operators compete on constellation density for commercial shipping coverage. Three strategic archetypes dominate: integrated bridge system bundlers, satellite-constellation operators, and defense-specialist transponder manufacturers. Competitive moves center on cloud-native platform launches and hybrid architecture certifications for government agency procurement.
Within the defense-specialist tier, L3Harris Technologies, Inc. and Thales Group occupy positions anchored by encrypted AIS heritage and classified program access. Among satellite-constellation operators, Spire Global / exactEarth exemplifies the pure-play model competing via orbital density without terrestrial infrastructure dependency. Kongsberg Gruppen ASA represents the Nordic integrated-systems archetype, bundling tracking with dynamic positioning for bridge-system deployments.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| Garmin Ltd. |
| ORBCOMM Inc. |
| Indra Sistemas |
| MarineTraffic |
| Kongsberg Gruppen ASA |
| Spire Global / exactEarth |
| Windward |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
L-band spectrum auction benchmarks cascade through satellite modem procurement into three-tier pricing structures across premium, standard, and economy certification levels. Neodymium magnet spot indices transmit volatility into GPS receiver manufacturing costs, compressing margins for hardware vendors serving price-sensitive logistics operators while naval fleets absorb premium markups for encrypted transponder architectures.
Pricing Analysis
Short-lead-time premiums of fifteen to twenty percent apply to satellite-AIS fusion systems required for Singapore port entry clearance, while spot inventory discounts attract recreational boating segments with flexible deployment timelines. Subscription-based SaaS pricing dominates commercial shipping, with differentiation anchored in CE marking tiers and after-sales service bundling. Price erosion runs through standard-grade hardware as Chinese manufacturers expand L-band modem production capacity. Logistics companies exhibit highest price sensitivity, whereas government agencies prioritize cybersecurity certification over unit cost.
Supply Chain Analysis
Refurbished transponder flows from European naval decommissioning programs feed secondary markets across Southeast Asian fishing fleets, extending component lifecycles. Manufacturing concentrates in China, South Korea, and Germany for GPS receivers, satellite modems, and precision antenna assemblies respectively. Rare-earth magnet processing draws from Chinese facilities, exposing hardware producers to single-source vulnerability. Distribution runs through OEM direct channels for naval contracts and satellite operator platforms for commercial subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
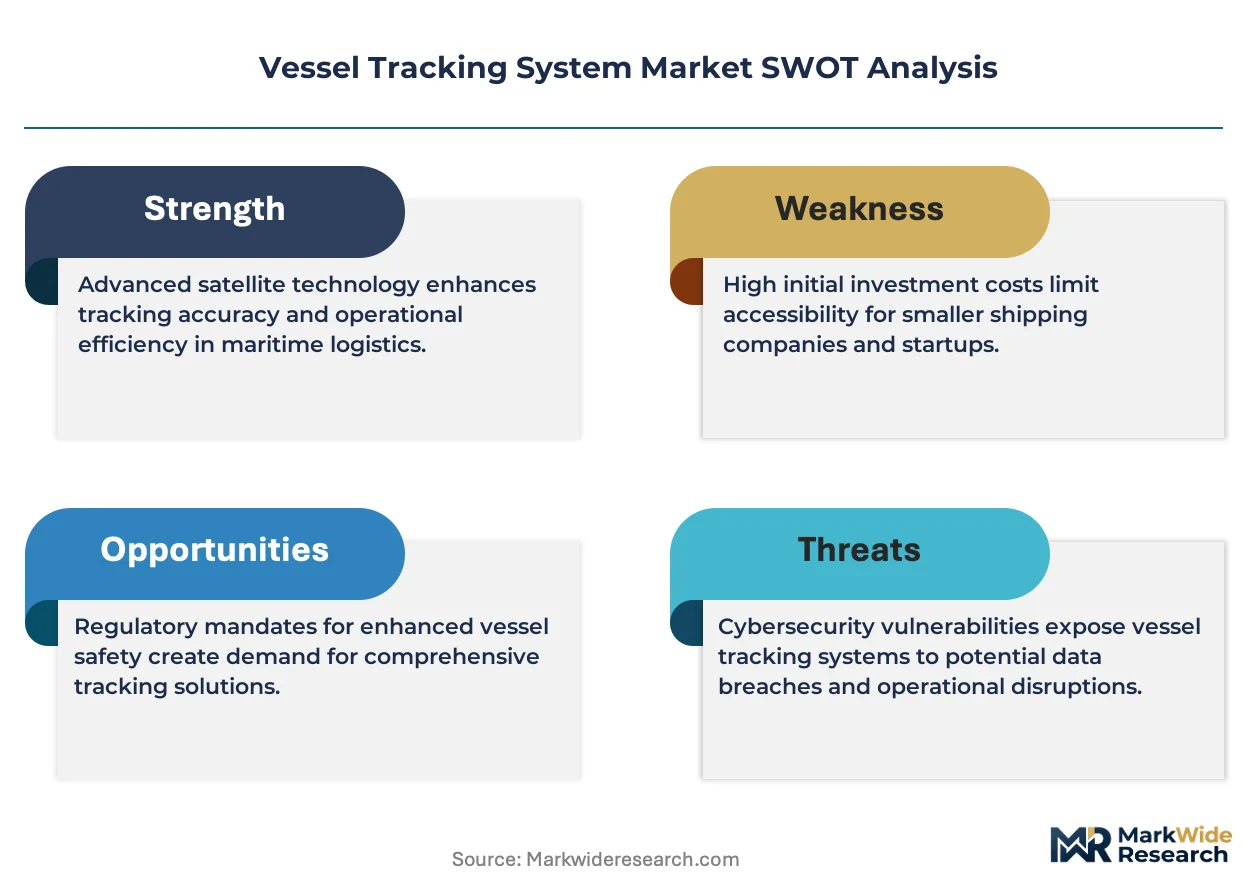
The Vessel Tracking System Market functions as a cost-of-compliance arena where IMO SOLAS carriage mandates erect certification barriers that filter out undercapitalized competitors. Fleet operators face retrofit obligations that favor incumbent providers with established type-approval portfolios.
For Market Incumbents: Extend cloud-native platform architectures to capture logistics company procurement shifts away from capital-intensive on-premise installations. Consolidate position through backward integration into L-band modem manufacturing to offset spectrum licensing cost inflation. Counter emerging satellite-constellation pure-plays by bundling tracking with dynamic positioning systems for Nordic shipyard contracts. For New Entrants and Emerging Players: Enter via Indonesian archipelago coverage gaps where terrestrial AIS infrastructure remains sparse across seventeen thousand islands. Target distant-water fishing fleets with satellite-dependent monitoring solutions under regional fisheries management organization mandates. Pursue commodity trader direct relationships in Singapore to bypass shipowner intermediation in cargo-position verification. For Investors and Strategic Acquirers: Distressed-cycle entries favor defense-electronics specialists with classified network certification in German and French naval supply chains. Long-term viability hinges on dual-use technology positioning across commercial and governmental procurement streams. Monitor EU FuelEU Maritime implementation intensity as inflection signal for integrated sensor deployment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Launch | Spire Global and satellite operators disintermediate shipowners through direct telemetry subscriptions to charterers. |
| Hybrid Architecture Certification | Government agencies in Rotterdam and Singapore extend procurement cycles for cybersecurity-compliant tracking deployments. |
| Backward Integration into L-Band Manufacturing | Hardware vendors reduce spectrum licensing friction exposure through captive modem production capacity. |
| Dynamic Positioning Convergence | Kongsberg Gruppen bundles tracking with automated station-keeping for Nordic integrated bridge system contracts. |
| Indonesian Archipelago Coverage Expansion | Satellite operators capture distant-water fishing fleet demand beyond terrestrial AIS infrastructure reach. |
Methodological Framework
Document review covered IMO SOLAS amendment texts, EU MRV implementing regulations, and FCC equipment authorization databases, complemented by interviews with fleet operations directors, maritime safety administration procurement officers, satellite constellation program managers, and port authority traffic control leads. Secondary validation drew from US Coast Guard port-state control inspection records, Maritime and Port Authority of Singapore circulars, and L-band spectrum allocation filings. Bottom-up vessel count modeling triangulated against top-down fleet operator expenditure surveys.
Segmentation outputs across technology, application, end user, and deployment mode informed volume projections throughout the forecast period. CAGRs derived from historical AIS carriage mandate adoption curves and satellite communication module price elasticity estimates. Industry-specific inputs included FuelEU Maritime regulatory timeline assumptions and East Asian shipping corridor traffic density forecasts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated IMO decarbonization mandates or L-band spectrum auction disruptions. Practitioners should monitor Indonesian infrastructure investment announcements and EU port-state control inspection intensity for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Offshore Support Vessel Service Market
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Global Maritime Safety Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
Ship Breaking Market