
 North America Offshore Support Vessels Market | 2026-2036
North America Offshore Support Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
North America Offshore Support Vessels Market Analytics
Dynamic Positioning Class 2 and Class 3 specification upgrades is unwinding across the North America fleet as operators face deeper-water assignments. Edison Chouest Offshore leverages its captive shipyard network to control newbuild delivery timelines. Tidewater Inc. anchors its competitiveness through a consolidated Gulf of Mexico logistics hub. Hornbeck Offshore Services specializes in high-specification multipurpose vessels for subsea construction campaigns.
Offshore support vessels are purpose-built marine craft typically ranging from 50 to 150 meters in length, equipped with diesel-electric or hybrid propulsion systems, and rated for specific bollard pull capacities and deck load thresholds to service oil, gas, and offshore wind installations. Platform supply vessels dominate current fleet composition due to steady consumables replenishment cycles for floating production units. Anchor handling tug supply units capture premium day rates in subsea installation support. Crew boat demand from renewable energy providers shows the fastest structural expansion as offshore wind lease rounds advance.
The US Bureau of Safety and Environmental Enforcement and the US Coast Guard enforce station-keeping and lifesaving equipment standards that elevate newbuild specifications above legacy tonnage. The International Maritime Organization's Tier III NOx emissions framework, adopted into US EPA marine engine regulations, accelerates engine retrofit and replacement cycles. Stakeholders must weigh charter-rate visibility against capital commitments for dual-fuel propulsion configurations before committing to yard slots.
Market Dynamics
Deepwater exploration contractors in the Gulf of Mexico are forcing rapid fleet renewal as station-keeping reliability requirements tighten under federal safety mandates. The US Bureau of Safety and Environmental Enforcement's stricter MODU support standards have rendered legacy tonnage economically unviable for new assignments.
Growth Catalysts
- US Bureau of Safety and Environmental Enforcement station-keeping mandates:Stricter reliability standards for MODU support operations are accelerating replacement of aging anchor handling tug supply units across the Louisiana-Texas corridor.
- Offshore wind lease rounds:Crew boat demand from renewable energy providers is structurally expanding as Atlantic coast lease areas advance through permitting and construction phases.
- Tier III NOx emissions framework:EPA marine engine regulations adopted from International Maritime Organization standards are compressing engine replacement cycles and creating newbuild demand.
Market Restraints
- Steel and marine equipment cost volatility:Fluctuations in high-tensile steel plate and specialized deck machinery pricing compress newbuild margins and extend payback periods for vessel owners.
- Gulf Coast shipyard concentration:Limited builder capacity along the Louisiana-Texas corridor creates queue bottlenecks and extends delivery timelines for platform supply vessel orders.
- Dual-fuel propulsion technical limitations:Methanol and ammonia bunkering infrastructure gaps constrain fuel flexibility specifications despite charterer preferences for future-proofed tonnage.
Strategic Opportunities
- Canadian Atlantic offshore wind:Newfoundland and Nova Scotia lease areas present underpenetrated demand for crew transfer vessels and construction support craft as provincial renewable targets harden.
- Hybrid-electric technology convergence:Battery-hybrid diesel-electric architectures paired with dynamic positioning systems enable fuel consumption reductions that differentiate charter bids.
- US Coast Guard subchapter M compliance services:Third-party vessel inspection and maintenance outsourcing creates recurring revenue streams for established Gulf of Mexico operators.
Industry Challenges
- Marine engineer and DP operator talent scarcity:Certified dynamic positioning officers with Class 2 and Class 3 credentials command premium wages and constrain fleet utilization rates.
- US Coast Guard certification timeline compression:Subchapter M inspection backlogs and certificate of inspection renewals delay vessel redeployment between charter contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Offshore Support Vessels Market |
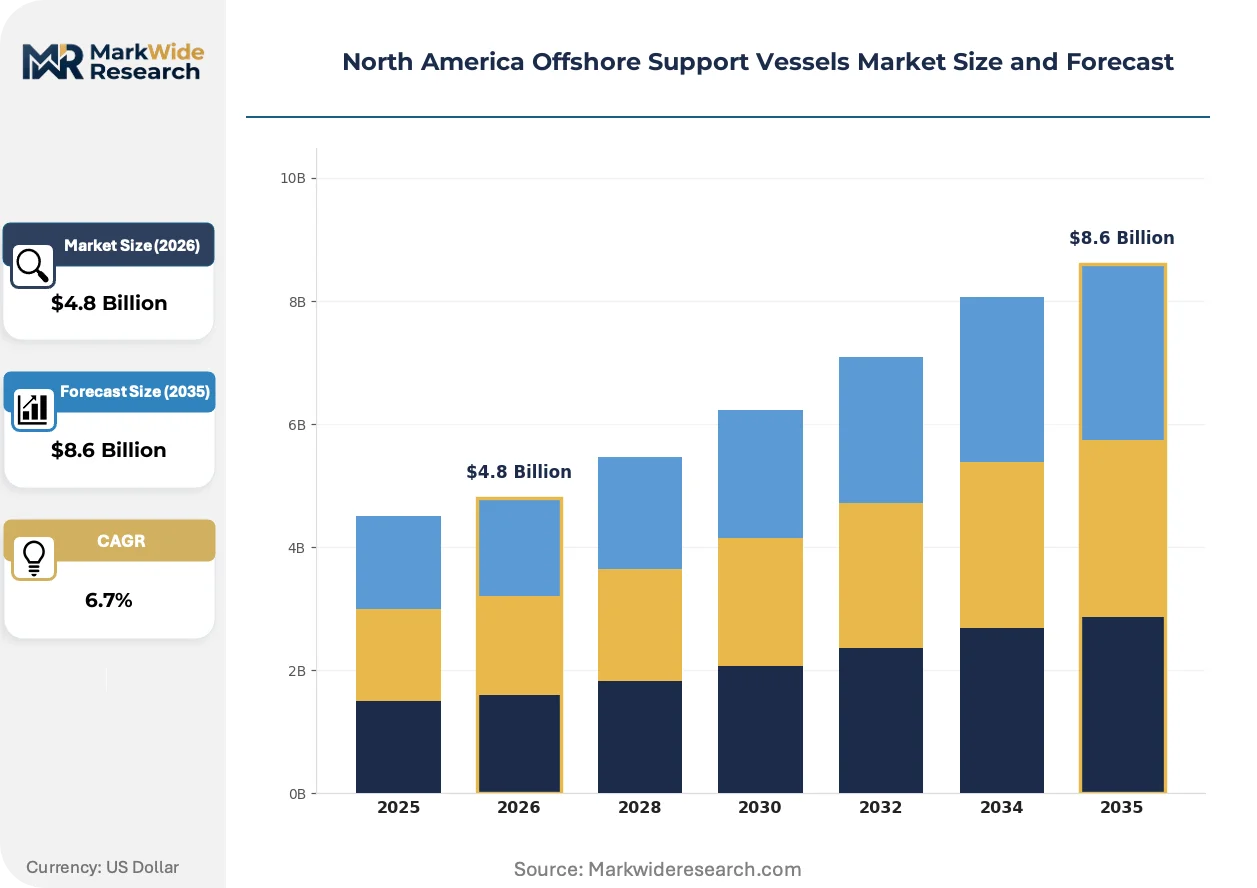
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Anchor Handling Tug Supply, Platform Supply Vessel, Multipurpose Support Vessel, Crew Boat Service Type: Logistics Support, Maintenance Services, Construction Support, Emergency Response End User: Oil & Gas Companies, Renewable Energy Providers, Marine Contractors, Research Institutions Operation Method: Dynamic Positioning, Conventional Anchoring, ROV Support, Survey Operations |
| Companies Covered | Edison Chouest Offshore, Tidewater Inc., Hornbeck Offshore Services, Inc., Harvey Gulf International Marine LLC, SEACOR Marine Holdings Inc., Siem Offshore Inc., Otto Candies, LLC, Galliano Marine Service, Abdon Callais Offshore, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Offshore Support Vessels Market Evolving Landscape
Propulsion architecture and emissions compliance systems are actively reshaping vessel specifications across North American offshore fleets. Charterers now prioritize fuel flexibility and reduced carbon intensity in tender evaluations.
Battery-hybrid energy storage systems are miniaturizing. These modular lithium-ion banks buffer load spikes during dynamic positioning operations and enable engine downsizing without sacrificing station-keeping redundancy. Deepwater drillship contractors are specifying hybrid configurations on new platform supply vessel charters to meet Scope 3 reporting obligations. The technology is compressing fuel consumption benchmarks and resetting competitive bidding thresholds for Gulf of Mexico logistics contracts.
The US EPA Tier III NOx emissions framework mandates selective catalytic reduction or exhaust gas recirculation on marine diesel engines above 130 kW. Vessel owners face retrofit obligations or accelerated scrapping of pre-2016 tonnage. Platform supply vessels with older engine installations are experiencing charter rate compression as major oil companies enforce sustainability clauses in supply agreements.
Charterers are consolidating preferred supplier lists and extending contract durations to secure high-specification tonnage. Integrated logistics providers are displacing spot-market vessel brokers in platform supply vessel procurement. This concentration is most visible along the Louisiana-Texas corridor where supermajor operators have reduced active supplier panels from twelve to four vendors over the past contract cycle.
North America Offshore Support Vessels Market Segmentation
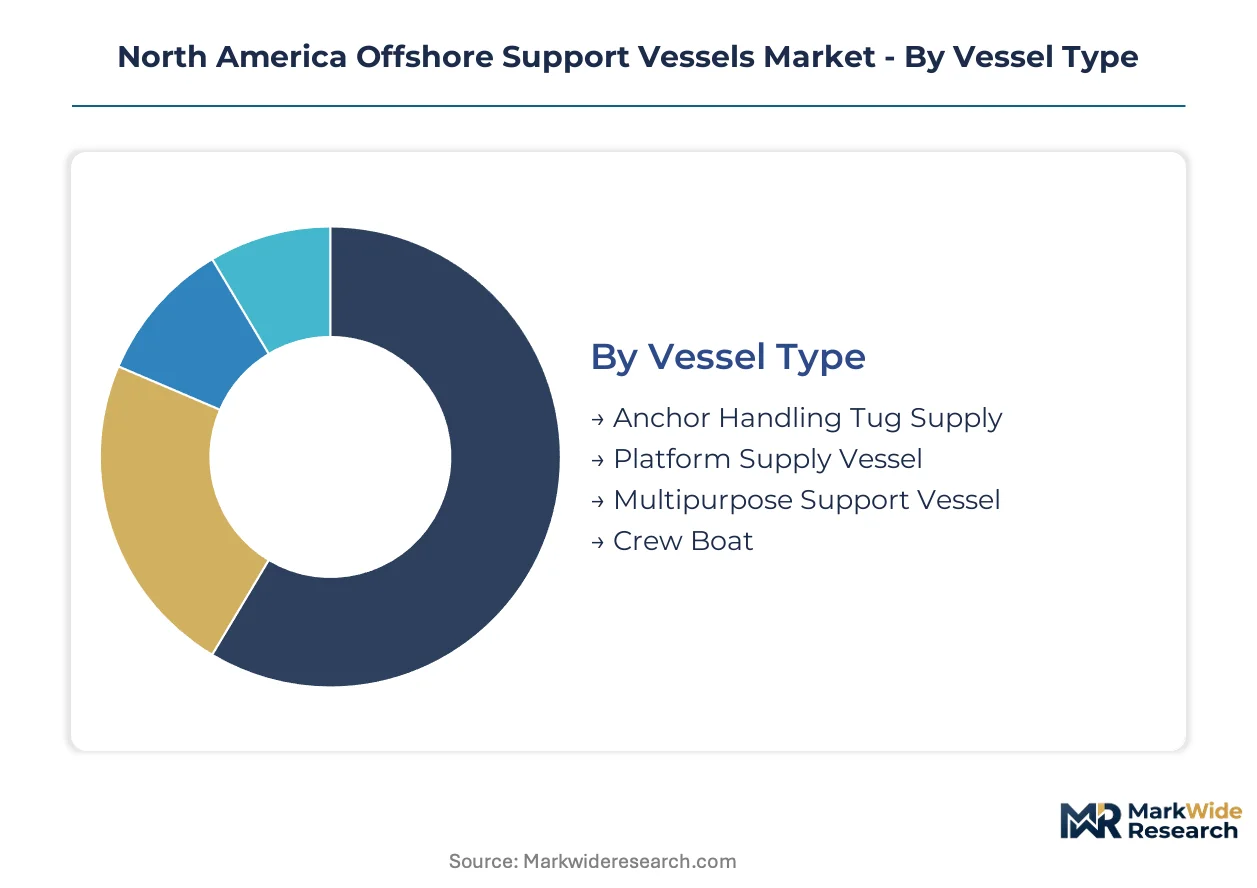
Offshore support vessel procurement in North America follows distinct technical and commercial logics that reshape fleet composition. Charterers segment requirements by water depth, station-keeping complexity, and regulatory exposure rather than tonnage alone.
Vessel Type:
US Bureau of Safety and Environmental Enforcement station-keeping mandates create divergent compliance burdens across hull configurations, concentrating investment in certifiable architectures.
- Anchor Handling Tug Supply:Twin-screw diesel-electric vessels rated above 200 tonnes bollard pull handle MODU mooring operations in ultra-deepwater Gulf of Mexico fields. Demand clusters around drillship contractors facing BSEE reliability audits for station-keeping redundancy.
- Platform Supply Vessel:Diesel-electric or hybrid propulsion craft between 50-90 meters LOA replenish floating production units with drilling fluids, cement, and provisions. The Louisiana-Texas corridor accounts for the densest charter activity as brownfield production sustains consumables cycles.
- Multipurpose Support Vessel:High-specification hulls with subsea crane capacity and moonpool arrangements support installation and IMR campaigns.
- Crew Boat:Fast aluminum or composite craft transfer personnel to platforms and wind turbine installations; Atlantic coast lease rounds are expanding structural demand from renewable energy providers.
Platform Supply Vessel handles the majority of throughput; Crew Boat is the fastest mover on share.
Service Type:
Margin structures vary sharply by service complexity, with construction and emergency response commanding premium day rates against commoditized logistics runs.
- Logistics Support:Routine consumables delivery and personnel transfer to fixed and floating installations. Gulf of Mexico brownfield operators compress margins through long-term charter agreements with integrated logistics providers.
- Maintenance Services:Subsea inspection, repair, and maintenance campaigns requiring ROV deployment and diving support. Demand concentrates around aging platform infrastructure requiring life-extension interventions.
- Construction Support:Heavy-lift and subsea installation assistance for newbuild platforms and wind farm foundations. Atlantic coast offshore wind lease areas are accelerating charter inquiries for high-specification tonnage.
- Emergency Response:Oil spill containment, firefighting, and rescue standby obligations mandated under US Coast Guard contingency planning requirements.
Logistics Support dominates contract volume; Construction Support carries the steepest expansion trajectory as offshore wind buildouts advance.
End User:
Procurement concentration among supermajor operators and integrated utilities is displacing fragmented spot-market vessel demand.
- Oil & Gas Companies:Supermajor and independent producers operating Gulf of Mexico deepwater leases. These charterers have consolidated preferred supplier panels from twelve to four vendors, extending contract durations to secure DP-2 and DP-3 certified tonnage.
- Renewable Energy Providers:Offshore wind developers and utilities holding Atlantic coast lease areas. Crew transfer and construction support demand from this segment is structurally expanding as provincial renewable targets harden in Canadian Atlantic provinces.
- Marine Contractors:Subsea installation and IMR specialists contracting vessel services on project-specific terms.
- Research Institutions:Oceanographic and seismic survey organizations requiring specialized survey vessel support.
Oil & Gas Companies anchor current fleet utilization; Renewable Energy Providers are gaining share fastest across the forecast window.
Operation Method:
Dynamic positioning certification tiers have become the primary technical discriminator in charter evaluations, with BSEE reliability standards rendering conventional anchoring economically marginal for new assignments.
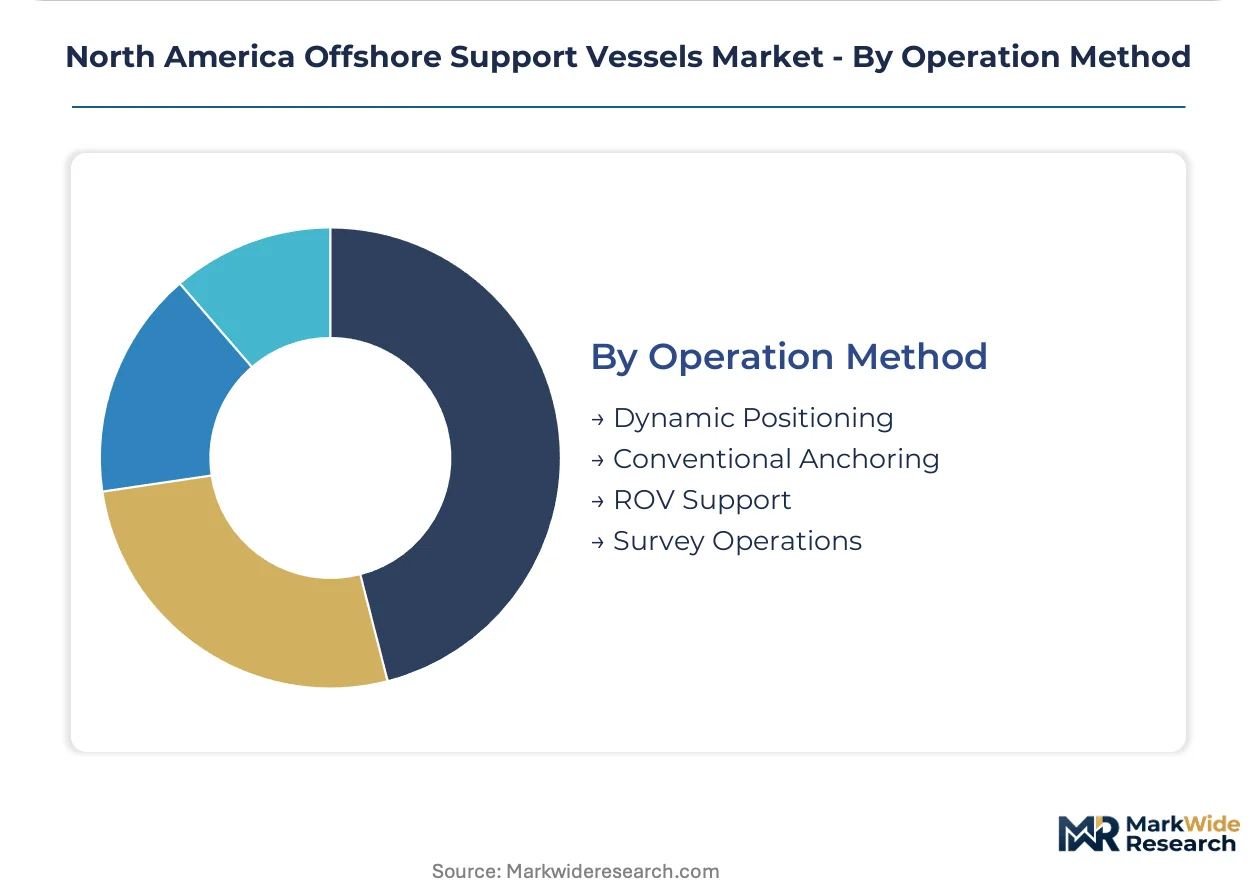
- Dynamic Positioning:Computer-controlled thruster systems maintaining vessel position without anchors, classified by redundancy level (DP-1, DP-2, DP-3). DP-2 and DP-3 specifications are unwinding across the North America fleet as operators face deeper-water assignments requiring BSEE-compliant station-keeping.
- Conventional Anchoring:Mooring systems using anchor and chain arrangements for position keeping. Legacy tonnage with conventional anchoring capabilities faces charter rate compression as major oil companies enforce sustainability and reliability clauses in supply agreements.
- ROV Support:Subsea robotics deployment for inspection and intervention tasks.
- Survey Operations:Geophysical and geotechnical data acquisition for field development planning.
Dynamic Positioning commands the dominant share of newbuild investment; ROV Support is climbing the fastest as subsea infrastructure density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipyard capacity clusters along the Louisiana-Texas corridor concentrate newbuild delivery schedules for deepwater-capable tonnage. Gulf Coast fabrication yards and Atlantic Canadian marine infrastructure shape regional supply dynamics.
United States
The Gulf of Mexico deepwater lease inventory and Atlantic offshore wind permitting drive vessel demand across multiple specifications. The US Bureau of Safety and Environmental Enforcement enforces station-keeping reliability standards that disqualify legacy anchor handling tug supply units from MODU support contracts. Port Fourchon, Louisiana anchors the densest platform supply vessel charter activity as brownfield production sustains consumables replenishment cycles.
Canada
Newfoundland and Nova Scotia offshore wind lease areas generate structural demand for crew transfer vessels and construction support craft. The Canadian Coast Guard and Transport Canada enforce vessel construction standards aligned with International Maritime Organization conventions. Atlantic Canada shipyards and St. John's marine service providers position for renewable energy installation campaigns as provincial targets harden.
Mexico
Pemex offshore field development and private operator deepwater assignments in the Gulf of Mexico sustain platform supply vessel requirements. The Mexican Maritime Authority and SEMAR coordinate port state control with US Coast Guard interoperability protocols. Tampico and Veracruz marine terminals handle offshore logistics coordination for Campeche Bay production units.
North America Offshore Support Vessels Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America offshore support vessels market. Integrated logistics providers with captive shipyard networks control newbuild specifications and delivery timelines, while independent operators compete on spot-market availability and specialized subsea capabilities. Three archetypes dominate: vertically integrated Gulf Coast operators, Atlantic-focused renewable energy specialists, and project-specific marine contractors. Competitive positioning depends on preferred supplier panel inclusion with supermajor oil companies and long-term charter contract capture.
Within the integrated operator tier, Edison Chouest Offshore and Tidewater Inc. exemplify scale-driven Gulf of Mexico market presence. Hornbeck Offshore Services occupies a position among high-specification multipurpose vessel specialists. These three entities anchor competitive dynamics through differentiated fleet compositions and charter relationship structures.
| Leading Market Players |
|---|
| Edison Chouest Offshore |
| Tidewater Inc. |
| Hornbeck Offshore Services, Inc. |
| Harvey Gulf International Marine LLC |
| SEACOR Marine Holdings Inc. |
| Siem Offshore Inc. |
| Otto Candies, LLC |
| Galliano Marine Service |
| Abdon Callais Offshore |
| Others |
Value Network & Pricing Analysis
Diesel-electric hybrid propulsion retrofits are displacing conventional mechanical drivelines across Gulf of Mexico newbuild specifications, compressing yard slot availability along the Louisiana-Texas corridor while elevating capital cost baselines for charter rate negotiations. This substitution dynamic concentrates pricing power with integrated operators holding captive shipyard access, forcing independent vessel owners toward extended delivery timelines or premium spot-market positioning.
Pricing Analysis
The US Bureau of Safety and Environmental Enforcement station-keeping mandates dictate the pricing tier structure across North American offshore support vessel charters. Three-tier pricing stratifies across DP-3 certified premium tonnage, DP-2 standard specifications, and legacy DP-1 or conventional anchoring economy assets. Price differentiation hinges on dynamic positioning certification grade and bollard pull capacity ratings. Cost compression in the economy tier is intensifying because major oil companies enforce sustainability clauses that disqualify pre-Tier III engine installations from preferred supplier panels. Renewable energy providers show least price sensitivity, prioritizing crew transfer vessel availability over day rate optimization for Atlantic offshore wind construction windows.
Supply Chain Analysis
Gulf Coast shipyard capacity bottlenecks constitute the critical chokepoint constraining North American offshore support vessel delivery schedules. Geographic supply concentration centers on the United States, with secondary fabrication capacity in Canada and project-specific outfitting in Mexico. Raw material dependencies draw from South Korean high-tensile steel plate, German specialized deck machinery, and Norwegian dynamic positioning systems. Single-source vulnerability in DP system integrators creates fleet expansion risk for operators without established vendor relationships. Distribution runs through Port Fourchon marine terminals for Gulf of Mexico logistics coordination, with Halifax and St. John's emerging for Atlantic Canadian renewable energy support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America offshore support vessels market represents an early-cycle expansion story, with offshore wind lease round advancement driving structural demand for crew transfer and construction support tonnage before fleet supply can fully respond.
For Market Incumbents: Compound fleet utilization advantages by extending preferred supplier panel contracts with supermajor operators before newbuild capacity releases from Gulf Coast yards. Anchor backward integration into battery-hybrid propulsion system supply chains to control specification differentiation against emerging Atlantic-focused competitors. Defensive consolidation of DP-2 and DP-3 certified tonnage through selective acquisition of distressed independent operators protects charter rate positioning as BSEE reliability audits tighten. For New Entrants and Emerging Players: Anchor in Canadian Atlantic offshore wind lease areas where incumbent Gulf of Mexico operators lack established marine service infrastructure. Newfoundland and Nova Scotia present the most penetrable geography, with provincial renewable targets hardening faster than local shipyard response capacity. A go-to-market angle pairing crew transfer vessel availability with construction support craft bundling addresses integrated utility procurement preferences for simplified logistics coordination. For Investors and Strategic Acquirers: The market sits at a fleet renewal phase that favors vertically integrated operators with captive shipyard networks and supermajor charter relationships. Long-term viability over the next decade rests on positioning ahead of Tier III NOx compliance deadlines and offshore wind construction peak demand. Acquisition target archetypes include independent platform supply vessel owners with DP-2 upgradeable tonnage and Atlantic Canada marine service providers holding local regulatory relationships. The signal to watch is US Coast Guard Subchapter M inspection backlog resolution timing, which would release redeployable capacity and shift charter rate trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Propulsion Retrofit Program | EPA Tier III compliance through methanol-ready engine installations secures charter eligibility with supermajor sustainability clauses. |
| Atlantic Canada Crew Transfer Base Establishment | Halifax marine terminal positioning captures Newfoundland and Nova Scotia offshore wind construction support demand. |
| Preferred Supplier Panel Consolidation | Long-term charter agreements with integrated oil companies lock in utilization rates before newbuild capacity releases. |
| DP Operator Training Academy Investment | Certified dynamic positioning officer pipeline development alleviates talent scarcity constraining fleet utilization. |
| Battery-Hybrid System Integration Partnership | Modular lithium-ion energy storage deployment differentiates fuel consumption benchmarks for Scope 3 reporting compliance. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with offshore vessel charter managers, Gulf Coast shipyard production planners, dynamic positioning system engineers, and US Coast Guard marine inspection officers. Secondary validation drew from BSEE incident investigation databases, EPA marine engine certification filings, Atlantic offshore wind lease round documentation, and platform supply vessel charter rate indices. Bottom-up vessel inventory tracking and top-down energy sector capital expenditure analysis enabled triangulation across data sources.
Across the projection horizon, the analytical framework modeled vessel type segmentation, service complexity tiers, end-user procurement concentration, and dynamic positioning certification grades. CAGRs were derived from charter rate trajectory analysis and newbuild orderbook conversion assumptions. Forecast inputs incorporated BSEE regulatory enforcement intensity scenarios, offshore wind lease area permitting velocity, and Gulf Coast shipyard capacity utilization thresholds.
Decision-makers should treat outputs as directional under assumptions of sustained Gulf of Mexico deepwater drilling activity and Atlantic offshore wind construction schedule adherence; material deviation in federal renewable energy policy or hydrocarbon lease auction timing would warrant model refresh. Practitioners should keep alternative scenarios live as US Coast Guard Subchapter M inspection capacity and marine engineer certification pipeline throughput evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Ship Stabilizers Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Platform Supply Vessels (PSV) Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Container Docking Stations Market
Maritime Equipment
Barge Transportation Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Asia-Pacific Digital Shipyard Market
Maritime Equipment
LNG Carrier Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Air Compressors on Ships Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Ship Plate Market