
 Global Shipbroking Market | 2026-2036
Global Shipbroking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shipbroking Market Outlook
Asset-light platform models are reshaping competitive dynamics in shipbroking, lowering capital barriers for specialized entrants. Clarkson PLC leverages its research and data analytics arm to sustain premium positioning across volatile freight cycles. Braemar Shipping Services PLC anchors its competitiveness in specialized vessel segments where technical knowledge creates stickier client relationships. Simpson Spence Young differentiates through geographic reach across emerging trade corridors.
Shipbroking encompasses the intermediation of maritime freight contracts, vessel sales, and newbuilding negotiations, requiring real-time intelligence on tonnage availability, cargo flows, and port congestion metrics. The practice functions as a price-discovery mechanism connecting ship owners with cargo interests across fragmented spot and term markets. Chartering services dominate transaction volumes, while consulting and market analysis segments capture expanding margin pools as clients demand scenario planning for fleet decarbonization. Bulk carrier and tanker broking remain mature, high-volume categories, whereas specialized vessels including LNG carriers command premium commissions reflecting technical complexity.
The International Maritime Organization enforces carbon intensity indicators and energy efficiency standards that compel owners to seek broker guidance on compliant chartering strategies. EU emissions trading system inclusion for maritime transport, administered by national regulators in Germany and Greece, reshapes contract structures and route economics. Classification societies including Lloyd's Register and DNV issue vessel sustainability notations that brokers must interpret for clients. Stakeholders should monitor how digital freight platforms and alternative fuel infrastructure investments redistribute information advantages traditionally held by established broker networks.
Market Dynamics
Digital freight platforms are virtualizing traditional broker functions, compressing information asymmetries that historically sustained commission premiums while forcing established networks to restructure around data analytics and specialized advisory services.
Growth Catalysts
- IMO 2023 Carbon Intensity Regulations:Mandatory energy efficiency standards compel shipowners to seek broker guidance on compliant chartering strategies and route optimization, elevating demand for technical advisory services.
- LNG Cargo Chartering Expansion:Commodity trading houses are entering LNG shipping markets, requiring specialized intermediation for cryogenic cargo contracts and vessel matching.
- Singapore Arbitration Hub Concentration:The city-state's dominance in maritime dispute resolution and fixture finalization draws transactional volume and broker presence from competing hubs.
Market Restraints
- Commission Compression from Platform Transparency:Real-time freight rate visibility on digital exchanges erodes the information premiums that traditionally underwrote broker margins.
- Concentrated Owner Consolidation:Top-tier shipowners in Greece and Germany are building in-house chartering desks, reducing third-party brokerage dependency for routine fixtures.
- Alternative Fuel Infrastructure Gaps:Limited bunkering availability for ammonia and methanol fuels constrains broker ability to structure compliant voyage contracts.
Strategic Opportunities
- EU Emissions Trading System Maritime Inclusion:Carbon contract structuring and allowance procurement advisory opens new fee-based revenue streams for compliance-specialized brokers.
- Offshore Wind Installation Vessels:Surging demand for jack-up and heavy-lift tonnage in North Sea and Taiwan Strait markets rewards technical brokers with offshore construction expertise.
- Blockchain-Enabled Smart Contracts:Distributed ledger technology convergence with freight derivatives is virtualizing post-fixture administration and reducing settlement friction.
Industry Challenges
- Decarbonization Analytics Talent Scarcity:Shortage of brokers capable of interpreting Lloyd's Register and DNV sustainability notations for client fleet planning limits service differentiation.
- Legacy System Integration Costs:Established houses face capital-intensive upgrades to API-connect their proprietary databases with external freight platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shipbroking Market |
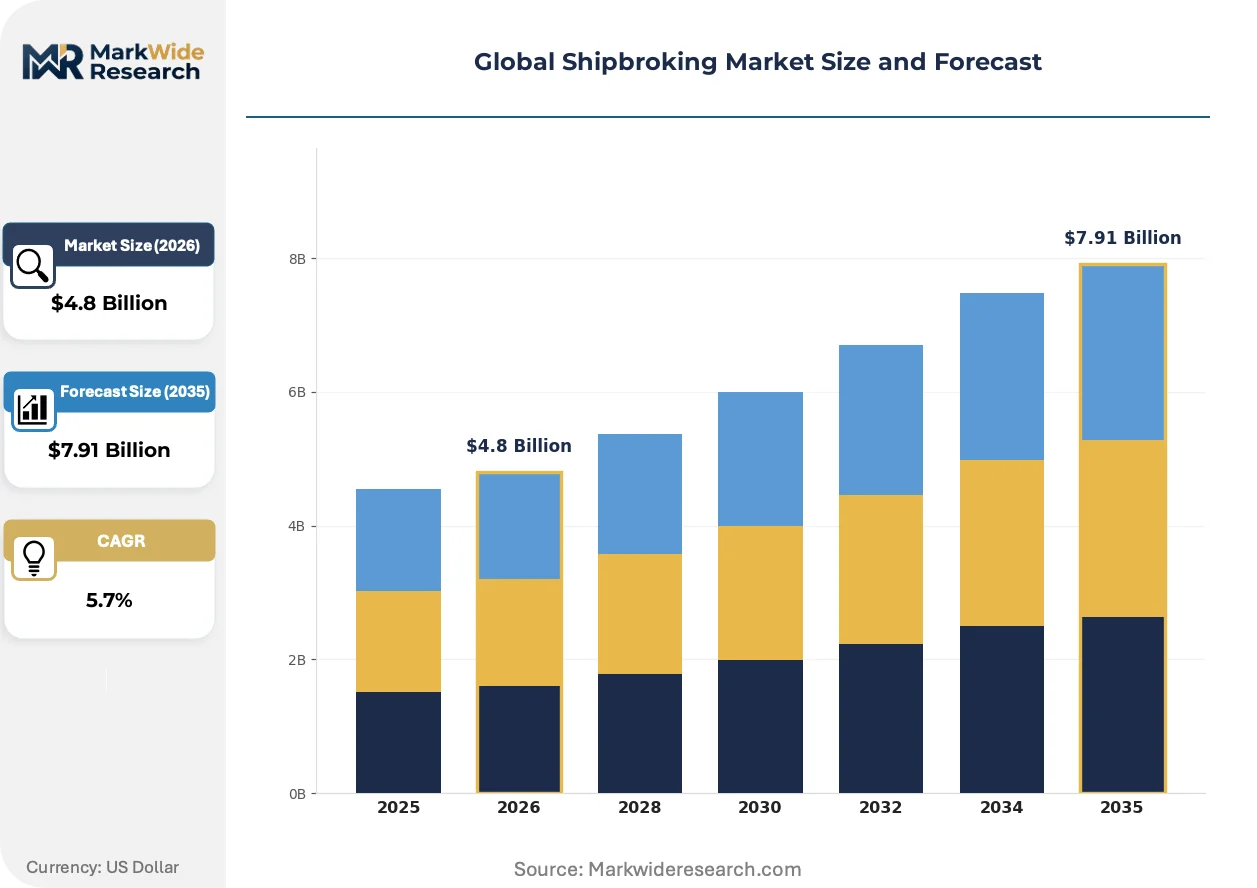
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Chartering, Brokerage, Consulting, Market Analysis Client Type: Ship Owners, Cargo Owners, Freight Forwarders, Charterers Segment: Tankers, Bulk Carriers, Container Ships, Specialized Vessels End User: Shipping Lines, Logistics Companies, Oil & Gas, Industrial Manufacturers |
| Companies Covered | Clarkson PLC, BRS Group, Braemar Shipping Services PLC, Howe Robinson Partners, Aries Shipbroking (Asia) Pte Ltd, Simpson Spence Young, Fearnleys A/S, SSY, Maersk Broker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shipbroking Market Strategic Shifts
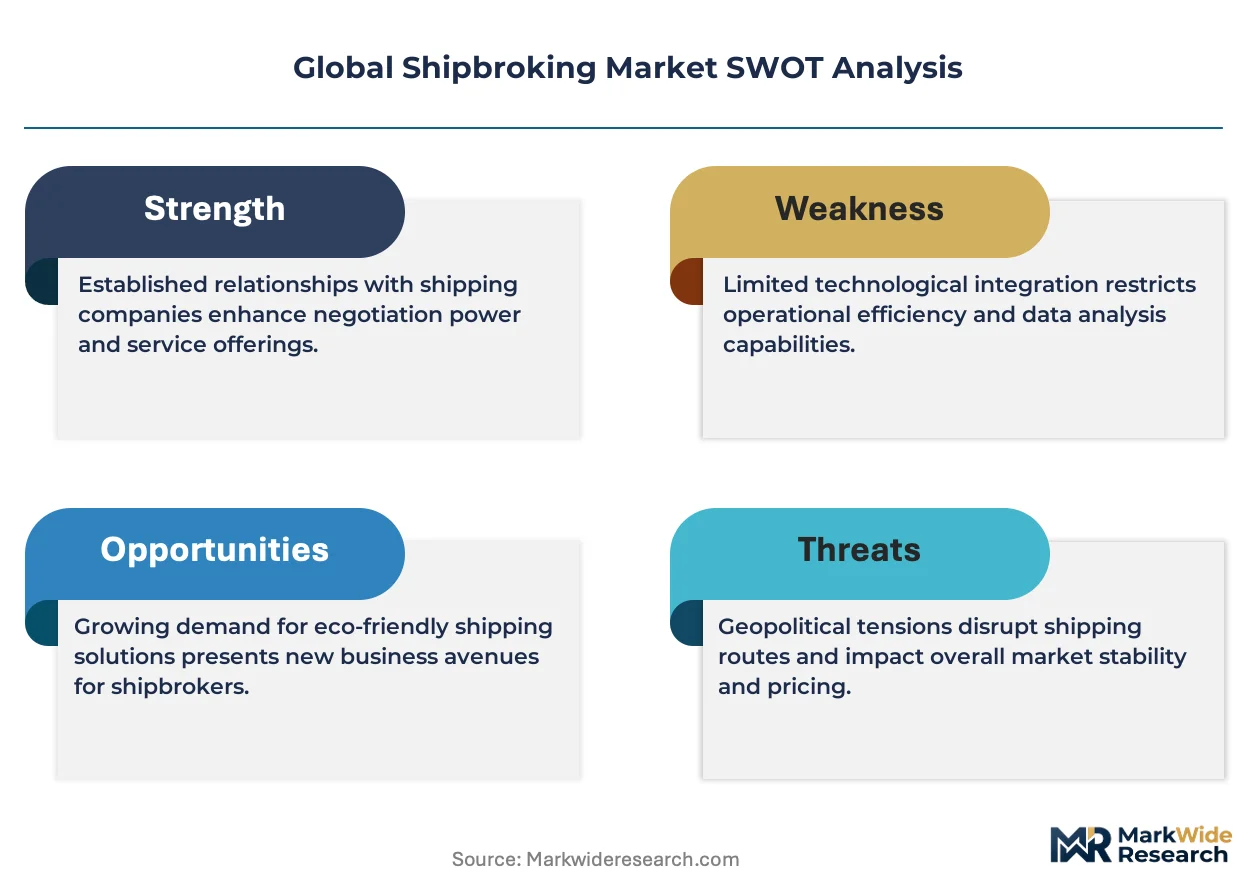
Artificial intelligence is reshaping vessel-cargo matching algorithms, while regulatory complexity around carbon accounting and alternative fuels is elevating the technical knowledge threshold for competitive intermediation.
Blockchain-based freight derivatives platforms are virtualizing the post-fixture settlement layer that traditional brokers once controlled manually. Container lines and dry bulk operators are piloting smart contract automation for standard voyage terms. This compression of administrative functions is forcing brokers to migrate upstream into pre-fixture advisory and carbon strategy consulting.
The EU Emissions Trading System inclusion for maritime transport, administered by German and Greek national regulators, is rewriting contract structures to allocate carbon liability between owners and charterers. Voyage clauses now require explicit allowance transfer mechanisms. Tanker and bulk carrier segments face the steepest compliance learning curves as they adapt term sheets to carbon-adjusted freight economics.
Charterers are unbundling market intelligence from execution services, purchasing raw data feeds from Clarksons Research and Braemar Seascope while retaining only specialized brokers for complex negotiations. This disintermediation of information from intermediation is most advanced among commodity traders in Singapore and Geneva, who have built internal analytics teams to interpret vessel supply-demand signals previously obtained through broker relationships.
Global Shipbroking Market Segmentation
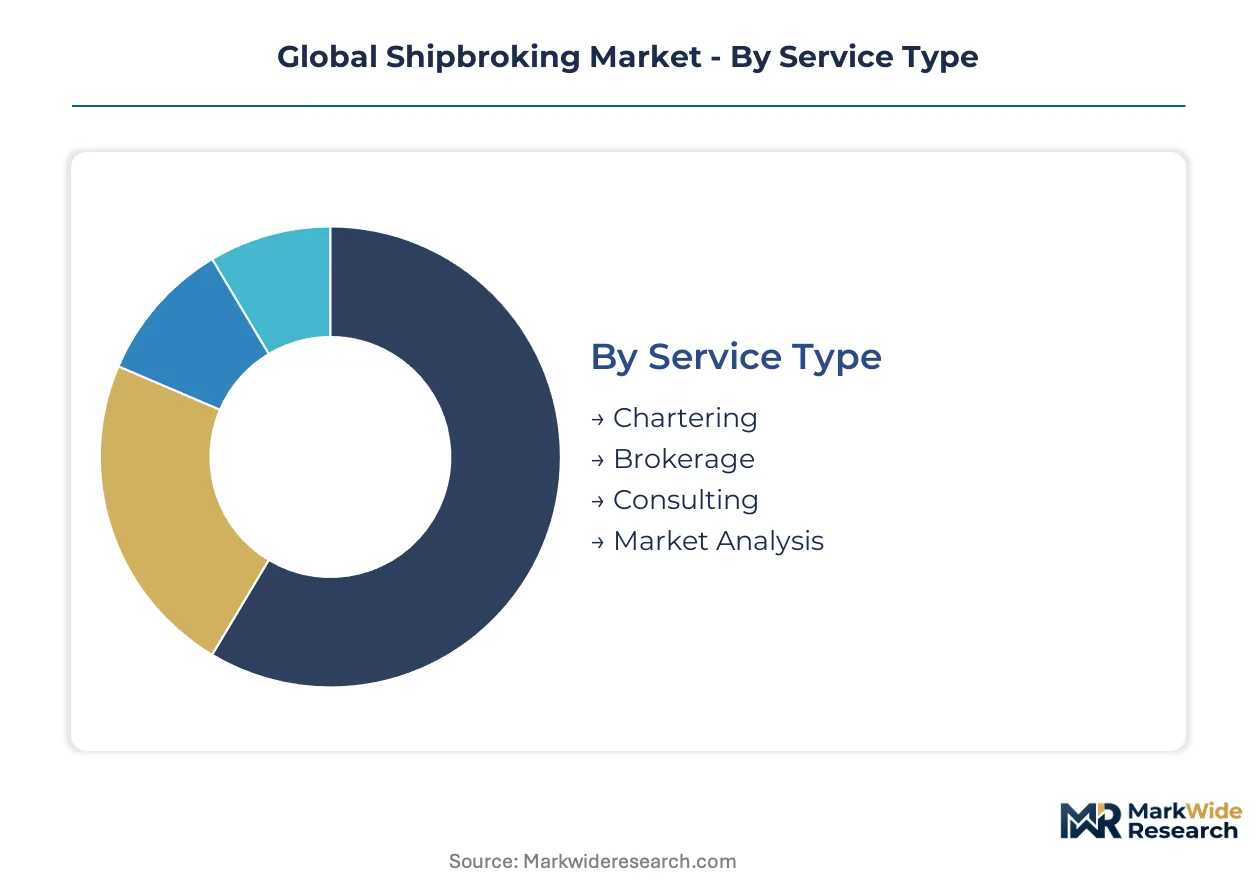
Shipbroking intermediation fragments across service specializations, client categories, and vessel types that demand distinct regulatory knowledge and relationship architectures. Commission structures, contract complexity, and advisory intensity vary substantially across these boundaries.
Service Type:
Chartering commands the widest use-case spectrum, spanning routine spot fixtures through multi-year term contracts that embed carbon compliance clauses.
- Chartering:Core intermediation matching vessel supply with cargo demand across spot, time-charter, and bareboat structures. Demand concentrates among Greek and German tanker owners seeking IMO 2023 carbon intensity compliance through route-optimized fixture strategies.
- Brokerage:Facilitates second-hand vessel sales and newbuilding negotiations requiring valuation expertise and yard relationship networks. Singapore-based commodity traders are driving expansion here as they build internal shipping desks.
- Consulting:Advisory on fleet renewal, decarbonization pathways, and regulatory compliance. EU ETS maritime inclusion has elevated demand for carbon allowance procurement guidance.
- Market Analysis:Subscription research on freight rates, vessel supply-demand balances, and port congestion metrics. Cargo owners in Geneva and Singapore increasingly unbundle this from execution services.
The dominant share belongs to Chartering, while Consulting is closing the gap fastest.
Client Type:
Cost tier stratification separates retained advisory relationships from transactional spot market access.
- Ship Owners:Principals seeking cargo coverage for owned tonnage, ranging from single-vessel operators to consolidated fleets. Greek and German top-tier owners are building in-house desks for routine fixtures.
- Cargo Owners:Commodity traders, miners, and energy majors requiring vessel procurement for cargo movements. LNG cargo chartering from trading houses in Geneva and Houston is expanding this segment's technical complexity.
- Freight Forwarders:Logistics intermediaries bundling ocean freight with multimodal services. Demand clusters in Singapore as the dominant maritime arbitration hub.
- Charterers:Operators taking vessels on time-charter for sub-leasing or own account trading. This segment demands brokers capable of structuring carbon-adjusted freight economics under EU ETS.
Ship Owners retain the largest engagement volume, though Cargo Owners are gaining share fastest through LNG and specialized vessel demand.
Segment:
Maturity gradients separate commoditized bulk markets from technically complex specialized tonnage.
- Tankers:Mature crude and product carrier broking with high transaction volumes and compressed margins. EU ETS compliance is rewriting contract structures to allocate carbon liability between owners and charterers.
- Bulk Carriers:Dry cargo fixtures for iron ore, coal, and grain trades. Digital freight platforms have eroded information premiums in this historically broker-dependent segment.
- Container Ships:Chartering for liner operators and non-operating owners. Post-pandemic rate volatility has sustained demand for market intelligence despite platform transparency.
- Specialized Vessels:LNG carriers, chemical tankers, offshore support, and heavy-lift tonnage. Cryogenic cargo expertise and jack-up vessel knowledge command premium commissions reflecting technical barriers.
Tankers and Bulk Carriers together dominate transaction counts, while Specialized Vessels is climbing the fastest on LNG chartering expansion and offshore wind installation demand.
End User:
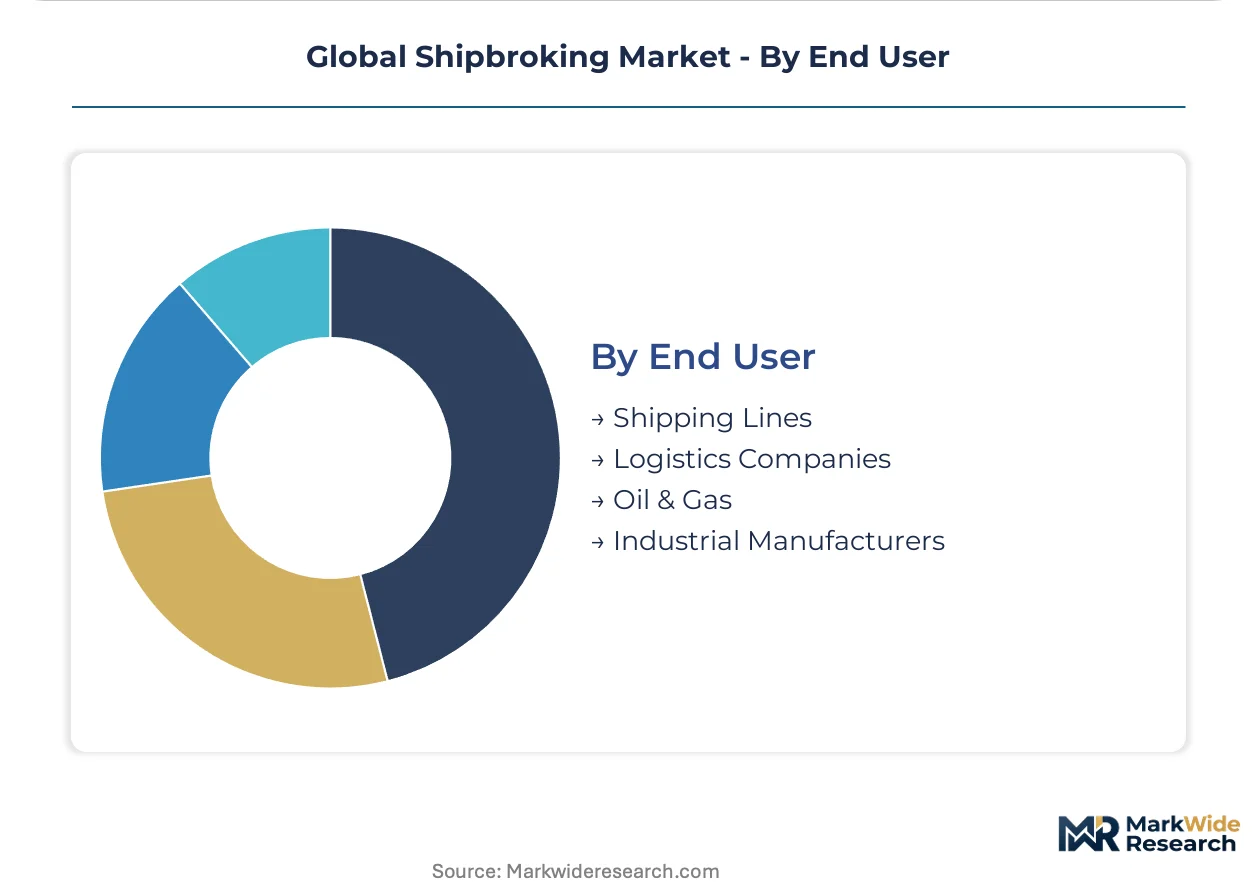
Application intensity varies from routine freight procurement through strategic fleet planning advisory.
- Shipping Lines:Container and bulk operators managing owned and chartered fleets. These clients are piloting blockchain-enabled smart contracts for standard voyage terms.
- Logistics Companies:Multimodal freight managers requiring ocean leg coordination. Singapore arbitration concentration draws broker presence for dispute resolution support.
- Oil & Gas:Majors and trading houses chartering tankers and LNG carriers. IMO 2023 carbon intensity regulations compel broker guidance on compliant chartering strategies.
- Industrial Manufacturers:Steel, cement, and chemical producers with captive cargo flows. These end users are building internal analytics capabilities to interpret vessel supply-demand signals.
Shipping Lines anchor the largest share of broker relationships, with Oil & Gas expanding most quickly on LNG cargo chartering growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commission premiums in Singapore exceed those in Hamburg by substantial margins, reflecting the city-state's dominance in maritime arbitration and fixture finalization. This pricing-power asymmetry concentrates broker talent and transactional volume in Southeast Asia while European houses compete on specialized technical advisory.
Singapore
LNG cargo chartering from commodity trading houses and offshore wind installation vessel demand drive broker expansion. The Maritime and Port Authority of Singapore administers licensing frameworks for carbon-adjusted freight contracts. The Marina Bay financial district anchors the highest concentration of international shipbroking desks outside London.
Germany
Top-tier tanker owners building in-house chartering desks reduce third-party dependency for routine fixtures. The Federal Maritime and Hydrographic Agency implements EU ETS maritime inclusion protocols for carbon allowance tracking. Hamburg's HafenCity district houses specialized brokers focused on compliant chartering strategies under IMO 2023 regulations.
Greece
Consolidated shipowner fleets in Piraeus and Glyfada sustain demand for premium sale-and-purchase brokerage. The Hellenic Ministry of Shipping and Island Policy enforces national emissions monitoring for EU ETS compliance. Athens-based brokers command premium commissions for complex vessel matching in the tanker segment.
United Kingdom
Research and data analytics unbundling from execution services reshapes London's traditional broker relationships. The Maritime and Coastguard Agency implements UK-specific carbon intensity indicator verification. The City of London retains its position in freight derivatives brokerage despite transactional volume migration eastward.
United States
Commodity trading houses in Houston entering LNG shipping markets require specialized cryogenic cargo intermediation. The Federal Maritime Commission monitors carrier-broker relationships under revised shipping act provisions. The Houston Ship Channel corridor attracts broker presence for Gulf Coast petrochemical export fixtures.
Global Shipbroking Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in vessel-specific niches where technical knowledge creates defensible positioning. The market structures around three tiers: consolidated research-driven houses, mid-scale specialized brokers, and emerging digital platforms compressing information premiums. Two dominant competitive moves are reshaping positioning: M&A activity consolidating research capabilities with execution networks, and strategic partnerships linking traditional brokers with carbon analytics providers.
Within the research-integrated tier, Clarkson PLC exemplifies the data-analytics anchor model, while Braemar Shipping Services PLC occupies a position emphasizing specialized vessel segments. Simpson Spence Young represents the geographic reach archetype across emerging trade corridors. These three London- and Singapore-based entities illustrate how scale, specialization, and coverage breadth define competitive positioning in fragmented maritime intermediation.
| Leading Market Players |
|---|
| Clarkson PLC |
| BRS Group |
| Braemar Shipping Services PLC |
| Howe Robinson Partners |
| Aries Shipbroking (Asia) Pte Ltd |
| Simpson Spence Young |
| Fearnleys A/S |
| SSY |
| Maersk Broker |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Greek and German tanker fleets is compressing spot fixture rates while elevating demand for specialized LNG and offshore wind brokerage, forcing suppliers to differentiate through carbon advisory rather than volume capture. This utilization asymmetry rewards Singapore-based brokers with premium pricing power while European houses absorb margin pressure on commoditized bulk segments.
Pricing Analysis
The customization-premium spread between standard spot fixture commissions and carbon-adjusted term contracts with EU ETS compliance clauses has widened substantially. Pricing stratifies across premium, standard, and economy tiers, with specialized LNG and offshore wind segments commanding multiples over commoditized tanker broking. Cost compression in dry bulk and container segments is intensifying because digital freight platforms have eroded information premiums. Cargo owners in Geneva and Singapore exhibit the highest price sensitivity, unbundling market intelligence from execution services, while oil majors remain least sensitive due to compliance complexity.
Supply Chain Analysis
Extended payment terms from commodity trading houses in Singapore and Geneva are reshaping working capital requirements for broker networks. Broker talent concentrates in Singapore, London, and Athens, with research capabilities anchored in the United Kingdom and execution networks spanning Hamburg and Piraeus. The supply chain draws from Lloyd's Register and DNV for sustainability notations, proprietary vessel databases, and carbon analytics subscriptions. Single-source vulnerability around specialized LNG cargo expertise constrains service expansion. Distribution runs through retained advisory relationships with shipowners and unbundled data subscriptions with cargo interests.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shipbroking market is approaching a platform-economics inflection where blockchain-enabled smart contracts and digital freight exchanges threaten to commoditize execution while elevating pre-fixture advisory value. Interoperability between carbon accounting systems and fixture settlement layers will determine which intermediaries capture retained relationships.
For Market Incumbents: Build data-analytics moats by integrating proprietary vessel supply-demand databases with external freight platforms through API connectivity. Clarkson PLC's research-driven model demonstrates how scale in market intelligence sustains premium positioning through volatile freight cycles. Incumbents should anchor backward integration into carbon analytics capabilities to defend against disintermediation from compliance-specialized boutiques. For New Entrants and Emerging Players: Build out white-space positions in EU ETS carbon allowance procurement advisory and offshore wind installation vessel matching. The most penetrable segment sits with commodity trading houses entering LNG shipping markets from Houston and Geneva, who lack internal cryogenic cargo expertise. A targeted go-to-market angle combines technical brokerage with scenario planning for fleet decarbonization pathways. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among research-integrated houses with subscription analytics arms that cargo owners cannot easily replicate internally. Long-term viability over the next decade hinges on positioning upstream from execution into regulatory advisory. Acquisition targets should display specialized vessel segment depth or carbon compliance expertise. The signal to watch is consolidation activity linking traditional brokers with sustainability analytics providers.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Analytics Acquisition | Integrates Lloyd's Register notation interpretation with client fleet planning advisory capabilities. |
| Blockchain Platform Partnership | Virtualizes post-fixture settlement layers that traditional brokers controlled manually. |
| Singapore Hub Expansion | Captures premium commissions from maritime arbitration concentration and LNG chartering growth. |
| EU ETS Advisory Service Launch | Opens fee-based revenue streams for carbon contract structuring and allowance procurement. |
| Offshore Wind Technical Desk Buildout | Addresses surging jack-up and heavy-lift tonnage demand in North Sea and Taiwan Strait markets. |
Study Parameters
The analysis maps chartering, sale-and-purchase brokerage, consulting, and market analysis sub-sectors, each validated through shipowner chartering managers, cargo owner procurement leads, broker desk heads, and classification society technical directors. Primary interviews with these stakeholders combined with secondary validation from Lloyd's Register filings, DNV sustainability databases, Maritime and Port Authority of Singapore licensing records, and EU ETS regulatory disclosures. Bottom-up transaction volume estimates and top-down market sizing triangulate to produce converged figures.
Assumptions around IMO 2023 carbon intensity enforcement stringency, digital freight platform adoption curves, and LNG cargo chartering expansion from commodity trading houses were held fixed across baseline scenarios while alternative fuel infrastructure buildout timelines were varied. The analytical framework segments by service type, client category, vessel segment, and end-user application across the analysis window. CAGRs derive from regression-based freight rate projections and broker commission elasticity models, incorporating vessel orderbook data and port congestion indices as industry-specific inputs.
Stress conditions across carbon price volatility, platform transparency acceleration, and Greek owner in-house desk expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions. Macroeconomic deviation in commodity trade flows, regulatory tightening in EU ETS maritime inclusion, or breakthrough adoption of autonomous vessel matching would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Ship Repair and Maintenance Services Market
Maritime Equipment
Marine Hatch Covers Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
Hong Kong Stevedoring and Marine Cargo Handling Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
United States Maritime Information Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Ship Stabilizers Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Latin America Offshore Support Vessels Market
Maritime Equipment
Global Spar Beacon Buoys Market