
 Offshore Support Vessel Service Market | 2026-2036
Offshore Support Vessel Service Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Support Vessel Service Market Analytics
Market Context
The gap between premium-specification offshore support vessels and commodity-tonnage is expanding as charterers prioritize fuel efficiency, dynamic positioning capability, and hybrid propulsion systems. Tidewater Inc. leverages its Americas-focused fleet modernization program to capture higher day-rate tiers in the Gulf of Mexico and Brazilian pre-salt basins. BOURBON anchors its competitive stance through a standardized vessel platform that reduces maintenance complexity across West African and North Sea operations. DOF Group specializes in subsea construction support, where IMR vessel specifications command sustained premium pricing from integrated oil companies.
Technical Definition and Segment Structure
Offshore support vessel service encompasses the chartering, operation, and technical management of specialized marine craft designed to transport personnel, provisions, and equipment to offshore installations, typically featuring dynamic positioning class 2 or 3 systems, deck cargo capacities exceeding 1,000 square meters, and bollard pull ratings above 100 tonnes for anchor handling applications. Platform Supply Vessels dominate transaction volume due to recurring logistics requirements across producing oil and gas fields, though Anchor Handling Tug Supply units concentrate margin pools where fleet scarcity and high-specification demands limit effective supply. Crew Boats represent the fastest-growing service category as offshore wind construction schedules multiply personnel transfer requirements in European and Asian waters.
Regulatory Environment
The International Maritime Organization's carbon intensity indicator and Energy Efficiency Existing Ship Index are forcing fleet operators to retire older tonnage or invest in engine retrofits, battery-hybrid installations, and alternative fuel trials. The EU Green Deal's Fit for 55 package and the F-Gas Regulation extend compliance obligations to vessel refrigerant systems and shore power connection standards in European ports. Stakeholders must monitor how regional carbon border adjustments and flag-state enforcement divergence reshape vessel deployment economics between OECD and non-OECD operating jurisdictions.
Market Dynamics
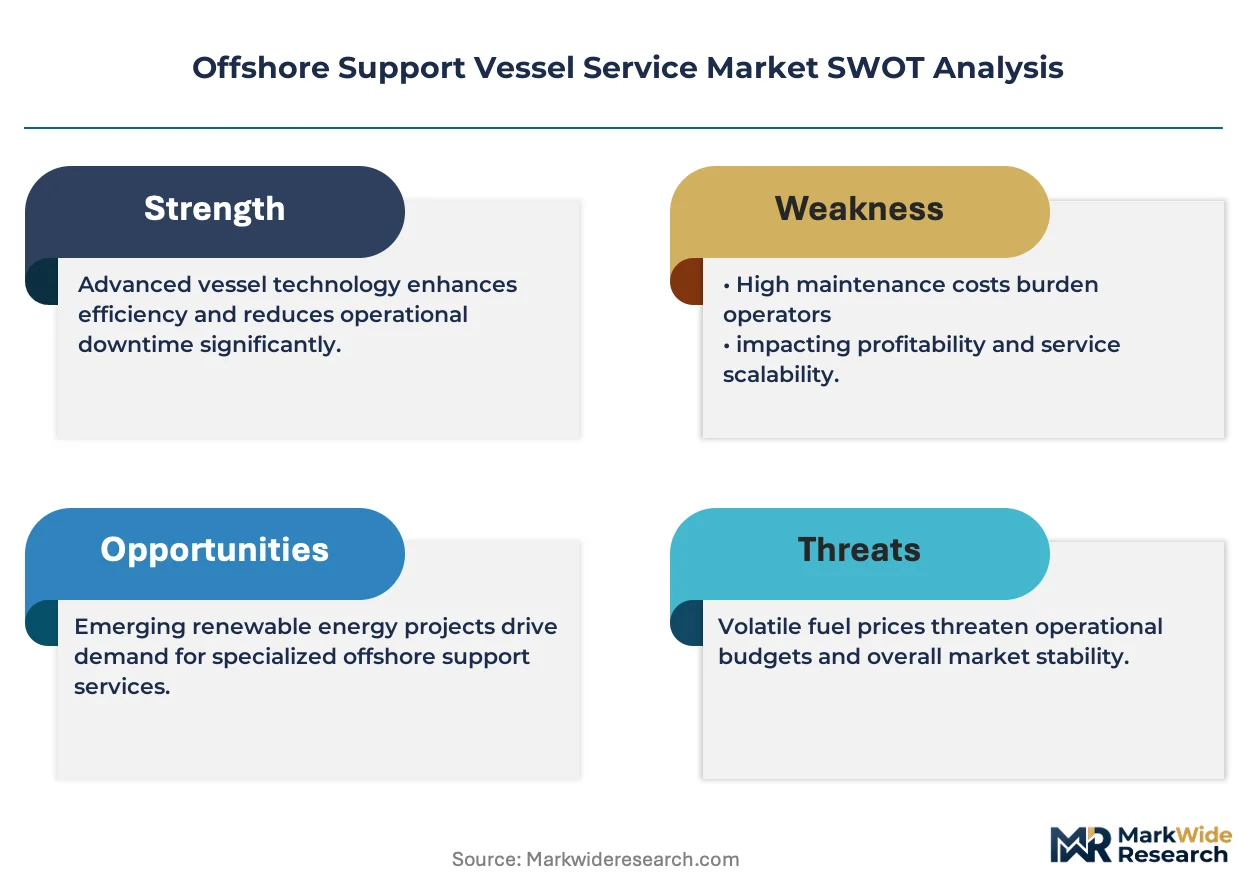
Fleet decarbonization mandates from the EU Green Deal and IMO carbon intensity regulations are forcing vessel operators into accelerated capital replacement cycles, widening the competitive gap between retrofitted legacy tonnage and newbuild hybrid-electric designs.
Growth Catalysts
- Offshore wind installation surge:Germany, the United Kingdom, and Denmark have committed to national capacity targets that multiply demand for turbine installation vessels and crew transfer units in the North Sea basin.
- IMO CII compliance deadlines:The carbon intensity indicator rating system is phasing out older diesel-mechanical propulsion, creating replacement demand for battery-hybrid and methanol-ready newbuilds.
- Deepwater pre-salt expansion:Brazilian and Gulf of Mexico field developments require higher bollard-pull anchor handling tug supply vessels with dynamic positioning class 3 systems.
Market Restraints
- Steel and marine equipment cost volatility:Newbuild vessel construction faces input price uncertainty from specialized propulsion systems and high-tensile steel plate markets.
- Shipyard capacity concentration:Specialized offshore vessel construction concentrates in Norwegian, Singaporean, and Chinese yards, creating orderbook bottlenecks during demand surges.
- Battery energy density limitations:Current lithium-ion cell configurations restrict all-electric range for long-duration offshore transits, forcing hybrid architectures.
Strategic Opportunities
- Asian offshore wind frontier:Taiwan, South Korea, and Japan are licensing seabed leases for utility-scale wind farms that lack established local vessel supply chains.
- Methanol fuel infrastructure:Port authorities in Rotterdam and Singapore are installing bunkering facilities that enable dual-fuel newbuilds to access carbon-adjusted charter contracts.
- Subsea decommissioning wave:North Sea oil and gas field retirements will require heavy-lift and cutting spread vessels for platform removal campaigns through the mid-2030s.
Industry Challenges
- Marine automation engineer scarcity:Dynamic positioning system programming and battery-hybrid power management require skill sets that outpace maritime academy curricula.
- Flag-state certification divergence:Vessel operators face inconsistent enforcement of IMO Energy Efficiency Existing Ship Index standards across open registries and traditional maritime administrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Support Vessel Service Market |
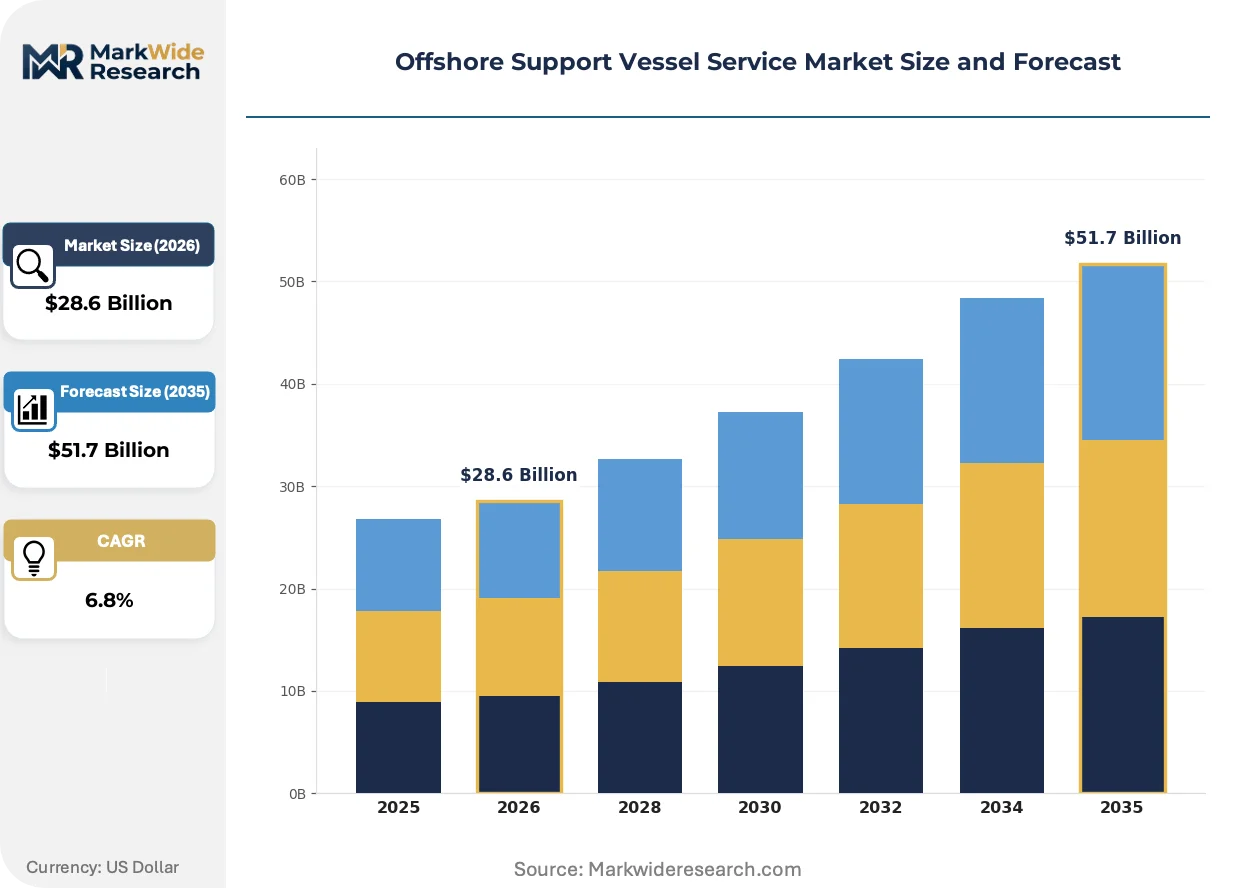
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Survey Vessels, Anchor Handling Tug Supply, Platform Supply Vessels, Crew Boats Deployment Model: Onshore, Offshore, Deepwater, Shallow Water End User: Oil & Gas Companies, Renewable Energy Providers, Marine Construction Firms, Fisheries Vessel Type: Multipurpose Support Vessels, AHTS Vessels, IMR Vessels, PSVs |
| Companies Covered | A.P. Moller-Maersk, Tidewater Inc., BOURBON, DOF Group, Deltamarin Ltd, Edison Chouest Offshore, SEACOR Marine Holdings Inc., Solstad Offshore ASA, Havila Shipping ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Support Vessel Service Market Evolving Landscape
Remote operations technology and predictive maintenance systems are compressing crew requirements while extending vessel utilization windows, fundamentally altering how offshore logistics contracts are priced and executed.
Autonomous navigation and collision-avoidance sensor suites are automating transit legs between port and offshore installations, reducing bridge manning levels on platform supply vessels. North Sea wind farm operators are piloting these systems on crew transfer vessels to extend daily transfer windows in marginal weather conditions. The technology is automating route optimization decisions that previously required continuous officer oversight, compressing operating cost structures for high-frequency shuttle services.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in vessel HVAC systems, mandating retrofits or newbuild specifications using natural refrigerants or ultra-low global warming potential alternatives. Shipyards in Norway and the Netherlands are integrating CO2-based refrigeration systems into hybrid vessel designs to secure European charter eligibility. Platform supply vessels operating under EU flags face the most compressed compliance timelines, with 2027 deadlines forcing mid-life refit decisions.
Charterers are unbundling vessel supply from integrated logistics contracts, creating spot-market exposure for vessel owners and demand for digital freight platforms that match vessel availability to campaign-specific requirements. Offshore wind developers in the United Kingdom are leading this transition, using short-term charters for turbine installation phases rather than multi-year agreements. The shift is most visible in crew transfer vessel procurement, where project-specific vessel pools replace dedicated fleet assignments.
Offshore Support Vessel Service Market Segmentation
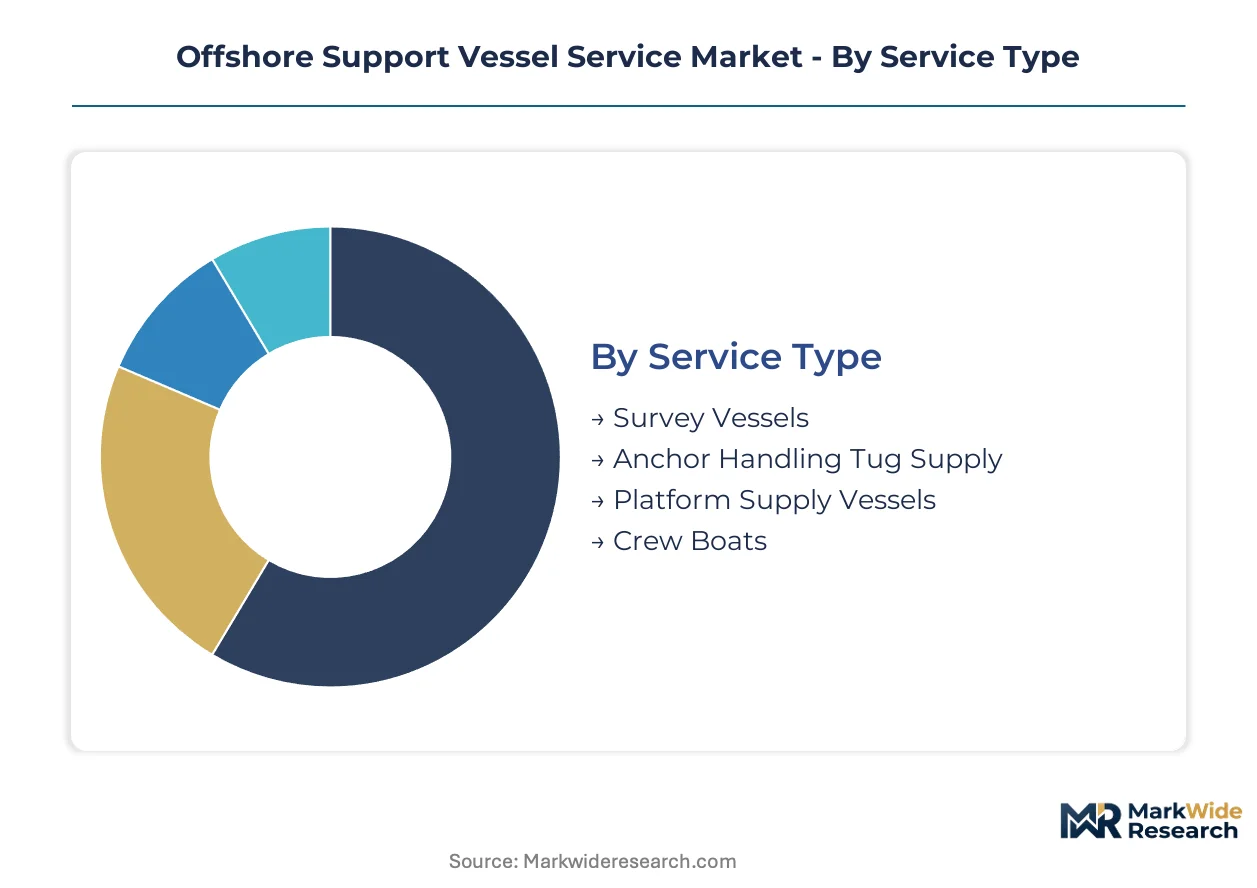
Fleet renewal cycles and decarbonization mandates are fragmenting the offshore support vessel service market into sharply differentiated performance tiers. Charterers now segment procurement by technical specification rather than tonnage alone, creating distinct pricing bands for hybrid-electric newbuilds versus retrofitted legacy assets.
Service Type:
Upgrade trajectories diverge sharply across service categories as IMO carbon intensity deadlines force replacement decisions on aging diesel-mechanical fleets.
- Platform Supply Vessels:These vessels transport drilling fluids, cement, and deck cargo to offshore installations with deck capacities exceeding 1,000 square meters. Demand concentrates in the North Sea and Gulf of Mexico, where recurring logistics requirements for producing oil and gas fields sustain contract visibility despite day-rate volatility from fleet oversupply in standard specifications.
- Anchor Handling Tug Supply:AHTS units combine anchor deployment capabilities with supply functions, requiring bollard pull ratings above 100 tonnes and dynamic positioning class 2 or 3 systems. Brazilian pre-salt and West African deepwater developments are absorbing higher-specification tonnage where fleet scarcity supports sustained premium pricing for DP-3 capable assets.
- Crew Boats:Fast personnel transfer craft with speeds exceeding 25 knots serve turbine installation and maintenance campaigns in European offshore wind zones.
- Survey Vessels:Geophysical and geotechnical survey platforms with specialized sensor suites support seabed mapping for wind farm site characterization.
Volume placements concentrate in Platform Supply Vessels; the faster expansion belongs to Crew Boats.
Deployment Model:
Water depth requirements dictate vessel specification intensity and contract duration, with deeper operations commanding longer-term charter commitments.
- Deepwater:Operations below 400 meters require dynamic positioning class 3 systems, dual-redundant power plants, and enhanced station-keeping capability for subsea construction support. Brazil's pre-salt basins and US Gulf of Mexico Lower Tertiary trends are absorbing specialized tonnage where technical barriers limit effective supply competition.
- Offshore:Mid-depth developments between 100-400 meters represent the largest addressable volume, with standardized vessel specifications enabling fleet mobility across the North Sea, West Africa, and Southeast Asian producing basins.
- Shallow Water:Shelf operations above 100 meters utilize lower-specification tonnage with reduced fuel efficiency requirements, though EU Green Deal compliance is forcing accelerated retirement of older assets even in these less demanding applications.
- Onshore:Port-based support and coastal logistics services use modified crew transfer and small supply craft for nearshore wind construction staging.
Revenue concentration sits with Offshore deployments; steepest specification upgrades are occurring in Deepwater.
End User:
Customer procurement patterns are diverging as renewable energy developers adopt spot-market vessel sourcing while oil and gas majors retain integrated logistics contracts.
- Oil & Gas Companies:Integrated majors and national oil companies in Norway, Brazil, and the United States charter vessels through multi-year agreements tied to field development timelines, with contract structures shifting toward performance-based day-rate mechanisms that penalize carbon intensity exceedances.
- Renewable Energy Providers:Offshore wind developers in the United Kingdom, Germany, and Denmark are unbundling vessel supply from construction contracts, creating fragmented demand for turbine installation vessels and crew transfer units organized around campaign-specific procurement.
- Marine Construction Firms:Subsea contractors executing cable lay, foundation installation, and inter-array work require specialized heavy-lift and construction support tonnage with integrated crane and ROV capabilities.
- Fisheries:Aquaculture support and fish farm maintenance generate seasonal demand for small multipurpose craft in Norwegian and Scottish coastal waters.
Contract value aggregates with Oil & Gas Companies; procurement velocity is climbing fastest among Renewable Energy Providers.
Vessel Type:
Technical classification systems are consolidating around hybrid-electric propulsion architectures that satisfy emerging charterer sustainability criteria.
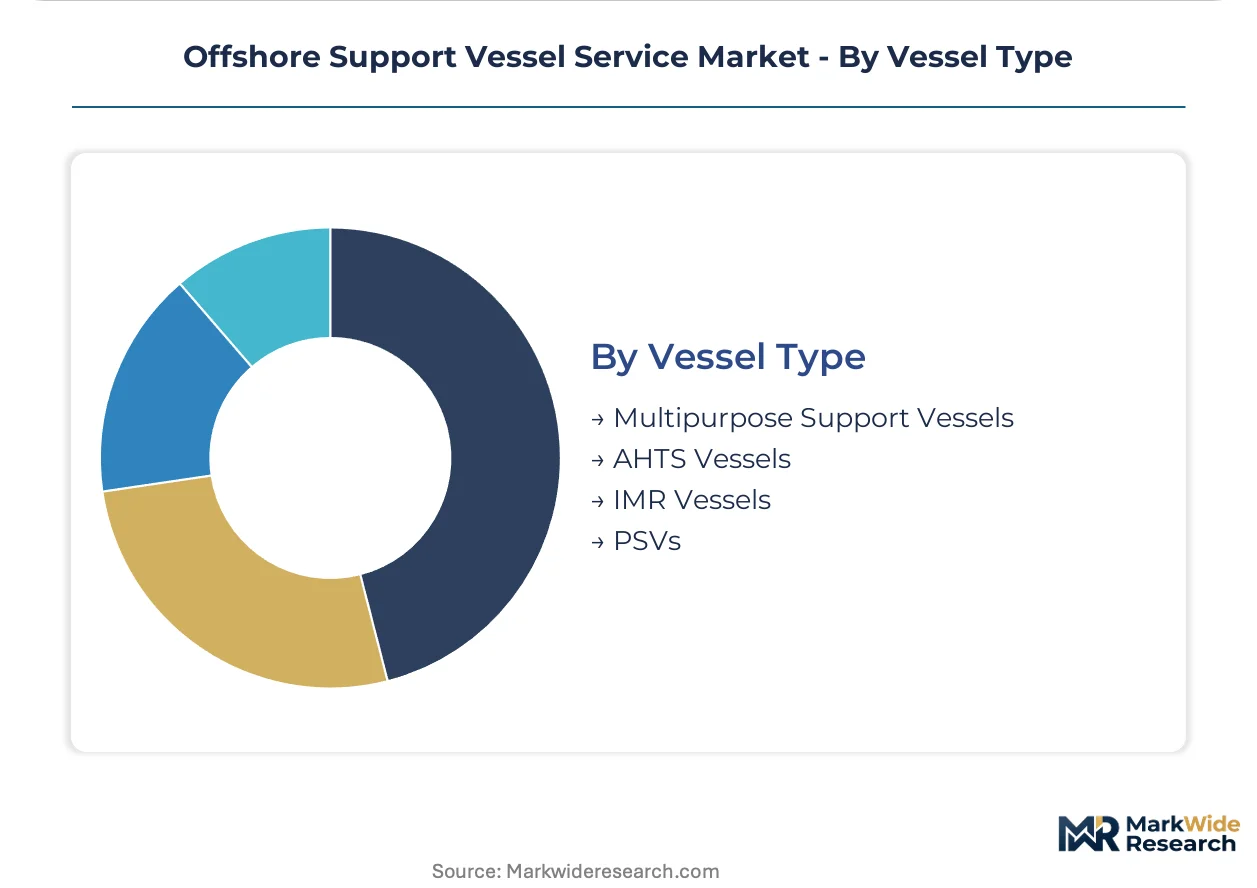
- PSVs:Platform supply vessels with open deck cargo capacity and below-deck tank configurations dominate transaction volume across producing basins, with newbuild specifications increasingly incorporating battery-hybrid systems to achieve favorable IMO carbon intensity indicator ratings.
- IMR Vessels:Inspection, maintenance, and repair craft with integrated work-class ROV systems and subsea crane packages command sustained premium pricing from integrated oil companies executing subsea infrastructure campaigns in the North Sea and Gulf of Mexico.
- AHTS Vessels:Anchor handling tug supply units with enhanced bollard pull ratings serve drilling rig positioning and mooring installation in deepwater basins.
- Multipurpose Support Vessels:Flexible deck configurations and modular mission equipment enable these assets to transition between supply, construction support, and light subsea intervention roles.
Fleet investment concentrates in PSVs; margin expansion is strongest in IMR Vessels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aberdeen anchors offshore support vessel demand through its concentration of North Sea oil and gas logistics operations and emerging wind farm service corridors.
United Kingdom
Offshore wind developers in the North Sea are multiplying crew transfer requirements for turbine installation campaigns. The UK's Contracts for Difference scheme accelerates seabed lease allocations that strain local vessel supply chains. Port of Grimsby is expanding dedicated offshore wind marshalling facilities to handle installation vessel staging.
Norway
Subsea construction support for North Sea decommissioning and IMR operations sustains demand for high-specification tonnage. The Norwegian Maritime Authority enforces stringent carbon intensity standards that favor hybrid-electric newbuilds. Stavanger's offshore supply base concentrates DP-3 capable anchor handling capacity for deepwater pre-salt support.
Brazil
Pre-salt field developments in the Santos Basin require enhanced bollard-pull AHTS units for floating production system mooring installations. Petrobras chartering policies now penalize carbon intensity exceedances through performance-based day-rate mechanisms. Rio de Janeiro's offshore supply cluster is absorbing specialized tonnage where technical barriers limit effective supply competition.
United States
Gulf of Mexico Lower Tertiary trends and offshore wind lease auctions in the Atlantic are diversifying vessel demand beyond traditional oil and gas logistics. The Bureau of Ocean Energy Management's offshore wind permitting timelines are compressing vessel procurement windows for developers. Houma-Martinsville corridor in Louisiana concentrates platform supply vessel construction and fleet management operations.
Singapore
The city-state's shipyards and offshore marine base serve as the primary construction and conversion hub for Southeast Asian and Middle Eastern offshore developments. The Maritime and Port Authority's methanol bunkering infrastructure investments enable dual-fuel newbuild specifications. Tuas industrial zone is consolidating specialized offshore vessel construction capacity amid regional orderbook bottlenecks.
Offshore Support Vessel Service Market Competitive Landscape
Premium-margin players sit above commodity-margin players across specification tiers, with hybrid-electric newbuilds commanding sustained day-rate premiums over retrofitted legacy tonnage. The vendor base concentrates around integrated fleet operators with Americas, North Sea, and West African presences alongside specialized subsea construction support providers. Two archetypes dominate: diversified fleet operators leveraging standardized vessel platforms and subsea specialists capturing IMR premium pricing. Consolidation through distressed asset acquisitions and newbuild orderbook positioning represent the dominant competitive vectors.
Within the diversified fleet tier, Tidewater Inc. and BOURBON occupy positions that exemplify regional specialization strategies, with Tidewater representing Americas-focused modernization approaches and BOURBON anchoring standardized platform deployment across multiple basins. DOF Group sits within the subsea construction support archetype where technical specification intensity limits effective supply competition.
| Leading Market Players |
|---|
| A.P. Moller-Maersk |
| Tidewater Inc. |
| BOURBON |
| DOF Group |
| Deltamarin Ltd |
| Edison Chouest Offshore |
| SEACOR Marine Holdings Inc. |
| Solstad Offshore ASA |
| Havila Shipping ASA |
| Others |
Value Network & Pricing Analysis
Battery-hybrid propulsion retrofits and newbuild specifications are compressing operating cost structures while concentrating vessel procurement power among charterers with multi-year field development commitments. Norwegian and Singaporean shipyards are absorbing premium pricing for specialized tonnage as IMO carbon intensity deadlines force accelerated replacement cycles across diesel-mechanical fleets.
Pricing Analysis
Day-rate premiums tied to uptime guarantees and fuel efficiency performance dominate contract structures for DP-3 capable anchor handling units in Brazilian pre-salt basins. Three-tier pricing structure across premium hybrid-electric, retrofitted mid-life, and legacy diesel-mechanical specifications separates charter rates by carbon intensity rating and dynamic positioning class. Pricing pressure stems from crew boat spot-market fragmentation in European offshore wind zones where project-specific procurement multiplies vessel availability mismatches. Renewable energy developers exhibit highest price sensitivity through unbundled campaign charters; integrated oil companies accept premium tiers for assured availability in deepwater pre-salt operations.
Supply Chain Analysis
High-tensile steel plate and specialized hybrid propulsion systems rest on Norwegian, South Korean, and Chinese manufacturing clusters with limited alternative sourcing. Lithium-ion battery cells, permanent magnet motors, and dynamic positioning control systems anchor newbuild cost structures. Single-source vulnerability concentrates in Norwegian DP system integrators and Chinese battery cell suppliers. Distribution runs through shipyard direct contracts with fleet operators, bypassing traditional vessel broker networks for high-specification tonnage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet decarbonization mandates and IMO compliance deadlines are consolidating procurement power among capitalized operators capable of hybrid-electric newbuild programs, forcing distressed asset sales from smaller owners.
For Market Incumbents: Acquire stranded legacy tonnage at distressed valuations to secure retrofit orderbook slots at concentrated Norwegian and Singaporean yards before capacity constraints intensify. Defend charter relationships by embedding carbon intensity performance clauses that align with Petrobras and Equinor procurement criteria. Prioritize DP-3 certification investment for anchor handling units serving Brazilian pre-salt mooring installation campaigns. For New Entrants and Emerging Players: Begin with crew transfer vessel deployment in Taiwanese and South Korean offshore wind zones where local supply chains remain undeveloped and licensing timelines compress procurement windows. Target spot-market charter platforms that match vessel availability to turbine installation campaign schedules. Pursue joint venture structures with established North Sea operators to access charterer qualification requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified fleet operators seeking basin-specific capacity additions rather than public market listings. Long-term viability favors subsea construction support specialists with IMR vessel specifications and integrated ROV capabilities where technical barriers limit supply competition. Watch IMO Energy Efficiency Existing Ship Index enforcement divergence across flag states as inflection indicator for asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Newbuild Program | Secures IMO CII compliance and premium day-rate tiers from carbon-conscious charterers in North Sea basins. |
| DP-3 Certification Investment | Unlocks Brazilian pre-salt and Gulf of Mexico Lower Tertiary anchor handling contracts with technical entry barriers. |
| Shipyard Capacity Reservation | Locks construction slots at Norwegian and Singaporean yards before orderbook bottlenecks intensify replacement demand. |
| Subsea Construction Support Expansion | Captures IMR premium pricing from integrated oil companies executing North Sea decommissioning campaigns. |
| Asian Offshore Wind Market Entry | Addresses crew transfer vessel supply gaps in Taiwan, South Korea, and Japan licensing corridors. |
Research Methodology
Document review covered customs trade data, shipyard orderbook disclosures, and flag-state registration records, complemented by interviews with fleet operations directors, chartering managers at integrated oil companies, offshore wind project developers, shipyard commercial executives, and maritime classification society surveyors. Secondary validation drew from Lloyd's List intelligence, Clarksons Research vessel databases, IMO regulatory filings, and national offshore wind leasing authority announcements. Bottom-up vessel deployment counts were triangulated against top-down charter market value estimates.
Cross-referencing historical fleet utilization patterns against panel input from chartering executives established baseline demand assumptions across the projection horizon. Segmentation modeling incorporated service type, water depth deployment, end-user procurement pattern, and vessel propulsion architecture dimensions. CAGRs were derived from fitted trend extrapolation adjusted for regulatory compliance deadline clustering and regional offshore wind capacity auction schedules. Forecast inputs included shipyard delivery timelines, battery energy density improvement curves, and carbon intensity rating distribution shifts.
Underlying measurement precision varies by segment; deepwater anchor handling and subsea construction support carry tighter precision than commoditized platform supply vessel categories due to concentrated charterer visibility. Forecasts reflect documented assumptions about regulatory enforcement consistency and alternative fuel infrastructure buildout pace. A small set of triggers warrants ongoing watch: flag-state EEXI enforcement divergence, lithium-ion battery supply constraints, and North Sea decommissioning campaign acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Middle East Offshore Support Vessels Market
Maritime Equipment
Drill Ships Market
Maritime Equipment
United States Maritime Information Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Global Maritime Safety Market
Maritime Equipment
Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
China Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Emergency Response and Rescue Vessels Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Hong Kong Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Marine Steering Gear Systems Market
Maritime Equipment
Marine Vessel Market