
 Integrated Marine Automation System Market | 2026-2036
Integrated Marine Automation System Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Marine Automation System Market Intelligence
DNV GL's type approval cycle for integrated automation systems is rotating vendor eligibility toward platforms with certified cybersecurity architectures. Kongsberg Gruppen ASA leverages its Kongsberg Maritime division to dominate bridge integration in the offshore support vessel segment. Wärtsilä Corporation anchors its automation portfolio through deep backward integration into propulsion hardware and energy management software. Siemens AG competes by extending its SIMIT simulation environment into virtual commissioning for marine control systems.
An integrated marine automation system fuses navigation, propulsion, power distribution, and cargo handling into a unified control architecture, typically operating on redundant Ethernet backbones with sub-50ms failover latency to maintain vessel safety and operational continuity under single-fault conditions. Its primary purpose is to reduce manning levels while improving fuel efficiency and regulatory compliance across commercial and naval fleets. Power Management systems lead system-type revenue due to their direct linkage with IMO decarbonization mandates and fuel cost reduction. Distributed Control System technology occupies the largest technology share, though Supervisory Control And Data Acquisition platforms are gaining fastest in offshore platform applications where shore-based remote monitoring reduces helicopter transport costs. Safety Monitoring commands premium pricing in the cruise ship application segment, driven by passenger-vessel liability frameworks and SOLAS chapter requirements.
The International Maritime Organization shapes product roadmaps through MARPOL Annex VI emission standards and the forthcoming revised STCW code for remote-operated vessel competencies. Classification societies including Lloyd's Register and Bureau Veritas enforce IEC 60945 electromagnetic compatibility and IEC 61162 digital interface standards as prerequisites for type approval. Ship operators and system integrators must monitor how flag-state interpretations of the IMO's Maritime Autonomous Surface Ships regulatory scoping exercise will redefine liability and insurance structures for reduced-crewing configurations.
Market Dynamics
The International Maritime Organization's Energy Efficiency Existing Ship Index is compressing retrofit timelines across aging commercial fleets, forcing shipowners to replace standalone control systems with unified automation architectures that can optimize fuel consumption in real time.
Growth Catalysts
- IMO decarbonization mandates:The Energy Efficiency Design Index and Carbon Intensity Indicator are compelling container ship operators to install integrated power management systems that reduce auxiliary engine runtime.
- Offshore wind expansion:Service vessel fleets in the North Sea are adopting dynamic positioning automation to maintain station-keeping precision during turbine maintenance operations.
- Cybersecurity certification requirements:Classification societies now mandate IEC 62443-compliant network architectures for type approval, accelerating replacement of legacy serial-based control systems.
Market Restraints
- Copper and semiconductor input volatility:Marine-grade cabling and industrial processor shortages are extending lead times for distributed control system hardware by four to eight months.
- Engineering talent concentration in Northern Europe:Hamburg and Oslo harbor the majority of system integration specialists capable of certifying complex bridge-to-engine room integrations.
- Legacy vessel electrical incompatibility:Pre-2010 tonnage often lacks redundant Ethernet backbone infrastructure, requiring expensive cable routing through classified spaces.
Strategic Opportunities
- Remote monitoring convergence:Supervisory Control And Data Acquisition platforms paired with shore-based operations centers are reducing helicopter transport costs for offshore platform support.
- Autonomous vessel regulatory scoping:The IMO's Maritime Autonomous Surface Ships framework will create first-mover advantage for automation suppliers with reduced-crewing liability models.
- Cruise ship safety monitoring premium:SOLAS Chapter II-1 amendments are mandating integrated alarm and monitoring systems with passenger-vessel-specific redundancy protocols.
Industry Challenges
- IEC 60945 electromagnetic compatibility certification:Testing cycles for integrated bridge systems now require eighteen to twenty-four months, delaying revenue recognition for new product launches.
- Multi-vendor protocol integration:Proprietary fieldbus implementations from propulsion OEMs complicate unified control architecture deployment on retrofitted vessels.
- Marine automation engineer scarcity:STCW Code training requirements for remote-operated vessel competencies have outpaced maritime academy curriculum updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Marine Automation System Market |
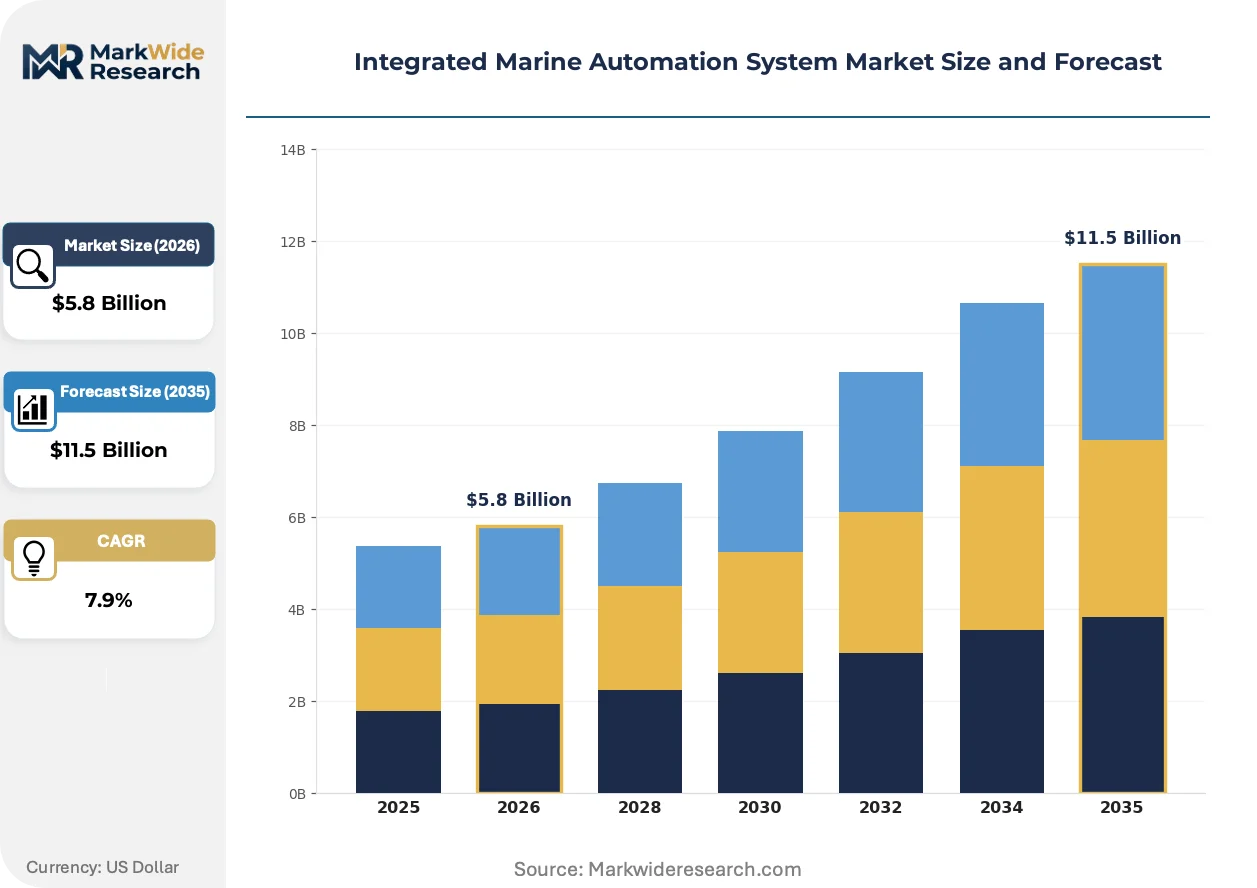
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Navigation Control, Power Management, Cargo Handling, Safety Monitoring, Propulsion Control, Communication Systems Technology: Distributed Control System, Programmable Logic Controller, Supervisory Control And Data Acquisition, Remote Terminal Unit, Human Machine Interface, Sensor Networks Application: Cruise Ships, Offshore Platforms, Fishing Vessels, Research Vessels, Tankers, Yachts End User: Shipyards, Maritime Defense, Ship Operators, Vessel Maintenance Providers, Marine Surveyors, Port Authorities |
| Companies Covered | ABB, Rolls-Royce Holdings plc, Kongsberg Gruppen ASA, Wärtsilä Corporation, Siemens AG, Emerson Electric Co., Honeywell International Inc., Rockwell Automation Inc., Navis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Marine Automation System Market Strategic Shifts & Innovations
Edge computing hardware is migrating from shore facilities onto vessels, enabling real-time analytics for predictive maintenance without satellite bandwidth dependency. This shift is compressing the traditional automation value chain and creating new competitive entry points.
Embedded sensor fusion modules are miniaturizing. These devices aggregate gyrocompass, radar, and GPS inputs into single-board navigation processors. Offshore support vessel operators are adopting them to reduce bridge console footprint. The technology is miniaturizing control room spatial requirements and enabling compact wheelhouse designs on smaller hulls.
The European Union's Cyber Resilience Act is extending CE marking requirements to marine automation software, mandating vulnerability disclosure and automatic update mechanisms. System integrators must now embed over-the-air patch capabilities into voyage-critical control loops. Cruise ship newbuilds in German and Italian yards are most affected, with classification societies revising type approval checklists to include software bill of materials documentation.
Shipowner purchasing committees are consolidating vendor relationships to reduce interface complexity. Integrated automation tenders now favor single-source accountability for navigation, propulsion, and power management over best-of-breed component selection. This concentration is visible in LNG carrier newbuild contracts at South Korean shipyards, where operators are accepting proprietary ecosystem lock-in to accelerate commissioning schedules and simplify crew training pathways.
Integrated Marine Automation System Market Segmentation
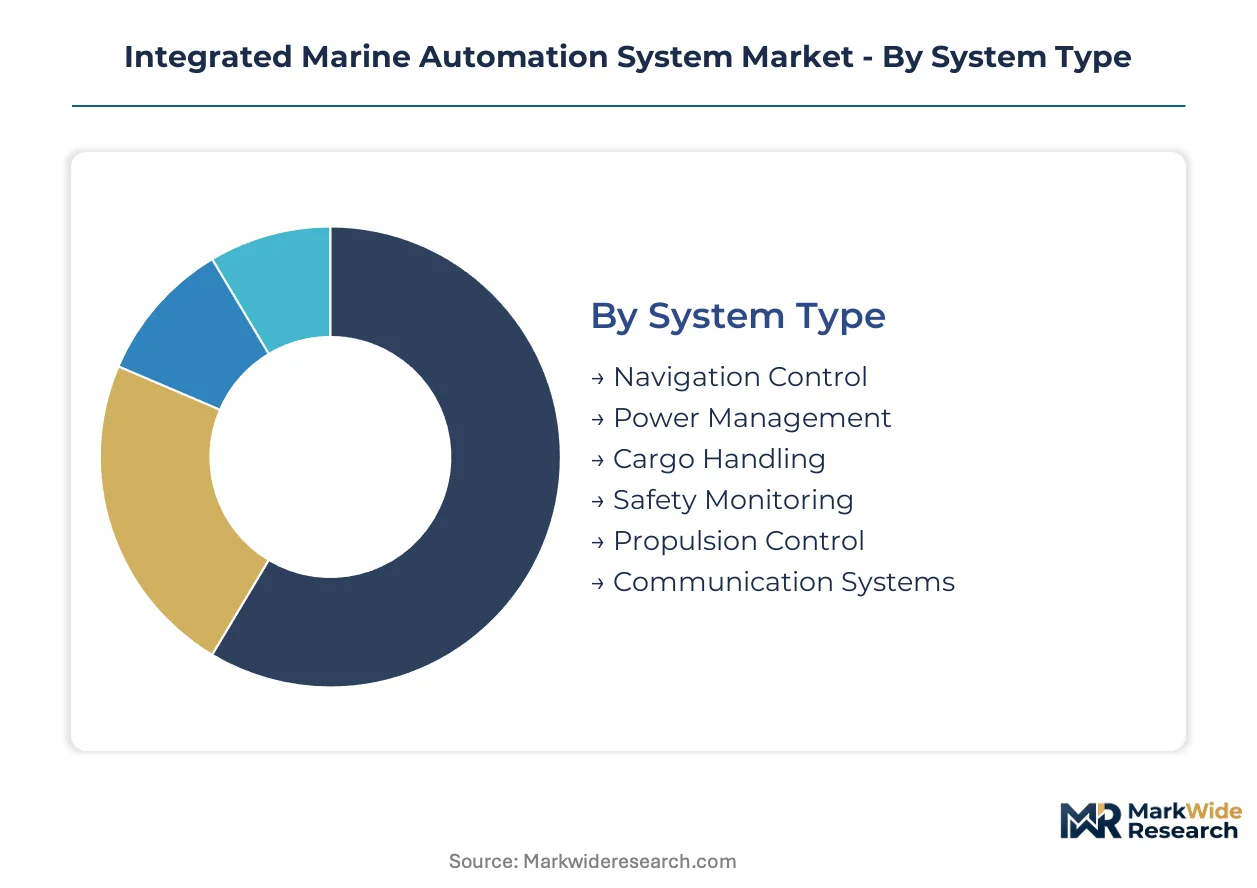
Segmentation in marine automation reveals how regulatory pressure and vessel economics concentrate investment across distinct technology tiers. Shipowners prioritize segments offering measurable fuel savings and compliance certification speed. Understanding these divisions exposes where procurement budgets flow and which system architectures capture upgrade cycles.
System Type:
German and Norwegian yards dominate domestic demand for bridge-integrated suites, while Asian retrofit markets absorb export-focused standalone modules.
- Power Management:These systems orchestrate generator scheduling, load distribution, and battery integration across hybrid propulsion architectures. Hamburg-based container operators are installing these systems to compress auxiliary engine runtime and satisfy IMO Carbon Intensity Indicator thresholds.
- Safety Monitoring:Integrated alarm and monitoring platforms with passenger-vessel-specific redundancy protocols. Italian and Finnish cruise newbuilds are mandating these systems under SOLAS Chapter II-1 amendments, driving premium pricing for certified suppliers.
- Navigation Control:Fuses gyrocompass, radar, and GPS inputs through redundant Ethernet backbones for bridge operation.
- Cargo Handling:Automates crane positioning and tank level monitoring for bulk carriers and LNG carriers.
- Propulsion Control:Governs main engine and thruster coordination for dynamic positioning operations.
- Communication Systems:Integrates GMDSS, satellite, and internal vessel networks into unified bridge architectures.
Power Management commands the established base. The steepest expansion runs through Safety Monitoring.
Technology:
Cost tier separation is pronounced: distributed architectures serve premium newbuilds, while programmable controllers capture mid-market retrofits.
- Distributed Control System:Redundant processor nodes managing propulsion, power, and cargo through unified Ethernet backbones with sub-50ms failover. North Sea offshore wind service fleets are specifying these platforms for dynamic positioning precision during turbine maintenance.
- Supervisory Control And Data Acquisition:Shore-to-vessel telemetry enabling remote diagnostics and reduced helicopter transport for platform support. Classification societies are mandating IEC 62443-compliant network architectures for type approval, accelerating displacement of legacy serial systems.
- Programmable Logic Controller:Standalone processors for discrete control loops on smaller vessels and fishing fleets.
- Remote Terminal Unit:Field-mounted I/O modules translating sensor signals for centralized processing.
- Human Machine Interface:Touchscreen consoles and alarm management displays for bridge and engine room operation.
- Sensor Networks:Embedded gyrocompass, radar, and GPS fusion modules miniaturizing control room footprints.
Distributed Control System anchors the revenue base. Supervisory Control And Data Acquisition platforms are climbing the fastest as shore-based operations centers proliferate.
Application:
Volume concentrates in deep-sea commercial tonnage, while margin pools in specialized vessels requiring precision station-keeping.
- Offshore Platforms:Dynamic positioning and power management systems for drilling rigs and wind farm service vessels. Norwegian and UK North Sea operators are retrofitting these systems to reduce fuel consumption during extended maintenance windows.
- Cruise Ships:Integrated alarm monitoring with passenger-vessel redundancy protocols and cybersecurity-hardened architectures. German and Italian yards are embedding over-the-air patch capabilities to satisfy EU Cyber Resilience Act CE marking requirements.
- Tankers:Cargo handling automation and ballast water treatment integration for crude and product carriers.
- Fishing Vessels:Compact navigation and communication suites for fleet management and catch monitoring.
- Research Vessels:Precision positioning and sensor integration for oceanographic data collection.
- Yachts:Bridge integration and entertainment system coordination for superyacht newbuilds.
Tankers represent the volume foundation. Offshore Platforms are gaining share fastest as wind farm installation accelerates.
End User:
Procurement authority is fragmenting: shipyards control newbuild specifications, while ship operators drive retrofit decisions.
- Ship Operators:Container, tanker, and cruise lines specifying integrated automation for fuel efficiency and reduced manning. South Korean LNG carrier operators are consolidating vendor relationships to accelerate commissioning and simplify crew training.
- Shipyards:Newbuild integrators selecting single-source accountability for navigation, propulsion, and power management. German and Italian yards are revising type approval checklists to include software bill of materials documentation under EU Cyber Resilience Act pressure.
- Maritime Defense:Naval fleets requiring hardened cybersecurity and redundant architectures for combat system integration.
- Vessel Maintenance Providers:Retrofit specialists upgrading pre-2010 tonnage with Ethernet backbone infrastructure.
- Marine Surveyors:Classification society representatives enforcing IEC 60945 electromagnetic compatibility and IEC 61162 digital interface standards.
- Port Authorities:Harbor control and vessel traffic management system operators.
Shipyards hold the specification authority. Ship Operators are expanding procurement fastest as EEXI retrofit deadlines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The International Maritime Organization's Energy Efficiency Existing Ship Index is compressing retrofit timelines across aging commercial fleets, forcing shipowners to replace standalone control systems with unified automation architectures that can optimize fuel consumption in real time. Regulatory pressure varies sharply by jurisdiction, with classification societies in Northern Europe and East Asia enforcing the strictest cybersecurity and electromagnetic compatibility standards. Procurement authority concentrates in maritime engineering clusters where shipyards, system integrators, and classification bodies maintain geographic proximity.
Germany
Hamburg and Bremerhaven anchor Europe's densest concentration of maritime automation engineering, serving container operators retrofitting tonnage for IMO Carbon Intensity Indicator compliance. The country's Federal Maritime and Hydrographic Agency enforces IEC 60945 electromagnetic compatibility certification cycles that now extend eighteen to twenty-four months. Bavaria-based industrial conglomerates supply simulation environments for virtual commissioning of marine control systems.
Norway
Oslo and Stavanger harbor system integration specialists certifying complex bridge-to-engine room integrations for offshore wind service fleets. The Norwegian Maritime Authority implements the IMO's Maritime Autonomous Surface Ships regulatory scoping exercise ahead of flag-state peers, creating first-mover testing grounds for reduced-crewing configurations. Kongsberg Gruppen ASA leverages its maritime division to dominate dynamic positioning automation in North Sea operations.
South Korea
LNG carrier operators at Ulsan and Geoje shipyards are consolidating vendor relationships to accelerate commissioning schedules and simplify crew training pathways. The Korea Maritime Safety Tribunal aligns domestic type approval with IEC 61162 digital interface standards as prerequisites for commercial operation. Samsung Heavy Industries and Hyundai Heavy Industries anchor demand for integrated power management systems in newbuild contracts.
China
Shanghai and Dalian shipyards drive volume demand for mid-market retrofits on pre-2010 tonnage lacking redundant Ethernet backbone infrastructure. The Maritime Safety Administration of China enforces MARPOL Annex VI emission standards through port state control inspections at Ningbo-Zhoushan and Qingdao. Domestic automation suppliers compete on cost for fishing vessel and coastal cargo applications.
United States
Houston and New Orleans service the Gulf of Mexico offshore platform sector, where shore-based remote monitoring reduces helicopter transport costs for drilling rig support. The US Coast Guard interprets SOLAS Chapter II-1 amendments for cruise vessels operating from Florida homeports. Classification society offices in Norfolk enforce IEC 62443-compliant network architectures for naval and commercial hybrid propulsion projects.
Integrated Marine Automation System Market Key Industry Players
Listed leaders compete with private specialists across certification-heavy segments, with publicly traded conglomerates anchoring premium newbuild specifications while private engineering houses capture retrofit niches requiring rapid customization. The vendor base stratifies into three tiers: full-stack integrators owning navigation, propulsion, and power management; component specialists certified for specific subsystems; and regional system houses serving flag-state-specific requirements. Consolidation pressure intensifies as shipowner purchasing committees demand single-source accountability, driving acquisition activity among bridge-to-engine room integration specialists and cybersecurity certification consultancies.
Within the full-stack integrator tier, Kongsberg Gruppen ASA and Wärtsilä Corporation represent contrasting geographic anchoring strategies, with the former exemplifying Nordic offshore specialization and the latter demonstrating deep backward integration into propulsion hardware. Siemens AG occupies a position bridging industrial automation heritage with marine-specific simulation environments. These three entities exemplify how European engineering conglomerates leverage type approval relationships with Lloyd's Register and Bureau Veritas to defend specification authority in German and Italian yard newbuilds.
| Leading Market Players |
|---|
| ABB |
| Rolls-Royce Holdings plc |
| Kongsberg Gruppen ASA |
| Wärtsilä Corporation |
| Siemens AG |
| Emerson Electric Co. |
| Honeywell International Inc. |
| Rockwell Automation Inc. |
| Navis |
| Others |
Cost & Logistics Intelligence
IEC 60945 electromagnetic compatibility certification gates supplier qualification while simultaneously stratifying price tiers, as eighteen-to-twenty-four-month approval cycles eliminate cost-competitive unqualified vendors and concentrate pricing power among Lloyd's Register and Bureau Veritas-certified integrators.
Pricing Analysis
Certification level creates the primary spread between premium bridge-to-engine room integrators and commodity component suppliers. Project-based contracting dominates, with pricing stratifying across IEC 62443-compliant platforms, standard Ethernet-backbone systems, and legacy serial retrofit modules. Copper and semiconductor input volatility is compressing margins on distributed control system hardware. Container operators in Hamburg exhibit lowest price sensitivity due to EEXI compliance deadlines, while Asian fishing fleet retrofits face acute cost pressure.
Supply Chain Analysis
Baltic Sea cable routing underwrites marine-grade Ethernet backbone availability for European newbuilds. Component manufacturing concentrates in Germany, Norway, and South Korea. Supply chains draw from marine-grade copper cabling, industrial-grade processors, and gyrocompass sensor modules. Single-source vulnerability runs through semiconductor foundry capacity for safety-critical processors. Distribution runs through shipyard procurement committees and system integrator channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor consolidation among shipowner purchasing committees fragments specification authority, creating white-space opportunities for cybersecurity-certified specialists and regional retrofit integrators.
For Market Incumbents: Consolidate through acquisition of bridge-to-engine room integration specialists in Hamburg and Oslo to defend against emerging pure-play cybersecurity certification consultancies. Deepen backward integration into propulsion hardware to lock out component competitors from LNG carrier newbuilds at South Korean yards. Prioritize IEC 62443-compliant network architecture R&D as classification societies mandate replacement cycles. For New Entrants and Emerging Players: Differentiate on rapid retrofit certification for pre-2010 tonnage lacking redundant Ethernet infrastructure, where legacy electrical incompatibility blocks incumbent solutions. Target Chinese mid-market fishing and coastal cargo fleets with cost-optimized programmable logic controller architectures. Pursue ship operator direct sales channels bypassing yard procurement gatekeepers. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core maritime automation divisions amid portfolio streamlining. Five-to-ten-year viability hinges on positioning within IMO Maritime Autonomous Surface Ships regulatory scoping outcomes. Monitor flag-state liability framework interpretations as inflection signal for reduced-crewing configuration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | IEC 62443 compliance accelerates displacement of legacy serial systems at Lloyd's Register. |
| Backward Integration into Propulsion Hardware | Wärtsilä's captive supply of energy management software locks Korean LNG carrier specifications. |
| Remote Monitoring Platform Integration | Shore-based SCADA convergence reduces helicopter transport costs for North Sea offshore platforms. |
| Regional Retrofit Specialist Acquisition | Hamburg and Bremerhaven engineering clusters concentrate scarce bridge-to-engine room integration talent. |
| Virtual Commissioning Capability Buildout | Siemens SIMIT simulation environment accelerates German and Italian yard newbuild schedules. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with ship automation engineers, classification society surveyors, shipyard procurement directors, and offshore wind service fleet managers; and secondary validation against Lloyd's Register type approval databases, IEC standards documentation, IMO regulatory circulars, and customs trade records for marine-grade cabling and industrial processors. Bottom-up vessel fleet segmentation triangulated against top-down shipyard orderbook analysis.
Across the analysis window, the forecasting framework modeled system type, technology architecture, vessel application, and end-user procurement authority dimensions. CAGRs derived from segment-level adoption curves weighted by regulatory enforcement timelines and retrofit deadline clustering. Forecast inputs incorporated Energy Efficiency Existing Ship Index compliance schedules and offshore wind installation capacity pipelines.
Material uncertainties — copper and semiconductor supply disruptions, flag-state MASS liability interpretations, and STCW code curriculum update lags — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as IMO decarbonization mandate enforcement intensity evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Europe Offshore Support Vessels Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Ship Stabilizers Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Ship-To-Shore (STS) Container Cranes Market
Maritime Equipment
Persian Gulf Offshore Support Vessels (OSV) Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
Europe Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
United States Offshore Support Vessels Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Voyage Data Recorder (VDR) Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market