
 Emergency Response and Rescue Vessels Market | 2026-2036
Emergency Response and Rescue Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Response and Rescue Vessels Market Analysis
Aftermarket service revenue is tilting toward integrated lifecycle support contracts as owners seek to reduce total cost of ownership over vessel operating lives. Damen Shipyards Group leverages its global service network to capture recurring maintenance streams. Ulstein Group ASA anchors its position through advanced hull design technology that commands premium positioning in the fast rescue boat segment. Edison Chouest Offshore sustains its competitive edge via in-house production of specialized offshore support craft across multiple Gulf Coast facilities.
Emergency response and rescue vessels are purpose-built marine craft engineered to withstand harsh sea states, typically featuring reinforced hull structures, firefighting systems rated to FIFI 1 or FIFI 2 classification, and recovery davits capable of launching rigid inflatable boats in sea states up to 5 meters significant wave height. Their primary commercial purpose is to protect human life, contain maritime incidents, and support offshore platform evacuation protocols. Fast rescue boats and firefighting vessels together represent the most technically demanding segment categories, with firefighting vessels carrying higher capital intensity due to pump capacity and foam system requirements. Crew boats remain the most mature vessel type, while dive support vessels attract specialized margin pools through saturation diving system integration.
IMO SOLAS regulations, the International Safety Management Code, and national maritime authority certifications such as those administered by Norway's Petroleum Safety Authority shape hull construction standards, crew training mandates, and equipment carriage requirements. These frameworks directly determine market access for builders and influence replacement cycles for aging fleets. Stakeholders must monitor evolving polar code requirements and alternative fuel compatibility standards as next-generation vessel specifications take shape.
Market Dynamics
Fleet renewal programs across North Sea offshore operators are compressing replacement cycles as aging vessels face stricter survivability standards under amended SOLAS regulations. This structural pressure is reshaping procurement timelines and technical specifications simultaneously.
Growth Catalysts
- IMO SOLAS amendments:Tightened evacuation system requirements mandate higher-capacity recovery davits and enhanced firefighting ratings, forcing platform operators toward certified newbuilds.
- North Sea offshore activity:Norway's Petroleum Safety Authority enforces national standards exceeding baseline international rules, sustaining premium vessel demand in harsh-environment zones.
- FIFI 2 pump systems:Advanced foam proportioning technology enables simultaneous firefighting and personnel recovery operations, expanding operational envelopes for multi-mission craft.
Market Restraints
- Specialized steel alloys:High-tensile hull plating for ice-class and polar code compliance faces volatile pricing from concentrated Nordic mill supply.
- Propulsion system complexity:Hybrid-electric architectures require scarce marine electrical engineering talent, extending delivery timelines for integrated powertrain vessels.
- Norwegian certification backlog:Petroleum Safety Authority approval queues for novel hull designs delay market entry for experimental rescue craft configurations.
Strategic Opportunities
- Polar code expansion:Arctic offshore exploration permits under Norway's jurisdiction create demand for ice-strengthened fast rescue boats with extended temperature ratings.
- Integrated lifecycle contracts:Multi-year maintenance agreements covering propulsion, davit systems, and firefighting equipment generate recurring revenue streams beyond initial hull delivery.
- Alternative fuel retrofit pathways:Ammonia-ready engine compartments and methanol fuel system pre-installation position existing fleets for future IMO carbon intensity regulations.
Industry Challenges
- Saturation diving system integration:Dive support vessel outfitting requires hyperbaric chamber certification timelines that misalign with platform operator emergency response readiness schedules.
- Crew certification gaps:Advanced dynamic positioning operation and fast rescue boat command qualifications outpace maritime academy output in key North Sea labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Response and Rescue Vessels Market |
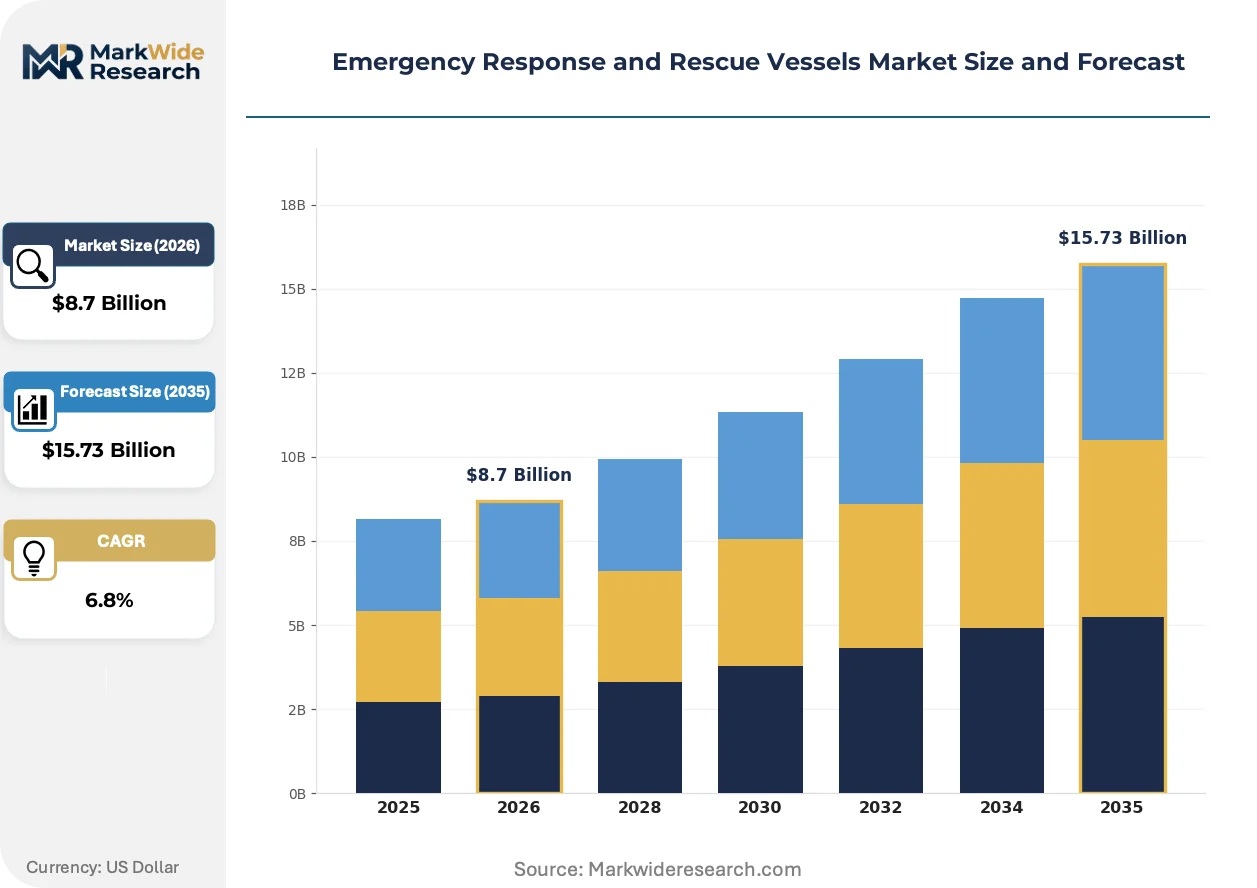
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Fast Rescue Boats, Firefighting Vessels, Crew Boats, Dive Support Vessels Application: Coast Guard Operations, Disaster Response, Search and Rescue, Maritime Security End User: Government Agencies, Non-Governmental Organizations, Military, Private Contractors Deployment Model: Onshore, Offshore, Inshore, Emergency Situations |
| Companies Covered | Bourbon, Ulstein Group ASA, Damen Shipyards Group, Gulfmark Offshore, Edison Chouest Offshore, Vroon, Kleven Maritime, Robert Allan Ltd, Esvagt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Response and Rescue Vessels Market Emerging Trajectories
Unmanned systems integration and predictive maintenance architectures are redefining vessel operational models. Platform operators now specify sensor-rich hulls capable of remote diagnostics and reduced onboard crew complements.
Autonomous surface vehicle docking systems are rendering obsolete conventional davit-launched rigid inflatable boat recovery protocols. Norwegian offshore operators are piloting self-righting unmanned rescue craft that extend search radius without risking secondary crew exposure. This convergence of robotics and maritime safety protocols is compressing manned fast rescue boat procurement volumes in high-automation platform clusters.
The EU Maritime Safety Agency is advancing harmonized standards for alternative fuel emergency response vessels under its sustainable shipping initiative. Shipyards must now demonstrate methanol bunkering compatibility and ammonia detection system integration to maintain market access across European offshore zones. Fast rescue boat segments face the steepest redesign curves as compact hull geometries complicate fuel tankage and ventilation engineering.
Charter contracting is displacing traditional ownership models for standby emergency response assets. UK and Dutch offshore operators now specify availability-based agreements where vessel providers assume operational risk and maintenance burden. Norway's state-affiliated platform consortia remain the exception, retaining owned fleets due to Petroleum Safety Authority continuity requirements and national content obligations.
Emergency Response and Rescue Vessels Market Segmentation
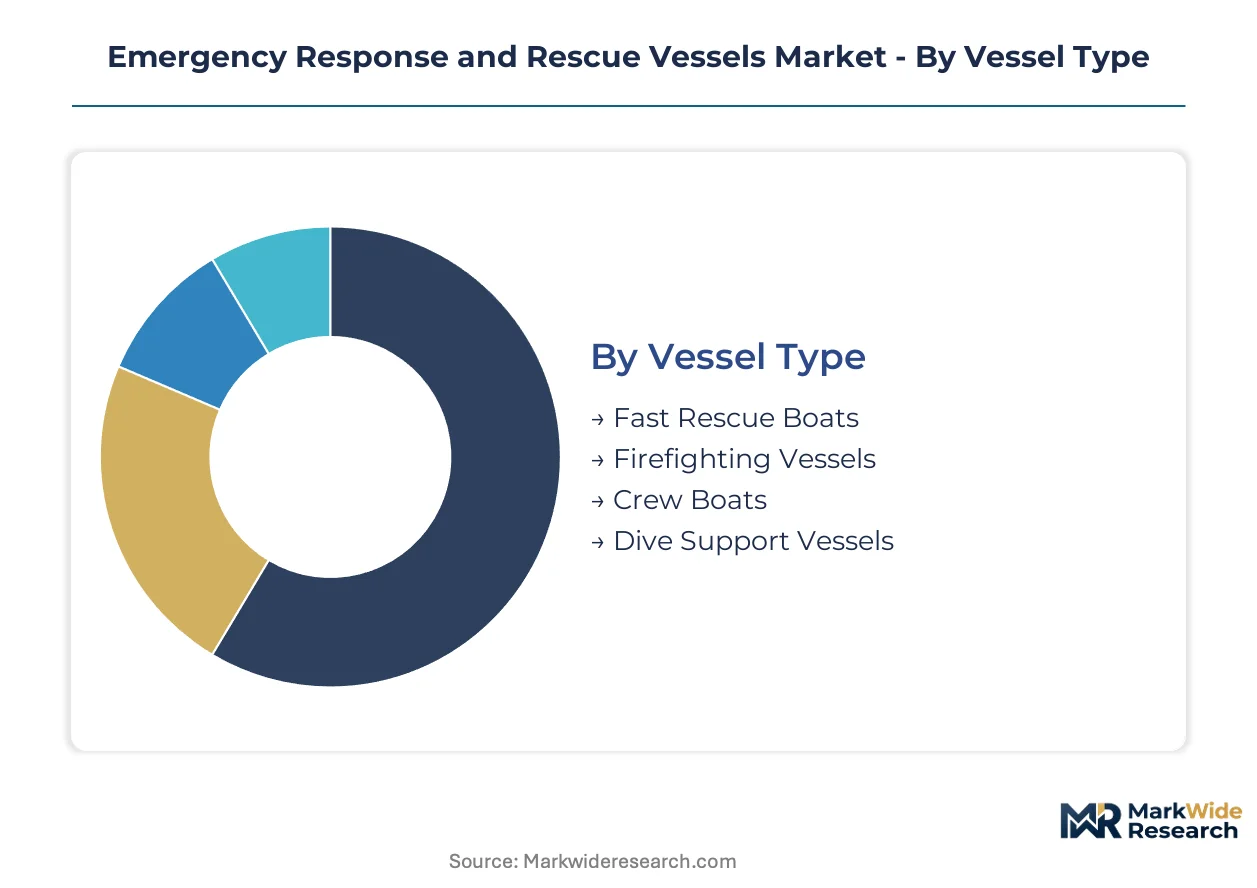
Segmentation in emergency response and rescue vessels reveals how technical specifications diverge across operational contexts. Vessel capabilities, deployment environments, and procurement authority structures each create distinct margin pools and competitive barriers for builders.
Vessel Type:
Cost tiers separate vessel categories by capital intensity and equipment complexity, with firefighting systems and diving infrastructure commanding premium positioning.
- Fast Rescue Boats:Compact hulls with self-righting capability and waterjet propulsion enable rapid deployment in sea states exceeding 3 meters. Norwegian North Sea operators specify these for platform evacuation protocols under Petroleum Safety Authority mandates. Crew certification requirements for fast rescue boat command outpace maritime academy output, constraining fleet expansion timelines.
- Firefighting Vessels:FIFI 1 and FIFI 2 pump ratings determine operational envelope, with foam proportioning systems enabling simultaneous firefighting and personnel recovery. Demand concentrates in UK and Dutch offshore zones where platform density requires dedicated standby assets. Capital intensity runs highest in this category due to pump capacity and integrated davit systems.
- Crew Boats:Mature vessel category with standardized specifications and compressed margins.
- Dive Support Vessels:Saturation diving system integration creates specialized margin pools through hyperbaric chamber certification requirements.
Firefighting vessels hold installed capacity. Fast rescue boats are rotating up the share rankings.
Application:
Application scope determines regulatory oversight intensity and equipment carriage mandates, with coast guard and maritime security operations facing the strictest certification requirements.
- Coast Guard Operations:National maritime authorities enforce equipment standards exceeding baseline SOLAS requirements. Patrol configurations prioritize endurance and communications redundancy for extended search patterns. Procurement concentrates in government budgets with multi-year capital planning cycles.
- Disaster Response:Multi-mission flexibility defines specifications, with modular deck layouts accommodating medical facilities, command centers, or cargo handling. Demand spikes correlate with climate-driven extreme weather frequency in coastal zones.
- Search and Rescue:Night vision compatibility and thermal imaging systems extend operational windows. Private contractors increasingly bid for outsourced SAR contracts in Mediterranean and North Sea zones.
- Maritime Security:Threat response protocols influence armor plating and small arms storage specifications. Port facility security assessments drive recurring vessel upgrades.
Coast guard operations anchor procurement volume. Disaster response is climbing the fastest as climate adaptation budgets expand.
End User:
Customer type segmentation exposes divergent procurement timelines, with government agencies operating on extended capital cycles and private contractors responding to spot charter demand.
- Government Agencies:National maritime administrations and coast guard services specify domestic content requirements and local build mandates. Norway's state-affiliated platform consortia retain owned fleets due to Petroleum Safety Authority continuity obligations.
- Military:Naval specifications prioritize communications interoperability and weapons compatibility. Procurement cycles align with defense budget authorizations spanning 5-10 year horizons.
- Non-Governmental Organizations:Humanitarian operators prioritize cost efficiency and multi-mission adaptability over specialized performance. Fleet composition emphasizes donated or second-hand vessels.
- Private Contractors:Availability-based charter agreements now dominate UK and Dutch offshore markets, transferring operational risk to vessel providers.
Government agencies maintain fleet ownership. Private contractors are gaining share fastest through charter model expansion.
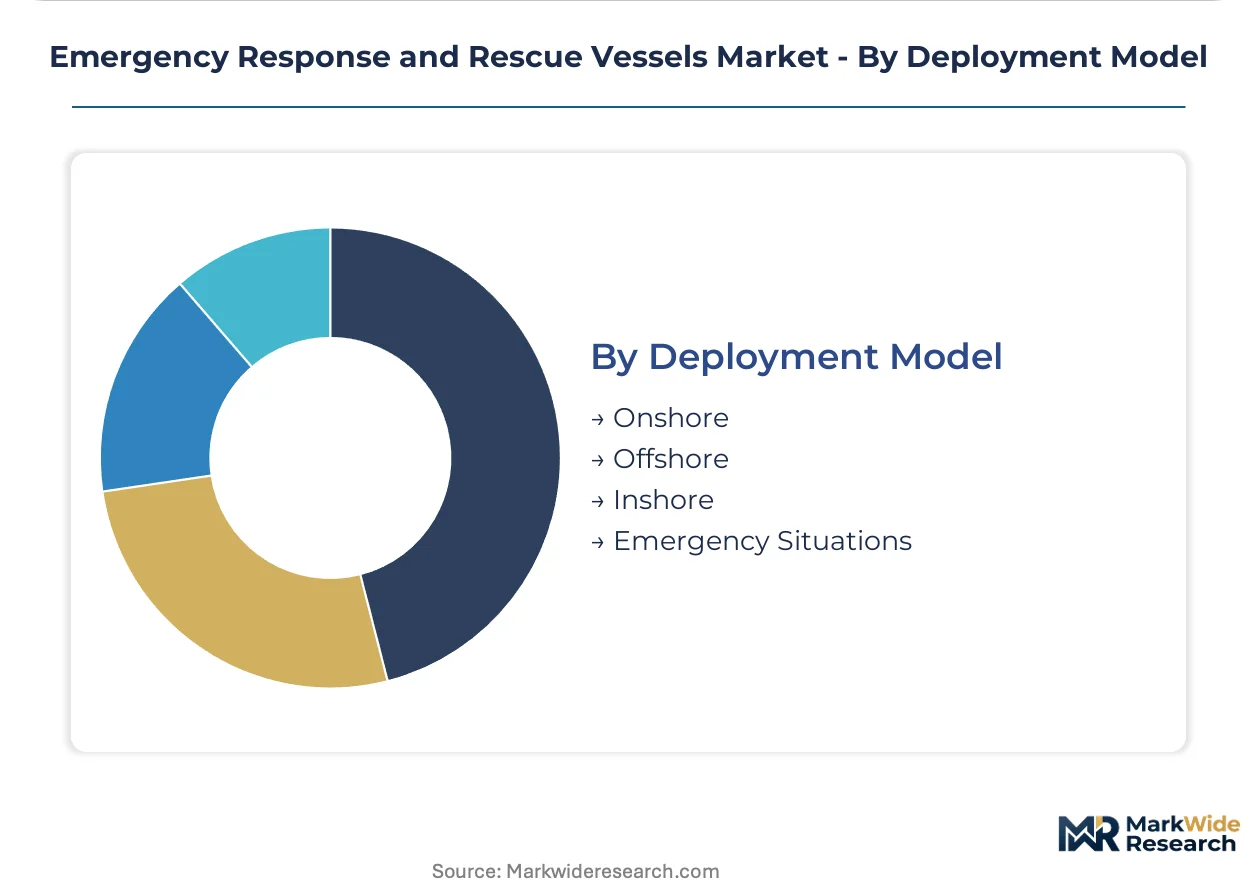
Deployment Model:
Geography and operational context shape hull construction standards, with offshore and polar environments demanding ice-class plating and extended temperature ratings.
- Offshore:Platform standby duties require dynamic positioning systems and rapid response readiness measured in minutes. Norway's jurisdiction leads specification intensity for harsh-environment survivability.
- Onshore:Harbor-based rapid response vessels prioritize shallow draft and beach landing capability. Coastal municipalities fund these through port security grants.
- Inshore:Estuary and riverine operations face draft constraints and bridge clearance limitations. Waterjet propulsion dominates for debris tolerance.
- Emergency Situations:Surge deployment contracts activate reserve fleets during catastrophic events. Vessel interoperability standards enable cross-border mutual aid protocols.
Offshore deployment holds installed capacity. Emergency situations is rotating up the share rankings as climate adaptation funding expands standby fleet contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway deploys emergency response vessels for platform standby duties under the harshest survivability standards, while the United Kingdom and Netherlands favor availability-based charter contracting that transfers operational risk to vessel providers. This consumption-mix differential separates ownership-retention markets from outsourcing-adoption zones.
Norway
North Sea offshore activity and state-affiliated platform consortia sustain premium vessel demand through owned-fleet retention. The Petroleum Safety Authority enforces national standards exceeding baseline IMO SOLAS requirements for harsh-environment survivability. Bergen and Stavanger anchor design engineering clusters where Ulstein Group ASA and Kleven Maritime advance hull technology for ice-strengthened fast rescue boats.
United Kingdom
Platform density in the UK Continental Shelf requires dedicated standby firefighting assets with FIFI 2 pump ratings and dynamic positioning systems. The Maritime and Coastguard Agency implements equipment standards aligned with evolving polar code requirements for North Sea operations. Aberdeen concentrates vessel management operations where charter contracting now dominates procurement, displacing traditional ownership models among offshore operators.
Netherlands
Rotterdam port complex and southern North Sea gas infrastructure drive demand for multi-mission emergency response craft with modular deck configurations. The Netherlands Shipping Inspectorate coordinates with EU Maritime Safety Agency initiatives on alternative fuel compatibility standards for standby vessels. Vroon maintains operational presence from Dutch harbors, supporting availability-based agreements that shift maintenance burden to vessel providers.
United States
Gulf of Mexico offshore oil and gas production sustains demand for crew boats and fast rescue vessels with rapid deployment specifications. The Coast Guard enforces port facility security assessments that drive recurring vessel upgrades for maritime security applications. Edison Chouest Offshore operates multiple Gulf Coast facilities producing specialized offshore support craft with in-house manufacturing integration.
Denmark
Danish offshore wind expansion and Baltic Sea maritime traffic create demand for search and rescue vessels with extended endurance and thermal imaging systems. The Danish Maritime Authority administers certifications aligned with EU sustainable shipping initiatives for methanol-ready emergency craft. Esvagt anchors North Sea operations from Danish ports, supporting standby contracts for platform evacuation protocols and personnel recovery missions.
Emergency Response and Rescue Vessels Market Vendor Landscape
Capability concentration sits with specialized designers of advanced hull technology; scale advantage sits with diversified shipyard groups operating global service networks. The market structures around three tiers: premium-positioned specialists commanding design premiums, integrated builders capturing lifecycle service revenue, and regional fabricators competing on delivery speed. Strategic moves center on integrated lifecycle support contracts that extend revenue beyond initial hull delivery, and alternative fuel pre-installation that positions existing fleets for IMO carbon intensity regulations.
Among Norwegian-based specialists, Ulstein Group ASA and Kleven Maritime occupy positions defined by advanced hull design technology and harsh-environment engineering heritage. Damen Shipyards Group represents the integrated builder archetype with global service network coverage for recurring maintenance streams. Edison Chouest Offshore anchors the regional-scale tier through Gulf Coast production integration and captive manufacturing of specialized offshore support craft.
| Leading Market Players |
|---|
| Bourbon |
| Ulstein Group ASA |
| Damen Shipyards Group |
| Gulfmark Offshore |
| Edison Chouest Offshore |
| Vroon |
| Kleven Maritime |
| Robert Allan Ltd |
| Esvagt |
| Others |
Supply Flow & Price Mechanics
North Sea freight corridors connecting Norwegian mill centers to shipyards in Bergen and Stavanger transmit steel alloy cost volatility directly into hull pricing, compressing margins for firefighting vessel builders while enabling premium capture for ice-class certified fast rescue boat specialists.
Pricing Analysis
Long-term offtake contracts dominate procurement for Norwegian state-affiliated platform consortia, insulating these buyers from spot steel price swings while charter-based availability agreements in UK and Dutch zones expose operators to fuel cost pass-throughs. Price differentiation separates FIFI 2-certified multi-mission craft from baseline crew boats through pump capacity ratings and integrated davit complexity. Cost compression in standard crew boat segments is intensifying because Vietnamese and Turkish yards are entering with simplified hull designs. Government agencies under Petroleum Safety Authority mandates show least price sensitivity; private contractors bidding Mediterranean SAR outsourcing contracts face acute margin pressure.
Supply Chain Analysis
Extended payment terms from Nordic steel mills to Norwegian shipyards have compressed working capital cycles, forcing builders to prioritize hulls with pre-sold charter commitments. High-tensile steel plate concentrates in Norway, Sweden, and Finland; marine electrical systems for hybrid-electric propulsion draw from German and Dutch engineering centers. Single-source vulnerability sits with concentrated Nordic mill supply for ice-class plating. Distribution runs through integrated shipyard service networks that bundle lifecycle maintenance with initial hull delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous surface vehicle docking systems threaten to displace conventional davit-launched recovery protocols, forcing incumbent vessel builders to defend their manned craft franchises through technology integration rather than pure hardware sales.
For Market Incumbents: Pre-empt autonomous craft displacement by embedding sensor-rich diagnostics and remote monitoring into newbuild specifications, locking platform operators into recurring software maintenance streams. Secure captive supply of high-tensile steel alloys through backward integration into Nordic mill partnerships, insulating production schedules from alloy price volatility that compresses firefighting vessel margins. For New Entrants and Emerging Players: Arctic offshore exploration permits under Norway's jurisdiction represent the most penetrable entry point, as ice-strengthened fast rescue boat demand outpaces established builder capacity and Petroleum Safety Authority approval queues delay incumbent market entry. Bid on availability-based charter contracts in UK Continental Shelf zones where platform operators have abandoned ownership models and seek vessel providers willing to assume operational risk. For Investors and Strategic Acquirers: Design-engineering boutiques with advanced hull form intellectual property and existing Petroleum Safety Authority certification track records offer the strongest acquisition rationale, as these capabilities cannot be replicated through capital expenditure alone. Monitor Norwegian approval queue lengths for novel hull configurations; shortening backlogs signal imminent competitive entry that would compress design premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Lifecycle Contracting | Multi-year maintenance agreements covering propulsion and davit systems generate recurring revenue beyond hull delivery. |
| Alternative Fuel Pre-Installation | Ammonia-ready engine compartments position existing fleets for future IMO carbon intensity regulations. |
| Autonomous Systems Integration | Self-righting unmanned rescue craft extend search radius without risking secondary crew exposure. |
| Polar Code Certification Investment | Ice-strengthened hull ratings unlock Arctic offshore exploration permit opportunities under Norwegian jurisdiction. |
| Petroleum Safety Authority Fast-Track | Expedited novel hull design approval compresses time-to-market for experimental rescue craft configurations. |
Methodological Framework
The analysis maps fast rescue boats, firefighting vessels, crew boats, and dive support vessels, each validated through fleet managers at offshore platform operators, shipyard procurement directors, and maritime certification engineers. Primary interviews with Petroleum Safety Authority technical reviewers and dynamic positioning system integrators combined with secondary validation from Lloyd's Register classification databases, IMO SOLAS amendment trackers, and Norwegian offshore licensing authority filings. Bottom-up vessel delivery tallies triangulate against top-down offshore operator capital expenditure surveys.
Assumptions held fixed include prevailing IMO SOLAS regulatory frameworks and Norwegian Petroleum Safety Authority certification intensity; variables tested include polar code expansion timing and autonomous craft adoption curves across platform clusters. Segmentation dimensions modeled encompass vessel type, deployment environment harshness, and end-user ownership structure. CAGRs derive from replacement cycle compression analysis and fleet age distribution profiling, with inputs from North Sea platform standby duty requirements and UK charter contracting penetration rates.
Practitioners should monitor Petroleum Safety Authority approval queue lengths and Nordic steel alloy spot pricing for early signals of supply constraint or competitive entry acceleration. Macroeconomic deviation in offshore oil and gas investment cycles, regulatory amendments to polar code requirements, or breakthroughs in autonomous rescue craft reliability would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Marine Hatch Covers Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Mooring Buoy Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Ship Leasing Market
Maritime Equipment
Cargo Ship Repair and Maintenance Services Market
Maritime Equipment
North America Container Terminal Operations Market
Maritime Equipment
Global Shipbuilding Anti-Vibration Market
Maritime Equipment
Singapore Maritime Market
Maritime Equipment
Global Maritime Safety Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Ship Breaking Market
Maritime Equipment
United States Offshore Support Vessels Market
Maritime Equipment
North America Offshore Support Vessels Market