
 Ship Leasing Market | 2026-2036
Ship Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Ship Leasing Market Analysis
A shortage of qualified marine finance underwriters and charter-party negotiators is redrawing competitive boundaries for lessors seeking scale. ICBC Financial Leasing leverages its state-backed balance sheet to dominate newbuild bulk carrier transactions in the Pacific basin. Seaspan Corporation anchors its position through long-term operating leases with top-tier liner operators. Danaos Corporation specializes in mid-size containerships, competing on vessel age and fuel efficiency metrics.
Ship leasing denotes the contractual arrangement where vessel owners transfer use rights to operators without transferring title, typically governed by BIMCO standard agreements specifying hull condition, off-hire clauses, and redelivery specifications. The primary commercial purpose is to enable shipping companies to deploy tonnage without capitalizing full asset values on their balance sheets. Containerships command the largest lease book values due to liner operators' preference for fleet flexibility over ownership. Tanker leasing under bareboat structures carries higher residual risk but attracts oil majors seeking operational control without equity commitment. Operating leases now dominate new transactions as lessees prioritize off-balance-sheet treatment under IFRS 16.
The International Maritime Organization enforces carbon intensity regulations that phase out inefficient tonnage and redirect lease demand toward eco-designed vessels. China's Ministry of Transport and the EU's Monitoring, Reporting and Verification framework both impose compliance costs that lessors must embed in charter rates. The US Coast Guard's Port State Control inspections influence vessel selection criteria for trades touching American terminals. Stakeholders must monitor how regional green-fuel mandates reshape lease tenor preferences and residual value assumptions across vessel categories.
Market Dynamics
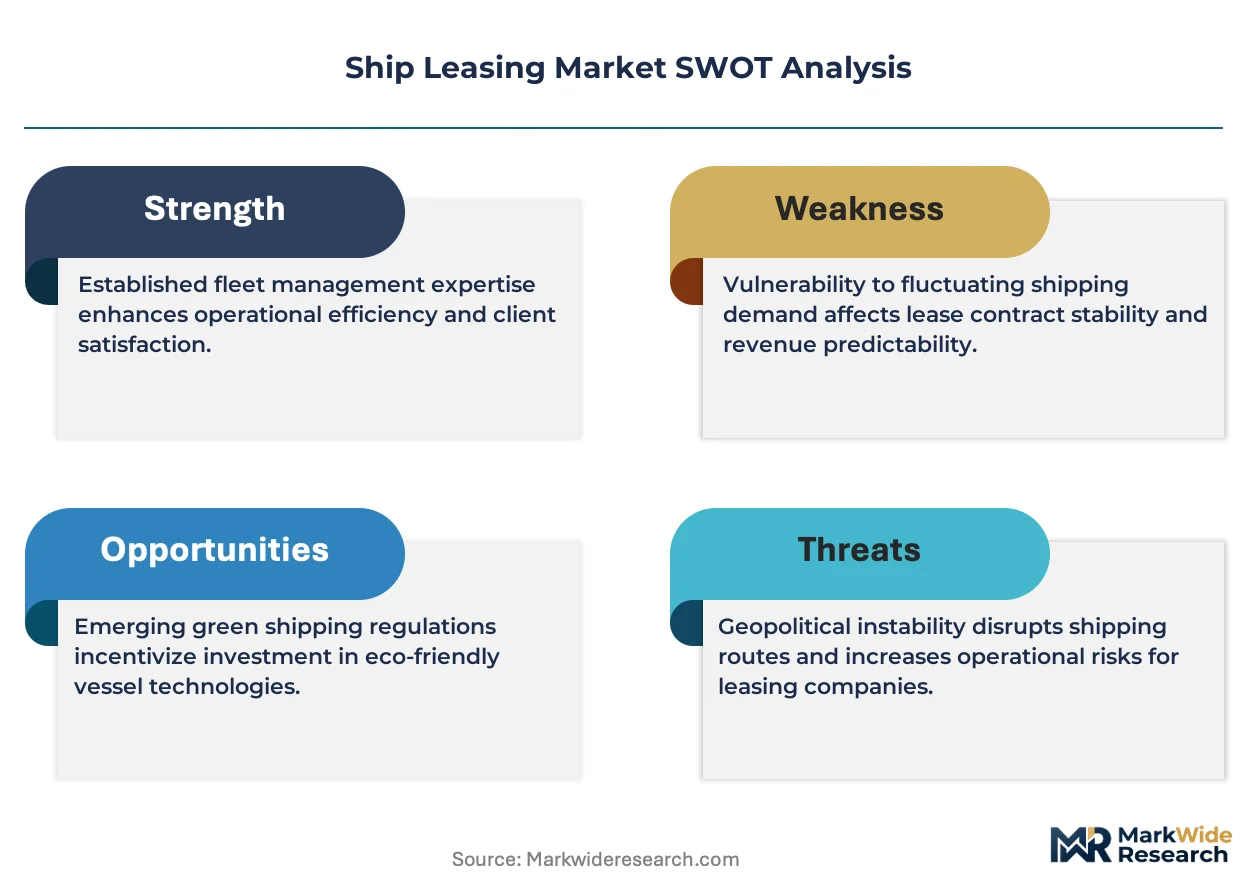
The IMO 2023 Carbon Intensity Indicator is forcing liner operators to retire older tonnage prematurely, redirecting lease demand toward dual-fuel-ready vessels and compressing residual values for conventional hulls across all major trading routes.
Growth Catalysts
- Containerized trade expansion:Asia-Pacific trunk routes absorb larger leased fleets as operators prioritize balance-sheet flexibility over vessel ownership. Chinese lessors capitalize on this preference through state-backed financing structures.
- EU Green Deal maritime provisions:The EU's Monitoring, Reporting and Verification framework imposes compliance costs that embed eco-premiums into charter rates, accelerating fleet renewal decisions.
- Methanol-ready propulsion:Dual-fuel engine technology enables longer lease tenors by future-proofing vessels against fuel-switching mandates, reducing lessee residual risk exposure.
Market Restraints
- Steel price volatility:Newbuild cost uncertainty constrains lessor ordering decisions, particularly for mid-size containerships where margins compress fastest.
- Concentrated shipyard capacity:Korean and Chinese yards control over 80 percent of eco-vessel construction slots, creating delivery backlogs that extend lead times.
- Substitution by vessel-sharing agreements:Liner alliances deploy cooperative capacity management as an alternative to third-party leasing, capping demand growth in saturated lanes.
Strategic Opportunities
- Southeast Asian feeder routes:Indonesian and Vietnamese port expansions create demand for sub-3,000 TEU vessels underserved by major lessor portfolios.
- Battery-hybrid coastal tonnage:Converging shore-power infrastructure and lithium-ion propulsion systems open short-sea leasing segments previously dominated by owned fleets.
- US Inflation Reduction Act maritime provisions:Green-fuel production credits indirectly subsidize charter rates for vessels operating on approved alternative fuels in American trades.
Industry Challenges
- Marine finance underwriting scarcity:Qualified charter-party negotiators command premium compensation, constraining lessor scaling velocity.
- IFRS 16 implementation complexity:Lessees struggle to optimize off-balance-sheet treatment while maintaining covenant compliance, extending transaction timelines.
- BIMCO clause standardization delays:Evolving carbon accounting requirements outpace contract template updates, creating negotiation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ship Leasing Market |
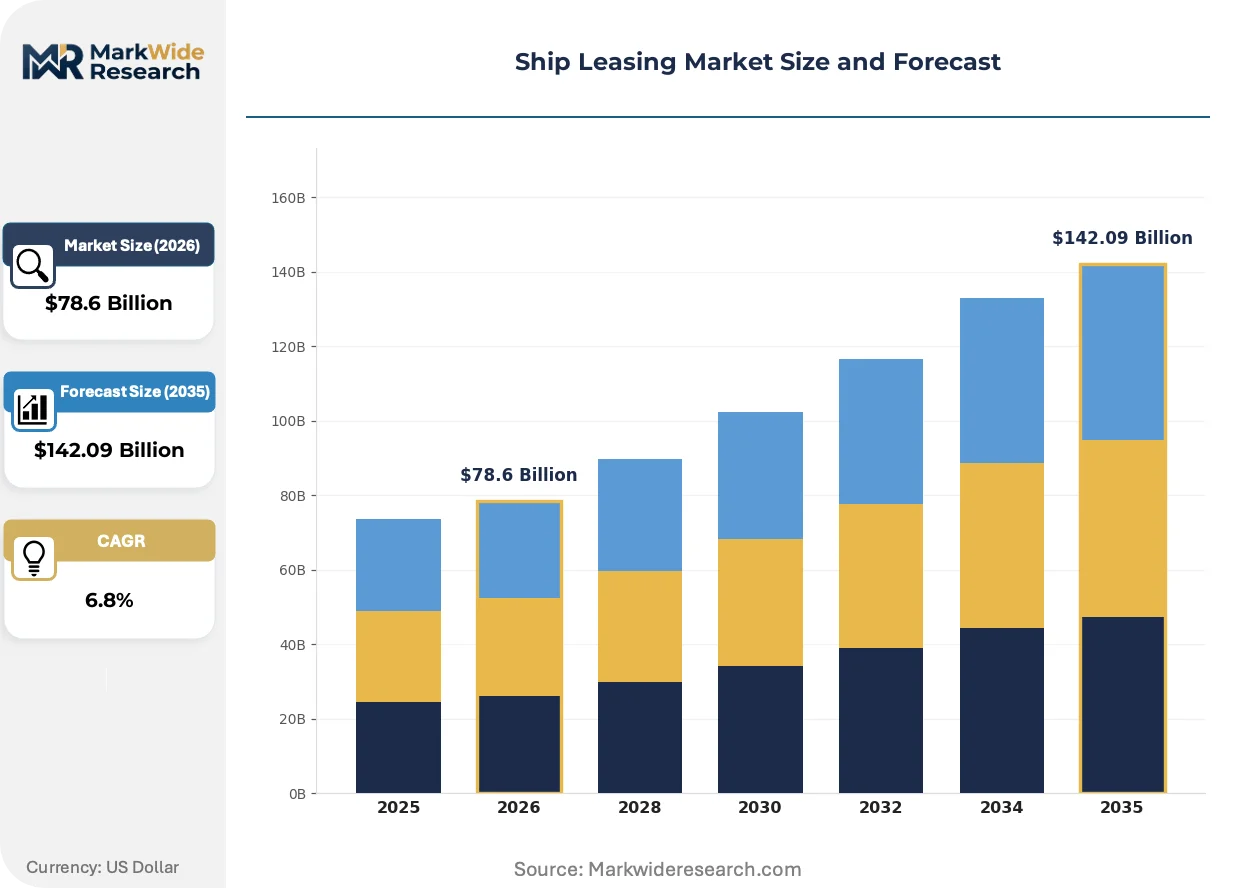
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Bulk Carriers, Tankers, Containerships, Offshore Support Vessels Customer Type: Shipping Companies, Freight Forwarders, Oil & Gas Firms, Charterers Lease Type: Operating Lease, Bareboat Charter, Time Charter, Voyage Charter Deployment Model: Short-term, Long-term, Seasonal, Spot Charter |
| Companies Covered | Minsheng Financial Leasing, SFL Corporation Ltd., ICBC Financial Leasing, Danaos Corporation, Seaspan Corporation, CMB Financial Leasing, Global Ship Lease, Inc., Ocean Yield ASA, Bank of Communications Financial Leasing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ship Leasing Market Emerging Trajectories
Digital twin technology and alternative fuel infrastructure are restructuring how lessors underwrite vessel performance and how charterers evaluate operating cost exposure across contract durations.
Ammonia-ready engine designs are bifurcating the newbuild orderbook. Engine manufacturers allocate R&D capacity toward dual-fuel ammonia systems while maintaining methanol options. Major liner operators split procurement between these pathways based on bunkering infrastructure assumptions, fragmenting lessor fleet standardization strategies.
The EU's Carbon Border Adjustment Mechanism extends to maritime transport emissions reporting, compelling lessors to embed verified carbon intensity data into lease documentation. Shipowners retrofit monitoring hardware to maintain charter eligibility. Container segments face the steepest compliance cost escalation given their route concentration through EU ports.
Charter duration preferences are compressing as fuel price volatility erodes long-term operating cost predictability. Liner operators favor three-to-five-year fixtures over traditional seven-to-ten-year structures. This behavioral shift concentrates in Asia-Europe trades where fuel exposure represents the highest cost component, forcing lessors to accelerate residual value recapture schedules.
Ship Leasing Market Segmentation
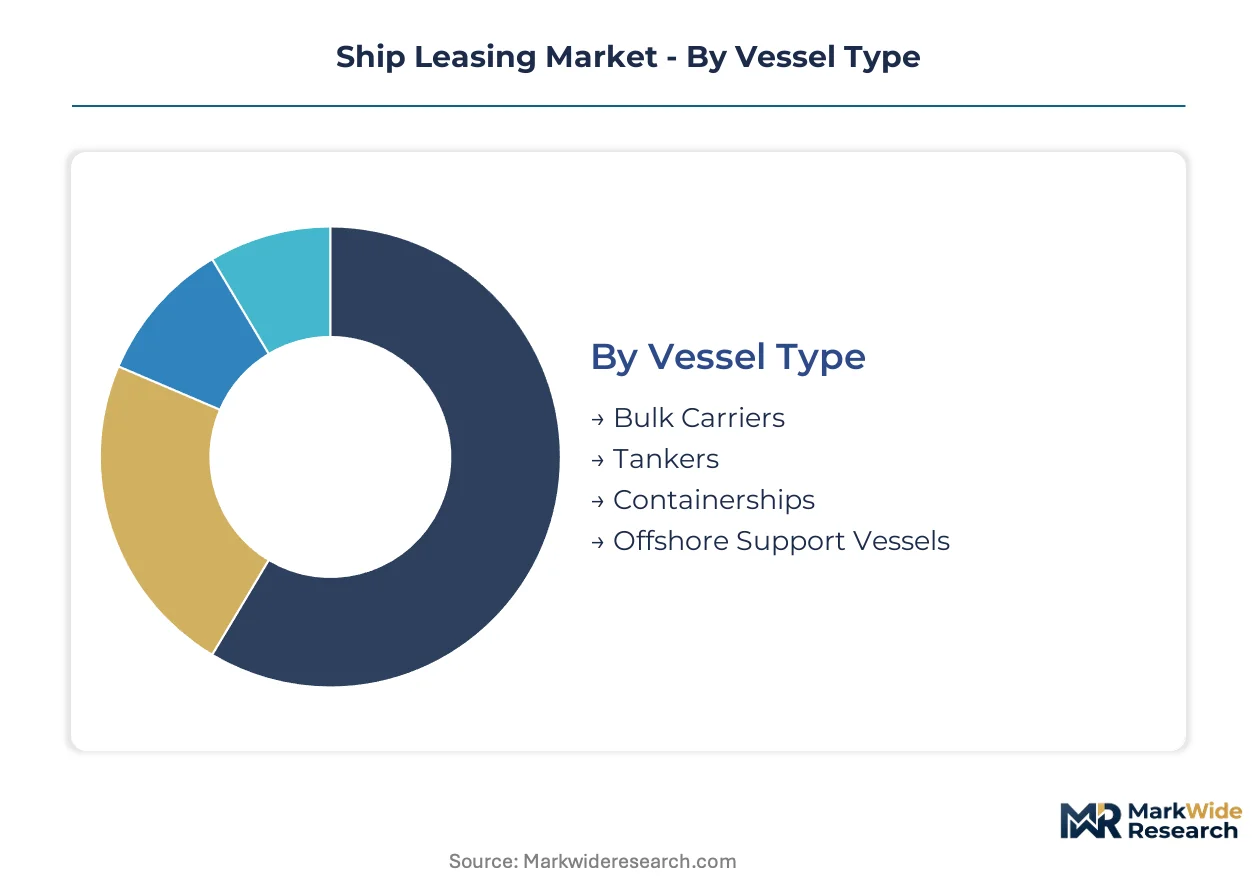
Segmentation in ship leasing reveals how capital structures, regulatory exposure, and operational flexibility distribute across vessel categories and contract mechanisms. Lessors configure portfolios by matching lease tenors to fuel transition risks and regional trade lane concentrations.
Vessel Type:
Margin pools concentrate in containerships where liner operators pay premiums for fleet flexibility and off-balance-sheet treatment, while bulk carriers generate volume through commodity trade cyclicality.
- Containerships:Standardized box dimensions enable rapid redeployment across Asia-Europe and transpacific trunk routes. Liner operators concentrate demand here as IMO carbon regulations force premature retirement of older tonnage, redirecting lease flows toward dual-fuel-ready newbuilds.
- Bulk Carriers:Capesize and Panamax hulls transport iron ore and coal under contracts tied to Baltic Dry Index fluctuations. Chinese state-backed lessors dominate newbuild financing for this segment as mineral import demand concentrates through Qingdao and Tianjin port clusters.
- Tankers:Crude and product carriers serve oil majors seeking operational control without equity commitment.
- Offshore Support Vessels:Platform supply and anchor-handling units support drilling campaigns in the North Sea and Gulf of Mexico.
Containerships hold installed capacity. Bulk carriers are rotating up the share rankings as Chinese lessors expand Pacific basin exposure.
Customer Type:
Contract sophistication and counterparty risk tolerance separate these demand pools, with oil majors and top-tier liners commanding preferential rate structures.
- Shipping Companies:Liner operators and tramp owners form the core demand base, prioritizing off-balance-sheet capacity additions. These customers dominate long-term operating leases as IFRS 16 implementation pushes structure optimization toward tenors exceeding five years.
- Freight Forwarders:NVOCCs and logistics integrators lease feeder vessels for intra-Asia and intra-European hub-and-spoke networks. Demand concentrates in sub-3,000 TEU tonnage as Indonesian and Vietnamese port expansions create route opportunities underserved by major lessor portfolios.
- Oil & Gas Firms:Majors and national oil companies prefer bareboat structures for crude transport.
- Charterers:Independent operators and trading houses seek short-term fixtures for speculative cargo positions.
Shipping companies hold installed capacity. Freight forwarders are rotating up the share rankings as regional hub development accelerates.
Lease Type:
Balance-sheet treatment and residual risk allocation drive selection, with operating leases expanding fastest as lessees prioritize accounting separation from asset ownership.
- Operating Lease:Lessors retain ownership and maintenance responsibility while lessees record periodic expenses. Container segments absorb the majority of new operating lease volume as liner operators optimize covenant compliance under IFRS 16.
- Bareboat Charter:Lessees assume full operational and maintenance control for the contract duration. Oil majors concentrate demand here for crude tankers, accepting higher residual value exposure in exchange for complete crew and bunkering autonomy.
- Time Charter:Vessel owners provide crew and technical management while lessees direct commercial deployment.
- Voyage Charter:Single-trip contracts for specific cargo movements with no ongoing obligation.
Operating leases hold installed capacity. Bareboat charters are rotating up the share rankings as energy majors restructure fleet ownership.
Deployment Model:
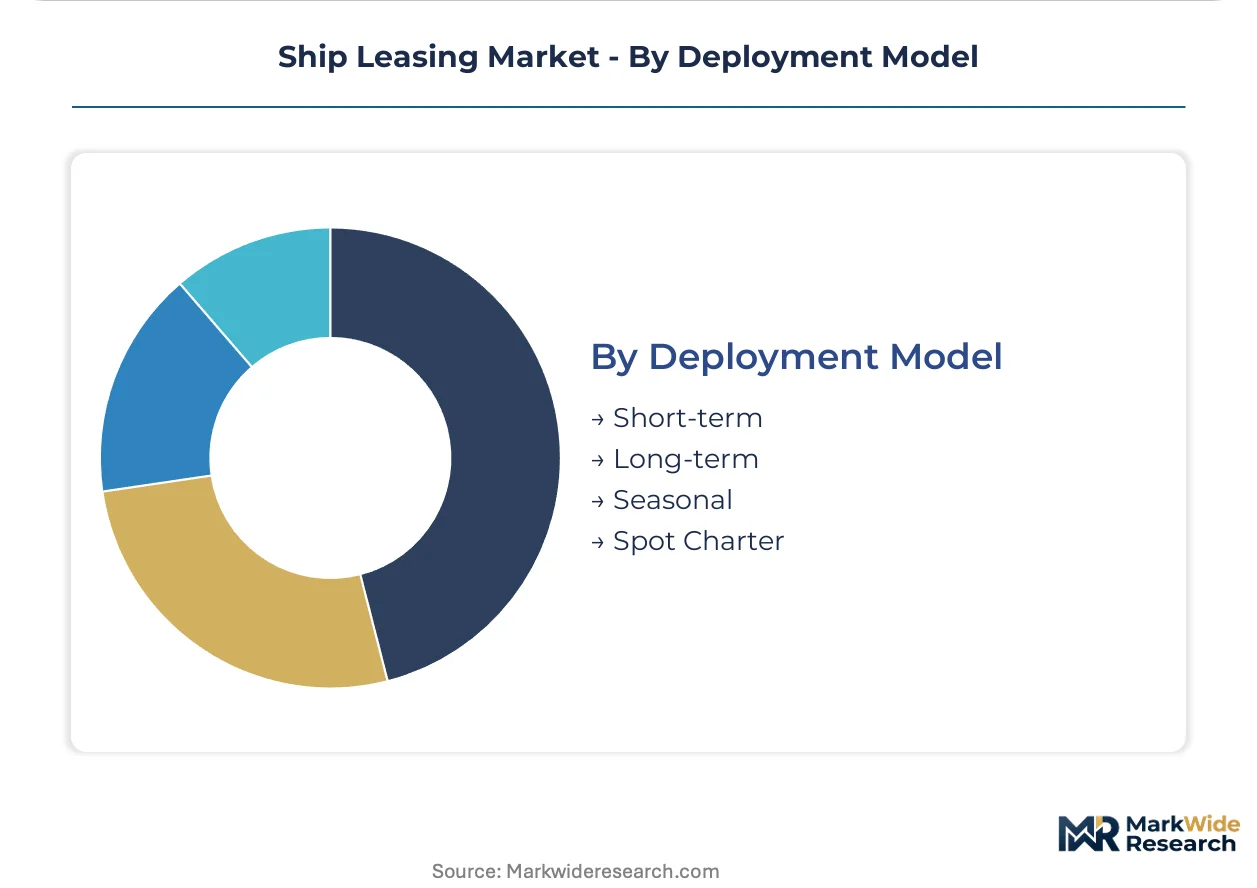
Tenor preferences are compressing across all segments as fuel price volatility erodes long-term operating cost predictability.
- Long-term:Seven-to-ten-year fixtures historically dominated container leasing but now face pressure. Asia-Europe trades show the steepest contraction toward three-to-five-year structures as methanol and ammonia fuel pathways remain unresolved.
- Short-term:Six-to-twelve-month contracts enable rapid fleet repositioning during trade lane disruptions. Demand concentrates in tanker segments where oil majors adjust cargo commitments to refinery maintenance schedules and geopolitical supply shifts.
- Seasonal:Agricultural export peaks and holiday retail surges drive temporary capacity additions.
- Spot Charter:Single-voyage arrangements respond to immediate freight rate spikes.
Long-term deployment holds installed capacity. Short-term fixtures are rotating up the share rankings as fuel uncertainty reshapes risk allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ministry of Transport anchors the dominant geography through port infrastructure investment and state-backed financing mandates that redirect vessel procurement toward domestic lessors. Regulatory pressure from the EU's Monitoring, Reporting and Verification framework and the US Coast Guard's Port State Control inspections shapes fleet deployment decisions across major trading routes.
China
Qingdao and Tianjin port clusters absorb the majority of newbuild bulk carrier financing as mineral import demand concentrates through northern terminals. The Ministry of Transport imposes green-fuel transition timelines that accelerate dual-fuel-ready vessel procurement. Shanghai-based lessors leverage state-backed balance sheets to dominate Pacific basin transactions.
Germany
Hamburg and Bremen harbor infrastructure supports containership leasing demand from European liner operators seeking fleet flexibility. The EU Green Deal maritime provisions embed compliance costs into charter rates, redirecting lease flows toward eco-designed tonnage. North Rhine-Westphalia's industrial corridor generates chemical tanker demand tied to Rhine barge connectivity.
United States
Los Angeles-Long Beach and Savannah port complexes drive containership fixture activity as retail import surges strain terminal capacity. The US Coast Guard's Port State Control inspections influence vessel selection criteria for trades touching American terminals. The Inflation Reduction Act's green-fuel production credits indirectly subsidize charter rates for alternative-fuel vessels.
Singapore
The Strait of Malacca chokepoint concentrates tanker and bulk carrier leasing demand from trading houses managing Asian commodity flows. The Maritime and Port Authority enforces environmental standards that filter eligible tonnage for regional deployment. Jurong shipyard clusters support retrofit activity for ammonia-ready engine conversions.
Japan
Tokyo Bay and Osaka-Kobe port networks anchor demand for mid-size containerships serving intra-Asian hub-and-spoke routes. METI's fuel-transition roadmaps guide lessor procurement toward methanol-ready propulsion systems. Nagoya's automotive export terminals generate specialized vehicle carrier leasing requirements.
Ship Leasing Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in ship leasing, with state-backed Chinese lessors and Western operating lease specialists commanding divergent competitive positions. Capital scale separates the upper tier, where balance sheet capacity enables newbuild financing at yard-direct pricing, from mid-tier players competing on vessel age and fuel efficiency metrics. Two strategic archetypes dominate: state-affiliated financial lessors deploying sovereign funding advantages, and independent operating lessors anchoring positions through long-term charter relationships. Competitive moves concentrate on fleet renewal velocity and geographic diversification into underserved feeder routes.
Within the state-backed tier, ICBC Financial Leasing and Bank of Communications Financial Leasing exemplify capital-scale positioning through their China-based corporate structures. Among independent operating lessors, Seaspan Corporation and Danaos Corporation occupy positions defined by containership specialization and charter duration management. SFL Corporation Ltd. sits within the diversified maritime asset segment, representing portfolio breadth across vessel categories rather than single-segment concentration.
| Leading Market Players |
|---|
| Minsheng Financial Leasing |
| SFL Corporation Ltd. |
| ICBC Financial Leasing |
| Danaos Corporation |
| Seaspan Corporation |
| CMB Financial Leasing |
| Global Ship Lease, Inc. |
| Ocean Yield ASA |
| Bank of Communications Financial Leasing |
| Others |
Supply Flow & Price Mechanics
Yard capacity utilization above eighty percent across Korean and Chinese shipbuilders concentrates pricing power with a narrow supplier base, compressing lessor margins while elevating newbuild cost floors for dual-fuel-ready tonnage. This supply tightness propagates through charter rate structures as lessors embed steel price volatility and extended delivery timelines into forward fixtures.
Pricing Analysis
Asia-Europe trunk routes command charter premiums fifteen to twenty percent above transpacific lanes due to higher fuel exposure and carbon compliance costs. Three-tier pricing structure across eco-premium, standard-compliant, and legacy tonnage segments reflects IMO Carbon Intensity Indicator grades. Cost compression in mid-size containerships intensifies because Chinese state-backed lessors price aggressively for market share. Freight forwarders operating sub-3,000 TEU feeder networks exhibit the highest price sensitivity, while oil majors accepting bareboat tanker structures prioritize operational control over rate minimization.
Supply Chain Analysis
Strait of Malacca transit underwrites the maritime leasing value chain by concentrating eighty percent of Asian commodity flows through Singapore-Jakarta corridor nodes. Newbuild supply concentrates in China, South Korea, and Japan, with specialized engine manufacturing anchored in Germany and Finland. Steel plate, dual-fuel propulsion systems, and carbon monitoring hardware constitute critical input dependencies. Single-source vulnerability in ammonia-ready engine technology creates fleet standardization risk as manufacturers split R&D between methanol and ammonia pathways. Distribution runs through Shanghai-based lessor headquarters for Pacific basin transactions and Hamburg-Bremen clusters for European operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ship leasing is approaching a platform-economics inflection as BIMCO standard contract templates evolve into interoperable data layers linking vessel performance, carbon accounting, and charter-party execution. This interoperability shift rewards lessors who embed digital twin infrastructure and real-time emissions verification into lease documentation.
For Market Incumbents: Compound fleet renewal velocity through state-backed financing partnerships that secure yard slots at cost-advantaged pricing. Deepen backward integration into green-fuel bunkering infrastructure to capture margin pools beyond bare charter rates. The substitution threat from liner alliance vessel-sharing agreements demands defensive positioning in underserved Southeast Asian feeder routes where cooperative capacity management offers inferior flexibility. For New Entrants and Emerging Players: Battery-hybrid coastal tonnage service gaps present white-space entry points as European and North American short-sea operators face shore-power mandates without lessor support infrastructure. Indonesian and Vietnamese port expansion zones offer the most penetrable geography for sub-3,000 TEU vessel deployment. A charter-rate-undercutting go-to-market angle, paired with carbon intensity guarantee clauses, secures initial fixtures against established lessor relationships. For Investors and Strategic Acquirers: Specialized lessors with methanol-ready fleet concentrations and seven-year weighted average lease tenors represent the optimal acquisition target archetype for fuel-transition optionality. Long-term viability over the next decade hinges on residual value recovery schedules that align with IMO decarbonization milestones. The signal to watch as inflection indicator is ammonia bunkering infrastructure commitment levels at Rotterdam, Singapore, and Houston port clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Newbuild Ordering | Secures yard slots for IMO 2023 CII-compliant tonnage before capacity constraints worsen. |
| Carbon Data Integration | Embeds EU MRV-verified emissions into BIMCO lease templates for charter eligibility. |
| Feeder Route Expansion | Captures Indonesian port growth with sub-3,000 TEU vessels outside major lessor portfolios. |
| Green Bunkering Partnership | Locks in methanol and ammonia supply chains for long-term charter rate competitiveness. |
| Digital Twin Deployment | Enables real-time vessel performance underwriting and predictive maintenance cost modeling. |
Methodological Framework
Operator-level perspectives from fleet managers at top-tier liner operators, charter-party negotiators at Chinese state-backed lessors, shipyard commercial directors in Korea and China, and marine finance underwriters at European export credit agencies anchored the qualitative base. Secondary validation drew from BIMCO contract template archives, IMO regulatory filings, EU MRV emissions databases, and Lloyd's List vessel transaction records. Bottom-up vessel-by-vessel lease book analysis triangulated against top-down macro trade flow projections.
Sensitivity analysis tested charter rate assumptions across fuel price volatility scenarios and carbon compliance cost trajectories. Segmentation dimensions modeled include vessel category, lease structure type, deployment tenor, customer counterparty tier, and regional trade lane concentration. CAGRs were derived from lease book growth rates and newbuild delivery schedules. Industry-specific forecast inputs incorporated IMO regulatory phase-in timelines and dual-fuel engine technology adoption curves.
Material uncertainties — steel price spikes, shipyard delivery delays, and green-fuel infrastructure buildout failures — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and liner operator outsourcing preferences. Practitioners should keep alternative scenarios live as IMO carbon intensity benchmarks tighten and regional fuel mandates diverge.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Maritime and Port Operations Emissions Transparency Platforms Market
Maritime Equipment
Ship-To-Shore (STS) Container Cranes Market
Maritime Equipment
Ship Wind Indicator Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Marine Hatch Covers Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
Vessel Tracking System Market
Maritime Equipment
Harbor Craft Market
Maritime Equipment
Ship Galley Equipment Market
Maritime Equipment
Global GPS Antenna for Boats Market
Maritime Equipment
Automated Mooring System Market
Maritime Equipment
Tugboat Operation Market
Maritime Equipment
Global Navigation Beacon Buoys Market