
 Garage and Service Station Service Market | 2026-2036
Garage and Service Station Service Market Size, Share, and Industry Trends Forecast 2026-2036
Garage and Service Station Service Market Insights
Preventive maintenance subscriptions is broadening the revenue base for garage operators beyond transactional repair visits. Shell leverages its global retail network to bundle lubricant services with loyalty-driven maintenance plans. BP anchors its position through integrated service bays at fuel stations across high-traffic corridors. Marathon Petroleum competes by concentrating on fleet-oriented quick-service formats in North American logistics corridors.
Garage and service station services encompass mechanical repair, fluid replacement, tire management, and diagnostic assessment performed on internal combustion and electric vehicles, typically requiring ISO-certified equipment and technician credentials for warranty compliance. The primary commercial purpose is sustaining vehicle operational uptime while ensuring regulatory safety and emissions conformity. Oil change and brake service categories within the Service Type dimension command stable volume but face margin compression from commodity lubricant pricing, while electric vehicle charging within the Technology segment represents the fastest-expanding capability investment as battery electric penetration rises. Maintenance subscriptions under Package Type are capturing recurring revenue streams that individual pay-per-service transactions cannot match.
EPA tailpipe standards and NHTSA safety recall enforcement in the United States shape demand for certified diagnostic tooling and documented service histories. The EU Green Deal and REACH chemical regulations in Europe restrict certain brake fluids and cleaning solvents, forcing reformulation investments by service providers. Stakeholders must monitor how battery electric vehicle service requirements reshape technician training curricula and bay equipment specifications ahead of powertrain mix inflections.
Market Dynamics
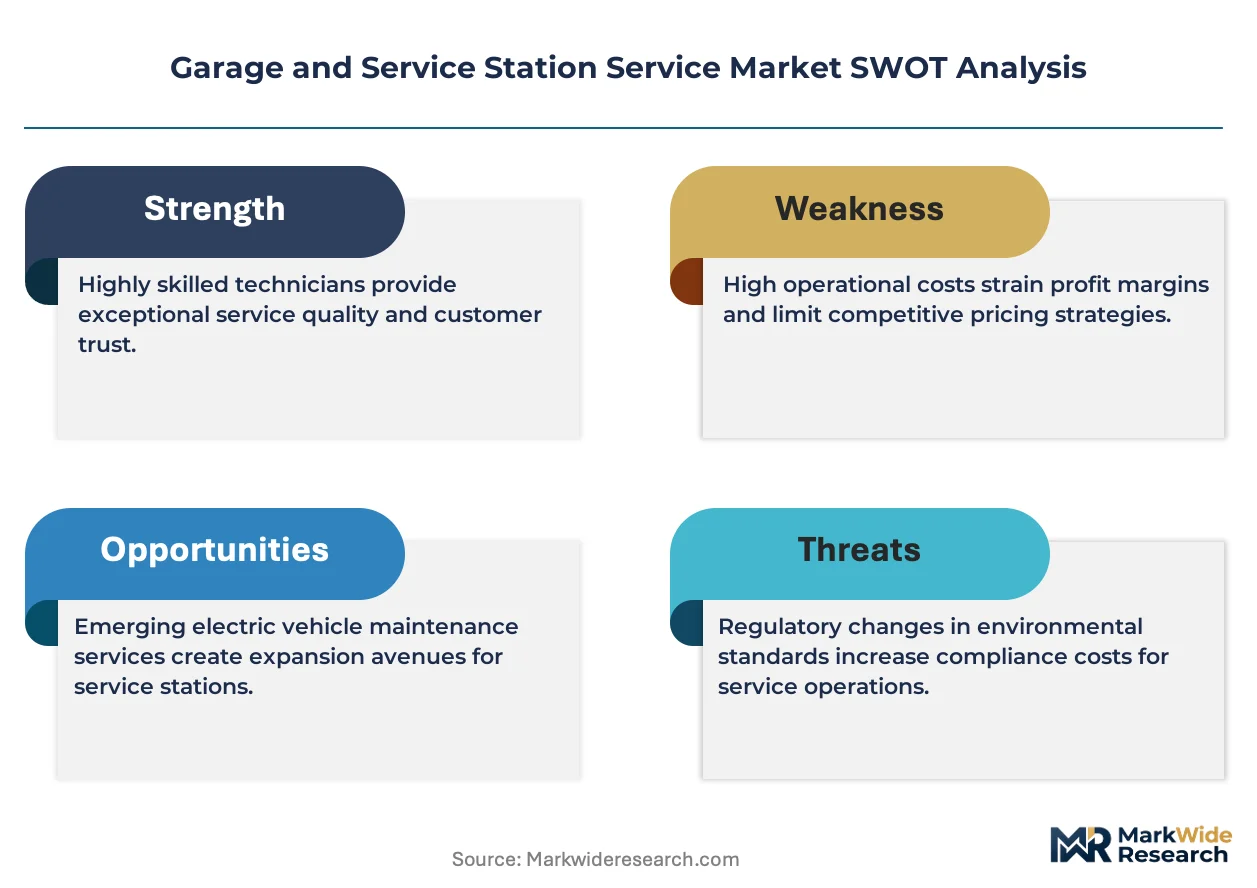
Fleet electrification timelines and divergent powertrain maintenance protocols are compressing service bay utilization models while forcing capital redeployment toward high-voltage diagnostic equipment and technician certification pipelines.
Growth Catalysts
- EPA tailpipe enforcement:NHTSA safety recall mandates in the United States require documented service histories and certified diagnostic tooling, pulling independent garages into compliance upgrade cycles.
- EV charging infrastructure:Battery electric vehicle penetration is rewriting bay equipment specifications as service providers install DC fast-charging capabilities alongside traditional lifts.
- Fleet maintenance contracts:Logistics operators in Germany are consolidating vendor relationships under the KBA's rigorous inspection protocols, concentrating demand at ISO-certified facilities.
Market Restraints
- Specialized equipment costs:High-voltage battery diagnostic systems and insulated tool sets impose capital barriers that strain independent garage cash flows.
- Technician certification pipelines:The gap between combustion-engine mechanics and EV-qualified technicians limits service capacity expansion despite equipment investments.
- REACH chemical restrictions:EU Green Deal solvent and brake fluid reformulations force inventory write-downs and supplier transitions across European service networks.
Strategic Opportunities
- Preventive maintenance subscriptions:Recurring revenue models are capturing fleet operators seeking operational uptime guarantees rather than transactional repair relationships.
- Integrated service-retail formats:High-traffic corridor locations combine fluid replacement with convenience retail, capturing dwell-time revenue from captive vehicle owners.
- EV readiness certification:Early investment in high-voltage training and bay isolation standards positions independent operators for warranty-compliant battery service.
Industry Challenges
- Powertrain skill bifurcation:Technician training curricula must simultaneously sustain internal combustion expertise while building battery thermal management and inverter diagnostics capabilities.
- Bay reconfiguration complexity:Existing service infrastructure requires electrical capacity upgrades and safety zone demarcation to accommodate high-voltage work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garage and Service Station Service Market |
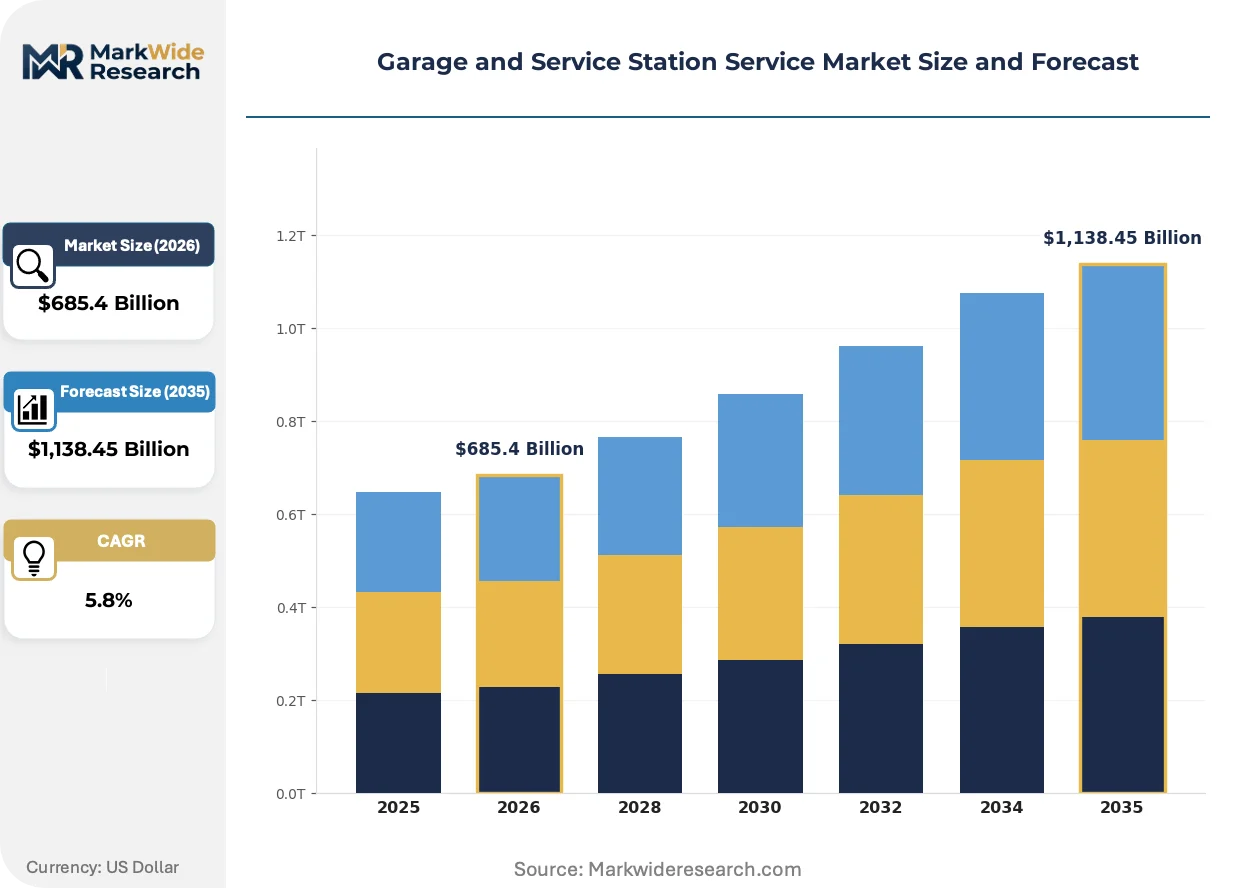
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,138.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Oil Change, Tire Rotation, Brake Service, Engine Repair End User: Fleet Operators, Individual Customers, Commercial Vehicles, Luxury Vehicles Technology: Diagnostic Tools, Fuel Injection Systems, Electric Vehicle Charging, Fluid Exchange Package Type: Standard Package, Premium Package, Maintenance Subscription, Pay-Per-Service |
| Companies Covered | Shell, ExxonMobil, BP, Chevron, TotalEnergies, Phillips 66, Marathon Petroleum, Valero Energy, Repsol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garage and Service Station Service Market Trends and Innovations
Service delivery models are pivoting from reactive repair toward predictive uptime management as connected vehicle data streams enable condition-based intervention before component failure.
Over-the-air diagnostic platforms are rewriting how service providers interact with vehicle systems. Fleet operators now receive real-time fault codes and predictive maintenance alerts directly from telematics providers. This compression of the information loop is enabling remote triage and parts pre-positioning before vehicles reach service bays.
REACH chemical regulations and the EU Green Deal are forcing solvent and brake fluid reformulations across European service networks. Service providers must purge non-compliant inventory and retrain technicians on new material handling protocols. Germany's KBA inspection stations are experiencing the steepest compliance transition costs due to mandatory documentation requirements.
Subscription-based maintenance packages are displacing individual service transactions among fleet operators seeking budget predictability. These contracts bundle preventive intervals with priority bay access and guaranteed turnaround times. North American logistics corridors show the densest adoption as just-in-time delivery requirements tighten vehicle availability windows.
Garage and Service Station Service Market Segmentation
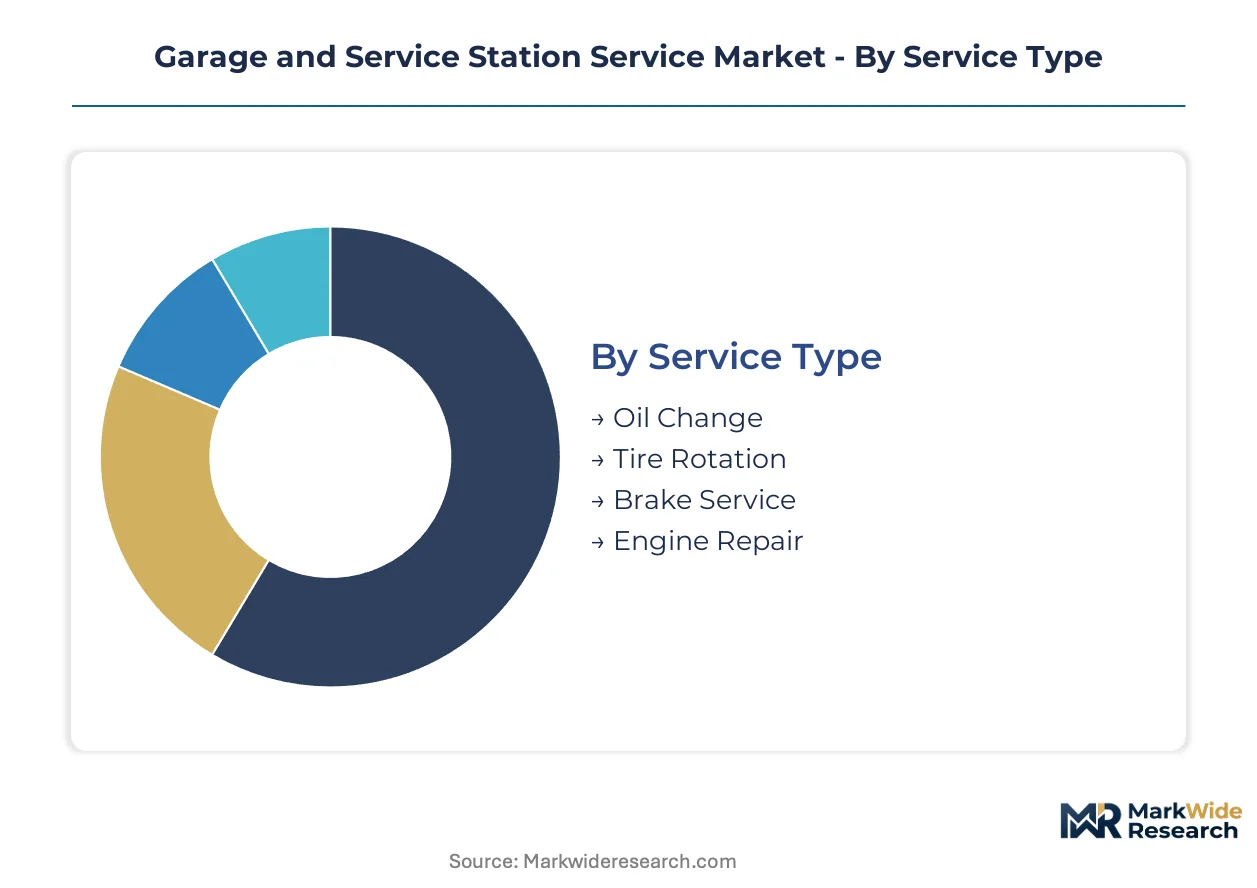
Service providers configure bay equipment and technician staffing around distinct demand profiles. Fleet operators require scheduled throughput with guaranteed turnaround windows, while individual customers tolerate variable wait times for lower per-visit costs.
Service Type:
Cost tier differentiation separates high-frequency commodity work from capital-intensive repair specialization.
- Oil Change:High-volume fluid replacement using bulk lubricant systems and standardized drain intervals. Fleet operators in Germany consolidate these services under KBA-mandated inspection schedules, compressing margins through volume contracting.
- Brake Service:Friction component replacement and hydraulic system maintenance requiring documented torque specifications. EPA emissions enforcement in the United States is pulling independent garages into compliance upgrade cycles for brake dust capture systems.
- Tire Rotation:Periodic repositioning services balancing tread wear across axle positions. Quick-service formats dominate this segment in North American logistics corridors.
- Engine Repair:Internal combustion powertrain overhaul requiring specialized machining equipment and warranty-compliant documentation. Technician certification pipelines limit capacity expansion despite equipment investments.
Oil Change leads volumes today; Brake Service is gaining share fastest.
End User:
Application context determines service frequency, price sensitivity, and bay reservation requirements.
- Fleet Operators:Multi-vehicle accounts demanding preventive maintenance subscriptions with uptime guarantees. Marathon Petroleum concentrates quick-service formats along logistics corridors to capture this demand.
- Individual Customers:Single-vehicle owners selecting transactional pay-per-service relationships. Shell bundles lubricant services with loyalty programs to retain this segment.
- Commercial Vehicles:Heavy-duty trucks and vans subject to DOT inspection requirements. NHTSA safety recall mandates require documented service histories for compliance.
- Luxury Vehicles:High-margin clientele requiring OEM-certified parts and specialized diagnostic tooling. BP integrates service bays at premium fuel stations to access this customer base.
Fleet Operators anchor revenue concentration; Maintenance subscriptions are expanding most quickly among Commercial Vehicles.
Technology:
Maturity gradients separate established combustion-era systems from emerging electric powertrain capabilities.
- Electric Vehicle Charging:DC fast-charging infrastructure and high-voltage bay isolation standards. Battery electric penetration is rewriting equipment specifications as providers install charging alongside traditional lifts.
- Diagnostic Tools:OBD-II scanners and manufacturer-specific software interfaces. Over-the-air platforms are compressing information loops for remote triage.
- Fuel Injection Systems:Precision component cleaning and sensor calibration for combustion engines. EPA tailpipe standards sustain demand for certified tooling.
- Fluid Exchange:Automated transmission and coolant replacement equipment. REACH chemical restrictions force solvent reformulation investments across European networks.
Diagnostic Tools dominate installed base; Electric Vehicle Charging shows the steepest expansion trajectory.
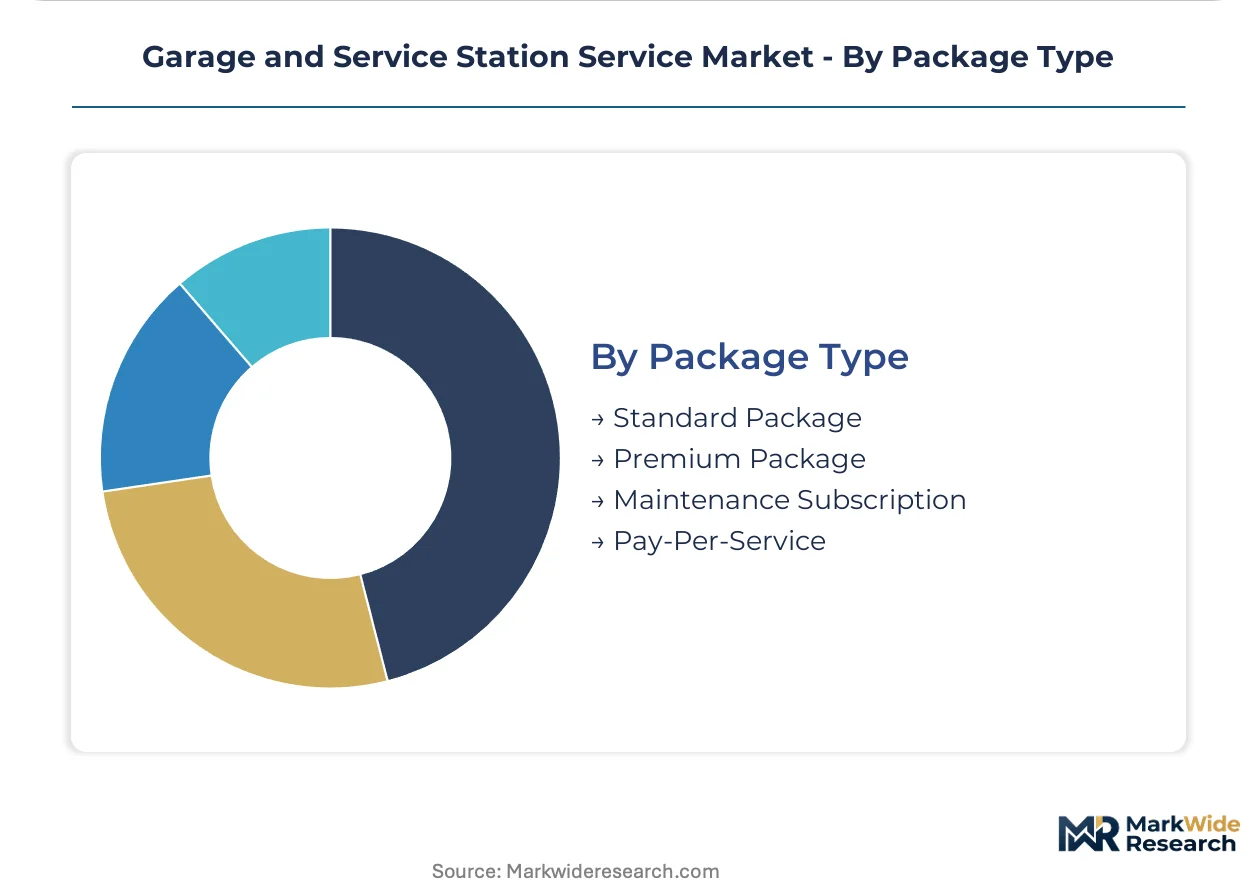
Package Type:
Customer relationship structure determines revenue predictability and working capital requirements.
- Maintenance Subscription:Recurring contracts bundling preventive intervals with priority bay access. Fleet operators in Germany seek budget predictability under KBA inspection protocols.
- Pay-Per-Service:Transactional pricing for unscheduled repairs with variable turnaround commitments. Individual customers tolerate this model for lower per-visit outlays.
- Premium Package:Enhanced service tiers including OEM parts guarantees and loaner vehicle provisions. Luxury vehicle owners demand this structure for warranty compliance.
- Standard Package:Basic service bundles covering oil changes and inspections at market-rate pricing. Price compression from commodity lubricant costs strains margins here.
Pay-Per-Service retains volume dominance; Maintenance Subscription is climbing the fastest among fleet accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA inspection protocols generate stricter compliance costs than the United States EPA framework, yet both markets concentrate service demand at certified facilities. Fleet operators in each geography prioritize documented maintenance histories to satisfy divergent regulatory mandates.
United States
NHTSA safety recall enforcement and EPA tailpipe standards pull independent garages into diagnostic upgrade cycles. The agency mandates documented service histories for warranty compliance. Dallas-Fort Worth logistics corridors concentrate quick-service formats serving fleet accounts with guaranteed turnaround windows.
Germany
KBA rigorous inspection protocols force ISO-certified equipment investments at independent garages. EU Green Deal chemical restrictions compel solvent and brake fluid reformulations. Stuttgart's automotive cluster drives EV readiness certification programs as battery electric penetration accelerates.
China
Dual carbon goals and MIIT new energy vehicle mandates reshape bay equipment specifications toward high-voltage capabilities. GB standards govern diagnostic tooling certification requirements. Shanghai's Yangtze River Delta corridor hosts the densest concentration of integrated service-retail formats.
Japan
METI energy transition policies accelerate battery electric service capability investments. JIS standards define technician certification requirements for high-voltage systems. Nagoya's Chubu manufacturing belt concentrates precision diagnostic equipment suppliers serving domestic OEM networks.
India
BIS automotive standards and PLI scheme incentives expand organized service network capacity. Central pollution control mandates tighten emissions testing protocols. Maharashtra's Mumbai-Pune corridor anchors fleet maintenance contract growth as logistics operators consolidate vendor relationships.
Garage and Service Station Service Market Competitive Landscape
Top-tier vendors anchor integrated fuel-service networks, while mid-scale operators concentrate on fleet-specific quick-service formats. The market structures around petroleum majors with retail infrastructure, independent garage chains with subscription capabilities, and specialized fleet maintenance providers. Three archetypes dominate: lubricant-anchored service bundlers, corridor-focused logistics specialists, and OEM-aligned premium service networks. Competitive moves center on bay electrification investments and preventive maintenance subscription expansion.
Among petroleum-anchored service networks, Shell, BP, and Marathon Petroleum occupy distinct positioning vectors. Shell exemplifies the lubricant-anchored archetype through loyalty-driven maintenance bundling. BP represents integrated corridor presence with service bays at high-traffic fuel stations. Marathon Petroleum sits within the fleet-specialist tier, concentrating quick-service formats along North American logistics corridors to capture commercial vehicle throughput.
| Leading Market Players |
|---|
| Shell |
| ExxonMobil |
| BP |
| Chevron |
| TotalEnergies |
| Phillips 66 |
| Marathon Petroleum |
| Valero Energy |
| Repsol |
| Others |
Pricing and Supply Chain Analysis
Bulk lubricant procurement costs cascade through three-tier pricing structures across premium, standard, and economy levels as fleet operators in Germany negotiate volume contracts under KBA inspection protocols while independent garages absorb margin compression from commodity fluid pricing.
Pricing Analysis
Capacity additions in China's Yangtze River Delta corridor are reshaping price floors for diagnostic equipment and high-voltage bay isolation systems. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified service networks from ISO-compliant independents and uncertified local operators. Pricing pressure stems from REACH chemical reformulation costs forcing inventory write-downs across European networks. Fleet operators show lowest price sensitivity due to uptime guarantee requirements, while individual customers drive commodity service tiers toward cost-plus structures.
Supply Chain Analysis
Technician certification pipelines in Germany, Japan, and the United States constrain equipment utilization rates as high-voltage training programs lag battery electric penetration curves. Insulated tool sets and DC fast-charging hardware draw from automotive electronics manufacturing clusters in Nagoya and Stuttgart. Single-source vulnerability concentrates in proprietary diagnostic software licenses from OEMs. Distribution runs through petroleum-anchored retail networks and independent garage chains with subscription capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion hinges on preventive maintenance subscription penetration as fleet operators trade transactional relationships for recurring revenue predictability, compressing customer acquisition costs across the installed base.
For Market Incumbents: Anticipate powertrain skill bifurcation by dual-tracking technician curricula for internal combustion expertise and battery thermal management capabilities. Secure backward integration into high-voltage diagnostic tooling supply to offset proprietary software licensing costs from OEMs. Channel control through loyalty-program bundling defends against petroleum majors expanding service-retail formats.
For New Entrants and Emerging Players: Launch via fleet-oriented quick-service formats along North American logistics corridors where Marathon Petroleum's concentration leaves white space for regional specialists. Target commercial vehicle maintenance subscriptions under DOT inspection requirements as the most penetrable segment. Go-to-market through telematics-integrated predictive uptime platforms enabling remote triage and parts pre-positioning.
For Investors and Strategic Acquirers: Consolidation pressure builds where independent garages lack capital for EV readiness certification and high-voltage bay reconfiguration. Long-term viability favors operators with integrated service-retail footprints and documented compliance histories under EPA or KBA frameworks. Acquisition targets include ISO-certified facilities with established fleet contracts. Signal to monitor: battery electric vehicle penetration inflection triggering warranty-compliant service demand.
| Strategic Initiative | Industry Significance |
|---|---|
| EV Readiness Certification Investment | Positions independents for warranty-compliant battery service as KBA protocols tighten. |
| Preventive Maintenance Subscription Expansion | Captures recurring revenue from fleet operators seeking operational uptime guarantees under NHTSA mandates. |
| High-Voltage Technician Training Pipeline | Closes capacity gap between combustion mechanics and EV-qualified staff in Germany's automotive cluster. |
| Integrated Service-Retail Format Rollout | Combines fluid replacement with convenience retail at high-traffic corridor locations per BP's model. |
| Over-the-Air Diagnostic Platform Integration | Enables remote triage and parts pre-positioning before vehicles reach service bays. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each market combining interviews with fleet operations managers, independent garage owners, OEM service network directors, petroleum retail executives, and high-voltage technician training providers. Secondary validation draws from EPA enforcement records, KBA inspection statistics, MIIT new energy vehicle mandates, METI policy disclosures, and BIS automotive standards. Bottom-up service bay utilization models triangulate against top-down fleet maintenance contract value estimates.
Rate-of-change decomposition separates volume growth from mix-shift effects across service type, end user, technology, and package type dimensions over the projection horizon. CAGRs derive from powertrain penetration curves, regulatory compliance cost trajectories, and subscription adoption elasticity. Industry-specific inputs include KBA inspection frequency data and NHTSA safety recall documentation requirements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated fleet electrification timelines or delayed technician certification pipeline expansion. Assumptions reflect documented service history mandates and REACH chemical restriction implementation schedules. Material deviation in battery electric vehicle penetration rates or high-voltage equipment cost curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Car Vending Machine Market
Automotive Services
Automotive Retail Market
Automotive Services
Vehicle Subscription Market
Automotive Services
Automotive Repair and Service Market
Automotive Services
Automotive Performance Tuning and Engine Remapping Services Market
Automotive Services
Global Cars-As-A-Service (CaaS) Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
Automatic Tire Changer Market
Automotive Services
Onboard Maintenance Systems Market
Automotive Services
Automotive MRO Market
Automotive Services
Global Street Sweeper Market
Automotive Services
Auto Leasing Services Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Europe Car Wash Market
Automotive Services
GCC Car Rental Market
Automotive Services
Automotive Digital Assistant Market