
 Harbor Craft Market | 2026-2036
Harbor Craft Market Size, Share, and Industry Trends Forecast 2026-2036
Harbor Craft Market Insights
Consolidation among port terminal operators is realigning vessel procurement toward fleet-wide standardization. Damen Shipyards Group leverages its modular platform strategy to serve these consolidated buyers across multiple harbor types. Sanmar Shipyards anchors its position in tug and pilot boat segments where repeat orders from major port groups sustain long-term contracts. Robert Allan specializes in custom naval architecture that differentiates its offerings in a market where buyers increasingly demand application-specific hull forms.
Harbor craft comprise workboats, tugs, pilot boats, and auxiliary vessels designed for confined-water port operations, typically constructed with steel or aluminum hulls ranging from 12 to 45 meters in length, and powered by diesel mechanical, diesel-electric, or emerging hybrid systems to execute towing, mooring, pilot transfer, and port maintenance functions. Aluminum hull configurations command premium positioning in segments where weight reduction directly translates to fuel efficiency and payload flexibility, while steel construction dominates heavy-duty towing applications where structural durability determines operational lifespan. The commercial application segment concentrates the largest installed base, though research-oriented vessels represent a margin-rich niche where specialized sensor integration and low-noise signatures justify higher build complexity.
The International Maritime Organization's MARPOL Annex VI standards, the European Union's F-Gas Regulation, and port-level air quality mandates from the US EPA collectively restrict conventional diesel propulsion in coastal and harbor zones, redirecting capital expenditure toward electrified or alternative-fuel platforms. Classification societies including Lloyd's Register and Bureau Veritas have introduced notation schemes for battery-hybrid harbor vessels that create compliance-driven demand for integrated energy storage systems. Stakeholders must monitor how port infrastructure electrification timelines align with vessel replacement cycles to avoid stranded asset risk in conventional propulsion fleets.
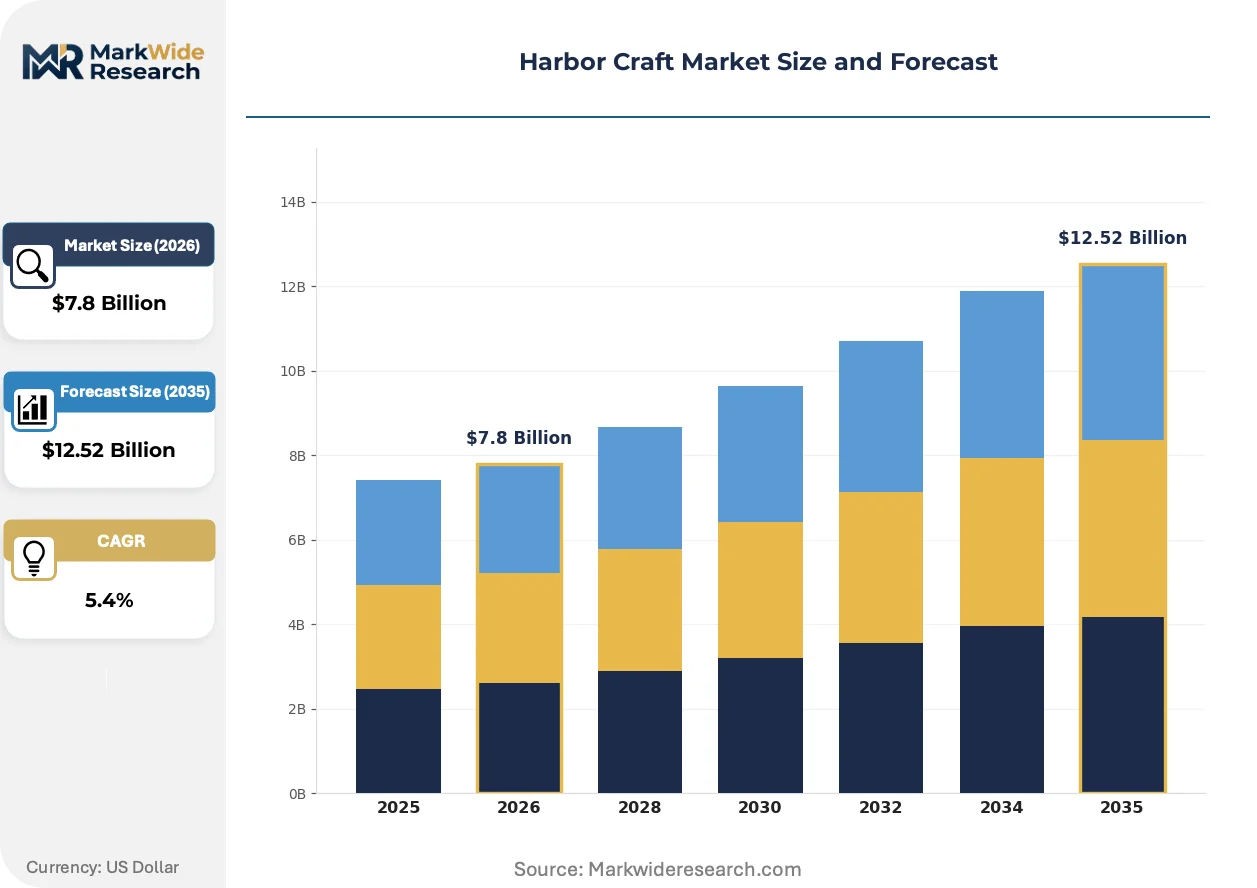
Market Dynamics
Port electrification mandates are compressing vessel replacement cycles as harbor operators face simultaneous pressure from EU F-Gas Regulation compliance deadlines and China's dual carbon goals enforcement timelines.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants in vessel HVAC systems is accelerating full-platform replacements rather than component retrofits across Rotterdam, Hamburg, and Antwerp terminals.
- Battery-hybrid propulsion:Classification society notations from Lloyd's Register and Bureau Veritas for integrated energy storage systems are creating procurement specifications that favor newbuilds over conventional diesel refits.
- China's coastal megaports:Ningbo-Zhoushan, Shanghai, and Shenzhen port authorities are consolidating fleet procurement under single-vendor framework agreements that standardize vessel specifications across multiple terminal operators.
Market Restraints
- Lithium-ion cell supply:Concentration of marine-grade battery production in South Korean and Chinese manufacturing bases exposes European and North American shipyards to input cost volatility and extended lead times.
- Harbor infrastructure gap:Shore power installation timelines at major transshipment hubs lag vessel electrification schedules by 18-36 months, creating operational mismatches for early adopters.
- Steel hull fabrication:Limited availability of certified welders for duplex stainless steel propulsion system integration is extending delivery schedules at mid-tier shipyards.
Strategic Opportunities
- Autonomous pilot boats:Norwegian and Singaporean port authorities are trialing remotely operated pilot transfer vessels that reduce crew costs and enable 24-hour scheduling flexibility in restricted visibility conditions.
- Methanol-ready tugs:Classification rule developments for dual-fuel methanol-diesel systems are opening specification windows for harbor craft operators seeking compliance pathways beyond battery electrification.
- Port maintenance robotics:Integration of hull-cleaning ROVs and subsea inspection drones into workboat platforms is creating bundled service offerings that differentiate vessel operators in concession bidding processes.
Industry Challenges
- Marine electrical engineering talent:Shortage of specialists capable of integrating high-voltage DC distribution systems with conventional vessel automation architectures is extending commissioning periods at hybrid-electric newbuilds.
- Type approval timelines:Protracted certification processes for novel energy storage configurations under Lloyd's Register's "Battery" notation and Bureau Veritas's "Hybrid Power" rules are delaying revenue recognition for shipyard deliveries.
- Legacy fleet stranding:Harbor operators with recent conventional diesel investments face asset impairment risk as port-level air quality mandates from the US EPA and EU member state regulators advance implementation dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Harbor Craft Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boats, Yachts, Barges, Fishing Vessels Material: Aluminum, Fiberglass, Steel, Wood Application: Recreational, Commercial, Transportation, Research Size: Small, Medium, Large, Extra Large |
| Companies Covered | Damen Shipyards Group, Sanmar Shipyards, Bord a Bord, Arctic Boat, Hukkelberg, Eastern Shipbuilding Group, Fincantieri, Robert Allan, Glosten, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Harbor Craft Market Trends and Innovations
Propulsion system architecture is fragmenting across multiple technology pathways as regulatory pressure and infrastructure readiness diverge across major port clusters.
Modular battery container systems are decentralizing energy storage configuration decisions for harbor craft operators. Tug and workboat fleets in Northern European ports are adopting swappable battery modules that enable operational flexibility without permanent hull integration. This architecture is decentralizing capital deployment by allowing operators to lease energy capacity rather than own fixed battery assets.
The EU F-Gas Regulation's refrigerant phase-down schedule is forcing HVAC system redesigns across pilot boat and crew transfer vessel segments. Shipyards serving North Sea and Mediterranean routes are specifying CO2-based refrigeration cycles that eliminate synthetic refrigerant dependencies. Aluminum-hulled fast craft operating in Spanish, Italian, and Greek ports are experiencing the most acute specification pressure due to their intensive climate control requirements.
Framework contracting by consolidated port groups is compressing supplier relationship structures in vessel procurement. Terminal operators in China's Pearl River Delta are awarding multi-year, multi-vessel agreements that bundle construction, maintenance, and crew training under single-source arrangements. This pattern is most visible in Shenzhen and Guangzhou where state-owned port groups have centralized fleet management functions previously distributed across individual terminals.
Harbor Craft Market Segmentation
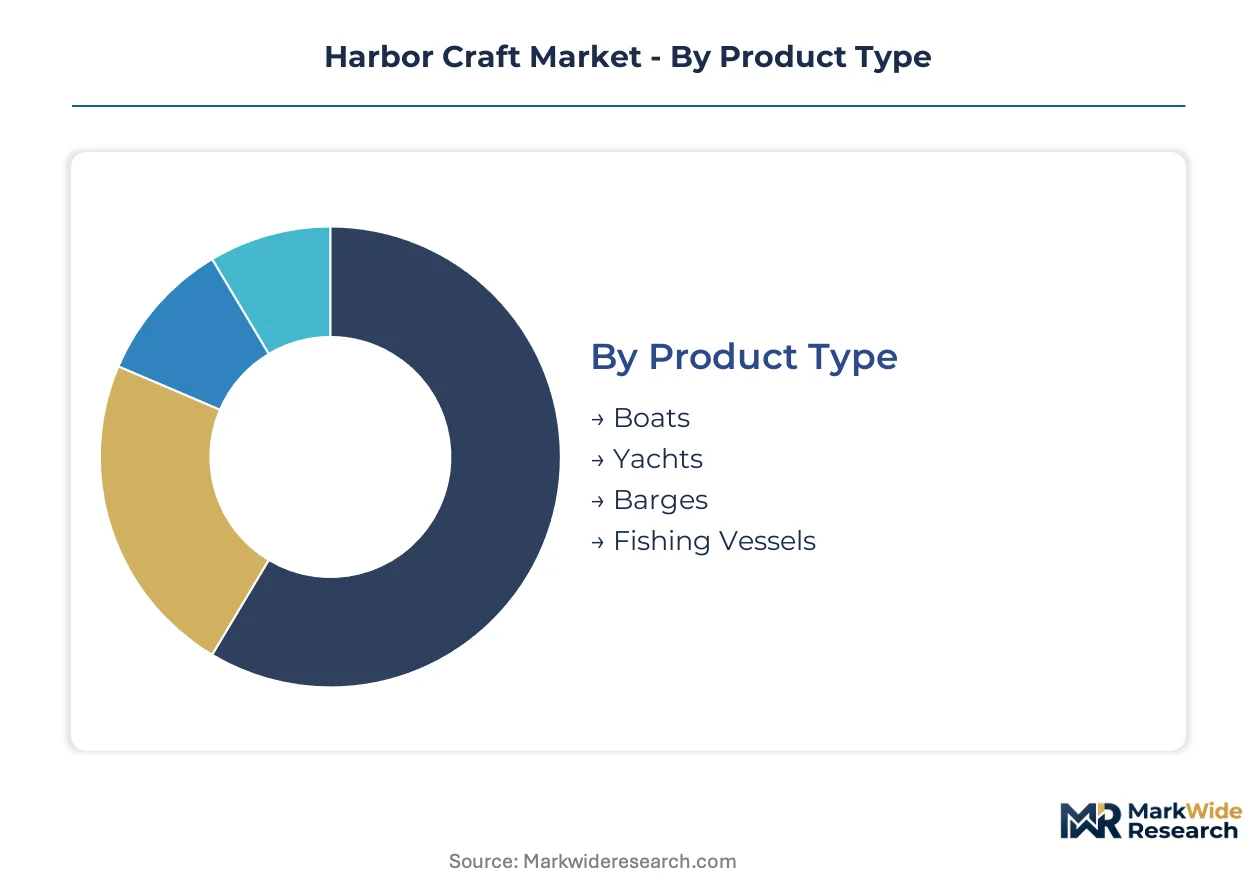
Harbor craft procurement patterns diverge sharply across vessel configurations, with port authorities prioritizing payload capacity and maneuverability specifications that align with terminal infrastructure constraints. Material selection and hull architecture determine operational lifecycles and compliance pathways under tightening emissions mandates.
Product Type:
Buyers in this category differentiate by operational intensity and duty cycle requirements rather than pure acquisition cost.
- Boats:Pilot boats and crew transfer vessels typically span 12-25 meters with planing or semi-displacement hulls optimized for harbor transit speeds. Demand concentrates in Rotterdam, Singapore, and Shanghai where pilotage services require all-weather operability and rapid turnaround between vessel calls.
- Yachts:Harbor patrol and VIP transport configurations employ aluminum or composite construction with low-noise signatures for sensitive marine environments. Mediterranean and Caribbean port authorities specify these vessels for customs enforcement and maritime security roles where crew comfort extends operational endurance.
- Barges:Flat-deck cargo platforms serve container lashing, bunkering, and waste collection functions across transshipment terminals.
- Fishing Vessels:Specialized harbor-based trawlers and processing craft support coastal fleet logistics at major landing ports.
Barges lead volumes today; pilot boats are gaining share fastest under port consolidation trends.
Material:
Cost tier positioning separates premium aluminum specifications from steel alternatives in procurement frameworks.
- Aluminum:Lightweight alloy construction reduces fuel consumption by 15-30% in high-cycle operations and enables faster acceleration for pilot transfer missions. Ningbo-Zhoushan and Shenzhen port groups specify aluminum hulls for newbuild tugs where payload flexibility justifies material premiums.
- Fiberglass:Composite laminates dominate crew boats and small work craft under 20 meters where corrosion resistance and molded complex shapes reduce maintenance intervals. Greek and Italian operators favor fiberglass for pilot boats operating in high-salinity Mediterranean conditions.
- Steel:High-tensile plate construction anchors heavy-duty towing applications where structural fatigue resistance determines 25-year service lifecycles.
- Wood:Traditional timber construction persists in heritage harbor craft and specialized training vessels where aesthetic specifications override operational metrics.
Steel dominates heavy-towing procurement; aluminum is climbing the fastest under EU emissions compliance pressure.
Application:
Volume concentration versus margin structure shapes strategic positioning across end-use segments.
- Commercial:Tug fleets, mooring boats, and port maintenance craft constitute the installed base majority with standardized specifications enabling multi-vessel framework contracts. China's state-owned port groups consolidate commercial vessel procurement under single-vendor agreements that bundle construction with lifecycle maintenance.
- Recreational:Harbor tour boats and water taxi services operate on shorter duty cycles with passenger comfort specifications driving interior configuration decisions.
- Transportation:Crew transfer and logistics vessels support offshore wind installation harbors in Northern Europe.
- Research:Oceanographic sampling and environmental monitoring craft command build premiums for specialized sensor integration and low-acoustic signatures.
Commercial applications anchor fleet volumes; research vessels follow the steepest expansion trajectory on offshore wind development.
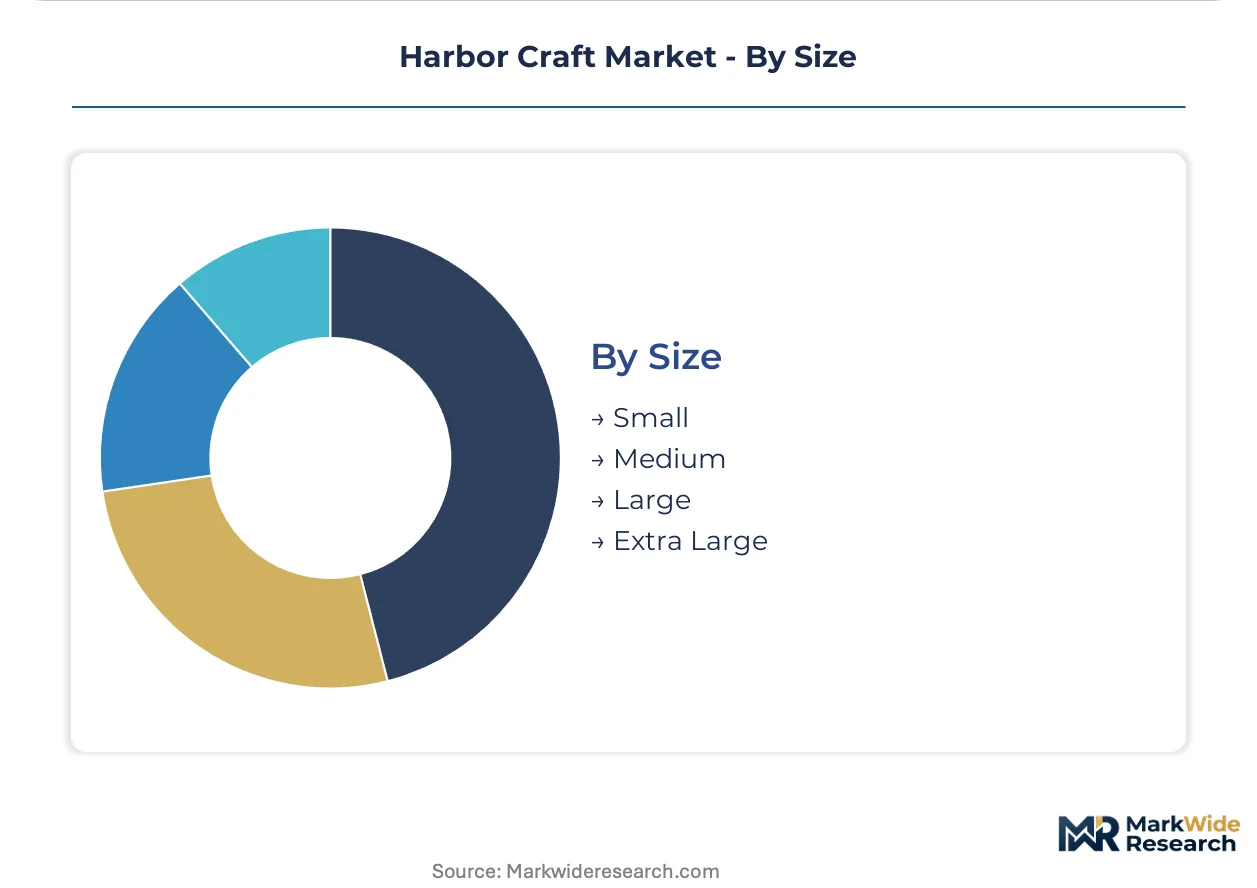
Size:
Infrastructure compatibility constraints at berth depth and crane capacity limit viable size selections for terminal operators.
- Small:Vessels under 15 meters serve line-handling, fender positioning, and harbor patrol where maneuverability in confined basins outweighs payload requirements. Singapore's Tuas terminal expansion specifies compact electric tugs for narrow-channel operations.
- Medium:15-30 meter configurations balance bollard pull with berth access across mixed-use container terminals.
- Large:30-45 meter harbor tugs execute ship-assist operations at mega-container terminals with ultra-large vessel calls.
- Extra Large:Specialized salvage and heavy-lift platforms exceed standard harbor craft classifications for emergency response roles.
Medium-size hulls lead procurement volumes today; small electric configurations are gaining share fastest on port electrification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welders for duplex stainless steel propulsion systems concentrate in Northern European shipyard clusters. This talent pool anchors fabrication capacity for hybrid-electric harbor craft serving EU F-Gas compliance deadlines.
China
Ningbo-Zhoushan and Shanghai port authorities are consolidating fleet procurement under single-vendor framework agreements. The country's dual carbon goals enforcement timelines are compressing vessel replacement cycles at coastal megaports. Shenzhen's state-owned terminal operators are standardizing aluminum-hull tug specifications across the Pearl River Delta.
Netherlands
Rotterdam terminal operators face EU F-Gas Regulation compliance deadlines for HVAC system refrigerant phase-down. The national port authority is accelerating full-platform replacements rather than component retrofits. Dutch shipyards serving North Sea routes are specifying CO2-based refrigeration cycles for pilot boat newbuilds.
Norway
Oslofjord and Bergen port authorities are trialing remotely operated pilot transfer vessels for 24-hour scheduling flexibility. The country's maritime regulator is advancing classification rules for autonomous harbor craft operations. Trondheim-based shipyards are integrating modular battery container systems for swappable energy configurations.
Singapore
Tuas terminal expansion is specifying compact electric tugs for narrow-channel maneuverability. The Maritime and Port Authority is aligning shore power installation timelines with vessel electrification schedules. Jurong ship repair clusters are developing bundled service offerings that integrate hull-cleaning ROVs into workboat platforms.
United States
Gulf Coast shipyards are extending delivery schedules due to limited availability of certified welders for hybrid propulsion integration. The EPA's port-level air quality mandates are creating asset impairment risk for recent conventional diesel investments. Houston and Long Beach terminal operators are monitoring infrastructure electrification timelines to avoid stranded fleet assets.
Harbor Craft Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across harbor craft procurement channels. The vendor base organizes into three tiers: full-service shipyard groups with modular platform strategies, regional fabricators anchored in specific vessel categories, and naval architecture boutiques delivering custom hull specifications. Consolidated port authorities increasingly favor framework contracting with tier-one players capable of bundling construction, maintenance, and crew training. Geographic expansion and technology licensing represent the dominant competitive moves as shipyards seek access to battery-hybrid propulsion expertise.
Within the European specialist tier, Damen Shipyards Group and Sanmar Shipyards exemplify divergent strategic positions. Damen represents the modular platform archetype serving consolidated buyers across multiple harbor types through standardized vessel families. Sanmar occupies a position within the tug and pilot boat segment where repeat orders from major port groups sustain long-term contracting relationships. Robert Allan sits within the custom naval architecture niche, differentiating through application-specific hull forms rather than production scale. These three anchors illustrate how procurement consolidation is compressing supplier relationship structures while preserving space for specialized design expertise.
| Leading Market Players |
|---|
| Damen Shipyards Group |
| Sanmar Shipyards |
| Bord a Bord |
| Arctic Boat |
| Hukkelberg |
| Eastern Shipbuilding Group |
| Fincantieri |
| Robert Allan |
| Glosten |
| Others |
Pricing and Supply Chain Analysis
State-backed port conglomerates and family-owned shipyard groups anchor vessel production capacity across East Asian manufacturing clusters, translating sovereign financing advantages into multi-year framework contracting power while compressing margins for independent fabricators serving spot-market buyers.
Pricing Analysis
The bundled-versus-unbundled service split separates harbor craft procurement into two distinct pricing architectures. Framework agreements from China's state-owned port groups bundle construction, maintenance, and crew training under long-term contracts, while European and North American operators purchase vessels on standalone transactional terms with aftermarket services negotiated separately. Price differentiation hinges on hull material certification grade and propulsion system integration complexity, with Lloyd's Register battery-hybrid notation commanding material premiums over conventional diesel specifications. Cost compression in mid-tier steel-hull fabrication is intensifying because certified welder scarcity extends delivery schedules and forces overtime premiums at shipyards. Commercial terminal operators exhibit highest price sensitivity due to standardized fleet specifications, whereas research vessel buyers demonstrate lowest sensitivity given specialized sensor integration requirements.
Supply Chain Analysis
Marine-grade battery cell supply rests on South Korean and Chinese specialty chemical producers, with Samsung SDI and CATL manufacturing bases feeding global harbor craft electrification programs. Lithium-ion cathode materials and high-voltage DC distribution components draw from concentrated East Asian supply nodes, while duplex stainless steel propulsion system fabrication sources from Northern European metallurgical specialists. Single-source vulnerability in battery management system semiconductors exposes shipyards to allocation risk during automotive sector demand surges. Distribution runs through direct OEM procurement channels for consolidated port groups, with smaller operators accessing vessels via regional shipyard representatives and maritime equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in harbor craft manufacturing stems from aluminum hull premiumization accelerating under EU F-Gas Regulation compliance deadlines, as weight-driven fuel efficiency gains justify material cost premiums in high-cycle port operations.
For Market Incumbents: To counter lithium-ion cell supply concentration in South Korean and Chinese manufacturing bases, Damen Shipyards Group and Sanmar Shipyards should deepen backward integration into battery pack assembly through joint ventures with European energy storage specialists, while securing multi-year cathode material offtake agreements to isolate procurement from spot-market volatility. Certification investment in Bureau Veritas hybrid-power notation systems creates switching costs that lock consolidated port buyers into incumbent service ecosystems. For New Entrants and Emerging Players: EU F-Gas Regulation in the Netherlands, Germany, and Belgium opens a window for CO2-based HVAC system specialists to capture pilot boat retrofit demand as Rotterdam and Hamburg terminal operators accelerate full-platform replacements. Autonomous harbor craft development in Norway and Singapore represents the most penetrable white-space target, with regulatory sandbox programs enabling technology validation without full classification society compliance. Go-to-market positioning should emphasize port maintenance robotics integration bundled with workboat platform sales to differentiate in concession bidding processes. For Investors and Strategic Acquirers: Port terminal operators and maritime infrastructure funds are the most active acquirer in this space, consolidating regional shipyard capacity to secure captive vessel supply for fleet renewal programs. Five-to-ten year viability hinges on electrification infrastructure deployment timelines aligning with vessel replacement cycles. Acquisition targets should display established relationships with Lloyd's Register or Bureau Veritas for accelerated type approval pathways. The signal to watch is shore power installation acceleration at major transshipment hubs, which would validate stranded-asset risk assumptions for conventional diesel fleet exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Battery Platform Development | Swappable energy configurations enable leasing models that reduce operator capital deployment at Northern European ports. |
| Classification Society Certification Investment | Lloyd's Register battery notation accelerates revenue recognition and creates procurement specification lock-in with port authorities. |
| Autonomous Vessel Technology Partnership | Remote pilot boat trials in Oslofjord and Singapore establish regulatory precedent for crew-cost reduction in 24-hour operations. |
| Framework Contracting with Port Conglomerates | Multi-year agreements with China's state-owned terminal operators standardize specifications across Pearl River Delta hubs. |
| CO2 Refrigeration System Integration | Elimination of synthetic refrigerant dependencies addresses EU F-Gas Regulation phase-down deadlines for Mediterranean pilot craft. |
Research Methodology
Bottom-up harbor craft fleet modeling reconciled against top-down shipyard orderbook tracking forms the analytical core of this study. Primary interviews with port authority fleet managers, shipyard procurement directors, classification society surveyors, and marine electrical engineering specialists were combined with secondary validation from Lloyd's Register and Bureau Veritas certification databases, customs trade records for aluminum and steel hull exports, and SEC filings from listed port operators. Triangulation across vessel delivery schedules, propulsion system supplier disclosures, and terminal operator capital expenditure announcements ensures statistical integrity.
Input-output matrices linking battery-hybrid propulsion penetration rates to port infrastructure electrification timelines drive volume projections across the analysis window. Segmentation dimensions include vessel type, hull material, application category, and size tier, with propulsion architecture and regional regulatory framework as cross-cutting variables. CAGRs were derived from fitted trend lines applied to historical fleet replacement patterns and forward-looking procurement announcements from consolidated port groups. Forecast inputs incorporate shore power installation schedules, EU F-Gas Regulation compliance deadlines, and China's dual carbon goals enforcement intensity.
Revisions become necessary when battery cell supply disruptions, classification society rule changes, or port infrastructure electrification delays materialize beyond modeled scenarios. Forecasts reflect assumptions regarding regulatory timeline adherence and technology cost curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Offshore Support Vessel Service Market
Maritime Equipment
Ship Plate Market
Maritime Equipment
United States Offshore Support Vessels Market
Maritime Equipment
Global Maritime Analytics Market
Maritime Equipment
Latin America Offshore Support Vessels Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
North America Offshore Support Vessels Market
Maritime Equipment
Global Waterway Transportation Software and Services Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Global Spar Beacon Buoys Market
Maritime Equipment
Asia-Pacific Maritime Satellite Communication Market
Maritime Equipment
North America Container Terminal Operations Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Marine Vessel Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Platform Supply Vessels (PSV) Market